
 Additive Manufacturing Machines Market | 2026-2036
Additive Manufacturing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Additive Manufacturing Machines Market Insights
The EU Green Deal is decoupling aerospace supply chains from energy-intensive subtractive methods, compelling tier-one suppliers to retool with lower-waste fabrication. EOS GmbH anchors European metal powder-bed system supply through its Munich engineering base. Stratasys Ltd leverages polymer expertise across dental and consumer prototyping segments in North America. GE Additive dominates industrial gas turbine component production with its proprietary electron beam melting architecture.
Additive manufacturing machines build three-dimensional objects through layer-by-layer deposition controlled by digital CAD files, with build envelopes ranging from 100 millimeters to over one meter and layer resolutions between 20 and 100 microns depending on technology class. These systems serve industrial applications requiring geometric complexity, material efficiency, or lot-size flexibility impossible with conventional machining. Selective laser sintering leads installed base volume due to polymer versatility across medical device and consumer product applications. Metal-directed energy deposition systems represent the fastest-expanding technology category as aerospace and automotive manufacturers qualify titanium and nickel superalloy components for structural loads. Electron beam melting occupies a specialized margin pool in orthopedic implant fabrication where pore architecture and biocompatibility certification command premium pricing.
The FAA and EASA impose stringent process qualification requirements on flight-critical additive components, forcing machine vendors to validate repeatability across thermal profiles and powder lots. China's MIIT publishes national additive manufacturing standards that shape domestic procurement specifications and constrain import eligibility for non-certified foreign equipment. ISO and ASTM frameworks govern feedstock characterization and mechanical testing protocols that determine market access across jurisdictions. Stakeholders must monitor evolving airworthiness qualification timelines and national standard harmonization gaps that determine where capital deployment yields fastest certification returns.
Market Dynamics
Powder-bed fusion systems are displacing conventional tooling across aerospace and medical implant production as airworthiness directives from the FAA and EASA mandate validated additive processes for flight-critical components.
Growth Catalysts
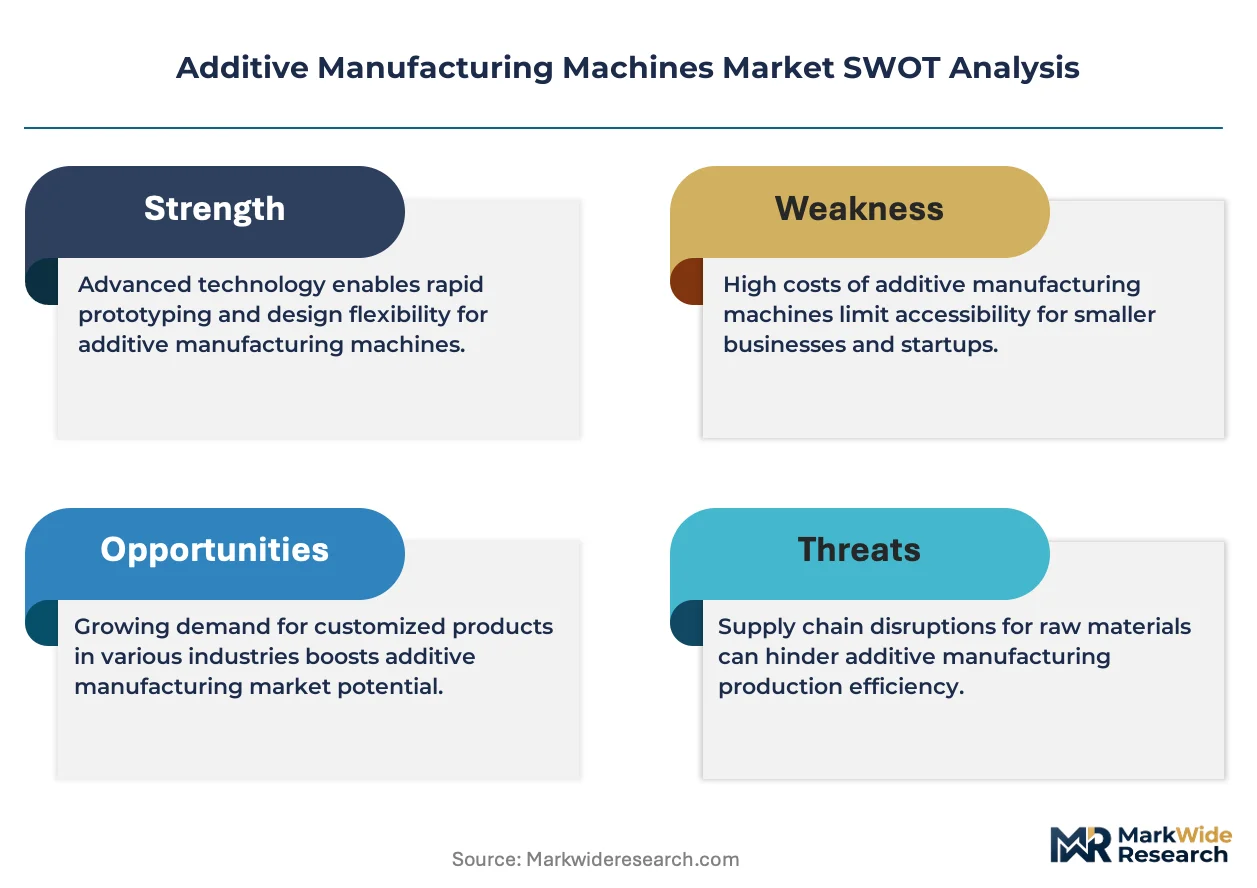
- EU Green Deal decarbonization mandates:Tier-one aerospace suppliers in Germany and France must retool with lower-waste fabrication methods to meet supply chain emissions thresholds.
- China's MIIT national standards:Domestic certification requirements accelerate procurement of locally qualified metal powder-bed systems around Shenzhen and Shanghai industrial clusters.
- Titanium superalloy qualification:Aerospace manufacturers in the United States expand electron beam melting capacity for structural airframe components under FAA process validation protocols.
Market Restraints
- Noble metal powder volatility:Titanium and nickel superalloy feedstock prices fluctuate with aerospace demand cycles, compressing machine utilization economics.
- European system supply concentration:Munich-based engineering clusters dominate high-precision metal powder-bed architecture, creating single-source vulnerability for tier-two suppliers.
- ISO/ASTM harmonization gaps:Divergent mechanical testing protocols between jurisdictions force redundant qualification runs, extending time-to-certification.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Domestic machine assembly incentives attract foreign vendors to establish localized production for medical and aerospace segments.
- Multi-material deposition convergence:Directed energy deposition systems integrate ceramic-metal gradients for turbine blade repair applications.
- Digital inventory models:Spare part on-demand printing compresses aerospace MRO supply chains, with Dubai and Singapore emerging as regional hub locations.
Industry Challenges
- Process control talent scarcity:Thermal profile optimization and powder lot traceability require specialized metallurgists that outpace university pipeline output.
- FAA/EASA parallel qualification timelines:Flight-critical component certification demands simultaneous validation across divergent airworthiness frameworks.
- Legacy ERP integration friction:Additive workflow data formats conflict with established aerospace manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Additive Manufacturing Machines Market |
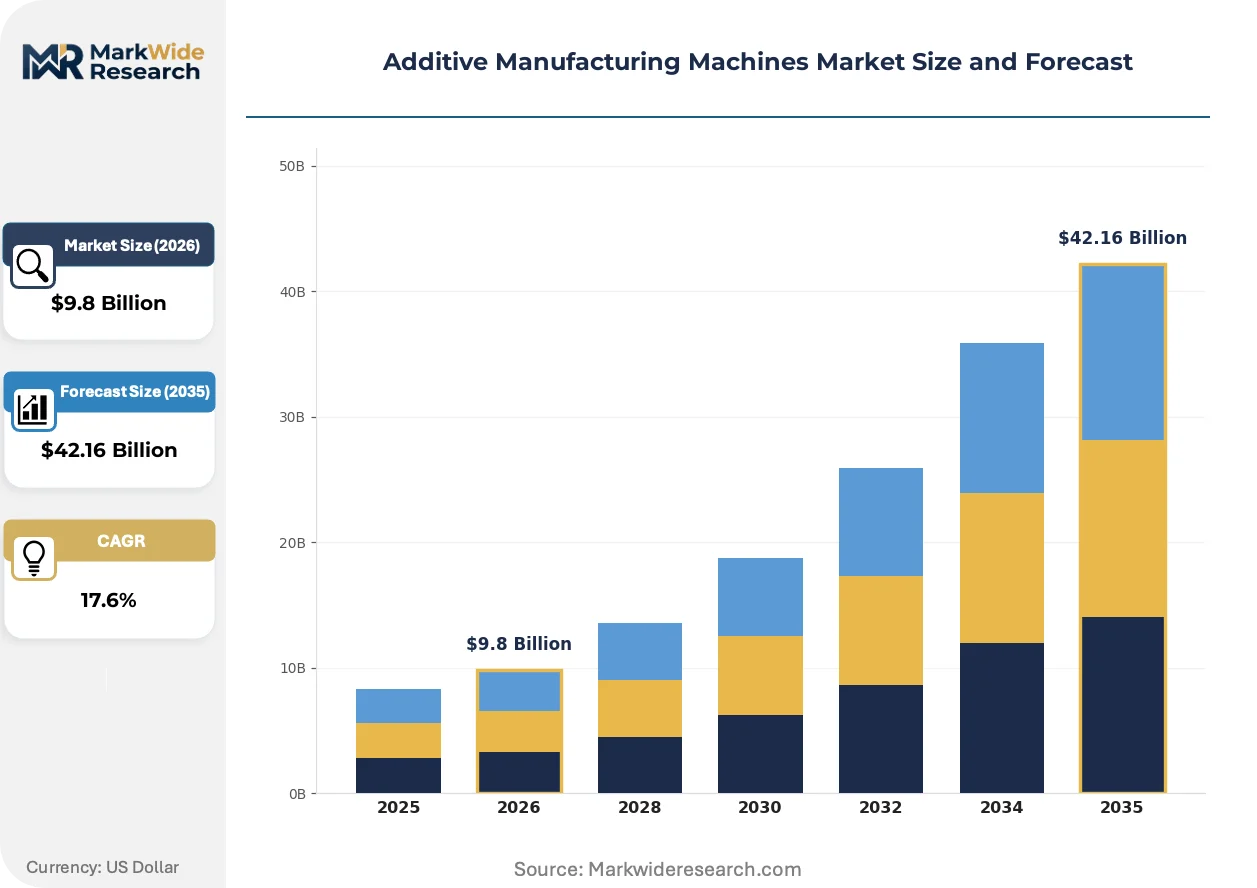
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $42.16 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Electron Beam Melting Application: Aerospace Components, Medical Devices, Automotive Prototypes, Consumer Products Material: Plastic, Metal, Ceramic, Composite End User: Aerospace Industry, Healthcare Sector, Automotive Manufacturing, Electronics |
| Companies Covered | Stratasys Ltd, 3D Systems Corporation, HP Inc., EOS GmbH, GE Additive, DMG MORI, Nikon SLM Solutions AG, Formlabs, Bright Laser Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Additive Manufacturing Machines Market Trends and Innovations
Real-time melt pool monitoring and machine learning feedback loops are compressing defect rates in metal powder-bed systems, while regulatory frameworks harden around process traceability requirements.
Artificial intelligence-driven predictive maintenance is converging with industrial metal printers to reduce unplanned downtime. Tier-one aerospace suppliers in the United States and Germany deploy sensor arrays that feed thermal history data into neural networks. This convergence is compressing qualification timelines for flight-critical components by flagging anomaly signatures before they propagate through build layers.
The EU AI Act imposes risk-classification requirements on automated quality control systems used in medical implant production. Machine vendors must document algorithmic decision pathways for pore architecture validation in orthopedic applications. European orthopedic manufacturers are responding by segregating AI-assisted and conventional inspection workflows to maintain CE marking eligibility under evolving MDR enforcement.
Consignment powder inventory models are displacing traditional feedstock purchasing in high-throughput dental and consumer prototyping segments. North American service bureaus now hold supplier-owned titanium and cobalt-chrome powder stocks, paying only for material consumed. This shift is most visible in California and Texas clusters where Stratasys polymer expertise overlaps with emerging metal service offerings.
Additive Manufacturing Machines Market Segmentation
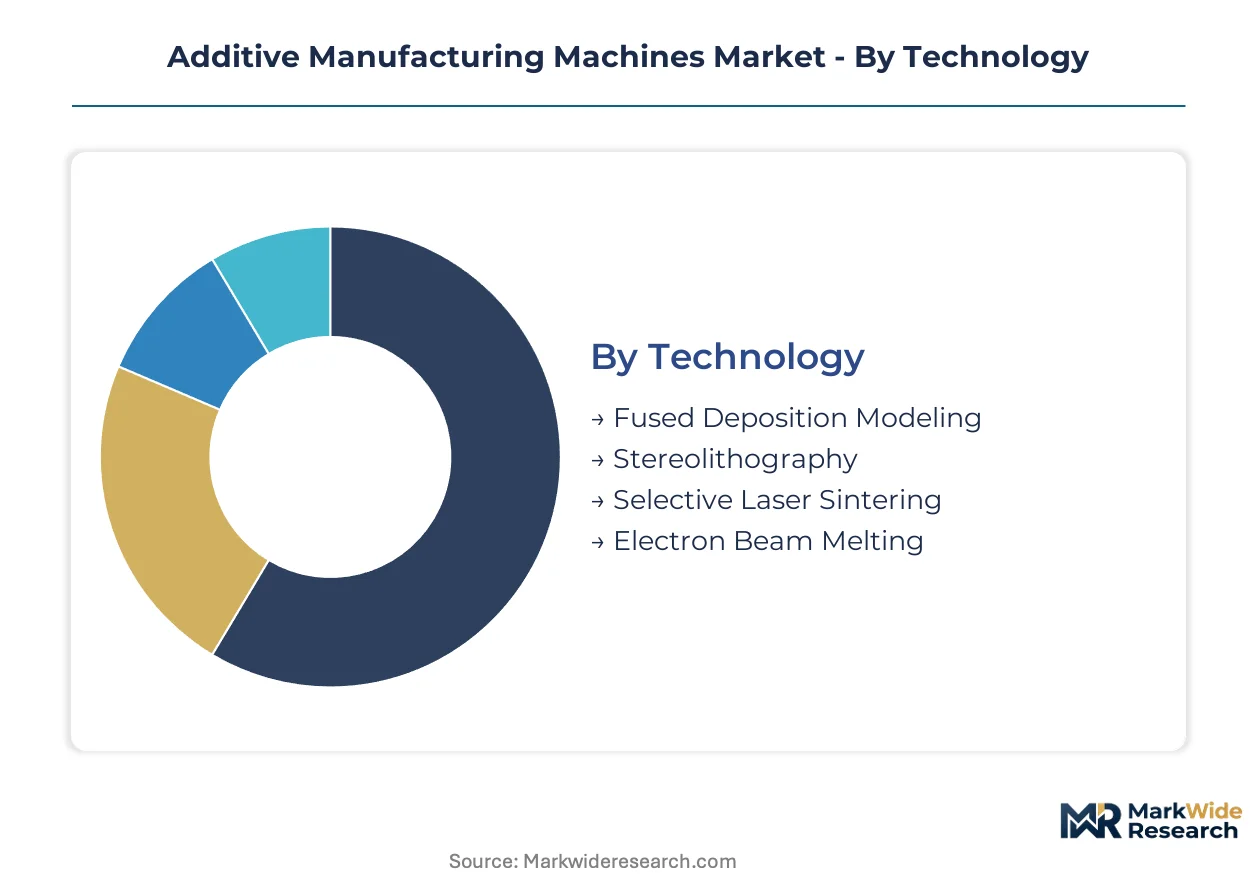
Additive manufacturing machines segment across multiple dimensions that determine capital allocation priorities and qualification timelines. Technology class dictates build envelope and material compatibility. Application focus shapes regulatory exposure and margin structure.
Technology:
Volume deployments cluster around polymer systems with lower qualification barriers, while premium metal architectures command extended certification cycles.
- Selective Laser Sintering:Polymer powder-bed systems dominate installed base volume through versatility across medical device housings and consumer product iterations. Demand concentrates in Shenzhen industrial clusters where MIIT standards accelerate domestic machine procurement for lot-size-flexible production.
- Electron Beam Melting:Vacuum-based metal powder-bed architecture achieves superior density in titanium and nickel superalloy components. Aerospace manufacturers in Germany expand capacity under EASA airworthiness directives mandating validated thermal profiles for structural airframe parts.
- Fused Deposition Modeling:Thermoplastic extrusion systems serve prototyping and tooling applications with minimal facility requirements.
- Stereolithography:Photopolymer vat polymerization delivers finest surface resolution for dental and jewelry master patterns.
Mature deployment sits with Selective Laser Sintering. Newer deployment is concentrated in Electron Beam Melting.
Application:
Regulatory intensity separates flight-critical and implant-grade applications from commercial prototyping segments.
- Aerospace Components:Structural airframe and engine parts require FAA and EASA process qualification across thermal history documentation and powder lot traceability. Manufacturers in the United States and Germany expand metal printer fleets to satisfy airworthiness directives for titanium superalloy brackets and turbine vanes.
- Medical Devices:Orthopedic implants and surgical guides demand pore architecture validation and biocompatibility certification. Powder-bed fusion technologies displace conventional tooling in hip implant production where geometric complexity and patient-specific matching command premium pricing.
- Automotive Prototypes:Functional validation parts compress design iteration cycles without production tooling investment.
- Consumer Products:Customized electronics enclosures and wearables leverage polymer versatility for low-volume differentiation.
Qualification maturity clusters in Medical Devices. Steepest expansion trajectory appears in Aerospace Components.
Material:
Feedstock economics and supply security differentiate commodity polymers from aerospace-grade superalloys.
- Metal:Titanium, aluminum, and nickel superalloy powders command highest unit economics and strictest lot certification. Noble metal powder price volatility with aerospace demand cycles compresses machine utilization economics for tier-two suppliers dependent on spot market purchasing.
- Plastic:Nylon, ABS, and photopolymer resins serve highest throughput segments with established supply chains and predictable pricing.
- Ceramic:Alumina and zirconia feedstocks target dental and biomedical applications requiring biocompatibility and wear resistance.
- Composite:Carbon fiber and glass-filled polymers bridge structural performance and processability for automotive and industrial tooling.
Established supply chains anchor Plastic deployment. Emerging qualification activity concentrates in Metal.
End User:
Customer scale and integration depth separate captive production from service bureau outsourcing models.
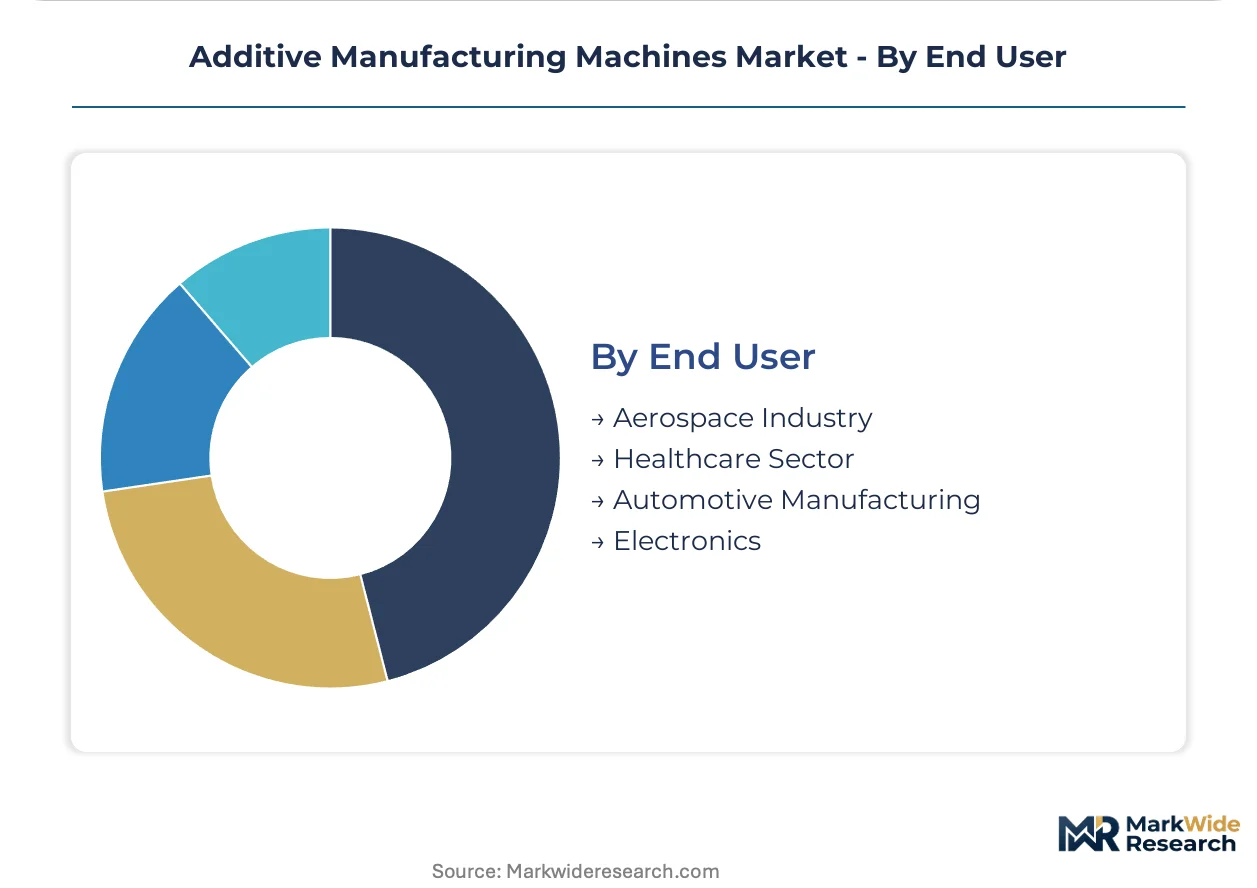
- Aerospace Industry:Tier-one manufacturers deploy in-house metal powder-bed systems to control intellectual property and process validation for flight-critical components. EU Green Deal decarbonization mandates compel retooling away from energy-intensive subtractive methods toward lower-waste fabrication.
- Healthcare Sector:Hospital networks and device manufacturers adopt point-of-care printing for surgical planning and custom implant production. FDA and EMA process validation requirements extend procurement cycles but lock in premium pricing for certified workflows.
- Automotive Manufacturing:OEMs and tier suppliers use polymer systems for design validation and limited custom tooling.
- Electronics:Prototyping labs and contract manufacturers produce enclosures and thermal management components.
Integration maturity sits with Aerospace Industry. Capacity expansion is accelerating fastest in Healthcare Sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German engineering clusters and Chinese industrial zones, while consumption spreads across aerospace hubs in the United States and medical device corridors in Europe. This geographic split shapes capital flows and qualification timelines.
United States
Aerospace manufacturers in Texas and Washington expand electron beam melting capacity for titanium superalloy structural components. FAA process validation protocols mandate thermal history documentation across build cycles. The Seattle-Tacoma industrial corridor hosts tier-one suppliers retooling for flight-critical additive production under airworthiness directives.
Germany
Tier-one automotive and aerospace suppliers in Bavaria and Baden-Württemberg deploy metal powder-bed systems to meet EU Green Deal decarbonization thresholds. EASA airworthiness frameworks drive process qualification for structural airframe parts. The Munich engineering base anchors European high-precision metal system supply with concentrated vendor engineering talent.
China
Domestic machine procurement accelerates around Shenzhen and Shanghai industrial clusters where MIIT national standards constrain import eligibility. Aerospace and medical device manufacturers qualify locally produced powder-bed systems for titanium implant and bracket production. The Yangtze River Delta hosts the fastest capacity expansion for metal-directed energy deposition systems.
Japan
Precision manufacturers in the Nagoya and Osaka industrial zones integrate additive systems for turbine component repair and dental implant production. METI industrial technology roadmaps prioritize multi-material deposition capabilities. The Chubu region concentrates electron beam melting adoption for orthopedic applications requiring pore architecture control.
India
Medical device and aerospace segments drive machine demand in Maharashtra and Karnataka under PLI scheme incentives for advanced manufacturing assembly. CDSCO and BIS certification requirements shape procurement specifications for imported metal systems. The Pune-Bengaluru corridor attracts foreign vendors establishing localized production for regional supply.
Additive Manufacturing Machines Market Competitive Landscape
The competitive structure tilts toward technology-specialized engineering houses over diversified industrial conglomerates. Vendor concentration remains moderate, with premium metal powder-bed architectures controlled by a handful of European and American engineering specialists. Two strategic archetypes dominate: integrated aerospace-industrial platforms with captive process validation capabilities, and pure-play system vendors focused on modular platform architectures. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as vendors race to qualify architectures under divergent regulatory frameworks.
Within the European engineering specialist tier, EOS GmbH and Nikon SLM Solutions AG exemplify the Munich-based metal powder-bed tradition, while GE Additive occupies a position bridging industrial platform integration and proprietary electron beam architecture. Stratasys Ltd anchors the polymer system segment with North American dental and prototyping penetration. These three companies represent distinct competitive archetypes: the precision engineering house, the industrial conglomerate additive division, and the polymer platform specialist.
| Leading Market Players |
|---|
| Stratasys Ltd |
| 3D Systems Corporation |
| HP Inc. |
| EOS GmbH |
| GE Additive |
| DMG MORI |
| Nikon SLM Solutions AG |
| Formlabs |
| Bright Laser Technologies |
| Others |
Pricing and Supply Chain Analysis
Specialized metallurgists in Bavaria and Baden-Württemberg command wage premiums that propagate through machine pricing tiers, widening spreads between European-engineered metal powder-bed systems and Asian-assembled alternatives.
Pricing Analysis
Margin tightening in mid-tier metal systems reflects titanium superalloy powder volatility and redundant ISO/ASTM qualification runs across jurisdictions. Three-tier pricing structure across premium, standard, and economy levels separates EASA-validated architectures from MIIT-certified domestic machines and unqualified prototyping equipment. Aerospace OEMs show lowest price sensitivity given captive process validation requirements, while dental service bureaus in California and Texas clusters negotiate consignment powder terms that shift working capital burden upstream.
Supply Chain Analysis
Certification gating through FAA and EASA airworthiness directives concentrates high-precision metal powder-bed supply in Germany and the United States, with emerging qualification activity in China under MIIT standards. Machine architecture draws from Munich-based engineering talent, Japanese precision components, and Chinese rare-earth magnet supplies. Single-source vulnerability in European electron beam melting optics creates structural risk. Distribution runs through direct vendor sales for tier-one aerospace and authorized service bureau networks for medical prototyping segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FAA and EASA process validation requirements erect barrier-to-entry moats that favor incumbents with existing qualification dossiers.
For Market Incumbents: Acquire specialized metallurgical talent pools in Germany and the United States to defend against process control scarcity. Deepen backward integration into noble metal powder supply through long-term offtake agreements with titanium and nickel superalloy producers, insulating utilization economics from aerospace demand cycles.
For New Entrants and Emerging Players: Begin with India's PLI scheme incentives for advanced manufacturing assembly in Maharashtra and Karnataka, where CDSCO and BIS certification requirements remain less stringent than FAA equivalents. Target point-of-care medical printing in hospital networks, leveraging lower regulatory intensity than flight-critical aerospace components.
For Investors and Strategic Acquirers: Re-rating potential sits with pure-play electron beam melting specialists given titanium superalloy qualification acceleration under FAA protocols. Long-term viability hinges on sustained aerospace capital expenditure and harmonized ISO/ASTM testing frameworks. Monitor EASA-MIIT mutual recognition negotiations as inflection signal for Chinese market access premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Process Validation Investment | FAA and EASA qualification dossiers lock in tier-one aerospace procurement relationships for flight-critical components. |
| Powder Supply Integration | Captive titanium and nickel superalloy feedstock secures machine utilization economics against noble metal price volatility. |
| Regional Assembly Localization | MIIT-certified production in Shenzhen and Shanghai industrial clusters unlocks domestic Chinese procurement specifications. |
| AI-Assisted Quality Control | EU AI Act compliance for automated pore validation preserves CE marking eligibility under evolving MDR enforcement. |
| Digital Inventory Partnership | On-demand spare part printing contracts with Dubai and Singapore MRO hubs compress aerospace aftermarket supply chains. |
Research Methodology
Independent corroboration across machine vendor technical documentation, aerospace OEM procurement specifications, and national regulator filings underwrites the qualitative findings. Primary interviews with additive manufacturing process engineers, aerospace tier-one supplier procurement leads, orthopedic implant quality directors, and metal powder feedstock specialists combined with secondary validation from FAA airworthiness directives, EASA certification databases, MIIT national standards publications, and ISO/ASTM mechanical testing protocols. Bottom-up installed base estimates and top-down capital expenditure triangulation anchored market sizing.
Comparable-period anchoring to historical aerospace production cycles and medical device approval timelines shaped the projection horizon. The analytical framework modeled technology class, application focus, material feedstock type, and end-user integration depth across the analysis window. CAGRs derived from qualification timeline compression rates and regional regulatory harmonization progress. Forecast inputs incorporated electron beam melting capacity expansion announcements and PLI scheme incentive disbursement patterns.
Underlying measurement precision varies by segment; aerospace components with established FAA validation carry tighter precision than emerging medical point-of-care applications. Forecasts reflect assumptions about EASA-MIIT mutual recognition timeline and sustained EU Green Deal decarbonization enforcement. A model refresh is warranted upon material change in noble metal powder spot market dynamics or ISO/ASTM protocol harmonization acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Food 3D Printing Market
3D Printing Technology
US Additive Manufacturing Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
Global 4D Printing in Healthcare Market
3D Printing Technology
Additive Manufacturing Platform Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
North America 3D Printing Market