
 North America Industrial 3D Printing Market | 2026-2036
North America Industrial 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial 3D Printing Market Insights
The North America industrial 3D printing landscape is rebalancing between premium metal systems serving aerospace qualification requirements and commodity polymer platforms filling prototyping workflows. 3D Systems, Inc. leverages its deep vertical integration across hardware, materials, and software to sustain pricing power in dental and medical device applications. Stratasys Ltd. anchors its position through extensive polymer technology breadth and established service bureau relationships across the region. HP Inc. competes on production speed with its Multi Jet Fusion platform, targeting automotive OEMs seeking bridge-to-production volumes.
North America industrial 3D printing encompasses additive manufacturing systems that build functional components through layer-by-layer deposition of metals, polymers, ceramics, or composites using directed energy or binding processes, typically achieving tolerances of ±0.1 mm to ±0.3 mm depending on technology and material. These systems serve industrial end users by enabling geometric complexity, lot-size flexibility, and supply chain compression that subtractive methods cannot replicate. Metal product types command the deepest qualification barriers and longest sales cycles, yet capture the highest installed-base value per unit across aerospace and medical implant applications. Polymer technologies including Fused Deposition Modeling and Selective Laser Sintering dominate unit shipments, though Stereolithography retains critical positioning in dental aligner and hearing aid manufacturing where surface finish precision determines adoption. The production parts application segment is outpacing prototyping in year-over-year expansion as qualification methodologies mature and repeatability data accumulates across regulated industries.
FAA airworthiness directives, FDA 21 CFR Part 820 quality system regulations, and OSHA combustible dust standards collectively shape equipment design, facility requirements, and market access pathways for industrial 3D printing operators across the United States. The EPA's emerging framework for metal powder handling and waste classification is adding compliance layers that favor established vendors with dedicated environmental health and safety infrastructure. Stakeholders must monitor how NIST measurement science advances and ANSI standardization efforts around process qualification will determine which technology platforms achieve regulatory acceptance for safety-critical applications.
Market Dynamics
The FAA's evolving airworthiness certification pathway for additively manufactured aerospace components is compressing qualification timelines and redrawing competitive boundaries between metal system vendors and their polymer counterparts across the United States and Canada.
Growth Catalysts
- FAA Certification Streamlining:The administration's accelerated pathway for flight-qualified metal parts is pulling aerospace OEMs toward production-scale additive investments in the Great Lakes corridor.
- Great Lakes Industrial Concentration:Michigan, Ohio, and Illinois manufacturers are clustering advanced metal powder bed fusion capacity to serve tier-one automotive and aerospace supply chains.
- Medical Implant Geometric Complexity:Patient-specific lattice structures for orthopedic and cranial applications are driving titanium and cobalt-chrome powder demand through FDA 21 CFR Part 820 regulated facilities.
Market Restraints
- Metal Powder Supply Concentration:Spherical titanium and nickel superalloy feedstock production concentrates among a handful of plasma atomization suppliers, creating input cost volatility for system operators.
- OSHA Combustible Dust Compliance:Facility modifications for aluminum and titanium powder handling are adding six-figure capital burdens that disqualify smaller job shops from metal system adoption.
- CNC Machining Substitution:Five-axis milling centers with adaptive tooling are retaining cost advantages for non-complex geometries below 500-unit production runs.
Strategic Opportunities
- Canada Defense Procurement:The country's national aerospace regulator is developing parallel qualification frameworks to FAA standards, opening military component sourcing to domestic additive suppliers.
- Distributed Spare Parts Networks:Forward-deployed metal printing cells at airline maintenance hubs are compressing AOG turnaround times for legacy aircraft obsolescence parts.
- Polymer-Ceramic Hybrid Systems:Silicon carbide-reinforced photopolymer platforms are penetrating semiconductor thermal management applications previously served by machined aluminum.
Industry Challenges
- Process Control Engineering Talent:The shortage of technicians trained in melt pool monitoring, thermal simulation, and in-situ metrology is constraining qualified machine utilization rates.
- Multi-Site Certification Complexity:Medical device manufacturers face redundant FDA facility inspections when replicating qualified additive processes across Michigan and Ohio production sites.
- Legacy ERP Integration:Shop floor data from closed-loop additive systems lacks standardized interfaces with incumbent manufacturing execution software, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial 3D Printing Market |
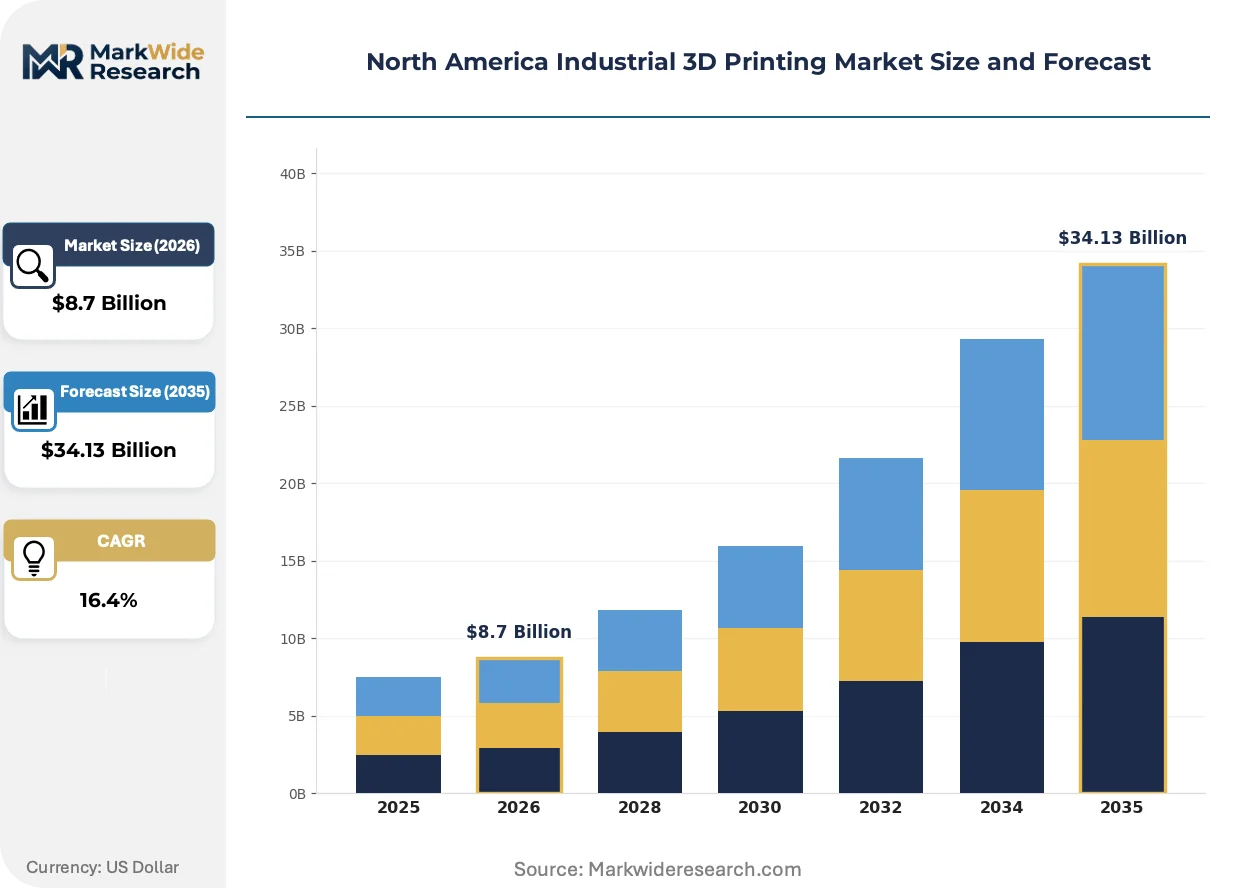
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, Polymer, Ceramic, Composite Technology: Fused Deposition Modeling, Selective Laser Sintering, Stereolithography, Digital Light Processing End User: Aerospace, Automotive OEMs, Consumer Electronics, Healthcare Application: Prototyping, Tooling, Production Parts, Customization |
| Companies Covered | 3D Systems, Inc., Stratasys Ltd., HP Inc., Carbon, Inc., Proto Labs Inc., Materialise NV, Desktop Metal, Velo3D, Formlabs Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial 3D Printing Market Trends and Innovations
Real-time process monitoring and closed-loop parameter adjustment are displacing open-loop build recipes across safety-critical applications, while regulatory data packages become the primary competitive differentiator.
Artificial intelligence-driven defect prediction is integrating thermal imaging, acoustic emission, and melt pool signature analysis into unified feedback architectures. Aerospace primes in the United States are piloting these systems for nickel superalloy turbine blade repairs, compressing post-build inspection cycles from days to hours. The technology is integrating quality assurance directly into the build process rather than treating it as a downstream gate.
Health Canada's parallel track for medical device additive manufacturing is harmonizing with FDA 21 CFR Part 820 quality system requirements, creating a unified North American regulatory corridor. Canadian orthopedic implant manufacturers are leveraging this alignment to access US reimbursement pathways without redundant validation studies. Dental aligner production facilities in Ontario are consolidating software validation documentation to satisfy both jurisdictions simultaneously.
Consolidated procurement of additive capacity through tier-one aerospace distributors is displacing direct OEM-to-printer-vendor relationships. United Airlines and Delta Air Lines are routing spare part printing contracts through Honeywell and GE Aviation service networks rather than maintaining captive powder bed fusion operations. This channel concentration is most visible in the US Southwest maintenance hub corridor spanning Texas and Arizona.
North America Industrial 3D Printing Market Segmentation
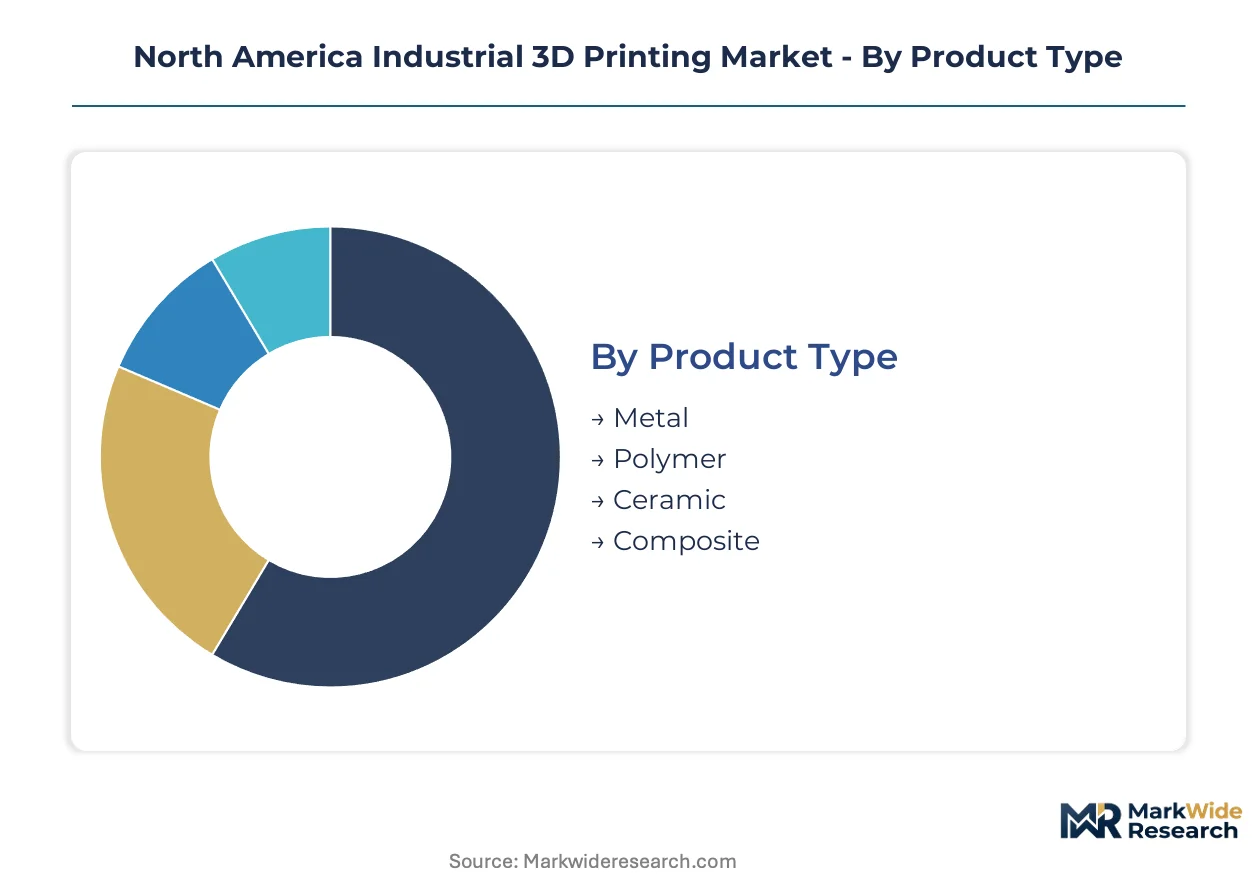
Industrial 3D printing segments diverge sharply between high-qualification metal systems and high-volume polymer platforms. Each category reveals distinct competitive dynamics shaped by regulatory barriers, geometric complexity requirements, and supply chain positioning across the United States and Canada.
Product Type:
Metal systems command premium installed-base value despite lower unit volumes, while polymer platforms dominate shipment counts through prototyping workflows.
- Metal:Powder bed fusion systems deposit titanium, nickel superalloys, and aluminum through directed energy processes achieving ±0.1 mm tolerances. Aerospace manufacturers in Michigan and Ohio are clustering flight-certified capacity to serve FAA qualification pathways for turbine blades and structural brackets.
- Polymer:Fused deposition modeling and selective laser sintering platforms process ABS, nylon, and polypropylene for geometrically complex housings and ducting. Automotive OEMs in the Great Lakes corridor deploy these systems for bridge-to-production volumes where tooling lead times exceed part value.
- Ceramic:Oxide and non-oxide ceramic systems serve semiconductor thermal management and biomedical implant applications requiring biocompatibility and dielectric stability.
- Composite:Continuous fiber-reinforced deposition systems embed carbon or glass fibers within thermoplastic matrices for aerospace brackets and automotive structural nodes.
Mature deployment sits with Polymer systems in prototyping bureaus. Newer deployment is concentrated in Metal systems for production aerospace components.
Technology:
Process selection tracks surface finish requirements against build speed economics, with photopolymer platforms retaining critical positioning where aesthetic precision determines adoption.
- Fused Deposition Modeling:Extrusion-based systems deposit thermoplastic filament through heated nozzles, offering the lowest capital entry point. Consumer electronics manufacturers in California and Texas deploy these for functional prototyping and jigs.
- Selective Laser Sintering:CO2 laser systems fuse nylon and TPA powder beds without support structures, enabling complex geometries for automotive ducting and medical device housings. SLS capacity is expanding fastest among polymer technologies for production part applications.
- Stereolithography:UV laser systems polymerize liquid resin with sub-25 micron layer resolution. Dental aligner manufacturers in Ontario and hearing aid producers in Minnesota rely on SLA surface quality for patient-facing devices.
- Digital Light Processing:Projector-based photopolymer systems achieve faster layer times than SLA through masked exposure. Jewelry and dental labs in New York and Illinois are adopting DLP for small-batch customization workflows.
Established deployment clusters around Fused Deposition Modeling in service bureaus. Steepest expansion trajectory belongs to Selective Laser Sintering for bridge manufacturing.
End User:
Customer concentration reflects sector-specific qualification maturity, with regulated industries demanding deeper process validation than consumer-facing applications.
- Aerospace:Boeing, Lockheed Martin, and Pratt & Whitney drive nickel superalloy and titanium powder demand through FAA-certified production programs. Great Lakes suppliers are qualifying laser powder bed fusion for flight-critical brackets and fuel nozzles.
- Automotive OEMs:Ford, General Motors, and Stellantis deploy polymer systems for tooling and low-volume interior components. Metal additive adoption concentrates in motorsport and luxury vehicle powertrain applications.
- Consumer Electronics:Apple, Microsoft, and regional device manufacturers use polymer prototyping for ergonomic validation and thermal management enclosures.
- Healthcare:Stryker, Zimmer Biomet, and Canadian orthopedic specialists are scaling titanium cranial and spinal implants through FDA and Health Canada parallel pathways.
Regulatory deployment concentrates in Aerospace and Healthcare. Volume deployment scales fastest in Automotive OEMs for non-critical applications.
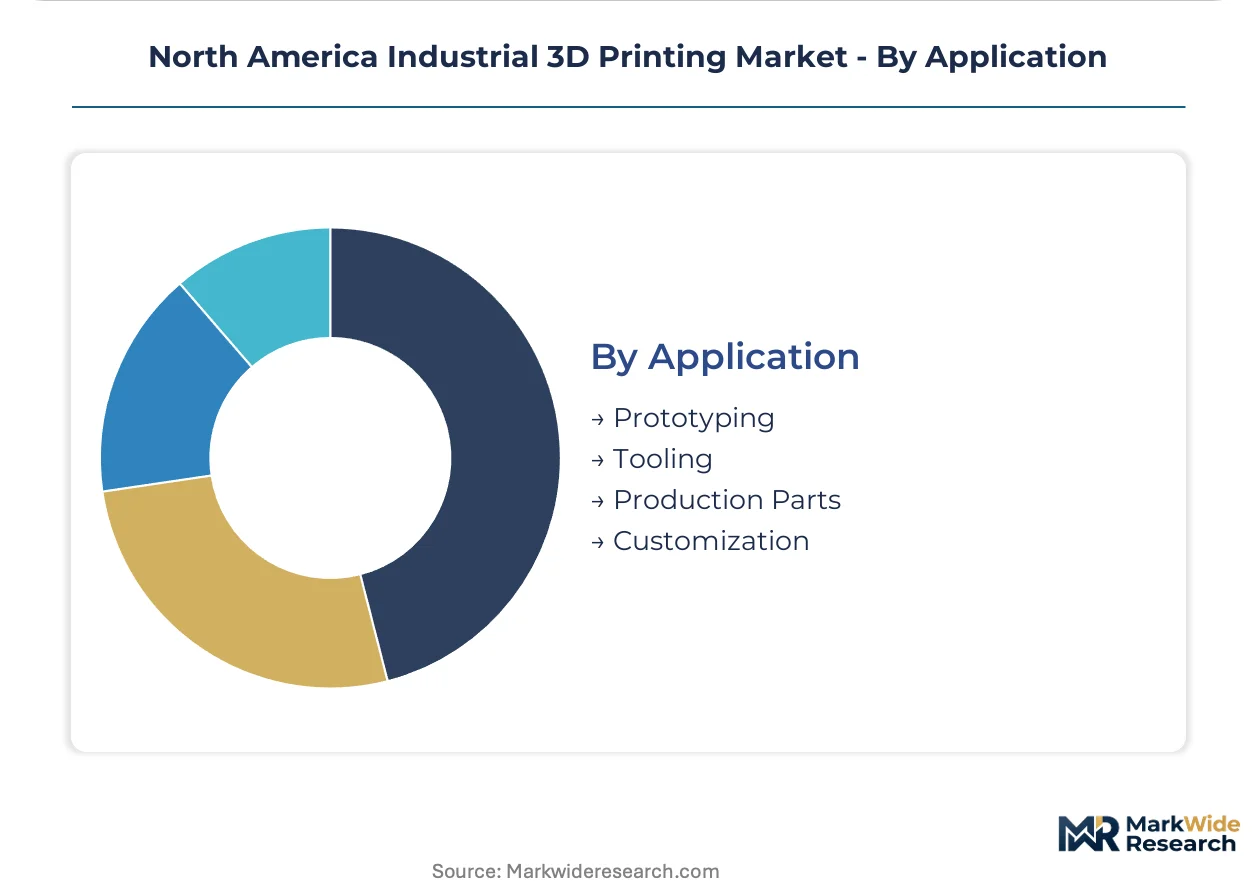
Application:
Use case evolution tracks industry maturity, with production parts gaining share as repeatability data accumulates across regulated sectors.
- Prototyping:Design validation and form-fit testing remain the dominant entry application across all technologies. Polymer systems capture the majority of unit demand in this category.
- Tooling:Conformal cooling channels in injection molds and composite layup fixtures represent high-value metal applications. Automotive suppliers in Ohio are deploying printed tooling to compress mold lead times.
- Production Parts:Flight-certified aerospace brackets, FDA-cleared spinal implants, and automotive interior components are shifting from qualification to recurring revenue. This application is gaining share fastest as process control matures.
- Customization:Patient-specific surgical guides, dental aligners, and luxury automotive trim reflect lot-size-one economics enabled by additive geometries.
Volume concentration remains in Prototyping. Margin expansion concentrates in Production Parts as qualification barriers filter competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes industrial corridor spanning Michigan, Ohio, and Illinois anchors North American additive manufacturing capacity, clustering aerospace-qualified metal powder bed fusion systems alongside automotive polymer prototyping hubs.
United States
Boeing, Lockheed Martin, and Pratt & Whitney drive nickel superalloy demand through FAA-certified production programs for turbine blades and structural brackets. The FAA's accelerated airworthiness pathway compresses qualification timelines for flight-critical components. Michigan and Ohio manufacturers concentrate laser powder bed fusion capacity to serve tier-one aerospace supply chains.
Canada
Health Canada's parallel medical device framework harmonizes with FDA 21 CFR Part 820 requirements, enabling Ontario orthopedic implant manufacturers to access US reimbursement pathways. The national aerospace regulator develops qualification standards mirroring FAA protocols. Toronto-area dental aligner production facilities consolidate software validation documentation for dual-jurisdiction compliance.
Mexico
Automotive OEMs in Nuevo León and the Bajío Region deploy polymer additive systems for tooling and low-volume interior component production. The Secretariat of Economy's advanced manufacturing incentives support maquiladora adoption of bridge-to-production technologies. Querétaro's aerospace cluster attracts metal system investments serving North American supply chain integration.
North America Industrial 3D Printing Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology vectors. The market structures around three tiers: vertically integrated hardware-materials-software stacks, pure-play equipment vendors, and distributed service bureau networks. Strategic differentiation concentrates on regulatory data package depth for aerospace qualification and production throughput metrics for automotive bridge manufacturing. Consolidation pressures favor vendors with captive powder supply chains and multi-site certification infrastructure.
Within the integrated systems tier, 3D Systems, Inc. and Stratasys Ltd. occupy positions defined by vertical technology stacks spanning hardware, materials, and software domains. HP Inc. represents the production-scale vector targeting automotive OEMs with speed-centric platforms. These three anchors illustrate how competitive positioning diverges between qualification-depth and throughput-velocity strategies across the North American installed base.
| Leading Market Players |
|---|
| 3D Systems, Inc. |
| Stratasys Ltd. |
| HP Inc. |
| Carbon, Inc. |
| Proto Labs Inc. |
| Materialise NV |
| Desktop Metal |
| Velo3D |
| Formlabs Inc. |
| Others |
Pricing and Supply Chain Analysis
EPA metal powder handling mandates gate qualified supply access and premium-tier pricing power for vendors with dedicated environmental health and safety infrastructure. Buyers without compliant facilities face six-figure capital burdens that disqualify them from metal system adoption, compressing demand toward established operators who capture pricing premiums through regulatory data package depth.
Pricing Analysis
Throughput-guaranteed service contracts anchor value-based pricing for production-scale metal powder bed fusion systems. Three-tier pricing structure across FAA-certified premium, production-validated standard, and prototyping economy levels separates aerospace qualification depth from automotive bridge volumes. Cost compression in economy-tier polymer platforms intensifies as HP and Carbon compete on speed metrics. Tier-one aerospace OEMs exhibit lowest price sensitivity, while job shops in the Great Lakes corridor face acute margin pressure from OSHA combustible dust compliance requirements.
Supply Chain Analysis
Dual-sourcing requirements for spherical titanium and nickel superalloy feedstock mandate multi-supplier qualification among plasma atomization specialists in the United States, Germany, and Canada. Raw material dependencies center on argon gas supply, high-purity metal ingots, and ceramic crucibles for atomization. Single-source vulnerability concentrates in plasma atomization capacity for nickel superalloys. Distribution runs through tier-one aerospace distributors including Honeywell and GE Aviation service networks rather than direct OEM-to-vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA 21 CFR Part 820 quality system regulations create a cost-of-compliance moat that filters competition toward vendors with multi-site certification infrastructure. This regulatory barrier protects qualified incumbents while raising entry costs for challengers seeking safety-critical applications.
For Market Incumbents: Acquire captive powder production assets to secure feedstock cost control against plasma atomization supply concentration. Lockheed Martin and Pratt & Whitney's qualification requirements favor vendors with backward integration into spherical titanium supply. Channel control through Honeywell and GE Aviation distributor networks defends position against emerging metal system vendors. For New Entrants and Emerging Players: Mid-tier automotive suppliers in Ohio and Illinois represent an underserved buyer archetype seeking bridge-to-production polymer capacity without aerospace qualification overhead. Semiconductor thermal management applications for silicon carbide-reinforced photopolymers offer the most penetrable white space. A equipment-as-a-service go-to-market angle bypasses capital constraints among regional job shops. For Investors and Strategic Acquirers: Health Canada's harmonization with FDA 21 CFR Part 820 requirements is the leading indicator that Canadian orthopedic implant manufacturers will consolidate toward dual-jurisdiction-capable platforms. Long-term viability favors vertically integrated hardware-materials-software stacks with captive powder supply chains. The signal to watch is tier-one aerospace distributor procurement consolidation shifting contract flow toward qualified vendor networks.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Powder Supply Integration | Backward integration into spherical titanium production locks in feedstock cost control for FAA-certified operators. |
| Multi-Site Certification Infrastructure | FDA facility inspection readiness across Michigan and Ohio production sites accelerates medical implant revenue scaling. |
| Real-Time Process Monitoring Deployment | AI-driven defect prediction compresses post-build inspection cycles from days to hours for nickel superalloy repairs. |
| Distributor Channel Consolidation | Honeywell and GE Aviation service networks concentrate spare parts procurement away from captive OEM operations. |
| Dual-Jurisdiction Regulatory Alignment | Health Canada-FDA harmonization enables Ontario manufacturers to access US reimbursement pathways without redundant validation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with additive manufacturing plant managers, aerospace procurement leads at Boeing and Lockheed Martin, FDA regulatory affairs specialists, and powder metallurgy R&D directors combined with FAA airworthiness directives, EPA metal powder handling guidance, and NIST measurement science publications. Bottom-up installed base counts and top-down industrial capex flows were triangulated to validate market sizing.
Data-stream reconciliation across hardware shipment databases, materials consumption tracking, and service bureau revenue disclosures shaped the analytical framework. Segmentation dimensions modeled include product type, technology platform, end-user industry, application maturity, and regional regulatory cluster. CAGRs were derived from curve-fitting qualification timeline acceleration and production part adoption trajectories. Forecast inputs incorporated FAA certification pathway evolution and Health Canada harmonization progress.
Revisions become necessary when EPA metal powder waste classification rules tighten, FAA qualification timelines extend, or plasma atomization capacity constraints materialize. Deviation in aerospace OEM procurement consolidation toward distributor channels would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Metal 3D Printing Service Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
3D Printer Market
3D Printing Technology
3D Printing Market
3D Printing Technology
4D Printing Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Hybrid Additive Manufacturing Machine Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
Conventional and Rapid Prototyping Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
Europe 3D Printing Market