
 Automotive 3D Printing Consumables Market | 2026-2036
Automotive 3D Printing Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive 3D Printing Consumables Market Insights
Direct supply relationships between powder producers and automotive OEMs is tilting away from traditional distributor networks. EOS GmbH leverages its European installed base to sustain premium metal powder contracts with German automakers. Hoganas AB anchors ferrous powder supply for structural powertrain components through captive smelting capacity. Markforged Inc. competes in chopped carbon fiber filament for jigs and fixtures, occupying a defensible niche below aerospace-grade pricing tiers.
Automotive 3D printing consumables encompass feedstock materials engineered to specific particle size distributions, melt flow indices, and thermal stability thresholds for layer-by-layer consolidation into vehicle components. These materials must achieve tensile strength and dimensional accuracy standards specified by OEM qualification protocols for functional prototyping and serial production. Powder-based metal alloys currently lead value capture in the material dimension, while composite filaments represent the fastest-expanding segment for tooling and fixturing applications. Thermoplastics remain the mature volume base for design verification and concept modeling across OEM design centers.
EPA oversees volatile organic compound emissions from resin curing operations in US additive manufacturing facilities, while REACH restricts candidate substance usage in European polymer formulations. OEM qualification standards from NHTSA for crash-relevant printed components are extending material certification timelines and raising barriers for unapproved suppliers. Stakeholders must monitor evolving performance benchmarks for recycled and bio-based feedstocks as sustainability criteria penetrate procurement specifications.
Market Dynamics
OEM qualification protocols for production-grade printed components are compressing supplier approval timelines while simultaneously raising material traceability requirements. Powder producers now face dual pressure from automakers demanding batch-level certification and from REACH substance restrictions tightening formulation flexibility.
Growth Catalysts
- EU Green Deal material mandates:Sustainability criteria are penetrating automotive procurement specifications, creating pull for recycled and bio-based feedstocks that meet performance thresholds.
- Powertrain electrification:Thermal management components for battery housings and electric motor mounts require aluminum and copper alloys optimized for additive consolidation.
- German manufacturing density:Stuttgart and Munich clusters concentrate both automotive OEM engineering centers and powder bed fusion equipment installed base.
Market Restraints
- Noble metal powder volatility:Titanium and nickel superalloy feedstock costs fluctuate with aerospace demand cycles, squeezing automotive supplier margins.
- Smelting concentration risk:Ferrous powder production anchors in Nordic captive capacity, exposing buyers to single-source geographic dependency.
- Layer thickness limitations:Current laser powder bed fusion systems face throughput ceilings for components exceeding 400mm in Z-axis dimension.
Strategic Opportunities
- India PLI scheme alignment:Component localization incentives for electric vehicle manufacturing create entry points for metal powder qualification with domestic OEMs.
- Closed-loop powder recycling:Unfused material recovery systems reduce effective feedstock cost per part while satisfying circular economy procurement criteria.
- Digital inventory convergence:Cloud-based spare part file libraries paired with distributed printing networks are compressing aftermarket supply chains.
Industry Challenges
- Metallurgical technician scarcity:Qualified personnel for powder characterization and process parameter optimization remain concentrated in German and US industrial clusters.
- NHTSA crash-relevant certification:Safety-critical component approval timelines extend 18-24 months, freezing supplier switching decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive 3D Printing Consumables Market |
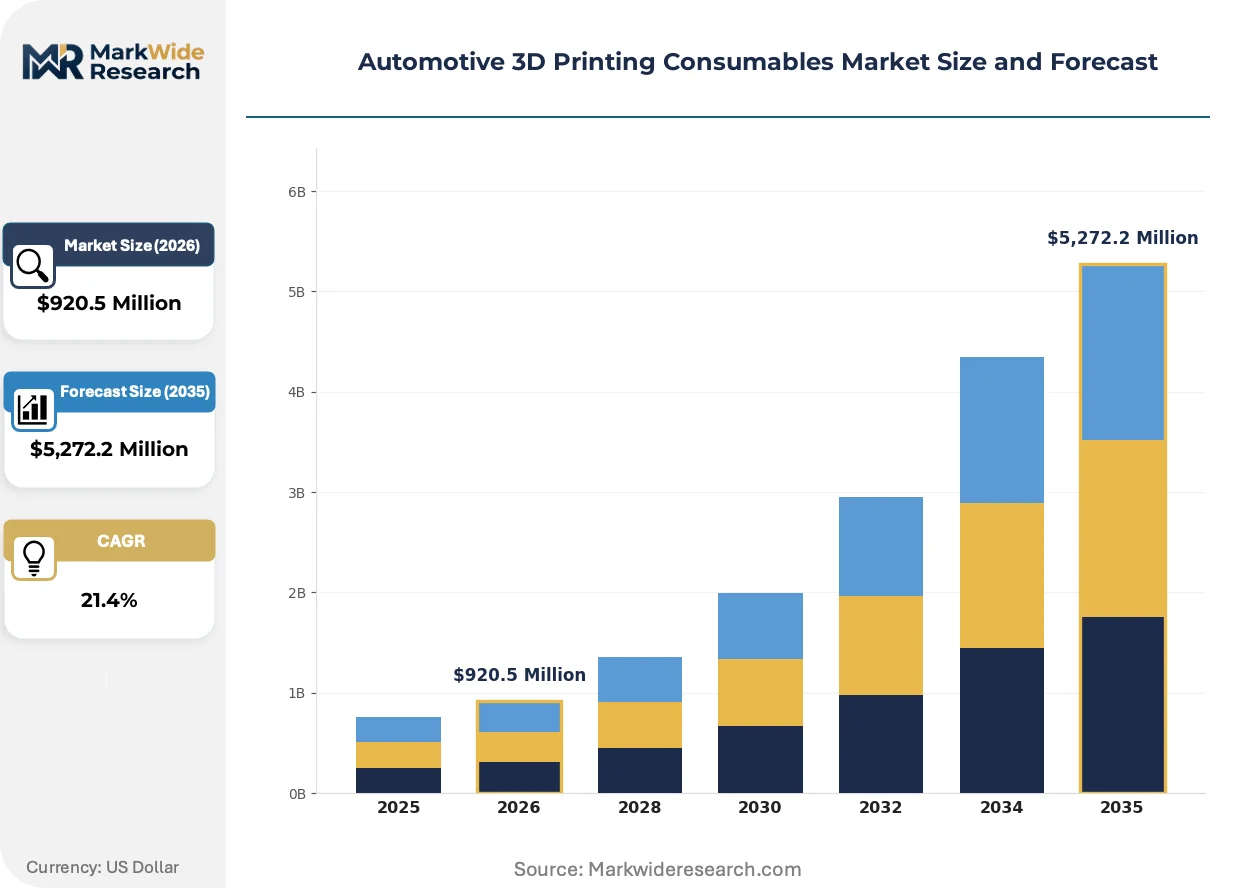
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $5,272.2 Million |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament, Resin, Powder, Liquid Material: Thermoplastics, Metals, Ceramics, Composites Application: Prototyping, Tooling, Production Parts, Custom Components End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Design Firms |
| Companies Covered | Stratasys Ltd, 3D Systems Corporation, EOS GmbH, HP Inc., Materialise NV, BASF Forward AM, Hoganas AB, Markforged Inc., Sandvik AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive 3D Printing Consumables Market Trends and Innovations
Multi-laser powder bed fusion architectures are virtualizing traditional tooling economics while regulatory frameworks harden around material provenance. These forces are reshaping how consumables suppliers structure qualification partnerships and geographic deployment.
High-speed sintering of polymer composites is virtualizing conventional injection molding for jigs, fixtures, and interior trim components. Tier 1 suppliers in Germany and Japan are adopting these systems at pilot scale for production volumes below 10,000 units annually. The technology is virtualizing the break-even threshold between additive and subtractive manufacturing for medium-complexity geometries.
REACH candidate substance restrictions are forcing reformulation of photopolymer resins used in dashboard prototyping and lighting lens verification. ECHA scrutiny of sensitizing monomers is extending material requalification cycles and raising R&D overhead for European formulators. Automotive design centers in France and Italy are accelerating shifts to powder-based alternatives to preempt compliance discontinuities.
Direct powder purchasing contracts are displacing distributor intermediaries for high-volume OEM programs. German automakers now negotiate annual tonnage commitments directly with smelters for aluminum and tool steel grades, bypassing regional material resellers. This pattern concentrates procurement leverage with buyers possessing in-house metallurgical laboratories and statistical process control capabilities.
Automotive 3D Printing Consumables Market Segmentation
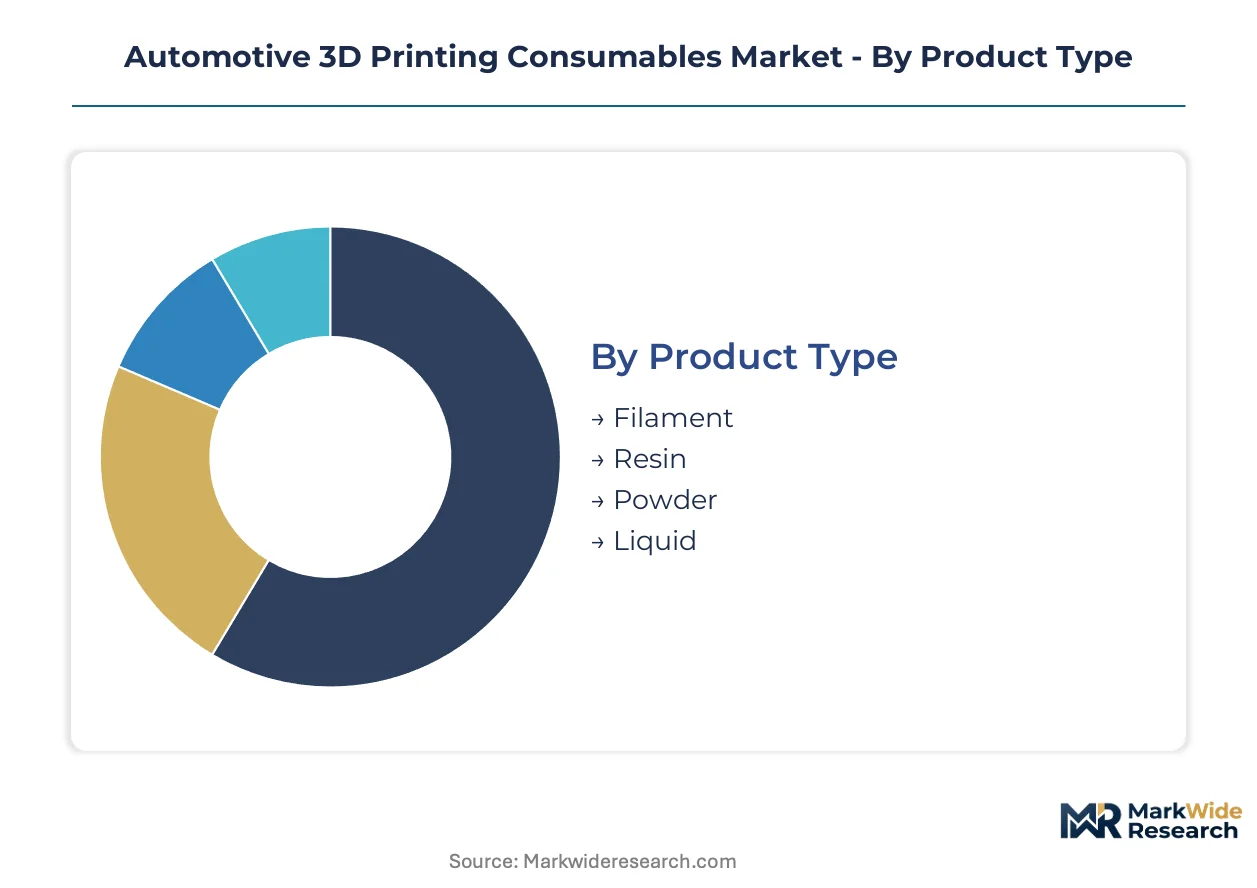
Automotive 3D printing consumables segment across material chemistry, application intensity, and buyer sophistication. Each dimension carries distinct qualification protocols and margin structures that reshape supplier strategy.
Product Type:
Product type captures the physical state of feedstock entering deposition systems, with each format demanding specialized handling infrastructure and environmental controls.
- Powder:Atomized metal and polymer particles engineered to tight particle size distributions for laser and electron beam fusion systems. German OEMs in Stuttgart and Munich clusters anchor demand for aluminum and tool steel grades, driven by powertrain electrification requiring thermal management components. REACH substance restrictions tighten formulation flexibility for European suppliers.
- Filament:Extruded thermoplastic and composite strands fed through fused deposition modeling equipment. Chopped carbon fiber variants for jigs and fixtures concentrate demand among Tier-1 suppliers seeking aerospace-grade performance below premium pricing tiers. Material traceability requirements compress supplier approval timelines.
- Resin:Photopolymer formulations cured through stereolithography and digital light processing. ECHA scrutiny of sensitizing monomers extends requalification cycles for dashboard prototyping applications.
- Liquid:Binder jetting inks and material jetting fluids depositing droplet-scale material volumes. Direct purchasing contracts displace distributor intermediaries for high-volume programs.
The dominant share belongs to Powder, while Filament is closing the gap fastest.
Material:
Material chemistry determines mechanical performance ceilings and regulatory compliance pathways across automotive qualification protocols.
- Metals:Aluminum, titanium, nickel superalloy, and ferrous alloys consolidated through powder bed fusion. Noble metal powder volatility squeezes automotive supplier margins when aerospace demand cycles spike. Nordic captive smelting capacity anchors ferrous powder production, exposing buyers to single-source geographic dependency.
- Thermoplastics:ABS, PLA, PA, and PEEK polymers extruded or sintered into functional prototypes. Mature volume base for design verification across OEM engineering centers, though sustainability criteria now penetrate procurement specifications.
- Composites:Carbon fiber and glass fiber reinforced polymers combining directional strength with lightweighting potential. High-speed sintering systems virtualize injection molding break-even thresholds for medium-complexity geometries below ten thousand units annually.
- Ceramics:Oxide and non-oxide formulations for high-temperature applications in exhaust and brake systems. Limited adoption constrained by brittleness and post-processing complexity.
Metals command the value premium, yet Composites expand most quickly as tooling applications multiply.
Application:
Application intensity spans concept validation through serialized production, with each tier imposing escalating certification burdens.
- Production Parts:Serialized components meeting OEM qualification standards for functional integration. NHTSA crash-relevant certification extends approval timelines eighteen to twenty-four months, freezing supplier switching decisions for safety-critical applications.
- Tooling:Jigs, fixtures, and manufacturing aids replacing conventional machined metal equivalents. Tier-1 suppliers in Germany and Japan adopt high-speed sintering at pilot scale, compressing lead times for assembly line customization.
- Prototyping:Design verification and concept modeling iterations preceding tooling commitment. Mature demand base concentrated in OEM design centers with established filament and resin workflows.
- Custom Components:Low-volume specialized parts for motorsport, luxury, and aftermarket applications. Digital inventory convergence through cloud-based file libraries paired with distributed printing networks compresses aftermarket supply chains.
Production Parts capture the highest unit economics, though Tooling applications scale most rapidly.
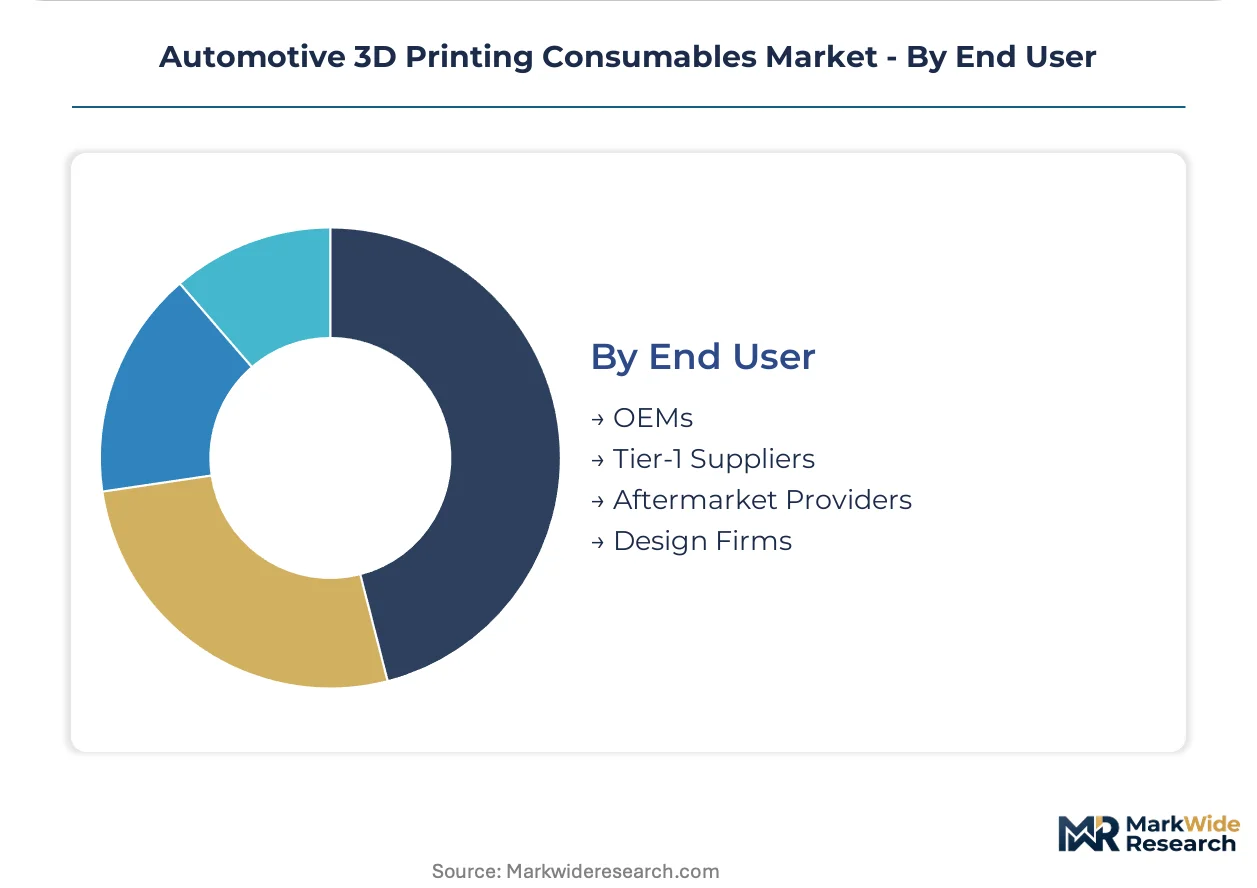
End User:
End user sophistication determines procurement leverage, technical specification authority, and qualification timeline pressure.
- OEMs:Vehicle manufacturers with in-house metallurgical laboratories and statistical process control capabilities. Direct annual tonnage negotiations with smelters bypass regional material resellers, concentrating procurement leverage with buyers possessing internal qualification infrastructure.
- Tier-1 Suppliers:Component manufacturers supplying integrated modules to vehicle assembly operations. Dual pressure from automakers demanding batch-level certification and REACH restrictions tightening formulation flexibility.
- Aftermarket Providers:Spare part distributors and service networks addressing vehicle maintenance demand. Closed-loop powder recycling systems reduce effective feedstock cost per part while satisfying circular economy procurement criteria.
- Design Firms:External engineering consultancies supporting OEM concept development. EPA oversight of volatile organic compound emissions from resin curing operations shapes facility location decisions in the US.
OEMs dominate procurement volume, while Tier-1 Suppliers deepen adoption fastest as production integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electric vehicle component localization is redirecting metal powder demand toward domestic qualification programs. Germany maintains the densest concentration of automotive additive manufacturing engineering centers. China's MIIT standards for industrial 3D printing are accelerating domestic powder specification development.
Germany
Stuttgart and Munich engineering clusters anchor European demand for aluminum and tool steel powders in thermal management components. REACH substance restrictions tighten formulation flexibility for polymer formulators serving dashboard prototyping applications. Bavaria's powder bed fusion equipment installed base sustains direct annual tonnage negotiations between automakers and Nordic smelters.
United States
EPA oversight of volatile organic compound emissions from resin curing operations shapes facility location decisions for design centers. NHTSA crash-relevant certification timelines extend eighteen to twenty-four months for safety-critical printed components. Michigan and Ohio automotive corridors concentrate Tier-1 supplier adoption of high-speed sintering systems for tooling applications below ten thousand units annually.
China
MIIT standards for industrial additive manufacturing are accelerating domestic specification development for aluminum and copper alloys in battery housing applications. Dual carbon goals penetrate procurement criteria for recycled feedstocks in electric vehicle programs. Yangtze River Delta manufacturing clusters concentrate both powder production capacity and laser powder bed fusion system deployment.
India
PLI scheme localization incentives for electric vehicle manufacturing create entry points for metal powder qualification with domestic OEMs. BIS standards for industrial 3D printing materials are evolving alongside automotive sector adoption. Tamil Nadu and Maharashtra automotive corridors concentrate Tier-1 supplier engineering centers seeking closed-loop powder recycling systems.
Japan
METI industrial technology roadmaps prioritize additive manufacturing for lightweight structural components in hybrid powertrains. JIS standards for metal powder characterization support OEM qualification protocols extending material certification timelines. Nagoya and Osaka manufacturing clusters anchor demand for nickel superalloy feedstocks in high-temperature exhaust applications.
Automotive 3D Printing Consumables Market Competitive Landscape
On the supply side, the industry is consolidating around direct purchasing relationships that bypass traditional distributor networks. Powder producers face dual pressure from automakers demanding batch-level certification and from regulatory restrictions tightening formulation flexibility. Three strategic archetypes dominate: integrated powder-smelter operations, equipment-integrated material suppliers, and specialized composite filament formulators. Competitive moves concentrate on captive smelting capacity expansion and cloud-based spare part file library development.
Among European-integrated powder specialists, EOS GmbH and Hoganas AB occupy positions anchored by regional equipment installed base and captive ferrous production capacity respectively. Markforged Inc. exemplifies the composite filament tier competing below aerospace-grade pricing thresholds for tooling applications. These three represent distinct competitive vectors: equipment-coupled material supply, upstream metallurgical control, and chopped fiber formulation specialization.
| Leading Market Players |
|---|
| Stratasys Ltd |
| 3D Systems Corporation |
| EOS GmbH |
| HP Inc. |
| Materialise NV |
| BASF Forward AM |
| Hoganas AB |
| Markforged Inc. |
| Sandvik AB |
| Others |
Pricing and Supply Chain Analysis
Nordic captive smelting capacity in Sweden and Finland anchors ferrous powder production for automotive additive manufacturing, concentrating upstream pricing leverage with integrated metallurgical operators while downstream buyers face limited alternative sourcing. This geographic concentration feeds directly into annual tonnage negotiations between German automakers and smelters, bypassing traditional distributor intermediaries and compressing margins for regional material resellers lacking captive production assets.
Pricing Analysis
Certification level creates the primary spread between automotive-qualified metal powders and industrial-grade alternatives, with OEM batch-level traceability requirements commanding substantial premia over standard formulations. Three-tier pricing structure separates aerospace-grade superalloys from automotive production powders and prototyping-grade feedstocks, with volume scale and after-sales technical support bundling as secondary differentiation factors. Pricing pressure stems from noble metal volatility when aerospace demand cycles spike titanium and nickel alloy costs, squeezing automotive supplier margins. Tier-1 suppliers exhibit highest price sensitivity due to dual pressure from automaker cost-down mandates and REACH compliance overhead, while OEMs with in-house metallurgical laboratories leverage direct smelter relationships to resist margin compression.
Supply Chain Analysis
Tariff exposure between China and Western automotive markets dominates supply chain risk planning as MIIT domestic specification development accelerates indigenous powder production capacity. Raw material flows draw from Swedish ferrous smelting, German aluminum atomization, and Chinese copper alloy processing, with spherical powder production resting on gas atomization equipment concentrated in German and Japanese engineering clusters. Single-source vulnerability persists in Nordic captive smelting for tool steel grades, exposing buyers to geographic concentration risk. Distribution runs through direct annual contracts between OEM procurement teams and integrated powder-smelter operations, displacing traditional regional distributor networks for high-volume programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
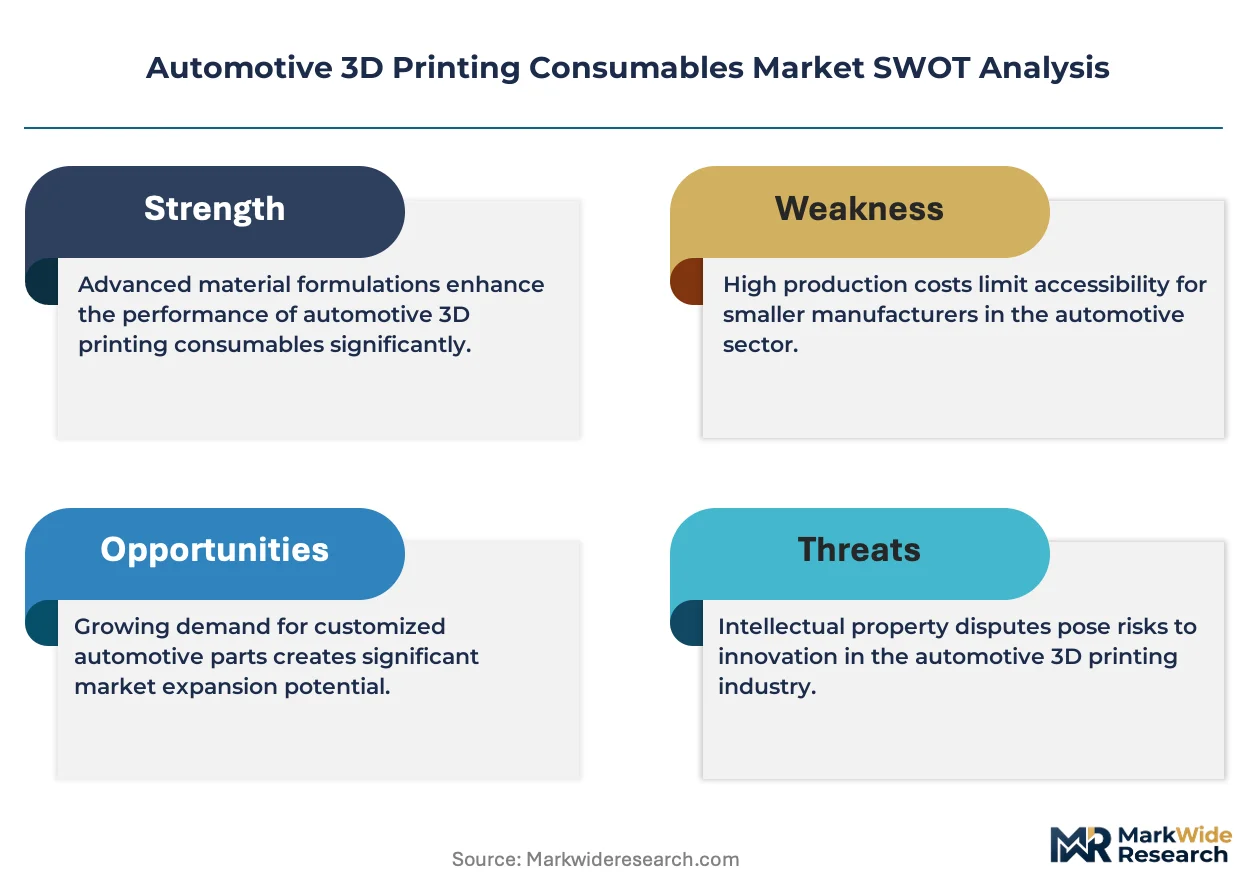
Automotive 3D printing consumables represent a high-growth disruption as multi-laser powder bed fusion architectures virtualize conventional tooling economics and EU Green Deal mandates force feedstock sustainability transitions. Powertrain electrification requiring thermal management components for battery housings creates structural demand inflection for aluminum and copper alloy powders.
For Market Incumbents: Harden qualification infrastructure against emerging composite filament competitors by expanding captive smelting capacity in Nordic and German clusters, securing batch-level certification protocols that freeze supplier switching decisions. Invest in closed-loop powder recycling systems to preempt circular economy procurement criteria from Tier-1 buyers while raising R&D overhead barriers for unapproved challengers facing extended NHTSA crash-relevant approval timelines.
For New Entrants and Emerging Players: Pursue India's PLI scheme localization incentives for electric vehicle component manufacturing, where domestic OEM qualification programs remain underpenetrated by established European powder suppliers. Target aftermarket digital inventory convergence through cloud-based spare part file libraries paired with distributed printing networks, leveraging lower certification burdens than safety-critical production applications to establish initial revenue traction.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated powder-smelter operations with captive metallurgical control and direct OEM contract relationships over equipment-integrated material suppliers vulnerable to printer vendor consolidation. Long-term viability hinges on sustainability credentialing as REACH substance restrictions and EU Green Deal mandates reshape procurement specifications. Watch for closed-loop powder recycling system deployment rates as the inflection signal indicating circular economy integration depth.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Smelting Capacity Expansion | Backward integration into Nordic ferrous production secures supply certainty against aerospace demand volatility. |
| Closed-Loop Powder Recycling Deployment | Unfused material recovery systems satisfy EU Green Deal circular economy criteria for Tier-1 procurement. |
| Direct OEM Qualification Partnerships | Annual tonnage contracts with Stuttgart and Munich engineering clusters bypass distributor margin extraction. |
| Composite Filament Formulation Specialization | Chopped carbon fiber grades for jigs and fixtures occupy defensible niche below aerospace pricing thresholds. |
| Digital Spare Part File Library Development | Cloud-based repositories paired with distributed printing networks compress aftermarket supply chain lead times. |
Research Methodology
Operator-level perspectives from powder metallurgy plant managers, OEM platform engineers, Tier-1 supplier procurement leads, and aftermarket service heads anchored the qualitative base for this automotive additive manufacturing analysis. Primary fieldwork combined structured interviews across German, Chinese, and Indian automotive corridors with secondary validation from MIIT industrial additive manufacturing standards, REACH substance restriction filings, EPA volatile organic compound emission records, and vehicle production databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers to establish consumption intensity benchmarks across material chemistry and application tiers.
Scenario-bracketing framed the analytical approach across the projection horizon, with conservative and expansion cases reflecting differential assumptions for NHTSA certification timeline compression and India PLI scheme uptake velocity. Segmentation dimensions modeled include material chemistry, physical feedstock format, application intensity from prototyping through serialized production, and buyer sophistication tier from design firms through integrated OEMs. CAGRs derived from fitted growth curves incorporating powertrain electrification penetration rates, powder bed fusion equipment installed base expansion, and regulatory compliance cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic powder producers or accelerated REACH substance restriction enforcement would shift outcomes materially from projected trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Food 3D Printing Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
Global 3D Printed Electronics Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
3D Printing Service Bureaus Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
Online 3D Printing Service Market
3D Printing Technology
Metal 3D Printing Service Market