
 Polymer 3D Printing Systems Market | 2026-2036
Polymer 3D Printing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer 3D Printing Systems Market Insights
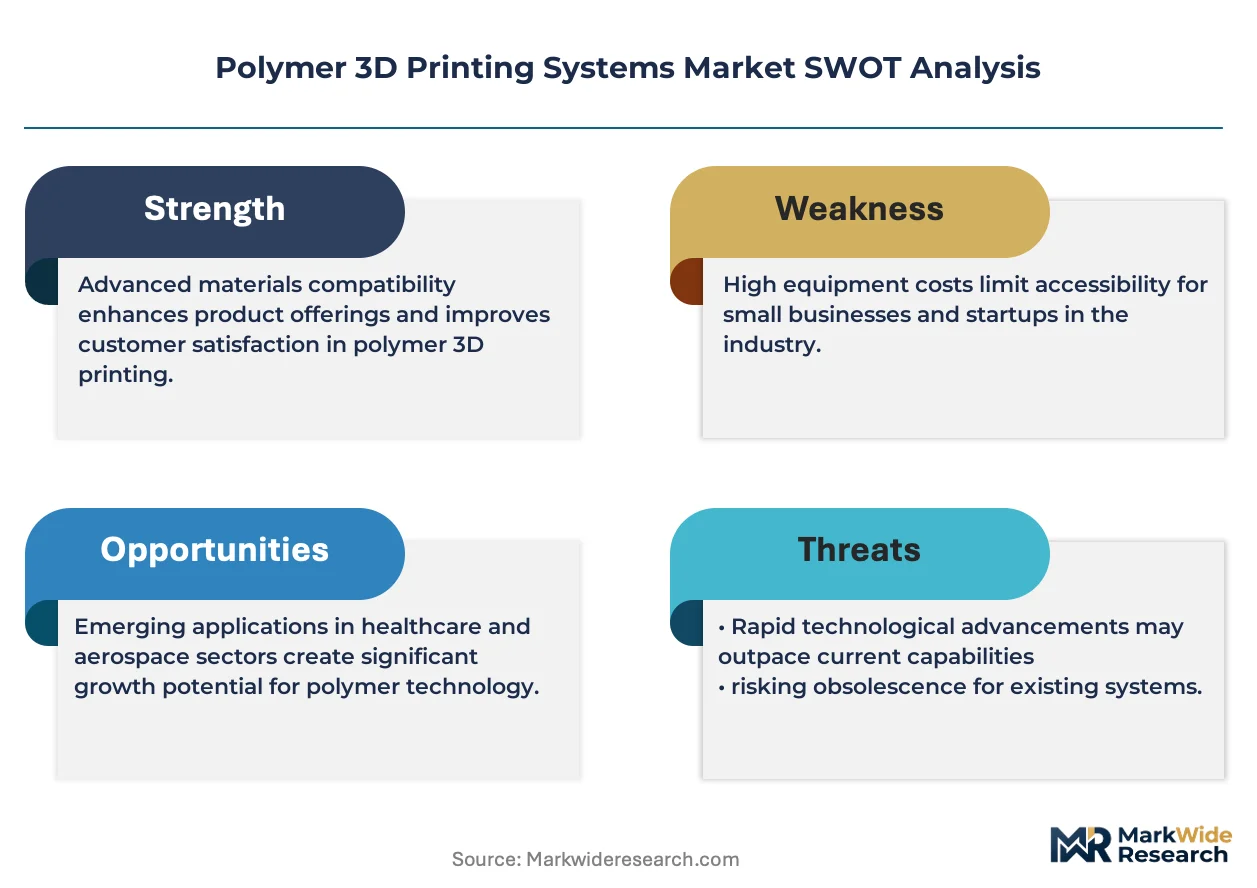
The EU Green Deal's material traceability mandates and Boeing's supplier sustainability compact is consolidating demand around bio-based photopolymers and closed-loop material systems. Stratasys leverages its Fortus platform range and certified material library to anchor aerospace and medical workflows. 3D Systems competes through its Figure 4 platform and NextDent biocompatible resin portfolio, sustaining leadership in dental and hearing-aid production. Arkema differentiates via its Rilsan PA11 bio-sourced polyamide, extending reach into sustainable industrial parts.
Polymer 3D printing systems are additive manufacturing platforms that build objects layer-by-layer from thermoplastic filaments, photopolymer resins, or polymer powders, typically achieving layer resolutions between 25 and 100 microns depending on the process. These systems serve primarily to produce functional prototypes, manufacturing aids, and end-use components without conventional tooling lead times. Fused Deposition Modeling dominates unit shipments due to low equipment cost and material accessibility, though Selective Laser Sintering captures disproportionate value in aerospace and medical-grade applications where nylon 12 and TPU performance justifies higher system prices. Industrial Printers represent the largest revenue pool, while Medical-Grade Printers are expanding fastest as FDA and EMA device manufacturing guidance increasingly accepts printed polymer implants and surgical guides.
The FDA's 510(k) pathway for patient-matched devices and EMA's MDR compliance requirements for printed medical products are reshaping validation protocols and quality management systems for polymer system vendors. REACH restrictions on certain photoinitiators and EPA VOC emissions standards for resin handling are forcing reformulation of established material chemistries and accelerating investment in low-odor, bio-based alternatives. Stakeholders must monitor evolving certification reciprocity between FDA and notified bodies, as divergence in biocompatibility testing standards threatens to fragment market access for cross-border medical device manufacturers.
Market Dynamics
Flight-certification pathways for polymer aerospace components are compressing qualification timelines and consolidating supplier relationships around established material libraries. Boeing and Airbus tier-1 suppliers now demand closed-loop traceability systems that extend from resin formulation through final part inspection.
Growth Catalysts
- FDA 510(k) pathway expansion:Patient-matched surgical guides and cranial implants now qualify for streamlined clearance, accelerating hospital procurement of medical-grade polymer systems across Ohio and Bavaria.
- EU Green Deal material mandates:Bio-based photopolymer quotas in industrial procurement are redirecting R&D budgets toward Rilsan PA11 and similar sustainable polyamides.
- Guangdong medical device cluster:Concentrated hearing-aid manufacturing demand is driving multi-site deployments of biocompatible resin printers with validated sterilization protocols.
Market Restraints
- Photoinitiator supply concentration:REACH restrictions on benzophenone derivatives have eliminated three European suppliers, forcing reformulation cycles that extend 18-24 months.
- Nylon 12 powder oligopoly:Selective Laser Sintering feedstock production concentrates in Germany and Japan, exposing aerospace contractors to allocation risk during demand surges.
- Post-processing bottleneck:Manual support removal and surface finishing for Fused Deposition Modeling parts limits throughput scalability in high-volume contract manufacturing.
Strategic Opportunities
- Brazil orthopedic implant localization:ANVISA's emerging guidance for printed patient-specific devices creates first-mover advantage for certified system vendors establishing São Paulo service hubs.
- Closed-loop resin recycling:Hardware-integrated material recovery systems are opening subscription-based pricing models that decouple equipment sales from recurring revenue.
- Digital dentistry convergence:Intraoral scanner-to-printer workflow integration is compressing dental lab turnaround from weeks to same-day delivery in Seoul and Tokyo metropolitan markets.
Industry Challenges
- Biocompatibility testing divergence:FDA and EMA cytotoxicity protocols now require separate validation studies, doubling certification costs for cross-border device manufacturers.
- Process technician scarcity:Qualified operators for Selective Laser Sintering parameter optimization command 40% wage premiums in Munich and Cincinnati manufacturing clusters.
- Legacy MES integration:Polymer 3D printing cells require custom middleware to synchronize with SAP and Oracle shop-floor systems, extending deployment timelines 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer 3D Printing Systems Market |
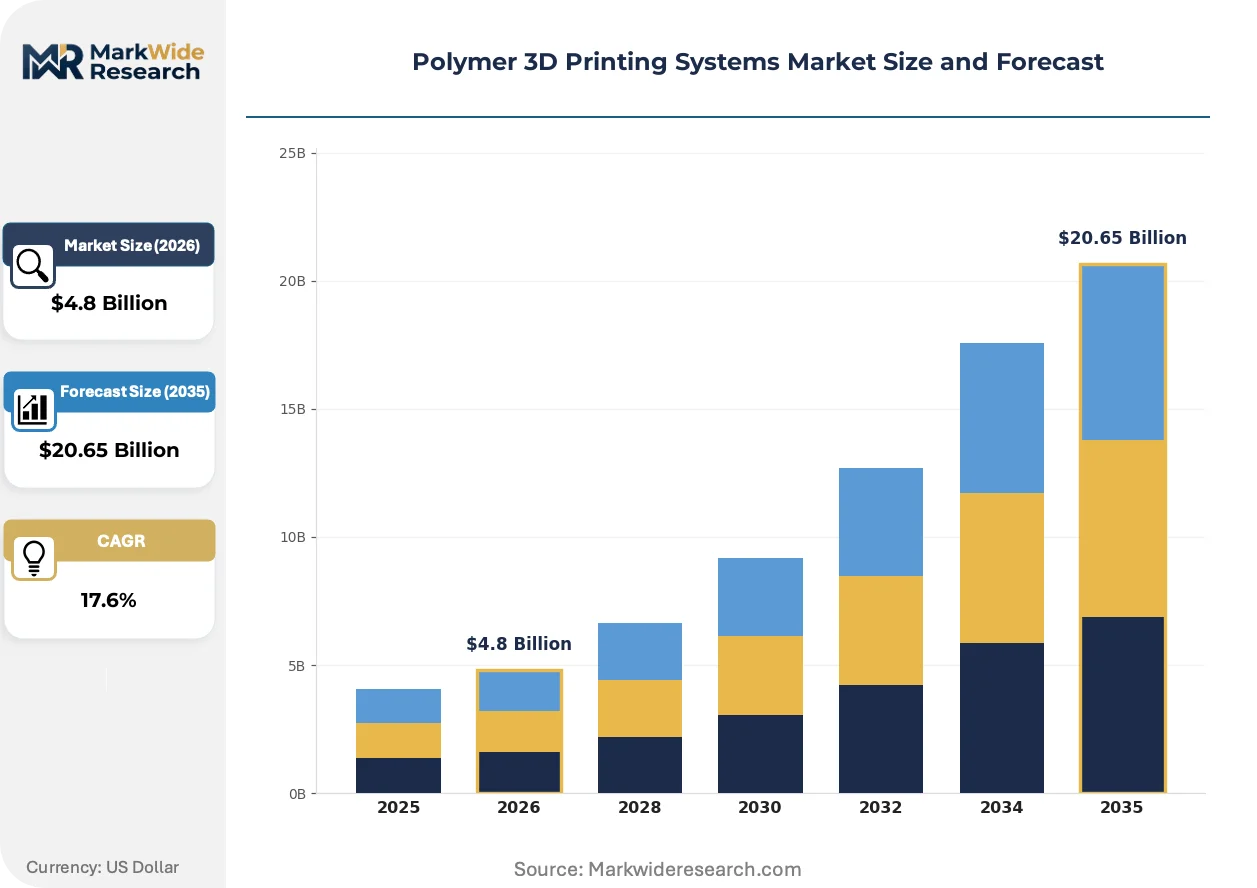
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing Product Type: Desktop Printers, Industrial Printers, Professional Printers, Medical-Grade Printers Application: Prototyping, Tooling, End-Use Parts, Concept Modeling, Custom Manufacturing End User Industry: Aerospace, Consumer Electronics, Education, Architecture, Jewelry |
| Companies Covered | Stratasys, 3D Systems, Materialise, HP Development Company, Formlabs, Arkema, Syensqo, Prodways Group, Ultimaker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer 3D Printing Systems Market Trends and Innovations
Autonomous post-processing and real-time quality verification are eliminating manual bottlenecks that have constrained polymer additive manufacturing throughput. These capabilities are reshaping competitive differentiation toward software-defined production systems.
Continuous fiber-reinforced extrusion is automating structural component production for unmanned aerial vehicle airframes and robotic end-effectors. Aerospace tier-2 suppliers in Wichita and Toulouse are adopting these systems at pilot scale, with qualification programs targeting 2026 production integration. The technology is automating layup labor previously performed by composite technicians, compressing skilled workforce requirements while extending geometric freedom.
EMA's Medical Device Regulation Annex I general safety and performance requirements are mandating design dossier documentation for printed patient-specific implants. German notified bodies have issued three guidance documents clarifying residual monomer testing protocols since 2023. Dental and hearing-aid manufacturers in Denmark and the Netherlands are restructuring quality management systems to accommodate unannounced audits of polymer powder handling facilities.
Hospital procurement committees are consolidating vendor relationships around single-source service contracts that bundle equipment, consumables, and regulatory documentation. Medical device distributors in Texas and Florida are repositioning as workflow consultants, displacing traditional capital equipment sales relationships. This pattern concentrates most visibly in orthopedic and maxillofacial surgical programs where case volume justifies dedicated production cells.
Polymer 3D Printing Systems Market Segmentation
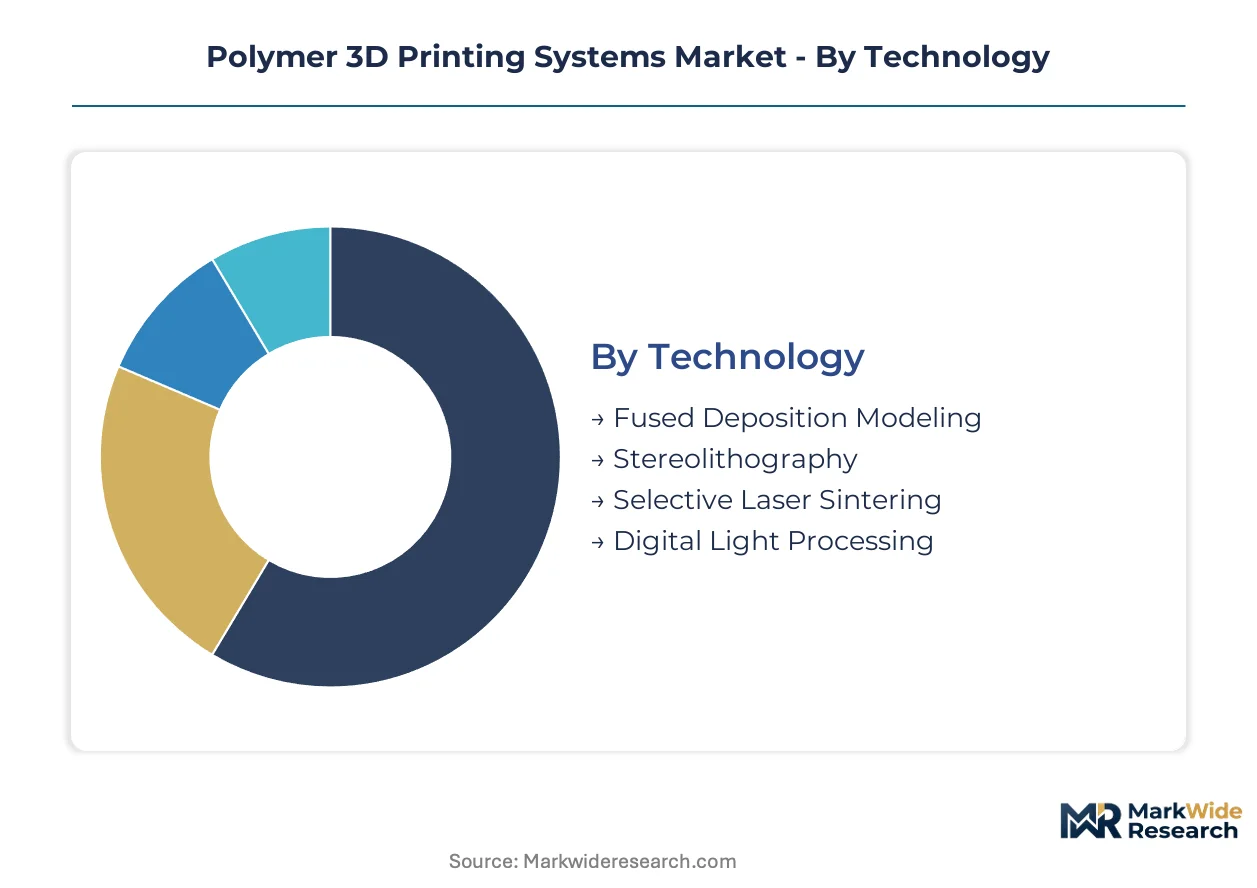
Technology choice dictates material compatibility, surface finish requirements, and regulatory pathways. Printer classification separates hobbyist experimentation from flight-certified production. Application and end-use segmentation reveals where capital deployment concentrates.
Technology:
Volume leadership sits with low-cost extrusion platforms. Premium capture belongs to powder-bed and photopolymer systems that command aerospace and medical validation.
- Fused Deposition Modeling:Thermoplastic filament extrusion through heated nozzles builds parts layer-by-layer with 50-400 micron resolution. Unit shipments dominate across education and consumer electronics prototyping in Guangdong and Ohio due to sub-$5,000 entry pricing and open-material architectures. Post-processing bottlenecks constrain throughput scaling in contract manufacturing environments.
- Selective Laser Sintering:CO2 laser fusion of nylon 12, TPU, and polyamide powders achieves isotropic mechanical properties without support structures. Demand concentrates in aerospace ducting and medical device housings across Germany and Japan where material traceability justifies $300,000+ system investments. Nylon 12 powder oligopoly in German and Japanese supply chains exposes tier-1 contractors to allocation risk.
- Stereolithography:UV laser polymerization of liquid photopolymer resins delivers sub-25 micron surface finish for dental aligners and hearing-aid shells.
- Digital Light Processing:Projector-based vat photopolymerization accelerates batch production of surgical guides through masked exposure patterns.
Mature deployment sits with Fused Deposition Modeling. Newer deployment is concentrated in Selective Laser Sintering.
Product Type:
Certification grade separates pricing tiers. Uncertified desktop units compete on acquisition cost. Validated medical-grade systems capture recurring consumables revenue.
- Industrial Printers:Build volumes exceeding 1,000 cubic centimeters with heated chambers process engineering-grade thermoplastics including ULTEM and PEEK. Aerospace manufacturers in Wichita and Toulouse deploy these systems for flight-certified brackets and ducting under FAA and EASA qualification protocols. Closed-loop material traceability systems extend from resin formulation through final inspection.
- Medical-Grade Printers:Biocompatible material pathways, validated sterilization protocols, and FDA 510(k) documentation packages enable patient-matched implant production. Hospital procurement committees across Bavaria and Texas consolidate vendor relationships around single-source service contracts bundling equipment, consumables, and regulatory documentation. EMA MDR Annex I requirements mandate design dossier documentation for printed patient-specific devices.
- Desktop Printers:Entry-level fused deposition systems serve education and hobbyist markets with limited thermal management.
- Professional Printers:Mid-range systems bridge prototyping and short-run manufacturing with enhanced material compatibility.
Equipment revenue concentrates in Industrial Printers. Steepest expansion trajectory belongs to Medical-Grade Printers.
Application:
Time-to-value differentiates use cases. Same-day turnaround commands premium pricing. Multi-week lead times compress margins.
- End-Use Parts:Flight-certified aerospace brackets, biocompatible cranial implants, and patient-specific surgical guides bypass conventional tooling. Boeing and Airbus tier-1 suppliers demand closed-loop traceability systems. FDA 510(k) pathway expansion accelerates hospital procurement across Ohio and Bavaria.
- Prototyping:Form and fit validation, design iteration, and functional testing dominate early-stage product development cycles.
- Tooling:Jigs, fixtures, and mold inserts compress manufacturing aid lead times from weeks to days.
- Concept Modeling:Visual prototypes support design reviews and stakeholder communication with minimal mechanical requirements.
- Custom Manufacturing:Lot-size-one production serves orthopedic and maxillofacial surgical programs where case volume justifies dedicated production cells.
Established deployment dominates Prototyping. Emerging deployment concentrates in End-Use Parts.
End User Industry:
Regulatory burden shapes vendor selection. Flight certification and biocompatibility requirements filter supplier pools. Unregulated applications tolerate broader sourcing.
- Aerospace:Polymer brackets, ducting, and interior components must satisfy FAA and EASA flammability, smoke, and toxicity standards. Boeing's supplier sustainability compact consolidates demand around bio-based photopolymers and closed-loop material systems. Flight-certification pathways compress qualification timelines around established material libraries.
- Consumer Electronics:Enclosure prototyping and manufacturing aid production serve compressed product development cycles.
- Education:Curriculum integration and research applications drive desktop printer deployments.
- Architecture:Scale models and facade prototypes leverage geometric freedom for complex surface articulation.
- Jewelry:Lost-wax casting patterns and direct precious metal printing serve bespoke and small-batch production.
Validated deployment concentrates in Aerospace. Volume deployment spreads across Consumer Electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German and Japanese powder supply chains while consumption spreads across aerospace clusters in Wichita, Toulouse, and medical device hubs in Ohio and Bavaria. This geographic split shapes procurement risk and vendor consolidation patterns.
United States
FAA flight-certification pathways compress qualification timelines for polymer aerospace brackets and ducting. Boeing's supplier sustainability compact mandates closed-loop material traceability from resin formulation through final inspection. Wichita and Cincinnati manufacturing clusters absorb qualified SLS parameter optimization technicians at 40% wage premiums.
Germany
EMA MDR Annex I requirements mandate design dossier documentation for printed patient-specific implants, restructuring quality management systems. REACH restrictions on benzophenone photoinitiator derivatives have eliminated three European suppliers, forcing 18-24 month reformulation cycles. Bavarian hospital procurement committees consolidate vendor relationships around single-source service contracts bundling equipment and regulatory documentation.
China
Guangdong Province's concentrated hearing-aid manufacturing demand drives multi-site deployments of biocompatible resin printers with validated sterilization protocols. The country's national pharmaceutical regulator is developing guidance for printed medical products that increasingly references FDA and EMA precedents. Shenzhen and Dongguan electronics prototyping clusters sustain high-volume FDM unit shipments through sub-$5,000 entry pricing.
Japan
ISO and JIS standards convergence supports dental lab workflow integration from intraoral scanner to same-day printer output in Tokyo and Osaka metropolitan markets. METI industrial policy channels R&D subsidies toward low-odor, bio-based photopolymer alternatives. Nagoya aerospace tier-2 suppliers pilot continuous fiber-reinforced extrusion systems for unmanned aerial vehicle airframes.
Brazil
ANVISA's emerging guidance for printed patient-specific orthopedic devices creates first-mover positioning for certified system vendors establishing São Paulo service hubs. The national health surveillance agency's regulatory development mirrors FDA 510(k) pathway structures for patient-matched surgical guides. Local medical device distributors reposition as workflow consultants to capture hospital procurement committee consolidation.
Polymer 3D Printing Systems Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with material science heritage. Equipment vendors and chemical suppliers occupy distinct value capture positions, with hardware-integrated material recovery systems opening subscription-based pricing models. Three archetypes dominate: platform-anchored system vendors, bio-based material specialists, and dental workflow integrators. Consolidation concentrates around aerospace qualification libraries and medical-grade certification reciprocity.
Among platform-anchored system vendors, Stratasys and 3D Systems occupy positions exemplifying divergent specialization vectors. Stratasys represents the aerospace-medical workflow consolidation archetype through its certified material library approach. 3D Systems sits within the dental-hearing-aid production specialization tier, leveraging biocompatible resin portfolios. Arkema exemplifies the bio-based material differentiation archetype, extending industrial reach through sustainable polyamide chemistry rather than equipment ownership.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| Materialise |
| HP Development Company |
| Formlabs |
| Arkema |
| Syensqo |
| Prodways Group |
| Ultimaker |
| Others |
Pricing and Supply Chain Analysis
Nylon 12 powder spot prices in German and Japanese supply chains cascade through aerospace tier-1 procurement, compressing margins for Selective Laser Sintering contractors while amplifying pricing power for integrated resin formulators serving medical-grade printer deployments.
Pricing Analysis
Outcome-based contracts tied to flight-certification throughput anchor premium pricing for aerospace-qualified polymer systems. Three-tier pricing structure across certified-flight, medical-grade, and industrial-prototyping levels reflects validation burden and material traceability requirements. Cost compression in entry-level Fused Deposition Modeling intensifies as Guangdong electronics clusters absorb sub-$5,000 equipment. Hospital procurement committees in Bavaria and Texas exhibit lowest price sensitivity due to bundled regulatory documentation requirements.
Supply Chain Analysis
FAA and EASA qualification gating restricts powder-bed feedstock sourcing to German and Japanese suppliers with established material libraries. Photopolymer resin formulations draw from benzophenone derivative precursors now constrained by REACH restrictions. Single-source vulnerability concentrates in nylon 12 powder oligopoly, exposing aerospace contractors to allocation risk. Distribution runs through authorized channel partners with certified installation and validation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous fiber-reinforced extrusion is displacing manual composite layup in unmanned aerial vehicle production, compressing the window for legacy equipment vendors to capture structural component workflows.
For Market Incumbents: Hedge against photoinitiator supply disruption by securing alternative formulation partnerships before REACH restrictions eliminate remaining European suppliers. Expand backward integration into bio-based polyamide production to capture EU Green Deal procurement mandates. Prioritize certification investment in Brazil's emerging ANVISA pathway to preempt competitor lock-in at São Paulo service hubs. For New Entrants and Emerging Players: FDA 510(k) pathway expansion in Ohio and Bavaria opens a window for specialized surgical guide producers to bypass established dental-hearing-aid incumbents. Target orthopedic implant localization in Brazil as the most penetrable geography with first-mover regulatory positioning. Deploy workflow-consultant go-to-market models that displace traditional capital equipment sales relationships in Texas hospital procurement committees. For Investors and Strategic Acquirers: Distressed-cycle entries favor bio-based material specialists with captive Rilsan PA11 chemistry in European manufacturing clusters. Long-term viability hinges on regulatory reciprocity convergence between FDA and EMA biocompatibility protocols. Watch for divergence in cytotoxicity testing standards as the inflection signal threatening cross-border device manufacturer margins.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Material Recovery System Deployment | Hardware-integrated recycling enables subscription pricing models that decouple equipment sales from recurring resin revenue. |
| FAA Flight-Certification Pathway Investment | Qualification library expansion captures Boeing and Airbus tier-1 supplier consolidation around traceable polymer brackets. |
| Intraoral Scanner-to-Printer Workflow Integration | Same-day dental lab turnaround in Seoul and Tokyo metropolitan markets compresses traditional multi-week delivery cycles. |
| Bio-Based Photopolymer R&D Scale-Up | EU Green Deal procurement quotas redirect industrial demand toward Rilsan PA11 and sustainable polyamide alternatives. |
| ANVISA-Certified São Paulo Service Hub Establishment | First-mover positioning in Brazil's emerging patient-specific orthopedic device guidance captures hospital procurement consolidation. |
Research Methodology
Multi-period observation of FDA 510(k) clearance volumes, EMA MDR design dossier submissions, and photopolymer resin formulation registrations anchored the trend analysis, supplemented by interviews with biomedical engineers at Bavarian hospital systems, aerospace procurement leads at Wichita tier-2 suppliers, and polymer powder plant managers in German manufacturing clusters. Secondary validation drew from FAA certification databases, REACH restriction notices, customs trade data for nylon 12 powder shipments, and SEC filings of listed additive manufacturing equipment vendors. Bottom-up equipment shipment tracking and top-down end-use industry absorption estimates were triangulated to constrain projection variance.
Segment-weighting across technology type, product certification grade, application use case, and end-user industry concentration shaped the analytical framework across the projection horizon. CAGRs were derived from fitted adoption curves calibrated to historical qualification timeline compression in aerospace and regulatory pathway expansion in medical devices. Forecast inputs included hospital procurement committee vendor consolidation patterns in Texas, Guangdong hearing-aid manufacturing cluster equipment deployment rates, and continuous fiber-reinforced extrusion pilot program progression at Nagoya aerospace suppliers.
The model assumes a particular technology adoption path; alternative pathways for autonomous post-processing integration would alter the outlook for Fused Deposition Modeling throughput scalability. Forecasts reflect assumptions regarding EMA-FDA biocompatibility testing standard convergence, REACH photoinitiator restriction enforcement timelines, and nylon 12 powder supply chain allocation stability. A model refresh is warranted upon material change in flight-certification pathway reciprocity between FAA and EASA.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Rapid Prototyping Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
3D Printing Robots Market
3D Printing Technology
Global 3D Printed Electronics Market
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Asia-Pacific 3D Printing Market
3D Printing Technology
Desktop 3D Printing Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
Latin America Industrial 3D Printing Market