
 Global 3D Pens Market | 2026-2036
Global 3D Pens Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Pens Market Analysis
REACH compliance is restructuring the cost-of-entry calculus for 3D pen manufacturers selling into European markets. MYNT3D leverages its filament certification pipeline to sustain premium positioning across multiple geographies. WobbleWorks anchors its brand strength through channel control in educational supply chains. Zhuhai Sunlu Industrial competes on manufacturing scale, dominating OEM supply relationships for battery-operated units.
A 3D pen is a handheld extrusion device that heats thermoplastic filament—typically ABS, PLA, or Nylon—to temperatures between 160°C and 230°C, depositing material through a motorized feed mechanism to create freeform three-dimensional structures. Its primary commercial purpose spans rapid prototyping, educational modeling, and artistic sculpture where desktop 3D printers lack portability or immediacy. Plug-in models retain margin concentration in professional prototyping workflows where sustained power and precision matter. Battery-operated variants represent the fastest-growing configuration as mobility requirements expand into field-based repairs and informal maker environments. The artist segment leads end-user value capture, though educator procurement channels are deepening through institutional bulk purchasing programs.
FDA material safety standards for indirect food-contact plastics, EU RoHS restrictions on electrical component heavy metals, and China's GB standards for lithium-ion battery enclosures collectively shape product design constraints and market access timelines. ECHA substance-of-very-high-concern listings for certain ABS additives are forcing reformulation investments among filament suppliers. Stakeholders must monitor evolving CE marking requirements under the EU's revised electrical equipment safety framework and assess whether regional compliance divergence will fragment supply chain configurations.
Market Dynamics
STEAM curriculum mandates across K-12 systems are restructuring procurement authority toward institutional buyers, compressing unit economics while expanding volume pipelines for filament-compatible hardware.
Growth Catalysts
- REACH compliance investments:European chemical safety frameworks are accelerating filament reformulation toward bio-based PLA alternatives, opening premium positioning for certified supply chains.
- Battery chemistry advances:Lithium-polymer cell density improvements are extending cordless operation windows, enabling field-based repair applications previously served by tethered tools.
- Maker-space infrastructure:Community fabrication hubs in the United States, China, and Germany are creating dedicated retail channels with trained staff and demonstration inventory.
Market Restraints
- ABS additive restrictions:ECHA substance-of-very-high-concern listings for styrene-based plasticizers are forcing filament suppliers into costly reformulation cycles with uncertain performance parity.
- Heating element concentration:Precision ceramic resistor manufacturing clusters in Guangdong Province create single-source vulnerability for temperature-control subassemblies.
- Desktop printer substitution:Sub-$200 fused deposition modeling units are capturing prototyping workflows where 3D pens previously held cost advantages.
Strategic Opportunities
- India's BIS certification pathway:Mandatory electronics safety standards for battery-operated devices are creating first-mover advantages for compliant OEMs ahead of enforcement deadlines.
- Medical modeling applications:Pre-surgical anatomical visualization is emerging as a high-value vertical requiring sterilizable filament grades and precision temperature control.
- EU Green Deal alignment:Circular economy packaging mandates and extended producer responsibility frameworks favor refillable filament systems over disposable cartridges.
Industry Challenges
- CE marking timeline compression:The EU's revised electrical equipment safety framework requires retesting of existing product lines, straining certification budgets and launch schedules.
- Filament diameter standardization gaps:Inconsistent tolerances between 1.75mm and 3.00mm feed systems create compatibility failures that damage extruder mechanisms and void warranties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Pens Market |
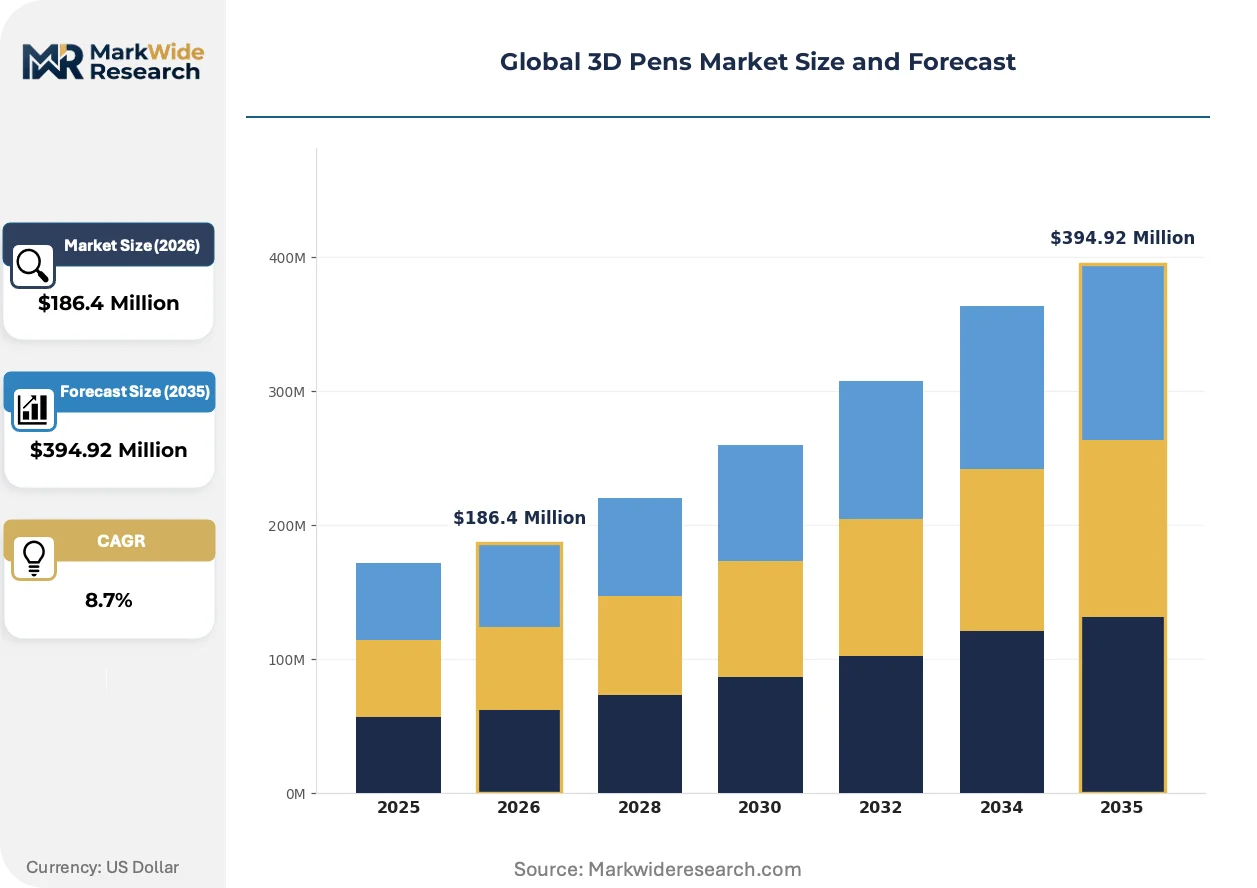
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $394.92 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery-operated, Plug-in, Refillable, Disposable End User: Artists, Educators, Hobbyists, Professionals Application: Art and Design, Prototyping, Education, Repairs Material: ABS, PLA, Nylon, Others |
| Companies Covered | MYNT3D, Scribbler, WobbleWorks (3Doodler), 3DSimo, 7Tech, Zhuhai Sunlu Industrial, CreoPop, XYZprinting, LIX PEN LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Pens Market Emerging Trajectories
Hardware architecture is fragmenting into purpose-built configurations as end-use requirements diverge between institutional, professional, and consumer segments. Three developments are compressing product development cycles.
Low-temperature PLA formulations are modularizing the safety profile of classroom-deployed units. School districts in California and Texas are mandating sub-60°C nozzle surfaces for elementary-grade equipment purchases. This thermal constraint is compressing material compatibility toward specialized copolymer grades with narrow processing windows.
China's GB standards for lithium-ion battery enclosures are forcing redesigns of cordless pen housings. Manufacturers serving export markets must maintain parallel tooling for domestic and international SKUs. The battery segment is responding with modular power packs that separate cells from control electronics, enabling regional certification without full product retesting.
Institutional purchasing cooperatives are consolidating procurement authority for K-12 districts into regional buying consortia. Amazon Business and dedicated educational supply platforms are displacing traditional distributor relationships in the United States. Bulk filament subscription models are emerging as the dominant contract structure for districts with active maker-space programs.
Global 3D Pens Market Segmentation
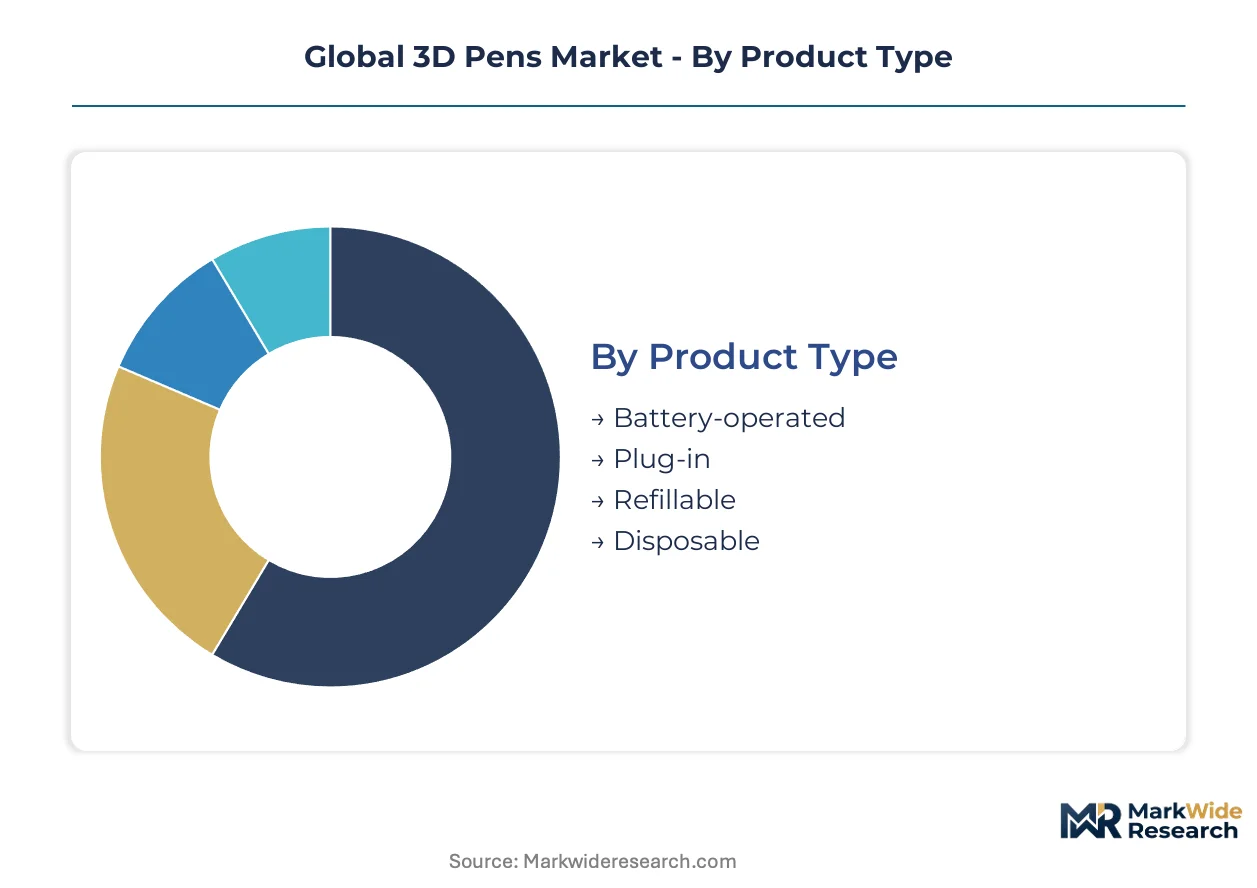
3D pen procurement patterns diverge sharply across user workflows and power requirements. Segment boundaries are hardening as institutional buyers impose safety certifications and filament compatibility standards that consumer channels rarely enforce.
Product Type:
The customization-vs-standardization spectrum runs from disposable classroom units to precision-engineered plug-in systems with replaceable heating elements.
- Plug-in:Mains-powered units deliver sustained thermal stability for professional prototyping workflows. Demand clusters in German engineering studios and Shenzhen electronics repair shops where precision tolerances outweigh mobility needs. Margin concentration remains highest here due to ceramic heating element costs and temperature control firmware.
- Battery-operated:Lithium-polymer configurations enable field-based repairs and informal maker environments across United States community colleges and Chinese maker-spaces. Cordless operation windows are extending through cell density improvements, though India's BIS certification deadlines are compressing launch timelines for non-compliant OEMs.
- Refillable:Open-filament architectures support 1.75mm and 3.00mm feed systems with user-replaceable cartridges. School districts in California and Texas favor these for bulk filament procurement flexibility.
- Disposable:Sealed units with fixed filament loads target single-project educational grants and museum workshop programs where equipment recovery rates are low.
Most installed capacity flows through Plug-in configurations. Expansion is steepest in Battery-operated variants.
End User:
Cost tier separation distinguishes institutional procurement with bulk filament subscriptions from individual purchases through retail channels.
- Educators:K-12 STEAM mandates and maker-space budgets drive volume through regional purchasing cooperatives. United States school districts are consolidating authority into Amazon Business and dedicated educational supply platforms, displacing traditional distributor relationships. Low-temperature PLA mandates for elementary grades are narrowing compatible hardware specifications.
- Artists:Premium segment users capture highest value per unit through specialized filament grades and precision temperature control for sculptural work. Gallery studios in Berlin and Shanghai sustain demand for multi-material capability and fine nozzle diameters.
- Professionals:Engineering and medical prototyping applications require sterilizable filament compatibility and CE-marked electrical safety. Pre-surgical anatomical visualization is emerging as a high-value vertical in United States hospital systems.
- Hobbyists:Price-sensitive segment served through DIY retail channels in Germany and direct-to-consumer platforms in China. Desktop 3D printer substitution is eroding this base for functional prototyping tasks.
Most installed capacity flows through Educators. Expansion is most rapid in Professionals.
Application:
Volume concentration versus margin yield varies by whether outputs are consumable or durable, and whether workflows tolerate iteration time.
- Education:Curriculum-mandated deployment across K-12 systems generates filament-compatible hardware demand with compressed unit economics. Maker-space infrastructure in United States, China, and Germany creates dedicated retail channels with trained demonstration staff.
- Prototyping:Rapid iteration workflows in electronics and product design favor 3D pens over desktop printers for immediate tactile feedback. Shenzhen repair clusters and Berlin hardware startups sustain this segment despite sub-$200 FDM unit competition.
- Art and Design:Freeform sculptural applications exploit portability that fixed-bed printers cannot match. Gallery commissions and installation work drive premium filament consumption.
- Repairs:Field-based plastic welding for automotive trim, appliance housings, and consumer electronics is gaining traction through cordless battery-operated units in mobile technician fleets.
Most installed capacity flows through Education. Expansion is climbing the fastest in Repairs.
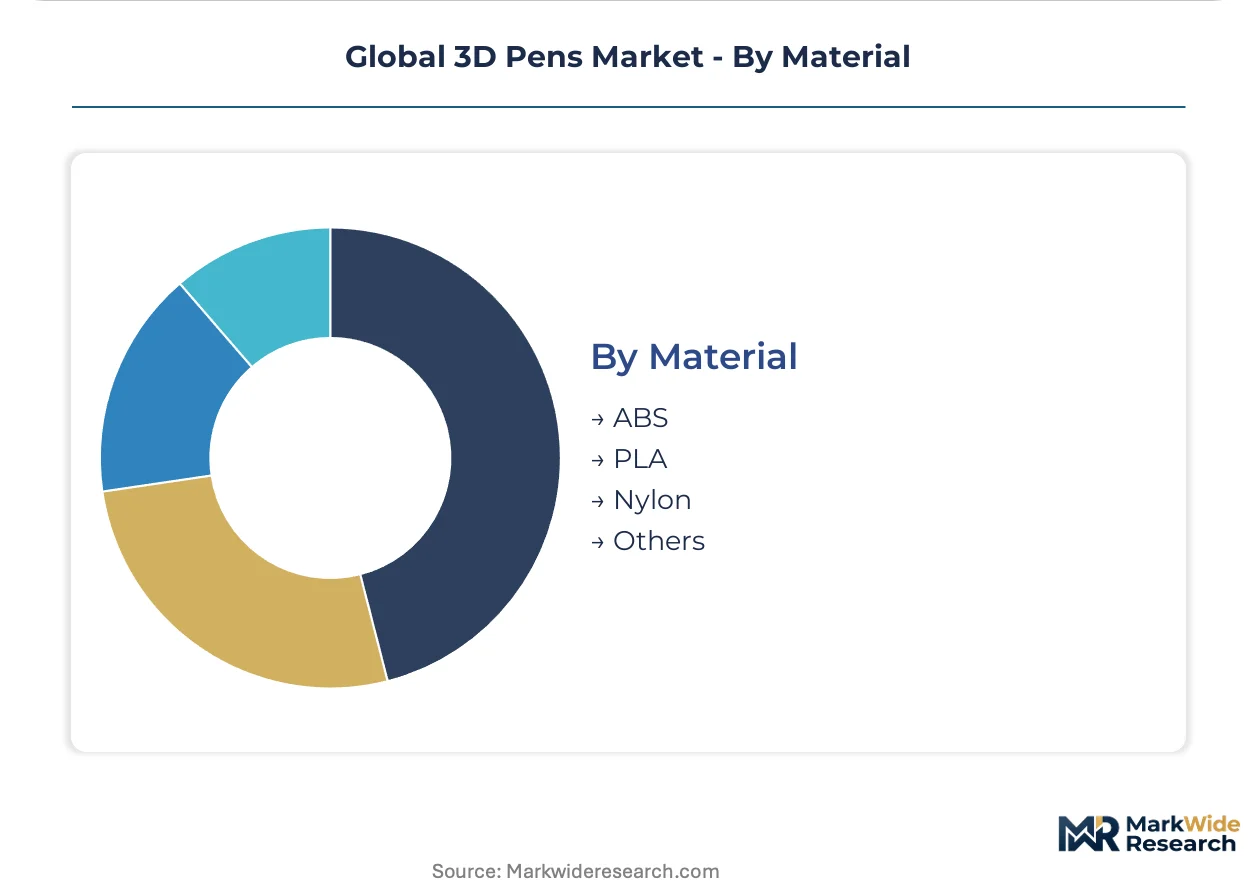
Material:
Supply concentration and regulatory burden differentiate commodity thermoplastics from certified grades with restricted additive packages.
- PLA:Bio-based polylactic acid formulations with sub-60°C nozzle surface compatibility are displacing petroleum-based alternatives in California and Texas elementary deployments. REACH compliance investments are accelerating certified supply chain premiums.
- ABS:Acrylonitrile butadiene styrene retains structural strength advantages for engineering prototypes. ECHA substance-of-very-high-concern listings for styrene-based plasticizers are forcing costly reformulation cycles with uncertain performance parity.
- Nylon:Polyamide grades serve mechanical repair applications requiring chemical resistance and layer adhesion strength. Medical modeling applications are driving interest in sterilizable variants.
- Others:Specialized copolymers, flexible TPU formulations, and wood-filled composites occupy niche artistic and functional segments with limited filament diameter standardization.
Most installed capacity flows through PLA. Expansion is gaining share fastest in Nylon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
STEAM educators and maker-space technicians cluster in specific metropolitan zones where procurement infrastructure and safety certification pathways have matured. These talent concentrations anchor demand across distinct regulatory environments.
United States
K-12 district purchasing cooperatives in California and Texas are consolidating filament-compatible hardware procurement through Amazon Business and dedicated educational supply platforms. FDA material safety standards for indirect food-contact plastics shape product design constraints for classroom-deployed units. Austin and Los Angeles maker-space clusters sustain demonstration inventory and trained staff for retail channel development.
Germany
Engineering studios in Berlin and hardware startups in Bavaria sustain demand for precision temperature control in professional prototyping workflows. EU RoHS restrictions on electrical component heavy metals and REACH compliance requirements accelerate certified supply chain premiums. The Eindhoven-Berlin corridor anchors maker-space infrastructure with dedicated retail channels and bulk filament subscription models.
China
Electronics repair technicians in Shenzhen and informal maker communities across community colleges drive battery-operated unit adoption. GB standards for lithium-ion battery enclosures force parallel tooling configurations for domestic and export SKUs. Guangdong Province ceramic resistor manufacturing clusters create single-source vulnerability for temperature-control subassemblies serving global OEM supply relationships.
India
Regional educational procurement authorities are expanding maker-space budgets ahead of BIS certification enforcement deadlines for battery-operated electronics. Mandatory electronics safety standards create first-mover positioning for compliant OEMs entering the market. Maharashtra and Karnataka industrial zones concentrate assembly operations for export-oriented manufacturers.
Japan
Gallery studios in Tokyo and Osaka sustain premium demand for multi-material capability and fine nozzle diameters in sculptural applications. METI industrial standards and JIS certification requirements filter import compatibility for professional-grade equipment. The Kanto region anchors specialized filament distribution networks serving artistic and medical modeling verticals.
Global 3D Pens Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between premium positioning anchored by certification pipelines and scale-driven OEM supply relationships serving battery-operated segments. Three archetypes dominate: filament-certification specialists, manufacturing-scale fabricators, and brand-strength incumbents controlling educational supply chains. Geographic expansion and strategic partnerships represent the dominant competitive moves as regional compliance divergence fragments supply chain configurations.
Within the certification-specialist tier, MYNT3D exemplifies premium positioning sustained across multiple geographies through compliant supply chains. WobbleWorks anchors brand strength through channel control in educational procurement systems. Zhuhai Sunlu Industrial occupies the scale-driven position, dominating OEM supply relationships for cordless configurations. These three represent distinct strategic postures rather than direct segment overlap.
| Leading Market Players |
|---|
| MYNT3D |
| Scribbler |
| WobbleWorks (3Doodler) |
| 3DSimo |
| 7Tech |
| Zhuhai Sunlu Industrial |
| CreoPop |
| XYZprinting |
| LIX PEN LTD |
| Others |
Supply Flow & Price Mechanics
Ceramic heating element costs from Guangdong Province flow through temperature-control firmware licensing to separate plug-in professional tiers from battery-operated education SKUs. REACH compliance investments in filament certification pipelines then widen spreads between certified PLA supply chains and commodity ABS alternatives serving price-sensitive hobbyist channels.
Pricing Analysis
Bundled filament subscription models dominate institutional procurement through regional K-12 purchasing cooperatives, while unbundled hardware-only transactions persist in retail hobbyist channels. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked professional units with sterilizable filament compatibility from basic classroom disposables. Cost compression in battery-operated education tiers is intensifying because India's BIS certification deadlines are compressing launch timelines for non-compliant OEMs. Hobbyists exhibit highest price sensitivity, while medical prototyping professionals accept premium positioning for precision temperature control.
Supply Chain Analysis
Certification gating through REACH, RoHS, and FDA material safety standards fragments supplier bases into compliant and non-compliant tiers with divergent cost structures. Manufacturing concentrates in China, Germany, and the United States, with ceramic resistor subassemblies drawing from Guangdong clusters and precision firmware development anchored in German engineering studios. Single-source vulnerability in temperature-control subassemblies creates supply chain risk for global OEM relationships. Distribution runs through Amazon Business and dedicated educational supply platforms in institutional channels, while DIY retail and direct-to-consumer platforms serve individual purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where STEAM curriculum mandates across K-12 systems generate recurring filament demand through institutional procurement channels.
For Market Incumbents: To counter desktop 3D printer substitution in prototyping workflows, deepen channel control through bulk filament subscription lock-in with regional educational purchasing cooperatives. Accelerate backward integration into certified PLA supply chains to capture REACH compliance premiums before ECHA additive restrictions force competitor reformulation cycles. For New Entrants and Emerging Players: Begin with India's BIS certification pathway for battery-operated electronics ahead of enforcement deadlines, targeting Maharashtra and Karnataka industrial zones for assembly partnerships. Medical modeling applications in pre-surgical anatomical visualization offer the most penetrable white-space vertical, with sterilizable filament compatibility as the specific go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for filament-certification specialists because regulatory divergence between EU REACH, US FDA, and China GB standards fragments supply chains and rewards multi-territory compliance infrastructure. Over the projection horizon, acquisition targets should demonstrate certified supply chain positioning across at least two major regulatory jurisdictions. The signal to watch is BIS certification completion rates among battery-operated OEMs entering Indian educational procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Filament Certification Pipeline Investment | REACH and FDA compliance investments open premium positioning in European and North American institutional channels. |
| Battery Chemistry Scale-Up | Lithium-polymer cell density improvements extend cordless operation windows for field-based repair applications. |
| Educational Supply Chain Partnership | Amazon Business and regional purchasing cooperatives displace traditional distributors in K-12 procurement. |
| Low-Temperature PLA Reformulation | Sub-60°C nozzle compatibility satisfies California and Texas elementary-grade safety mandates. |
| Medical Modeling Vertical Entry | Sterilizable filament grades and precision temperature control capture pre-surgical visualization demand in hospital systems. |
Methodological Framework
Multiple input streams — primary interviews with filament suppliers, educational procurement officers, and maker-space operators, alongside secondary validation through customs records, SEC filings from diversified conglomerates, and ECHA substance registration databases — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed conversations with OEM manufacturing directors, STEAM curriculum coordinators, and retail channel managers across the United States, China, and Germany. Secondary sources included trade data from battery component imports, CE marking registration files, and institutional purchasing cooperative contract disclosures.
Data-stream reconciliation across product type, end user, application, material, and regional regulatory cluster dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic indicators and technology adoption curves. Industry-specific forecast inputs incorporated lithium-polymer cell density improvement trajectories and BIS certification timeline assumptions for Indian market entry.
Several conditions sit outside the modeled scope, including abrupt ECHA substance-of-very-high-concern listings, ceramic heating element supply disruptions from Guangdong manufacturing clusters, and desktop 3D printer price compression below functional prototyping thresholds. Forecasts reflect documented assumptions regarding STEAM curriculum mandate continuity and filament diameter standardization convergence. A model refresh is warranted upon material change in EU electrical equipment safety framework implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
3D Printing Market
3D Printing Technology
3D Printing in Aviation Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
Military 3D and 4D Printing Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
Food 3D Printing Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market
3D Printing Technology
3D Printing Software Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
Online 3D Printing Service Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
North America 3D Printing Market