
 Digital Printing Market | 2026-2036
Digital Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Printing Market Intelligence
Digital front-end workflow software is fragmenting traditional prepress architectures into distributed, cloud-connected production nodes. HP Inc. leverages its Indigo electrophotography platform to anchor high-volume label and flexible packaging workflows across North America and Europe. Canon Inc. competes through imagePRESS and Colorado inkjet lines that sustain margin pools in commercial photo and wide-format signage. Ricoh Company Ltd. differentiates via lean, toner-based systems that occupy mid-volume corporate in-plant environments.
Digital printing encompasses the direct transfer of electronic image files onto substrates using non-impact mechanisms such as piezoelectric inkjet heads, thermal transfer arrays, or electrophotographic drums operating at resolutions from 600 to 2400 dpi without intermediate plates or cylinders. Its primary commercial purpose is the economic production of variable-data, short-run, or on-demand output across packaging, marketing collateral, and functional decor. Inkjet printers lead installed base expansion due to substrate versatility and declining per-page economics, while UV printing technology captures premium margin pools through instant curing and outdoor durability. Direct-to-garment systems represent the fastest-growing technology segment as fashion brands adopt micro-batch apparel decoration.
FDA food-contact regulations in the United States govern migration limits for digital inks used in primary packaging, while the EU REACH framework restricts hazardous photoinitiators and pigment formulations across member states. China's SAMR enforces GB standards for labeling quality and environmental compliance on domestically sold equipment. Stakeholders must monitor evolving chemical compliance thresholds and substrate certification requirements as sustainability mandates tighten across all three jurisdictions.
Market Dynamics
Packaging converters across Germany, the United States, and China are accelerating fleet modernization to capture short-run brand contracts, compressing traditional offset economics and redistributing margin pools toward digital-native workflows.
Growth Catalysts
- REACH chemical restrictions:European ECHA mandates on hazardous photoinitiators are pushing OEMs toward water-based and UV-curable ink formulations, expanding addressable substrate portfolios.
- Food-contact compliance:FDA migration limits for digital inks in primary packaging are standardizing safety protocols, opening shelf-ready flexible packaging to digital production.
- Direct-to-garment systems:Fashion micro-batch decoration is displacing screen-printing minimums, with apparel brands in North America and Europe adopting on-demand fulfillment models.
Market Restraints
- Piezoelectric printhead supply:Concentrated manufacturing in East Asia creates input vulnerability for inkjet system OEMs, with single-source dependencies for high-frequency nozzle arrays.
- UV-curable ink feedstock volatility:Photoinitiator and oligomer costs fluctuate with petrochemical inputs, compressing margin stability for wide-format signage producers.
- Substrate certification timelines:Brand-owner validation cycles for new material-ink combinations extend 12-18 months, delaying revenue recognition on technical innovations.
Strategic Opportunities
- China's GB standards enforcement:SAMR labeling quality mandates are accelerating domestic equipment replacement, creating openings for compliant inkjet and electrophotography platforms.
- Pharmaceutical serialization:Track-and-trace regulations across Europe and North America are mandating variable-data printing on secondary packaging, expanding security-ink applications.
- Cloud-connected prepress nodes:Distributed workflow architectures are enabling print-service networks to pool capacity across metropolitan clusters, reducing stranded asset risk.
Industry Challenges
- Color management specialization:ICC profile engineering and spectral calibration expertise shortages constrain quality consistency across multi-site brand deployments.
- Legacy MIS integration:ERP connectivity gaps between digital front-end software and established print-broker accounting systems delay job onboarding and invoicing automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Printing Market |
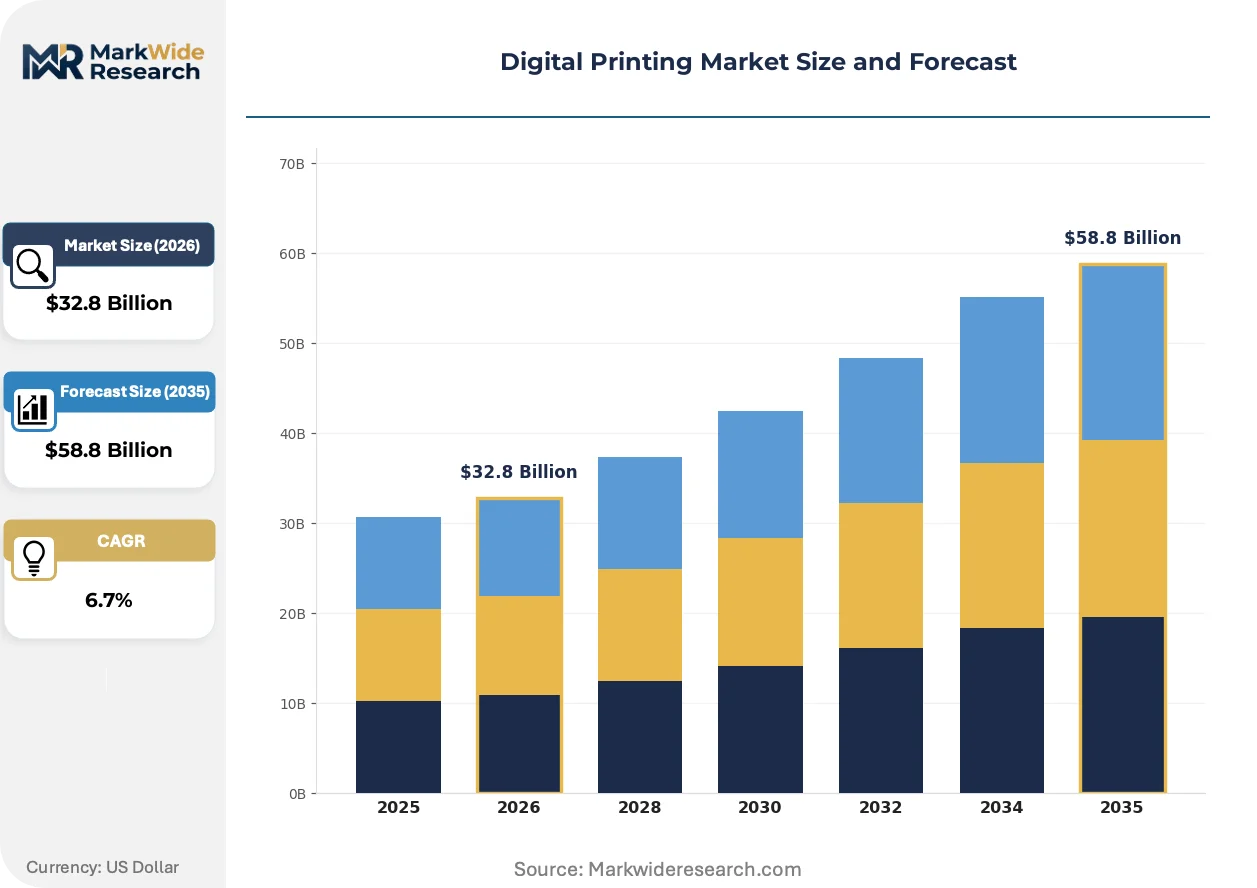
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $58.8 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Laser Printers, 3D Printers, Textile Printers Technology: UV Printing, Dye Sublimation, Direct-to-Garment, Digital Flexography Application: Packaging, Labeling, Signage, Commercial Printing End User: Retail, Manufacturing, Education, Personal |
| Companies Covered | Konica Minolta, Vistaprint, HP Inc., Landa Corporation Ltd., Ricoh Company Ltd., Canon Inc., Fujifilm Holdings Corporation, SCREEN Holdings, Xerox Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Printing Market Strategic Shifts & Innovations
Electrophotography and inkjet architectures are converging on packaging-grade productivity thresholds, while regulatory chemical frameworks and brand sustainability mandates are rewriting formulation specifications and equipment procurement criteria.
Single-pass inkjet arrays with fixed piezoelectric heads spanning full web widths are rendering obsolete multi-pass scanning architectures in corrugated and folding-carton applications. European packaging converters in Germany and the Netherlands are retrofitting legacy flexo lines with these systems to capture 500- to 5,000-unit brand runs. The structural consequence is margin compression for conventional plate-making and cylinder engraving services.
EU REACH Annex XVII restrictions on benzophenone and ITX photoinitiators are forcing reformulation of UV-curable food-contact inks toward safer alternatives. Ink manufacturers are accelerating migration to LED-UV systems with reduced energy consumption and eliminated ozone emissions. German and French converters face the most immediate compliance deadlines, with brand owners demanding full material certification documentation.
Brand procurement teams are consolidating print spend through managed print-service contracts that bundle equipment, consumables, and workflow software into per-page or per-package pricing. This model displaces traditional capital-acquisition cycles and shifts risk to OEM financing arms. The pattern is most advanced in North American beverage and personal-care verticals, where marketing procurement officers now specify digital-native suppliers for seasonal and limited-edition launches.
Digital Printing Market Segmentation
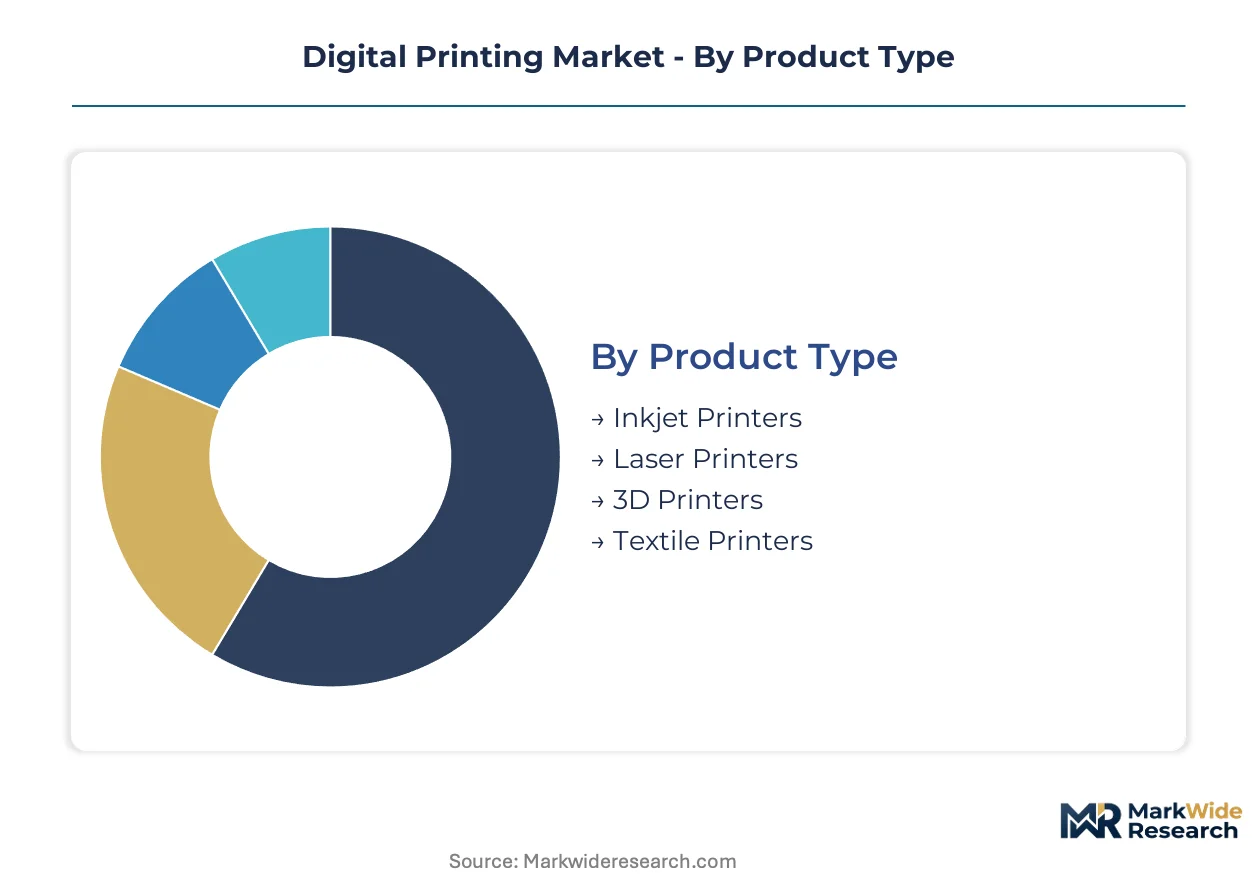
Segmentation in digital printing reveals divergent service intensity and margin profiles across hardware categories. Each dimension carries distinct aftermarket revenue potential and customer retention mechanics.
Product Type:
After-sales-service intensity varies sharply across hardware architectures, with industrial inkjet systems demanding continuous nozzle maintenance and laser platforms requiring periodic drum replacement.
- Inkjet Printers:Piezoelectric or thermal head arrays deposit aqueous, solvent, or UV-curable droplets at 600–2400 dpi. Demand concentrates in corrugated packaging converters across Germany and the United States, where short-run brand contracts require rapid changeover capability.
- Laser Printers:Electrophotographic engines fuse toner via heat and pressure onto paper or synthetic substrates. Corporate in-plant environments in China and Japan anchor replacement cycles, driven by document security requirements and managed print-service contracts.
- 3D Printers:Additive fabrication systems build resin or polymer objects layer-by-layer.
- Textile Printers:Direct-to-fabric systems for apparel and soft signage decoration.
By volume, Inkjet Printers leads. By growth pace, Textile Printers is ahead.
Technology:
Cost tier separation between premium UV-curable platforms and economy dye-sublimation systems determines customer acquisition economics and lifetime value calculations.
- UV Printing:LED-UV or mercury-arc curing instantly polymerizes ink for outdoor durability and substrate versatility. Wide-format signage producers in the United States and France absorb premium equipment costs to capture high-margin point-of-sale contracts.
- Dye Sublimation:Heat-transfer process embeds disperse dyes into polyester coatings for photographic output. Commercial photo labs and personalized merchandise vendors in Japan and Germany sustain installed base through consumable lock-in.
- Direct-to-Garment:Water-based inkjet deposition onto cotton and cotton-blend fabrics.
- Digital Flexography:Hybrid plateless imaging for flexible packaging and label webs.
By margin contribution, UV Printing dominates. By expansion trajectory, Direct-to-Garment is climbing the fastest.
Application:
Application focus shapes customer concentration risk, with packaging converters consolidating spend while commercial print shops fragment across metropolitan clusters.
- Packaging:Folding carton, corrugated, and flexible substrate decoration with food-contact compliance requirements. German and Chinese converters modernize fleets to capture 500- to 5,000-unit brand runs from FMCG procurement teams.
- Labeling:Pressure-sensitive and shrink-sleeve variable-data printing for pharmaceutical serialization mandates.
- Signage:Outdoor and indoor display graphics across retail and construction verticals.
- Commercial Printing:Marketing collateral, direct mail, and book-on-demand production.
By revenue concentration, Packaging leads. By contract velocity, Labeling is gaining share fastest.
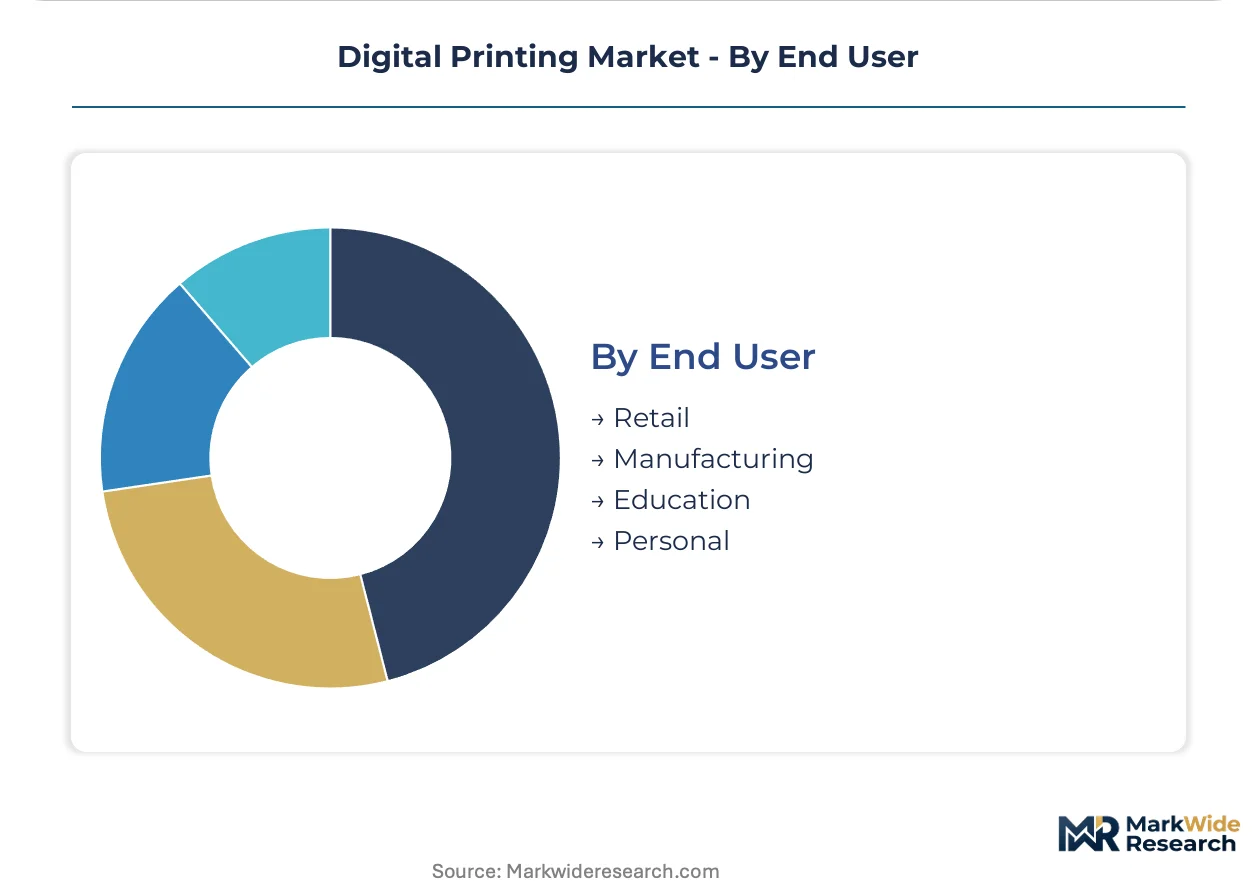
End User:
End-user maturity determines procurement sophistication, with retail and manufacturing buyers demanding outcome-based pricing while personal and education segments remain transaction-driven.
- Retail:In-store signage, packaging, and promotional material production. United States and United Kingdom apparel and cosmetics brands deploy on-demand fulfillment to compress seasonal inventory risk.
- Manufacturing:Industrial marking, functional decor, and prototype fabrication.
- Education:Academic poster, thesis, and instructional material printing.
- Personal:Consumer photo products, custom apparel, and hobbyist fabrication.
By contract value, Retail leads. By volume growth, Personal is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging procurement officers in Germany, the United States, and China command the largest contract volumes, while regulatory divergence across FDA, REACH, and SAMR frameworks fragments compliance roadmaps for equipment vendors.
Germany
REACH Annex XVII restrictions on benzophenone photoinitiators are accelerating LED-UV ink adoption among folding-carton converters. ECHA enforcement deadlines in 2025-2026 compress reformulation timelines for UV-curable food-contact applications. The Rhine-Ruhr industrial corridor hosts concentrated packaging modernization, with Düsseldorf and Cologne converters retrofitting legacy flexo lines with single-pass inkjet arrays.
United States
FDA migration limits for digital inks in primary packaging are standardizing safety protocols across flexible packaging converters. Beverage and personal-care brands in the Midwest and Southeast are consolidating print spend through managed service contracts with per-page pricing. Chicago and Atlanta metropolitan clusters anchor the highest concentration of corrugated digital press installations serving e-commerce fulfillment networks.
China
SAMR labeling quality mandates under GB standards are accelerating domestic equipment replacement cycles for non-compliant legacy systems. Dual carbon goals are pushing state-owned packaging groups toward water-based inkjet platforms with reduced volatile organic compound emissions. The Yangtze River Delta, particularly Shanghai and Suzhou manufacturing zones, concentrates the fastest fleet turnover for pharmaceutical serialization applications.
Japan
METI efficiency standards for industrial printing equipment are tightening energy consumption thresholds for new press installations. Commercial photo labs and corporate in-plant environments in Tokyo and Osaka sustain replacement demand for high-resolution toner systems. Kansai region converters specialize in short-run premium packaging for cosmetics export markets requiring variable-data decoration.
United Kingdom
Post-Brexit divergence from EU chemical regulations is creating parallel compliance tracks for ink formulations serving domestic versus continental European markets. Retail apparel brands in London and Manchester are adopting on-demand fulfillment models for micro-batch garment decoration. The Midlands packaging belt, centered on Birmingham and Leicester, is retrofitting wide-format signage capacity toward corrugated e-commerce applications.
Digital Printing Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tiers. Electrophotography and inkjet architectures anchor distinct margin pools, with consolidated positions in high-volume label production and fragmented competition in mid-volume commercial segments. Three archetypes dominate: full-platform OEMs with captive consumables ecosystems, regional system integrators with customized workflow bundles, and niche specialists in textile or 3D deposition. M&A activity concentrates on workflow software acquisitions, while capacity expansion targets single-pass inkjet array manufacturing.
Within the full-platform OEM tier, HP Inc., Canon Inc., and Ricoh Company Ltd. exemplify contrasting technology bets. HP Inc. anchors high-volume flexible packaging workflows through electrophotography platforms. Canon Inc. sustains margin pools across commercial photo and wide-format signage through diversified inkjet and toner architectures. Ricoh Company Ltd. occupies mid-volume corporate in-plant environments with lean toner-based systems and managed print-service financing arms.
| Leading Market Players |
|---|
| Konica Minolta |
| Vistaprint |
| HP Inc. |
| Landa Corporation Ltd. |
| Ricoh Company Ltd. |
| Canon Inc. |
| Fujifilm Holdings Corporation |
| SCREEN Holdings |
| Xerox Holdings Corporation |
| Others |
Cost & Logistics Intelligence
East Asian piezoelectric printhead manufacturing concentrates upstream supply for inkjet system OEMs, anchoring margin pools in the aftermarket service tier where nozzle maintenance and replacement cycles generate recurring revenue streams.
Pricing Analysis
Cost-plus contracts with photoinitiator and oligomer indexation dominate UV-curable ink supply agreements. Three-tier pricing structure across premium LED-UV, standard mercury-arc, and economy aqueous formulations separates certification-grade food-contact systems from general commercial applications. Pricing pressure stems from petrochemical feedstock volatility squeezing wide-format signage producers. Commercial print shops exhibit highest price sensitivity, while pharmaceutical serialization mandates render label converters relatively inelastic.
Supply Chain Analysis
Foxconn and Jabil Electronics hold contract-manufacturing capacity for digital press assembly, with production concentrated in China, Taiwan, and Vietnam. Raw material dependencies center on Japanese piezoelectric ceramics, German precision optics, and Chinese rare-earth magnet components. Single-source vulnerability for high-frequency nozzle arrays creates input risk. Distribution runs through OEM direct-sales teams and authorized dealer networks serving metropolitan print-service clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital printing incumbents face substitution defense against analog-to-digital migration accelerating beyond offset and flexo retention thresholds.
For Market Incumbents: Entrench consumables lock-in through captive ink formulation ecosystems and cloud-connected workflow software. Backward integration into LED-UV photoinitiator supply secures margin stability against petrochemical volatility. Defensive capacity addition in Rhine-Ruhr and Yangtze River Delta clusters captures brand-owner consolidation of short-run packaging spend.
For New Entrants and Emerging Players: India's underpenetrated corrugated packaging conversion market offers white-space entry with water-based inkjet platforms compliant with emerging environmental mandates. Direct-to-garment micro-batch fulfillment networks in Southeast Asian apparel manufacturing zones present second penetration vector. Go-to-market angle should emphasize per-page managed service financing to bypass capital-acquisition barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional system integrators holding customized workflow bundles for mid-volume corporate in-plants. Long-term viability hinges on software-defined service revenue displacing hardware transactional exposure. Acquisition targets should display captive consumables attach rates above industry medians. Watch FDA food-contact compliance certification timelines as inflection signal for flexible packaging digital adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| LED-UV Ink Formulation Migration | ECHA REACH Annex XVII deadlines in Germany and France accelerate compliant system replacement cycles. |
| Cloud-Connected Prepress Platform | HP Indigo and Canon imagePRESS integration enables distributed production node pooling across metropolitan clusters. |
| Single-Pass Inkjet Array Manufacturing | Fixed piezoelectric head web-width systems displace multi-pass scanning architectures in corrugated applications. |
| Managed Print-Service Financing Arm | Ricoh and Xerox per-page pricing models shift capital risk from brand procurement to OEM balance sheets. |
| Pharmaceutical Serialization Compliance | FDA track-and-trace mandates expand variable-data security ink applications in secondary packaging. |
Research Approach
Findings reconcile primary fieldwork against secondary review of OEM technical documentation, ECHA regulatory filings, and FDA food-contact guidance. Packaging converter operations directors, ink formulation chemists, and brand procurement officers provided operational validation. SEC 10-K equipment revenue disclosures, SAMR GB standards bulletins, and trade customs data furnished secondary anchors. Bottom-up press installation counts triangulate against top-down consumables spend estimates.
Forecast inputs span hardware architecture type, ink curing technology, and substrate application across the projection horizon. Segmentation dimensions model product type, technology tier, end-use vertical, and geographic regulatory cluster. CAGRs derive from installed base expansion rates and consumables attach rate assumptions. Industry-specific inputs incorporate REACH chemical reformulation timelines and pharmaceutical serialization mandate compliance curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-owned packaging groups or consolidated beverage brand procurement teams would shift outcomes. Quarterly review of ECHA enforcement actions, FDA migration limit updates, and SAMR labeling quality audits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Digital Paper System Market
Printing Technology
Commercial Printing Outsourcing Market
Printing Technology
Print Equipment Market
Printing Technology
Cloud Print Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Barcode Printers and Consumables Market
Printing Technology
Industrial Printer Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Global Wireless Printers Market
Printing Technology
Card Printers Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Europe Commercial Printing Market
Printing Technology
Digital Presses Market
Printing Technology
Variable Data Printing Market
Printing Technology
Digital Printing on Wood Market