
 Military 3D and 4D Printing Market | 2026-2036
Military 3D and 4D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Military 3D and 4D Printing Market Foresight
Defense contractor demand for flight-critical metal components is hardening as airframe OEMs shift from polymer prototyping to certified titanium production. Stratasys Ltd leverages its F900 platform deployments across U.S. Air Force maintenance depots to sustain recurring material revenue streams. EOS GmbH anchors European defense supply chains through its direct metal laser sintering systems qualified under German military aerospace standards. Norsk Titanium US Inc dominates plasma rapid deposition for structural airframe parts, occupying a niche that conventional powder-bed systems cannot match.
Military 3D and 4D printing encompasses additive manufacturing processes that build objects layer-by-layer from digital models, with 4D printing incorporating shape-memory polymers that respond to environmental stimuli such as temperature or pressure changes after fabrication. Electron beam melting achieves full-density titanium-6Al-4V parts with tensile strengths exceeding 900 MPa, enabling direct replacement of forged components in rotorcraft and unmanned aerial systems. Selective laser sintering leads technology adoption for non-critical polymer tooling and drone housings where surface finish tolerances of ±0.1 mm suffice. Printing materials represent the fastest-growing segment as defense-qualified metal powders command premiums over commercial grades due to traceability and lot certification requirements.
The U.S. Department of Defense additive manufacturing roadmap, NATO STANAG guidelines, and FAA airworthiness certification pathways collectively determine which processes transition from prototype to production. EPA emissions standards for metal powder handling and OSHA respiratory protection mandates shape facility investment requirements for in-house military printing operations. Stakeholders must monitor evolving qualification protocols for multi-material 4D structures that self-assemble in contested logistics environments.
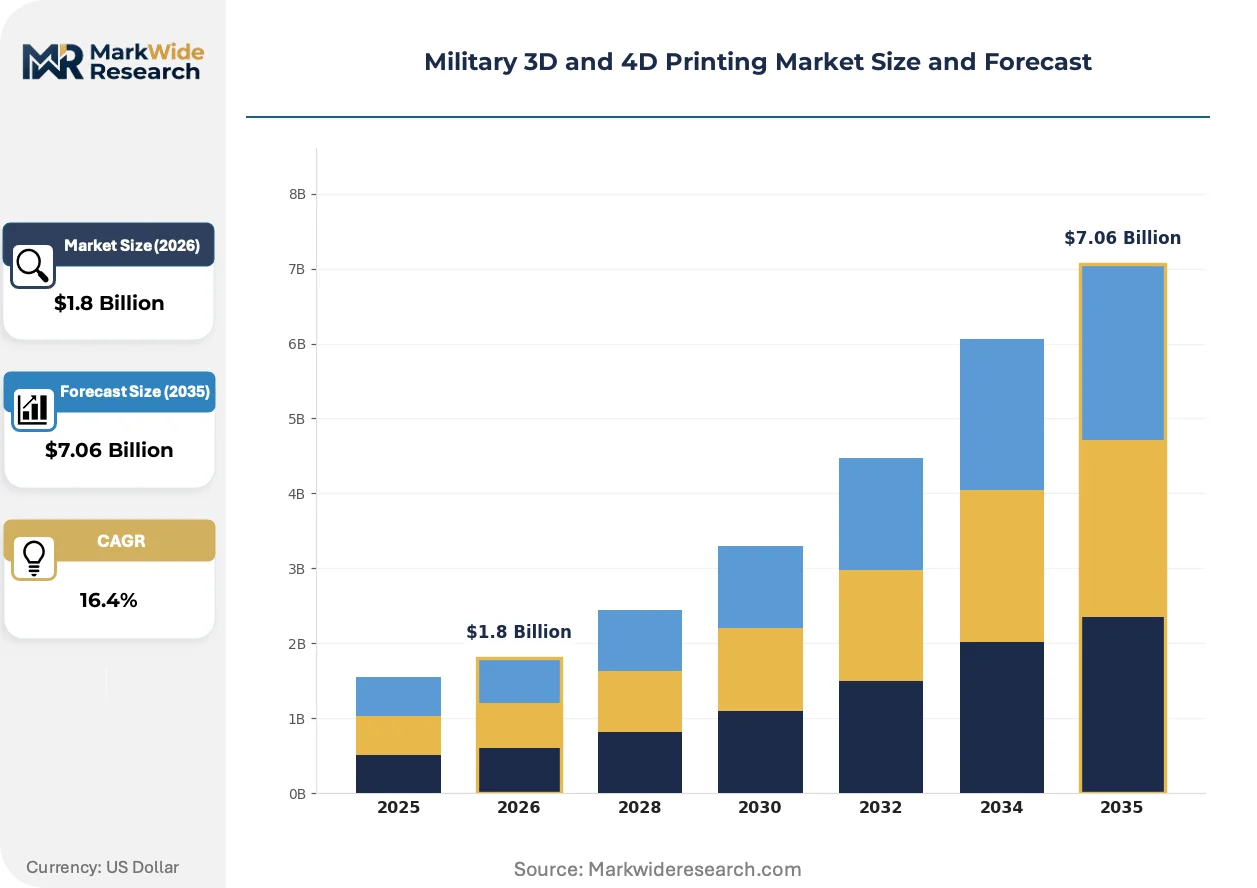
Market Dynamics
The U.S. Department of Defense additive manufacturing roadmap is compressing certification timelines for flight-critical metal components, pulling titanium and nickel superalloy printing from prototype labs into active production lines for rotorcraft and unmanned systems.
Growth Catalysts
- NATO STANAG standardization:Battlefield repair kit interoperability mandates are accelerating qualification protocols for deployable metal printing systems across allied defense forces.
- Titanium-6Al-4V powder-bed fusion:Full-density tensile strengths exceeding 900 MPa now match forged specifications, enabling direct substitution in structural airframe applications without redesign.
- Ohio and Texas manufacturing clusters:Concentrated defense contractor presence around Wright-Patterson Air Force Base and Army Futures Command facilities is creating localized demand density for qualified additive suppliers.
Market Restraints
- Defense-qualified powder premiums:Lot traceability and certification requirements push metal powder costs substantially above commercial grades, constraining cost-competitive scaling.
- German aerospace qualification bottlenecks:EOS GmbH's near-monopoly on direct metal laser sintering systems under Bundeswehr standards creates single-source vulnerability for European supply chains.
- Electron beam melting throughput limits:Vacuum chamber processing speeds lag behind conventional forging for high-volume jet engine component runs.
Strategic Opportunities
- South Korean defense modernization:KF-21 fighter and unmanned wingman programs are opening qualification pathways for foreign additive suppliers under offset agreements.
- 4D shape-memory polymer integration:Self-assembling structures responding to temperature stimuli offer contested logistics applications where pre-positioned spare storage is impossible.
- FAA airworthiness certification reciprocity:Dual-use component approvals are streamlining military-civilian technology transfer for drone airframe manufacturers.
Industry Challenges
- Multi-material 4D qualification gaps:No standardized test protocols exist for shape-memory polymers operating across extreme temperature and pressure gradients in combat environments.
- Metal powder handling compliance:EPA emissions standards and OSHA respiratory protection mandates require capital-intensive facility upgrades for in-house military printing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military 3D and 4D Printing Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prototyping Equipment, Manufacturing Systems, Printing Materials, Software Solutions Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Electron Beam Melting Application: Rapid Prototyping, Parts Fabrication, Tooling, Complex Structures End User: Defense Contractors, Military Organizations, Research Institutions, Technology Providers |
| Companies Covered | Stratasys Ltd, 3D Systems Corporation, Norsk Titanium US Inc, EOS GmbH, Engineering & Manufacturing Services Inc, 3T Additive Manufacturing Ltd, Markforged Holding Corporation, GE Additive, Renishaw plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military 3D and 4D Printing Market Shifts & Advancements
Defense procurement patterns are pivoting from polymer prototyping tools toward certified production systems capable of generating recurring material revenue through depot-level sustainment contracts.
Plasma rapid deposition technology is automating structural titanium fabrication for airframe components that exceed the build envelope constraints of conventional powder-bed systems. Norsk Titanium US Inc has secured sole-source positions on F-35 and T-7A programs where forging alternatives face multi-year lead times. The process is automating near-net-shape production of bulkheads and wing spars previously machined from solid billets, compressing buy-to-fly ratios from 15:1 toward 3:1.
EU Green Deal industrial emissions benchmarks are tightening energy intensity requirements for metal additive manufacturing facilities operating within European defense supply chains. ECHA REACH compliance for nickel superalloy powder handling is forcing facility relocations toward regions with renewable grid access. German aerospace suppliers are responding by consolidating electron beam melting operations in Lower Saxony to leverage offshore wind power purchase agreements.
Air Force maintenance depots are unbundling hardware ownership from material supply through performance-based logistics contracts with original equipment manufacturers. Stratasys Ltd retains F900 platform assets at Tinker Air Force Base and Hill Air Force Base while charging per-part fees for certified ULTEM 9085 drone housings. This arrangement concentrates in Texas and Oklahoma installations where organic engineering capacity supports field-level design modifications without OEM intervention.
Military 3D and 4D Printing Market Segmentation
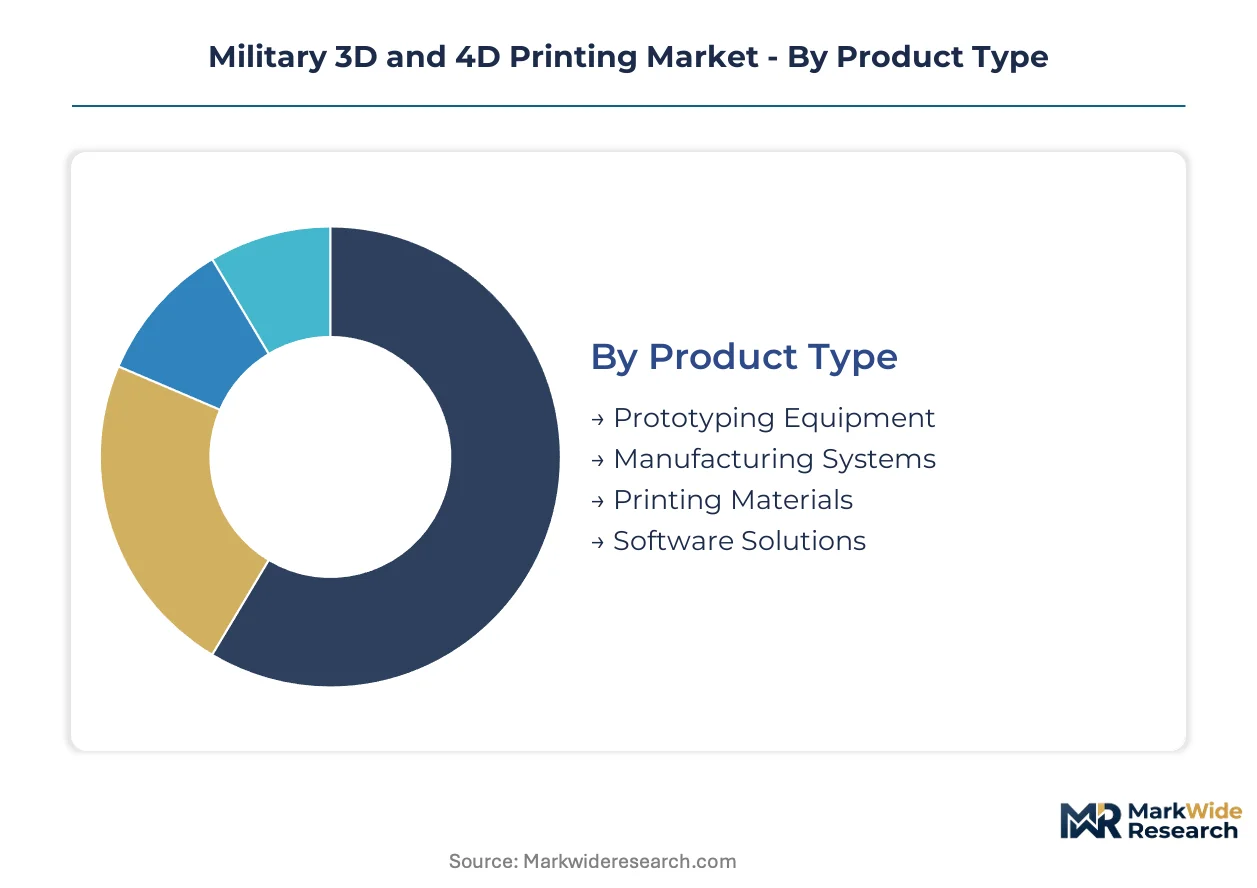
Defense procurement officers segment additive manufacturing by qualification burden and operational tempo. Each category reflects distinct buyer risk tolerances, from flight-critical metal systems to deployable polymer field kits.
Product Type:
Buyers in this category separate by capital commitment and recurring revenue appetite. Defense contractors with depot sustainment contracts favor manufacturing systems that lock in material supply agreements. Research institutions prioritize prototyping equipment with open-architecture material parameters.
- Prototyping Equipment:Entry-level fused deposition systems dominate military R&D facilities where design iteration speed outweighs certification requirements. U.S. Air Force Research Laboratory installations in Ohio concentrate demand for polymer-based concept validation before metal production handoff.
- Manufacturing Systems:Direct metal laser sintering and electron beam melting platforms command qualification protocols under FAA airworthiness and NATO STANAG guidelines. Texas-based Army Futures Command facilities anchor procurement for certified titanium production lines.
- Printing Materials:Defense-qualified titanium-6Al-4V and nickel superalloy powders carry traceability premiums over commercial grades.
- Software Solutions:Workflow management and build preparation tools integrate with existing PLM systems at prime contractor engineering centers.
Manufacturing Systems leads volumes today; Printing Materials is gaining share fastest.
Technology:
Process selection hinges on material density requirements and surface finish tolerances. Flight-critical applications demand full-density metal consolidation, while field-deployable systems tolerate polymer porosity.
- Fused Deposition Modeling:Thermoplastic extrusion systems service non-structural drone housings and maintenance tooling where ±0.2 mm tolerances suffice. Oklahoma depot installations deploy Stratasys F900 platforms under performance-based logistics contracts.
- Selective Laser Sintering:Polymer powder-bed fusion dominates rapid tooling for composite layup molds in rotorcraft production. German aerospace suppliers under Bundeswehr standards qualify EOS GmbH systems for PA12 flight-certified components.
- Stereolithography:Photopolymer vat polymerization produces high-resolution investment casting patterns for turbine blades.
- Electron Beam Melting:Vacuum-based titanium processing achieves 900+ MPa tensile strengths for structural airframe substitution.
Electron Beam Melting anchors flight-critical revenue; Fused Deposition Modeling shows steepest expansion trajectory in contested logistics applications.
Application:
Operational use case determines certification pathway complexity. Sustainment commands prioritize interchangeable spare production, while development programs emphasize design freedom.
- Parts Fabrication:Certified production of titanium bulkheads and wing spars replaces forged components in F-35 and T-7A programs. Norsk Titanium's plasma rapid deposition compresses buy-to-fly ratios from 15:1 toward 3:1 at Texas manufacturing clusters.
- Rapid Prototyping:Design iteration cycles for unmanned aerial systems accelerate at Wright-Patterson Air Force Base additive manufacturing centers.
- Tooling:Conformal cooling channels in injection molds reduce cycle times for polymer drone component production.
- Complex Structures:Lattice geometries and topology-optimized brackets serve weight-constrained satellite and missile applications.
Parts Fabrication commands premium pricing today; Complex Structures is climbing the fastest as topology optimization software matures.
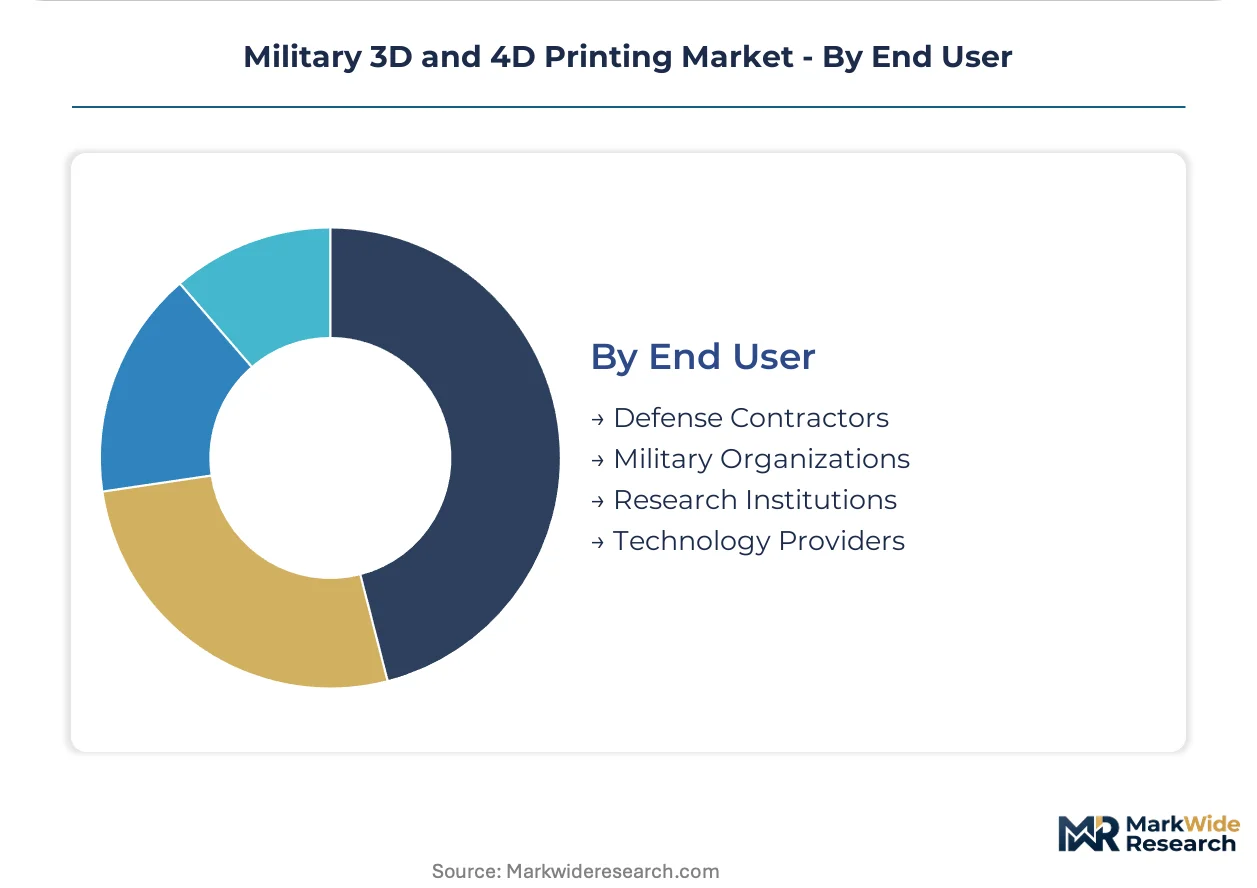
End User:
Procurement authority and technical sophistication divide this category. Prime contractors control qualification budgets; military organizations prioritize operational availability metrics.
- Defense Contractors:Lockheed Martin and Boeing additive manufacturing centers in Texas and California drive certified titanium demand for production airframe contracts. These facilities integrate electron beam melting into existing supply chains under FAA military certification reciprocity.
- Military Organizations:U.S. Air Force maintenance depots at Tinker and Hill Air Force Bases adopt performance-based logistics models for F900 platform sustainment.
- Research Institutions:AFRL and Army Research Laboratory programs advance 4D shape-memory polymer protocols for self-assembling structures.
- Technology Providers:Equipment OEMs and material suppliers position for NATO STANAG standardization compliance.
Defense Contractors dominate current procurement value; Military Organizations is expanding most quickly under organic manufacturing mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense-qualified powder premiums and emissions compliance gaps are driving production migration toward jurisdictions with subsidized renewable energy and streamlined military certification pathways. Facility investment concentrates where national additive manufacturing roadmaps offset qualification costs through direct procurement contracts.
United States
Wright-Patterson Air Force Base and Army Futures Command facilities anchor titanium demand for rotorcraft and unmanned systems. FAA airworthiness certification reciprocity with military standards accelerates dual-use component approvals. Ohio and Texas manufacturing clusters host concentrated electron beam melting operations under Department of Defense additive manufacturing roadmap mandates.
Germany
Bundeswehr aerospace standards and EU Green Deal emissions benchmarks shape facility siting decisions for defense suppliers. ECHA REACH compliance for nickel superalloy powder handling forces consolidation toward Lower Saxony's offshore wind-powered industrial zones. EOS GmbH's direct metal laser sintering systems dominate qualification protocols for European NATO supply chains.
South Korea
KF-21 fighter and unmanned wingman programs generate offset-driven qualification pathways for foreign additive suppliers. MFDS-equivalent defense material standards are harmonizing with NATO STANAG guidelines under bilateral security agreements. Seoul Capital Area defense contractors are integrating plasma rapid deposition for structural airframe components facing multi-year forging lead times.
United Kingdom
RAF maintenance depot privatization is creating performance-based logistics contracts for polymer and metal printing systems. UK Ministry of Defence additive manufacturing strategy documents prioritize battlefield repair kit interoperability with allied forces. Midlands aerospace suppliers qualify Renishaw plc systems under dual-use civilian-military certification frameworks.
Israel
Contested logistics requirements drive demand for deployable field printing systems in remote operational theaters. National security export controls shape technology transfer agreements with NATO partners for qualified metal powder supply. Tel Aviv-area defense technology clusters specialize in topology-optimized lattice structures for weight-constrained missile applications.
Military 3D and 4D Printing Market Competitive Landscape
Capacity expansion dominates the current landscape as equipment manufacturers scale service bureau networks to capture recurring material revenue. The vendor base stratifies between integrated platform-material suppliers and specialized process technology licensors. Three archetypes define positioning: full-stack system providers with captive powder supply, niche deposition specialists occupying build-envelope gaps, and software-anchored workflow integrators. Geographic expansion through NATO-aligned certification partnerships and vertical integration into defense-qualified powder production represent the dominant competitive vectors.
Among North American platform providers, Stratasys Ltd and Norsk Titanium US Inc exemplify divergent specialization strategies. Stratasys occupies the performance-based logistics tier through depot-level F900 platform deployments with unbundled hardware ownership. Norsk Titanium anchors the structural metal deposition niche where plasma rapid deposition exceeds conventional powder-bed build envelopes. EOS GmbH represents the European qualification-heavy archetype, with Bundeswehr-standard system certifications creating regional supply chain stickiness. These three entities collectively illustrate how certification pathway control, rather than unit economics alone, determines sustainable positioning in defense additive manufacturing.
| Leading Market Players |
|---|
| Stratasys Ltd |
| 3D Systems Corporation |
| Norsk Titanium US Inc |
| EOS GmbH |
| Engineering & Manufacturing Services Inc |
| 3T Additive Manufacturing Ltd |
| Markforged Holding Corporation |
| GE Additive |
| Renishaw plc |
| Others |
Supply & Pricing Matrix
Titanium-6Al-4V powder spot indices cascade through defense supply chains into three distinct pricing tiers, with lot-traceable military-grade material commanding substantial premiums over commercial alternatives due to FAA airworthiness and NATO STANAG certification requirements.
Pricing Analysis
Distributor markups on defense-qualified metal powders compress as direct-to-OEM channels expand under performance-based logistics contracts. Three-tier pricing structure across flight-critical, depot-sustainment, and field-deployable certification levels reflects traceability burden and lot-testing overhead. Pricing pressure stems from electron beam melting throughput constraints limiting high-volume jet engine component economics. Research institutions exhibit highest price sensitivity, while prime contractors absorbing sustainment contracts demonstrate lowest sensitivity due to pass-through mechanisms.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Texas and Ohio defense manufacturing clusters, bypassing traditional distribution layers for qualified titanium and nickel superalloy powders. Supply concentration rests on Germany, the United States, and South Korea for electron beam melting system production and certified powder atomization. Raw material dependencies include titanium sponge from Japan, nickel from Canada, and argon gas for vacuum chamber processing. Single-source vulnerability around EOS GmbH's Bundeswehr-standard system certification creates European supply chain risk. Distribution runs through prime contractor additive manufacturing centers and Air Force maintenance depots under unbundled hardware ownership arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal emissions benchmarks and ECHA REACH compliance costs in Germany push production investment toward Texas and Ohio jurisdictions with streamlined military certification pathways and subsidized energy access.
For Market Incumbents: To counter plasma rapid deposition technology displacing conventional powder-bed systems for structural airframe components, incumbent electron beam melting providers should deepen backward integration into defense-qualified titanium powder production and expand capacity within Texas manufacturing clusters where Army Futures Command procurement concentrates. Certification investment in FAA-NATO reciprocity pathways represents the critical defensive lever.
For New Entrants and Emerging Players: Performance-based logistics contractors offer the most penetrable channel entry point for 4D shape-memory polymer systems targeting contested logistics applications where pre-positioned spare storage is impossible. White-space opportunities concentrate in South Korean KF-21 fighter offset agreements and Israeli deployable field printing for remote operational theaters. Go-to-market positioning should emphasize NATO STANAG interoperability compliance from inception.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-material 4D qualification gaps prevent standardized test protocol development for self-assembling structures. Long-term viability favors vertically integrated platform-material providers with captive powder supply and depot-level sustainment contracts. Acquisition targets should display dual-use civilian-military certification frameworks enabling technology transfer. Watch for FAA airworthiness reciprocity announcements as inflection signals for dual-use component approval velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Defense-Qualified Powder Production | Captive titanium-6Al-4V atomization secures margin control against commercial-grade price erosion. |
| Plasma Rapid Deposition Scale-Up | Norsk Titanium's F-35 bulkhead contracts validate near-net-shape automation exceeding powder-bed envelopes. |
| NATO STANAG Certification Investment | Interoperability compliance unlocks allied defense procurement beyond single-nation contracts. |
| Performance-Based Logistics Contracts | Stratasys F900 depot deployments at Tinker and Hill Air Force Bases demonstrate recurring material revenue capture. |
| 4D Shape-Memory Polymer R&D | Self-assembling structures address contested logistics where conventional spare pre-positioning fails. |
Research Methodology
Coverage spans the United States, Germany, South Korea, the United Kingdom, and Israel, with primary inputs from each defense manufacturing cluster combining interviews with additive manufacturing program managers at prime contractors, Air Force depot sustainment officers, powder metallurgy procurement leads, and regulatory affairs directors handling FAA military certification reciprocity. Secondary validation draws from Department of Defense additive manufacturing roadmap publications, NATO STANAG documentation, SEC filings from listed equipment providers, and customs data on titanium powder trade flows. Bottom-up demand modeling from individual program procurement schedules triangulates against top-down defense budget allocation analysis.
Granularity-level modeling disaggregates volume and value across product type, technology, application, and end user dimensions, with additional segmentation by certification tier and geographic manufacturing cluster. CAGRs derive from fitted growth curves applied to program-level procurement timelines and facility investment announcements. Industry-specific forecast inputs include electron beam melting system delivery schedules, plasma rapid deposition contract awards, and 4D polymer qualification protocol development milestones across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to multi-material 4D standardization delays, EU Green Deal emissions compliance cost trajectories, and potential shifts in FAA-NATO certification reciprocity frameworks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing Vacuum Furnaces Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
4D Printing Market
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Additive Manufacturing Software Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
North America Additive Manufacturing Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
Food 3D Printing Market