
 Industrial Printer Market | 2026-2036
Industrial Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Printer Market Insights
The capital-intensity divergence between high-volume OEMs and niche specialists is redrawing competitive boundaries across the industrial printer landscape. HP Inc. leverages its scale in electrophotography and page-wide array architectures to sustain service contracts with packaging manufacturers. Zebra Technologies anchors its position in thermal and RFID-enabled labeling through deep channel control in automated logistics. Canon Inc. differentiates via in-house printhead manufacturing and ink chemistry integration that extends gross margins on continuous inkjet systems.
An industrial printer is a durable, high-duty-cycle output device engineered for continuous or batch production environments, typically rated above 100,000 pages monthly duty cycle with modular ink or toner delivery architectures designed for minimal swap-out downtime. These systems execute primary functions including variable-data marking, decorative surface imaging, and substrate-specific adhesion for commercial and manufacturing workflows. Inkjet platforms, spanning continuous inkjet and drop-on-demand technologies, command the largest installed base among product categories due to versatility across porous and non-porous substrates. Thermal technology dominates barcode and RFID labeling applications where electrophotography lacks media flexibility. Dye sublimation, though narrower in end-user reach, occupies the highest margin pool within technology segments because of colorant chemistry specialization and textile enterprise loyalty.
EPA emissions standards and OSHA workplace exposure limits govern volatile organic compound thresholds in ink formulations across United States manufacturing facilities, while REACH and RoHS directives in Europe restrict hazardous substance content in both consumables and equipment disposal streams. China's GB standards and MIIT energy-efficiency certifications create a dual compliance layer for suppliers targeting domestic electronics assemblers and vehicle manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized or regionalized product platform strategies minimize certification redundancy.
Market Dynamics
High-speed inkjet migration into corrugated packaging workflows is compressing replacement cycles and forcing electrophotography incumbents to defend service-contract renewals through predictive maintenance bundling.
Growth Catalysts
- REACH compliance deadlines:European packaging converters are accelerating capital deployment toward water-based inkjet systems ahead of 2025 substance restriction phase-ins.
- Electronics assemblers in China:Continuous inkjet demand for PCB marking and component traceability is expanding MIIT-certified production lines.
- RFID-enabled thermal transfer:Automated logistics operators are mandating smart-label compatibility across warehouse management system upgrades.
Market Restraints
- Printhead supply concentration:Precision MEMS fabrication capacity clusters in East Asian foundries, exposing OEMs to single-source fragility.
- Pigment chemistry volatility:Specialty colorant precursors face price instability tied to rare earth processing bottlenecks.
- EPA VOC thresholds:Stricter OSHA workplace exposure limits are forcing solvent-ink users toward costly ventilation retrofits or formulation switches.
Strategic Opportunities
- Textile dye sublimation in Vietnam:Apparel manufacturing relocation from China is creating greenfield demand for high-volume fabric imaging systems.
- EU Green Deal procurement mandates:Public-sector packaging tenders now preference equipment with circular-design certification and remanufactured component programs.
- AI-driven print quality inspection:Machine vision convergence with inkjet architectures enables real-time defect correction without line stoppage.
Industry Challenges
- Mechatronics technician scarcity:Fluid dynamics and piezoelectric calibration expertise lags behind installed base expansion in emerging manufacturing clusters.
- Dual certification timelines:Simultaneous GB standard and CE marking compliance for China-bound exports extends product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Printer Market |
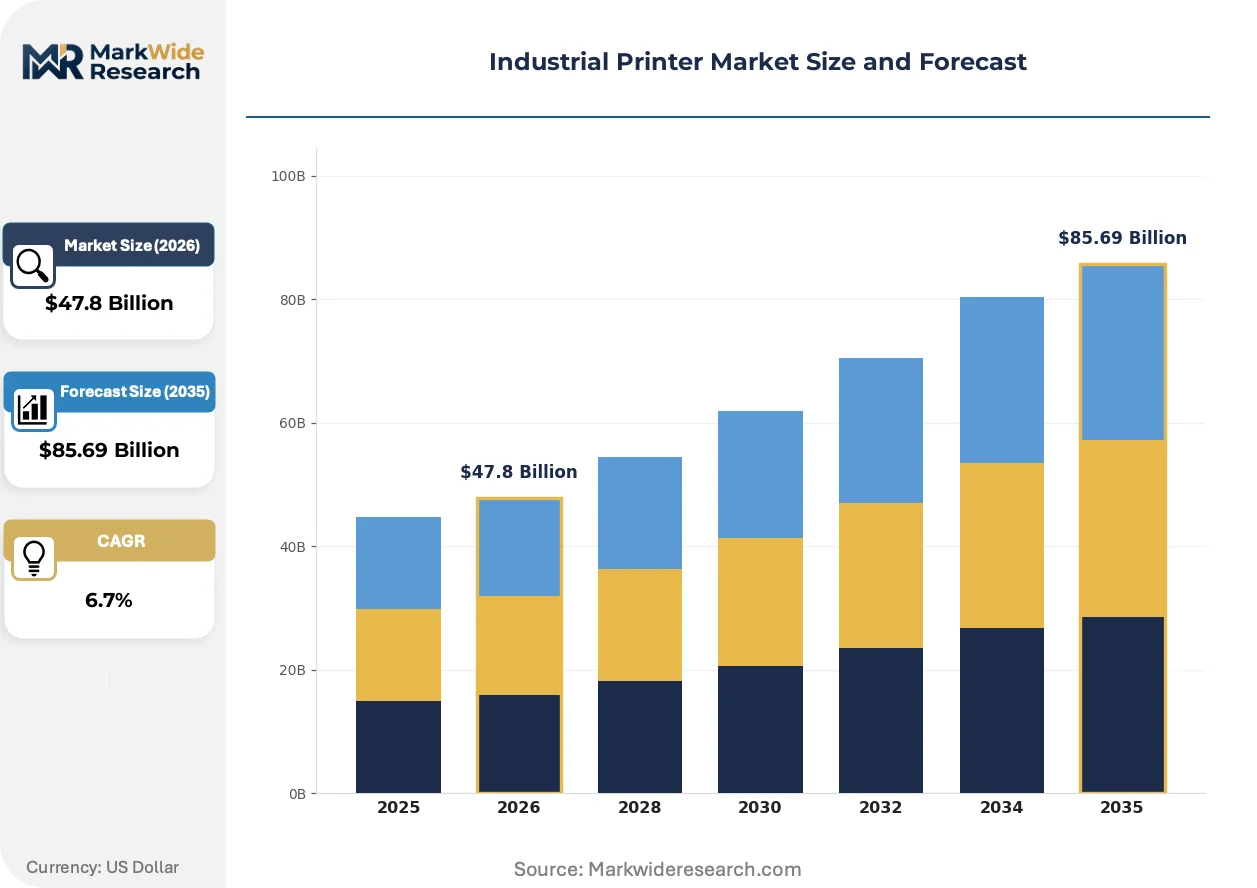
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $85.69 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet, Laser, Thermal, Dot Matrix, LED Technology: Continuous Inkjet, Drop-on-Demand, Solid Ink, Electrophotography, Dye Sublimation Application: Packaging, Textile Decoration, Electronics Manufacturing, Labeling, Automotive OEMs End User: Printing Service Providers, Packaging Manufacturers, Textile Enterprises, Electronics Assemblers, Vehicle Manufacturers |
| Companies Covered | HP Inc., Canon Inc., Seiko Epson Corporation, Brother Industries, Xerox Holdings Corporation, Ricoh Company, Konica Minolta, Kyocera Document Solutions, Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Printer Market Trends and Innovations
Print technology architectures are fragmenting along speed-versus-flexibility tradeoffs, with modular inkjet platforms capturing share from fixed-configuration electrophotography in high-mix production environments.
Drop-on-demand piezoelectric printhead technology is bifurcating the corrugated board segment. Mid-volume converters are adopting single-pass array systems for short-run customization. This compression of makeready time is displacing flexographic pre-press workflows and enabling 24-hour turnaround contracts previously uneconomical at conventional scale.
EPA emissions standards for hazardous air pollutants are tightening volatile organic compound limits in lithographic and screen printing facilities. Packaging manufacturers operating multi-site networks face divergent state-level enforcement interpretations. California's South Coast Air Quality Management District maintains the most stringent local thresholds, pushing converters toward UV-cured inkjet alternatives ahead of federal baseline compliance dates.
Service contract unbundling is reshaping buyer-supplier relationships in automated logistics. Third-party maintenance providers now compete directly with OEM service organizations for thermal printer fleet management. This disintermediation is most advanced in German distribution centers, where independent technical service partnerships reduce total cost of ownership through multi-vendor spare parts pooling and remote diagnostics integration.
Industrial Printer Market Segmentation
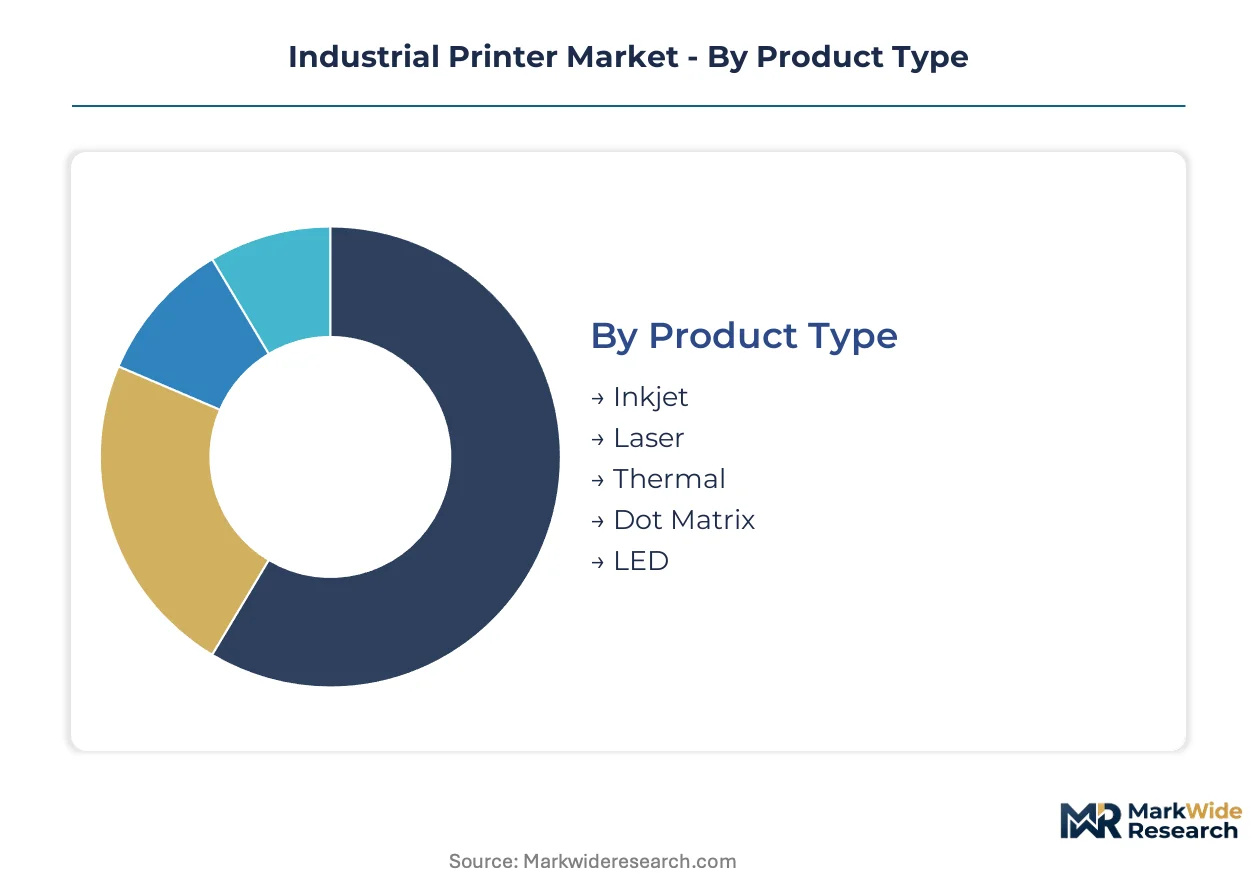
Industrial printer procurement patterns diverge sharply between domestic production workflows and export-oriented manufacturing hubs. Understanding these segment boundaries clarifies why inkjet platforms dominate corrugated packaging in Germany while thermal systems anchor warehouse automation in the United States.
Product Type:
Inkjet and laser systems serve predominantly export-driven manufacturing clusters, whereas thermal and dot matrix equipment concentrate in domestic logistics and legacy industrial documentation.
- Inkjet:Continuous and drop-on-demand architectures handle variable-data marking across porous and non-porous substrates. Demand concentrates in Chinese electronics assemblers and Vietnamese textile exporters where MIIT-certified production lines require high-speed PCB marking and fabric imaging capabilities.
- Laser:Electrophotographic engines deliver precision output for high-volume document and label production. German automotive OEMs and packaging converters in the Netherlands deploy these systems for traceability compliance under REACH substance restrictions.
- Thermal:Direct thermal and thermal transfer technologies dominate barcode and RFID label generation. United States automated logistics operators mandate smart-label compatibility across warehouse management system upgrades, driving fleet refresh cycles.
- Dot Matrix:Impact printing persists in heavy industrial environments requiring multi-part form output. Domestic steel and chemical processors in India retain these systems for invoice and shipping documentation resistant to environmental contamination.
- LED:Solid-state electrophotographic arrays offer energy efficiency advantages over conventional laser engines. Japanese precision manufacturers favor these systems for cleanroom-compatible marking applications.
Inkjet holds the largest share; momentum sits with thermal as RFID mandates expand across automated logistics networks.
Technology:
Cost tier stratification separates continuous inkjet and electrophotography as premium platforms from dye sublimation's specialized margin pool and solid ink's mid-market positioning.
- Continuous Inkjet:Piezoelectric printheads propel electrically charged ink droplets at velocities exceeding 40 meters per second for non-contact marking. Electronics assemblers in Shenzhen and Dongguan deploy these systems for component traceability under China's dual carbon compliance frameworks.
- Drop-on-Demand:Thermal and piezoelectric actuators eject precise ink volumes only when required. Mid-volume corrugated converters in Italy and Spain adopt single-pass arrays for 24-hour customization contracts displacing flexographic pre-press workflows.
- Solid Ink:Wax-based colorant blocks melt and jet without liquid ink logistics. Educational institutions and government facilities in Australia select these systems for reduced packaging waste and simplified consumable management.
- Electrophotography:Laser-driven toner transfer enables high-resolution output at speeds exceeding 200 pages per minute. Commercial print service providers in France and Belgium maintain these fleets for transactional document volumes.
- Dye Sublimation:Solid dye diffusion into polyester substrates produces photographic-quality textile imaging. Apparel manufacturers relocating from China to Vietnam create greenfield demand for high-volume fabric printing systems.
Electrophotography retains installed base dominance; dye sublimation gains share fastest among technology segments as textile production relocates to Southeast Asia.
Application:
Volume concentration varies dramatically across applications, with packaging and labeling commanding fleet scale while textile decoration and electronics manufacturing drive technology specialization.
- Packaging:Corrugated board, folding carton, and flexible film printing workflows demand high-speed inkjet migration. European converters accelerate capital deployment toward water-based systems ahead of ECHA substance restriction enforcement.
- Textile Decoration:Direct-to-garment and roll-to-roll fabric imaging requires dye sublimation and pigment inkjet chemistry. Vietnamese apparel exporters invest in MIIT-certified equipment as manufacturing relocates from Chinese coastal provinces.
- Electronics Manufacturing:PCB marking, component labeling, and device serialization mandate continuous inkjet precision. South Korean semiconductor packaging facilities specify printheads with MEMS fabrication tolerances below 5 microns.
- Labeling:Pressure-sensitive and shrink-sleeve label production spans thermal transfer, inkjet, and laser technologies. Brazilian food processors upgrade fleets to meet ANVISA traceability requirements for packaged goods distribution.
- Automotive OEMs:Under-hood component marking and interior trim decoration require solvent-resistant ink formulations. German vehicle manufacturers specify REACH-compliant colorants for plastic and metal substrate adhesion.
Packaging commands the largest application share; textile decoration exhibits the steepest expansion trajectory as apparel manufacturing diversifies across Southeast Asian production clusters.
End User:
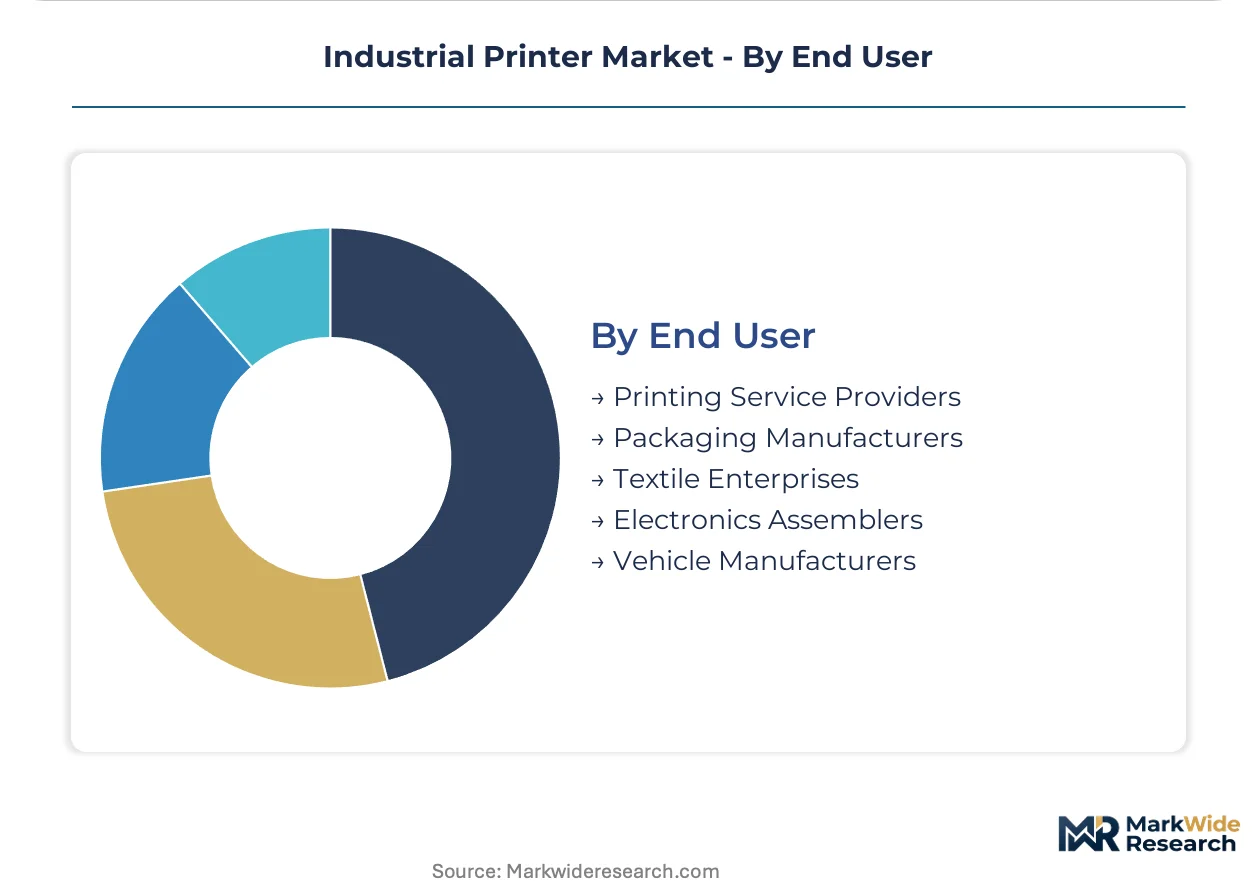
Customer type determines procurement sophistication, with packaging manufacturers and electronics assemblers driving specification intensity while printing service providers prioritize fleet flexibility.
- Printing Service Providers:Commercial print shops and quick-print franchises require equipment capable of job-to-job substrate switching. These operators in Canada favor modular inkjet platforms supporting both transactional document and wide-format graphic workflows.
- Packaging Manufacturers:Corrugated converters and folding carton producers demand 24-hour turnaround capability. United States converters in California's South Coast Air Quality Management District face the nation's strictest VOC thresholds, accelerating UV-cured inkjet adoption.
- Textile Enterprises:Apparel mills and home furnishing manufacturers invest in roll-to-roll dye sublimation for polyester-based fabric imaging. Indonesian textile exporters specify equipment with GB standard and CE marking dual certification for China-bound export flexibility.
- Electronics Assemblers:Contract manufacturers and OEM in-house production lines require continuous inkjet for component traceability. Mexican maquiladora facilities serving United States technology brands deploy EPA-compliant marking systems for cross-border supply chain integration.
- Vehicle Manufacturers:Tier-1 suppliers and final assembly plants need durable marking for under-hood and interior components. Thai automotive production hubs specify equipment meeting both national industrial standards and export-market regulatory requirements.
Packaging manufacturers represent the largest end-user segment; electronics assemblers expand most quickly as PCB production concentrates in East Asian manufacturing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys continuous inkjet systems for PCB traceability at scale, while Germany anchors precision electrophotography for automotive compliance, and the United States drives thermal transfer adoption for warehouse automation.
China
Electronics assemblers in Shenzhen and Dongguan drive continuous inkjet demand for component marking under MIIT dual carbon compliance frameworks. GB standards and energy-efficiency certifications create dual compliance layers for domestic and export-bound production lines. The Pearl River Delta concentrates PCB fabrication facilities specifying MEMS-tolerance printheads below 5 microns.
Germany
Automotive OEMs and packaging converters deploy electrophotographic systems for traceability under REACH substance restrictions. The KBA enforces vehicle component marking standards that mandate solvent-resistant ink formulations. Bavaria's precision manufacturing corridor favors LED-based solid-state arrays for cleanroom-compatible applications.
United States
Automated logistics operators mandate RFID-enabled thermal transfer systems across warehouse management upgrades. EPA VOC thresholds and OSHA workplace exposure limits force solvent-ink users toward ventilation retrofits or formulation switches. California's South Coast Air Quality Management District maintains the nation's strictest local emissions thresholds, accelerating UV-cured inkjet adoption among corrugated converters.
Vietnam
Apparel manufacturers relocating from China create greenfield demand for high-volume dye sublimation fabric imaging systems. The country's national industrial standards authority aligns equipment certification with export-market requirements for textile enterprises. Ho Chi Minh City and surrounding provinces concentrate new roll-to-roll production facilities serving European and North American fashion brands.
Japan
Precision manufacturers favor LED electrophotographic systems for energy efficiency in cleanroom marking applications. METI industrial standards govern equipment disposal streams and hazardous substance content under RoHS-aligned directives. The Chubu region around Nagoya anchors semiconductor packaging facilities requiring sub-micron printhead fabrication tolerances.
Industrial Printer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale-driven OEMs controlling service contract renewals through predictive maintenance bundling while niche players capture margin pools in textile and electronics applications. The structure bifurcates between electrophotography incumbents defending installed bases and inkjet challengers compressing makeready times in corrugated workflows. Two dominant competitive moves are reshaping positioning: strategic partnerships for MEMS printhead supply security, and geographic expansion into Southeast Asian manufacturing corridors.
Within the integrated leader tier, HP Inc. and Canon Inc. represent scale-driven archetypes with in-house printhead manufacturing and ink chemistry integration, while Zebra Technologies occupies a specialist position anchoring thermal and RFID-enabled labeling through channel control in automated logistics. These three companies exemplify the competitive tension between electrophotography service-contract bundling and inkjet platform flexibility.
| Leading Market Players |
|---|
| HP Inc. |
| Canon Inc. |
| Seiko Epson Corporation |
| Brother Industries |
| Xerox Holdings Corporation |
| Ricoh Company |
| Konica Minolta |
| Kyocera Document Solutions |
| Zebra Technologies |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day printhead inventory cycles at East Asian foundries concentrate pricing power among MEMS fabrication specialists, forcing OEMs to absorb cost volatility or pass through to packaging manufacturers locked into multi-year service contracts. This lead-time band tightens further when EPA VOC compliance deadlines accelerate water-based inkjet conversions ahead of solvent-ink phase-outs.
Pricing Analysis
Long-term offtake agreements dominate procurement between corrugated converters and electrophotography incumbents, bundling predictive maintenance with per-page consumption metrics. Price differentiation rests on REACH certification tier and after-sales service depth, with European packaging manufacturers absorbing premium tiers for circular-design compliance while domestic logistics operators in the United States drive cost compression through third-party maintenance unbundling. Margins are tightening in the mid-market inkjet segment due to single-pass array commoditization. Electronics assemblers in China exhibit lowest price sensitivity given traceability mandates, whereas textile enterprises relocating to Vietnam negotiate aggressively on dye sublimation system bundles.
Supply Chain Analysis
MEMS fabrication chokepoints in Taiwan and South Korea tether printhead supply to sub-5-micron tolerance foundries serving Shenzhen and Dongguan electronics clusters. Raw material dependencies span piezoelectric ceramics from Japan, specialty pigments processed in Germany, and rare earth colorant precursors subject to Chinese export licensing. Single-source vulnerability concentrates in thermal actuator arrays where Kyocera and Ricoh maintain captive production. Distribution runs through OEM-direct channels for high-volume packaging contracts, while independent technical service partnerships in German distribution centers pool multi-vendor spare parts for automated logistics fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial printer demand tracks capital expenditure cycles in packaging and electronics manufacturing, with corrugated board investment waves now recovering from post-pandemic inventory destocking. Electronics assembly reshoring initiatives in Mexico and Southeast Asia reinforce replacement cycle momentum.
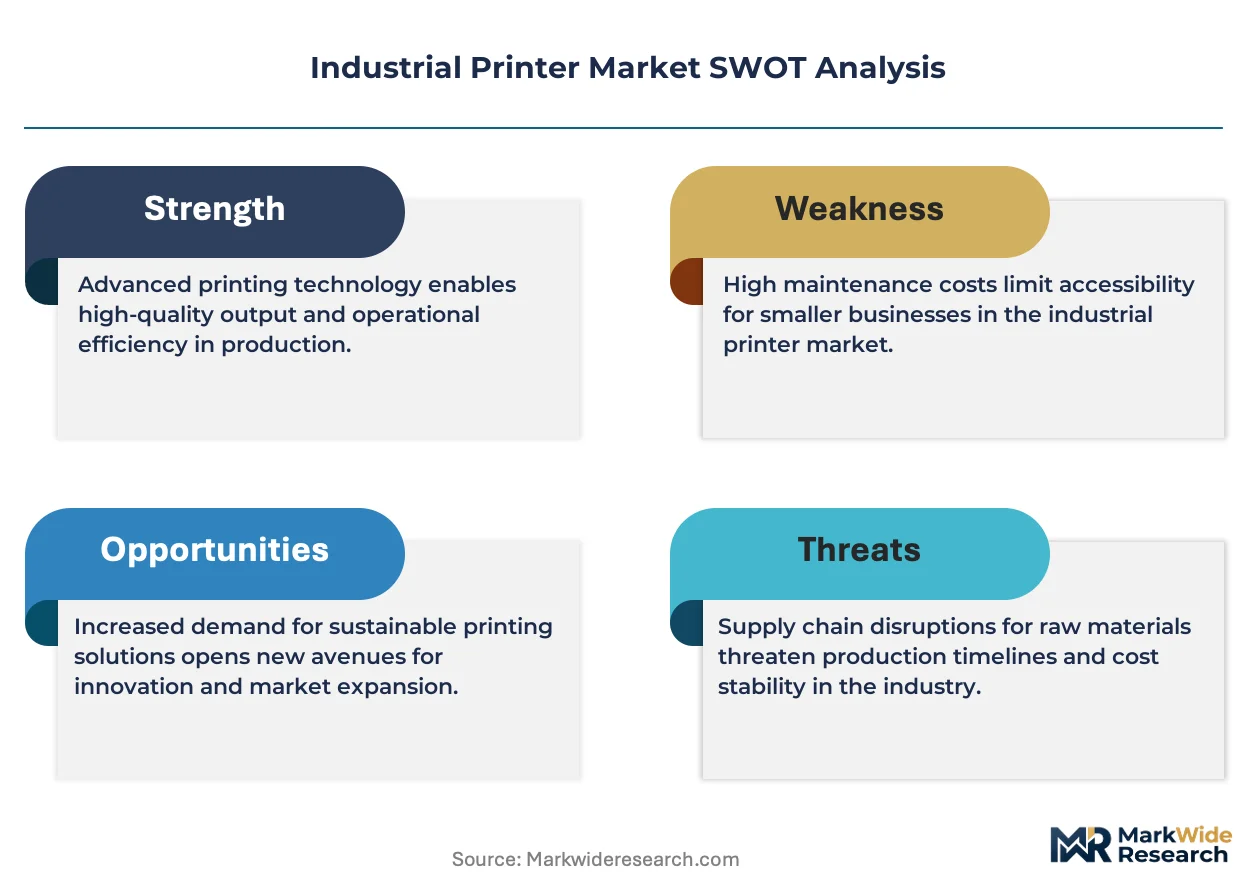
For Market Incumbents: Secure MEMS printhead supply through strategic foundry partnerships or backward integration into piezoelectric ceramic processing, insulating against East Asian single-source fragility. Defend electrophotography service contract renewals by embedding AI-driven print quality inspection into predictive maintenance bundles, countering inkjet challengers compressing makeready times in corrugated workflows. For New Entrants and Emerging Players: Aftermarket service-layer gaps in Vietnamese textile dye sublimation offer white-space entry where incumbent OEMs under-serve relocated apparel manufacturers lacking GB standard certification expertise. Target mid-volume corrugated converters in Italy and Spain adopting single-pass arrays for 24-hour customization contracts. Lead with equipment-as-a-service pricing to displace flexographic pre-press workflows without upfront capital barriers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because MEMS fabrication scale advantages and ink chemistry integration widen margin pools for vertically integrated leaders against fragmented specialist tiers. Acquisition targets should display captive printhead manufacturing or regional certification expertise in MIIT or REACH compliance. Monitor EPA VOC threshold enforcement divergence across United States state-level air quality districts as inflection signal for water-based inkjet acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Printhead Supply Partnership | Secures piezoelectric fabrication capacity against Taiwan foundry concentration risk. |
| Water-Based Inkjet Formulation Switch | Anticipates EPA VOC threshold tightening in California South Coast AQMD enforcement. |
| AI-Driven Print Quality Integration | Enables real-time defect correction without line stoppage in corrugated workflows. |
| Dual Certification Program Investment | Accelerates GB standard and CE marking compliance for China-bound textile exports. |
| Predictive Maintenance Service Unbundling | Captures third-party maintenance demand in German automated logistics distribution centers. |
Research Methodology
Operator-level perspectives from plant engineers at corrugated converters, procurement leads at electronics assemblers, and aftermarket service heads at automated logistics operators anchored the qualitative base for this study. Primary interviews triangulated against secondary validation from SEC filings of listed OEMs, MIIT energy-efficiency certification databases, and ECHA REACH substance restriction timelines. Customs data on printhead and specialty pigment trade flows, alongside FERC filings for industrial energy cost assumptions, supplied quantitative anchors. Bottom-up segment sizing across inkjet, thermal, and electrophotography platforms converged with top-down market consolidation estimates.
Sensitivity analysis tested forecast outputs against variable assumptions for EPA VOC compliance acceleration, rare earth pigment price volatility, and electronics assembly relocation velocity across the projection horizon. Segmentation dimensions modeled include technology architecture, substrate compatibility tier, end-use application intensity, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, technology migration curves, and capital expenditure correlation with packaging and electronics manufacturing output indices. Industry-specific inputs incorporated REACH substance restriction phase-in schedules and MIIT dual carbon compliance framework adoption rates.
Forecasts assume regulatory continuity in EPA emissions standards, REACH substance restrictions, and MIIT certification requirements; material policy shifts would require re-modeling. Commodity price volatility in rare earth processing and printhead fabrication capacity constraints represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
RFID Printer Market
Printing Technology
Digital Printing Market
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Print Equipment Market
Printing Technology
Card Printers Market
Printing Technology
Managed Print Services Market
Printing Technology
Photo Printing Market
Printing Technology
US Print on Demand Market
Printing Technology
Print on Demand Market
Printing Technology
Global Computer to Plate Printing System Market
Printing Technology
Digital Presses Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Industrial Inkjet Printer Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
GCC Digital Printing Market
Printing Technology
Photo Printing and Merchandise Market