
 Europe 3D Printing Market | 2026-2036
Europe 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe 3D Printing Market Analysis
The EU Medical Device Regulation is realigning certification costs for patient-specific implants across European additive manufacturing. EOS GmbH leverages its laser sintering heritage to dominate industrial metal applications from its Krailling headquarters. Materialise NV sustains its software-to-manufacturing workflow control across orthopedic and aerospace verticals. SLM Solutions Group AG anchors German automotive interest through its selective laser melting platforms for powertrain components.
Europe 3D Printing encompasses layer-by-layer fabrication using photopolymer resins, metal powders, or thermoplastic filaments cured by laser, electron beam, or extrusion heads, typically achieving tolerances of 20-100 microns depending on process modality. Its primary commercial purpose spans rapid prototyping, direct tooling, and end-use production across sectors requiring geometric complexity or lot-size flexibility. Metal 3D printing leads technology value capture due to aerospace and medical qualification cycles, while polymer 3D printing extends reach through desktop FDM systems in education and design bureaus. Bioprinting occupies an emerging margin pool as tissue engineering research accelerates under Horizon Europe funding envelopes.
EMA device standards, REACH chemical compliance for powder feedstocks, and CE marking under the EU Machinery Directive collectively govern market access and material qualification pathways across member states. These frameworks elevate R&D overhead but also filter out non-compliant imports, reinforcing incumbent European positions. Stakeholders must monitor evolving CSRD disclosure requirements for supply chain carbon footprinting as procurement criteria harden around sustainability verification.
Market Dynamics
Metal powder bed fusion is compressing qualification timelines for aerospace engine components across German and French supply chains, forcing incumbent polymer-focused service bureaus to retool or exit industrial contracts.
Growth Catalysts
- EU MDR recertification deadlines:Patient-specific implant manufacturers face mandatory 2027 compliance windows, pulling demand toward certified European additive production facilities.
- Titanium aluminide adoption:Turbine blade geometries impossible through casting are now producible via electron beam melting, locking in aerospace procurement shifts.
- Bavarian cluster density:Krailling-to-Munich corridor hosts concentrated powder metallurgy expertise, reducing supplier search costs for qualified buyers.
Market Restraints
- Nickel powder price volatility:Inconel 718 feedstock costs swing with aerospace order cycles, compressing margins for undifferentiated service bureaus.
- Single-source scanner dependency:German optical component suppliers dominate laser galvo subassemblies, creating chokepoints for equipment OEMs.
- REACH chemical registration:Novel alloy compositions face 18-24 month toxicity evaluation windows before commercial powder production authorization.
Strategic Opportunities
- Polish manufacturing corridor:Lower labor costs and EU structural fund access position Wrocław-Katowice axis for automotive tooling contract migration from Western Europe.
- CSRD supply chain disclosure:Mandatory carbon footprint reporting creates first-mover advantage for powder producers with lifecycle-certified recycled feedstock.
- Multi-material deposition:Combining directed energy deposition with CNC finishing enables repair-to-print workflows for aging European rail infrastructure.
Industry Challenges
- Post-processing bottleneck:Heat treatment and surface finishing capacity lags behind installed printer base, extending lead times for precision medical implants.
- Cross-border powder logistics:ADR hazardous material classifications fragment bulk shipment economies, inflating inbound material costs for peripheral EU plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe 3D Printing Market |
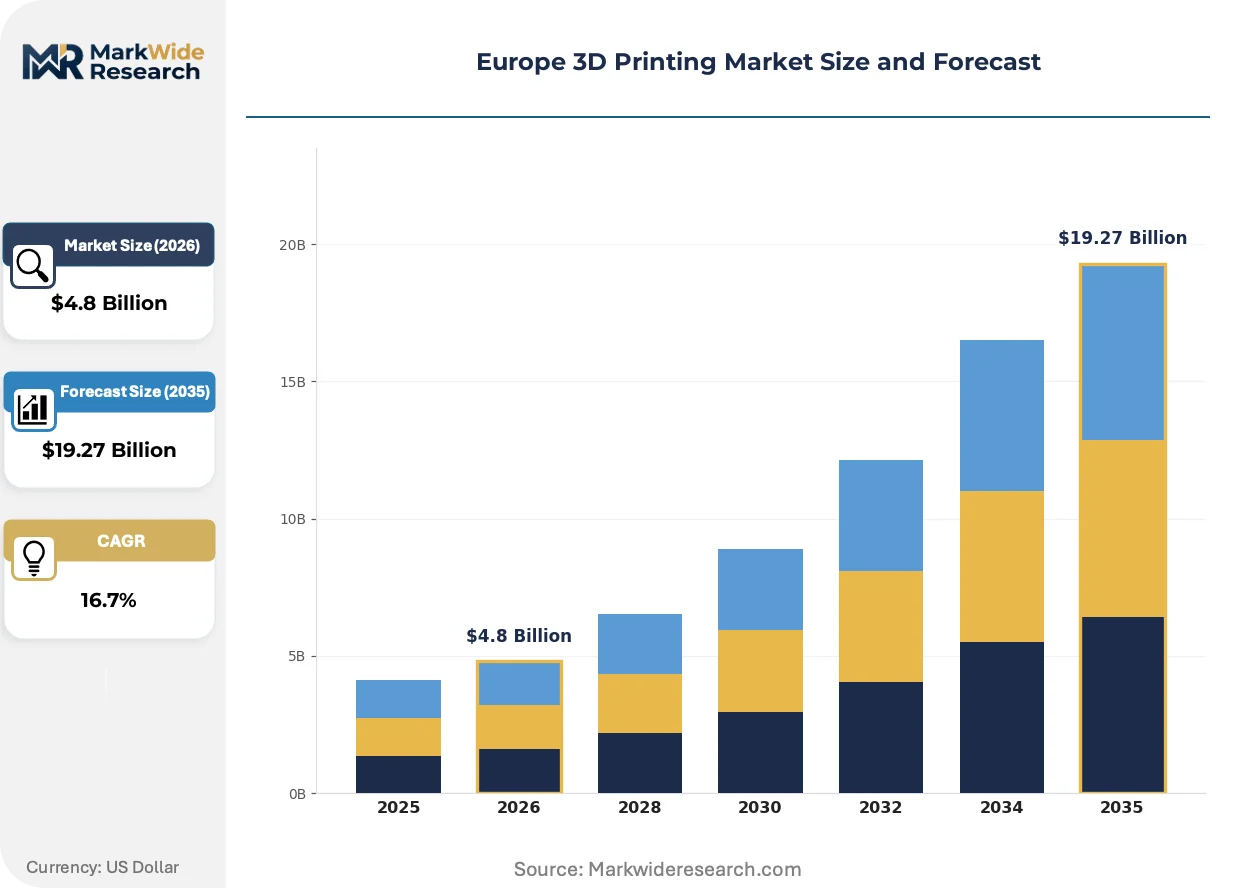
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FDM, SLA, SLS, DLP End User: Aerospace, Automotive, Healthcare, Education Technology: Metal 3D Printing, Polymer 3D Printing, Bioprinting, Hybrid Manufacturing Application: Prototyping, Tooling, Production, Repair |
| Companies Covered | EOS GmbH, Materialise NV, Renishaw PLC, Stratasys Ltd., 3D Systems Corporation, SLM Solutions Group AG, Voxeljet AG, Ultimaker, Trumpf GmbH + Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe 3D Printing Market Emerging Trajectories
Process automation and in-situ monitoring are collapsing the manual intervention burden that has constrained metal additive throughput, while regulatory data requirements are hardening around traceability infrastructure.
Multi-laser powder bed fusion is expanding into production-scale aerospace component manufacturing, replacing single-laser systems in tier-one supplier facilities. Airbus and Safran procurement teams now specify four-laser minimum configurations for new equipment tenders. This compression of build times per part is expanding into cost parity with precision casting for low-volume turbine hardware.
EMA device master file requirements are tightening material pedigree documentation for implantable titanium structures, forcing powder suppliers to invest in batch-level spectral analysis. Manufacturers without validated quality management systems face 12-18 month backlog queues at notified bodies. Orthopedic OEMs in Ireland and Switzerland are responding by vertically integrating powder atomization to secure supply chain control.
Consolidated procurement desks at major automotive groups are unbundling design services from production execution, pressuring independent bureaus to choose specialization or scale. BMW and Volkswagen now maintain approved vendor lists segregated by material family, compressing supplier counts per category. This concentration is most visible in Baden-Württemberg, where mid-size bureaus face margin pressure from captive printing operations at Bosch and Siemens Energy.
Europe 3D Printing Market Segmentation
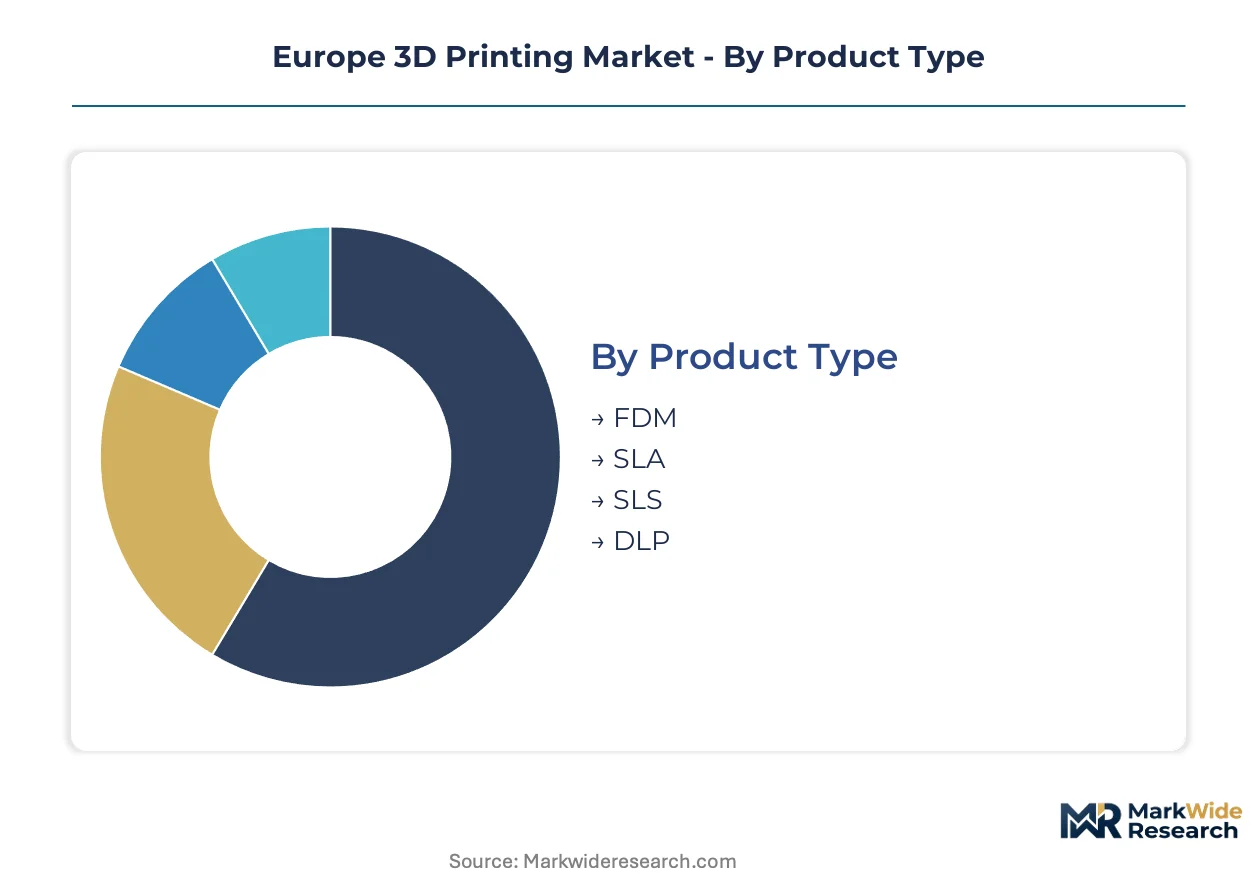
Technology modality determines capital intensity and certification pathways across European additive manufacturing. Equipment buyers face distinct upgrade cycles depending on whether they serve aerospace qualification requirements or desktop prototyping demand.
Product Type:
Printer hardware replacement cycles diverge sharply between industrial metal systems and desktop polymer units, with EU MDR compliance deadlines accelerating refresh decisions in medical-focused installations.
- FDM:Fused deposition modeling extrudes thermoplastic filament through heated nozzles, building parts layer by layer with typical layer heights of 100-400 microns. German vocational schools and design bureaus across Bavaria drive replacement demand as educators upgrade from open-source kits to enclosed-chamber systems with material dryness controls.
- SLA:Stereolithography cures photopolymer resin with ultraviolet lasers, achieving surface finishes of 25-50 microns that satisfy dental mold and jewelry pattern requirements. French dental laboratories in Lyon and Paris clusters are consolidating toward large-format SLA platforms to capture patient-specific aligner production volumes.
- SLS:Selective laser sintering fuses nylon and TPA powders without support structures, enabling complex geometries for functional prototypes and low-volume end-use parts.
- DLP:Digital light processing projects entire layers simultaneously via micromirror arrays, compressing print times for small, detailed components in jewelry and hearing aid applications.
Volume placements concentrate in FDM; the faster expansion belongs to SLA.
End User:
Customer procurement sophistication varies dramatically across sectors, with aerospace and healthcare buyers demanding validated quality systems while education purchasers prioritize equipment cost and curriculum alignment.
- Aerospace:Turbine blade and structural component manufacturers in Germany and France require electron beam melting and multi-laser powder bed fusion systems with full traceability documentation. Safran and Airbus procurement specifications now mandate four-laser minimum configurations for new equipment tenders, displacing older single-laser installations.
- Automotive:Powertrain prototyping and custom tooling dominate German OEM demand, with BMW and Volkswagen maintaining segregated approved vendor lists by material family that compress supplier counts.
- Healthcare:Patient-specific implant production faces mandatory EU MDR recertification by 2027, pulling demand toward certified European additive facilities with validated quality management systems.
- Education:Universities and technical colleges across Poland and the Czech Republic prioritize low-cost FDM systems for curriculum integration, with procurement decisions driven by filament material availability rather than precision specifications.
Procurement volumes center on Automotive; Healthcare claims the steepest expansion trajectory.
Technology:
Process modality determines margin structure and barrier height, with metal systems requiring powder atomization partnerships and polymer platforms competing on equipment financing terms.
- Metal 3D Printing:Powder bed fusion and directed energy deposition processes using titanium, nickel superalloys, and aluminum powders achieve aerospace-grade material properties. German Krailling-to-Munich corridor hosts concentrated powder metallurgy expertise that reduces supplier search costs for qualified aerospace buyers.
- Polymer 3D Printing:Material extrusion, vat photopolymerization, and powder bed fusion of thermoplastics and photopolymers span prototyping through end-use production. Desktop FDM systems extend reach into education and design bureaus across peripheral EU member states.
- Bioprinting:Extrusion-based and light-based fabrication of cell-laden bioinks occupies emerging margin pools as tissue engineering research accelerates under Horizon Europe funding envelopes.
- Hybrid Manufacturing:Combining directed energy deposition with CNC finishing enables repair-to-print workflows for aging European rail infrastructure and aerospace component refurbishment.
Equipment placements concentrate in Polymer 3D Printing; Bioprinting is climbing the fastest.
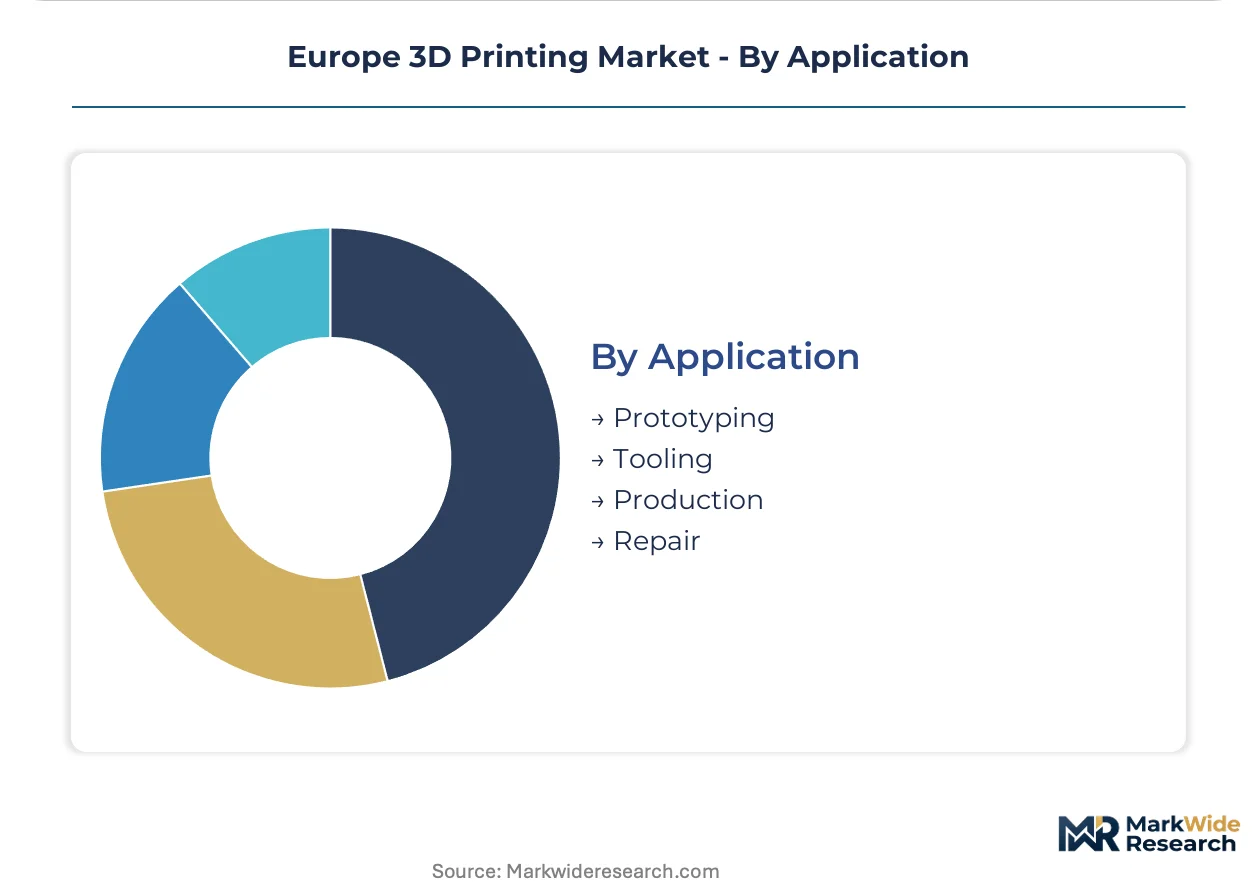
Application:
Use case maturity determines pricing power and customer retention, with production applications commanding long-term contracts while prototyping relationships face annual recompetition.
- Prototyping:Rapid iteration of design concepts and functional verification models remains the entry point for additive adoption across industrial sectors. German automotive design studios maintain high prototype throughput requirements that favor service bureaus with overnight turnaround capabilities.
- Tooling:Direct fabrication of jigs, fixtures, and injection mold inserts compresses lead times compared to conventional machining. Polish manufacturing corridors leverage lower labor costs to capture automotive tooling contract migration from Western Europe.
- Production:Series manufacturing of end-use components requires process validation and statistical process control documentation. Aerospace turbine blade production via electron beam melting has achieved cost parity with precision casting for low-volume hardware.
- Repair:Directed energy deposition restores worn surfaces on high-value components, extending service life for European rail and power generation infrastructure.
Contract volumes concentrate in Prototyping; Production is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bavaria and Baden-Württemberg channel federal R&D tax credits toward additive manufacturing clusters, concentrating powder metallurgy expertise and equipment assembly operations in southern Germany.
Germany
Aerospace procurement from Airbus and Safran specifications mandate four-laser powder bed fusion configurations, displacing legacy single-laser installations. REACH chemical registration requirements govern novel alloy compositions before commercial powder authorization. The Krailling-to-Munich corridor hosts EOS GmbH headquarters and dense service bureau networks serving automotive and medical verticals.
France
Turbine blade manufacturers adopt electron beam melting for titanium aluminide geometries impossible through conventional casting. ANSM device standards align with EU MDR frameworks for patient-specific implant traceability. Lyon and Paris dental laboratory clusters consolidate toward large-format SLA platforms for aligner production volumes.
United Kingdom
Renishaw PLC anchors metal additive equipment supply from its Gloucestershire base, serving aerospace precision component demand. MHRA convergence with EMA device master file requirements tightens material pedigree documentation. The Midlands manufacturing belt hosts concentrated directed energy deposition service providers for rail infrastructure repair contracts.
Poland
Automotive tooling contract migration from Western Europe accelerates as Wrocław-Katowice corridor operators exploit EU structural fund access and lower labor costs. The country's national industrial regulator enforces CE marking under Machinery Directive transpositions. Technical universities across Kraków and Warsaw prioritize low-cost FDM curriculum integration over precision specifications.
Switzerland
Orthopedic OEMs respond to EU MDR recertification deadlines by securing captive powder atomization capacity for implantable titanium supply chain control. Swissmedic device standards exceed baseline EMA requirements, extending qualification timelines. Zurich and Basel clusters concentrate bioprinting research funded through Horizon Europe tissue engineering envelopes.
Europe 3D Printing Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment, software, and service bureau verticals. Market structure tilts toward consolidated premium-tier metal systems and fragmented desktop polymer segments. Three archetypes dominate: laser system heritage manufacturers, software-to-manufacturing workflow integrators, and regional service bureau networks. Competitive moves center on multi-laser platform refreshes and backward integration into powder atomization capacity.
Among German heritage equipment manufacturers, EOS GmbH and SLM Solutions Group AG exemplify the laser-system archetype with Krailling and Lübeck headquarters respectively. Materialise NV represents the software-to-manufacturing workflow tier from its Belgian base. These three anchors occupy positions spanning industrial metal qualification requirements and medical device traceability mandates.
| Leading Market Players |
|---|
| EOS GmbH |
| Materialise NV |
| Renishaw PLC |
| Stratasys Ltd. |
| 3D Systems Corporation |
| SLM Solutions Group AG |
| Voxeljet AG |
| Ultimaker |
| Trumpf GmbH + Co. |
| Others |
Supply Flow & Price Mechanics
Multi-laser powder bed fusion adoption across German aerospace tier-one suppliers simultaneously collapses per-part build economics and concentrates procurement leverage among equipment OEMs with qualified four-laser configurations. This technology transition restructures both cost baselines and supplier power dynamics as buyers trade capital intensity for throughput gains.
Pricing Analysis
Premium pricing for sub-48-hour lead times on medical implant builds contrasts with spot-market discounts for undifferentiated polymer prototyping capacity. Three-tier pricing structure across certified production, qualified industrial, and desktop education levels segments buyers by traceability requirements. Cost compression in polymer service bureaus is intensifying because automotive OEMs unbundle design from production execution. Education purchasers across Poland and the Czech Republic exhibit highest price sensitivity; aerospace procurement teams at Airbus and Safran demonstrate lowest sensitivity due to qualification lock-in.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs require qualified powder suppliers to maintain redundant atomization capacity across Germany and Switzerland. Titanium and nickel superalloy feedstocks draw from German, French, and Swiss metallurgical specialists. Single-source vulnerability concentrates in laser galvo optical subassemblies from Bavarian component suppliers. Distribution runs through certified service bureau networks for medical applications and direct equipment sales for industrial metal systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
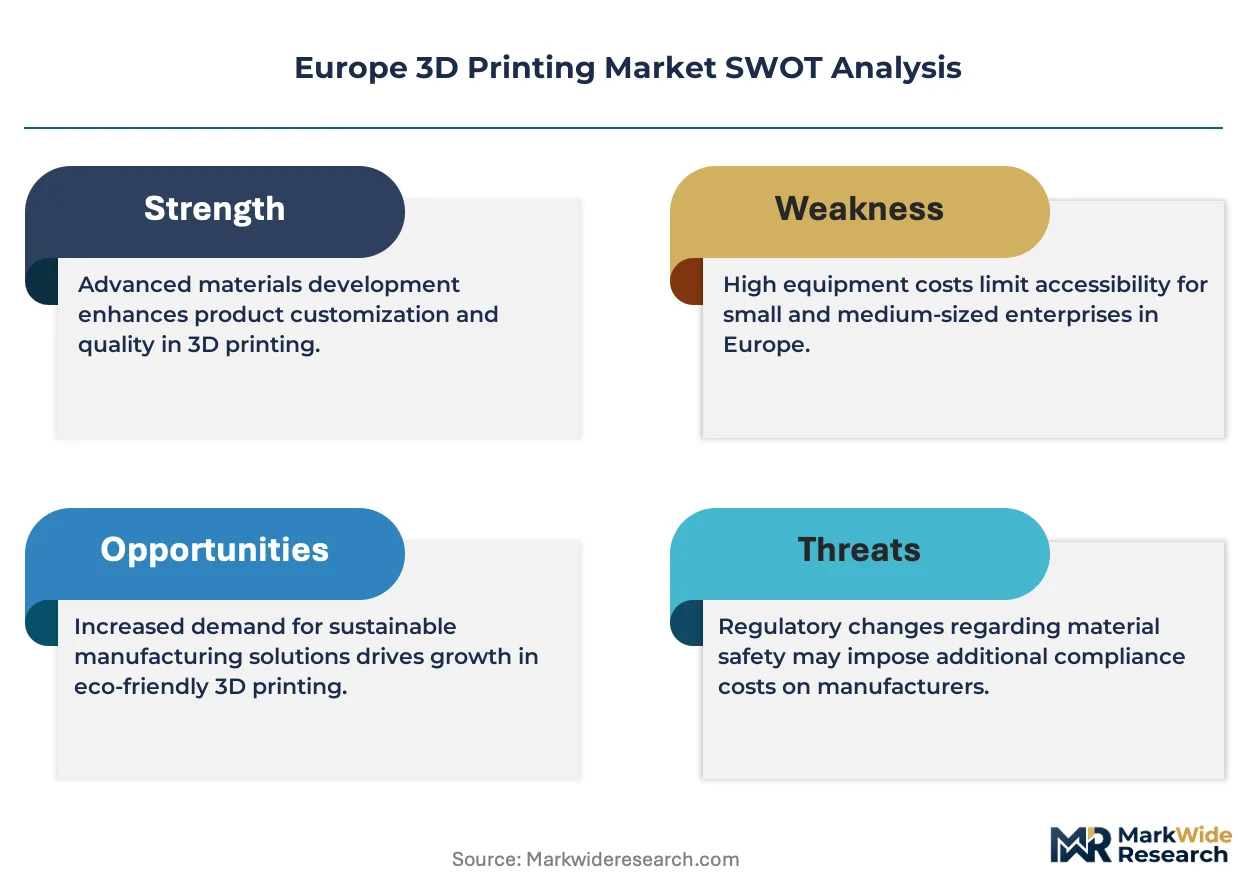
EU MDR recertification deadlines erect a cost-of-compliance barrier that rewards incumbent powder producers with validated quality management systems while filtering undifferentiated imports. This regulatory moat sustains margin premiums for certified European additive manufacturing facilities.
For Market Incumbents: Extend backward integration into powder atomization capacity to secure supply chain control against REACH chemical registration delays threatening novel alloy commercialization. Consolidate post-processing heat treatment and surface finishing capacity to resolve the bottleneck extending medical implant lead times. Channel control through captive service bureau networks in Bavaria and Baden-Württemberg reinforces positioning against automotive OEM unbundling strategies.
For New Entrants and Emerging Players: Dental laboratory networks in Lyon and Paris clusters represent the most penetrable white-space target as aligner production volumes consolidate toward large-format SLA platforms. Polish technical universities and vocational schools offer curriculum-integrated FDM procurement channels with lower competitive density than German industrial corridors. A go-to-market angle emphasizing material dryness controls and enclosed-chamber reliability addresses educator frustration with open-source kit maintenance burdens.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified industrial conglomerates seeking additive manufacturing capability. Long-term viability hinges on differentiation through regulatory certification depth rather than equipment hardware commoditization. The signal to watch is CSRD supply chain disclosure adoption rates, as mandatory carbon footprint reporting creates first-mover advantage for powder producers with lifecycle-certified recycled feedstock.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Laser Platform Refresh | Four-laser configurations satisfy Airbus and Safran procurement specifications displacing legacy single-laser installations. |
| Powder Atomization Backward Integration | Captive titanium supply secures implant manufacturers against EMA device master file documentation requirements. |
| Post-Processing Capacity Expansion | Heat treatment and surface finishing investments resolve bottleneck constraining precision medical implant throughput. |
| CSRD-Compliant Recycled Feedstock | Lifecycle-certified powder production captures procurement preference under mandatory carbon footprint disclosure rules. |
| Polish Manufacturing Corridor Establishment | Wrocław-Katowice axis operators exploit EU structural fund access for automotive tooling contract migration. |
Methodological Framework
Trade association filings, EMA device registration databases, and REACH chemical authorization records formed the secondary backbone for supply chain mapping and regulatory timeline assessment. Primary interviews with powder metallurgy procurement directors, biomedical engineers at orthopedic OEMs, and additive manufacturing service bureau operators combined with secondary validation to triangulate demand patterns. Bottom-up equipment shipment analysis and top-down aerospace procurement budget assessments cross-checked market sizing across the analysis window.
Historical trendline analysis of metal powder bed fusion adoption rates and polymer prototyping contract volumes established baseline growth trajectories without year-specific anchoring. Segmentation modeling spanned technology modality, end-use vertical, application maturity, and geographic regulatory cluster dimensions. CAGRs derived from equipment replacement cycle compression and EU MDR compliance deadline acceleration. Forecast inputs incorporated titanium aluminide adoption curves and CSRD disclosure implementation timelines.
Caveats apply where REACH chemical evaluation delays or nickel powder price volatility could materially shift the outlook for novel alloy commercialization and service bureau margin structures. Deviation in EU MDR notified body backlog queues would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
3D Printing in Consumer Goods Market
3D Printing Technology
4D Printing Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
3D Printing for Medical Market
3D Printing Technology
US Additive Manufacturing Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
Germany Additive Manufacturing Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
Middle East and Africa Additive Manufacturing Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
Personal 3D Printers Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
Aluminum Alloy 3D Printing Service Market
3D Printing Technology
Global 4D Printing in Healthcare Market