
 3D Printing in Consumer Goods Market | 2026-2036
3D Printing in Consumer Goods Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing in Consumer Goods Market Insights
Industrial-grade surface finish and dimensional tolerance standards are bifurcating the competitive landscape between professional manufacturers and desktop entrants. HP Inc. leverages its Multi Jet Fusion platform to control production-scale polymer printing for consumer brands seeking batch consistency. Carbon differentiates through its programmable resin chemistry, anchoring high-margin applications in athletic wear and personalized dental products. Stratasys sustains technology leadership in FDM and PolyJet systems, occupying the prototyping tier where design studios and hobbyists converge.
3D printing in consumer goods encompasses additive manufacturing processes that build objects layer-by-layer from digital models, typically employing photopolymer resins, thermoplastic filaments, or powder bed fusion materials with layer resolutions ranging from 50 to 200 microns. Its primary purpose is enabling mass customization, distributed production, and rapid iteration cycles for consumer-facing products from jewelry to home fixtures. Prototyping remains the dominant product type segment, though custom accessories capture expanding margin pools as brands monetize personalization at premium price points. PLA and resin materials lead volume consumption, while nylon commands structural applications where fatigue resistance determines product longevity.
FDA oversight of printed medical-adjacent consumer items, EPA regulations on volatile organic compound emissions from resin curing, and REACH compliance for chemical substances in imported filaments collectively elevate compliance costs for cross-border material sourcing. The EU AI Act and emerging product digital passport requirements under CSRD will further reshape how printer OEMs document supply chain provenance. Stakeholders must monitor evolving material certification standards and assess whether regional production nodes or centralized export hubs offer superior regulatory arbitrage.
Market Dynamics
Mass customization demand is decomposing traditional batch manufacturing economics, forcing consumer brands to reconfigure production footprints around distributed micro-factories rather than centralized assembly.
Growth Catalysts
- EU Green Deal material mandates:Tightening compliance requirements for polymer feedstocks are accelerating investment in bio-based and recycled resin formulations for consumer product applications.
- Footwear personalization:Athletic brands are deploying printed midsole technologies to capture premium pricing through biomechanically tailored insole geometries.
- Bavaria-North Rhine-Westphalia cluster concentration:Industrial printer OEM density in these German states is creating specialized supplier ecosystems and reducing equipment procurement lead times.
Market Restraints
- Photopolymer resin cost volatility:Specialized acrylate and epoxy formulations command 3-5x commodity polymer pricing, compressing margins on high-resolution consumer goods.
- Single-source powder bed fusion equipment:Production-scale polymer printers concentrate among three German and US manufacturers, creating supply vulnerability for scaling consumer brands.
- Layer resolution throughput trade-offs:Sub-100 micron finishes required for jewelry and eyewear reduce build speeds by 40-60% versus industrial prototyping tolerances.
Strategic Opportunities
- India BIS standards harmonization:Emerging certification pathways for additive manufacturing equipment are opening import channels for desktop printer OEMs targeting design studios and hobbyist segments.
- Generative design-AI convergence:Topology optimization software paired with lattice generation tools is enabling mass-customized home fixtures with material efficiency gains.
- Digital product passport mandates:EU CSRD requirements for supply chain provenance documentation are creating service revenue streams for printer OEMs offering blockchain-integrated production logging.
Industry Challenges
- Multi-material process engineering talent:Operators capable of managing sequential resin deposition and support material removal remain scarce relative to single-filament FDM technicians.
- FDA 510(k) pathway navigation:Printed dental aligners and sleep apnea devices face extended clearance timelines, delaying revenue recognition for personalized medical-adjacent consumer products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing in Consumer Goods Market |
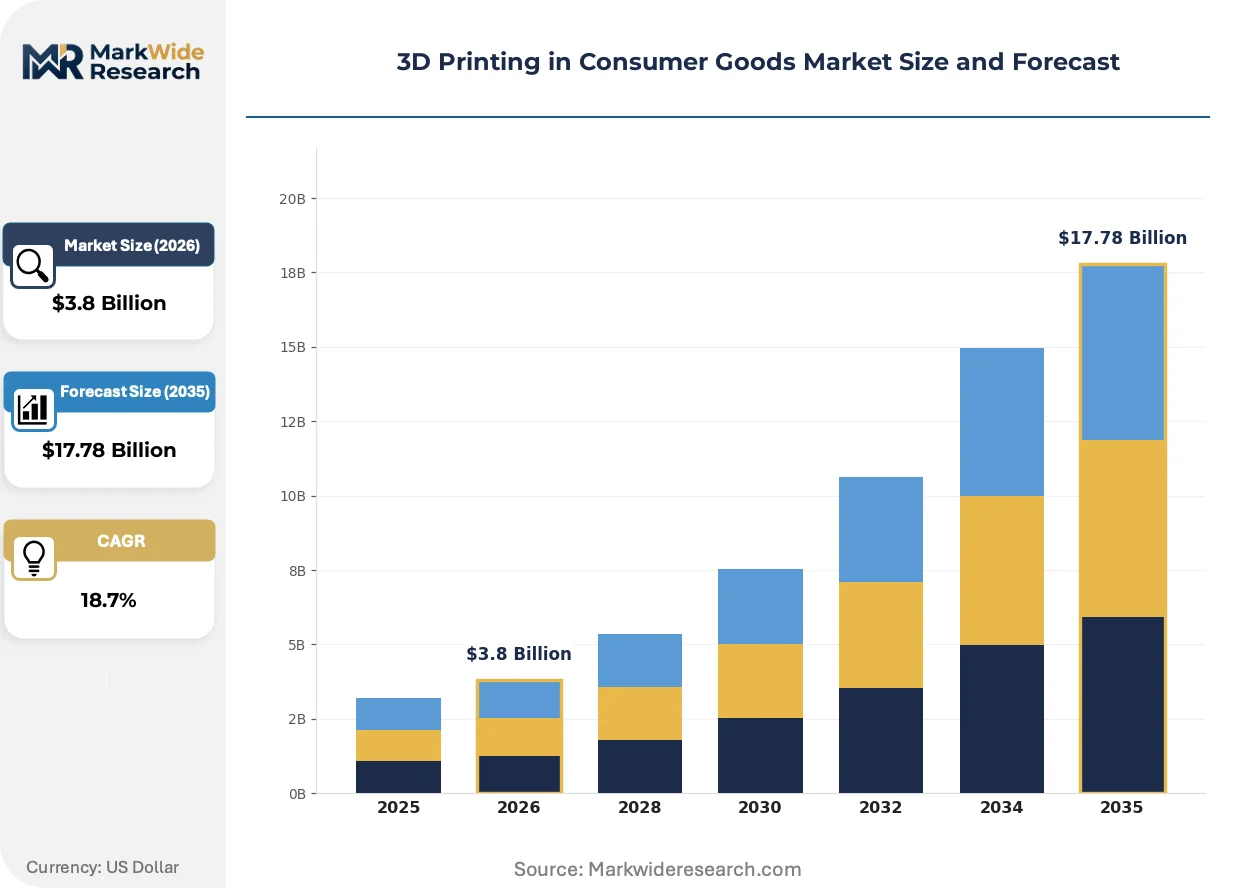
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prototyping, Custom Accessories, Toys, Home Decor Material: PLA, ABS, Nylon, Resin End User: Consumers, Hobbyists, Designers, Startups Distribution Channel: Online Retail, Specialty Stores, Marketplaces, Direct Sales |
| Companies Covered | Stratasys, 3D Systems, HP Inc., EOS GmbH, Materialise, General Electric Company, Renishaw plc, Carbon, Markforged, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing in Consumer Goods Market Trends and Innovations
Continuous liquid interface production is compressing cycle times for transparent optical components, while regulatory pressure on volatile organic compound emissions is reshaping resin chemistry R&D priorities across formulation houses.
Programmable resin chemistry is decomposing the traditional tooling-injection molding value chain for complex elastomeric geometries. Athletic wear manufacturers are adopting digital light synthesis for gradient-density midsoles at production volumes exceeding 100,000 units annually. This technology is decomposing the minimum efficient scale for customized footwear, enabling economically viable lot sizes below 500 pairs.
REACH authorization requirements for photoinitiator substances are forcing reformulation of UV-curable resins used in jewelry and eyewear applications. ECHA substance of very high concern listings for bisphenol-A derivatives are accelerating migration to thiol-ene and cationic epoxy chemistries. German formulation houses are responding with bio-based alternatives derived from lignin and vegetable oil precursors to preempt regulatory displacement.
Direct-to-consumer configuration platforms are displacing wholesale channel dependence for premium accessory brands. Jewelry designers are deploying browser-based parametric tools that translate biometric scans into printable ring geometries within 72-hour fulfillment windows. This channel shift concentrates in metropolitan Germany and the Netherlands where digital fabrication literacy and same-day logistics infrastructure intersect.
3D Printing in Consumer Goods Market Segmentation
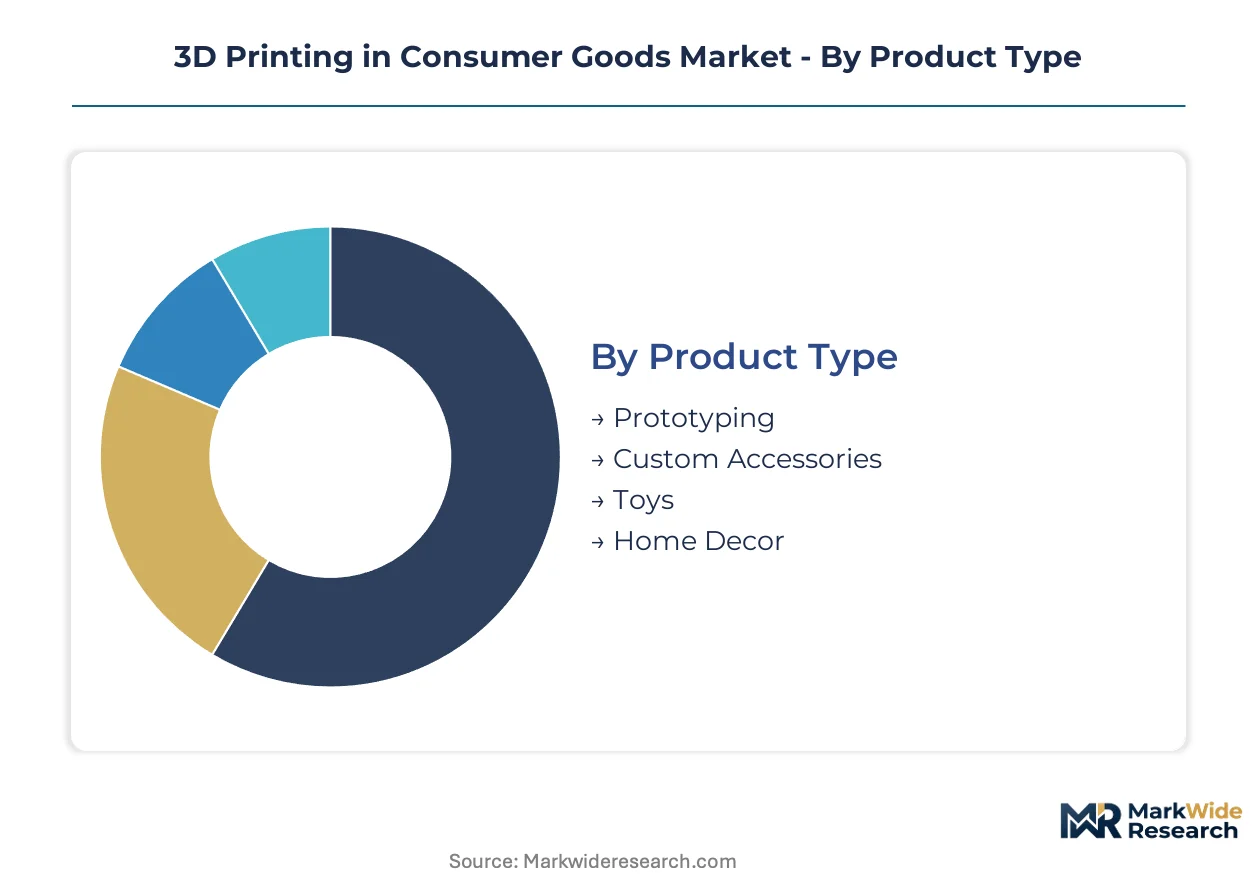
Segmentation in 3D printing for consumer goods reveals how margin pools concentrate in customization-enabled workflows versus commodity prototyping. Distinct material tolerances, end-user sophistication levels, and channel economics create divergent competitive requirements across each dimension.
Product Type:
Margin pools concentrate in applications where digital fabrication replaces artisanal labor or unlocks geometries impossible through conventional molding.
- Prototyping:Design iteration cycles for consumer brands rely on fused deposition modeling and stereolithography for form-fit validation. Demand clusters with industrial design studios in Germany and the Netherlands where rapid iteration contracts command premium day-rates.
- Custom Accessories:Biometric capture and parametric design tools enable made-to-measure jewelry, eyewear, and wearables at price points 3-4x above mass-produced equivalents. Athletic brands in Bavaria are deploying this segment for personalized midsole geometries.
- Toys:Collectible figurines and modular construction sets target hobbyist communities through limited-edition drops.
- Home Decor:Lattice-structured lighting fixtures and acoustic panels leverage generative design for material efficiency.
Prototyping holds installed capacity. Custom Accessories is rotating up the share rankings.
Material:
Cost tiers separate commodity feedstocks from performance polymers where regulatory compliance and mechanical properties justify price premiums.
- Resin:Photopolymer formulations deliver sub-50 micron resolution for jewelry and dental-adjacent consumer products. REACH authorization pressure on photoinitiators is forcing German formulation houses toward thiol-ene and bio-based lignin alternatives.
- Nylon:Selective laser sintering-grade polyamide 12 provides fatigue resistance for structural components in sporting goods and functional footwear. Powder bed fusion equipment concentration in North Rhine-Westphalia reduces procurement lead times for this segment.
- PLA:Polylactic acid dominates desktop printing volumes with bio-derived feedstock appeal under EU Green Deal procurement guidelines.
- ABS:Acrylonitrile butadiene styrene serves temperature-resistant applications in automotive-adjacent consumer goods.
PLA captures volume leadership. Resin is climbing the fastest on value-per-kilogram metrics.
End User:
Customer sophistication determines equipment specifications, with professional users demanding closed-loop quality systems absent in hobbyist segments.
- Designers:Professional design studios require ISO-certified dimensional tolerances and surface finish validation for client-presentable prototypes. Contract workflows in metropolitan Germany and the Netherlands specify Multi Jet Fusion or PolyJet systems for color-accurate models.
- Startups:Direct-to-consumer brands leverage browser-based configurators and distributed micro-factories to bypass wholesale channels. Digital product passport requirements under EU CSRD are creating compliance service opportunities for this segment.
- Consumers:End purchasers of finished printed goods interact primarily through configuration platforms rather than equipment ownership.
- Hobbyists:Desktop FDM operators drive filament volume through maker communities and open-source design repositories.
Designers anchor professional equipment procurement. Startups are gaining share fastest as direct-to-consumer platforms proliferate.
Distribution Channel:
Channel selection shapes margin capture, with vertically integrated direct sales preserving pricing power that marketplace intermediaries erode.
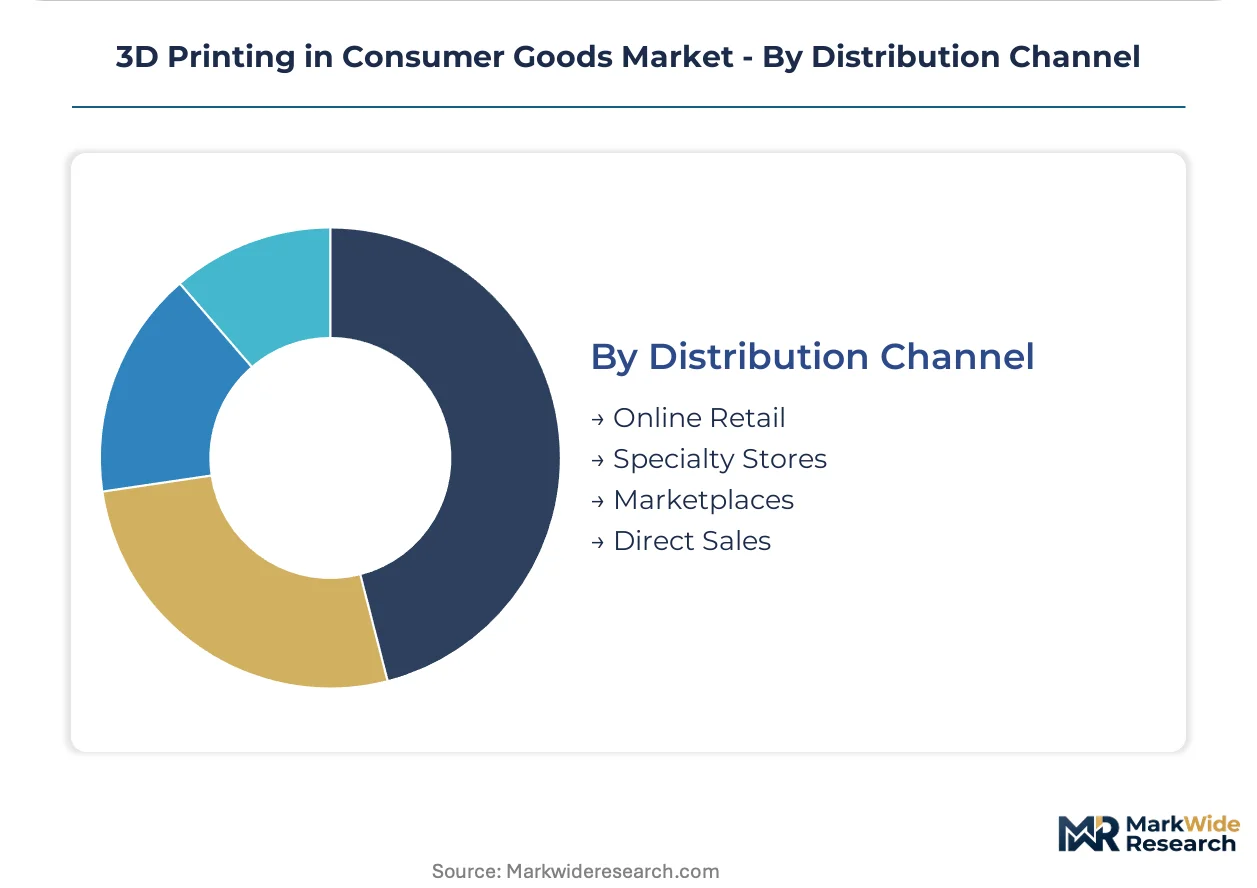
- Direct Sales:Printer OEMs and formulation houses sell production-scale systems and material subscriptions through captive sales forces. HP Inc. and Carbon deploy this channel for enterprise accounts requiring service-level agreements.
- Online Retail:Desktop printers and consumables move through specialized e-commerce platforms with technical documentation and community support. India BIS standards harmonization is opening import channels for this segment.
- Specialty Stores:Physical showrooms in design districts provide hands-on equipment demonstration and training.
- Marketplaces:Aggregator platforms connect print service bureaus with upload-and-print demand from non-equipment owners.
Direct Sales commands system-level revenue. Online Retail is expanding most quickly in unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for production-scale polymer powder bed fusion equipment concentrates procurement risk in German and US manufacturing clusters, while export-oriented custom footwear brands in Bavaria and North Rhine-Westphalia drive regional feedstock demand.
Germany
Industrial printer OEMs cluster around Bavaria and North Rhine-Westphalia, creating specialized supplier ecosystems that reduce equipment procurement lead times for consumer brands. REACH authorization requirements for photoinitiator substances under ECHA oversight are forcing reformulation of UV-curable resins used in jewelry applications. Formulation houses in these states are responding with bio-based alternatives derived from lignin and vegetable oil precursors.
United States
FDA oversight of printed dental aligners and sleep apnea devices creates extended clearance timelines that delay revenue recognition for personalized medical-adjacent consumer products. EPA regulations on volatile organic compound emissions from resin curing elevate compliance costs for cross-border material sourcing. Carbon and HP Inc. anchor production-scale polymer printing capacity serving athletic wear manufacturers deploying gradient-density midsole technologies.
China
Dual carbon goals under MEE oversight are reshaping feedstock sourcing priorities for desktop printer OEMs targeting export markets with bio-derived PLA formulations. MIIT standards harmonization for additive manufacturing equipment is accelerating domestic certification pathways. Yangtze River Delta manufacturing hubs concentrate filament extrusion capacity serving hobbyist communities through specialized e-commerce platforms.
India
BIS standards harmonization for additive manufacturing equipment is opening import channels for desktop printer OEMs targeting design studios and hobbyist segments. DGFT import policies on polymer feedstocks create procurement friction for resin formulations used in jewelry applications. Maharashtra and Karnataka host emerging distributed micro-factory networks serving direct-to-consumer configuration platforms.
Netherlands
Digital fabrication literacy and same-day logistics infrastructure in metropolitan areas enable 72-hour fulfillment windows for browser-based parametric jewelry design tools. CSRD digital product passport requirements under EU oversight are creating service revenue streams for printer OEMs offering blockchain-integrated production logging. Design studios in Randstad specify Multi Jet Fusion systems for color-accurate client-presentable prototypes.
3D Printing in Consumer Goods Market Competitive Landscape
Listed leaders compete with private specialists across technology platforms, with public companies commanding production-scale system revenue while private entities capture niche formulation and software layers. Market structure bifurcates between consolidated powder bed fusion equipment supply and fragmented desktop printer distribution. Three archetypes dominate: polymer platform specialists, resin formulation houses, and generative design software providers. Competitive moves concentrate on strategic partnerships between equipment OEMs and consumer brands, plus geographic expansion through regional certification harmonization.
Within the polymer platform tier, HP Inc. and Stratasys exemplify divergent positioning strategies, with the former anchoring production-scale batch consistency and the latter occupying the prototyping tier where design studios converge. EOS GmbH represents the German equipment manufacturing archetype concentrated in Bavaria and North Rhine-Westphalia. These three entities collectively illustrate how technology specialization—Multi Jet Fusion, FDM and PolyJet systems, and selective laser sintering—creates distinct competitive territory rather than direct overlap.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| HP Inc. |
| EOS GmbH |
| Materialise |
| General Electric Company |
| Renishaw plc |
| Carbon |
| Markforged |
| Others |
Pricing and Supply Chain Analysis
REACH authorization requirements for photoinitiator substances gate both resin formulation supply qualification and jewelry-grade material price differentiation simultaneously. This regulatory filter concentrates premium pricing power among German formulation houses with ECHA pre-certification while compressing margins for importers facing reformulation lag.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ISO-certified dimensional tolerances and after-sales service bundling. Cost compression in desktop filament tiers is intensifying because Yangtze River Delta extrusion capacity is expanding. Hobbyist segments exhibit highest price sensitivity while production-scale polymer printer procurement teams prioritize batch consistency over unit cost.
Supply Chain Analysis
Germany and the United States anchor production-scale powder bed fusion equipment manufacturing. Raw material flows draw from lignin-derived bio-resin precursors, photopolymer acrylate formulations, and polyamide 12 powders. Single-source vulnerability concentrates among three equipment OEMs controlling selective laser sintering platforms. Distribution runs through captive sales forces for enterprise accounts and specialized e-commerce platforms for desktop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass customization demand is fragmenting manufacturing economics into niche-configurable micro-factories. This decomposition creates specialist opportunities for formulation houses, generative design software providers, and distributed production operators.
For Market Incumbents: Compound technology leadership in programmable resin chemistry through backward integration into bio-based precursor supply. Carbon and HP Inc. must preempt ECHA substance displacement by accelerating thiol-ene formulation R&D. Defend equipment procurement relationships in Bavaria and North Rhine-Westphalia against emerging Asian certification pathways.
For New Entrants and Emerging Players: Blockchain-integrated production logging services represent a service-layer gap where incumbents under-serve EU CSRD compliance requirements. Target design studios in metropolitan Netherlands and Germany with browser-based parametric tools. Pursue BIS harmonization pathways for desktop printer import channels into Maharashtra and Karnataka micro-factory networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across generative design-AI convergence layers. Five-to-ten year viability favors acquisition targets with digital product passport integration capabilities and thiol-ene chemistry portfolios. Monitor ECHA substance of very high concern listing velocity as inflection indicator for resin formulation displacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Resin Formulation | ECHA REACH pressure is accelerating lignin-derived alternatives for jewelry applications. |
| Digital Product Passport Integration | EU CSRD mandates are creating service revenue streams for blockchain-logging capabilities. |
| Distributed Micro-factory Deployment | Athletic brands in Bavaria are deploying gradient-density midsole production below 500-unit thresholds. |
| Generative Design-AI Convergence | Topology optimization paired with lattice tools enables material-efficient home fixture customization. |
| Regional Certification Harmonization | India BIS standards are opening import channels for desktop OEMs targeting design studios. |
Research Methodology
Desk research of ECHA substance authorization databases, EU CSRD implementation guidance, and customs trade data preceded structured interviews with polymer formulation chemists, industrial printer OEM procurement managers, athletic brand manufacturing directors, and design studio technical leads. Primary fieldwork with Bavaria-based equipment manufacturers and Netherlands-based configurators combined with secondary validation from FDA 510(k) filing records and BIS certification pathways. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Variance decomposition across material type, end-user sophistication tier, and distribution channel anchored the analytical framework over the projection horizon. Modeled dimensions encompassed product type, material chemistry, customer archetype, and geographic regulatory cluster. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion. Forecast inputs incorporated photoinitiator reformulation timelines and powder bed fusion equipment procurement lead times.
Forecasts assume regulatory continuity in REACH authorization regimes and FDA 510(k) review protocols; material policy shifts would require re-modeling. Specific risks include ECHA substance of very high concern acceleration, EPA volatile organic compound emission tightening, and MIIT standards disruption. Recalibration cycles align with material shifts in polymer feedstock compliance thresholds and distributed manufacturing platform adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Metal 3D Printing Service Market
3D Printing Technology
3D Printing Market
3D Printing Technology
Conventional and Rapid Prototyping Market
3D Printing Technology
North America Additive Manufacturing Market
3D Printing Technology
Military 3D and 4D Printing Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
Additive Manufacturing Platform Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
Additive Manufacturing Software Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
Food 3D Printing Market
3D Printing Technology
Binder Jet Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market