
 Global Automated 3D Printing Market | 2026-2036
Global Automated 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated 3D Printing Market Analysis
Contract manufacturers is reorganizing procurement priorities around lights-out additive production, shifting volume from job shops to integrated tier-one suppliers. Stratasys Ltd leverages its polymer platform breadth to sustain service bureau relationships across medical and consumer goods. EOS GmbH anchors metal powder-bed demand through direct OEM partnerships in automotive and aerospace. ABB Ltd competes on robotic arm precision for post-processing automation, differentiating from Universal Robots A/S on payload capacity.
Automated 3D printing denotes computer-controlled additive manufacturing systems that execute build jobs with minimal operator intervention, typically incorporating robotic material handling, in-situ monitoring via thermal cameras or laser profilometry, and automated part removal. These systems produce functional prototypes, tooling inserts, and end-use components across polymers, metals, and ceramics by sequentially depositing or fusing material layers according to digital CAD files. Metal powder-bed fusion commands premium system pricing and margins, while FDM retains volume leadership in prototyping and jigs. Aerospace and medical verticals concentrate demand for certified automated workflows, whereas automotive buyers prioritize throughput over qualification breadth.
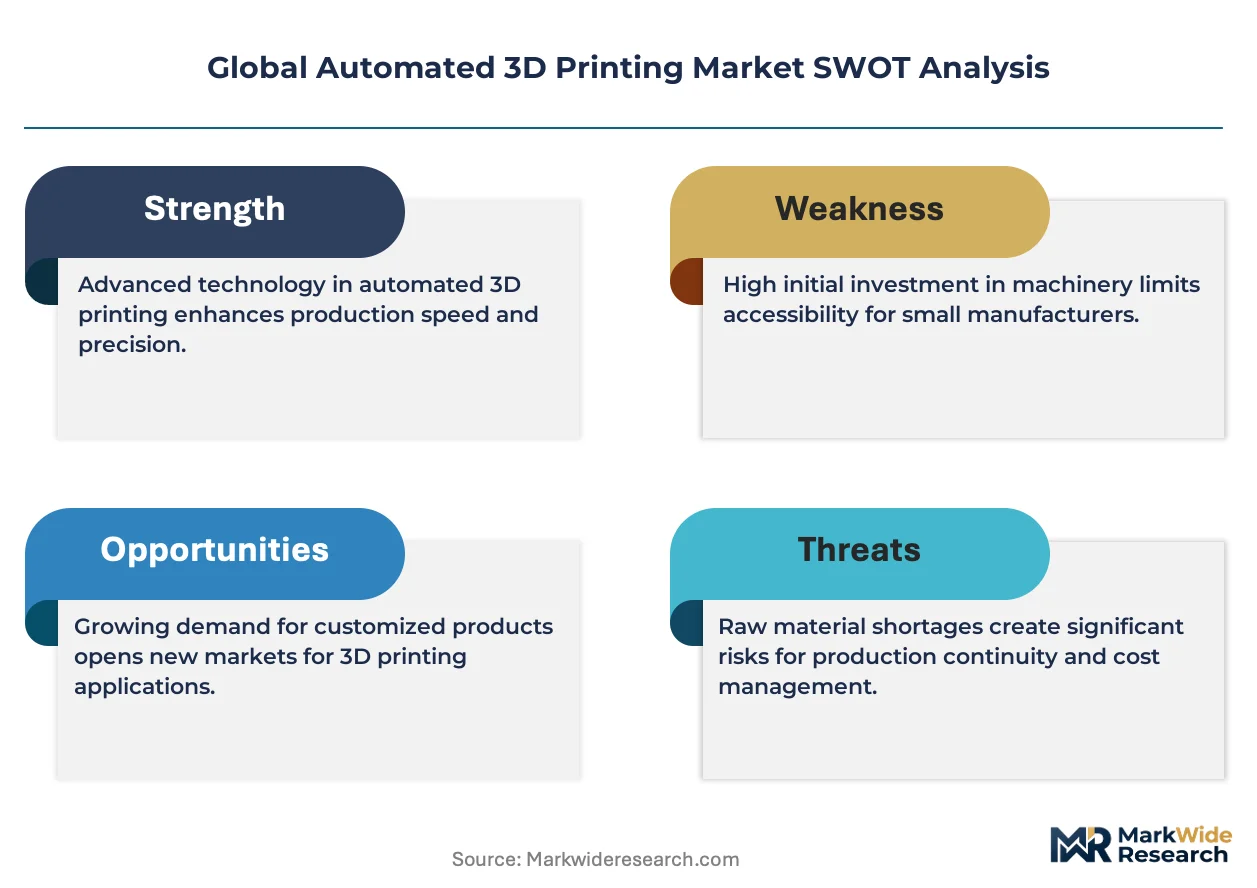
FDA quality system regulation and EU MDR traceability mandates compel automated 3D printing vendors to embed serialized process logging and material genealogy. EPA emissions guidelines and REACH chemical restrictions shape powder handling and post-processing chemistry selections in North America and Europe. ISO/ASTM additive manufacturing standards provide the interoperability baseline that OEMs require before qualifying autonomous production cells. Stakeholders must monitor how regulatory divergence between FDA predicate device pathways and EU notified body expectations fragments validation protocols.
Market Dynamics
Flight-certification requirements from the FAA and EASA are compressing validation timelines for automated additive cells, forcing aerospace suppliers to pre-qualify entire production workflows rather than individual parts. This structural pressure is redrawing competitive boundaries between integrated system vendors and component specialists.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers must embed serialized process logging in automated 3D printing workflows, creating pull for qualified production systems across Germany, Switzerland, and the Netherlands.
- Polymer laser sintering:Automotive interior component programs are adopting automated powder-bed systems for serial tooling, replacing machined aluminum fixtures with printed PA12 equivalents.
- Japan's METI additive manufacturing roadmap:Government-funded pilot lines in Osaka and Nagoya are demonstrating lights-out metal deposition for turbine blades, accelerating domestic supplier qualification.
Market Restraints
- Metal powder supply concentration:Spherical titanium and nickel superalloy feedstock production clusters in Germany and the United States, exposing buyers to single-source risk during alloy certification transitions.
- REACH chemical restrictions:Powder handling systems require modified filtration chemistry to comply with European substance restrictions, adding capex burden to post-processing automation.
- Subtractive machining substitution:Five-axis CNC centers retain cost advantages for aluminum structural brackets below 500-unit production runs, limiting automated 3D printing penetration in legacy aerospace programs.
Strategic Opportunities
- India's PLI scheme for capital goods:Domestic additive manufacturing equipment production incentives are opening procurement pathways for automated polymer systems serving medical implant job shops in Gujarat and Karnataka.
- In-situ monitoring convergence:Thermal camera arrays fused with machine learning defect prediction are enabling real-time process adjustment, reducing post-build inspection overhead for flight-critical components.
- Service bureau consolidation:Tier-one contract manufacturers are acquiring regional 3D printing job shops to capture automated production volume, displacing fragmented local suppliers in France and Italy.
Industry Challenges
- Multi-material process engineering talent:Automated systems require operators fluent in both polymer rheology and metal phase transformation, a skill combination scarce in traditional manufacturing labor pools.
- AS9100D certification timelines:Aerospace suppliers face 18-24 month validation cycles for autonomous production cells, compressing ROI windows against faster-qualified conventional automation.
- Legacy MES integration:Automated 3D printing cells must interface with decades-old shop-floor data systems, creating middleware development burdens that delay deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated 3D Printing Market |
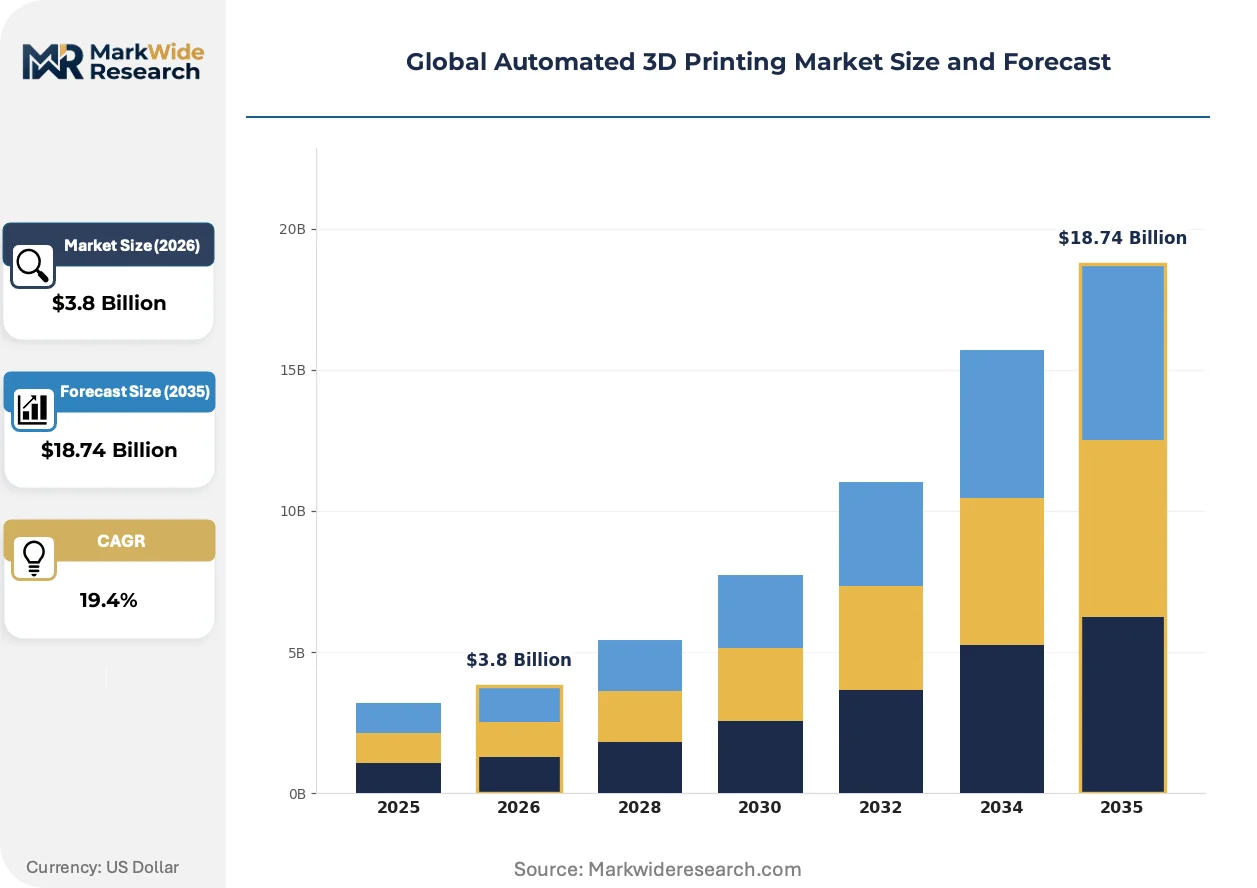
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
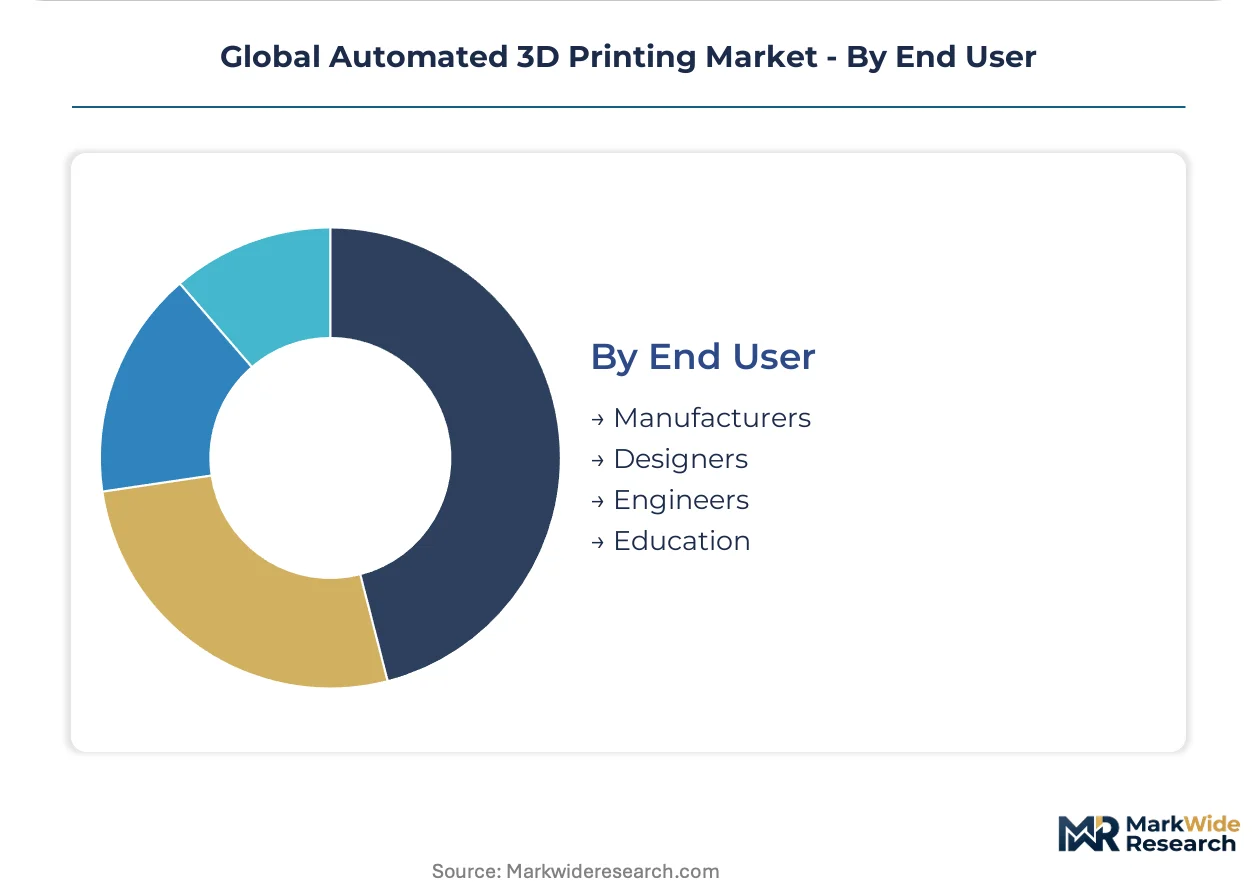
| Segmentation | Product Type: FDM, SLA, SLS, DLP Industry Vertical: Aerospace, Automotive, Medical, Consumer Goods Material: Plastic, Metal, Ceramic, Composites End User: Manufacturers, Designers, Engineers, Education |
| Companies Covered | Stratasys Ltd, 3D Systems Corporation, GE Additive, The ExOne Company, SLM Solutions Group AG, Universal Robots A/S, ABB Ltd, HP Inc., EOS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated 3D Printing Market Emerging Trajectories
Continuous fiber-reinforced deposition is redrawing the structural performance boundary between printed and machined components. Regulatory divergence between the FDA's predicate device pathway and EU notified body expectations is fragmenting validation protocols. Buyer concentration among tier-one contract manufacturers is compressing pricing power for equipment vendors.
Continuous fiber-reinforced thermoplastic printing is displacing machined aluminum brackets in unmanned aerial vehicle airframes. Aerospace tier-two suppliers in the United States and Israel are adopting automated tape-laying systems at pilot-line scale. This displacement is compressing the traditional metals supply chain for sub-50 kilogram structural assemblies.
REACH authorization requirements for nickel powder handling are forcing post-processing automation redesigns across European metal additive installations. Industrial users in Germany and Sweden must retrofit robotic depowdering stations with closed-loop filtration. Medical implant manufacturers face the steepest compliance burden, as biocompatible alloy genealogy requirements intersect with chemical exposure limits.
Certificate-of-analysis-driven procurement is consolidating purchase authority among integrated tier-one suppliers. Medical device OEMs in Switzerland and the United States now require automated 3D printing partners to pre-validate entire production workflows, not just final components. This shift is marginalizing independent job shops that lack capital for full-process qualification.
Global Automated 3D Printing Market Segmentation
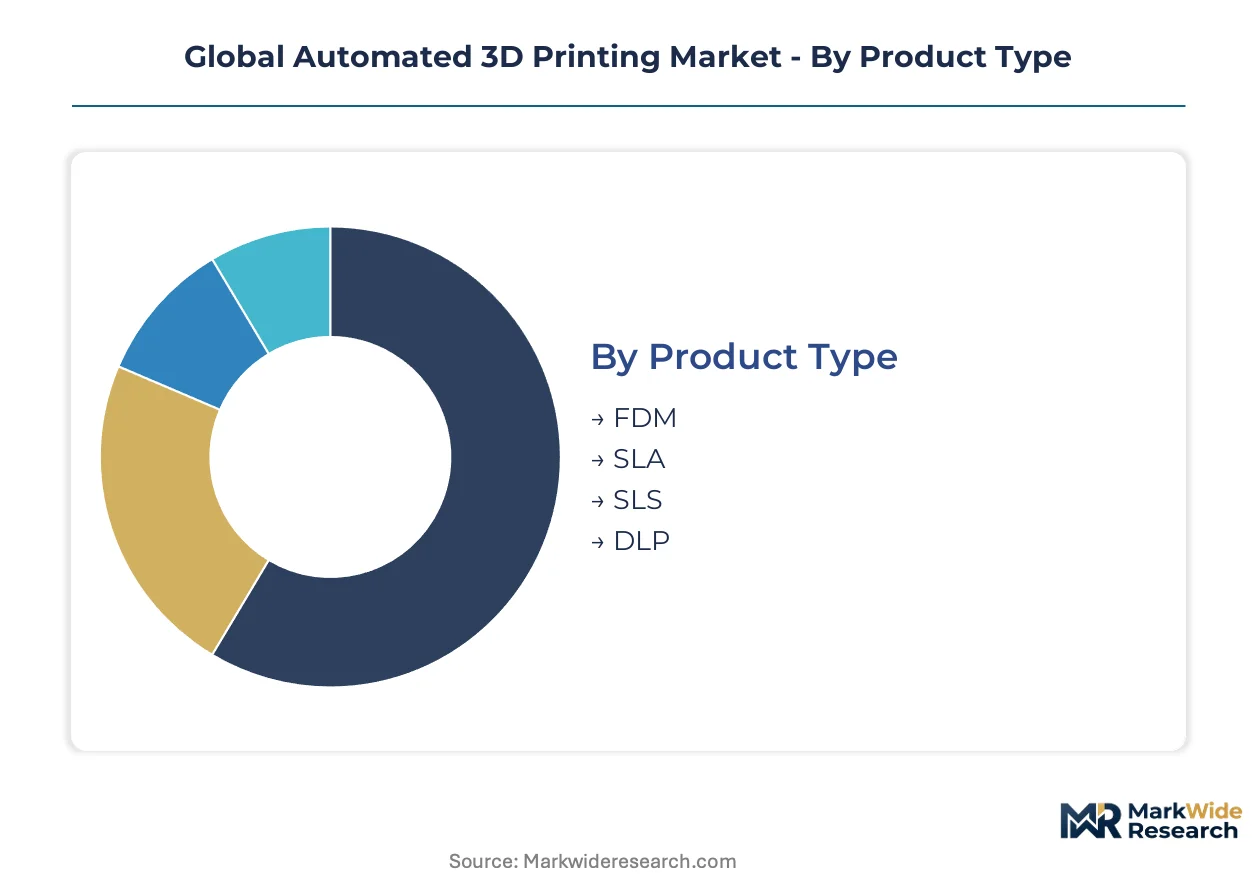
Automated 3D printing segmentation reveals how technology choice, material constraints, and end-user sophistication fragment procurement patterns across industries. Buyers prioritize different performance thresholds—flight certification versus prototyping speed—creating distinct competitive arenas within each dimension.
Product Type:
SLA and DLP face intensifying substitution pressure from continuous fiber-reinforced systems in structural applications, while powder-bed technologies defend aerospace and medical niches through regulatory lock-in.
- SLS:Laser-sintered polymer and metal powder-bed systems achieve the highest automation integration with robotic powder handling and thermal monitoring. Demand concentrates in Germany for automotive tooling fixtures and aerospace bracket production, driven by EU MDR traceability mandates requiring serialized process logging.
- FDM:Fused deposition modeling dominates prototyping volumes through material extrusion simplicity and lower capex thresholds. Automotive interior programs in Japan and consumer goods manufacturers in the United States adopt automated FDM cells for jigs and low-volume end-use parts, constrained by surface finish limitations versus competing processes.
- SLA:Stereolithography delivers micron-scale resolution through photopolymer vat curing, serving dental aligner and hearing aid manufacturers requiring biocompatible surface quality.
- DLP:Digital light projection accelerates layer throughput via masked exposure, attracting jewelry and microfluidic device producers balancing speed against build envelope constraints.
SLS retains volume leadership in certified production; DLP holds the steepest expansion curve in micro-precision medical applications.
Industry Vertical:
Cost tier stratification separates capital-intensive qualification programs from high-throughput, low-margin production environments.
- Aerospace:FAA and EASA flight-certification requirements compress validation timelines for automated additive cells, forcing tier-one suppliers to pre-qualify entire workflows. Demand clusters in the United States and Israel for unmanned aerial vehicle airframes and turbine blade repair.
- Medical:FDA predicate device pathways and EU MDR traceability mandates compel serialized material genealogy and process logging. Swiss and German implant manufacturers drive premium system specifications for titanium and PEEK biocompatible alloys.
- Automotive:Serial tooling programs prioritize throughput over qualification breadth, with German OEMs adopting automated powder-bed systems for interior fixture production.
- Consumer Goods:Mass customization and rapid prototyping cycles emphasize equipment flexibility and material cost efficiency over regulatory compliance depth.
Medical commands the steepest system pricing; automotive represents the largest addressable equipment volume.
Material:
Supply concentration risk varies dramatically by feedstock chemistry, with spherical metal powders exposing buyers to single-source dependencies during alloy transitions.
- Metal:Titanium and nickel superalloy powder-bed fusion commands premium system pricing and margins through aerospace and medical certification requirements. German and United States powder producers anchor global supply, creating vulnerability during REACH authorization transitions for nickel handling.
- Plastic:PA12 and photopolymer resins dominate prototyping and tooling volumes through lower material cost and broader supplier bases. REACH chemical restrictions on powder handling chemistry add capex burden to European installations.
- Ceramic:Oxide and non-oxide technical ceramics serve high-temperature tooling and biomedical scaffolds, constrained by sintering shrinkage control and limited feedstock standardization.
- Composites:Continuous fiber-reinforced thermoplastics displace machined aluminum in structural brackets, with automated tape-laying systems gaining traction in Israeli and United States aerospace tier-two suppliers.
Plastic sustains the broadest installed base; composites are gaining share fastest in structural performance-critical applications.
End User:
Customer capability maturity determines automation depth, with integrated manufacturers deploying lights-out cells while fragmented users rely on service bureau relationships.
- Manufacturers:Tier-one contract manufacturers reorganize procurement around autonomous production, acquiring regional job shops to capture volume. India's PLI scheme for capital goods opens domestic equipment pathways for medical implant producers in Gujarat and Karnataka.
- Designers:Industrial design studios prioritize build speed and material aesthetics over process traceability, driving demand for desktop-scale automated systems with minimal operator intervention.
- Engineers:R&D and prototyping groups require multi-material flexibility and rapid job changeover, favoring FDM and SLA platforms with open material ecosystems.
- Education:Universities and technical institutes emphasize equipment reliability and curriculum alignment over production throughput, constrained by budget cycles and maintenance support availability.
Manufacturers capture the steepest automation investment trajectory; education represents the most price-sensitive procurement segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors continental Europe's metal powder logistics, while the Port of Long Beach handles Pacific Rim feedstock flows. These maritime gateways determine where automated additive manufacturing cells achieve viable operating economics.
United States
Aerospace tier-one suppliers in Connecticut and California pre-qualify entire automated workflows under FAA flight-certification timelines. EPA emissions guidelines shape powder handling system designs across Ohio and Texas installations. Greater Boston medical device clusters demand serialized process logging for FDA predicate device pathways.
Germany
Automotive OEMs in Bavaria adopt automated powder-bed systems for serial interior tooling production. REACH chemical restrictions force modified filtration chemistry in post-processing automation. The EOS GmbH and SLM Solutions Group AG supplier ecosystem concentrates around Munich and Lübeck.
Japan
METI-funded pilot lines in Osaka and Nagoya demonstrate lights-out metal deposition for turbine blade applications. JIS standards provide interoperability baselines that OEMs require before qualifying autonomous production cells. Chubu region aerospace suppliers accelerate domestic qualification timelines.
Switzerland
Swissmedic traceability mandates compel implant manufacturers to embed material genealogy systems in automated workflows. Geneva and Basel medical device clusters drive premium specifications for titanium and PEEK biocompatible alloys. Alpine precision machining heritage transfers to robotic post-processing automation.
India
PLI scheme incentives for capital goods equipment open procurement pathways for medical implant job shops in Gujarat and Karnataka. CDSCO quality system regulations mirror FDA predicate device structures. Maharashtra contract manufacturers reorganize procurement around autonomous production volume.
Global Automated 3D Printing Market Vendor Landscape
Listed leaders compete with private specialists across system integration depth, with public equipment vendors facing pressure from privately held automation integrators. The vendor base stratifies between integrated platform providers and component specialists. Three archetypes dominate: polymer platform generalists, metal powder-bed specialists, and robotic automation suppliers. Competitive moves concentrate on strategic partnerships between equipment vendors and tier-one contract manufacturers, plus technology licensing for in-situ monitoring modules.
Within the metal powder-bed specialist tier, EOS GmbH and SLM Solutions Group AG occupy positions anchored by direct OEM relationships in automotive and aerospace. Among robotics automation providers, ABB Ltd and Universal Robots A/S exemplify divergent payload capacity strategies for post-processing automation. Stratasys Ltd represents the polymer platform breadth archetype sustaining service bureau relationships across regulated verticals.
| Leading Market Players |
|---|
| Stratasys Ltd |
| 3D Systems Corporation |
| GE Additive |
| The ExOne Company |
| SLM Solutions Group AG |
| Universal Robots A/S |
| ABB Ltd |
| HP Inc. |
| EOS GmbH |
| Others |
Supply Flow & Price Mechanics
Continuous fiber-reinforced thermoplastics displacing machined aluminum brackets simultaneously redraws supply geography toward Israeli and United States aerospace tier-two suppliers while compressing pricing premiums for legacy metal powder-bed systems. This substitution dynamic forces equipment vendors to reposition pricing architectures around performance-per-kilogram rather than build-volume metrics.
Pricing Analysis
Volume-discount tiering structures separate aerospace qualification-grade systems from prototyping-tier equipment, with FDA and EU MDR certification premiums commanding substantial markups over uncertified alternatives. Price differentiation hinges on serialized process logging capabilities and flight-certification documentation depth. Cost compression in the prototyping tier intensifies as desktop-scale automated FDM platforms commoditize jigs and fixture production. Medical implant manufacturers exhibit the lowest price sensitivity due to biocompatible alloy genealogy requirements, whereas consumer goods buyers prioritize capital efficiency over qualification breadth.
Supply Chain Analysis
Inbound logistics costs through the Port of Hamburg and Port of Long Beach determine viable operating economics for automated additive manufacturing cells dependent on spherical titanium and nickel superalloy feedstock. Powder production clusters in Germany and the United States anchor global metal supply, with REACH authorization transitions for nickel handling creating regulatory friction. Raw material dependencies span certified powder feedstock, robotic arm components, and thermal monitoring arrays. Single-source vulnerability during alloy certification transitions constitutes the dominant structural risk. Distribution runs through integrated tier-one contract manufacturers acquiring regional job shops to capture autonomous production volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated 3D printing represents high-growth manufacturing disruption justified by EU AI Act traceability mandates compelling serialized process logging adoption across flight-critical and implant-grade production workflows.
For Market Incumbents: Compound defensive positioning through backward integration into spherical powder production and captive qualification laboratory capacity. Lock in tier-one aerospace contracts via pre-validated autonomous workflow offerings before emerging robotics integrators achieve AS9100D certification. Prioritize post-processing automation IP to differentiate from Universal Robots A/S payload-centric approaches. For New Entrants and Emerging Players: FDA predicate device pathway fast-tracks offer penetration leverage into Greater Boston medical device clusters underserved by qualified automated polymer systems. White-space targets include India's Gujarat and Karnataka medical implant job shops responding to PLI scheme capital goods incentives. Pursue service bureau acquisition strategies in fragmented French and Italian regional markets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated platform providers over component specialists. Long-term viability centers on vendors controlling both powder-bed fusion hardware and in-situ monitoring software stacks. Acquisition target archetype: mid-cap automation integrators with existing aerospace tier-two relationships. Watch for FAA-EASA regulatory convergence on flight-certification timelines as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Production | Captive spherical titanium supply insulates against REACH nickel authorization disruptions. |
| Pre-Validated Workflow Partnerships | Tier-one aerospace contracts lock out emerging robotics competitors. |
| In-Situ Monitoring Module Licensing | Thermal camera ML defect prediction reduces post-build inspection overhead. |
| Service Bureau Consolidation | Regional job shop acquisitions capture automated production volume in France and Italy. |
| Regulatory Fast-Track Certification | FDA predicate device pathway penetration opens Greater Boston medical clusters. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and equipment vendor disclosures. Interviews with additive manufacturing plant managers, aerospace procurement leads, medical device regulatory affairs directors, and robotic automation integration specialists informed demand-side validation. Secondary sources include FAA certification databases, EU MDR technical documentation, EPA emissions guidelines, and ISO/ASTM additive manufacturing standards. Bottom-up equipment shipment analysis triangulates against top-down end-use industry spend estimates.
Segmentation dimensions modeled span product type, material chemistry, industry vertical, and end-user capability maturity across the projection horizon. Technology adoption curves incorporate regulatory compliance timelines and flight-certification validation cycles. CAGRs derive from equipment pricing trajectories, powder feedstock cost structures, and labor substitution economics. Industry-specific inputs include AS9100D certification cycle lengths and REACH chemical restriction implementation schedules.
Underlying assumptions cover sustained aerospace tier-one procurement concentration, stable spherical powder supply from Germany and United States producers, and gradual FDA-EASA regulatory convergence, with deviation risk concentrated in REACH nickel authorization delays and legacy MES integration failures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
United States 3D Printing Market
3D Printing Technology
Asia-Pacific Additive Manufacturing Market
3D Printing Technology
Metal 3D Printing Service Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Hybrid Additive Manufacturing Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
3D Printing Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
3D Printing Enabled Augmented Manufacturing Market