
 Personal 3D Printers Market | 2026-2036
Personal 3D Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Personal 3D Printers Market Intelligence
REACH is hardening material compliance obligations for any desktop printer sold into European households. Creality leverages its Shenzhen manufacturing base to absorb certification costs across high shipment volumes. Bambu Lab differentiates through closed-loop motion systems that reduce calibration burden for casual users. Prusa Research sustains premium positioning via in-house extruder development and open-source firmware stewardship.
Personal 3D printers are compact additive manufacturing systems, typically with build volumes under 300 mm per axis, that deposit thermoplastic filament or cure photopolymer resin layer by layer to produce physical objects from digital models. FDM systems dominate unit shipments due to sub-$300 entry pricing and benign material handling, while SLA configurations capture margin pools in dental modeling and jewelry casting where surface finish requirements exceed filament capabilities. Resin material compatibility is fragmenting as third-party formulations bypass OEM cartridge lock-in, pressuring proprietary revenue streams.
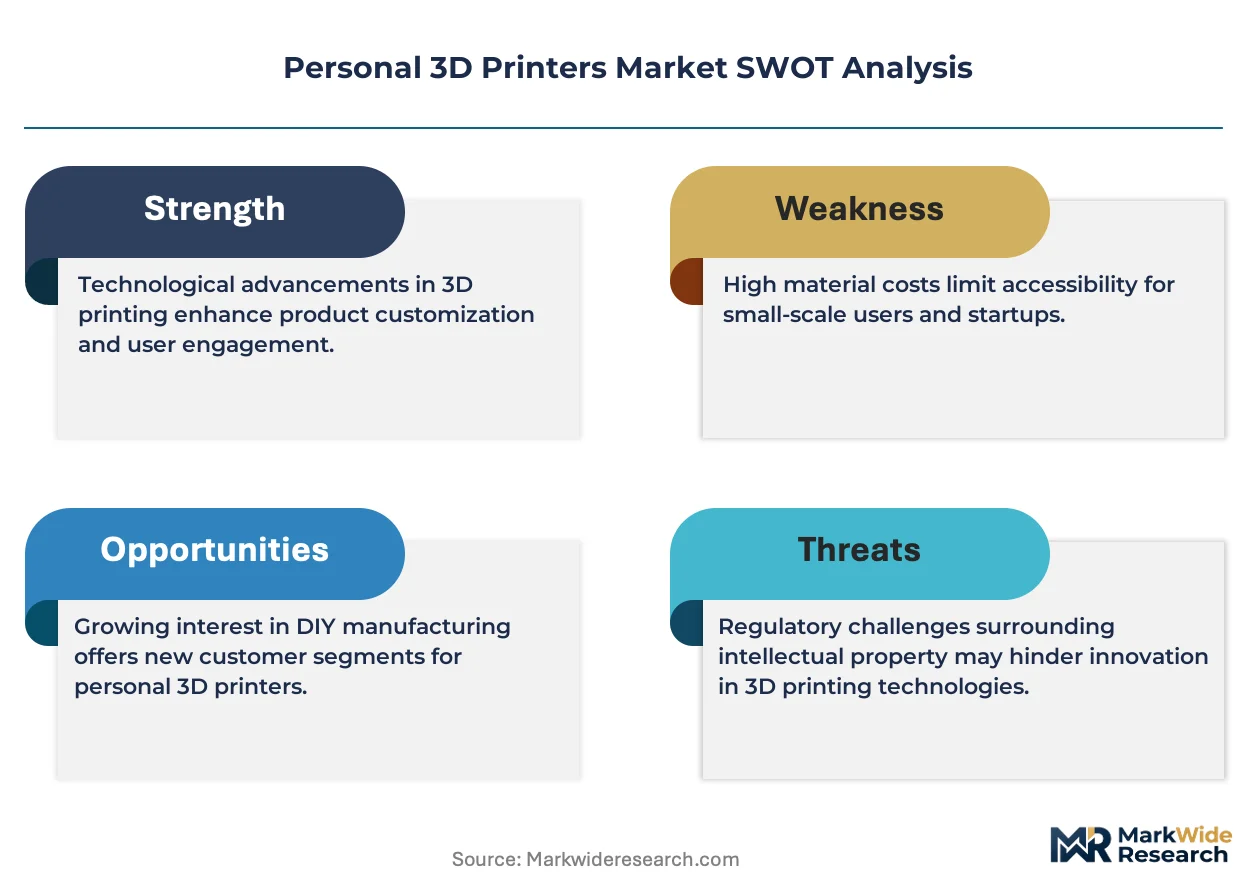
The US Consumer Product Safety Commission and China's SAMR both scrutinize thermal runaway protections and enclosure emissions for devices marketed to residential users. CE marking under the EU Machinery Directive now demands documented risk assessments for pinch points and heated components accessible to children. Stakeholders must monitor whether emerging ISO/ASTM standards for desktop system safety become de facto import prerequisites in major consumer markets.
Market Dynamics
Component cost compression in Shenzhen's hardware ecosystem is redrawing competitive boundaries between FDM and resin-based systems, forcing incumbents to absorb certification burdens across shrinking margin pools.
Growth Catalysts
- Hobbyist Maker Segment Expansion:Small-scale product designers and DIY enthusiasts in North American and European households are driving unit volume growth for sub-$400 filament systems. This demographic prioritizes plug-and-play operation over professional-grade calibration.
- RoHS Compliance Maturation:The EU's restriction of hazardous substances in electrical equipment has forced material suppliers to develop lead-free hotend assemblies and halogen-reduced wiring harnesses. OEMs now bundle compliance documentation with retail packaging.
- Photopolymer Formulation Advances:Third-party resin chemistries with improved biocompatibility and reduced odor profiles are unlocking dental modeling applications previously gated by proprietary cartridge economics.
Market Restraints
- Critical Component Concentration:Stepper motor drivers and precision lead screws concentrate among a handful of Guangdong suppliers, exposing assemblers to lead time volatility during peak demand windows.
- Thermoplastic Input Cost Sensitivity:PLA and ABS filament prices track corn starch and butadiene feedstock indices, compressing gross margins when agricultural commodity markets tighten.
- CE Marking Documentation Burden:The EU Machinery Directive's risk assessment requirements for heated enclosures and pinch points add 8-12 weeks to product launch timelines for new entrants lacking established notified body relationships.
Strategic Opportunities
- India Hardware Startup Ecosystem:Bengaluru and Hyderabad incubators are cultivating indigenous printer designs optimized for unreliable grid power and tropical humidity conditions, bypassing Western-centric thermal management assumptions.
- Educational Institution Procurement:K-12 STEM budgets in South Korea and Japan are allocating dedicated additive manufacturing equipment lines, favoring vendors with curriculum-aligned software stacks and educator certification programs.
- Closed-Loop Motion System Convergence:Integration of AI-powered first-layer detection with active vibration compensation is reducing support ticket volumes for casual users who lack traditional calibration expertise.
Industry Challenges
- Firmware Development Talent Scarcity:Embedded systems engineers with real-time motion control experience command premium compensation, constraining in-house R&D expansion for mid-tier assemblers.
- Multi-Jurisdictional Safety Certification:Simultaneous pursuit of UL listing for US residential sales, CE marking for EU access, and CCC compliance for Chinese domestic distribution strains quality assurance bandwidth.
- Resin Waste Stream Management:Uncured photopolymer disposal protocols vary by municipality, creating post-sale liability exposure and complicating direct-to-consumer resin subscription models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal 3D Printers Market |
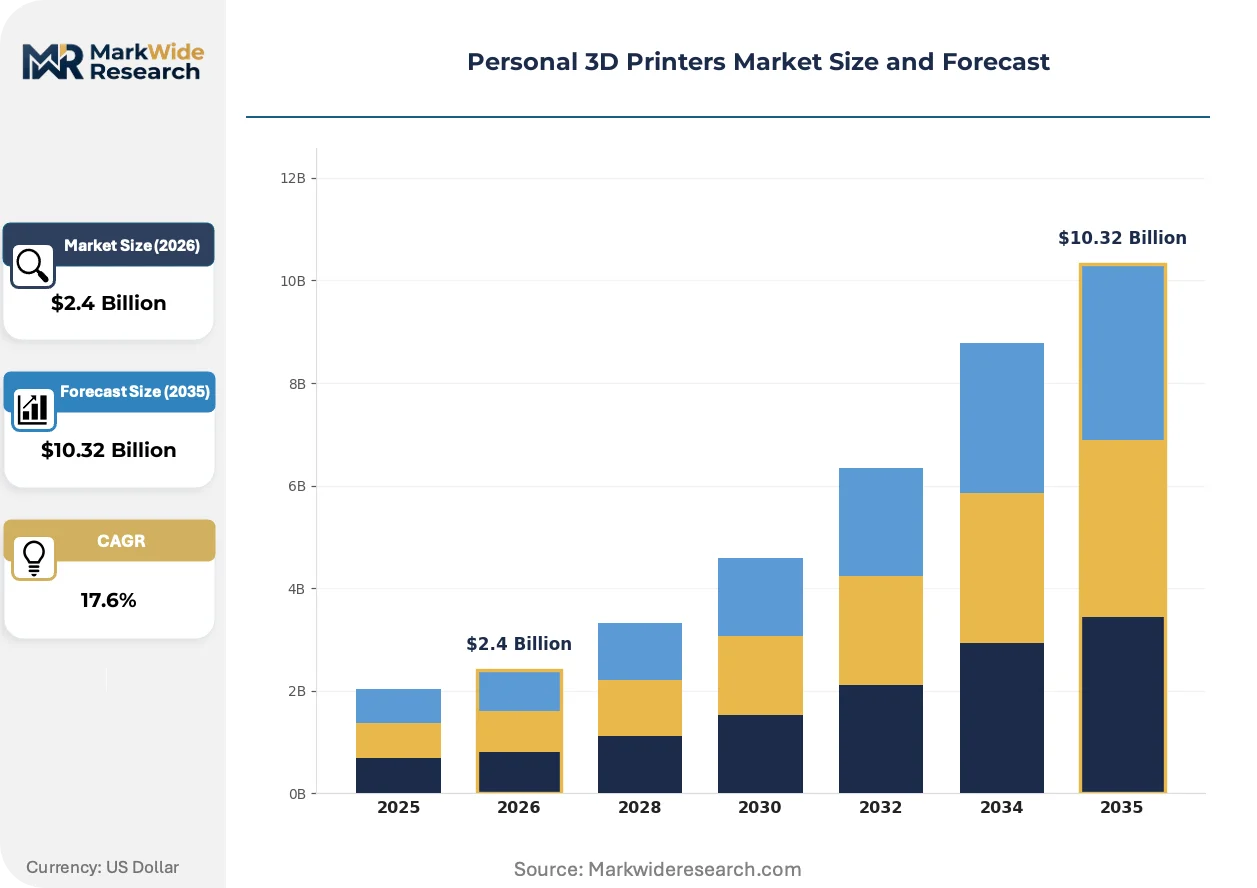
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $10.32 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FDM, SLA, SLS, DLP Application: Prototyping, Education, Home Use, Art Material: PLA, ABS, PETG, Resin Connectivity: USB, Wi-Fi, Bluetooth, Ethernet |
| Companies Covered | Creality, Snapmaker, Bambu Lab, Sovol, QIDI Tech, Elegoo, Anycubic, Original Prusa, Prusa Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal 3D Printers Market Strategic Shifts & Innovations
Active noise cancellation in stepper motor drivers and AI-assisted print failure detection are compressing the expertise gap between casual hobbyists and professional operators.
Multi-material FDM extrusion is expanding into jigs and fixtures production for small-batch manufacturers who previously outsourced machined aluminum components. Automotive prototyping shops in Stuttgart and Detroit are adopting these systems for overnight iteration cycles. The technology is expanding into applications where surface finish tolerances previously mandated CNC subcontracting.
REACH substance restrictions on photoinitiators and plasticizers are forcing resin formulators to reformulate standard catalog products for European market access. ECHA's candidate list expansion is accelerating substitution of bisphenol-A derivatives in dental-grade materials. German and French distributors now require full material disclosure sheets before listing new consumable SKUs.
Direct-to-consumer resin subscription models are displacing traditional distributor stocking arrangements for recurring material purchases. Dental clinics in Tokyo and Seoul are bypassing regional importers to source specialty biocompatible formulations from Shenzhen manufacturers. This channel compression is most pronounced in East Asian markets where e-commerce platform integration reduces procurement friction for repeat buyers.
Personal 3D Printers Market Segmentation
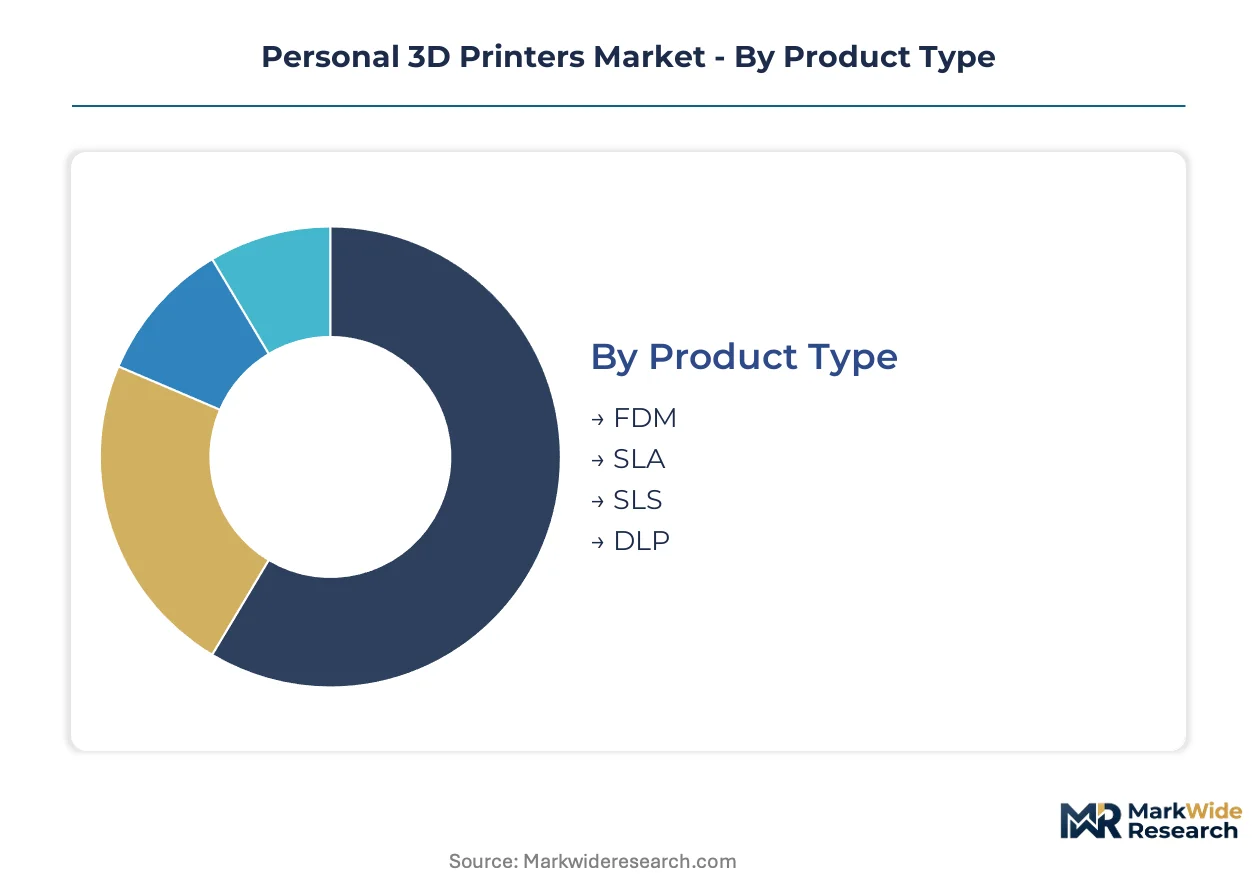
Personal 3D printer segmentation reveals how component sourcing and assembly economics fragment across technology tiers. Supply chain concentration in Shenzhen's hardware ecosystem directly shapes which configurations achieve viable price points for household penetration.
Product Type:
Shenzhen's component ecosystem favors FDM system assembly with standardized extruder kits and open-source control boards, while resin-based configurations require tighter optical calibration tolerances that concentrate among specialized suppliers.
- FDM:Fused deposition modeling deposits thermoplastic filament through a heated nozzle onto a build platform, layer by layer. Shenzhen's vertical integration into stepper motors and aluminum extrusion frames enables sub-$300 retail pricing that dominates North American hobbyist demand. Thermal runaway protection firmware and all-metal hotend upgrades now differentiate mid-tier offerings from entry-level imports.
- SLA:Stereolithography cures liquid photopolymer resin with a UV laser or LCD masking system, achieving surface finishes below 25 microns. Dental modeling labs in Stuttgart and jewelry casting houses in Mumbai drive premium pricing despite higher material costs and post-processing complexity. Third-party resin compatibility is eroding proprietary cartridge lock-in.
- SLS:Selective laser sintering fuses nylon powder beds with infrared lasers, producing functional mechanical parts without support structures. Industrial patent expirations are lowering equipment costs, though powder recycling systems remain concentrated among German and Chinese OEMs.
- DLP:Digital light processing projects entire layers simultaneously through micromirror arrays, accelerating print speeds for small-format dental appliances. Texas Instruments' DLP chip supply constraints limit scaling beyond boutique manufacturing volumes.
Today's leader: FDM. Tomorrow's challenger: SLA.
Application:
End-use concentration determines firmware feature prioritization and bundled software ecosystems, with education and home use segments demanding divergent reliability guarantees.
- Prototyping:Product designers in Detroit automotive studios and Shenzhen hardware startups iterate overnight on fit-check models, replacing machined aluminum jigs with carbon-fiber-reinforced nylon fixtures. Build volume requirements above 250 mm per axis dominate this segment.
- Education:K-12 STEM programs in Seoul and Tokyo procure classroom-sized fleets with cloud-based print queue management and educator certification modules. Curriculum-aligned lesson plans now gate vendor selection more than hardware specifications.
- Home Use:Casual makers prioritize plug-and-play calibration and enclosed build chambers for residential safety compliance with EU Machinery Directive requirements.
- Art:Sculptors and miniature painters exploit SLA surface resolution for collectible figurines and architectural maquettes, tolerating resin odor and post-cure workflows.
Prototyping commands the steepest expansion trajectory as distributed manufacturing displaces centralized machining subcontracting.
Material:
Feedstock chemistry dictates printer hardware compatibility and recurring revenue economics, with biopolymer formulations disrupting petroleum-based incumbent positions.
- PLA:Polylactic acid derived from corn starch offers low-temperature processing and benign decomposition for classroom environments. Agricultural commodity price volatility in the US Midwest and Brazilian soybean regions compresses margin predictability for compounders.
- ABS:Acrylonitrile butadiene styrene requires heated build chambers and ventilation for styrene emission control, limiting residential adoption despite superior impact resistance for functional prototypes.
- PETG:Glycol-modified polyethylene terephthalate bridges PLA ease-of-use with ABS durability, gaining share fastest among small-batch manufacturers in Barcelona and Melbourne maker spaces.
- Resin:Photopolymer formulations span standard prototyping through ECHA-compliant dental biocompatibility grades, with third-party Shenzhen suppliers bypassing OEM cartridge authentication.
PLA retains volume leadership. PETG emerges as the ascendant challenger for functional applications.
Connectivity:
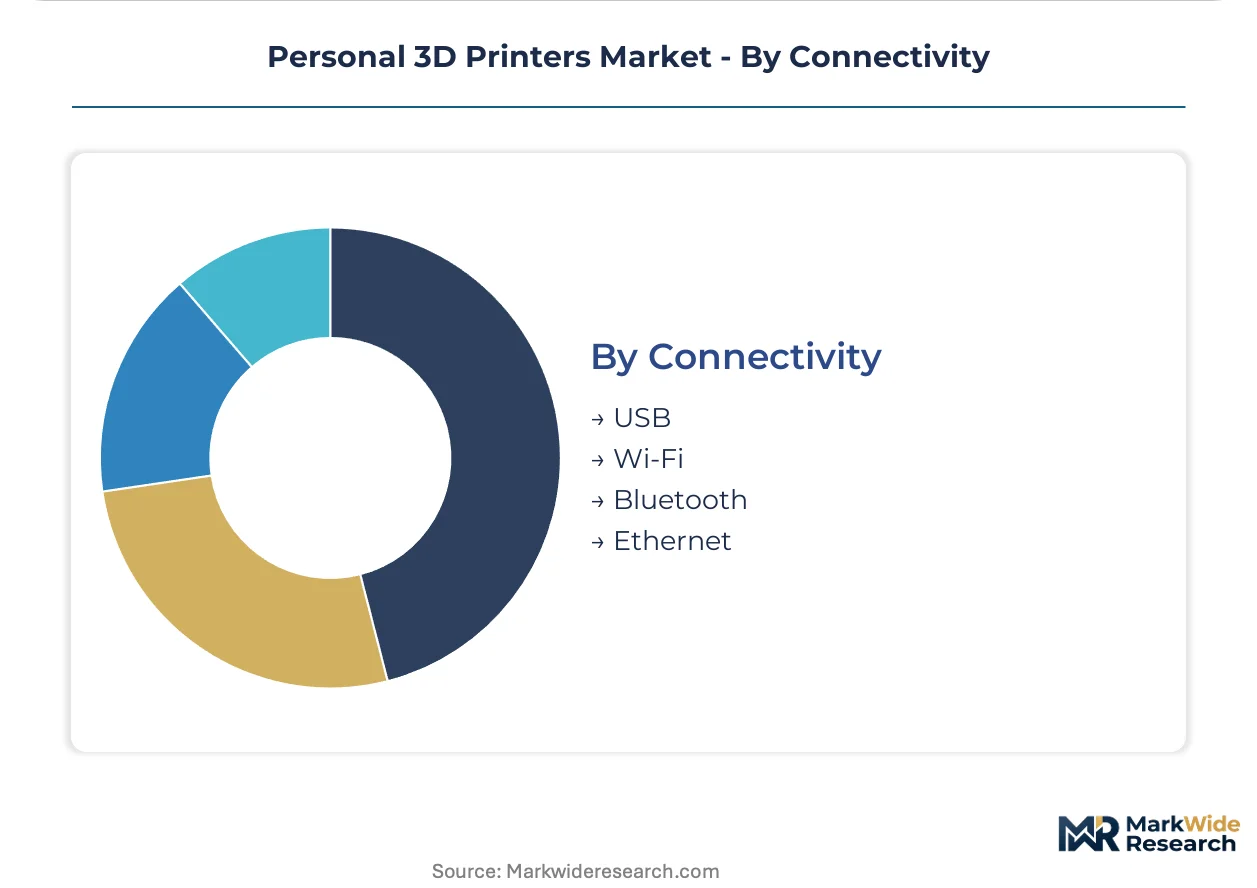
Interface architecture determines cloud service integration depth and remote monitoring capabilities, with wireless protocols now standard above entry price tiers.
- USB:Tethered connection persists in budget segments and secure facility deployments where air-gapped operation is mandatory.
- Wi-Fi:Wireless LAN enables smartphone-based print initiation and AI-powered failure detection alerts, now standard across mid-tier FDM and resin systems.
- Bluetooth:Short-range pairing supports initial setup and local firmware updates without router configuration, favored for educational deployments with restricted network policies.
- Ethernet:Wired reliability dominates university maker labs and small business production floors where Wi-Fi congestion threatens print job integrity.
Wi-Fi anchors current connectivity preferences. Ethernet defends critical production environments against wireless interference risks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems engineers with motion control expertise cluster in Shenzhen, Stuttgart, and Boston, anchoring firmware development capacity for desktop additive manufacturing platforms.
United States
Hobbyist makers and K-12 STEM programs drive filament system demand across suburban households and district procurement budgets. The Consumer Product Safety Commission scrutinizes thermal runaway protections for residential sales. Boston's hardware incubator density supports early-stage ventures developing AI-assisted calibration tools.
China
Shenzhen's component ecosystem compresses stepper motor and aluminum extrusion costs below global benchmarks. SAMR mandates enclosure emission testing and heated component accessibility documentation for domestic distribution. The Pearl River Delta concentrates LCD masking system suppliers serving resin printer assemblers.
Germany
Automotive prototyping studios in Stuttgart and dental modeling labs demand surface finishes below 25 microns. REACH substance restrictions on photoinitiators force resin formulators to reformulate for European market access. Bavaria's precision optics cluster supplies UV LED curing modules to desktop SLA manufacturers.
Japan
METI allocates K-12 STEM budgets toward additive manufacturing equipment lines with curriculum-aligned software requirements. JIS standards for desktop system safety influence procurement specifications for educational institutions. Tokyo's dental clinics source biocompatible resins through direct-to-consumer subscription channels bypassing regional importers.
India
Bengaluru and Hyderabad incubators cultivate indigenous printer designs optimized for unreliable grid power and tropical humidity. BIS certification requirements for electrical safety add compliance lead times for imported systems. Maharashtra's engineering institutes pilot closed-loop motion systems for novice operator segments.
Personal 3D Printers Market Key Industry Players
The competitive structure tilts toward vertically integrated Shenzhen assemblers with captive component supply. Shenzhen-based manufacturers leverage stepper motor and aluminum frame backward integration to absorb REACH and RoHS certification costs across high shipment volumes. Two strategic archetypes dominate: ecosystem-integrated hardware assemblers with Guangdong supply chain control, and firmware-specialist European vendors with open-source community stewardship. Capacity expansion and AI-powered calibration licensing represent the dominant competitive vectors.
Among Shenzhen-based fabricators, Creality, Bambu Lab, and Elegoo exemplify the ecosystem-integrated archetype. Creality occupies a position defined by Guangdong component sourcing scale. Bambu Lab represents closed-loop motion system differentiation targeting casual calibration-averse users. Elegoo anchors the resin system segment where third-party formulation compatibility erodes proprietary cartridge economics. Original Prusa, headquartered in Prague, exemplifies the European firmware-specialist model with in-house extruder development and open-source stewardship positioning.
| Leading Market Players |
|---|
| Creality |
| Snapmaker |
| Bambu Lab |
| Sovol |
| QIDI Tech |
| Elegoo |
| Anycubic |
| Original Prusa |
| Prusa Research |
| Others |
Cost & Logistics Intelligence
EU Machinery Directive CE marking documentation requirements for heated enclosures and pinch point risk assessments are compressing product launch timelines for new entrants lacking notified body relationships, forcing supply chains to absorb compliance costs across high shipment volumes or retreat to unregulated channels.
Pricing Analysis
The bundled hardware-plus-consumables versus unbundled hardware-only split defines pricing architecture across the personal 3D printer landscape. Three-tier pricing structure across premium, standard, and economy levels separates closed-loop motion systems with AI calibration from open-frame filament kits and entry-level resin machines. Certification tier under EU REACH and RoHS frameworks drives price differentiation alongside volume scale and after-sales service bundling. Pricing pressure stems from Shenzhen component cost compression as stepper motor and aluminum extrusion backward integration accelerates. Hobbyist makers exhibit highest price sensitivity, while dental modeling labs tolerate premium positioning for biocompatible resin compatibility.
Supply Chain Analysis
Stepper motor driver supply rests on Guangdong specialty manufacturers, LCD masking systems draw from Pearl River Delta optics clusters, and precision lead screws feed from German and Japanese machine tool suppliers. Raw material dependencies span corn starch for PLA filament, butadiene derivatives for ABS, and photoinitiator chemicals for resin formulations. Single-source vulnerability concentrates in Texas Instruments DLP chip allocations for desktop systems. Distribution runs through direct-to-consumer e-commerce platforms and regional electronics distributors serving maker spaces and educational institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The personal 3D printer market functions as a regulatory compounder where EU REACH substance restrictions on photoinitiators and plasticizers are accelerating material reformulation investments and reshaping competitive positioning among resin formulators.
For Market Incumbents: Extend firmware development capacity through embedded systems engineering partnerships in Boston and Stuttgart clusters to counter talent scarcity constraining real-time motion control R&D expansion. Absorb REACH and RoHS certification costs across Guangdong manufacturing scale to defend against Shenzhen-based assemblers with captive component supply. Prioritize closed-loop motion system patent filings to maintain differentiation as AI-powered calibration becomes table stakes. For New Entrants and Emerging Players: REACH reformulation requirements in Europe open a window for third-party resin suppliers with ECHA-compliant material disclosure sheets to bypass OEM cartridge lock-in and capture dental modeling margin pools. Target India's unreliable grid power and tropical humidity conditions with indigenous thermal management designs cultivated through Bengaluru and Hyderabad incubator partnerships. Lead with curriculum-aligned software stacks and educator certification modules to penetrate K-12 STEM procurement channels in South Korea and Japan. For Investors and Strategic Acquirers: Asymmetric upside sits with firmware-specialist vendors with open-source community stewardship and in-house extruder development capabilities that sustain premium positioning against ecosystem-integrated hardware assemblers. Long-term viability over a multi-year horizon favors European vendors with established notified body relationships and documented CE marking pathways. Watch for ISO/ASTM desktop safety standard adoption as de facto import prerequisites signaling regulatory barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Motion System Development | AI-powered first-layer detection reduces support tickets for calibration-averse casual users. |
| REACH-Compliant Resin Formulation | ECHA substance restrictions force reformulation for European dental modeling market access. |
| Educator Certification Program Launch | Curriculum-aligned software stacks gate K-12 STEM procurement in Seoul and Tokyo districts. |
| Direct-to-Consumer Subscription Model | Channel compression bypasses regional importers for recurring resin purchases in East Asian markets. |
| Backward Integration into Stepper Motors | Guangdong component sourcing scale absorbs multi-jurisdictional safety certification burdens. |
Research Approach
Multiple input streams — primary interviews with hardware engineering leads, regulatory compliance officers, and educational procurement managers; secondary validation through SAMR emission testing documentation, EU Machinery Directive risk assessment filings, and Shenzhen customs trade data; plus bottom-up and top-down triangulation — were reconciled to construct segment-level demand estimates.
Historical shipment data cross-referenced against panel input from resin formulators and filament compounders anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application end-use, material chemistry, and connectivity architecture. CAGRs were derived through trend extrapolation moderated by patent expiration timelines and component cost compression trajectories in the Pearl River Delta.
Revisions become necessary when ISO/ASTM desktop safety standards achieve de facto import prerequisite status, when agricultural commodity volatility disrupts PLA feedstock economics, or when DLP chip supply constraints from Texas Instruments intensify. A small set of named triggers — regulatory standard adoption, feedstock price spikes, and semiconductor allocation shifts — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Europe Industrial 3D Printing Market
3D Printing Technology
4D Printing Market
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
Global Automated 3D Printing Market
3D Printing Technology
Automotive 3D Printing Consumables Market
3D Printing Technology
North America 3D Printing Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
3D Printer Market
3D Printing Technology
Saudi Arabia and Egypt Healthcare 3D Printing Market
3D Printing Technology
Asia-Pacific Industrial 3D Printing Market
3D Printing Technology
Additive Manufacturing Machines Market
3D Printing Technology
Powder Bonding 3D Printing Construction Market
3D Printing Technology
PEEK Filament Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
Hybrid Additive Manufacturing Machine Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market