
 Global Hydraulic Equipment Market | 2026-2036
Global Hydraulic Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulic Equipment Market Intelligence
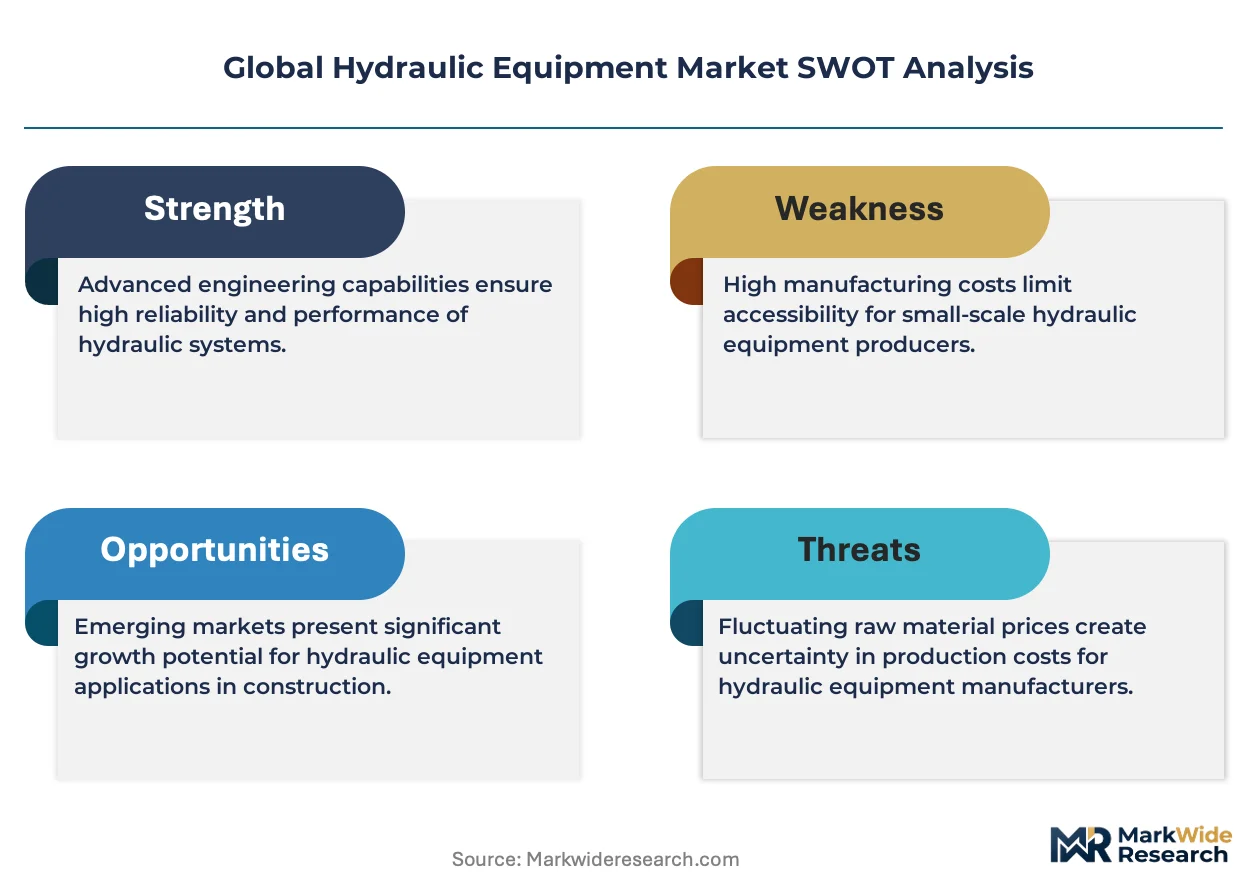
The premium hydraulic tier is consolidating around high-pressure electro-hydraulic systems with integrated condition monitoring, while commodity pumps and valves face price pressure from standardized Asian manufacturing. Bosch Rexroth leverages its digital hydraulic platform to anchor premium positioning in European press applications. Parker Hannifin sustains North American distribution density through its motion and control network. KYB Corporation dominates compact construction equipment supply in Japan and Southeast Asia.
Hydraulic equipment comprises fluid power systems that transmit force through pressurized oil or synthetic media, typically operating at pressures from 3,000 to 10,000 psi to drive linear or rotary actuation in heavy machinery. The primary industrial purpose centers on converting mechanical power into controlled force transmission for load-lifting, pressing, and precision positioning where electric alternatives lack torque density. Pumps and motors represent the mature revenue core with stable replacement cycles, while electro-hydraulic and servo technology segments capture expanding margin pools through energy recovery and position accuracy demands. Cylinders and accumulators grow fastest in offshore wind installation vessels and tidal energy systems requiring corrosion-resistant sealing.
ISO 4406 cleanliness standards and the EU F-Gas Regulation are reshaping hydraulic fluid formulations and seal material specifications, forcing manufacturers to certify biodegradable alternatives and lower-friction compounds. The EPA in the United States enforces spill prevention rules under SPCC guidelines that elevate containment system requirements for industrial hydraulic reservoirs. Stakeholders must monitor how China's MIIT dual carbon goals and Japan's METI energy efficiency benchmarks will recalibrate competitive requirements for power density and leak-free operation.
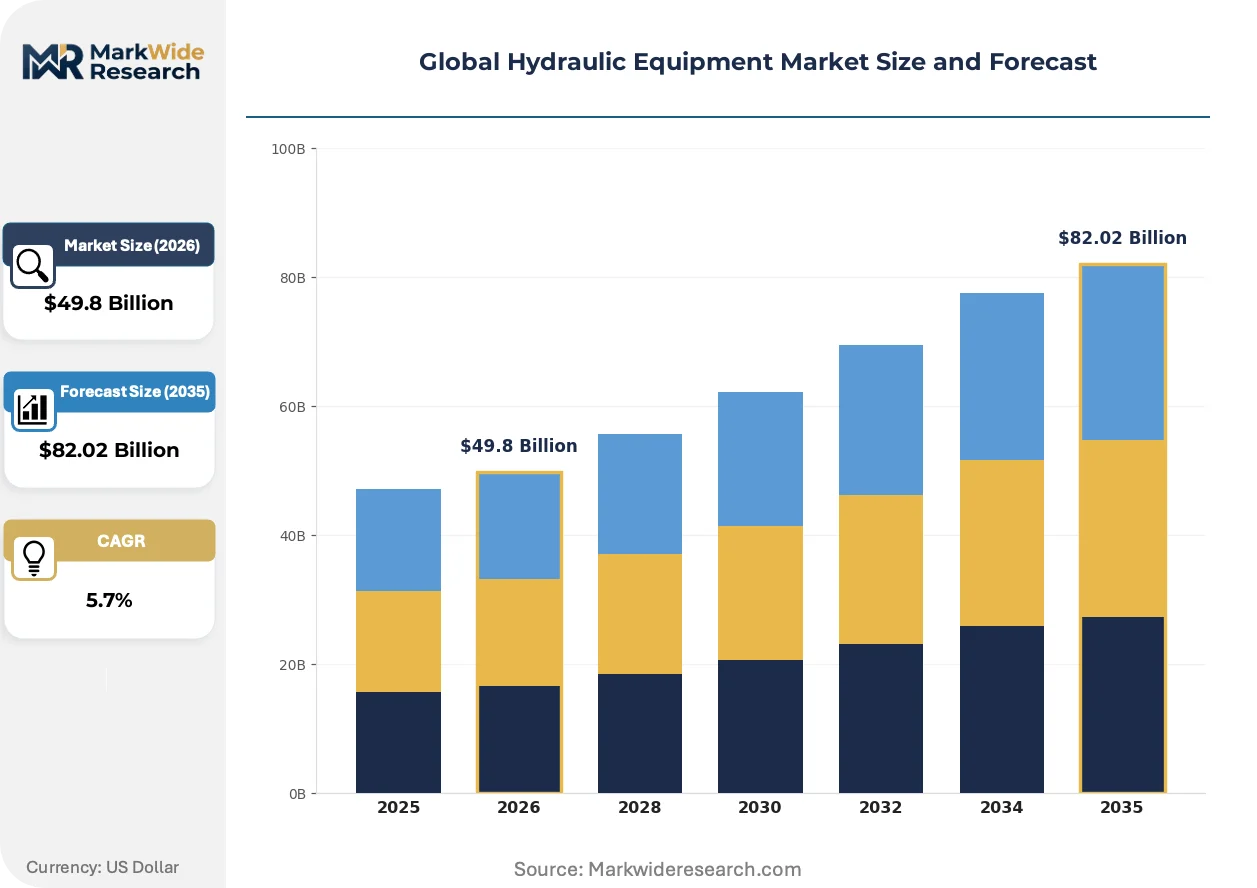
Market Dynamics
Electrification mandates in heavy machinery are compressing demand for traditional hydraulic powertrains while simultaneously expanding the addressable market for high-pressure electro-hydraulic actuation systems with integrated energy recovery.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating R&D investment in CO2-compatible hydraulic fluids and low-global-warming-potential sealing compounds across German and Italian press manufacturers.
- Offshore wind installation:Vessel operators in the North Sea and Baltic Sea are specifying corrosion-resistant hydraulic cylinders with 10,000+ psi ratings for monopile handling and jacket installation.
- China MIIT dual carbon goals:Energy efficiency benchmarks for industrial equipment are forcing domestic OEMs to replace fixed-displacement pumps with variable-speed electro-hydraulic drives in injection molding and die casting.
Market Restraints
- Cast iron and specialty steel input costs:Foundry capacity constraints in India and Brazil are elevating cylinder block and valve body material costs with limited near-term substitution pathways.
- High-pressure seal supply concentration:Fluorocarbon and polyurethane seal manufacturing clusters in Japan and Germany create vulnerability for non-integrated hydraulic component suppliers.
- Direct electromechanical substitution:Linear motor and ball screw systems are capturing load positioning applications below 50 kN where hydraulic torque density advantages diminish.
Strategic Opportunities
- India compact construction equipment:Domestic infrastructure spending and rental fleet expansion are creating demand for cost-optimized hydraulic power units with localized assembly.
- ISO 4406 cleanliness-as-a-service:Fluid condition monitoring and predictive filter replacement contracts are emerging as recurring revenue streams for distributors with IoT-enabled diagnostic capabilities.
- Japan METI energy efficiency incentives:Subsidies for industrial equipment retrofits are opening upgrade markets for servo-proportional valve retrofits in aging automotive press lines.
Industry Challenges
- Electro-hydraulic systems integration:Cross-functional engineering teams must bridge power electronics, embedded controls, and high-pressure fluid mechanics with limited university pipeline output.
- Biodegradable fluid certification timelines:OEM validation cycles for ester-based and water-glycol formulations extend 18-36 months, delaying market entry for alternative chemistry suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulic Equipment Market |
| Market Size in 2026 | $49.8 Billion |
| Market Size in 2035 | $82.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Valves, Cylinders, Motors, Accumulators, Seals Technology: Electro-Hydraulic, Hydrostatic, Pneumatic-Hydraulic, Electro-Mechanical, Proportional, Servo Application: Construction Equipment, Agricultural Machinery, Marine Systems, Material Handling, Aerospace Systems, Energy Sector End User: Original Equipment Manufacturers, Equipment Maintenance Firms, Industrial Plants, Mining Companies, Commercial Vehicle Makers, Offshore Operators |
| Companies Covered | Danfoss, KYB Corporation, Bosch Rexroth, Hydac, HAWE, Parker Hannifin, Kawasaki Heavy Industries, Moog Inc., Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulic Equipment Market Strategic Shifts & Innovations
Digital hydraulic architectures are collapsing the traditional separation between power generation and motion control, enabling kilowatt-scale energy recovery that was technically infeasible with analog valve technology.
Digital displacement pump technology is rewriting energy efficiency benchmarks in excavator and wheel loader applications. Komatsu and Volvo Construction Equipment are piloting systems with independently controlled pistons that eliminate throttling losses at partial load. The technology is compressing fuel consumption differentials between hydraulic and hybrid-electric drivetrains in 20-30 ton machine classes.
The EU F-Gas Regulation and accompanying ECHA restrictions on per- and polyfluoroalkyl substances are forcing seal compound reformulation across European hydraulic supply chains. Manufacturers must qualify hydrogenated nitrile and thermoplastic elastomer alternatives for high-pressure dynamic sealing. German automotive press OEMs are accelerating validation timelines to maintain CE marking compliance for export equipment.
Asset-light procurement models are fragmenting traditional distributor relationships in North American mobile equipment. Fleet managers are unbundling hardware procurement from fluid analysis and remanufacturing services, sourcing components through direct channels while contracting maintenance through specialized fluid power service networks. The pattern is most pronounced in Texas and Alberta oilfield service fleets with high equipment turnover rates.
Global Hydraulic Equipment Market Segmentation
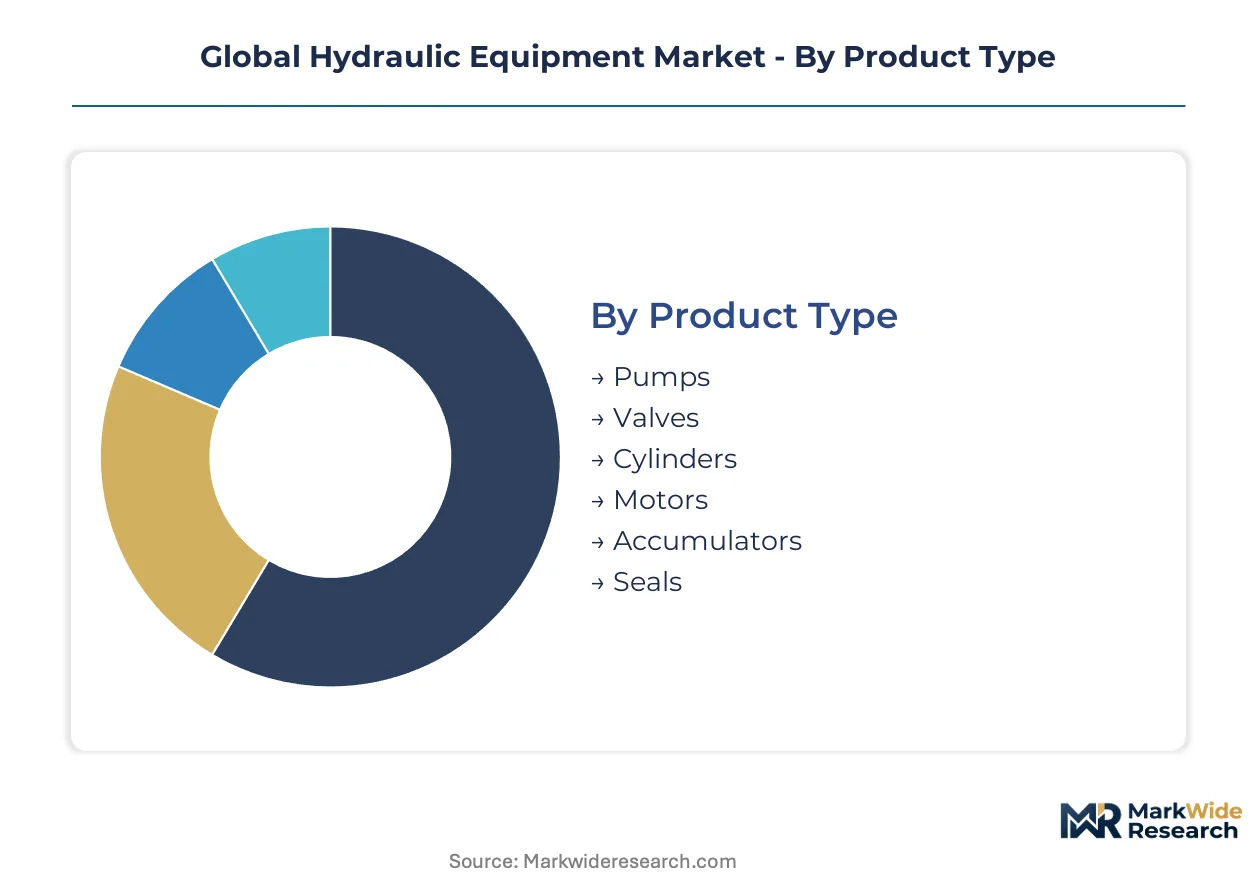
Hydraulic equipment segmentation reveals divergent capital requirements across product categories, with high-pressure component manufacturing demanding foundry and precision machining investments that commodity seal production avoids. Technology tiers separate energy-recovery systems requiring embedded controls integration from conventional hydrostatic drives with mature supply chains. Application segments align with cyclical infrastructure spending patterns that reshape regional demand concentration.
Product Type:
Pumps and motors absorb the heaviest capital intensity through foundry investments in ductile iron casting and precision grinding centers for high-pressure cylinder blocks.
- Pumps:Fixed-displacement gear pumps dominate volume in compact construction equipment, while variable-displacement piston pumps with swashplate control capture premium positioning in German automotive press lines. German and Italian OEMs specify pumps with integrated load-sensing circuits to meet EU F-Gas Regulation energy efficiency benchmarks.
- Valves:Directional control valves with spool-and-sleeve architectures require micron-level machining tolerances that concentrate production in Japanese and German manufacturing clusters. Demand clusters in Chinese injection molding machine retrofits where MIIT dual carbon goals mandate variable-speed drives.
- Cylinders:Welded rod construction for mobile equipment versus honed tube mill-run cylinders for industrial presses.
- Motors:Orbital motors for agricultural machinery versus bent-axis piston motors for marine winch applications.
- Accumulators:Bladder and piston configurations for energy storage in offshore wind installation vessels.
- Seals:Fluorocarbon O-rings and polyurethane wiper seals facing reformulation pressure from ECHA PFAS restrictions.
Most installed capacity flows through pumps and valves. Expansion is steepest in cylinders for offshore wind applications.
Technology:
Technology selection determines margin structure, with electro-hydraulic systems commanding engineering service premiums while proportional valve platforms compete on distributor density.
- Electro-Hydraulic:Systems integrating servo motors with hydraulic pumps enable position-controlled actuation with energy recovery in excavator boom circuits. Komatsu and Volvo Construction Equipment pilots in Japan and Sweden validate fuel consumption compression against hybrid-electric alternatives.
- Hydrostatic:Closed-loop pump-motor combinations for wheel loaders and skid-steer loaders with mature supply chains in US Midwest manufacturing corridors.
- Pneumatic-Hydraulic:Intensifier systems for clamping applications in Brazilian automotive stamping plants.
- Electro-Mechanical:Ball screw and linear motor systems displacing hydraulics below 50 kN force requirements in Japanese electronics assembly.
- Proportional:Valve spools with onboard electronics for open-center mobile equipment circuits.
- Servo:High-response valve technology for Japanese automotive press line retrofits under METI energy efficiency subsidies.
Technology mix shifts toward electro-hydraulic architectures in construction equipment above 20 tons. Servo-proportional retrofits climb fastest in aging industrial press installations.
Application:
Application segmentation tracks infrastructure investment cycles, with construction equipment and marine systems showing inverse correlation to interest rate sensitivity.
- Construction Equipment:Excavators and wheel loaders specify pumps rated to 5,000 psi with load-sensing priority valves. Chinese OEMs expand fleet electrification programs that compress traditional hydraulic powertrain demand while expanding electro-hydraulic actuator requirements.
- Agricultural Machinery:Tractor hydraulic systems prioritize cost-optimized gear pumps with open-center circuits for implement control.
- Marine Systems:Corrosion-resistant cylinders with 10,000+ psi ratings for North Sea and Baltic Sea monopile handling vessels.
- Material Handling:Forklift mast cylinders and steering units with priority valve circuits.
- Aerospace Systems:Flight control actuators with redundant sealing for commercial aviation applications.
- Energy Sector:Hydraulic power units for wellhead control in Texas and Alberta oilfield service fleets.
Construction equipment anchors installed base volume. Marine systems for offshore wind installation gain share fastest.
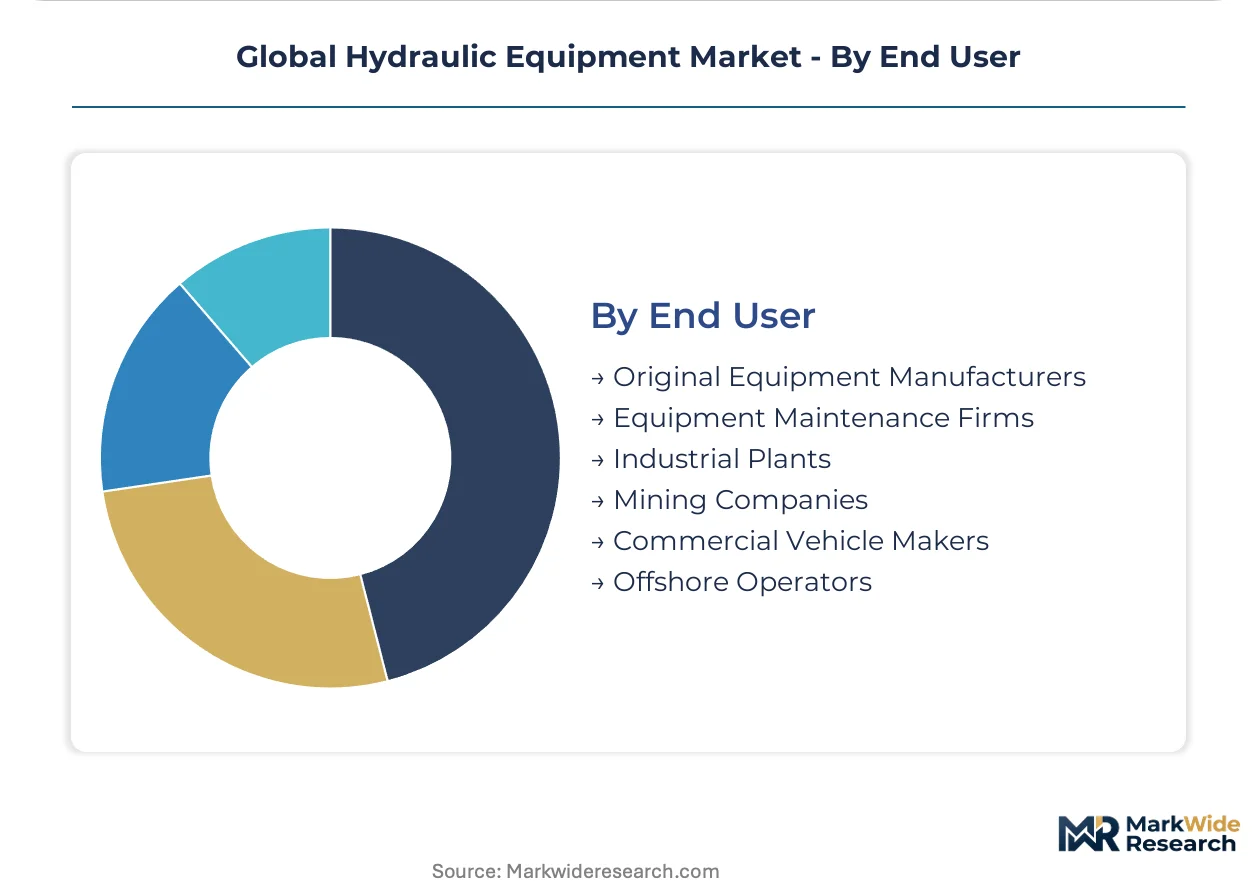
End User:
End user categories separate specification authority from procurement volume, with OEMs driving technical standards while maintenance firms control aftermarket fluid and filter replenishment.
- Original Equipment Manufacturers:Construction and agricultural machinery builders specify integrated hydraulic systems with proprietary control algorithms. Chinese and Indian OEMs localize power unit assembly to meet domestic content requirements.
- Equipment Maintenance Firms:Independent service networks in North America unbundle fluid analysis from component procurement.
- Industrial Plants:Automotive press line operators in Germany and Japan specify servo-proportional retrofits.
- Mining Companies:Haul truck and shovel hydraulic system rebuild programs with extended warranty requirements.
- Commercial Vehicle Makers:Truck-mounted crane and refuse collection hydraulic specifications.
- Offshore Operators:Wind farm installation contractors specifying corrosion-resistant sealing for subsea exposure.
OEM procurement dominates volume flow. Equipment maintenance firms expanding fastest through ISO 4406 cleanliness-as-a-service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates automotive press line demand while China drives construction equipment electrification, yet both markets face tightening fluid cleanliness mandates. Regulatory divergence between the EU F-Gas Regulation and China's MIIT dual carbon goals is fragmenting equipment specifications across manufacturing corridors.
United States
Oilfield service fleets in Texas and Alberta unbundle procurement from maintenance contracts, creating specialized fluid power service networks. EPA spill prevention rules under SPCC guidelines elevate containment requirements for industrial hydraulic reservoirs. Houston anchors energy sector hydraulic power unit demand for wellhead control systems.
Germany
Automotive press OEMs accelerate servo-proportional valve retrofits under METI-aligned efficiency benchmarks imported via supply chain pressure. EU F-Gas Regulation phases down fluorinated greenhouse gases, forcing CO2-compatible fluid R&D across Bavarian and North Rhine-Westphalian manufacturing clusters. Stuttgart press manufacturers validate hydrogenated nitrile seal compounds for CE marking compliance.
China
Construction equipment OEMs expand fleet electrification programs that compress traditional hydraulic powertrain volumes while expanding electro-hydraulic actuator requirements. MIIT dual carbon goals mandate variable-speed drives in injection molding and die casting across Yangtze River Delta industrial zones. Shanghai and Suzhou anchor domestic power unit assembly localization.
Japan
Shipyard automation and compact construction equipment sustain demand for corrosion-resistant cylinders with integrated condition monitoring. METI energy efficiency subsidies open upgrade markets for servo-proportional retrofits in aging automotive press lines. Kobe and Nagoya manufacturing clusters concentrate high-pressure seal production for regional supply security.
India
Domestic infrastructure spending and rental fleet expansion create demand for cost-optimized hydraulic power units with localized assembly. Foundry capacity constraints in Maharashtra and Gujarat elevate cylinder block material costs with limited near-term substitution pathways. Pune and Chennai anchor compact construction equipment supply chains for Southeast Asian export markets.
Global Hydraulic Equipment Market Key Industry Players
Top-tier vendors anchor premium electro-hydraulic systems with integrated energy recovery, while commodity component specialists face margin compression from standardized Asian manufacturing. The vendor base separates into three strategic archetypes: integrated motion-control platforms, high-pressure component specialists, and regional power unit assemblers. Dominant competitive moves include geographic expansion into Indian compact equipment markets and technology licensing for digital displacement pump architectures.
Within the integrated platform tier, Danfoss and Bosch Rexroth occupy positions exemplifying European engineering-centric positioning, while KYB Corporation represents Japanese specialization in compact construction equipment supply. Parker Hannifin anchors North American distribution density through motion and control network infrastructure. These three entities collectively illustrate how geographic origin and organizational structure shape competitive archetype differentiation across premium and volume market segments.
| Leading Market Players |
|---|
| Danfoss |
| KYB Corporation |
| Bosch Rexroth |
| Hydac |
| HAWE |
| Parker Hannifin |
| Kawasaki Heavy Industries |
| Moog Inc. |
| Eaton Corporation |
| Others |
Cost & Logistics Intelligence
Specialty steel and ductile iron casting costs cascade from foundry capacity constraints in India and Brazil through to finished cylinder block pricing tiers, compressing margins for non-integrated valve body suppliers while amplifying premium capture for German and Japanese manufacturers with captive metallurgy operations.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standardized gear pumps and directional valves. Three-tier pricing structure across premium, standard, and economy levels separates Bosch Rexroth's electro-hydraulic platforms from Indian assembled power units. Cost compression in commodity tiers is intensifying because of standardized Asian manufacturing. Fleet managers in Texas oilfield service represent the most price-sensitive buyers, while German automotive press OEMs exhibit the least sensitivity due to energy efficiency compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with fluorocarbon and polyurethane seal manufacturing clusters in Japan and Germany. High-pressure component production concentrates in Germany, Japan, and China, with foundry operations drawing from Indian and Brazilian metallurgical feedstock. The supply chain rests on ductile iron castings, specialty steel bar stock, and precision-ground valve spools as critical inputs. Tariff exposure on Chinese-manufactured pumps creates structural risk for North American distributors. Distribution runs through authorized service networks for premium tiers and direct procurement platforms for commodity replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydraulic equipment market represents a late-cycle quality story where specification authority is migrating toward energy-recovery systems with integrated condition monitoring, compressing addressable margin for commodity component suppliers.
For Market Incumbents: Cement premium positioning through backward integration into high-pressure seal compounds and digital displacement pump intellectual property. Defensive consolidation moves should prioritize acquiring fluid condition monitoring capabilities to anchor recurring revenue streams against direct electromechanical substitution threats in sub-50 kN applications. Channel control through IoT-enabled diagnostic networks offers the strongest defensive lever. For New Entrants and Emerging Players: Independent equipment maintenance firms in North America represent the most penetrable buyer archetype for ISO 4406 cleanliness-as-a-service contracts. White-space targets include cost-optimized hydraulic power unit assembly for India's compact construction equipment rental fleet expansion. A direct go-to-market angle through specialized fluid power service networks bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where electro-hydraulic systems integration capabilities span power electronics, embedded controls, and high-pressure fluid mechanics with limited university pipeline output. Long-term viability over the next decade favors vertically integrated platforms with captive seal production and digital hydraulic R&D. The signal to watch is METI subsidy renewal timelines for Japanese automotive press retrofits as an inflection indicator for servo-proportional valve demand.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Displacement Pump Licensing | Komatsu and Volvo pilots validate fuel consumption compression against hybrid-electric alternatives in 20-30 ton excavators. |
| Biodegradable Fluid Certification Investment | ECHA PFAS restrictions and EU F-Gas Regulation force 18-36 month OEM validation cycles for ester-based formulations. |
| Condition Monitoring Platform Integration | IoT-enabled diagnostic capabilities transform distributor relationships into recurring ISO 4406 cleanliness-as-a-service contracts. |
| Corrosion-Resistant Cylinder Capacity Expansion | North Sea and Baltic Sea offshore wind installation vessels specify 10,000+ psi ratings for monopile handling. |
| Localized Assembly Joint Venture | MIIT dual carbon goals and domestic content requirements in China and India mandate regional power unit production. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged hydraulic systems engineers at construction equipment OEMs, maintenance directors at Texas and Alberta oilfield service fleets, procurement leads at German automotive press manufacturers, aftermarket service heads at North American fluid power distributors, and plant engineers at Chinese injection molding operations. Secondary validation drew from SEC filings of listed component suppliers, customs data on hydraulic pump and valve trade flows, ISO 4406 cleanliness standard documentation, and EU F-Gas Regulation implementation reports. Bottom-up equipment installation tracking and top-down industrial machinery production estimates were cross-referenced for triangulation.
Segment-weighting across product type, technology tier, application vertical, and end-user category anchored the analytical framework over the projection horizon. Modeled dimensions included fixed versus variable displacement architectures, electro-hydraulic versus conventional hydrostatic systems, construction equipment versus marine versus industrial press applications, and OEM versus aftermarket procurement channels. CAGRs were derived from installed base turnover analysis and replacement cycle compression in electrifying equipment segments. Energy efficiency benchmark trajectories under China's MIIT dual carbon goals and Japan's METI incentives informed technology mix assumptions.
Underlying measurement precision varies by segment; electro-hydraulic and servo-proportional categories carry tighter precision than commodity pump and valve volumes due to concentrated supplier disclosure. Forecasts reflect documented assumptions regarding electrification penetration rates, regulatory phase-in timelines, and foundry capacity expansion in India and Brazil. Specific risk factors that could revise projections include faster-than-anticipated direct electromechanical substitution below 50 kN, accelerated EU F-Gas Regulation enforcement, and supply disruption in Japanese fluorocarbon seal production. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Material Handling Integration Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Helical Gear Market
Material Handling Equipment
Global Linear Guide Market
Material Handling Equipment
Heavy Loader Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
Rail Mounted Gantry Crane Market
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Industrial Piggable Wye Fitting Market
Material Handling Equipment
Conveyor Scales Market