
 Telehandler Market | 2026-2036
Telehandler Market Size, Share, and Industry Trends Forecast 2026-2036
Telehandler Market Analysis
EPA Tier 4 Final emission standards for off-road diesel engines is decoupling legacy equipment from new fleet procurement across North American construction and agriculture sectors. JCB leverages its British manufacturing base to supply EPA-certified diesel telehandlers with integrated after-treatment systems. Caterpillar anchors its position through captive engine production and dealer network density across the United States and Canada. Manitou Group competes via specialization in compact telehandler architectures optimized for confined European and North American job sites.
A telehandler is a mobile lifting machine combining telescopic boom extension with forklift-style load carriage, typically offering reach heights from 6 to 20 meters and load capacities spanning 2.5 to 25 metric tons; its primary purpose centers on material placement and elevated work platform support across uneven terrain. Rough terrain telehandlers dominate unit volumes in construction and mining applications where all-wheel drive and oscillating chassis designs prove essential. Electric telehandler technology leads R&D allocation as rental services and urban construction sites face escalating noise ordinances and indoor emission restrictions. Diesel technology sustains margin pools in agriculture and remote mining operations where charging infrastructure remains absent.
FAA regulations governing airport ground support equipment influence telehandler design specifications for material handling near active runways in the United States. EPA Tier 4 Final and OSHA crane operator certification requirements jointly shape engine architecture and operator training protocols across domestic fleets. Stakeholders must monitor battery-electric range performance and autonomous load-sensing integration as these capabilities determine competitive differentiation in rental fleet procurement cycles.
Market Dynamics
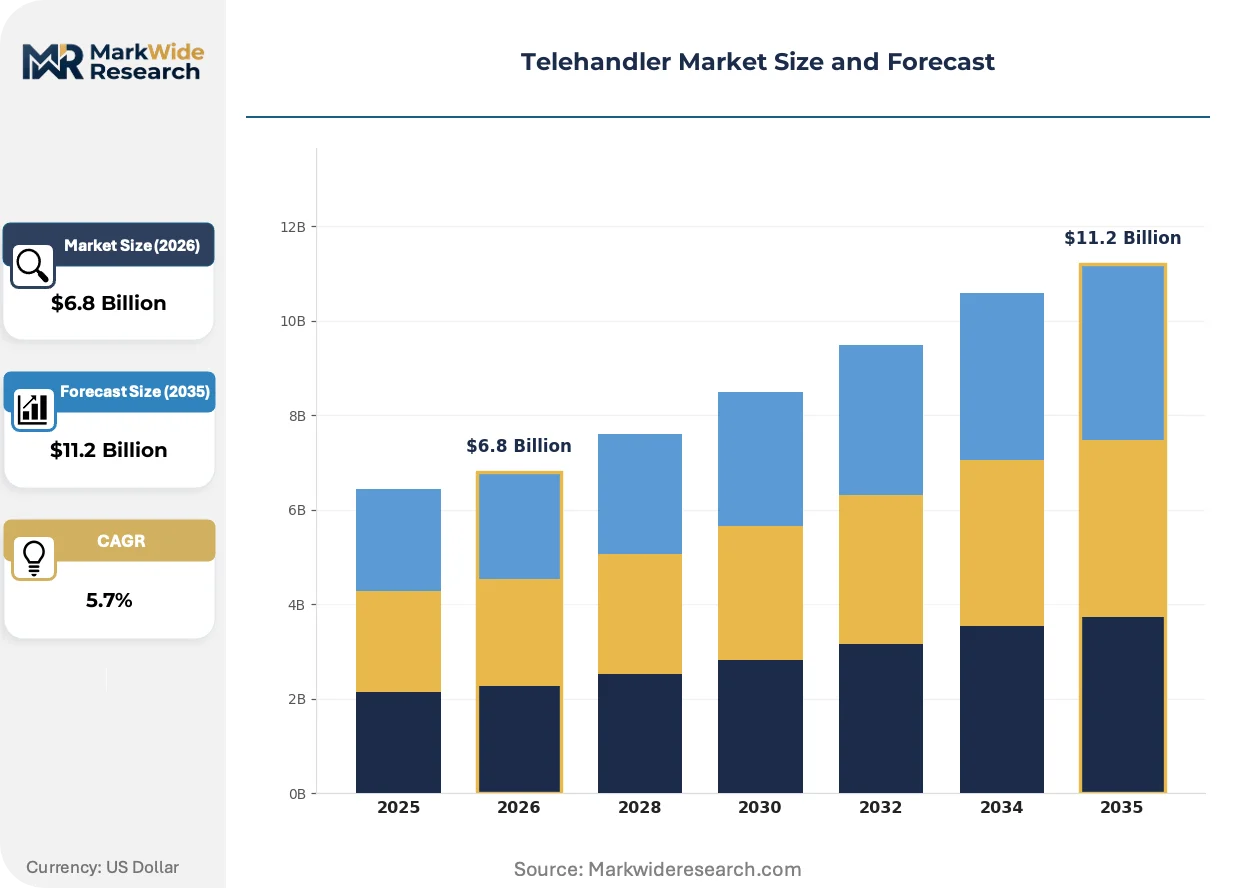
EPA Tier 4 Final emission standards are forcing rapid fleet turnover in North American construction and agriculture, decoupling legacy diesel telehandlers from new procurement cycles as rental operators face compliance deadlines and total cost of ownership recalculations.
Growth Catalysts
- Infrastructure Investment and Jobs Act disbursements:United States federal highway and bridge allocations sustain equipment utilization rates across rental fleets and contractor yards, sustaining replacement demand for rough-terrain material handlers.
- Airport ground support modernization:FAA regulations governing active runway proximity equipment specifications create specialized procurement channels for telehandlers with enhanced visibility and stability systems.
- Electric telehandler R&D acceleration:Battery-electric architectures address indoor emission restrictions and urban noise ordinances, opening rental fleet deployment in enclosed logistics facilities and metropolitan construction sites.
Market Restraints
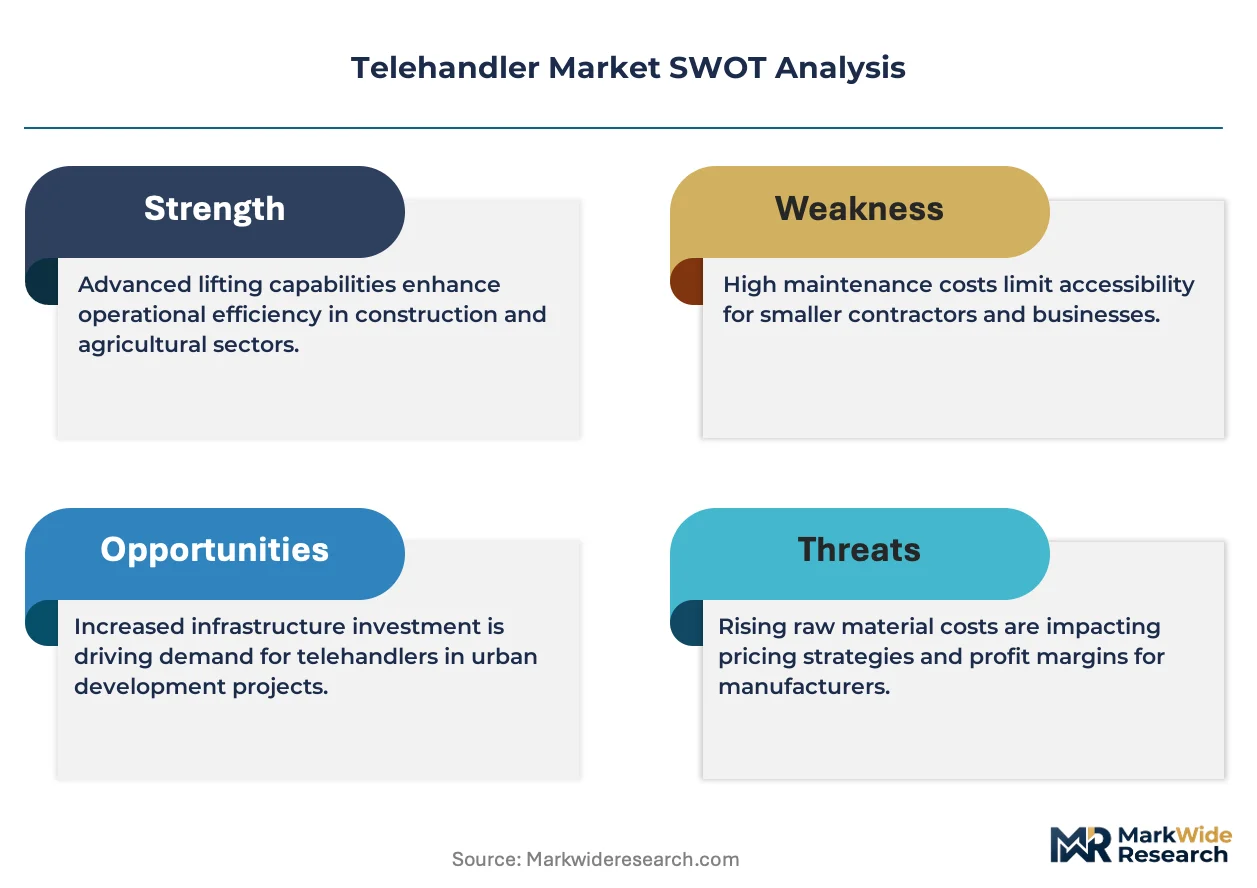
- Diesel after-treatment cost inflation:Selective catalytic reduction and diesel particulate filter integration adds fifteen to twenty-five percent to base machine cost, compressing margin pools for mid-capacity models.
- Steel and hydraulic component supply concentration:Forged boom sections and high-pressure cylinder supply chains concentrate in East Asian foundries, exposing North American and European OEMs to input volatility and extended lead times.
- Electric range limitations in remote applications:Battery energy density constraints exclude electric telehandlers from agriculture and mining operations where charging infrastructure remains absent across vast operational radii.
Strategic Opportunities
- Autonomous load-sensing integration:Machine learning-enabled stability control and automated boom positioning converge with telematics platforms to differentiate rental fleet procurement decisions.
- OSHA crane operator certification alignment:Telehandler-specific training protocols and certification pathways create service revenue streams for equipment distributors and rental houses.
- Compact architecture specialization:Confined urban job sites and European regulatory weight restrictions favor sub-3.5-ton compact telehandler development for residential construction and facility maintenance.
Industry Challenges
- Skilled operator pipeline constraints:OSHA certification requirements and aging workforce demographics create recruitment friction for rental fleet operators and construction contractors.
- Legacy fleet integration complexity:Telematics platform standardization lags across mixed-vendor rental yards, complicating unified fleet management and predictive maintenance deployment.
- Emission compliance timeline compression:EPA enforcement windows and state-level diesel equipment bans in California and New York force accelerated depreciation schedules and residual value uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telehandler Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Telehandlers, Industrial Telehandlers, High-Capacity Telehandlers, Rough Terrain Telehandlers End User: Agriculture, Construction, Mining, Rental Services Application: Material Handling, Lifting Operations, Site Maintenance, Loading Technology: Electric, Diesel, Hybrid, Autonomous |
| Companies Covered | Liebherr, Terex Corporation, Caterpillar, CNH Industrial, Bobcat Company, JCB, Merlo, XCMG Group, Manitou Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telehandler Market Emerging Trajectories
Battery-electric powertrains, autonomous load management, and telematics-enabled predictive maintenance are compressing traditional equipment lifecycle assumptions and reshaping how rental fleets and contractors evaluate total cost of ownership.
Electrification is consolidating competitive positioning in urban construction and indoor logistics applications. Lithium-ion battery packs with thermal management systems now deliver eight-hour operational cycles for mid-capacity telehandlers. Rental services in noise-restricted metropolitan zones adopt electric units at pace, compressing diesel dominance in sub-4-ton categories and forcing engine suppliers to defend position in agriculture and mining.
OSHA crane operator certification requirements are reshaping training protocols and equipment specification across domestic fleets. The standard mandates documented competency verification for telehandler operators in construction applications, creating compliance infrastructure costs for rental houses. United States contractors respond by bundling certified operator services with equipment leases, shifting procurement evaluation toward total service reliability rather than unit economics alone.
Telematics unbundling is fragmenting traditional after-sales service relationships. Equipment owners now procure predictive maintenance analytics and remote diagnostics from third-party software vendors rather than captive dealer networks. This pattern concentrates in large rental fleet operators with in-house technical capabilities, compressing margin pools for traditional parts-and-service departments across the United States and Canada.
Telehandler Market Segmentation
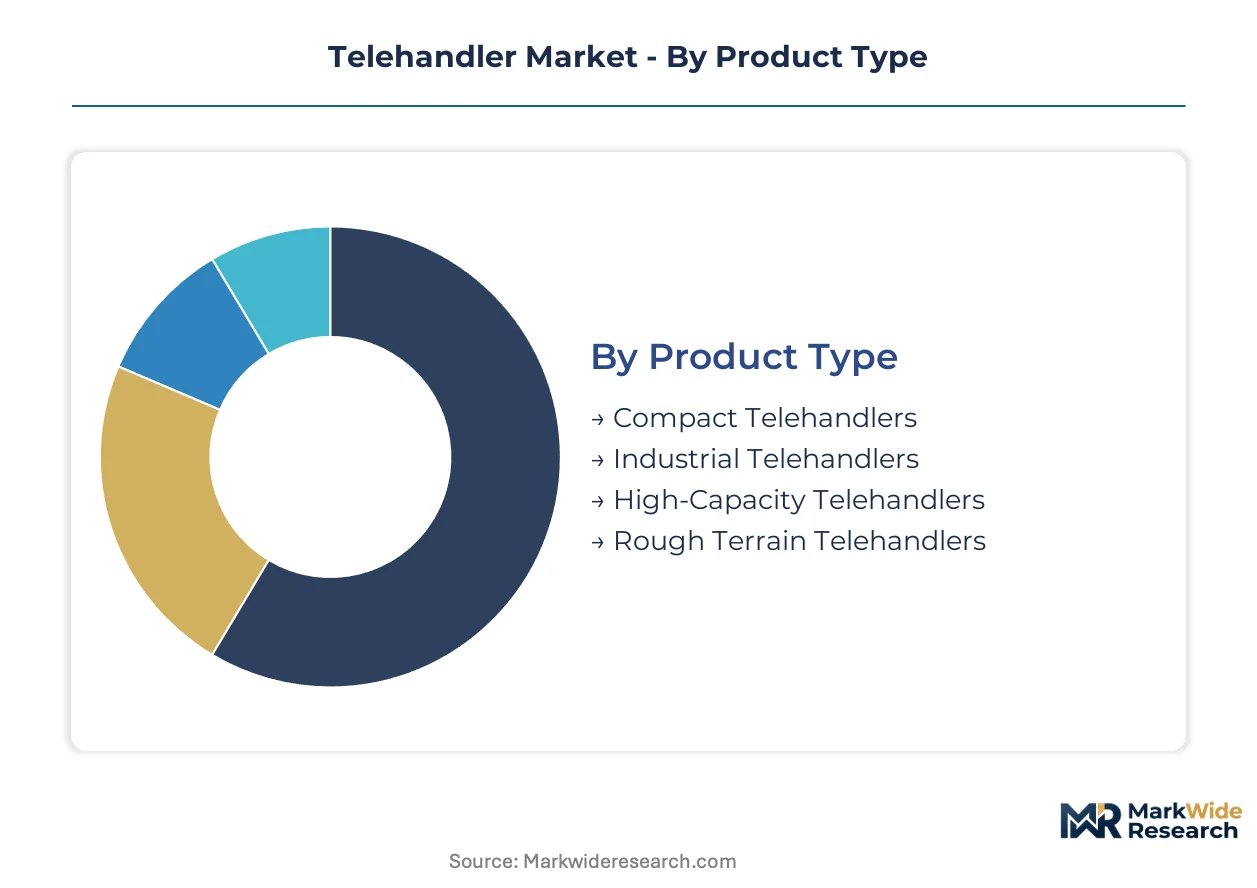
Telehandler procurement decisions diverge sharply between standalone rental fleet deployment and integrated contractor operations. Each segmentation dimension reveals distinct performance requirements, compliance burdens, and total cost of ownership calculations that reshape competitive positioning across equipment categories.
Product Type:
Integration depth varies substantially across product architectures, with compact units embedding into mixed-equipment yards while high-capacity models operate as standalone fleet centerpieces.
- Rough Terrain Telehandlers:All-wheel drive and oscillating chassis designs dominate construction and mining applications where uneven ground conditions demand traction stability. United States infrastructure contractors concentrate procurement in this category as EPA Tier 4 Final deadlines force fleet turnover. Diesel after-treatment integration adds cost but sustains operational range in remote job sites lacking charging infrastructure.
- Compact Telehandlers:Sub-3.5-ton architectures optimize for confined European and North American residential construction zones. Manitou Group specialization in this category addresses urban weight restrictions and indoor emission protocols. Rental services in metropolitan United States markets deploy these units for facility maintenance and restricted-access building sites.
- Industrial Telehandlers:Standardized boom geometries serve manufacturing and logistics facilities with predictable load cycles.
- High-Capacity Telehandlers:Extended reach and heavy-lift specifications anchor mining and heavy civil projects.
Rough terrain telehandlers lead volumes today; compact telehandlers are gaining share fastest.
End User:
Customer archetypes span cost-tier stratification, with rental services absorbing technology risk while mining operators prioritize durability over capital efficiency.
- Construction:General contractors and specialty trades drive replacement demand through utilization-based depreciation schedules. United States federal highway disbursements sustain equipment utilization rates across contractor yards. OSHA crane operator certification requirements add compliance infrastructure costs that favor bundled operator-equipment leases.
- Rental Services:Fleet operators aggregate demand across fragmented contractor bases and absorb technology transition risk. Electric telehandler adoption concentrates in this channel as rental houses respond to urban noise ordinances and indoor emission restrictions. Telematics unbundling fragments traditional after-sales relationships toward third-party predictive maintenance platforms.
- Agriculture:Seasonal utilization patterns and remote operational radii sustain diesel dominance despite after-treatment cost inflation.
- Mining:Harsh duty cycles and absent charging infrastructure exclude electrification from viable procurement options.
Construction leads volumes today; rental services are expanding most quickly.
Application:
Volume concentration tracks material throughput intensity, with loading operations commanding dedicated fleet allocation while site maintenance blends telehandlers into mixed-equipment deployments.
- Material Handling:Palletized load placement and elevated work platform support constitute core telehandler functionality across construction and logistics. FAA regulations governing airport ground support equipment create specialized procurement channels with enhanced visibility specifications. Battery-electric architectures penetrate this application fastest given predictable duty cycles and indoor operational prevalence.
- Lifting Operations:Extended reach applications demand stability control systems and documented operator competency under OSHA protocols. United States contractors face certification alignment costs that shift procurement evaluation toward total service reliability. Autonomous load-sensing integration targets this application for differentiation.
- Loading:Repetitive cycle operations in agriculture and mining sustain diesel margin pools.
- Site Maintenance:Intermittent utilization patterns favor rental fleet access over ownership.
Material handling leads volumes today; lifting operations show steepest expansion trajectory.
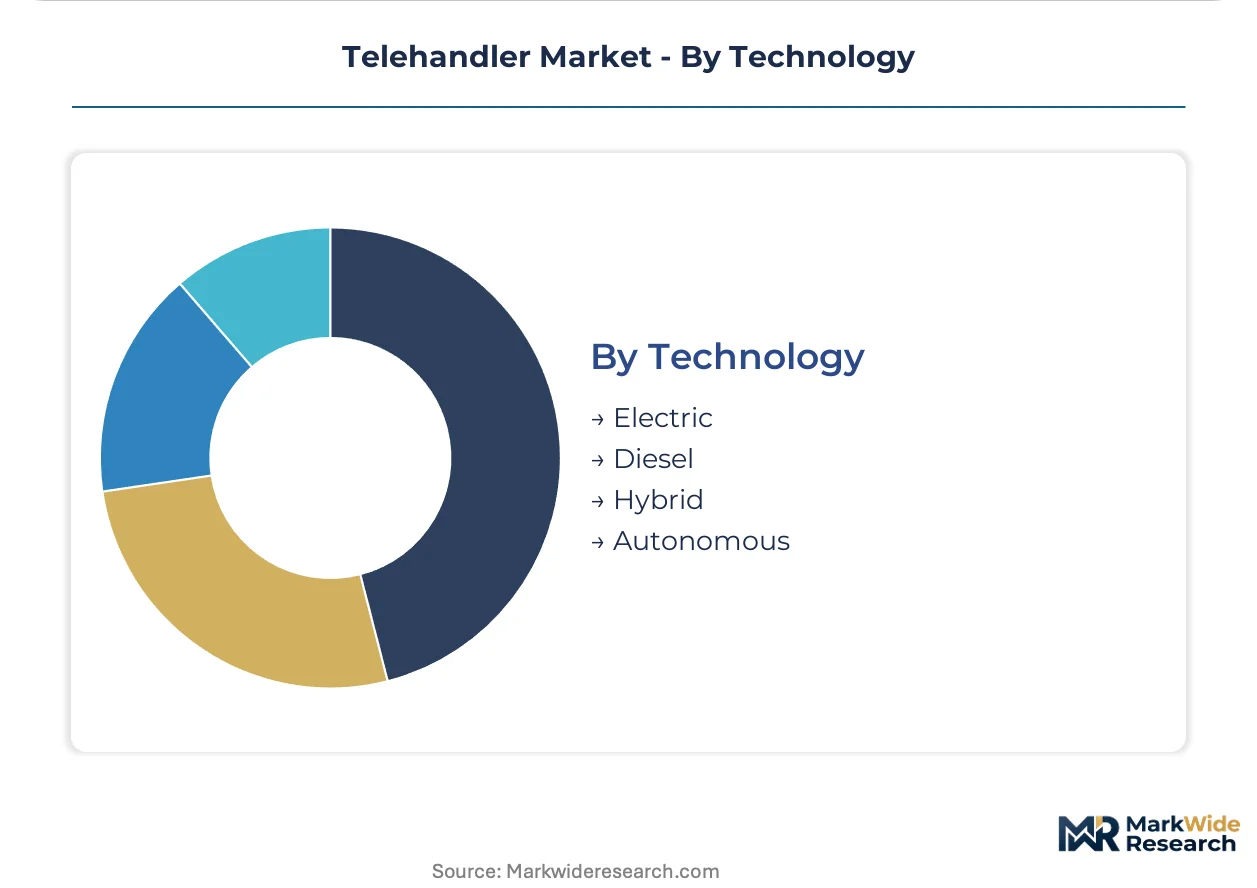
Technology:
Maturity gradients separate proven diesel architectures from emerging electric and autonomous categories, with hybrid systems occupying transitional positioning.
- Diesel:EPA Tier 4 Final certified engines with selective catalytic reduction and particulate filtration sustain agriculture and mining applications. Caterpillar captive engine production anchors supply security for North American fleets. After-treatment integration adds fifteen to twenty-five percent to base machine cost, compressing mid-capacity margins.
- Electric:Lithium-ion battery packs with thermal management deliver eight-hour operational cycles for mid-capacity urban construction. JCB leverages British manufacturing to supply emission-compliant architectures addressing indoor restrictions. Range limitations exclude this technology from remote operational radii.
- Hybrid:Dual-power architectures attempt bridge positioning between compliance and range requirements.
- Autonomous:Machine learning-enabled stability control and automated boom positioning converge with telematics for fleet differentiation.
Diesel leads volumes today; electric is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled equipment operators and certified technicians concentrate in construction corridors where infrastructure spending drives fleet utilization. Their geographic clustering shapes regional procurement patterns and rental service density across mature and emerging markets.
United States
Federal highway disbursements and residential building permits sustain telehandler utilization across contractor yards and rental fleets. EPA Tier 4 Final emission deadlines force diesel fleet turnover in Texas, Florida, and California construction markets. Dallas-Fort Worth anchors Sun Belt equipment distribution with major rental houses expanding electric unit trials for urban noise compliance.
Germany
Compact telehandler demand concentrates in residential construction and facility maintenance across Bavaria and Baden-Württemberg. REACH chemical regulations and EU machinery directives shape after-treatment system specifications for diesel units. Stuttgart industrial corridor hosts specialized component suppliers serving Manitou Group and Merlo assembly operations.
China
Infrastructure investment in western provinces and Belt-and-Road construction sites drives rough-terrain unit procurement. MIIT emission standards and GB certification requirements govern domestic manufacturing quality. XCMG Group anchors production in Xuzhou with supply chain linkages to Yangtze River Delta steel and hydraulic component foundries.
United Kingdom
Agricultural seasonal patterns and construction rental demand sustain mixed diesel-electric fleet deployment. JCB leverages Staffordshire manufacturing base for EPA-certified export production targeting North American compliance windows. Midlands logistics corridor concentrates equipment refurbishment and aftermarket parts distribution for European fleet operators.
India
Urban metro construction and rural agricultural mechanization expand addressable demand for sub-5-ton capacity units. BIS certification and state-level construction safety codes create compliance layering for imported and domestically assembled equipment. Maharashtra industrial belt around Pune hosts emerging fabrication capacity serving rental fleet operators in Mumbai and Delhi-NCR corridors.
Telehandler Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across telehandler manufacturing, with integrated engine foundries and captive boom fabrication anchoring cost structures for volume leaders. The vendor base stratifies into three tiers: full-line construction equipment conglomerates with captive powertrain production, specialized telehandler pure-plays optimizing compact architectures, and regional fabricators serving price-sensitive emerging markets. Consolidation pressure concentrates in mid-capacity segments where after-treatment cost inflation compresses margin pools. Dominant competitive moves include backward integration into hydraulic component supply and geographic expansion through distributor network density.
Within the full-line equipment tier, Caterpillar anchors North American positioning through captive engine production and dealer infrastructure. JCB exemplifies specialized telehandler architecture optimization with British manufacturing serving EPA compliance requirements. XCMG Group occupies a position among scale-driven Asian fabricators addressing domestic infrastructure demand and export price competition. Manitou Group represents compact specialization targeting European weight restrictions and confined job site requirements.
| Leading Market Players |
|---|
| Liebherr |
| Terex Corporation |
| Caterpillar |
| CNH Industrial |
| Bobcat Company |
| JCB |
| Merlo |
| XCMG Group |
| Manitou Group |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists anchor European telehandler manufacturing, consolidating component sourcing discipline while defending pricing power through captive boom fabrication and long-term rental service contracts across North American and European markets.
Pricing Analysis
Bundled operator-equipment leases dominate United States procurement, while unbundled machine-only transactions prevail in European agriculture. Three-tier pricing structure across premium EPA Tier 4 Final-certified, standard diesel, and economy refurbished units separates OEMs from independent rebuilders. Cost compression in mid-capacity diesel models intensifies because selective catalytic integration adds base machine expense. Rental services exhibit highest price sensitivity; mining operators demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth, Stuttgart, and Xuzhou coordinate hub-and-spoke patterns for North American, European, and Asian demand clusters respectively. Forged boom sections and high-pressure hydraulic cylinders draw from Yangtze River Delta and Ruhr Valley foundries. Single-source vulnerability concentrates in East Asian cylinder suppliers. Distribution runs through captive dealer networks for Caterpillar and JCB, while independent distributors serve compact specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The telehandler market reads as a late-cycle quality story, with fleet operators prioritizing EPA-certified machines and telematics-enabled predictive maintenance over base-unit economics.
For Market Incumbents: Extend captive engine production and dealer network density to defend against electric specialist entrants. Backward integration into hydraulic component supply reduces Yangtze River Delta exposure. Prioritize autonomous load-sensing R&D to differentiate rental procurement decisions. For New Entrants and Emerging Players: Enter via electric compact architectures targeting metropolitan United States noise ordinances and indoor logistics facilities. The most penetrable segment sits in sub-3.5-ton urban construction units. Pursue telematics platform partnerships with third-party predictive maintenance vendors rather than building captive service infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialists with regional manufacturing bases and EPA certification pathways. Long-term viability hinges on electrification transition execution and software-defined service revenue capture. Watch battery-electric range performance improvements as the inflection signal for agriculture and mining penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Components | Reduces Yangtze River Delta supply concentration for North American and European OEMs. |
| Electric Architecture Development | Addresses EPA Tier 4 Final compliance costs and urban noise ordinance restrictions. |
| Telematics Platform Partnership | Enables predictive maintenance revenue streams independent of captive dealer networks. |
| OSHA Certification Alignment | Creates service revenue through bundled operator-equipment lease offerings. |
| Compact Product Line Expansion | Captures European weight restrictions and confined North American residential job sites. |
Methodological Framework
Multiple input streams — fleet operator interviews, OEM procurement director discussions, and rental house maintenance head consultations — were reconciled against customs filings, EPA certification databases, and construction equipment registration data. Bottom-up unit shipment estimates from manufacturer disclosures were triangulated with top-down infrastructure spending allocations and utilization rate assumptions.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, end-user archetype, application intensity, and technology maturity tier. CAGRs were derived from equipment replacement cycle analysis and emission compliance deadline clustering. Forecast inputs incorporated diesel after-treatment cost trajectories and lithium-ion battery energy density improvement curves.
Inputs from rental fleet operators and OEM production planners were available through the study window; gaps in autonomous system deployment timelines introduce uncertainty bands around technology transition assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Forklift Tire Market
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
Container Handler Market
Material Handling Equipment
Spring Shackles Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
Truck Mounted Cranes Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
Roll Handling Machine Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Industrial Belt Drives Market