
 Helical Gear Market | 2026-2036
Helical Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Helical Gear Market Analytics
AGMA 2000 precision-grade specifications is unwinding across the helical gear supply base as end-users prioritize noise reduction and load-bearing efficiency. Siemens leverages extensive in-house metallurgy R&D to sustain leadership in high-speed industrial gearbox applications. SEW-EURODRIVE anchors its competitive position through deep vertical integration from foundry operations to finished drive assemblies. Bosch Rexroth differentiates via hydraulic-electric hybrid systems that incorporate precision helical stages for construction and mobile machinery.
A helical gear is a cylindrical gear with teeth cut at an angle to the axis of rotation, typically featuring helix angles between 15° and 30° and requiring axial thrust compensation through bearings or herringbone configurations; its primary purpose is to transmit power between parallel or crossed shafts with smoother, quieter engagement than spur gears. Precision and high-speed product types command the strongest margin pools as aerospace and automotive OEMs specify tighter tolerances for noise-critical applications. Industrial machinery and construction applications represent substantial volume bases where double helical configurations address heavy-load reversing-duty cycles. The aftermarket provider channel competes on availability and reverse-engineering capability rather than original specification control.
The EPA enforces noise and emissions standards that shape gear system design for construction and mobile equipment sold in the United States. ISO 6336 and AGMA standards govern load capacity calculations and material ratings that determine market access for premium-tier suppliers. The EU Green Deal's industrial decarbonization requirements are pressuring foundry energy intensity and lubricant chemistry across European gear manufacturing. Stakeholders must monitor how additive manufacturing qualification standards evolve to decide when near-net-shape helical gear production displaces conventional hobbing economics.
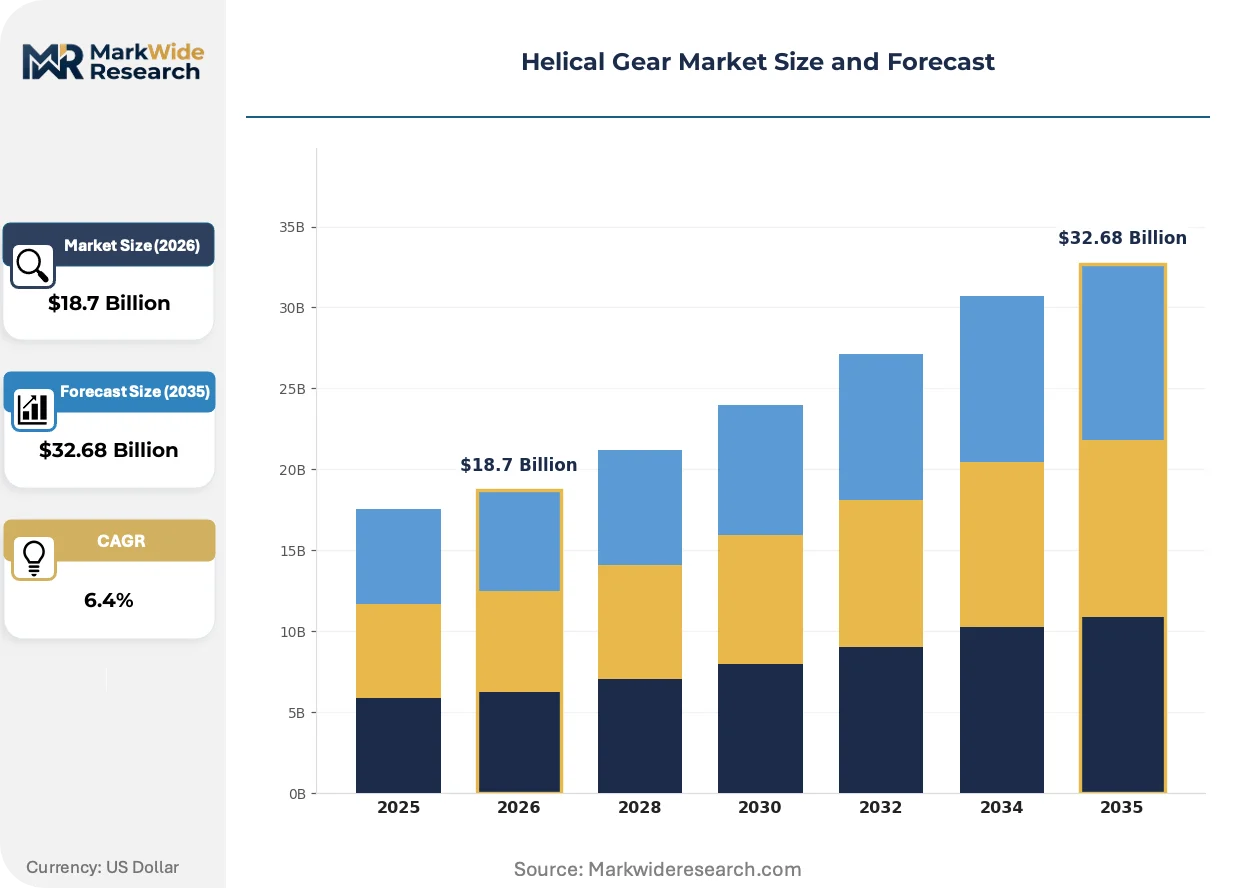
Market Dynamics
Helical gear manufacturing is contending with the collision of EU Green Deal decarbonization mandates and the metallurgical precision required by electric vehicle powertrains, forcing foundries to reconfigure energy-intensive heat-treatment workflows while maintaining AGMA 2000-grade tolerances.
Growth Catalysts
- EU Green Deal industrial decarbonization:Foundry energy intensity regulations are accelerating capital deployment into electric arc furnace retrofits and hydrogen-fired heat treatment, tightening supply of premium-grade helical gears for automotive OEMs.
- Additive manufacturing qualification:Near-net-shape powder bed fusion is advancing through ISO/ASTM 52900 certification pathways, enabling complex double-helical geometries without conventional hobbing scrap rates.
- Electric vehicle powertrain specifications:Automakers specify 15°–25° helix angles for multi-speed reduction gearboxes to achieve NVH targets below 35 decibels at highway speeds.
Market Restraints
- Specialized alloy supply concentration:Vacuum-arc-remelted 9310 steel and Pyrowear 53 sourcing clusters in Austrian and Swedish specialty mills create single-point vulnerability for aerospace-grade helical gear production.
- ISO 6336 calculation complexity:Load capacity verification under combined bending-torsion-contact stress regimes extends engineering validation cycles by 40–60 percent for custom gearboxes.
- Polymer composite substitution:High-performance PEEK and carbon-fiber-reinforced thermoplastics are capturing light-load motion transmission in medical and food-processing equipment.
Strategic Opportunities
- India PLI scheme for automotive components:Domestic gear manufacturing incentives are attracting precision machining investments to serve Tata Motors and Mahindra electric vehicle programs.
- Wind turbine drivetrain refurbishment:2–3 MW gearbox rebuild cycles create aftermarket demand for reverse-engineered helical gear sets with 20-year design life specifications.
- AI-assisted tooth contact pattern optimization:Machine learning convergence with multi-body dynamics simulation is compressing prototype validation from months to weeks for custom industrial gearboxes.
Industry Challenges
- Metallurgical heat-treatment skill scarcity:Vacuum carburizing and nitriding expertise is retiring faster than vocational programs in Germany and Japan can replenish qualified furnace operators.
- AGMA 2000-A88 certification timeline:Third-party precision-grade verification for new production lines requires 18–24 months of sustained statistical process control documentation before OEM qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helical Gear Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Helical, Double Helical, High-Speed, Precision Application: Automotive, Aerospace, Construction, Industrial Machinery End User: OEMs, Aftermarket Providers, Distributors, Tier-1 Suppliers Installation Type: Horizontal, Vertical, Integrated, Modular |
| Companies Covered | Nord Drivesystems, Siemens, SEW-EURODRIVE, Bosch Rexroth, ZF Friedrichshafen, Flender, Bonfiglioli, WEG, Sumitomo Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helical Gear Market Evolving Landscape
Additive manufacturing workflows, regulatory carbon accounting, and procurement model fragmentation are simultaneously rewriting helical gear production economics and supplier qualification protocols.
Direct metal laser sintering of 18Ni300 maraging steel is supplanting subtractive hobbing for prototype and low-volume helical gear production, with aerospace tier-1 suppliers adopting it for 50–500 unit annual runs where lead time compression outweighs powder cost premiums, compressing traditional gear job shop margins in high-complexity segments.
REACH Annex XIV authorization requirements for hexavalent chromium plating are forcing gear manufacturers toward trivalent chromium and thin dense chrome alternatives, with German automotive suppliers bearing the highest compliance burden as KBA type-approval documentation must demonstrate equivalent wear resistance for transmission synchronizer hubs.
Buyers are fragmenting procurement between captive in-house gear production for proprietary drivetrains and spot-market sourcing for standard industrial sizes, with Japanese construction equipment OEMs most visibly unbundling precision helical stage manufacturing from final gearbox assembly to preserve design secrecy while outsourcing commodity gearing to Taiwanese specialists.
Helical Gear Market Segmentation
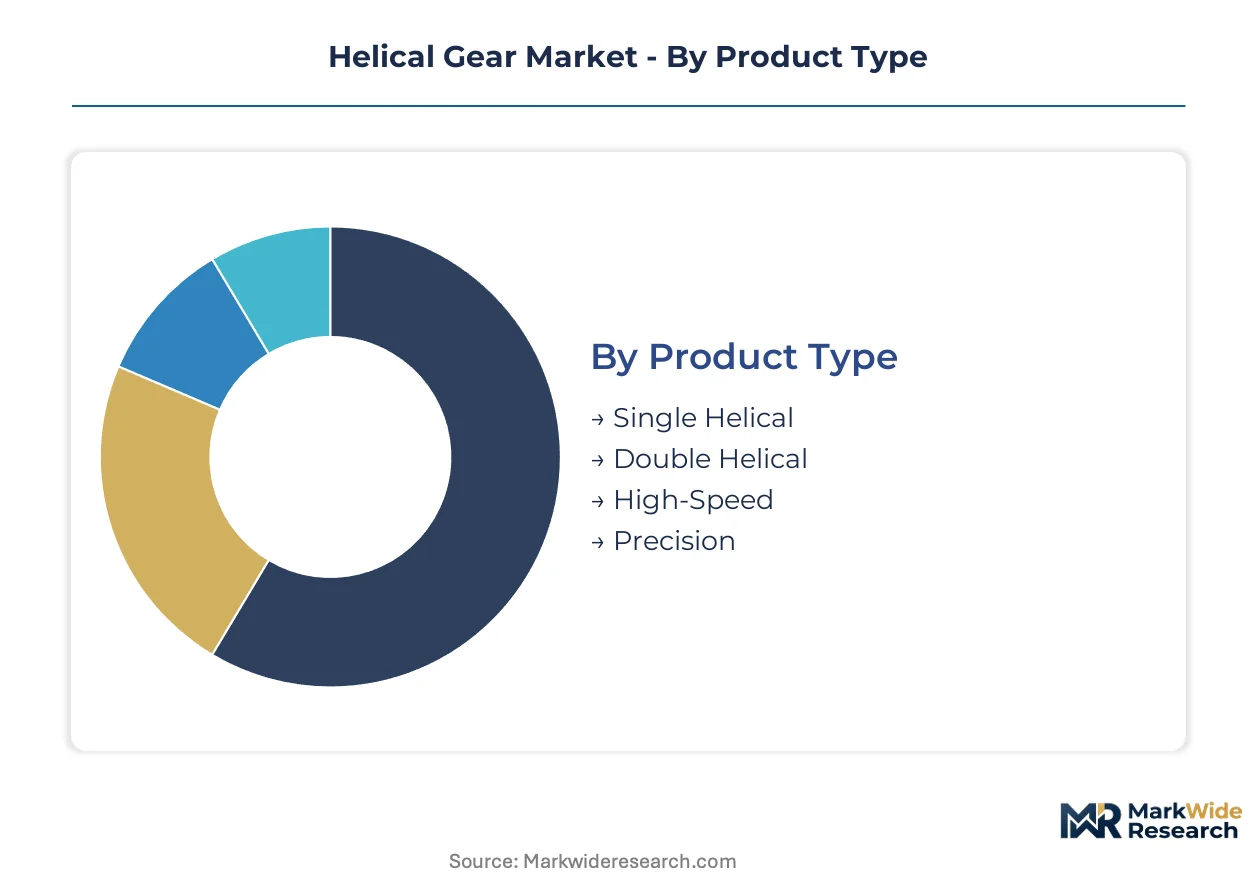
Helical gear procurement patterns fragment sharply across precision grades and installation configurations, with AGMA 2000-A88 certification tiers and EU Green Deal carbon-accounting requirements forcing buyers to segment suppliers by metallurgical capability rather than price alone. Each category below reveals where specification control concentrates and where commodity substitution threatens margin pools.
Product Type:
REACH Annex XIV authorization timelines for hexavalent chromium plating differentiate premium-grade suppliers from commodity producers, with trivalent chromium conversion costs pushing precision segments toward additive manufacturing workarounds.
- Single Helical:Features teeth cut at a continuous helix angle (typically 15°–30°) requiring thrust bearings to counteract axial loads; demand concentrates in German automotive powertrain manufacturing where NVH regulations under KBA type-approval mandate sub-35 decibel operation at highway speeds.
- Double Helical:Pairs opposing helix angles to cancel axial thrust internally, eliminating complex bearing arrangements; heavy-load reversing-duty cycles in construction and mining equipment specify this configuration, with Austrian specialty mills supplying vacuum-arc-remelted alloy blanks for critical applications.
- High-Speed:Balanced for rotational velocities exceeding 10,000 RPM with enhanced surface finish requirements; turbine and compressor OEMs specify these for energy sector applications.
- Precision:Holds AGMA 2000-grade tolerances for noise-critical aerospace and medical equipment; qualification cycles extend 18–24 months for new production lines.
Single helical configurations handle the majority of throughput; double helical is expanding most quickly on share as heavy-industry buyers prioritize bearing simplification.
Application:
Cost tier differentiation separates specification-controlled aerospace programs from price-sensitive industrial machinery replacement cycles.
- Automotive:Electric vehicle multi-speed reduction gearboxes specify 15°–25° helix angles to meet noise-emission thresholds; Tata Motors and Mahindra procurement under India's PLI scheme is redirecting volume toward domestic precision machining investments.
- Aerospace:Pyrowear 53 and 9310 steel vacuum-arc-remelted grades required for landing gear and actuation systems; Swedish and Austrian mill concentration creates supply vulnerability for tier-1 aerostructures suppliers.
- Construction:EPA noise and emissions standards shape gearbox design for mobile equipment sold in the United States; Japanese OEMs unbundle precision stage manufacturing to preserve design secrecy.
- Industrial Machinery:Represents substantial volume base where standard AGMA ratings suffice; Taiwanese job shops capture commodity gearing through reverse-engineering capability.
Automotive applications command the steepest expansion trajectory; industrial machinery maintains the largest installed base for aftermarket conversion.
End User:
Customer type determines whether procurement emphasizes specification control or availability velocity.
- OEMs:Captive in-house gear production for proprietary drivetrains preserves design secrecy; Siemens and SEW-EURODRIVE maintain foundry-to-assembly vertical control.
- Aftermarket Providers:Compete on reverse-engineering capability and inventory depth rather than original specification authority; wind turbine 2–3 MW gearbox rebuild cycles drive demand for 20-year design life replacements.
- Distributors:Bridge spot-market sourcing for standard industrial sizes; fragmented procurement patterns favor unbundled supply relationships.
- Tier-1 Suppliers:Face KBA documentation burdens for transmission synchronizer hub wear resistance equivalence under REACH compliance deadlines.
OEMs dominate specification-controlled segments; aftermarket providers are gaining share fastest in refurbishment-heavy verticals.
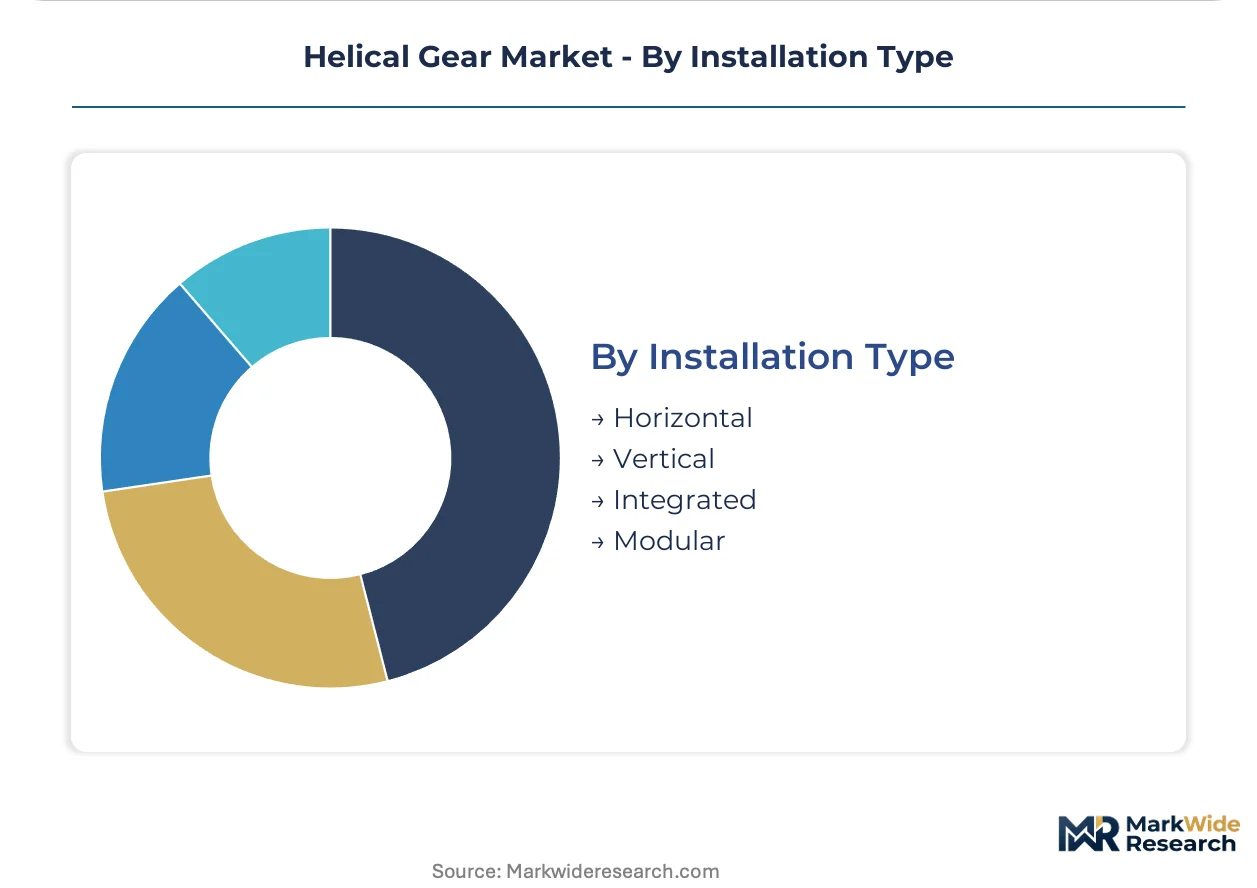
Installation Type:
Volume concentration follows modular system adoption in factory automation and renewable energy infrastructure.
- Horizontal:Standard configuration for parallel shaft arrangements; industrial gearbox manufacturers in Germany specify these for conveyor and pump drives.
- Vertical:Required for space-constrained installations and lifting applications; construction equipment OEMs in Japan favor this orientation for compact excavator drivetrains.
- Integrated:Motor-gearbox combinations reduce assembly complexity; food-processing and medical equipment buyers specify stainless steel integrated units to eliminate contamination points.
- Modular:Enables field reconfiguration and standardized spare parts; wind turbine drivetrain refurbishment programs specify modular helical stages for 20-year service life extension.
Horizontal installations retain the largest installed base; modular configurations are climbing the fastest as renewable energy refurbishment cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in precision gearing tilt toward manufacturing economies with deep metallurgical expertise and stringent regulatory exposure. Export-oriented suppliers in Germany and Japan ship high-grade helical gear sets to automotive and aerospace programs worldwide, while import-dependent markets in India and Southeast Asia build domestic machining capacity under industrial policy incentives.
Germany
Automotive OEMs in Stuttgart and Munich specify AGMA 2000-grade helical gears for electric vehicle multi-speed reduction gearboxes. The KBA enforces noise-emission thresholds under type-approval protocols that mandate sub-35 decibel operation at highway speeds. Bavarian industrial clusters around Augsburg and Nuremberg host dense supplier ecosystems where foundry-to-assembly vertical control remains the competitive norm.
United States
Construction equipment manufacturers in Illinois and Ohio procure helical gear sets for mobile machinery subject to EPA noise and emissions standards. The EPA's Tier 4 Final regulations shape gearbox design for equipment sold domestically. Midwestern industrial corridors concentrate aftermarket refurbishment demand, particularly for wind turbine drivetrain rebuild cycles requiring 20-year design life specifications.
Japan
Construction equipment OEMs in Tokyo and Osaka unbundle precision helical stage manufacturing from final gearbox assembly to preserve design secrecy. METI oversees JIS standards that govern load capacity calculations for industrial machinery applications. Nagoya-area suppliers specialize in compact excavator drivetrains favoring vertical installation configurations for space-constrained environments.
India
Domestic gear manufacturing accelerates under the PLI scheme for automotive components, attracting precision machining investments to serve Tata Motors and Mahindra electric vehicle programs. The BIS administers certification requirements for industrial gear imports that protect nascent domestic production. Tamil Nadu and Maharashtra industrial zones concentrate new capacity for 15°–25° helix angle specifications in multi-speed reduction gearboxes.
China
MIIT's industrial upgrading directives prioritize high-performance gearing for robotics and precision machinery applications. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou scale additive manufacturing workflows for near-net-shape helical gear production. GB standards alignment with ISO 6336 enables export market access for domestic suppliers targeting Southeast Asian industrial machinery demand.
Helical Gear Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and specification control. The vendor base stratifies into three tiers: integrated drivetrain OEMs with captive gear production, independent precision gear manufacturers serving aerospace and automotive programs, and regional job shops competing on reverse-engineering velocity. Consolidation pressure concentrates among mid-scale European suppliers facing EU Green Deal decarbonization mandates. Dominant competitive moves include M&A to secure metallurgical expertise and strategic partnerships to access additive manufacturing qualification pathways.
Among Germany-based integrated suppliers, Siemens, SEW-EURODRIVE, and ZF Friedrichshafen occupy positions defined by foundry-to-assembly vertical control and in-house metallurgy R&D. These entities exemplify the specification-controlled archetype where AGMA 2000-grade certification and KBA type-approval documentation create defensive moats against commodity substitution. Their geographic concentration in Baden-Württemberg and Bavaria reflects historic industrial clustering around automotive and industrial machinery demand.
| Leading Market Players |
|---|
| Nord Drivesystems |
| Siemens |
| SEW-EURODRIVE |
| Bosch Rexroth |
| ZF Friedrichshafen |
| Flender |
| Bonfiglioli |
| WEG |
| Sumitomo Heavy Industries |
| Others |
Value Network & Pricing Analysis
AGMA 2000-A88 certification gates both supplier qualification and price differentiation simultaneously, compressing commodity producers into spot-market tiers while rewarding precision-grade specialists with multi-year contract premiums from automotive and aerospace OEMs.
Pricing Analysis
Industrial OEM buyers anchor contract structures around three-tier pricing across premium, standard, and economy levels, with AGMA 2000-grade certification and vacuum-arc-remelted alloy specifications commanding 40-60 percent premiums over standard industrial ratings. Price differentiation rests on metallurgical traceability and KBA type-approval documentation rather than brand recognition alone. Cost compression in economy-tier job shop segments is intensifying because Taiwanese reverse-engineering specialists capture standard industrial gearbox replacement cycles. Aftermarket providers exhibit highest price sensitivity due to inventory velocity requirements, while aerospace tier-1 suppliers demonstrate lowest sensitivity given specification-locked procurement protocols.
Supply Chain Analysis
Inventory cycles for vacuum-arc-remelted 9310 steel and Pyrowear 53 extend 16-24 weeks, forcing precision-grade manufacturers to pre-position alloy blanks ahead of confirmed orders. Supply concentrates in German, Austrian, and Swedish specialty mills for aerospace-grade inputs, while precision machining capacity clusters in Baden-Württemberg and Bavaria. Raw material dependencies center on nickel-alloy steel billets, bearing-grade chromium coatings, and powder-bed fusion metal powders. Single-source vulnerability in Austrian vacuum-arc-remelting capacity creates structural risk for landing gear and actuation system suppliers. Distribution runs through captive OEM supply chains for proprietary drivetrains and fragmented spot-market channels for standard industrial replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with AGMA certification timelines and KBA type-approval protocols creating 18-24 month switching costs that protect incumbent precision-grade suppliers from commodity substitution.
For Market Incumbents: Fortify metallurgical heat-treatment expertise through apprenticeship pipeline investments in Germany and Japan, where vacuum carburizing skill scarcity threatens production continuity. Deepen backward integration into specialty alloy sourcing through long-term offtake agreements with Austrian and Swedish mills, securing Pyrowear 53 and 9310 steel allocations ahead of aerospace program ramps. Priority defensive positioning targets additive manufacturing qualification pathways where ISO/ASTM 52900 certification threatens to democratize complex geometry production. For New Entrants and Emerging Players: Aftermarket refurbishment velocity gaps in wind turbine 2-3 MW gearbox rebuild cycles offer white-space entry where incumbents under-serve on lead time compression and reverse-engineering agility. India's PLI scheme for automotive components presents the most penetrable geography, with Tata Motors and Mahindra electric vehicle programs actively qualifying new precision machining suppliers. Go-to-market positioning should emphasize AI-assisted tooth contact pattern optimization services that compress prototype validation timelines for custom industrial gearbox orders. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across additive manufacturing qualification pathways as ISO/ASTM 52900 certification requirements extend equipment depreciation schedules and powder cost premiums. Long-term viability favors precision-grade specialists with demonstrated AGMA 2000-A88 production line qualification rather than commodity job shop roll-ups. Target acquisition archetype: mid-scale German suppliers with captive heat-treatment capacity and existing KBA documentation relationships. Signal to monitor: additive manufacturing qualification standard evolution toward production-scale powder bed fusion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Secures Pyrowear 53 and 9310 steel allocations from Austrian and Swedish mills against single-source vulnerability. |
| Additive Manufacturing Qualification Investment | Enables ISO/ASTM 52900-certified near-net-shape production without conventional hobbing scrap rates. |
| AI-Assisted Tooth Contact Optimization | Compresses prototype validation timelines for custom industrial gearboxes using machine learning convergence. |
| Heat-Treatment Apprenticeship Pipeline | Addresses vacuum carburizing and nitriding expertise scarcity retiring faster than vocational replenishment. |
| Wind Turbine Refurbishment Service Expansion | Captures 2-3 MW gearbox rebuild cycle demand for 20-year design life helical gear replacements. |
Research Methodology
A standing panel of gearbox design engineers, foundry operations managers, automotive OEM procurement directors, and aftermarket refurbishment specialists provided ongoing calibration across the analysis period. Primary fieldwork combined structured interviews with heat-treatment furnace operators in Germany and Japan, procurement leads at Stuttgart and Munich automotive clusters, and technical directors at Austrian specialty alloy mills. Secondary validation drew from AGMA technical standards documentation, KBA type-approval filings, EU Green Deal industrial decarbonization progress reports, and customs trade data for precision gear imports. Bottom-up volume estimates triangulated against top-down addressable market calculations derived from electric vehicle powertrain production forecasts and wind turbine installation databases.
Consistency checks validated volume and value outputs against external benchmarks including industrial machinery capex surveys, aerospace landing gear program announcements, and construction equipment production data from Japanese and US manufacturers. The analytical framework modeled demand across product type, application, end user, and installation configuration dimensions, with additional segmentation by precision grade tier and regional regulatory cluster. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking OEM specification roadmaps, incorporating electric vehicle multi-speed reduction gearbox adoption curves and wind turbine drivetrain refurbishment cycle timing.
Forecasts assume regulatory continuity in EU Green Deal industrial decarbonization mandates, EPA noise and emissions standards, and REACH Annex XIV authorization timelines; material policy shifts would require re-modeling of foundry energy intensity compliance costs and hexavalent chromium plating substitution economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Industrial Belt Drives Market
Material Handling Equipment
Asia Pacific Material Handling Equipment Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Air Hose Market
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Pneumatic Caster Market
Material Handling Equipment
Crane Mats Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Asia Pacific Automated Material Handling and Storage Systems Market
Material Handling Equipment
Level Loader Market