
 Industrial Piggable Wye Fitting Market | 2026-2036
Industrial Piggable Wye Fitting Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Piggable Wye Fitting Market Analytics
A shift from single-source to multi-source procurement is expanding across the industrial piggable wye fitting supply base. Oil States Industries leverages its integrated manufacturing footprint to sustain long-term contracts with major pipeline operators. Hartmann Valves anchors European demand through specialized high-pressure designs. Titan Subsea Innovations differentiates via subsea-rated piggable systems for deepwater infrastructure.
An industrial piggable wye fitting is a branched pipeline component engineered to allow passage of pipeline inspection gauges (pigs) without flow interruption, typically manufactured from forged carbon steel, stainless steel, or duplex alloys with smooth internal weld profiles and minimum bend radius compliance. Its primary purpose is to enable simultaneous product diversion and inline maintenance access in multi-product transmission systems. Metallic fittings dominate installed base economics due to pressure rating requirements in oil and gas transmission, while composite variants capture fastest growth in corrosive chemical processing environments where weight reduction matters. The application split reveals pipelines as the mature revenue core, with water treatment emerging as a margin-accretive segment driven by municipal infrastructure renewal cycles.
PHMSA pipeline safety regulations in the United States, Pressure Equipment Directive compliance in Europe, and API 6D valve standards collectively shape product certification requirements and market access thresholds for wye fitting manufacturers. These frameworks mandate traceable material sourcing, hydrostatic testing protocols, and documented pigging compatibility that elevate engineering standards across the supply chain. Stakeholders must monitor evolving integrity management rules and assess in-house versus outsourced fabrication strategies as regulatory scope broadens beyond traditional hydrocarbon applications.
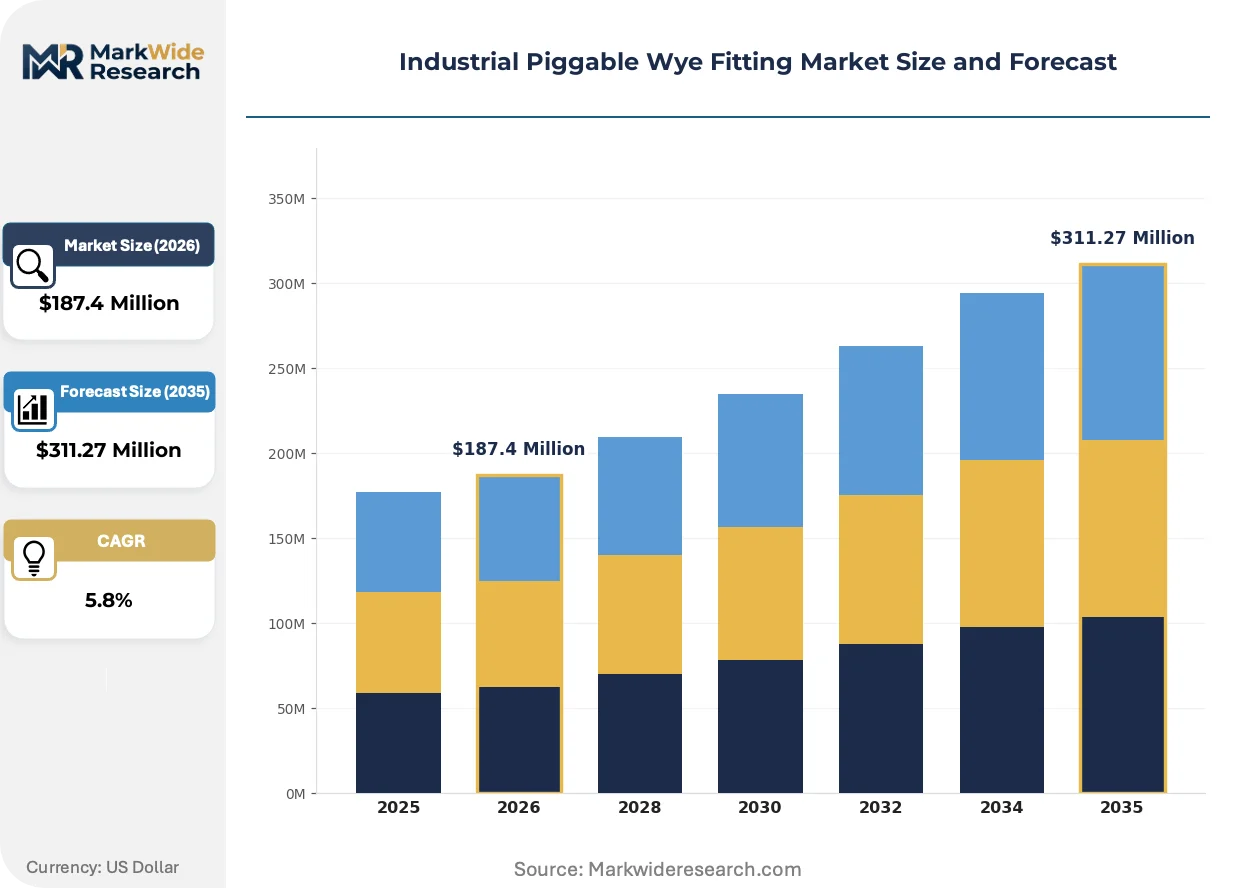
Market Dynamics
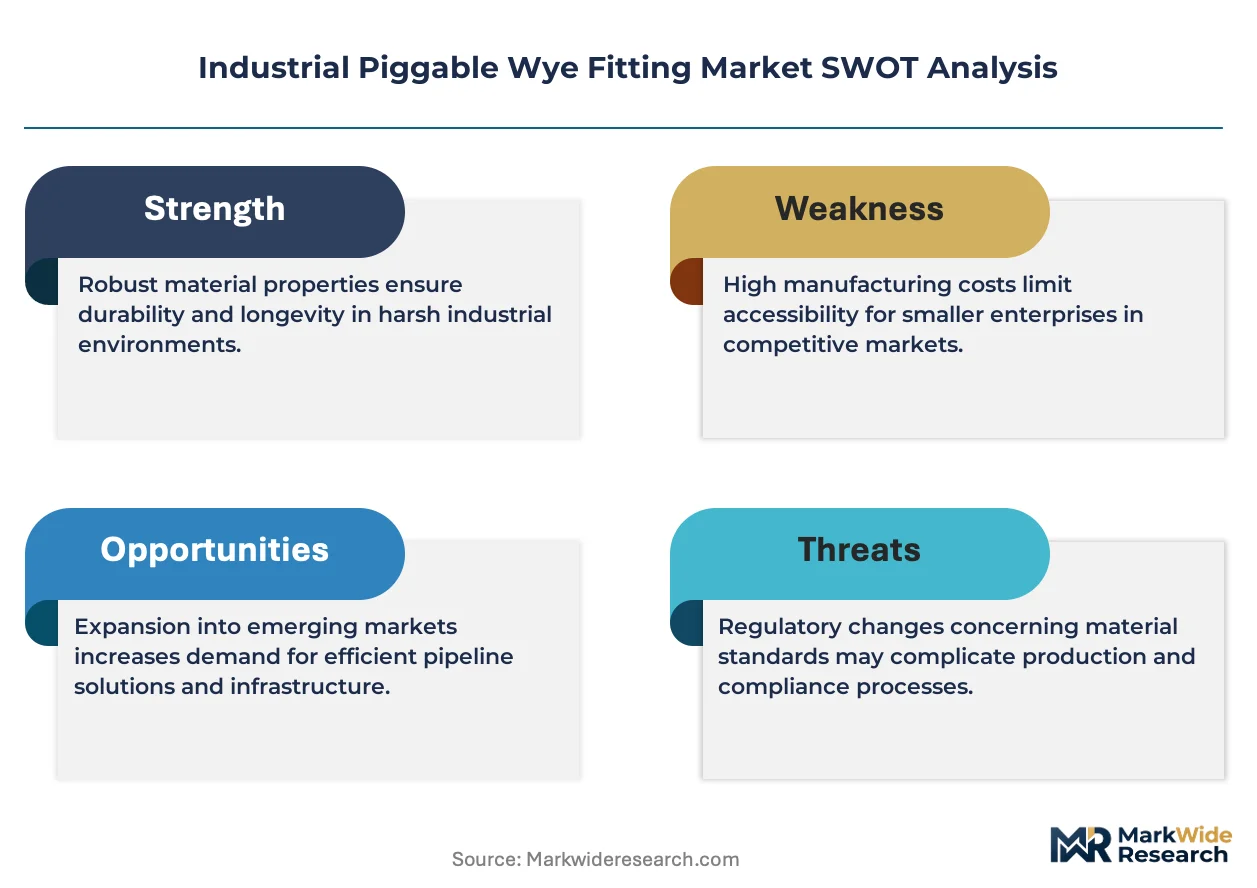
Pipeline integrity mandates from PHMSA and parallel regulators in Germany and Saudi Arabia are forcing systematic replacement of non-piggable branch connections, compressing procurement cycles and elevating engineering specifications across the supply base.
Growth Catalysts
- PHMSA Integrity Management:Mandatory pigging-accessible infrastructure upgrades across US transmission networks accelerate fitting replacement schedules.
- Deepwater Subsea Expansion:Brazil and West Africa offshore developments specify subsea-rated piggable wye systems for unmanned platform tiebacks.
- Duplex Alloy Adoption:Corrosion-resistant metallurgy extends service intervals in sour gas service, justifying premium procurement.
Market Restraints
- Forged Steel Input Volatility:Nickel and molybdenum price swings compress fabrication margins on large-diameter orders.
- German Supplier Concentration:European high-pressure design expertise clusters with specialized valve houses near Dortmund and Essen.
- Weld Profile Tolerances:ASME B31.8 and API 6D pigging compatibility requirements disqualify generic fabrication shops.
Strategic Opportunities
- US Municipal Water Rehabilitation:Aging cast-iron distribution networks present conversion potential for piggable diversion fittings.
- Hydrogen Blend Compatibility:European DSOs require embrittlement-tested metallurgy for repurposed natural gas infrastructure.
- Digital Twin Integration:RFID-embedded fittings enable lifecycle tracking and predictive maintenance in Saudi Aramco's intelligent pipeline program.
Industry Challenges
- Certified Welder Scarcity:ASME Section IX-qualified technicians for smooth-bore branch connections command premium wages and extended lead times.
- Multi-Standard Harmonization:Reconciling API 6D, ISO 14313, and EN 1984 testing protocols delays cross-border shipment approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Piggable Wye Fitting Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic, Plastic, Composite, Hybrid Application: Pipelines, Water Treatment, Oil & Gas, Chemical Processing End User: Utilities, Industrial Manufacturers, Construction, Transportation Size: Small, Medium, Large, Custom |
| Companies Covered | Oil States Industries, BKW, Jag Valves, Stokinger, Titan Subsea Innovations, Hartmann Valves, Sofis Valve, GE Oil & Gas, Tiger Valve Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Piggable Wye Fitting Market Evolving Landscape
Digital instrumentation and advanced metallurgy are redefining piggable fitting specifications, shifting value capture from commodity fabrication toward engineered systems with embedded monitoring capabilities.
Additive manufacturing of complex branch geometries is converging with conventional forging for prototype-to-production acceleration. Subsea contractors in the North Sea are piloting wire-arc deposited wye bodies with integral sensor pockets. This hybrid approach is converging with traditional supply chains by compressing lead times for custom pressure ratings below 12 weeks.
EU Pressure Equipment Directive 2014/68/EU amendments now mandate traceable digital material passports for Category IV pipeline components. German notified bodies are rejecting legacy paper-based certification packages. Fitting suppliers serving Rotterdam and Antwerp storage terminals are reconfiguring quality systems to capture full alloy provenance from melt to final hydrotest.
Integrated service contracts now bundle fitting supply with pigging campaign management. US midstream operators in the Permian Basin are contracting pipeline maintenance on throughput-guarantee terms rather than capital purchase. This shifts supplier relationships from discrete component sales toward decade-long operational partnerships with shared uptime accountability.
Industrial Piggable Wye Fitting Market Segmentation
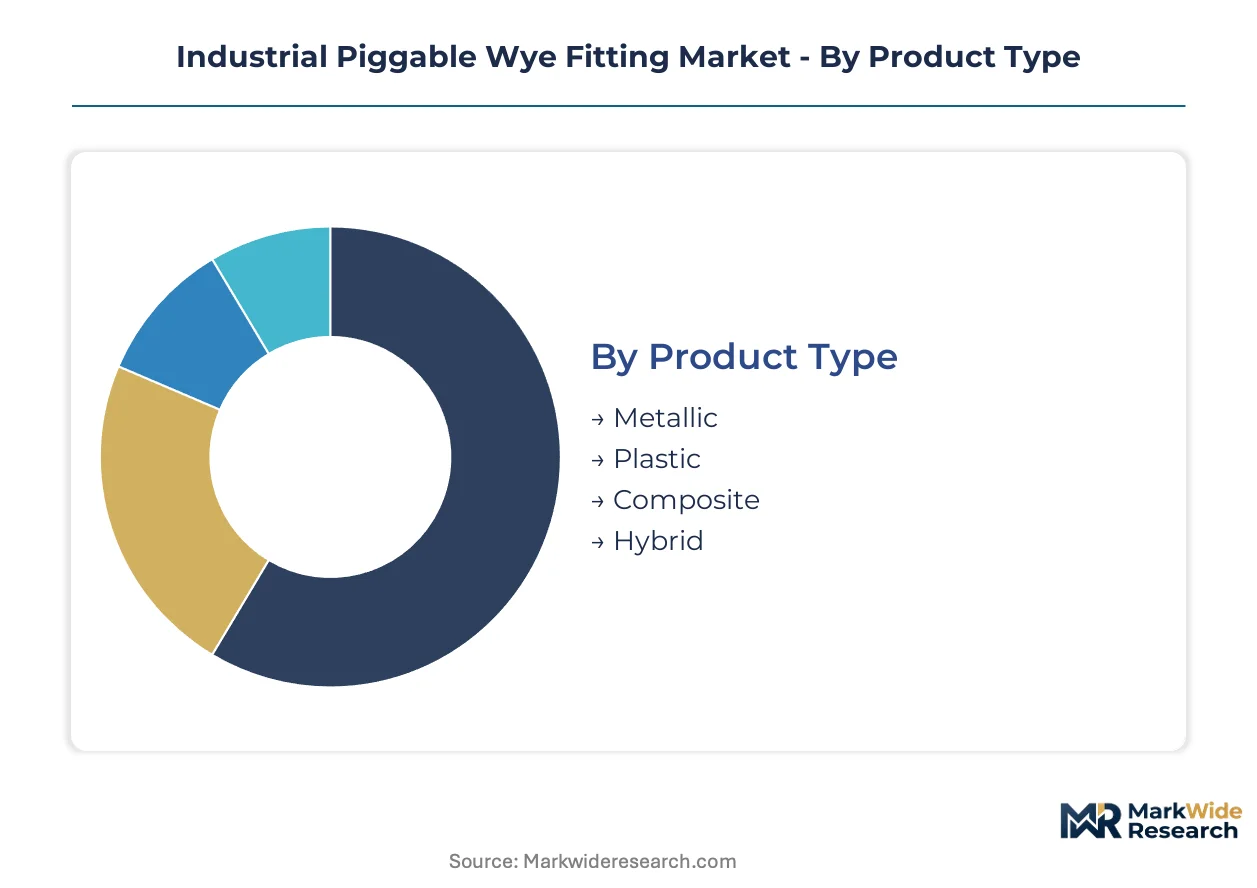
Piggable wye fitting procurement varies sharply by material specification, pressure rating, and end-use environment. Segment boundaries determine which suppliers qualify for contract tiers and which fabrication technologies command pricing premiums.
Product Type:
Capital intensity escalates from polymer molding through precision forging to exotic alloy fabrication, with metallurgical complexity driving equipment amortization schedules.
- Metallic:Forged carbon steel, stainless steel, and duplex alloys dominate high-pressure transmission service. PHMSA-mandated integrity upgrades across US interstate pipelines sustain demand for ASME-compliant weld profiles with full traceability.
- Composite:Glass-reinforced and carbon-fiber epoxy constructions capture chemical processing environments where weight reduction and corrosion immunity offset higher per-unit material costs. German chemical clusters near Ludwigshafen specify composite wyes for chlorine-handling headers.
- Plastic:PVC and HDPE variants serve low-pressure municipal water diversion with minimal pigging frequency.
- Hybrid:Metal-composite bonded constructions address transitional pressure ratings in offshore platform tiebacks.
Most installed capacity flows through Metallic. Expansion is steepest in Composite.
Application:
Operating environment dictates inspection frequency, pigging tool selection, and fitting replacement cycles across divergent infrastructure vintages.
- Pipelines:Multi-product transmission networks require full-bore piggable geometry for batch separation and inline inspection. Saudi Aramco's Master Gas System specifications define the engineering benchmark for desert and offshore trunk lines.
- Water Treatment:Municipal distribution rehabilitation drives conversion of legacy cast-iron tees to piggable configurations. German cities including Dortmund and Essen embed smart water mandates into procurement specifications.
- Oil & Gas:Upstream gathering systems and downstream terminals specify wye fittings compatible with multi-diameter pig trains.
- Chemical Processing:Corrosive fluid handling demands specialty linings and alloy selections beyond standard transmission grades.
Pipeline infrastructure absorbs the dominant share of fabrication output. Water treatment applications are climbing fastest as municipal renewal cycles accelerate.
End User:
Procurement sophistication separates regulated utilities from speculative industrial buyers, with contract structures ranging from decade-long service agreements to spot purchases.
- Utilities:Gas distribution and water authorities mandate certified material passports and documented pigging compatibility. Rotterdam and Antwerp storage terminal operators bundle fitting supply with integrated maintenance contracts.
- Industrial Manufacturers:Petrochemical complexes and fertilizer plants specify custom geometries for process-specific pigging campaigns.
- Construction:Greenfield pipeline projects source fittings through EPC contractor specifications with volume-tier pricing.
- Transportation:Rail and marine loading terminals require rapid-delivery replacement programs for high-cycle diversion points.
Utilities command the largest committed procurement volumes. Industrial manufacturers are expanding their specification influence fastest through direct engineering engagement.
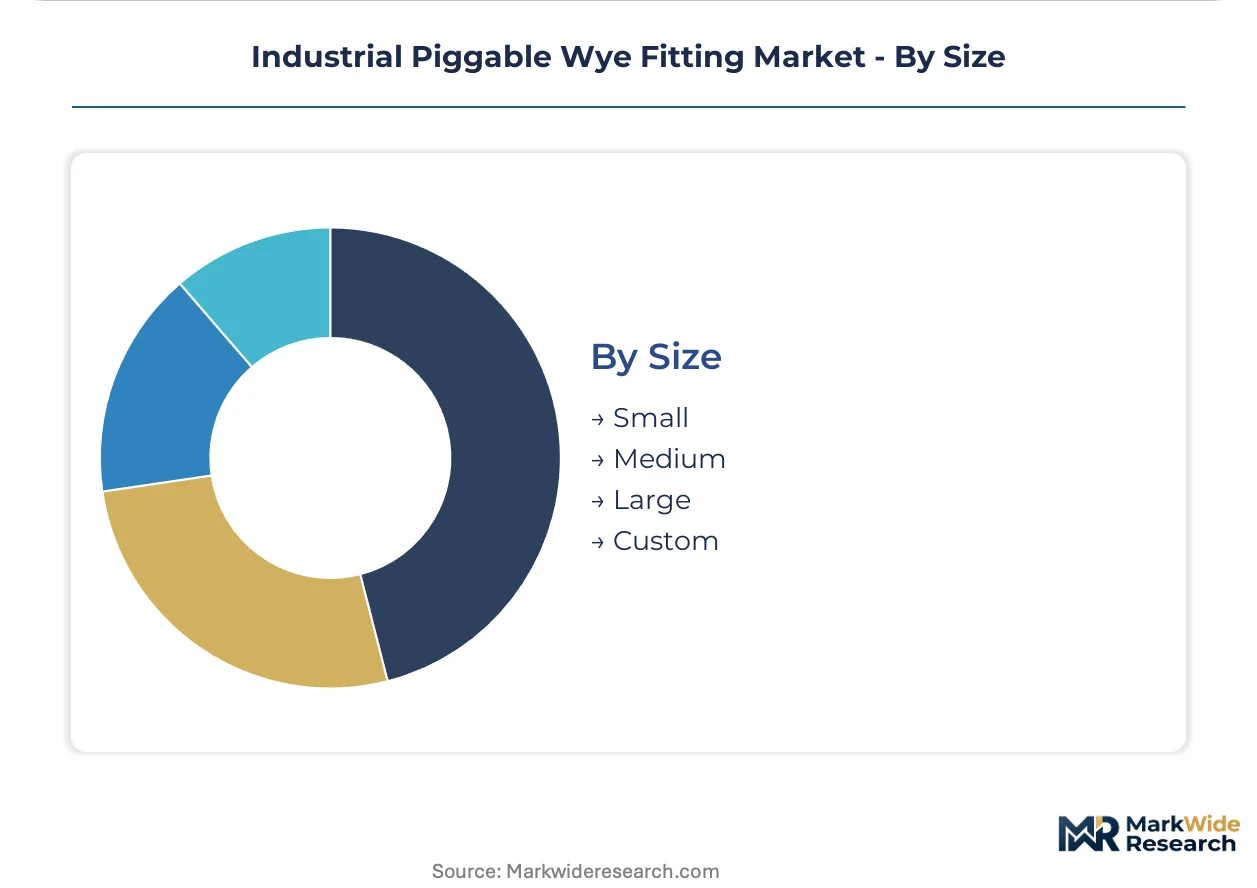
Size:
Dimensional range determines forging press capacity requirements and weld qualification complexity across the supplier base.
- Large:Above 24-inch nominal bore, these fittings require dedicated press lines and Section IX-qualified welders for smooth-bore branch connections. US midstream operators in the Permian Basin dominate order books.
- Custom:Non-standard geometries and pressure ratings command prototype-to-production lead times below 12 weeks through hybrid additive-conventional manufacturing.
- Medium:Standard ANSI ratings serve the majority of distribution network rehabilitation.
- Small:Below 8-inch bore, these fittings approach commodity economics with reduced qualification overhead.
Medium sizes carry the bulk of replacement demand. Custom specifications are expanding most quickly as intelligent pipeline programs embed sensor integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin anchors procurement intensity for industrial piggable wye fittings, with US midstream operators driving replacement cycles for aging branch connections. Pipeline integrity mandates and subsea expansion programs are reshaping geographic demand patterns across multiple jurisdictions.
United States
PHMSA integrity management rules compress replacement schedules for non-piggable infrastructure across interstate transmission networks. The Permian Basin and Gulf Coast corridor concentrate procurement volume for large-diameter forged fittings. Houston-area fabricators face certified welder scarcity as operators accelerate pigging-accessible upgrades.
Germany
Pressure Equipment Directive compliance mandates digital material passports for Category IV pipeline components serving Rotterdam and Antwerp storage terminals. Dortmund and Essen industrial clusters host specialized valve houses with high-pressure design expertise. Municipal water authorities in North Rhine-Westphalia embed smart water mandates into piggable diversion specifications.
Saudi Arabia
Saudi Aramco's Master Gas System specifications define engineering benchmarks for desert and offshore trunk line applications. The national oil company's intelligent pipeline program drives RFID-embedded fitting demand for lifecycle tracking. Eastern Province industrial cities anchor fabrication partnerships with decade-long operational accountability terms.
Brazil
Deepwater subsea expansion off Brazil's coast specifies subsea-rated piggable wye systems for unmanned platform tiebacks. Pre-salt development programs require corrosion-resistant metallurgy extending service intervals in sour gas service. Rio de Janeiro subsea contractors pilot hybrid additive-conventional manufacturing for custom pressure ratings.
United Kingdom
North Sea decommissioning and repurposing cycles create demand for hydrogen blend-compatible embrittlement-tested metallurgy. Aberdeen subsea engineering clusters specify piggable systems compatible with multi-diameter pig trains for platform tieback maintenance. UK regulators align with EU Pressure Equipment Directive amendments for traceable certification packages.
Industrial Piggable Wye Fitting Market Competitive Landscape
Global majors compete with regional champions across certification depth and pressure rating specialization. The supply base organizes into three tiers: integrated forging houses with captive metallurgy, specialized valve fabricators with notified body relationships, and subsea engineering boutiques with hybrid manufacturing capabilities. Market structure rewards ASME Section IX welding qualifications and multi-standard harmonization expertise. Competitive moves center on backward integration into alloy sourcing and capacity expansion for large-diameter press lines.
Within the integrated manufacturing tier, Oil States Industries exemplifies long-term contract sustainability through geographic footprint breadth. Hartmann Valves GmbH and Titan Subsea Innovations occupy distinct specialization vectors—European high-pressure design and subsea-rated systems respectively—demonstrating how regional engineering heritage and offshore application focus create defensible positioning. Jag Valves and BKW represent mid-scale fabricators competing on notified body relationships and custom geometry responsiveness. The competitive field rewards players who bridge fabrication excellence with digital certification compliance.
| Leading Market Players |
|---|
| Oil States Industries |
| BKW |
| Jag Valves |
| Stokinger |
| Titan Subsea Innovations |
| Hartmann Valves |
| Sofis Valve |
| GE Oil & Gas |
| Tiger Valve Company |
| Others |
Value Network & Pricing Analysis
Captive in-house forging capacity at integrated manufacturers anchors both supply security and pricing power for ASME-compliant wye fittings, insulating Oil States Industries and Hartmann Valves from nickel and molybdenum volatility that erodes margins at outsourced fabricators serving spot buyers.
Pricing Analysis
Input-cost pass-through from nickel and molybdenum alloy swings compresses fabrication margins on large-diameter orders, forcing contract-based long-term offtake structures that lock in material baselines for Permian Basin midstream operators. Price differentiation rests on ASME Section IX weld certification tier and volume scale, with PHMSA-mandated integrity upgrades rendering certified fittings least price-sensitive while municipal water authorities face acute budget constraints. Cost compression in standard ANSI ratings is intensifying because generic shops cannot meet API 6D pigging compatibility tolerances.
Supply Chain Analysis
Freight costs from German specialized valve houses near Dortmund and Essen to Rotterdam and Antwerp storage terminals elevate landed costs for European Category IV pipeline components against US Gulf Coast fabrication. Supply concentrates in the United States, Germany, and Saudi Arabia, with raw material dependencies on forged carbon steel billets, duplex alloy ingots, and nickel-chromium feedstock. Single-source vulnerability around ASME-qualified welders for smooth-bore branch connections threatens delivery schedules. Distribution runs through EPC contractor specifications for greenfield projects and direct long-term service agreements with national oil companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial piggable wye fitting market functions as a stable compounder, with PHMSA integrity management mandates and parallel regulatory frameworks in Germany and Saudi Arabia generating predictable replacement demand cycles across aging pipeline networks.
For Market Incumbents: Lock in decade-long operational partnerships with Saudi Aramco and US midstream operators that bundle fitting supply with pigging campaign management, insulating against spot-market price erosion. Deepen backward integration into duplex alloy sourcing to control nickel-molybdenum exposure, while expanding Section IX-certified welder training pipelines in Houston to address scarcity-driven lead time extension. For New Entrants and Emerging Players: EPC contractors serving Brazilian pre-salt deepwater developments represent the most penetrable channel, as unmanned platform tiebacks demand subsea-rated piggable systems with prototype-to-production acceleration below 12 weeks. Target hybrid additive-conventional manufacturing capabilities to capture custom pressure rating orders that incumbent forging houses cannot fulfill within compressed schedules. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale fabricators with notified body relationships because European Pressure Equipment Directive amendments are disqualifying legacy paper-based certification packages, creating forced-seller dynamics among non-compliant shops. Monitor Saudi Aramco RFID-embedded fitting procurement thresholds as the inflection signal for intelligent pipeline program scale-up.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Sourcing | Captive nickel-molybdenum supply hedges PHMSA-mandated replacement cycle volatility for integrated manufacturers. |
| ASME Section IX Welder Pipeline Expansion | Houston-area fabrication capacity unlocks Permian Basin midstream operator contract tiers. |
| Hybrid Additive-Conventional Manufacturing | Wire-arc deposition compresses custom subsea fitting lead times for Brazilian pre-salt contractors. |
| Digital Material Passport Compliance | Full alloy provenance capture satisfies EU Pressure Equipment Directive amendments for Rotterdam terminal operators. |
| Integrated Service Contract Bundling | Throughput-guarantee terms shift supplier relationships from component sales to decade-long operational partnerships. |
Research Methodology
Direct dialogue with pipeline integrity managers, ASME-certified welding supervisors, EPC procurement leads, and notified body auditors in Germany grounded qualitative findings, cross-referenced against PHMSA incident databases, API certification registries, EU Pressure Equipment Directive filings, and customs trade data for forged steel fittings. Bottom-up and top-down triangulation validated fabrication capacity estimates and replacement cycle assumptions.
Bottom-up modeling aggregated segment-level demand across material type, pressure rating, and end-use environment, while top-down cross-checks against national pipeline mileage data and integrity management expenditure patterns anchored volume outputs across the analysis window. CAGRs derived from fitted trend extrapolation of historical replacement cycles, overlaying regulatory mandate acceleration effects and subsea expansion program specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel price volatility, certified welder availability, and harmonization timelines for API-ISO-EN testing protocols. A model refresh is warranted upon material change in PHMSA integrity rule enforcement intensity or Saudi Aramco intelligent pipeline procurement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Scissor Lift Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Heavy Duty Loading Ramps Market
Material Handling Equipment
Global Industrial Weighing Equipment Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Hydraulic Cylinder Rod Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Global Bucket Loader Market