
 Conveyors and Belt Loaders Market | 2026-2036
Conveyors and Belt Loaders Market Size, Share, and Industry Trends Forecast 2026-2036
Conveyors and Belt Loaders Market Outlook
Airport ground support operations is recalibrating material handling priorities as narrow-body fleet expansion accelerates turnaround-time targets. Daifuku Co., Ltd. dominates automated sorting architectures for air cargo terminals across East Asia. Continental AG anchors heavy-duty belt manufacturing for mining and bulk-logistics applications with specialized rubber-composite formulations. Siemens AG leverages digital twin integration to extend predictive maintenance capabilities across electric-drive conveyor networks.
Conveyors and belt loaders constitute mechanized transport systems engineered to move bulk materials, unit loads, or passenger baggage through continuous belt, roller, or overhead traction mechanisms, typically specified by load capacity per meter, belt speed in meters per second, and drive motor kilowatt rating. Their primary industrial purpose centers on eliminating manual handling bottlenecks while synchronizing throughput with upstream production or downstream dispatch schedules. Floor conveyor installations occupy the largest installed base across automotive assembly plants, where chain-driven pallet systems synchronize with robotic welding stations. Electric drive technology leads replacement demand as energy-efficiency regulations tighten operational cost structures for warehousing and logistics companies. Belt loader units serving airport operations command premium pricing due to aircraft-compatibility certification requirements and ground-support equipment interoperability standards.
OSHA mandates guarding and lockout-tagout protocols for powered conveyor systems, while FAA regulations govern belt loader stability and aircraft proximity safety in commercial aviation environments. The European Union's Machinery Directive and CE marking requirements enforce design-risk assessments and electromagnetic compatibility testing for equipment deployed across member states. ISO 5048 and CEMA standards establish belt tension, idler spacing, and pulley dimension benchmarks that manufacturers must satisfy for cross-border project acceptance. Stakeholders must monitor evolving carbon-border adjustment mechanisms and embedded-emissions reporting obligations that will reshape supplier qualification criteria for conveyor steel, rubber, and electric drivetrain components.
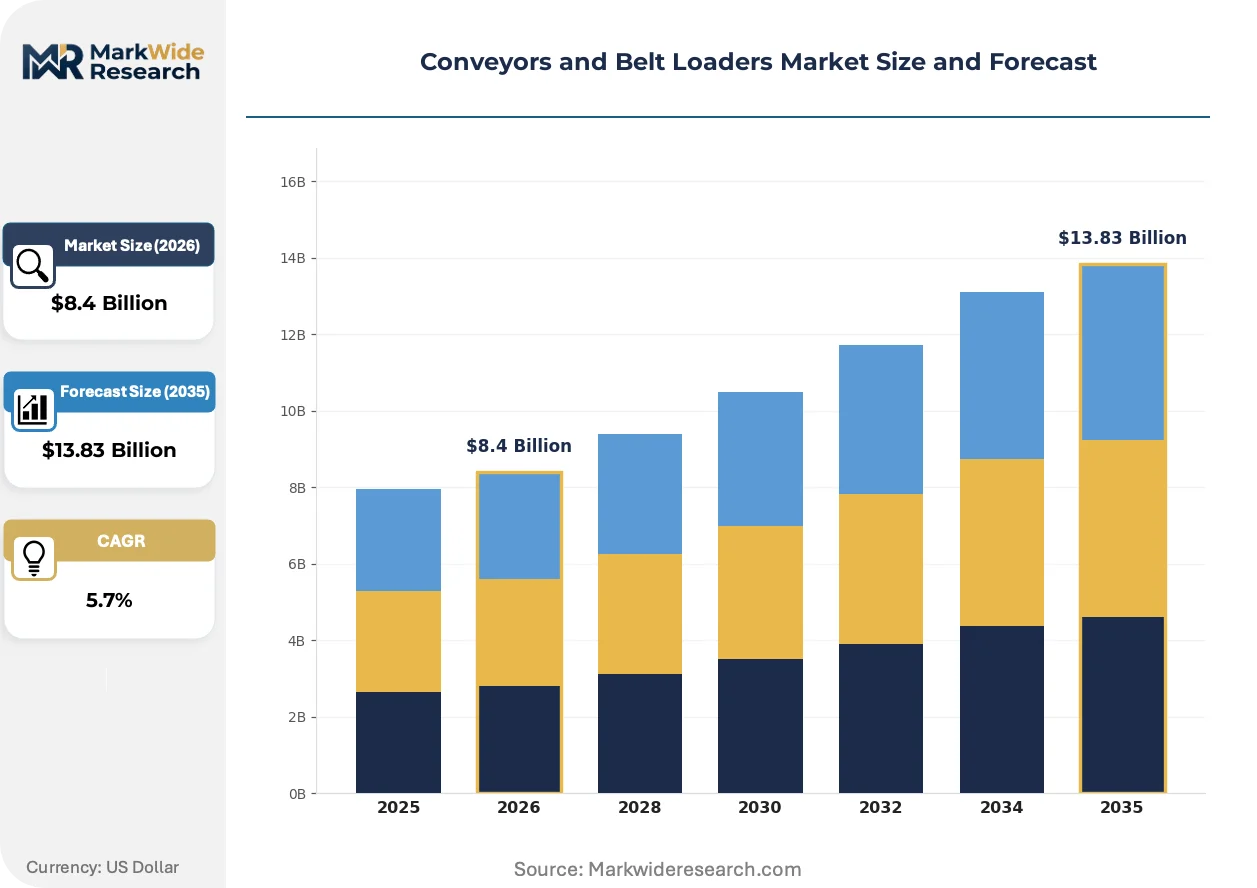
Market Dynamics
Electric-drive floor conveyor systems are displacing pneumatic and hydraulic alternatives across automotive assembly plants as energy-efficiency mandates tighten operational cost structures and carbon accounting requirements.
Growth Catalysts
- OSHA Guarding Mandates:Powered conveyor lockout-tagout protocols are forcing facility upgrades across US warehousing operations, creating replacement demand for compliant control architectures.
- Narrow-Body Fleet Expansion:Airport ground support operations are recalibrating turnaround-time targets, accelerating belt loader procurement for single-aisle aircraft compatibility.
- Automotive Synchronization:Chain-driven pallet systems are integrating with robotic welding stations in Germany, driving precision conveyor specification for just-in-sequence assembly.
Market Restraints
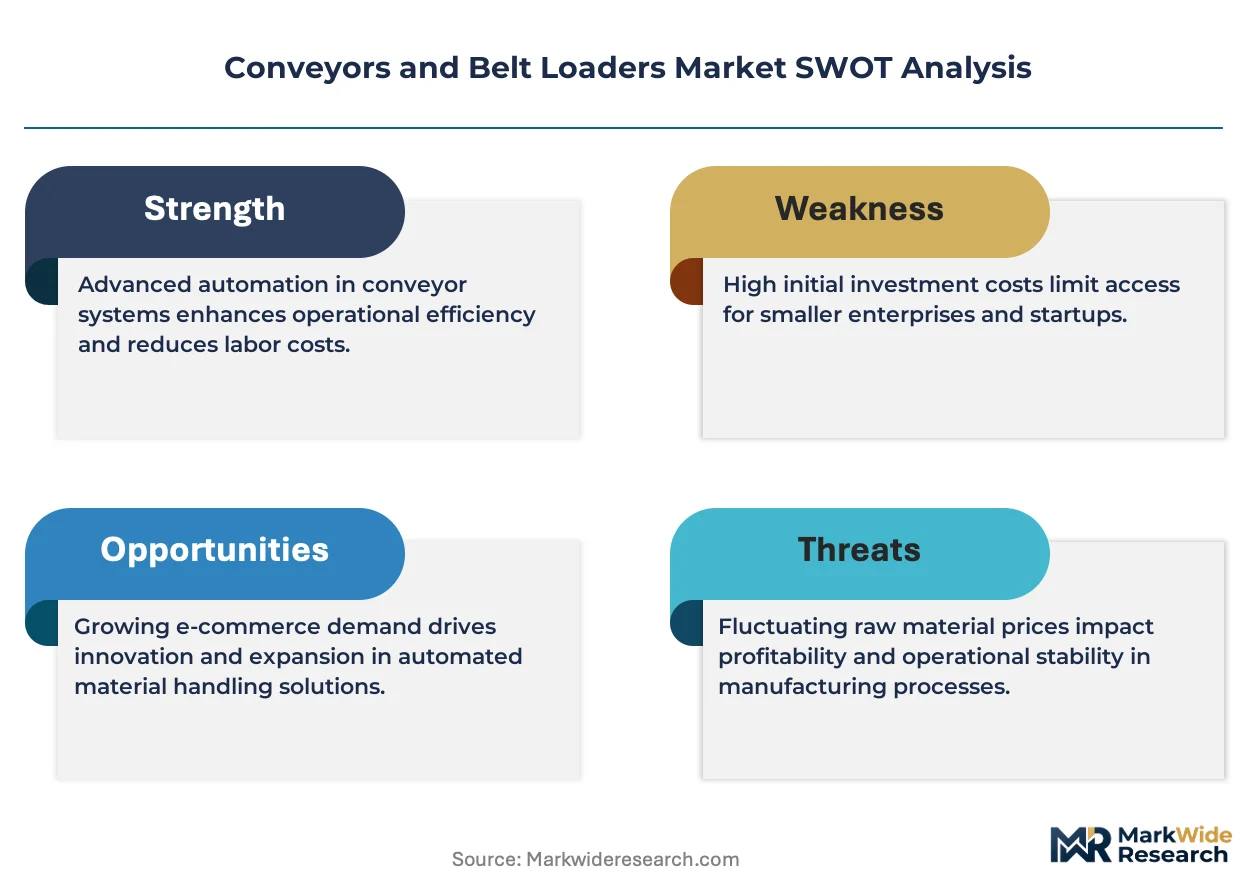
- Rubber-Composite Input Volatility:Specialized belt formulations depend on petroleum-derived feedstocks and carbon-black supply concentration, exposing margins to energy-price fluctuations.
- Steel Supply Concentration:Conveyor frame and idler manufacturing relies on Chinese and Indian rolled-steel capacity, creating tariff-exposure and carbon-border adjustment risks for European buyers.
- Aircraft-Certification Friction:FAA ground-support equipment interoperability standards impose multi-year validation timelines that compress supplier cash conversion cycles.
Strategic Opportunities
- India Cargo Hub Modernization:PLI scheme incentives for logistics infrastructure are opening procurement windows for electric-drive sorting systems at emerging air freight terminals.
- Predictive Maintenance Convergence:Digital twin integration with vibration-monitoring sensors is converging with cloud-based fleet management platforms to unlock subscription revenue streams.
- EU Green Deal Tailwind:Embedded-emissions reporting obligations under the Carbon Border Adjustment Mechanism are favoring suppliers with verified low-carbon steel and rubber sourcing.
Industry Challenges
- Mechatronics Skill Scarcity:Servo-drive commissioning and PLC programming expertise is concentrating in automotive supplier clusters, creating hiring bottlenecks for conveyor system integrators.
- Legacy Pneumatic Integration:Hybrid retrofit projects face compressed-air infrastructure incompatibility, forcing costly parallel system architectures during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conveyors and Belt Loaders Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Overhead Conveyor, Floor Conveyor, Belt Loader, Telescopic Loader Application: Packaging, Automotive Assembly, Warehousing, Airport Operations End User: Manufacturing Sector, Air Cargo, Logistics Companies, Retail Technology: Electric Drive, Pneumatic, Gravity-Driven, Hybrid Systems |
| Companies Covered | Daifuku Co., Ltd., Continental AG, Fives Group, Siemens AG, BEUMER Group, Intralox, Textron Ground Support Equipment Inc., TLD Group, JBT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveyors and Belt Loaders Market Strategic Shifts
Sensor fusion and edge-computing architectures are redefining how conveyor networks coordinate with upstream production schedules, compressing latency between material arrival and processing initiation.
Digital twin platforms are converging with physical conveyor installations to enable real-time belt-tension optimization and idler-wear prediction. German automotive OEMs are deploying these systems across multi-facility networks, standardizing predictive maintenance protocols. This convergence is compressing mean-time-between-failures and reducing unplanned downtime penalties in high-volume assembly environments.
The EU Machinery Directive's updated electromagnetic compatibility testing requirements are forcing redesigns of variable-frequency drive enclosures and motor cabling architectures. Manufacturers serving member states must now document risk assessments for conducted and radiated emissions across the 150 kHz to 6 GHz spectrum. Belt loader producers targeting European airports are absorbing compliance costs into premium pricing tiers while accelerating CE-marking timeline investments.
Outcome-based service contracts are displacing traditional equipment-sales models in warehouse and distribution center procurement. Third-party logistics operators in the United States are bundling conveyor uptime guarantees with energy-consumption performance clauses, transferring operational risk to OEM service organizations. This behavioral shift is most visible in e-commerce fulfillment networks where seasonal volume volatility demands flexible capacity scaling without capital ownership.
Conveyors and Belt Loaders Market Segmentation
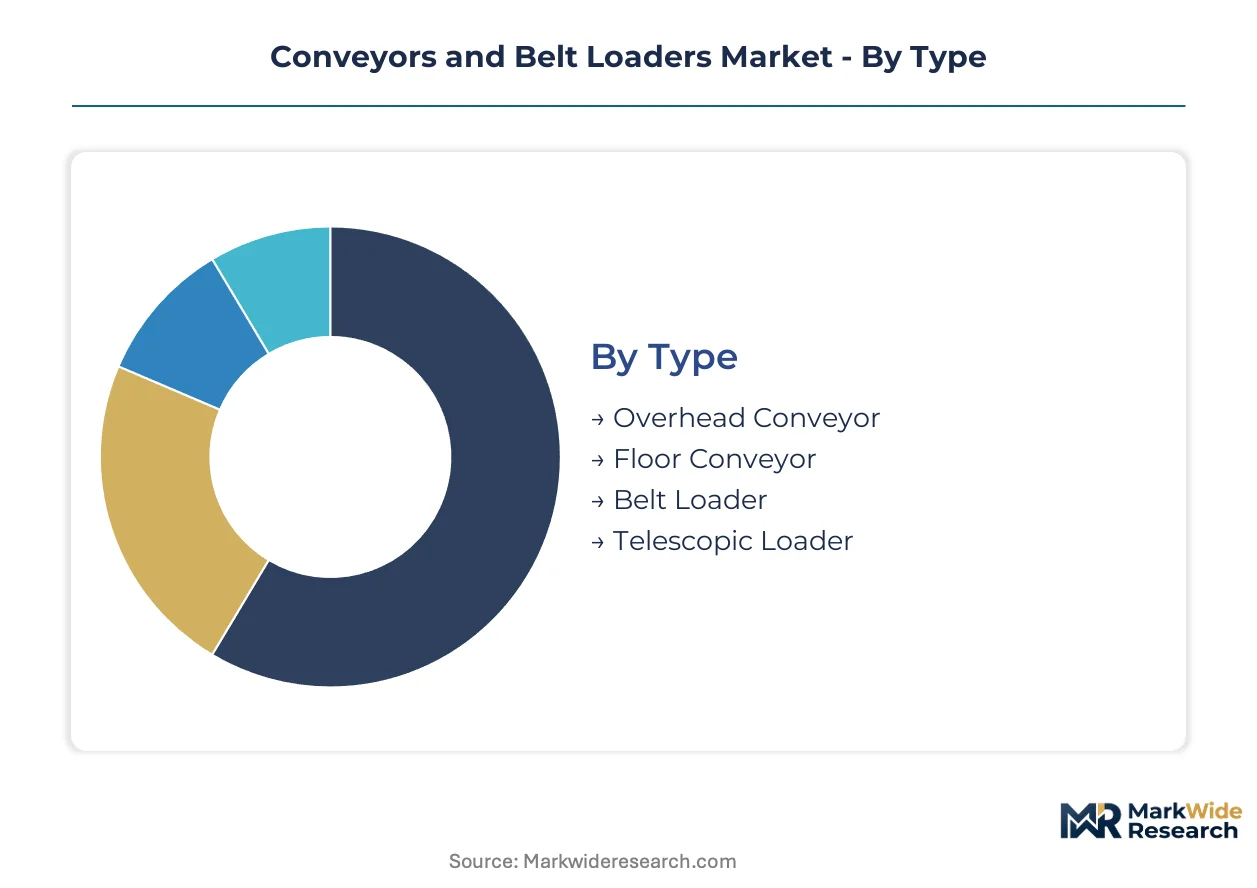
Segmentation in conveyors and belt loaders reveals how supply concentration shapes procurement patterns across divergent operational environments. Equipment specification varies dramatically between high-frequency airport turnarounds and continuous automotive assembly cycles.
Type:
Supply concentration in conveyor manufacturing clusters around specialized fabrication capabilities for each type variant.
- Overhead Conveyor:These systems employ trolley-mounted carriers suspended from ceiling-mounted track networks, typically rated for 50-500 kg per carrier. Demand concentrates in German automotive paint shops and final assembly zones where floor space optimization drives specification. Energy-efficiency mandates are accelerating electric trolley motor replacement cycles.
- Floor Conveyor:Chain-driven pallet systems dominate automotive body-in-white lines with synchronized stop-and-go precision. German OEMs anchor replacement demand as just-in-sequence assembly tightens tolerance requirements for weld station alignment.
- Belt Loader:Aircraft-compatible units feature telescopic boom extensions and adjustable height mechanisms for narrow-body cargo holds. FAA certification requirements create supply bottlenecks, compressing qualified vendor pools.
- Telescopic Loader:Extendable boom designs serve high-volume parcel hubs with variable reach configurations. E-commerce fulfillment networks in the United States drive specification for rapid deployment and retraction cycles.
Today's leader: Floor Conveyor. Tomorrow's challenger: Belt Loader.
Application:
Cost tier differentiation separates premium synchronized systems from standardized bulk-handling installations.
- Packaging:Accumulation conveyors with zero-pressure zoning prevent product damage during batch transitions. Food and beverage facilities in Germany specify stainless-steel construction for washdown compliance.
- Automotive Assembly:Precision pallet-based systems integrate with robotic welding stations through PLC-coordinated motion profiles. German OEMs drive specification for electric servo drives replacing hydraulic alternatives.
- Warehousing:High-velocity sortation networks employ cross-belt and tilt-tray technologies for parcel routing. Third-party logistics operators prioritize energy-consumption performance clauses in procurement.
- Airport Operations:Ground support equipment demands aircraft-compatibility certification and interoperability with existing fleet management systems. Narrow-body fleet expansion accelerates turnaround-time targets.
Automotive Assembly commands premium pricing tiers. Warehousing represents the steepest expansion trajectory.
End User:
Customer type determines service model preference between capital ownership and outcome-based contracts.
- Manufacturing Sector:Discrete production lines demand synchronized material flow with upstream fabrication schedules. Automotive and electronics verticals anchor specification for predictive maintenance integration.
- Air Cargo:Terminal operators prioritize equipment interoperability and FAA ground-support certification. Hub modernization across India opens procurement windows under PLI scheme incentives.
- Logistics Companies:Third-party operators favor uptime guarantees bundled with energy performance clauses. Seasonal volume volatility drives demand for flexible capacity scaling without asset ownership.
- Retail:Omnichannel fulfillment networks require rapid reconfiguration capabilities for peak demand surges. Distribution centers specify modular conveyor architectures for aisle-density optimization.
Logistics Companies are consolidating procurement leverage. Air Cargo presents the fastest-climbing specification tier.
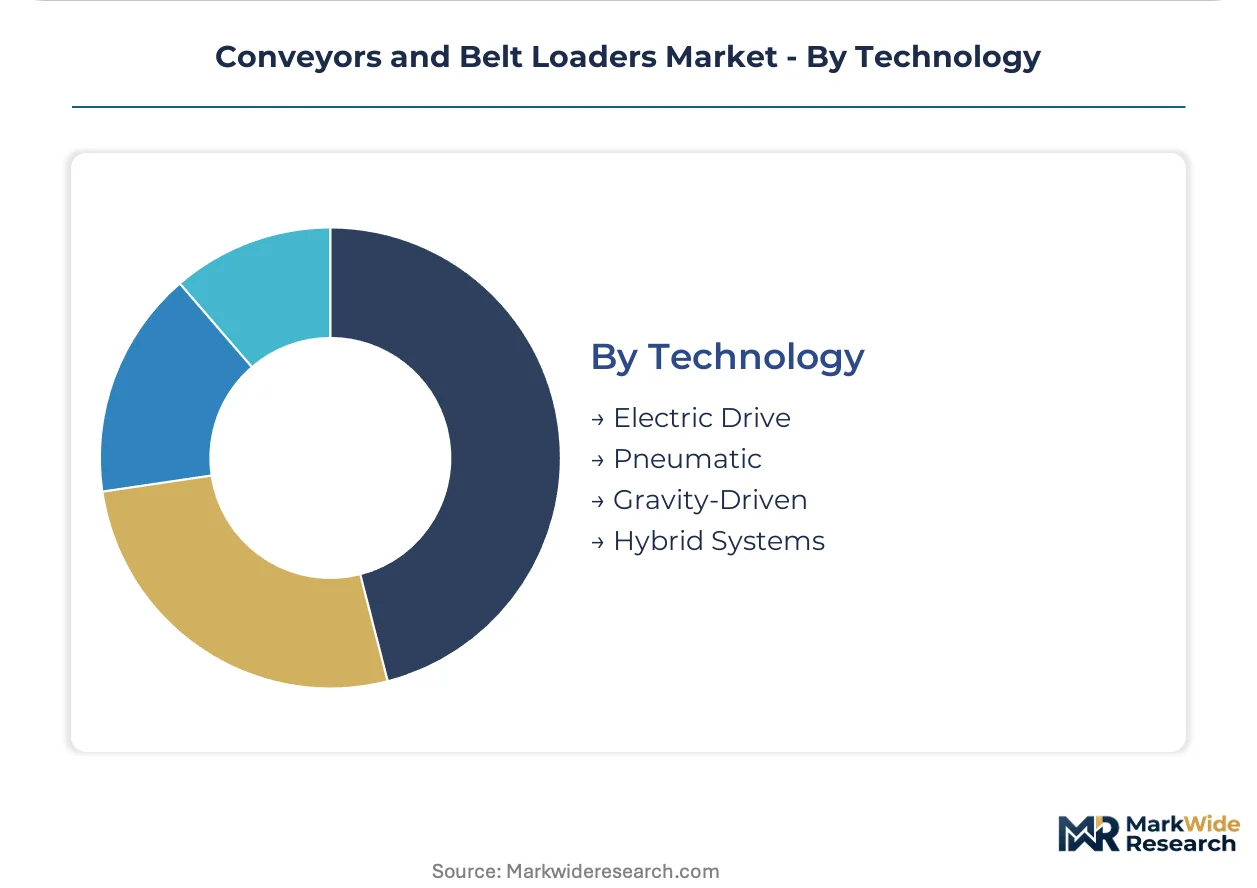
Technology:
Maturity curves separate established electric architectures from emerging hybrid configurations.
- Electric Drive:Variable-frequency drive systems with regenerative braking dominate new installations. EU energy-efficiency regulations tighten operational cost structures for warehousing and logistics operators.
- Pneumatic:Compressed-air actuation persists in legacy facilities with existing infrastructure investments. Retrofit projects face hybrid integration challenges during transition periods.
- Gravity-Driven:Unpowered roller conveyors serve low-velocity accumulation zones with minimal maintenance requirements. Cost-sensitive applications in retail distribution favor this technology for non-priority lanes.
- Hybrid Systems:Combined electric-pneumatic architectures address compressed-air infrastructure incompatibility during phased upgrades. Automotive plants in Germany deploy these configurations during multi-year facility transitions.
Electric Drive anchors current installed base. Hybrid Systems represent the fastest-gaining specification category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting conveyor manufacturing investment toward jurisdictions with streamlined machinery certification pathways and lower embedded-carbon compliance costs. Production capacity is migrating to countries where energy-efficiency mandates and carbon-border mechanisms create competitive positioning advantages for local fabricators.
United States
OSHA lockout-tagout mandates are forcing warehousing facility upgrades across the Midwest and Southeast distribution corridors. FAA ground-support equipment standards govern belt loader certification timelines for narrow-body fleet expansion. Dallas-Fort Worth and Atlanta cargo hubs are absorbing premium-priced electric-drive systems for turnaround efficiency targets.
Germany
Automotive assembly plants in Bavaria and Baden-Württemberg are replacing hydraulic floor conveyors with electric servo-drive precision systems. EU Machinery Directive electromagnetic compatibility testing is redesigning variable-frequency drive enclosures for CE marking compliance. Stuttgart and Wolfsburg industrial clusters are standardizing predictive maintenance protocols through digital twin integration.
China
Steel frame and idler manufacturing concentrates in Hebei and Jiangsu provinces serving domestic and export conveyor markets. MIIT energy-efficiency standards are accelerating electric motor replacement cycles in logistics infrastructure. Yangtze River Delta port automation projects are specifying high-capacity bulk handling systems for container terminal throughput expansion.
India
PLI scheme incentives for logistics infrastructure are opening procurement windows at emerging air freight terminals in Maharashtra and Karnataka. BIS machinery safety standards are tightening design-risk assessment requirements for imported equipment. Delhi-Mumbai Industrial Corridor cargo hubs are specifying modular sorting architectures for e-commerce fulfillment scale-up.
Japan
METI carbon-neutral industrial targets are driving replacement demand for regenerative braking systems in automotive assembly networks. JIS standards govern belt tension and pulley dimension specifications for cross-border project acceptance. Nagoya and Osaka manufacturing clusters are integrating edge-computing architectures for real-time conveyor coordination with robotic welding stations.
Conveyors and Belt Loaders Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium-tier certification requirements concentrating vendor pools in airport ground support while warehousing applications sustain fragmented supply. The vendor base organizes around three strategic archetypes: integrated automation conglomerates with digital twin capabilities, specialized belt and component fabricators with rubber-composite expertise, and regional ground-support equipment specialists with FAA certification track records. Competitive positioning hardens through M&A consolidation of predictive maintenance software assets and geographic expansion into India cargo hub modernization projects under PLI scheme incentives.
Within the integrated automation tier, Daifuku Co., Ltd. and Siemens AG exemplify the convergence of physical conveyor hardware with cloud-based fleet management platforms. Continental AG anchors specialized belt manufacturing expertise across heavy-duty mining and bulk-logistics applications. These three companies occupy positions where digital twin integration and predictive maintenance subscriptions are displacing traditional equipment-sales models.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Continental AG |
| Fives Group |
| Siemens AG |
| BEUMER Group |
| Intralox |
| Textron Ground Support Equipment Inc. |
| TLD Group |
| JBT Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive steel and rubber-compound fabrication in Hebei and Jiangsu provinces anchors both supply security and pricing power for Chinese conveyor OEMs, compressing margin structures for European and North American fabricators facing carbon-border adjustment exposure. This geographic concentration of foundational inputs creates tiered procurement economics where proximity to rolled-steel capacity determines landed cost competitiveness across belt loader and floor conveyor categories.
Pricing Analysis
Distributor markups of 15-25% separate OEM gate pricing from end-user acquisition costs in warehousing and logistics procurement, while direct-to-automotive-OEM contracts command volume discounts tied to just-in-sequence delivery guarantees. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—FAA ground-support equipment interoperability standards elevate belt loader pricing, while uncertified bulk-handling units compete on steel-frame commodity economics. Cost compression in standard-tier warehousing equipment is intensifying because third-party logistics operators are bundling energy-consumption performance clauses that transfer operational risk to OEM service organizations. Retail distribution centers exhibit highest price sensitivity due to seasonal volume volatility and modular reconfiguration requirements, whereas airport ground support operations show lowest sensitivity given aircraft-compatibility certification mandates and fleet interoperability imperatives.
Supply Chain Analysis
Refurbishment and remanufacturing flows for electric-drive floor conveyor systems are concentrating in Stuttgart and Wolfsburg industrial clusters, where predictive maintenance data from digital twin platforms extends component lifecycles and feeds secondary parts markets. Primary manufacturing draws from Chinese rolled-steel capacity in Hebei province, German servo-drive motor production in Bavaria, and Indian rubber-compound processing in Maharashtra for belt formulations. Tariff exposure on Chinese steel inputs creates margin volatility for European conveyor fabricators as carbon-border adjustment mechanisms phase in embedded-emissions reporting obligations. Distribution runs through regional system integrators with PLC programming and servo-drive commissioning expertise, concentrating procurement leverage among automotive OEMs and air cargo terminal operators with multi-facility standardization requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU carbon-border adjustment mechanisms and embedded-emissions reporting obligations inflate landed costs for Chinese steel-dependent fabricators, creating procurement windows for Indian and Southeast Asian suppliers with verified low-carbon sourcing.
For Market Incumbents: Anchor defensive positioning through backward integration into rubber-compound formulation capabilities and captive steel-frame fabrication, insulating margin structures from petroleum-derived feedstock volatility and tariff-exposure on rolled-steel imports. Accelerate CE-marking timeline investments and electromagnetic compatibility testing documentation to preempt EU Machinery Directive redesign cycles that compress qualified vendor pools. Prioritize predictive maintenance software asset consolidation through targeted acquisition of vibration-monitoring sensor platforms and cloud-based fleet management providers. For New Entrants and Emerging Players: India's PLI scheme incentives for logistics infrastructure open a window for electric-drive sorting system penetration at emerging air freight terminals in Maharashtra and Karnataka, where BIS machinery safety standards tighten design-risk assessment requirements for imported equipment and favor local assembly partnerships. Target warehousing and distribution center procurement with outcome-based service contracts bundling uptime guarantees and energy-consumption performance clauses, transferring operational risk from capital-constrained third-party logistics operators. Deploy modular conveyor architectures with rapid reconfiguration capabilities to capture omnichannel fulfillment network demand from retail distribution centers facing seasonal volume volatility. For Investors and Strategic Acquirers: Roll-up economics work for predictive maintenance software specialists because digital twin integration with physical conveyor installations is displacing traditional equipment-sales models and unlocking recurring subscription revenue streams across automotive and warehousing verticals. Focus acquisition screening on mid-cap system integrators with servo-drive commissioning expertise and established FAA ground-support equipment certification track records, as mechatronics skill scarcity concentrates hiring bottlenecks and elevates qualified vendor valuations. Monitor carbon-border adjustment mechanism implementation timelines and embedded-emissions verification protocol adoption rates as inflection indicators for supplier qualification criteria shifts that will reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber-Compound Formulation | Captive supply of specialized belt materials insulates margins from petroleum feedstock volatility and carbon-black supply concentration. |
| Predictive Maintenance Platform Acquisition | Digital twin integration with vibration-monitoring sensors unlocks subscription revenue streams across automotive assembly networks. |
| CE-Marking Timeline Acceleration | EU Machinery Directive electromagnetic compatibility testing redesigns favor early-compliant vendors with documented risk assessments. |
| India PLI Scheme Localization Partnership | BIS machinery safety standards and logistics infrastructure incentives open procurement windows at emerging air freight terminals. |
| Outcome-Based Service Contract Expansion | Uptime guarantees bundled with energy performance clauses transfer operational risk from third-party logistics operators to OEMs. |
Study Parameters
Direct dialogue with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across automotive assembly, air cargo terminal, and warehousing operations grounded qualitative findings in operational reality. Primary insights combined with secondary validation from customs and trade data, SEC 10-K filings of listed automation conglomerates, and FAA ground-support equipment certification databases. Bottom-up and top-down triangulation cross-checked equipment installation counts against facility expansion announcements and regulatory mandate implementation timelines.
Bottom-up modeling segmented volume and value outputs across conveyor type, application, end user, and technology dimensions, with additional granularity for electric-drive motor kilowatt ratings and belt speed specifications. Top-down demand estimation anchored in automotive production schedules, narrow-body fleet expansion projections, and e-commerce fulfillment network capex disclosures. CAGRs derived from regression analysis of replacement cycle acceleration patterns and energy-efficiency regulation phase-in schedules, incorporating steel price volatility indices and carbon-border adjustment mechanism implementation assumptions.
Revisions become necessary when carbon-border adjustment mechanism timelines accelerate, petroleum-derived rubber-compound feedstock prices spike beyond historical volatility bands, or FAA ground-support equipment interoperability standards expand certification scope. Practitioners should monitor EU embedded-emissions verification protocol adoption rates, Indian PLI scheme incentive disbursement patterns, and narrow-body aircraft delivery schedules for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
Hydraulic Fittings Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Pug Mill Mixers Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market
Material Handling Equipment
Motorized Decoiler Machine Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
Forklift Rental Market
Material Handling Equipment
Slitting Machines Market
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Japan Conveyor Belt Market