
 Global Linear Guide Market | 2026-2036
Global Linear Guide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Linear Guide Market Outlook
Semiconductor fabrication equipment is realigning linear guide procurement toward sub-micron positioning grades. THK leverages its captive supply of precision-ground ball screws to dominate Japanese tool builder relationships. Hiwin sustains manufacturing scale across Taichung to compete on cost in standard-grade automation. Bosch Rexroth anchors European demand through backward integration into linear motor and drive systems.
A linear guide is a mechanical bearing element comprising a rail and carriage assembly that constrains motion to a single degree of freedom with micron-level repeatability, typically manufactured through induction-hardened steel grinding or cold-drawn aluminum extrusion depending on load rating. Ball guide rails remain the volume leader across general automation while magnetic guides capture the fastest expansion in cleanroom and vacuum-compatible semiconductor stages. Roller guides occupy the premium margin pool in heavy-load machine tool applications where stiffness and damping outweigh cost sensitivity.
Japan's METI enforces JIS B 6330 standards for positioning accuracy that gate domestic OEM qualification, while the EU Machinery Directive through CE marking mandates functional safety validation for integrated linear axis systems. China's SAMR coordinates GB standard harmonization with IEC frameworks for motion control components entering industrial robot supply chains. Stakeholders must monitor divergence between regional certification requirements when configuring global product platforms.
Market Dynamics
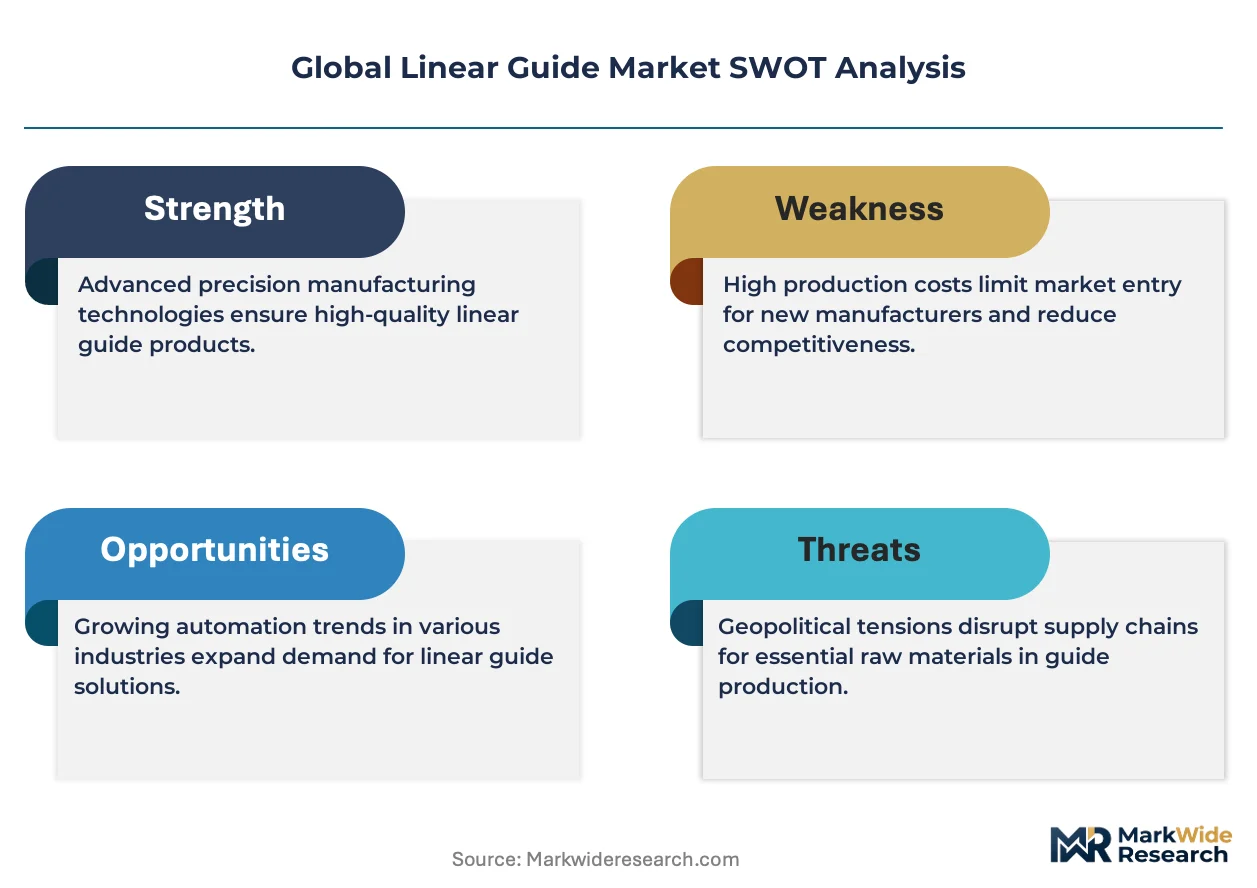
Semiconductor tool builders are compressing positioning tolerances to sub-micron grades, forcing linear guide suppliers to synchronize thermal stability, material purity, and motion control architectures into unified qualification protocols.
Growth Catalysts
- MIIT dual carbon mandates:China's tightening energy-efficiency standards for industrial machinery components are accelerating replacement cycles in automotive and electronics manufacturing equipment.
- Ball screw integration:Captive supply of precision-ground ball screws enables Japanese builders to guarantee positioning repeatability across multi-axis semiconductor stages.
- Stuttgart manufacturing cluster:Germany's Baden-Württemberg region concentrates demand for heavy-load roller guides in machine tool rebuilds and automotive press automation.
Market Restraints
- Specialized alloy dependency:Induction-hardened bearing steel supply concentrates among a limited set of European and Japanese metallurgical suppliers, exposing lead times to raw material allocation.
- JIS B 6330 qualification gates:Japan's METI-enforced positioning accuracy standards create friction for non-domestic suppliers seeking OEM integration contracts.
- Magnetic guide substitution:Cleanroom-compatible magnetic levitation stages are capturing positioning applications below 100 nanometers where mechanical contact introduces particle contamination risk.
Strategic Opportunities
- India industrial automation:The PLI scheme for manufacturing and warehousing automation is creating first-time specification of linear motion components in domestic assembly operations.
- GB-IEC harmonization:China's SAMR coordination of national standards with IEC frameworks reduces certification duplication for motion control components entering industrial robot supply chains.
- Linear motor convergence:Integration of direct-drive linear motors with guide rail architectures is unbundling traditional ball screw assemblies in high-speed packaging and inspection equipment.
Industry Challenges
- Precision grinding workforce:The specialized skill base for sub-micron surface finishing is aging in Germany and Japan without sufficient apprenticeship pipeline replacement.
- Multi-standard certification timelines:Simultaneous JIS, CE marking, and GB qualification processes extend product launch cycles by 18-24 months for global platform configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Linear Guide Market |
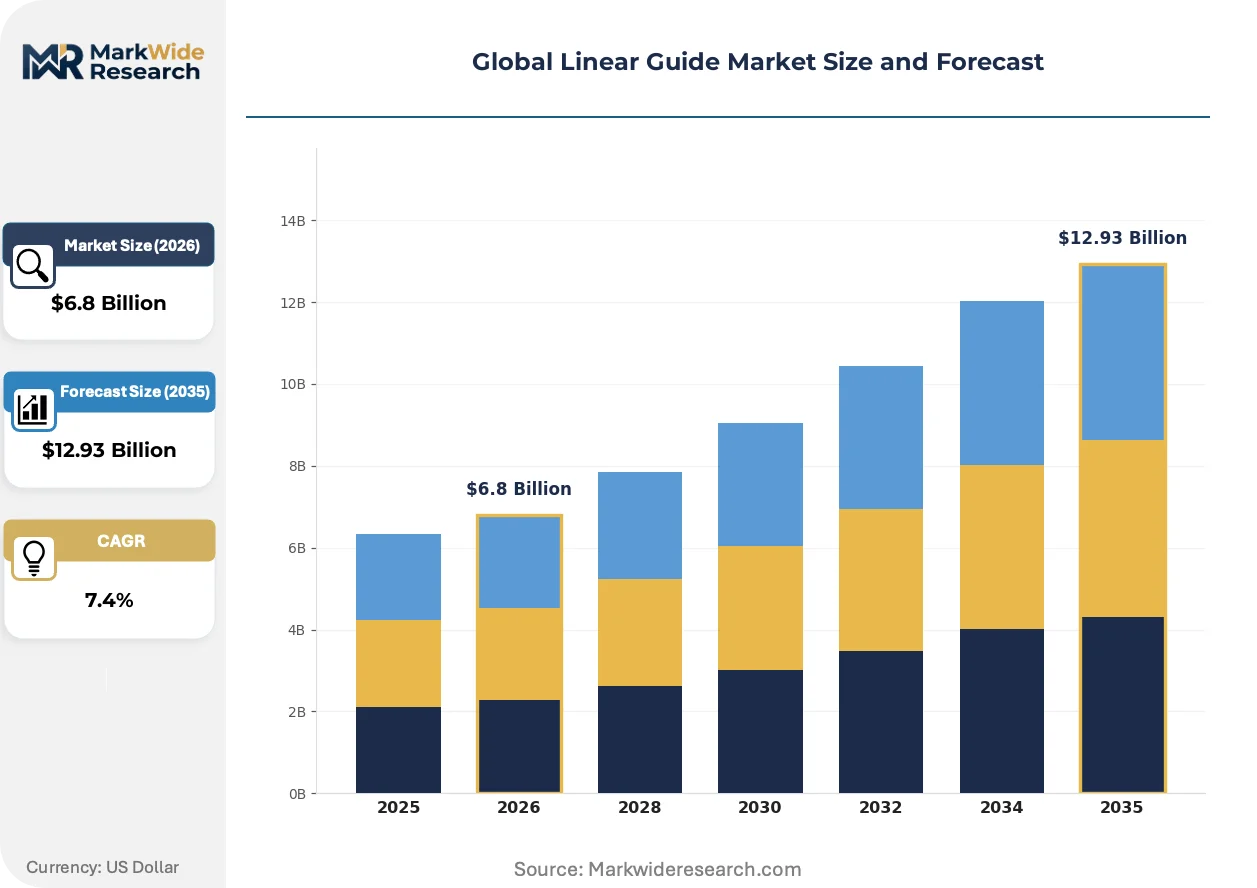
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Guide, Roller Guide, Magnetic Guide, Profile Guide Material: Aluminum, Steel, Plastic, Composite End User: Aerospace, Manufacturing, Robotics, Medical Installation Type: Pre-assembled, In-field Assembly, Standard Mount, Custom Mount |
| Companies Covered | THK, Hiwin, NSK, Bosch Rexroth, IKO, Schaeffler, Schneeberger Group, PMI, ZNT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Linear Guide Market Strategic Shifts
Motion system architectures are converging around integrated sensing and thermal compensation, collapsing the traditional separation between mechanical guidance and electronic control into unified smart rail platforms.
Monolithic ceramic carriage structures are unifying stiffness and thermal stability in a single material system. Semiconductor wafer handling equipment builders in Taiwan and South Korea are specifying these for vacuum-compatible stages. The technology is unifying previously separate vibration isolation and positioning functions into compact envelope designs.
REACH substance restrictions on chromium(VI) surface treatments are forcing conversion to trivalent chrome or thin-dense chrome alternatives. European machine tool rebuilders face coating adhesion and wear-life validation gaps during transition. German suppliers are responding with accelerated salt-spray and rolling-contact fatigue testing protocols to maintain CE marking compliance.
After-sales service unbundling is fragmenting the traditional bundled maintenance model. Automotive OEMs in Stuttgart and Wolfsburg are separating linear guide replacement from integrated axis service contracts, sourcing direct from component manufacturers. This pattern is most visible in Germany where fleet standardization enables volume direct procurement bypassing system integrators.
Global Linear Guide Market Segmentation
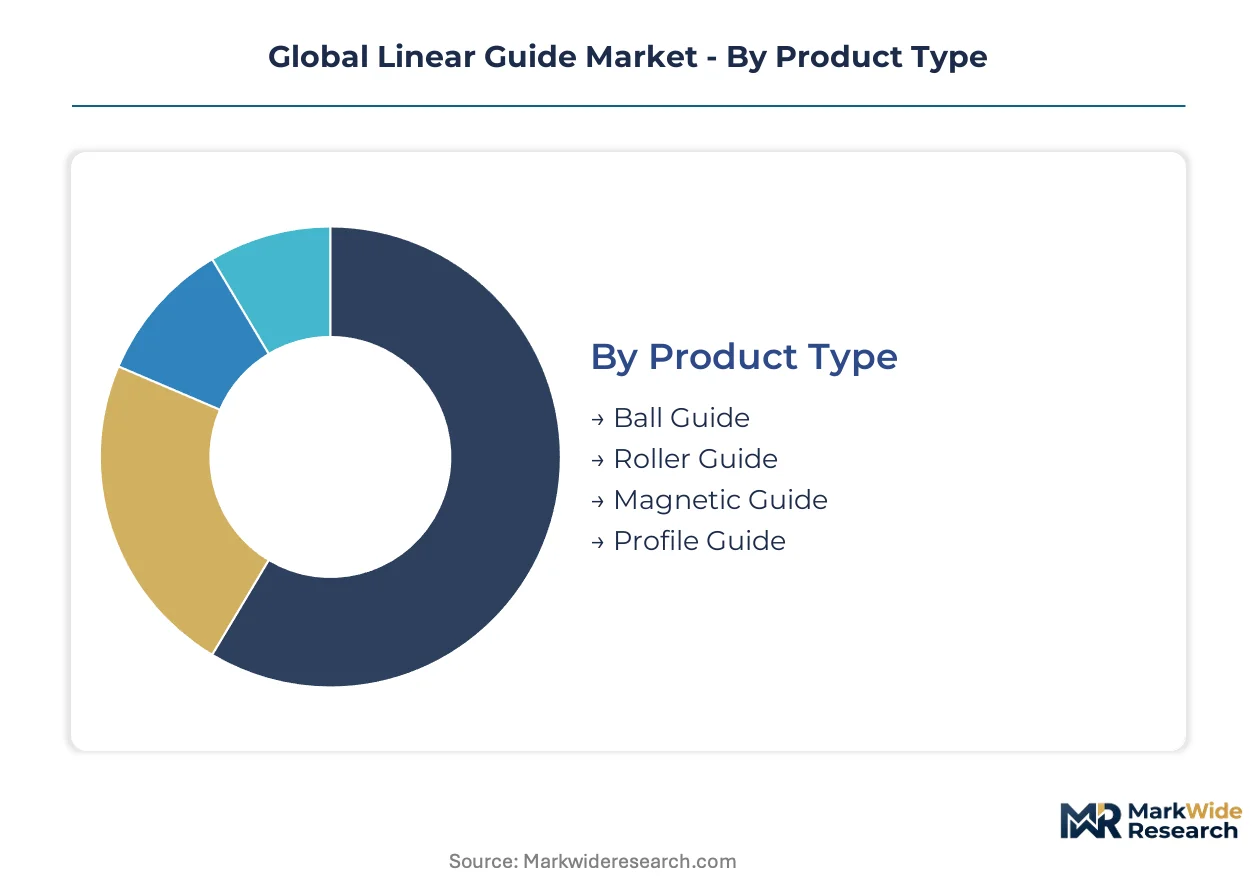
Linear guide procurement patterns diverge sharply across product grades, material specifications, and installation protocols. Semiconductor tool builders, automotive press manufacturers, and medical device OEMs each impose distinct qualification requirements that reshape supplier priorities across segments.
Product Type:
Supply concentration in precision grinding capacity favors established Japanese and German producers for high-accuracy grades, while standard automation applications support broader vendor participation.
- Ball Guide:Induction-hardened steel rails with recirculating ball carriages deliver micron-level repeatability across general automation. Stuttgart's automotive press builders specify these for high-cycle stamping lines where cost-efficiency outweighs absolute stiffness.
- Roller Guide:Cylindrical roller elements distribute heavy loads across extended contact surfaces, enabling machine tool builders in Baden-Württemberg to achieve the damping characteristics required for titanium aerospace machining.
- Magnetic Guide:Cleanroom-compatible levitation stages eliminate particle generation for sub-100-nanometer semiconductor positioning.
- Profile Guide:Cold-drawn aluminum extrusions serve light-load packaging and inspection equipment where rapid acceleration dominates load rating.
Ball guides absorb the bulk of installed capacity; magnetic guides are expanding most quickly.
Material:
Cost tiers separate premium bearing steel from commodity aluminum and engineered composites, with thermal stability requirements driving specification divergence across climate-controlled and shop-floor environments.
- Steel:Through-hardened bearing alloys from European and Japanese metallurgical suppliers anchor heavy-load machine tool and aerospace applications where elastic modulus and fatigue resistance are non-negotiable.
- Aluminum:Anodized extrusions dominate cleanroom automation and medical device manufacturing in Taiwan and South Korea, where magnetic compatibility and rapid thermal equilibration outweigh absolute stiffness.
- Plastic:Self-lubricating polymer carriages serve food-processing and chemical-exposure environments requiring corrosion immunity without external lubrication systems.
- Composite:Carbon-fiber-reinforced structures unify stiffness and thermal stability for vacuum-compatible semiconductor wafer handling stages.
Steel commands the premium pricing tier; aluminum scales fastest across emerging automation markets.
End User:
Customer-type concentration creates divergent certification burdens, with aerospace and medical segments imposing traceability requirements that exclude general industrial suppliers.
- Manufacturing:Automotive and electronics assembly operations in Germany and China drive volume demand for standard-grade ball guides with predictable replacement cycles.
- Robotics:Industrial robot OEMs in Japan integrate linear axes with harmonic drives and servo motors, requiring synchronized qualification across motion control architectures.
- Aerospace:AS9100 traceability mandates and NADCAP surface treatment validation restrict qualified suppliers for flight-control actuator and landing gear applications.
- Medical:ISO 13485 quality systems and biocompatibility requirements govern imaging equipment and surgical robot specifications in the US and EU.
Manufacturing absorbs the highest unit volumes; medical applications sustain the steepest expansion trajectory.
Installation Type:
Volume scale separates pre-assembled axis systems from field-configured components, with fleet standardization in German automotive enabling direct procurement bypassing integrators.
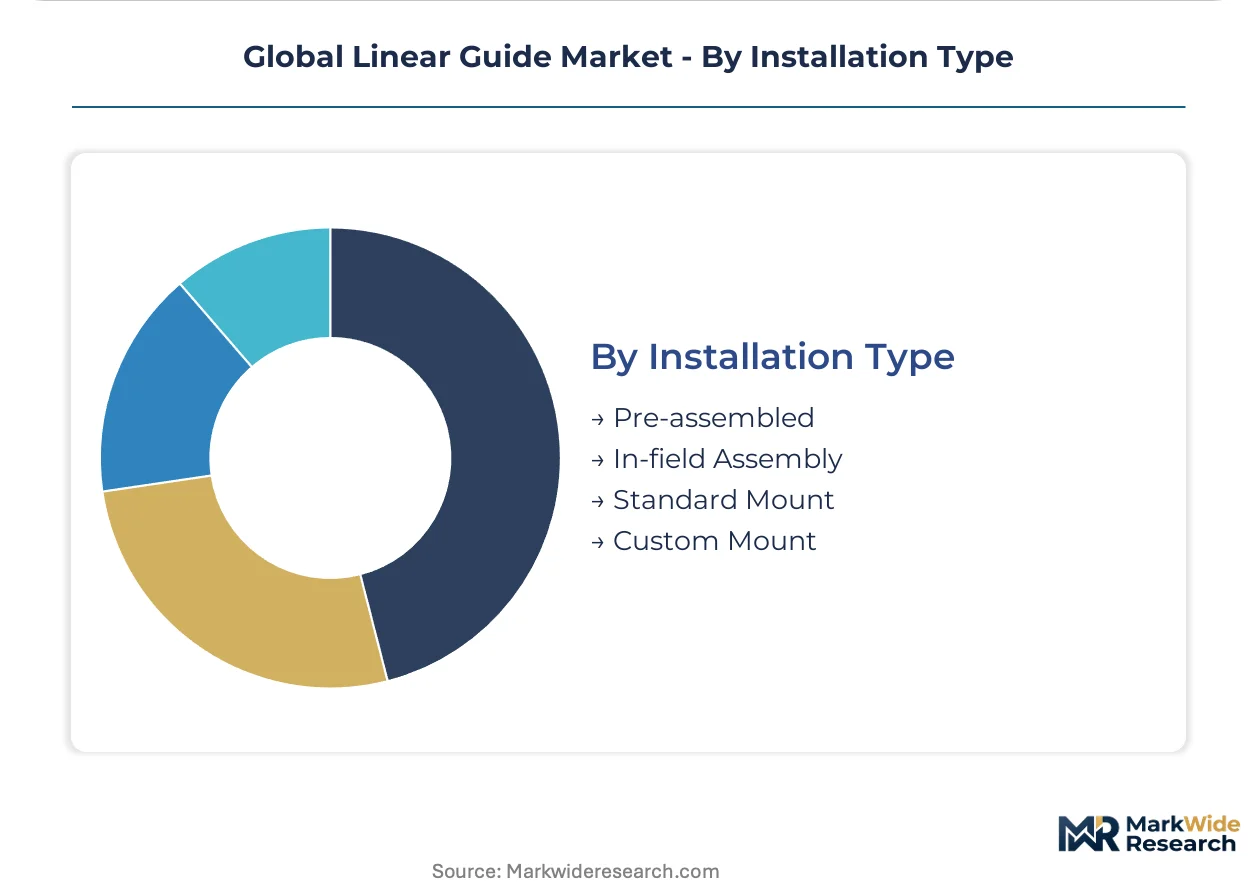
- Pre-assembled:Factory-aligned rail-carriage-motor assemblies reduce commissioning time for semiconductor tool builders requiring guaranteed positioning accuracy without field adjustment.
- In-field Assembly:Component-level procurement allows machine tool rebuilders to match specific rail lengths and carriage configurations to legacy equipment envelopes.
- Standard Mount:DIN-compliant hole patterns enable drop-in replacement across European automation infrastructure without mechanical redesign.
- Custom Mount:Application-specific rail geometries and carriage interfaces serve aerospace structural testing and specialized medical imaging platforms.
Pre-assembled systems dominate new equipment procurement; in-field assembly persists strongest in mature industrial economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in precision grinding centers across Germany and Japan, while consumption pulls from semiconductor fabrication clusters in Taiwan and South Korea and automotive automation corridors in China.
Germany
Baden-Württemberg's machine tool rebuilders and Stuttgart automotive press manufacturers sustain demand for heavy-load roller guides. The EU Machinery Directive through CE marking mandates functional safety validation for integrated linear axis systems. KBA vehicle-type approval processes in Wolfsburg and Munich tighten positioning accuracy requirements for electric powertrain assembly lines.
China
MIIT dual carbon goals accelerate replacement cycles in automotive and electronics manufacturing equipment. SAMR coordinates GB standard harmonization with IEC frameworks for motion control components entering industrial robot supply chains. Yangtze River Delta semiconductor foundries in Shanghai and Suzhou specify sub-micron positioning grades for wafer handling stages.
Japan
METI enforces JIS B 6330 standards for positioning accuracy that gate domestic OEM qualification for semiconductor tool builders. Captive supply of precision-ground ball screws enables integrated motion system architectures. Chubu region Nagoya-based industrial robot manufacturers synchronize linear axis qualification with harmonic drive and servo motor portfolios.
South Korea
MFDS medical device regulations and semiconductor cleanroom standards drive specification of magnetic-compatible aluminum guide systems. Busan-Ulsan manufacturing complexes integrate linear motion components into display panel automation. Daegu-Gyeongbuk machinery builders source vacuum-compatible stages for wafer inspection equipment.
United States
FAA AS9100 traceability mandates restrict qualified suppliers for flight-control actuator applications in aerospace corridors. OSHA machinery safety standards govern linear axis integration in automotive assembly operations. Pacific Northwest semiconductor equipment manufacturers and Southeast automotive clusters pull precision motion components through independent distributor networks.
Global Linear Guide Market Competitive Environment
Top-tier vendors anchor premium-grade precision segments, while mid-scale fabricators compete on standard automation volumes. Japanese and German producers dominate sub-micron qualification protocols through captive metallurgical supply and grinding capacity. Three strategic archetypes emerge: integrated motion system builders, precision grinding specialists, and scale-driven standard-grade manufacturers. Competitive moves center on backward integration into bearing steel supply and strategic partnerships with semiconductor equipment OEMs.
Within the integrated motion tier, THK Co., Ltd. and Bosch Rexroth AG exemplify architectures that unify linear guides with drive systems and control electronics. NSK Ltd. occupies a position bridging precision bearing heritage with automation-scale production. These entities represent how qualification depth in semiconductor and aerospace segments creates defensive positioning against commodity-grade competition.
| Leading Market Players |
|---|
| THK |
| Hiwin |
| NSK |
| Bosch Rexroth |
| IKO |
| Schaeffler |
| Schneeberger Group |
| PMI |
| ZNT |
| Others |
Value Chain & Pricing Dynamics
MIIT dual carbon mandates in China gate qualified supply and premium-tier pricing access by disqualifying energy-inefficient component suppliers from automotive and electronics manufacturing equipment procurement, compressing margins for non-compliant producers while elevating certified precision-grade suppliers into protected pricing tiers.
Pricing Analysis
Margin tightening in standard-grade ball guides reflects Hiwin's manufacturing scale in Taichung forcing cost-down pressure on European and Japanese competitors serving general automation. Three-tier pricing structure across precision-ground, induction-hardened, and cold-drawn grades separates semiconductor-qualified suppliers from machine tool rebuilders and packaging equipment builders. Price differentiation rests on JIS B 6330 certification tier and captive ball screw integration rather than raw material cost alone. Automotive press manufacturers in Stuttgart exhibit highest price sensitivity; semiconductor tool builders in Taiwan and South Korea prioritize positioning repeatability over unit cost.
Supply Chain Analysis
Refurbishment flows from German machine tool rebuilders and Japanese automotive press manufacturers are extending service life of heavy-load roller guides, creating secondary supply channels that compete with new equipment procurement. Precision grinding capacity concentrates in Germany and Japan; bearing steel metallurgy draws from European and Japanese suppliers. Raw material dependencies include induction-hardened bearing alloys, precision-ground ball screws, and ceramic carriage structures. Single-source vulnerability in specialized alloy supply exposes lead times to raw material allocation decisions. Distribution runs through OEM direct procurement in fleet-standardized German automotive and independent distributor networks in US semiconductor corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Japan's METI-enforced JIS B 6330 standards create a barrier-to-entry moat that protects qualified precision-grade suppliers from commodity competition.
For Market Incumbents: Hedge against magnetic levitation substitution in sub-100-nanometer semiconductor positioning by accelerating captive supply of precision-ground ball screws and ceramic carriage structures. Defensive consolidation through backward integration into bearing steel metallurgy in Germany and Japan protects margin pools from raw material allocation volatility. Channel control via direct procurement relationships with Stuttgart automotive OEMs bypasses integrator margin capture. For New Entrants and Emerging Players: GB-IEC harmonization under China's SAMR opens a window for first-time specification of standard-grade linear motion components in Yangtze River Delta industrial robot supply chains. White-space targets include India's PLI-scheme manufacturing automation and South Korea's Busan-Ulsan display panel equipment rebuilds. Go-to-market angle: aluminum profile guides for cleanroom-compatible medical device manufacturing in Taiwan and South Korea. For Investors and Strategic Acquirers: Workforce attrition in German and Japanese precision grinding is the leading indicator that consolidation opportunity is concentrating among mid-scale specialists with apprenticeship pipeline investments. Long-term viability frames around 5-10 year windows for precision-grade qualification depth rather than standard automation volume scale. Acquisition target archetype: regional precision grinding specialists with JIS B 6330 or AS9100 certification heritage. Signal to monitor: semiconductor equipment OEMs unbundling after-sales service contracts from integrated axis agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bearing Steel Supply | Mitigates raw material allocation risk from European and Japanese metallurgical suppliers. |
| GB-IEC Harmonization Certification Investment | Reduces duplication costs for motion control components entering Chinese industrial robot supply chains. |
| Ceramic Carriage Structure Development | Unifies stiffness and thermal stability for vacuum-compatible semiconductor wafer handling equipment. |
| Direct Procurement Channel Establishment | Bypasses system integrator margins in German automotive fleet standardization environments. |
| Precision Grinding Workforce Pipeline Investment | Defends against aging skill base attrition in Germany and Japan through apprenticeship programs. |
Study Parameters
Independent corroboration across semiconductor equipment OEM procurement leads, German automotive press manufacturer maintenance directors, and Japanese industrial robot builder engineering teams underwrites the qualitative findings. Primary interviews with precision grinding specialists, bearing steel metallurgy suppliers, and linear motion component distributors combined with secondary validation from METI JIS standard filings, MIIT energy-efficiency directives, and SAMR GB standard harmonization announcements. Bottom-up and top-down triangulation reconciles equipment builder procurement patterns with regional production capacity data.
Comparable-period anchoring to historical semiconductor capital expenditure cycles and automotive press automation replacement waves structures the projection horizon. Segmentation dimensions modeled include guide type (ball, roller, magnetic, profile), material specification (steel, aluminum, composite), end-use industry (semiconductor, automotive, aerospace, medical), and installation protocol (pre-assembled versus field-configured). CAGRs derive from equipment builder procurement intention surveys and regional manufacturing automation investment trajectories. Forecast inputs incorporate MIIT dual carbon mandate compliance timelines and JIS B 6330 qualification gate evolution.
The model assumes a particular technology adoption path; alternative pathways for magnetic levitation in sub-100-nanometer positioning would alter the outlook. Forecasts reflect assumptions around semiconductor fabrication equipment capital expenditure continuity and automotive electrification-driven press automation replacement cycles. Practitioners should monitor magnetic guide substitution rates in Taiwan and South Korea cleanroom applications and German precision grinding apprenticeship enrollment figures for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
Industrial Girth Gear Market
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Dump Tubs Market
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Heavy Hex Nuts Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Pipelayer Market