
 Conveyor Scales Market | 2026-2036
Conveyor Scales Market Size, Share, and Industry Trends Forecast 2026-2036
Conveyor Scales Market Analytics
The EU Green Deal's embodied carbon tracking requirements for bulk material handling is restructuring procurement priorities across European cement and aggregate processors. METTLER TOLEDO leverages its OIML-certified platform architecture to dominate high-precision installations in German packaging lines. Yamato Scale Co., Ltd. anchors Asian food-grade conveyor weighing through its hygienic design specialization and JIS-compliant manufacturing base.
Conveyor scales are continuous weighing instruments installed on belt conveyor systems to measure material mass flow rate, typically achieving accuracies of 0.25% to 1% of totalized load depending on belt speed, idler alignment, and load cell configuration. Their primary industrial purpose is real-time inventory management, process control, and trade-certified bulk material accounting in continuous production environments. Belt scales capture the largest installed base due to their integration into existing material handling infrastructure, while electromagnetic load cell technology leads growth as processors replace mechanical lever systems for improved drift stability and digital calibration. Mining and aggregate applications sustain the deepest replacement cycles, though Food & Beverage installations command premium pricing through stainless-steel construction and washdown compliance.
FDA food-contact material rules, NTEP Handbook 44 commercial weighing standards, and OIML R50 international belt conveyor scale regulations collectively determine product certification requirements and market access thresholds across major demand centers. The EPA's particulate monitoring mandates for coal and mineral processing indirectly drive precision weighing investments as operators optimize load-out volumes to minimize fugitive dust exposure. Stakeholders must weigh the capital cost of integrated modular installations against the operational risk of legacy mechanical systems failing emerging digital traceability audits.
Market Dynamics
The shift from mechanical lever systems to electromagnetic load cell technology is compressing replacement cycles across bulk material handling operations, as digital calibration protocols and drift stability requirements reshape capital planning priorities.
Growth Catalysts
- OIML R50 Certification Mandates:European cement processors are retrofitting existing installations to meet updated international belt conveyor scale regulations, creating forced upgrade demand across German packaging corridors.
- Coal Corridor Modernization:Chinese steel facilities and power generation infrastructure are deploying high-capacity belt scales to optimize throughput measurement in integrated material handling systems.
- EPA Particulate Controls:US mining operators are investing in precision load-out weighing to minimize fugitive dust exposure from bulk material transfer points, linking environmental compliance to weighing infrastructure.
Market Restraints
- Stainless Steel Input Volatility:Food-grade conveyor scale construction depends on austenitic steel grades subject to nickel price swings, compressing margins for hygienic design manufacturers serving dairy and meat processing.
- Load Cell Supply Concentration:Strain gauge production for precision electromagnetic systems concentrates among specialized German and Japanese component suppliers, exposing integrators to single-source risk.
- Mechanical System Persistence:Legacy lever-arm belt scales in Australian and Brazilian mining operations exhibit extended service lives, delaying replacement timelines despite superior digital alternatives.
Strategic Opportunities
- EU Green Deal Embodied Carbon Tracking:European aggregate and cement processors require certified mass flow data for Scope 3 emissions calculations, creating premium demand for OIML-certified installations with digital traceability.
- Food-Grade Washdown Convergence:Hygienic design specialization is opening pharmaceutical and nutraceutical applications beyond traditional protein processing, as JIS-compliant manufacturing protocols expand addressable verticals.
- Integrated Modular Retrofit Channels:System integrators are bundling conveyor scales with condition monitoring sensors and edge computing nodes, displacing standalone equipment procurement in brownfield mining sites.
Industry Challenges
- Field Calibration Expertise Scarcity:Electromagnetic load cell commissioning requires technicians proficient in digital signal processing and belt tension modeling, creating talent bottlenecks in remote mining regions.
- NTEP Commercial Certification Timelines:US trade-certified installations face extended approval cycles under Handbook 44 protocols, delaying revenue recognition for legal-for-trade bulk material accounting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conveyor Scales Market |
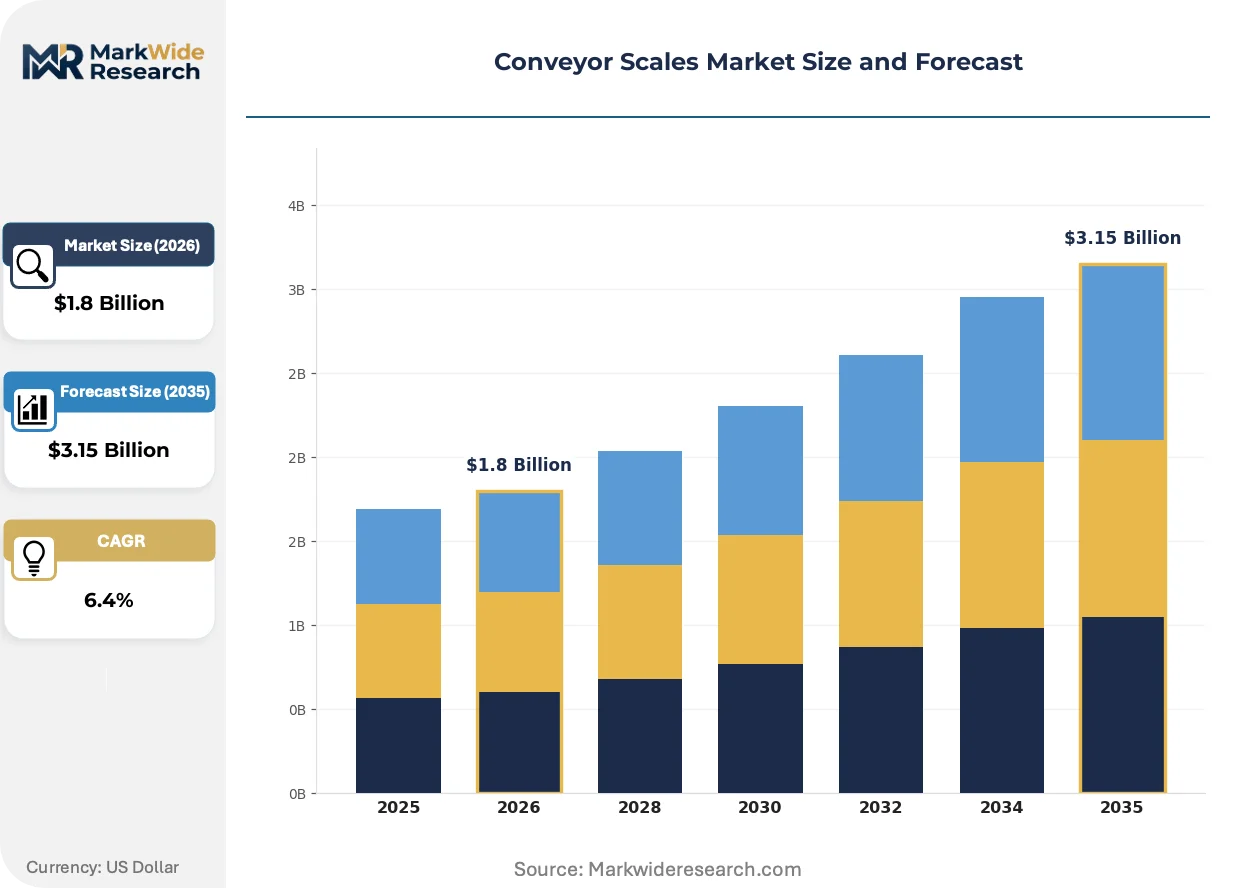
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dynamic Scales, Static Scales, Belt Scales, Load Cells End User: Manufacturing, Mining, Food & Beverage, Pharmaceuticals Installation: On-site, Off-site, Integrated, Modular Technology: Electromagnetic, Hydraulic, Mechanical, Pneumatic |
| Companies Covered | Siemens AG, METTLER TOLEDO, Rice Lake Weighing Systems, Thermo Fisher Scientific Inc., Schenck Process, Yamato Scale Co., Ltd., Merrick Industries, Thayer Scale, Avery Weigh-Tronix LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveyor Scales Market Evolving Landscape
Digital traceability architectures and edge-native weighing systems are restructuring how bulk material accountability flows through continuous production environments, compressing the gap between measurement and enterprise resource planning integration.
Electromagnetic load cell technology is electrifying conveyor scale architecture by eliminating mechanical pivot wear and enabling real-time drift compensation algorithms. Australian iron ore operators are adopting these systems at accelerated replacement cycles. The technology is electrifying competitive positioning among precision integrators by collapsing the historical accuracy gap between belt scales and static weighbridge verification.
REACH chemical substance restrictions and the EU Green Deal's embodied carbon disclosure requirements are forcing European cement and aggregate processors to document mass flow data at transfer points. Industrial consequence includes mandatory digital calibration records and blockchain-anchored certificates of conformity. German packaging lines and Dutch bulk terminals are responding by specifying OIML-certified platforms with integrated data logging as standard procurement criteria.
Buyer preference is gravitating toward performance-guaranteed service contracts that unbundle hardware capital expenditure from ongoing calibration and certification liability. System integrators are displacing traditional equipment vendors by assuming measurement accuracy risk and embedding predictive maintenance protocols. This contracting evolution is most visible in Chinese coal-handling corridors and integrated steel facilities where state-owned enterprises prioritize operational expenditure flexibility over asset ownership.
Conveyor Scales Market Segmentation
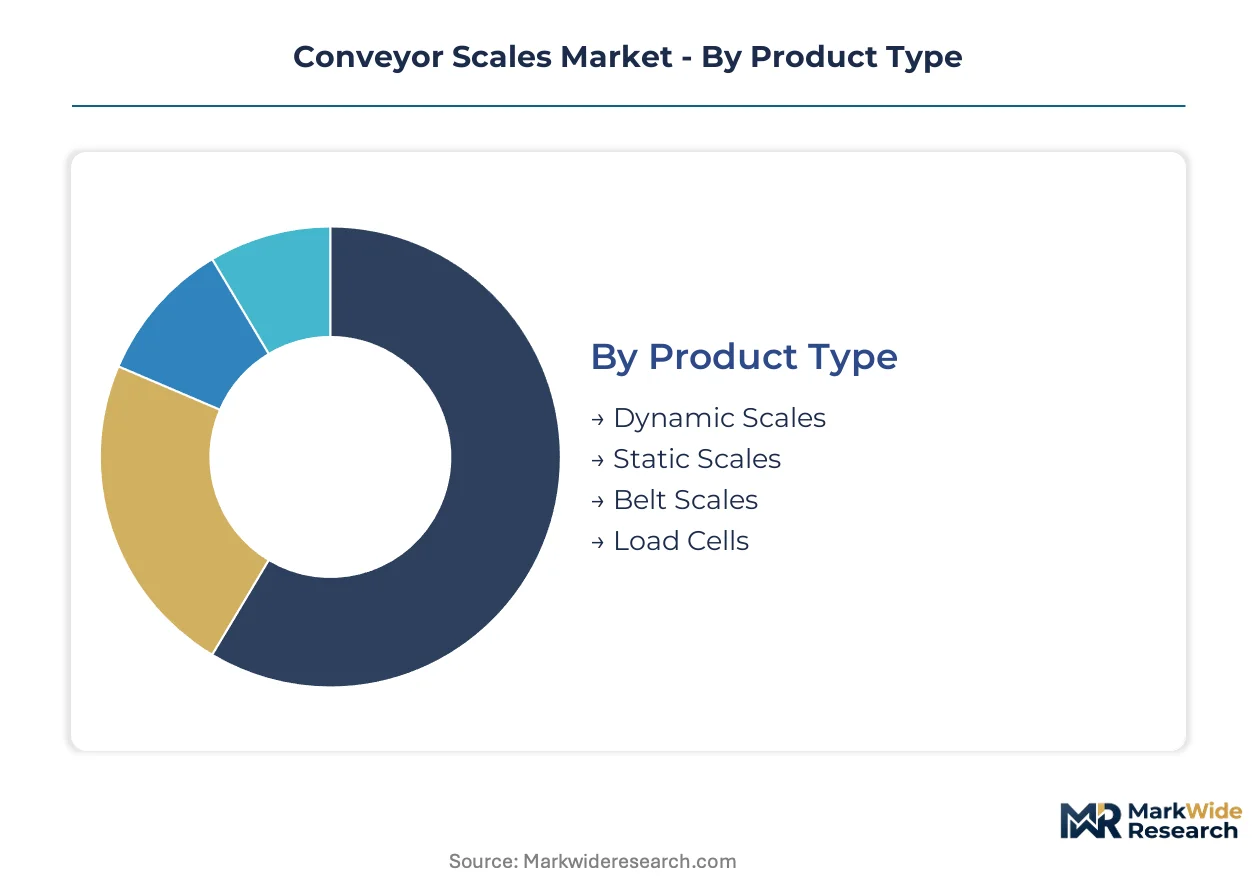
Segmentation in conveyor scales reveals how certification requirements, material specifications, and installation complexity fragment procurement patterns across bulk material handling operations. Each dimension carries distinct regulatory burdens that reshape vendor selection and capital allocation priorities.
Product Type:
OIML R50 certification mandates fall unevenly across product categories, with trade-certified belt scales facing the most stringent approval timelines while load cells navigate component-level conformity pathways.
- Belt Scales:Continuous weighing instruments integrated directly onto conveyor infrastructure, achieving 0.25% to 1% accuracy depending on belt speed and idler alignment. Australian iron ore operators and Brazilian mining corridors deploy these for real-time throughput measurement, driven by bulk material accounting requirements in export-oriented operations. Leading the category by volume: Belt Scales. Growing fastest: Load Cells.
- Load Cells:Strain gauge-based force transducers that convert mechanical load into electrical signals, forming the measurement core of electromagnetic scale architectures. German packaging lines and Dutch bulk terminals specify these for OIML-certified platforms requiring digital traceability under EU Green Deal embodied carbon tracking.
- Dynamic Scales:In-motion weighing systems capturing material mass without process interruption, common in high-speed sorting applications.
- Static Scales:Stationary weighing platforms requiring material stoppage, typically serving verification and calibration roles rather than continuous production integration.
Margin concentration follows certification intensity: belt scales and load cells command premium positioning through OIML and NTEP compliance, while static and dynamic variants compete on price in non-trade applications.
End User:
End-use segmentation maps directly to material exposure risks and washdown severity, with food-contact and pharmaceutical installations facing FDA and EFSA compliance layers absent in mining or general manufacturing.
- Mining:Surface and underground bulk material operations requiring explosion-proof configurations and extended temperature tolerance. Australian and Brazilian operators dominate installed base volume, though replacement cycles stretch longer than digital upgrade timelines would predict. Leading the category by volume: Mining. Expanding most quickly: Food & Beverage.
- Food & Beverage:Protein processing, dairy, and packaged goods operations demanding stainless-steel construction, IP69K washdown ratings, and hygienic design protocols. JIS-compliant manufacturing from Japanese suppliers anchors Asian demand, while European processors respond to EFSA material contact regulations.
- Manufacturing:General industrial material handling across automotive, chemical, and construction sectors, typically prioritizing cost efficiency over precision certification.
- Pharmaceuticals:Active ingredient and excipient weighing under GMP conditions, requiring validation documentation and cleanroom-compatible materials.
Customer concentration patterns show mining sustaining deepest replacement cycles, food and beverage commanding stainless-steel premiums, and pharmaceutical applications driving validation service bundling.
Installation:
Installation modality determines commissioning complexity and field calibration liability, with integrated and modular approaches increasingly displacing standalone procurement through performance-guaranteed contracting structures.
- Integrated:Scale systems embedded within complete material handling lines, requiring coordination with conveyor OEMs and controls integrators. Chinese coal-handling corridors and integrated steel facilities favor this approach for state-owned enterprise procurement flexibility. Leading the category by volume: Integrated. Gaining share fastest: Modular.
- Modular:Pre-engineered scale subsystems enabling rapid deployment and future reconfiguration, often bundled with condition monitoring sensors and edge computing nodes. System integrators leverage these for brownfield mining retrofits where operational expenditure flexibility outweighs asset ownership preferences.
- On-site:Custom-fabricated installations built to specific conveyor dimensions and material characteristics.
- Off-site:Factory-assembled scale modules delivered for drop-in replacement, minimizing production downtime during commissioning.
Procurement is shifting toward modular and integrated channels as operators seek to unbundle hardware capital expenditure from ongoing calibration and certification liability.
Technology:
Technology segmentation tracks the displacement of mechanical architectures by electromagnetic systems, with hydraulic and pneumatic alternatives retaining niche roles in hazardous or high-shock environments.
- Electromagnetic:Load cell-based measurement eliminating mechanical pivot wear and enabling real-time drift compensation through digital signal processing. Australian iron ore operators accelerate replacement cycles to capture accuracy improvements and predictive maintenance capabilities. Leading the category by volume: Electromagnetic. Steepest expansion trajectory: Electromagnetic.
- Mechanical:Lever-arm and pivot-based systems with extended service lives but inferior stability and calibration demands. Legacy installations in Australian and Brazilian mining operations persist despite digital alternatives, compressing near-term replacement revenue.
- Hydraulic:Fluid-pressure force transmission suited to explosive atmospheres and extreme shock loading where electrical components face restrictions.
- Pneumatic:Air-pressure-based measurement for specialized cleanroom or corrosive material handling with limited current deployment.
Technology migration favors electromagnetic architectures as processors replace mechanical lever systems for improved drift stability, digital calibration protocols, and enterprise resource planning integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara iron ore corridor anchors the heaviest belt scale deployment density globally, with Australian operators retrofitting legacy mechanical systems to meet export throughput verification standards.
United States
EPA particulate monitoring mandates for coal and mineral processing drive precision load-out weighing investments across Appalachian mining operations. NTEP Handbook 44 certification requirements force extended approval cycles for trade-certified installations, compressing vendor revenue recognition timelines. Powder River Basin coal terminals specify integrated modular systems to optimize bulk transfer point accountability.
Germany
OIML R50 international belt conveyor scale regulations compel cement and aggregate processors to retrofit existing packaging line infrastructure. EU Green Deal embodied carbon tracking requirements restructure procurement priorities toward certified mass flow data for Scope 3 emissions calculations. The Rhine-Ruhr industrial corridor dominates high-precision platform specification for bulk terminal operations.
China
State-owned enterprises in coal-handling corridors and integrated steel facilities prioritize operational expenditure flexibility over asset ownership, accelerating performance-guaranteed service contract adoption. SAMR metrology supervision and GB standards enforcement tighten calibration documentation requirements. Shanxi province coal basins deploy high-capacity belt scales for throughput optimization in power generation infrastructure.
Brazil
Iron ore export operations sustain extended replacement cycles for legacy lever-arm belt scales despite digital alternative availability. ANVISA industrial equipment regulations intersect with mining safety protocols for surface bulk material handling. The Carajás mineral province anchors South American installed base volume for continuous weighing instrumentation.
Australia
Iron ore operators accelerate electromagnetic load cell replacement cycles to capture predictive maintenance capabilities and real-time drift compensation. TGA-equivalent state-level measurement standards govern trade-certified export verification systems. Western Australian mining corridors concentrate the deepest retrofit demand as mechanical pivot wear drives digital architecture migration.
Conveyor Scales Market Competitive Landscape
The competitive structure tilts toward precision instrumentation specialists with OIML-certified platform architectures. Consolidation pressure concentrates among electromagnetic load cell integrators and hygienic design manufacturers serving divergent certification pathways. Three archetypes dominate: German precision engineering houses with metrology heritage, Japanese hygienic design specialists with JIS-compliant manufacturing bases, and North American modular system integrators bundling condition monitoring capabilities. M&A activity targets edge computing and digital calibration technology assets, while geographic expansion focuses on Chinese coal corridor and Australian iron ore retrofit channels.
Within the precision-metrology tier, METTLER TOLEDO and Siemens AG exemplify OIML-certified platform dominance in European packaging and process control applications. Yamato Scale Co., Ltd. occupies a distinct position anchoring Asian food-grade conveyor weighing through hygienic design specialization. Rice Lake Weighing Systems represents the North American modular integration archetype, with Schenck Process and Thermo Fisher Scientific Inc. situating within bulk material handling system bundling strategies. Avery Weigh-Tronix LLC and Thayer Scale exemplify mid-scale precision positioning across mining and aggregate verticals, while Merrick Industries anchors continuous weighing instrumentation for power generation and industrial minerals processing.
| Leading Market Players |
|---|
| Siemens AG |
| METTLER TOLEDO |
| Rice Lake Weighing Systems |
| Thermo Fisher Scientific Inc. |
| Schenck Process |
| Yamato Scale Co., Ltd. |
| Merrick Industries |
| Thayer Scale |
| Avery Weigh-Tronix LLC |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between OIML R50-compliant precision platforms and non-certified commodity belt scales splits procurement budgets across European cement packaging lines and Australian iron ore corridors, with supply chain configuration tracking this bifurcation through German-Japanese component concentration for premium tiers versus distributed Asian fabrication for baseline equipment.
Pricing Analysis
Outcome-guaranteed service contracts now anchor conveyor scale pricing, unbundling hardware capital expenditure from calibration liability and predictive maintenance bundling. Pricing stratifies across OIML-certified precision installations, NTEP-compliant trade systems, and non-certified operational monitoring tiers, with stainless-steel input volatility compressing margins for food-grade manufacturers. Cost compression in hygienic design segments intensifies because nickel price swings directly impact austenitic steel construction costs. Mining operators in Brazil and Australia exhibit lowest price sensitivity due to throughput verification requirements, while general manufacturing buyers prioritize capital efficiency over certification premiums.
Supply Chain Analysis
Dual-sourcing requirements for strain gauge load cells force electromagnetic scale integrators to qualify both German and Japanese component suppliers, mitigating single-source concentration risk. Manufacturing draws from Germany, Japan, and China, with precision metrology heritage anchoring European high-end output and JIS-compliant protocols governing Asian hygienic design production. Raw material dependencies center on nickel-bearing austenitic steels, semiconductor-grade strain gauges, and specialized signal conditioning electronics. Single-source vulnerability concentrates in specialized strain gauge production. Distribution runs through system integrators bundling condition monitoring and edge computing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
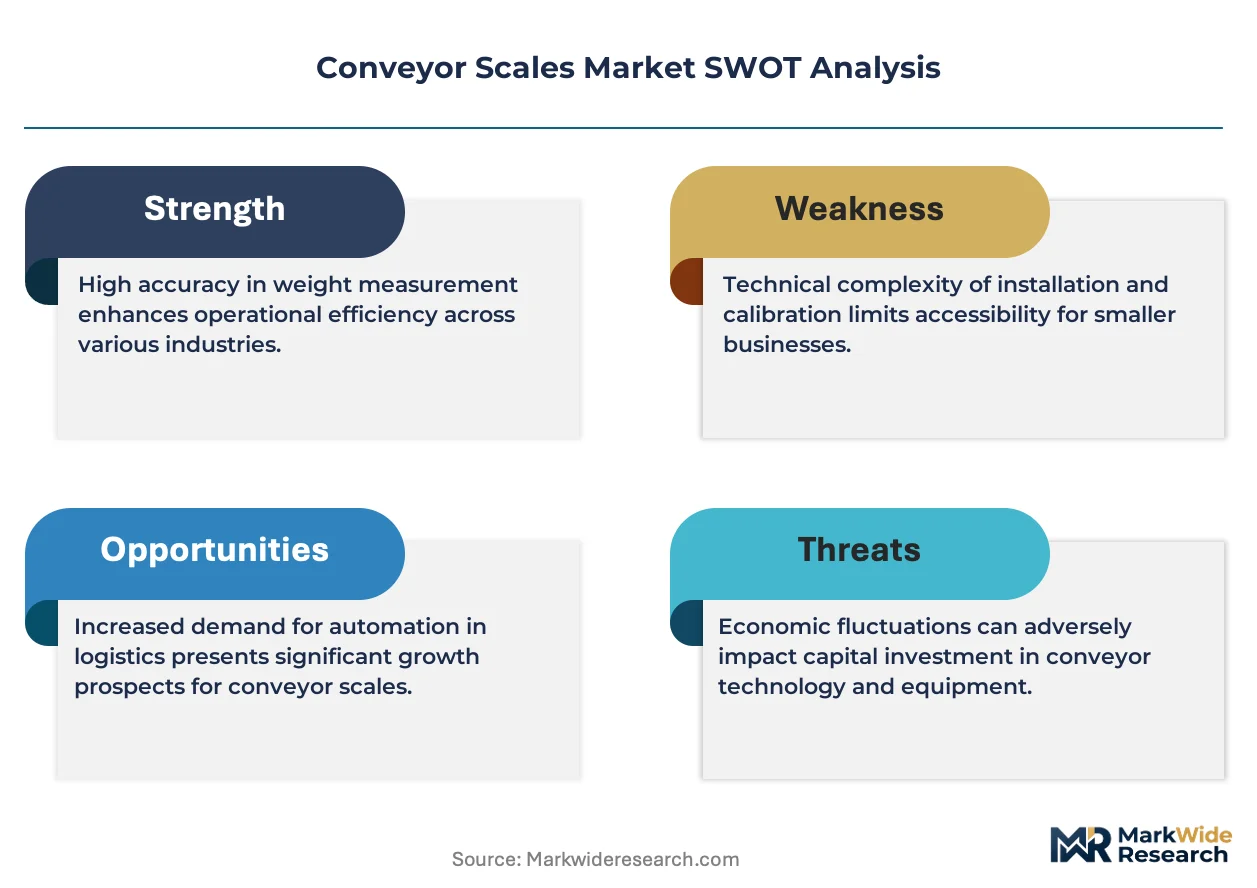
The conveyor scales market functions as a vertical-integration race where electromagnetic load cell technology and digital calibration IP represent the decisive upstream levers. Players capturing these capabilities collapse the accuracy gap between belt scales and static weighbridge verification.
For Market Incumbents: Anchor market position through captive control over strain gauge supply relationships and OIML-certified platform architectures. Defensive consolidation should target edge computing assets that enable predictive maintenance bundling, countering modular system integrators displacing standalone equipment vendors. Certification investment in EU Green Deal traceability protocols creates switching costs against emerging digital-native competitors.
For New Entrants and Emerging Players: Cloud-based calibration-as-a-service platforms offer the lowest-friction entry vector into brownfield mining retrofit channels where field expertise scarcity creates incumbent vulnerability. White-space targets concentrate in pharmaceutical nutraceutical applications beyond traditional protein processing, and in Chinese state-owned enterprise procurement seeking operational expenditure flexibility. Go-to-market should leverage performance-guaranteed contracting structures that assume measurement accuracy risk.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision-metrology specialists with OIML platform dominance and hygienic design manufacturers with JIS-compliant production bases. Long-term viability favors electromagnetic architecture integrators over mechanical lever system incumbents facing compressed replacement timelines. Watch for inflection in Australian iron ore corridor retrofit velocity as drift compensation algorithms prove operational reliability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Gauge Production | Captive supply of precision force transducers insulates margins from Japanese-German component concentration. |
| OIML R50 Certification Investment | Regulatory compliance unlocks EU Green Deal embodied carbon tracking premiums in German packaging corridors. |
| Edge Computing Platform Development | Real-time drift compensation algorithms differentiate electromagnetic architectures from mechanical lever systems. |
| Performance-Guaranteed Service Contract Expansion | Revenue model shift aligns with Chinese state-owned enterprise preference for operational expenditure flexibility. |
| Hygienic Design Protocol Extension | JIS-compliant manufacturing expansion opens pharmaceutical and nutraceutical verticals beyond food processing. |
Research Methodology
Independent corroboration across plant engineers at Australian iron ore operations, procurement leads at German cement packaging facilities, and aftermarket service heads at Chinese coal-handling corridors underwrites the qualitative findings. Secondary validation draws from OIML R50 certification registries, SAMR metrology supervision filings, EPA particulate monitoring compliance databases, and SEC disclosures from listed precision instrumentation suppliers. Bottom-up segmentation modeling triangulates against top-down demand aggregation across mining, food and beverage, and pharmaceutical verticals.
Decomposition of replacement cycle acceleration, certification mandate timelines, and technology migration rates structures the analytical framework across the projection horizon. Segmentation dimensions span product type, end-use industry, installation modality, and technology architecture. CAGRs derive from installed base turnover analysis and upgrade intensity coefficients. Industry-specific forecast inputs include nickel price trajectory impacts on stainless-steel construction costs and NTEP Handbook 44 approval cycle durations for US trade-certified installations.
Inputs from electromagnetic load cell manufacturers and system integrators were available through the study window; gaps in legacy mechanical system retirement timelines introduce uncertainty bands around replacement revenue timing. Deviation in EPA enforcement intensity or EU Green Deal Scope 3 disclosure deadlines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
Torque Limiting Couplings Market
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Industrial Jacks Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Global Industrial Lifting Equipment Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Autonomous Material Handling Equipment Market
Material Handling Equipment
Hook Lifts and Skip Loaders Market
Material Handling Equipment
Flux Spraying Machine Market