
 Apron Feeder Market | 2026-2036
Apron Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Apron Feeder Market Analysis
Australia is rewriting capacity dynamics for apron feeder supply chains as mining infrastructure investment climbs across the Pilbara and Bowen Basin. Sandvik AB leverages its underground hard-rock specialization to sustain premium positioning in heavy-duty segments. thyssenkrupp AG anchors European demand through integrated steel-and-mining equipment portfolios. Metso Corp. competes aggressively on aftermarket services and wear-part lifecycle contracts.
An apron feeder is a mechanical conveying device employing interlinked steel pans mounted on roller chains to transport heavy, abrasive bulk materials at controlled feed rates, typically handling lump sizes exceeding 1,500 mm and throughput capacities above 10,000 tph. Its primary industrial purpose centers on extracting raw materials from hoppers or bins and delivering uniform feed streams to crushers, screens, or processing plants in continuous mining and aggregate operations. Heavy-duty apron feeders dominate margin pools in copper and iron ore applications where extreme abrasion resistance commands premium pricing, while electric drive technology captures fastest-growing preference as sites phase out hydraulic systems for energy efficiency compliance. Standard apron feeders retain mature, price-sensitive demand in construction aggregate yards where replacement cycles stretch beyond fifteen years.
OSHA machinery guarding standards and EPA emissions frameworks in the United States compel retrofit investments in enclosed electric drive systems, while REACH and CE marking requirements in Europe restrict hazardous lubricants and mandate interoperability documentation for cross-border equipment sales. China's GB standards and MEE environmental enforcement push domestic manufacturers toward heavier pan constructions and dust-suppression integration. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven cost escalations that could reshape supplier qualification criteria.
Market Dynamics
Electric drive retrofits are compressing the installed base of hydraulic apron feeders as mining operators face dual pressures from EU Green Deal mandates and site-level decarbonization targets. This technology substitution is redrawing capital allocation patterns across heavy-duty bulk material handling.
Growth Catalysts
- EU Green Deal machinery directives:Stricter safety and emissions standards are compelling European mining and aggregate operators to replace legacy hydraulic systems with enclosed electric drives, accelerating replacement cycles in Germany's lignite sector and Scandinavia's iron ore belt.
- Australia Pilbara iron ore expansion:Rio Tinto and BHP are deploying heavy-duty apron feeders at new 50-million-tonne-per-annum hubs, creating sustained demand for abrasion-resistant pan constructions and integrated sizer-feeder packages.
- China Shanxi coal belt modernization:Provincial state-owned enterprises are consolidating small mines into mega-complexes, mandating bulk material handling upgrades that specify heavy-duty apron feeders for raw coal extraction and blending operations.
Market Restraints
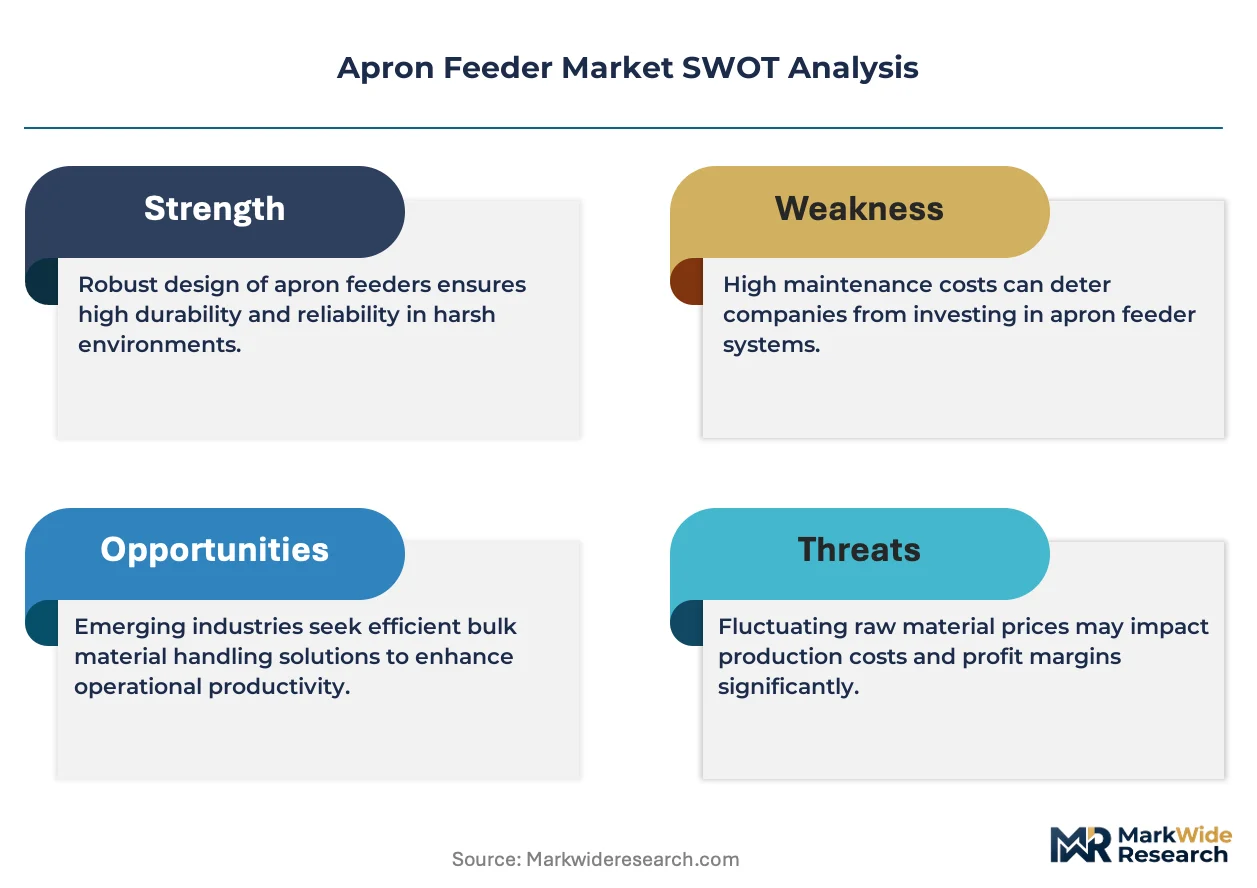
- High-grade manganese steel input costs:Pan and chain fabrication depends on specialized wear-resistant alloys whose prices fluctuate with South African and Gabonese ore export constraints, compressing fabricator margins on fixed-price contracts.
- European supplier concentration:Integrated steel-and-equipment portfolios at thyssenkrupp AG and limited alternative sourcing for forged chain links create bottleneck risks for large-scale project deliveries.
- Hydraulic system lock-in:Existing mines with fifteen-to-twenty-year hydraulic feeder depreciations face stranded asset calculations that delay electric conversion decisions despite regulatory pressure.
Strategic Opportunities
- India's captive mining expansion:Steel Ministry PLI scheme incentives for iron ore self-sufficiency are driving greenfield mine development in Odisha and Chhattisgarh, opening demand for apron feeder packages in previously import-dependent segments.
- Predictive maintenance convergence:Vibration sensor arrays and edge computing analytics are enabling remote condition monitoring contracts that transform capital equipment sales into recurring revenue streams.
- Underground hard-rock automation:Autonomous loading and haulage systems in Chilean copper and Canadian potash operations require synchronized apron feeder controls, creating specification pull-through for integrated OEM solutions.
Industry Challenges
- Welding technician scarcity:Fabrication of heavy-duty pan assemblies requires certified ASME and EN 287 welders, with labor shortages in Poland and Czech Republic extending delivery lead times for European projects.
- Legacy control system integration:Mines running 1990s-era PLC architectures face protocol incompatibility when retrofitting modern variable frequency drives, requiring costly intermediate gateway hardware and commissioning delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apron Feeder Market |
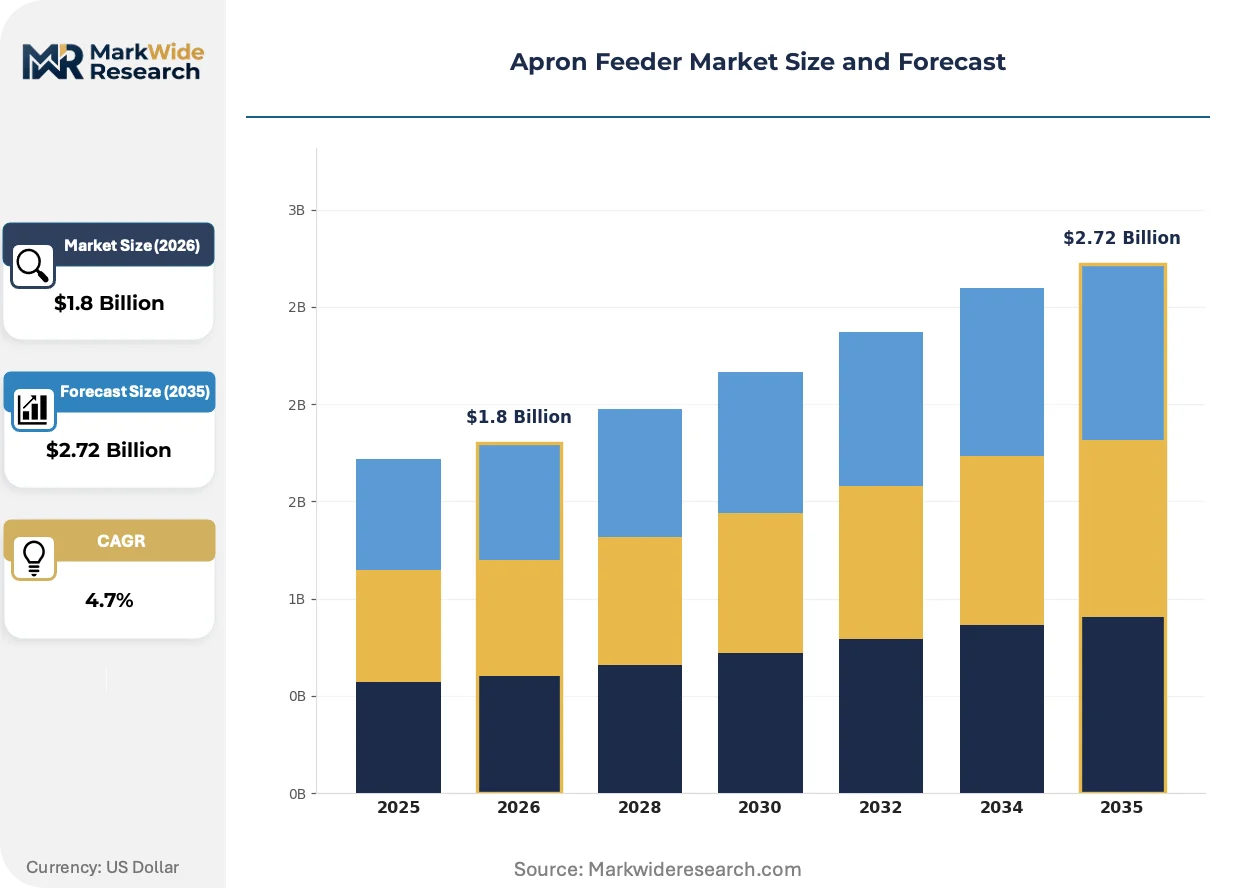
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-duty Apron Feeders, Standard Apron Feeders, Low-profile Apron Feeders, Multiple-drive Apron Feeders End User: Mining, Construction, Energy, Agriculture Technology: Hydraulic Systems, Electric Drives, Pneumatic Drives, Mechanical Drives Application: Bulk Material Handling, Ore Processing, Aggregate Handling, Waste Management |
| Companies Covered | Sandvik AB, MMD GPHC Ltd., FLSmidth A/S, Terex Corp., N.M. Heilig B.V., McLanahan Corp., thyssenkrupp AG, MDS International, Metso Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apron Feeder Market Emerging Trajectories
Digitalization and electrification are converging to transform apron feeder architecture from mechanical reliability systems into data-generating nodes within integrated mine automation networks.
Permanent magnet synchronous motor technology is collapsing the efficiency gap that once justified hydraulic power transmission in high-torque extraction applications. Copper and iron ore operators in Western Australia and northern Sweden are specifying direct-drive electric configurations for new installations, eliminating hydraulic oil contamination risks and enabling precise feed rate modulation through variable frequency drives. The technology is collapsing the historical trade-off between torque density and energy efficiency that shaped feeder architecture decisions for three decades.
REACH restrictions on hazardous lubricants and the EU Green Deal's embodied carbon reporting requirements are forcing pan and chain manufacturers to reformulate grease specifications and document full lifecycle environmental footprints. German and Finnish fabricators are investing in water-based quenching processes and recycled steel feedstocks to maintain CE marking eligibility for cross-border sales. Heavy-duty segments serving abrasion-intensive copper applications face the steepest compliance cost escalations due to thicker material specifications and extended wear-life guarantees.
Lifecycle contracting is displacing transactional equipment procurement as mining operators seek to outsource reliability risk to OEMs. Sandvik AB and Metso Corp. are unbundling traditional sales into performance-based agreements covering wear parts, remote monitoring, and guaranteed availability thresholds, with contracts spanning ten-to-fifteen-year operational periods. This restructuring is most advanced in Chilean copper and Pilbara iron ore, where concentrator operators prioritize throughput continuity over capital ownership.
Apron Feeder Market Segmentation
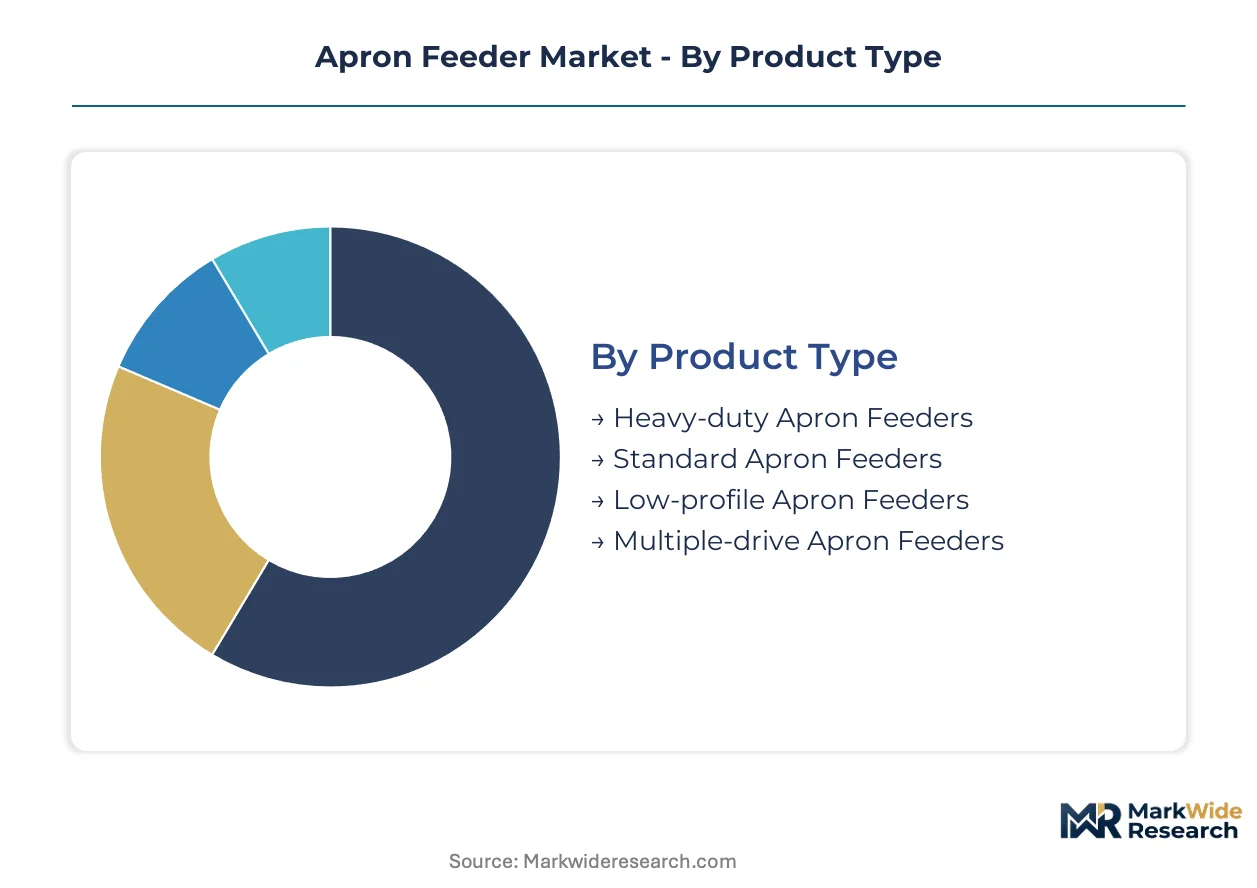
Apron feeder procurement patterns diverge sharply across duty ratings, end-use abrasiveness, and power transmission architectures. Buyers in copper extraction and iron ore transport prioritize fundamentally different specifications than aggregate yard operators, fragmenting supplier portfolios across incompatible performance tiers.
Product Type:
Mature heavy-duty designs dominate capital allocation in extreme abrasion environments, while emerging configurations reshape electrification pathways and space-constrained installations.
- Heavy-duty Apron Feeders:Pan assemblies utilize manganese steel castings exceeding 40 mm thickness with forged alloy roller chains rated for 15,000+ tph. Australia's Pilbara iron ore hubs and Chilean copper concentrators specify these for direct loading from 200-tonne haul trucks, where pan replacement intervals determine total cost of ownership calculations.
- Standard Apron Feeders:Moderate-duty pan constructions handle lump sizes below 800 mm in construction aggregate and cement limestone applications. European quarry operators favor these for fifteen-to-twenty-year replacement cycles where capital constraints outweigh throughput maximization priorities.
- Low-profile Apron Feeders:Compact vertical envelopes suit underground hard-rock headings with restricted headroom. Canadian potash and South African platinum mines deploy these for extraction from shallow bins where conventional feeder geometry conflicts with stope access.
- Multiple-drive Apron Feeders:Distributed power modules enable precise torque control across extended feeder lengths exceeding 30 meters. Chinese Shanxi coal belt mega-complexes specify these for blending yard applications requiring variable discharge rates to parallel processing lines.
Heavy-duty apron feeders handle the majority of throughput; multiple-drive configurations are expanding most quickly on share as distributed power architectures displace single-point mechanical transmissions.
End User:
Application-driven cost structures separate capital-intensive extraction industries from price-sensitive material handling operations.
- Mining:Copper, iron ore, and coal extraction commands premium pan specifications with guaranteed wear-life contracts. Rio Tinto and BHP procurement frameworks prioritize availability thresholds over initial capital expenditure, locking in OEM service partnerships across decade-long operational periods.
- Construction:Aggregate and cement limestone operations drive volume demand for standardized pan geometries with minimal customization. Replacement cycles stretch beyond twenty years in mature North American and European quarry markets, compressing aftermarket revenue pools for suppliers.
- Energy:Lignite and biomass co-firing applications in Germany and Poland require dust-suppression integration and spark-resistant drive enclosures. EU Green Deal emissions frameworks are accelerating electric retrofits in this segment ahead of pure mining applications.
- Agriculture:Fertilizer handling and grain port terminals specify corrosion-resistant pan coatings and washdown-compatible drive housings. Brazilian phosphate and Saudi potash export facilities dominate procurement in this category.
Mining commands the dominant share of heavy-duty procurement; energy sector retrofits are climbing fastest as decarbonization mandates compress replacement timelines.
Technology:
Power transmission architectures are bifurcating between legacy hydraulic lock-in and emerging electric efficiency standards.
- Hydraulic Systems:High-torque radial piston motors and closed-loop hydrostatic transmissions retain installed base dominance in 1990s-era copper and iron ore operations. Stranded asset calculations delay conversion despite regulatory pressure, particularly in African and Southeast Asian mines with extended depreciation schedules.
- Electric Drives:Permanent magnet synchronous motors with variable frequency drives eliminate hydraulic oil contamination risks and enable precise feed rate modulation. Northern Sweden's iron ore belt and Western Australia's newest Pilbara hubs specify these for direct-drive configurations that collapse historical efficiency gaps.
- Pneumatic Drives:Compressed air power transmission survives in underground coal applications with strict explosion-proofing requirements. Chinese state-owned enterprises maintain limited procurement for gassy mine headings where electrical spark suppression remains technically challenging.
- Mechanical Drives:Gearbox and chain-drive configurations persist in small-scale aggregate operations with minimal automation requirements. Indian captive mining expansion favors these for initial cost minimization in greenfield Odisha iron ore developments.
Electric drives are overtaking hydraulic systems on new installations; mechanical drives retain residual share in emerging economy price-sensitive procurement.
Application:
Material characteristics and process integration requirements dictate incompatible feeder specifications across downstream operations.
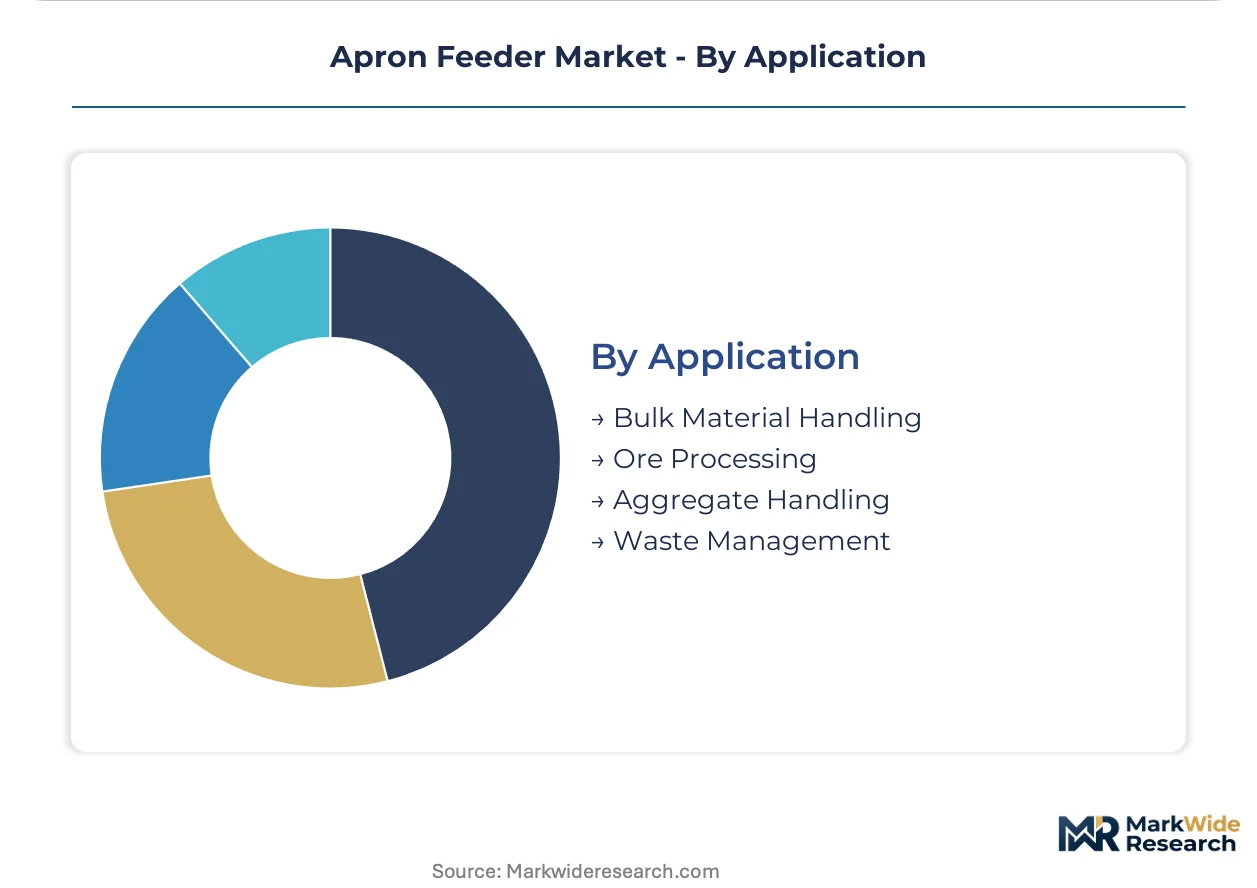
- Bulk Material Handling:Raw coal extraction and run-of-mine ore reception demand maximum abrasion resistance with minimal maintenance access requirements. China's provincial mine consolidation into Shanxi mega-complexes is standardizing specifications across previously fragmented state-owned enterprise procurement.
- Ore Processing:Crusher feed and concentrator blending applications require synchronized controls with upstream haulage and downstream grinding circuits. Chilean copper operators specify integrated sizer-feeder packages from single OEMs to guarantee throughput continuity.
- Aggregate Handling:Construction material screening and washing plants prioritize simple pan geometries with rapid wear-part replacement. European quarry automation trends are introducing basic vibration monitoring, though full predictive maintenance penetration lags mining applications significantly.
- Waste Management:Municipal solid waste and construction debris recycling specifies reinforced pan edges and tramp metal detection integration. German and Nordic circular economy infrastructure expansion is creating specification pull-through for specialized corrosion-resistant alloys.
Bulk material handling absorbs the largest equipment volume; ore processing applications are gaining specification intensity fastest as concentrator automation demands tighter feeder integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE environmental enforcement in China anchors the dominant geography for apron feeder procurement, with Australia's Pilbara expansion and EU Green Deal mandates creating parallel demand centers across three continents.
Australia
Rio Tinto and BHP are deploying heavy-duty apron feeders at new 50-million-tonne-per-annum hubs in the Pilbara. TGA machinery safety standards govern equipment certification for cross-state mining operations. Western Australia's iron ore belt concentrates procurement for abrasion-resistant pan constructions and integrated sizer-feeder packages.
China
Provincial state-owned enterprises in Shanxi Province are consolidating small mines into mega-complexes requiring bulk material handling upgrades. GB standards and MEE environmental enforcement push domestic manufacturers toward heavier pan constructions and dust-suppression integration. The Shanxi coal belt dominates capital spending for raw coal extraction and blending operations.
Germany
Lignite sector operators face compressed replacement timelines under EU Green Deal machinery directives compelling electric drive retrofits. REACH restrictions on hazardous lubricants and CE marking requirements restrict cross-border equipment sales without full lifecycle documentation. The Rhineland mining region anchors European demand for enclosed electric drive systems.
United States
OSHA machinery guarding standards and EPA emissions frameworks compel retrofit investments in enclosed electric drive systems across copper and iron ore operations. Stranded asset calculations delay conversion at mines with fifteen-to-twenty-year hydraulic feeder depreciations. Arizona's copper concentrators and Minnesota's iron ranges concentrate specification activity.
India
Steel Ministry PLI scheme incentives for iron ore self-sufficiency are driving greenfield mine development in Odisha and Chhattisgarh. BIS certification requirements and CEA electrical safety standards govern equipment qualification for captive mining expansion. Odisha's emerging iron ore developments open demand for apron feeder packages in previously import-dependent segments.
Apron Feeder Market Vendor Landscape
Integrated mining-equipment conglomerates and specialized bulk-material handling fabricators split the market between premium lifecycle-contracting positions and price-sensitive project procurement. The vendor base concentrates around three strategic archetypes: European steel-and-equipment integrators with forged-chain supply control, Nordic hard-rock specialists with underground automation expertise, and diversified process-equipment OEMs with aftermarket service networks. Competitive moves center on ten-to-fifteen-year performance-based contracting and predictive maintenance capability integration.
Among European integrated portfolios, thyssenkrupp AG occupies a position exemplifying steel-and-equipment convergence, while Sandvik AB and Metso Corp. represent contrasting archetypes of hard-rock specialization versus diversified process-equipment breadth. The Swedish and Finnish companies anchor Nordic competitive positioning through differentiated service-contracting structures.
| Leading Market Players |
|---|
| Sandvik AB |
| MMD GPHC Ltd. |
| FLSmidth A/S |
| Terex Corp. |
| N.M. Heilig B.V. |
| McLanahan Corp. |
| thyssenkrupp AG |
| MDS International |
| Metso Corp. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's domestic apron feeder fabrication base compresses margins for export-oriented suppliers while concentrating pricing power with integrated European steel-and-equipment conglomerates. Utilization differentials between Shanxi Province's state-owned mega-complexes and fragmented Indian fabricators reshape procurement negotiations across the Asia-Pacific mining belt.
Pricing Analysis
Geographic price spreads between European CE-marked heavy-duty units and Chinese GB-standard equipment exceed thirty percent on equivalent throughput specifications. Three-tier pricing structure across premium lifecycle-contracting, standard project procurement, and economy mechanical-drive tiers dominates procurement frameworks. Cost compression in the economy tier intensifies because Indian captive mining expansion favors initial capital minimization over wear-life guarantees. Construction aggregate operators exhibit highest price sensitivity, while Pilbara iron ore concentrators prioritize availability thresholds over capital expenditure.
Supply Chain Analysis
Upstream manganese steel feedstock draws from South African and Gabonese ore export channels, with forging capacity concentrating in Germany, Poland, and China's Shanxi industrial corridor. Specialized wear-resistant alloys, forged alloy roller chains, and permanent magnet synchronous motor assemblies constitute critical component dependencies. Single-source vulnerability around forged chain link fabrication at thyssenkrupp AG creates bottleneck risks for large-scale project deliveries. Distribution runs through OEM-direct lifecycle contracting for mining majors and regional fabricator networks for construction aggregate procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric drive substitution threatens hydraulic system incumbents with stranded asset exposure, compelling defensive repositioning around service-contracting architectures and predictive maintenance integration.
For Market Incumbents: Build switching-cost moats through ten-to-fifteen-year performance-based availability contracts that embed remote condition monitoring and guaranteed wear-part replacement. Sandvik AB and Metso Corp. demonstrate this trajectory in Chilean copper and Pilbara iron ore, where concentrator operators outsource reliability risk to OEMs. Backward integration into forged chain fabrication secures supply continuity against thyssenkrupp AG's bottleneck dominance. For New Entrants and Emerging Players: Pursue white-space penetration in India's Odisha and Chhattisgarh greenfield iron ore developments, where Steel Ministry PLI scheme incentives create first-mover opportunities in previously import-dependent captive mining. Mechanical-drive configurations for price-sensitive initial procurement offer the most penetrable entry wedge. Target aftermarket service partnerships with provincial state-owned enterprises in China's Shanxi coal belt modernization, where bulk material handling upgrades outpace domestic predictive maintenance capability. For Investors and Strategic Acquirers: Long-term, this sits as a cyclical infrastructure replacement play because mining decarbonization mandates and EU Green Deal machinery directives compress replacement timelines for legacy hydraulic systems. Acquisition targets should cluster around specialized vibration sensor array developers and edge computing analytics platforms that enable remote condition monitoring contracts. Watch electric drive retrofit penetration rates in Germany's lignite sector as the inflection signal for broader European replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Contracting Unbundling | Transforms capital equipment sales into recurring revenue streams through guaranteed availability thresholds. |
| Predictive Maintenance Platform Acquisition | Integrates vibration sensor arrays and edge computing analytics for remote condition monitoring contracts. |
| Electric Drive Retrofit Certification | Secures CE marking eligibility under EU Green Deal machinery directives for enclosed drive systems. |
| Forged Chain Fabrication Backward Integration | Captive supply of specialized wear-resistant alloys mitigates South African ore export constraint exposure. |
| Underground Hard-Rock Automation Partnership | Synchronizes apron feeder controls with autonomous loading systems in Chilean copper and Canadian potash. |
Methodological Framework
A standing panel of maintenance directors at Pilbara iron ore hubs, plant engineers in China's Shanxi coal belt, OEM procurement teams at Sandvik AB and thyssenkrupp AG, and aftermarket service heads provided ongoing calibration across the study period. Primary interview intelligence combined with secondary validation from SEC 10-K filings, EIA energy infrastructure data, EU Green Deal directive documentation, and Chinese MEE environmental enforcement records. Bottom-up equipment shipment tallies and top-down mining capital expenditure estimates underwent iterative reconciliation.
Scenario-bracketing framed low, base, and high cases across the analysis window, with segmentation modeling across duty rating, power transmission architecture, end-use abrasiveness, and regional regulatory cluster. CAGRs derived from equipment replacement cycle compression rates and greenfield mine development pipelines. Industry-specific forecast inputs incorporated electric drive retrofit penetration curves and manganese steel alloy price volatility indices.
Macroeconomic conditions sit as an overlay; deviation in mining commodity prices, South African ore export policy, or EU carbon border adjustment implementation would shift the trajectory. Cross-checking against FLSmidth A/S and Metso Corp. aftermarket revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Motorized Decoiler Machine Market
Material Handling Equipment
Slitting Machines Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Container Handling Equipment Market