
 LAMEA Mini Excavators Market | 2026-2036
LAMEA Mini Excavators Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Mini Excavators Market Insights
Brazil is narrowing the supply gap for compact earthmoving equipment through localized assembly partnerships and import substitution policies. Caterpillar Inc. leverages its established dealer network across São Paulo and Minas Gerais to sustain aftermarket parts availability. Komatsu Ltd. anchors its LAMEA strategy with a dedicated remanufacturing facility near Belo Horizonte. Hyundai Construction Equipment Co., Ltd. competes aggressively on total cost of ownership for rental fleet operators.
Mini excavators are tracked or wheeled hydraulic machines with operating weights below six metric tons, powered by diesel engines or electric drivetrains, and designed for precision digging in confined spaces. Their boom geometry and zero-tail-swing variants enable trenching, grading, and material handling where standard excavators cannot maneuver. Diesel configurations still dominate rental fleets across LAMEA due to refueling infrastructure maturity and acquisition cost thresholds. Electric variants are gaining share in urban demolition and landscaping applications where noise ordinances and emissions restrictions tighten operational parameters. Site preparation workloads generate the highest utilization hours per machine in Brazil's residential subdivision boom.
Brazil's ANFAVEA emission standards and South Africa's Department of Labour OSH Act certification requirements shape engine specifications and operator training protocols for imported equipment. Peru's SUNAT customs valuation rules and Chile's SEC electrical safety markings add compliance layers for manufacturers distributing across Andean markets. Buyers must weigh total lifecycle costs against evolving carbon intensity regulations as municipal tender criteria shift toward lower-emission fleet specifications.
Market Dynamics
Brazil's ANFAVEA emission tier progression and South Africa's OSH Act enforcement are compressing equipment lifecycles while accelerating replacement demand across municipal and rental fleets.
Growth Catalysts
- Urban renewal mandates:São Paulo's metro expansion and Rio de Janeiro's port modernization drive sustained municipal procurement of compact earthmoving equipment for confined-space infrastructure work.
- ANFAVEA emission standards:Brazil's progressive diesel emission regulations force fleet turnover toward Stage V-compliant engines, creating replacement pull across southeastern state contractors.
- Electric drivetrain maturation:Battery-electric mini excavators penetrate landscaping and demolition segments where noise ordinances and indoor emissions restrictions tighten operational parameters.
Market Restraints
- Import dependency concentration:Peru's SUNAT customs valuation rules and Chile's SEC electrical safety markings fragment compliance costs for manufacturers distributing across Andean markets.
- Refueling infrastructure lock-in:Diesel configurations dominate rental fleets due to Brazil's established fuel distribution network and electric charging gaps at remote construction sites.
- Skilled operator scarcity:South Africa's Department of Labour certification requirements under the OSH Act create training bottlenecks that constrain fleet utilization rates.
Strategic Opportunities
- Remanufacturing localization:Dedicated component refurbishment facilities near Belo Horizonte capture aftermarket value from aging fleet bases across Minas Gerais and São Paulo states.
- Zero-tail-swing penetration:Tight urban job sites in Brazilian residential subdivisions favor compact-radius machines for trenching and grading in alley-width constraints.
- Rental fleet electrification:Municipal tender criteria in São Paulo increasingly specify lower-emission equipment, opening procurement channels for battery-electric variants.
Industry Challenges
- Certification timeline compression:South Africa's OSH Act safety certifications and Brazil's ANFAVEA homologation create parallel approval tracks that extend time-to-revenue for new model introductions.
- Aftermarket parts availability:Dealer network density gaps in northern Brazil and Andean secondary cities strain uptime commitments for fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Mini Excavators Market |
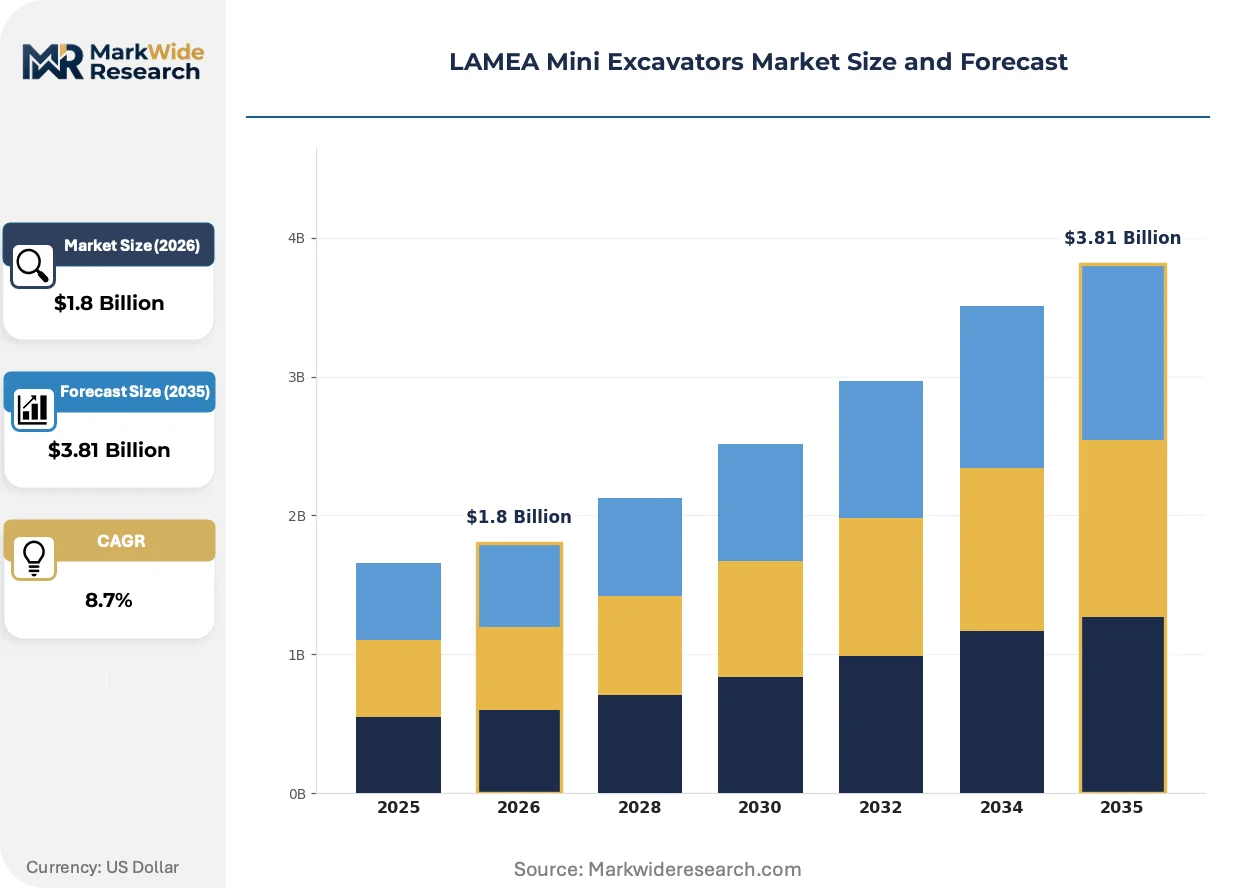
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel, Electric, Hybrid, Hydraulic End User: Construction, Landscaping, Agriculture, Mining Size: Compact, Standard, Large, Mini Application: Earthmoving, Demolition, Trenching, Site Preparation |
| Companies Covered | Volvo Construction Equipment AB, Caterpillar Inc., Komatsu Ltd., Hitachi Construction Machinery Co., Ltd., Hyundai Construction Equipment Co., Ltd., J C Bamford Excavators Ltd., Kobe Steel Ltd., Doosan Corporation, Zoomlion Heavy Industry Science & Technology Co., Ltd., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Mini Excavators Market Trends and Innovations
Electrification architectures and telematics integration are redefining equipment value propositions, while regulatory pressure on emissions and operator safety accelerates technology substitution cycles.
Telematics-enabled predictive maintenance is rendering obsolete reactive service models across Brazilian rental fleets. Equipment lessors in São Paulo and Rio de Janeiro states deploy remote diagnostics to compress downtime intervals. This capability shifts competitive differentiation from acquisition price toward uptime guarantees and total cost of ownership contracting.
South Africa's Department of Labour enforces stricter construction equipment safety certifications under amended OSH Act provisions. The regulations mandate rollover protective structures and operator visibility standards that reshape import specifications. Brazilian manufacturers supplying the LAMEA region must dual-certify to ANFAVEA and OSH Act requirements, raising compliance engineering costs.
Rental fleet operators increasingly specify outcome-based utilization contracts rather than traditional dry-hire arrangements. Municipal infrastructure departments in Brazil's southeastern states now tender for cubic-meters-moved rather than machine-days. This procurement evolution concentrates demand with lessors offering telematics-verified productivity guarantees and bundled maintenance.
LAMEA Mini Excavators Market Segmentation
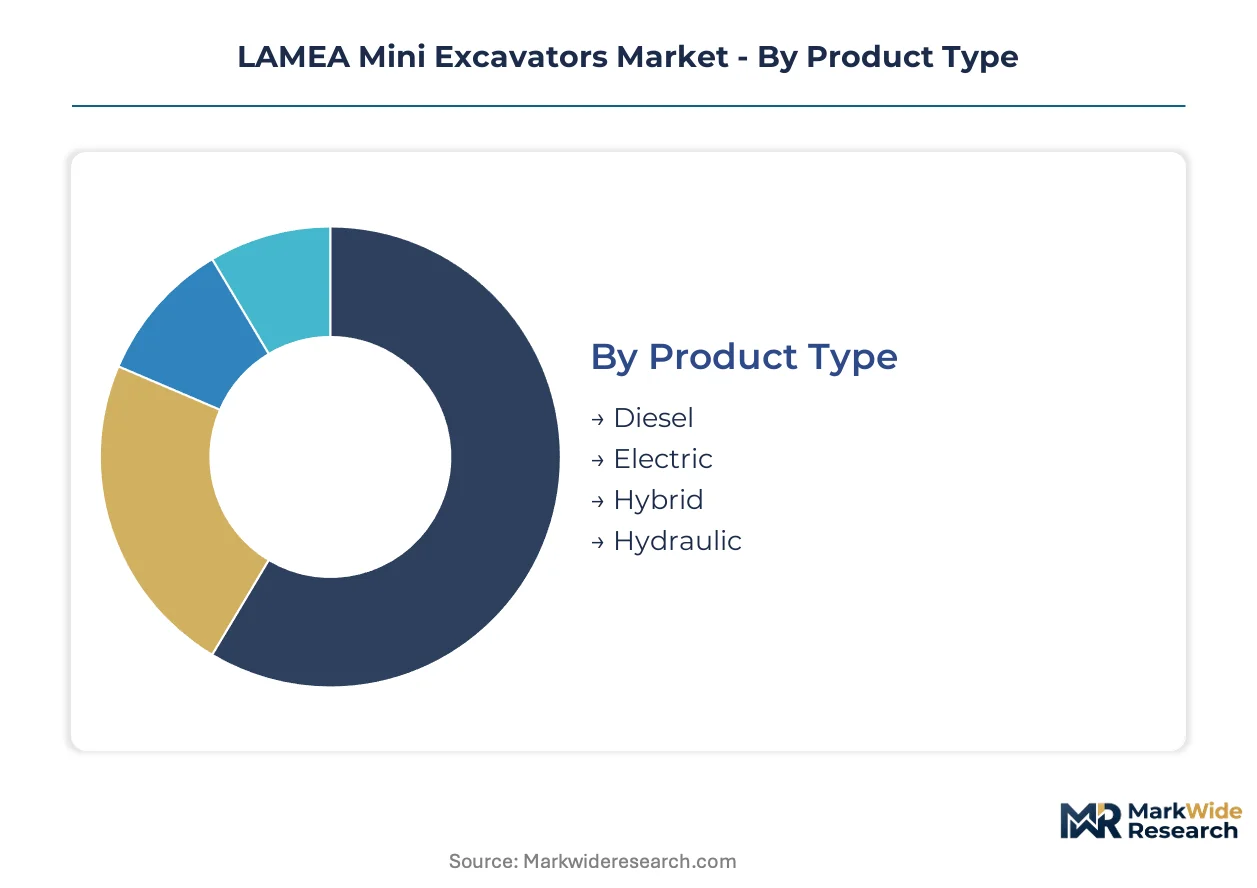
Mini excavator procurement in LAMEA diverges sharply across powertrain technologies and end-use intensity. Fleet managers in Brazil and South Africa calibrate specifications to ANFAVEA emission tiers, OSH Act safety mandates, and site-specific duty cycles rather than standardized equipment classes.
Product Type:
Powertrain architecture determines total cost of ownership calculations across Brazilian rental fleets and South African municipal contractors.
- Diesel:Compression-ignition engines from 15kW to 55kW output dominate LAMEA rental inventories. Brazil's established fuel distribution network and ANFAVEA Stage V compliance deadlines sustain replacement demand across São Paulo state construction clusters.
- Electric:Battery-electric drivetrains with 4-8 hour operational ranges penetrate urban demolition and landscaping segments. São Paulo's metro expansion projects specify zero-emission equipment for tunnel ventilation constraints, tightening procurement criteria.
- Hybrid:Diesel-electric parallel systems capture earthmoving applications with intermittent load cycles. The technology bridges refueling infrastructure gaps at remote Brazilian residential subdivision sites.
- Hydraulic:Conventional open-center hydraulic systems persist in price-sensitive Andean markets. Peru's SUNAT customs valuation rules elevate landed costs for electronically complex alternatives.
Diesel holds installed capacity. Electric is rotating up the share rankings.
End User:
Customer intensity and utilization patterns segment demand across project duration and equipment mobility requirements.
- Construction:General contractors in Brazil's southeastern states generate the highest fleet turnover rates. ANFAVEA emission tier progression forces equipment replacement ahead of mechanical end-of-life.
- Landscaping:Precision grading and tree-planting operations favor sub-3-ton machines with zero-tail-swing geometry. Noise ordinances in São Paulo's urban parks accelerate electric variant inquiries.
- Agriculture:Coffee and sugarcane plantation maintenance in Minas Gerais drives seasonal demand for compact trenching equipment. Diesel configurations retain dominance due to remote site refueling logistics.
- Mining:Artisanal and small-scale operations in Peru and Chile employ mini excavators for narrow-vein extraction. OSH Act certification requirements in South Africa constrain equipment import specifications for underground deployment.
Construction anchors procurement volume. Landscaping is climbing the fastest.
Size:
Operating weight classes align with transport logistics and site access constraints across LAMEA's fragmented infrastructure.
- Compact:Machines below 2.5 metric tons enable trailer transport without commercial licensing. Brazilian residential subdivision contractors in Rio de Janeiro's constrained urban cores specify this class for alley-width access.
- Standard:The 2.5-4.5 ton bracket balances breakout force with maneuverability. Rental fleet operators in São Paulo concentrate inventory here for cross-application utilization.
- Large:Units approaching the 6-ton threshold serve demolition and light mining duties. South Africa's Department of Labour rollover protective structure mandates elevate engineering costs for this segment.
- Mini:Sub-1.5 ton machines access interior renovation and utility maintenance. Indoor emissions restrictions in Brazilian commercial building retrofits favor electric configurations.
Standard size dominates rental availability. Compact is gaining share fastest.
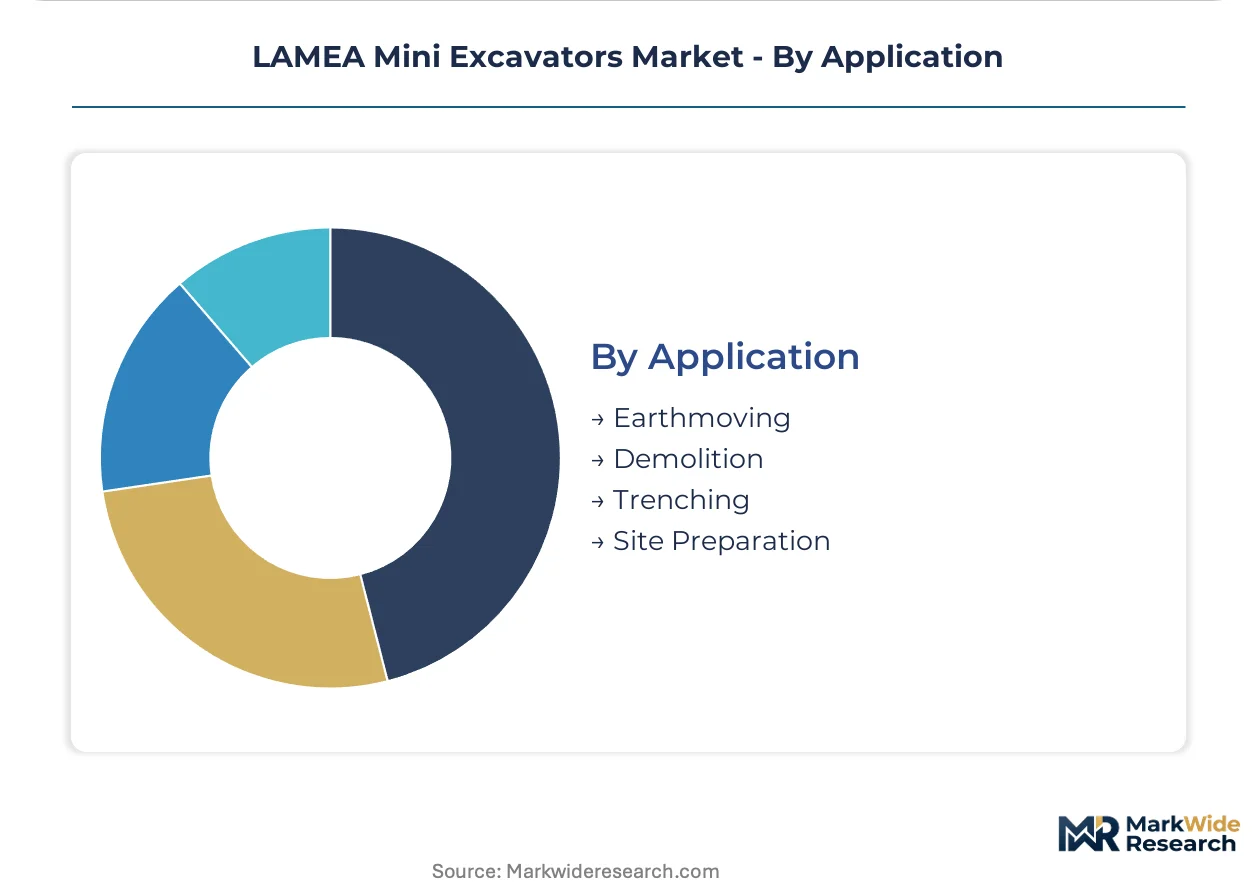
Application:
Worksite task specificity determines attachment configuration and boom geometry specifications.
- Earthmoving:Bulk material relocation and rough grading consume the highest machine hours per project. Site preparation workloads in Brazil's residential subdivision boom sustain utilization rates.
- Demolition:Structural dismantling and debris sorting demand reinforced booms and hydraulic breaker compatibility. São Paulo's urban renewal mandates specify noise-suppressed equipment for residential adjacency.
- Trenching:Utility installation and drainage construction require precise depth control. Municipal infrastructure departments in Rio de Janeiro's port modernization project specify GPS-integrated machines.
- Site Preparation:Clearing, leveling, and compaction sequencing demands versatile quick-coupler systems. Andean market fragmentation across Peru, Chile, and Colombia elevates parts availability requirements for multi-application fleets.
Earthmoving holds the deepest installed base. Demolition is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers concentrate assembly capacity in Brazil's southeastern industrial corridor, with import flows filling gaps across Andean and Southern African markets. ANFAVEA emission tier progression and South Africa's OSH Act enforcement create divergent compliance requirements that fragment regional distribution strategies. Municipal procurement in São Paulo and Rio de Janeiro anchors volume demand, while secondary markets in Peru, Chile, and South Africa operate on replacement cycles.
Brazil
São Paulo's metro expansion and Rio de Janeiro's port modernization drive municipal fleet procurement for confined-space earthmoving. ANFAVEA Stage V emission standards force equipment replacement ahead of mechanical end-of-life across southeastern state contractors. Minas Gerais hosts remanufacturing facilities serving aging fleet bases in Belo Horizonte's construction cluster.
South Africa
Johannesburg's urban renewal projects and Cape Town's infrastructure maintenance sustain rental fleet utilization rates. The Department of Labour enforces OSH Act certification requirements that constrain operator availability and extend equipment approval timelines. Gauteng province concentrates mining-related procurement for narrow-vein extraction equipment.
Chile
Copper mine mechanization and Santiago's commercial building retrofits generate demand for sub-3-ton electric variants. SEC electrical safety markings add compliance layers for imported equipment, elevating landed costs relative to Brazilian-sourced alternatives. The Antofagasta mining corridor specifies zero-tail-swing machines for tunnel ventilation constraints.
Peru
Artisanal mining operations in the Andean highlands employ compact excavators for narrow-vein extraction where larger equipment cannot maneuver. SUNAT customs valuation rules fragment compliance costs for manufacturers distributing from Brazilian assembly hubs. Lima's infrastructure departments specify GPS-integrated machines for utility trenching precision.
United Arab Emirates
Dubai's commercial construction pipeline and Abu Dhabi's infrastructure maintenance sustain premium-tier equipment procurement. MOHAP equipment safety protocols and municipal green building codes accelerate electric variant inquiries for indoor demolition. The Jebel Ali industrial zone serves as a re-export hub for equipment redistribution across Gulf Cooperation Council markets.
LAMEA Mini Excavators Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on hydraulic and drivetrain subsystems. The vendor base organizes around three archetypes: full-line construction equipment multinationals with established dealer networks, regional assemblers leveraging localized content rules, and rental fleet operators backward-integrating into equipment specification. Competitive moves concentrate on remanufacturing localization and telematics-enabled service contracting rather than pure price competition.
Among full-line equipment manufacturers, Caterpillar Inc., Komatsu Ltd., and Hyundai Construction Equipment Co., Ltd. occupy positions spanning the premium-to-mid-tier spectrum. Caterpillar exemplifies the dealer-network-dependent archetype with established parts distribution across São Paulo and Minas Gerais. Komatsu represents the remanufacturing-localization strategy through dedicated component refurbishment facilities. Hyundai anchors the total-cost-of-ownership competitive vector for rental fleet operators calibrating procurement to utilization economics.
| Leading Market Players |
|---|
| Volvo Construction Equipment AB |
| Caterpillar Inc. |
| Komatsu Ltd. |
| Hitachi Construction Machinery Co., Ltd. |
| Hyundai Construction Equipment Co., Ltd. |
| J C Bamford Excavators Ltd. |
| Kobe Steel Ltd. |
| Doosan Corporation |
| Zoomlion Heavy Industry Science & Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
São Paulo's southeastern industrial corridor concentrates assembly capacity for mini excavators, with localized production conferring pricing power over Andean import-dependent markets. Brazilian manufacturers leverage ANFAVEA emission tier compliance as a cost anchor, while Peruvian SUNAT valuation rules and Chilean SEC markings fragment landed costs for cross-border distributors.
Pricing Analysis
ANFAVEA Stage V dictates the pricing tier structure across Brazilian procurement channels, separating premium remanufactured units with telematics bundling from standard diesel configurations and economy-tier hydraulic alternatives. Certification dualities with South Africa's OSH Act elevate engineering costs for multinationals, compressing margins on large-class machines. Cost compression in the economy tier intensifies as regional assemblers exploit import substitution policies. Municipal contractors in Rio de Janeiro exhibit highest price sensitivity due to tender-driven procurement, while UAE commercial developers show lowest sensitivity for premium electric variants.
Supply Chain Analysis
Steel plate and hydraulic valve imports from China, Japan, and Germany feed Brazilian assembly lines, with diesel engines sourced from localized Tier IV/V compliant foundries. Battery cell supply for electric variants rests on Korean and Chinese chemistry suppliers, creating single-source vulnerability for LAMEA electrification roadmaps. Tariff exposure runs through Peru's SUNAT administrative valuation methodology, which elevates effective duties on electronically complex hybrid systems. Distribution runs through Caterpillar and Komatsu dealer networks in São Paulo and Minas Gerais, with Jebel Ali serving Gulf re-export functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified operator scarcity constrains fleet utilization across South Africa's OSH Act enforcement zones, creating a bottleneck that reshapes competitive returns. Equipment lessors with captive training capabilities capture disproportionate share in municipal tender processes.
For Market Incumbents: Insulate aftermarket revenue streams by deepening component refurbishment capacity near Belo Horizonte, where aging fleet bases concentrate replacement demand. Counter Hyundai's total-cost-of-ownership positioning through telematics-verified uptime guarantees that shift procurement criteria from acquisition price to lifecycle contracting. For New Entrants and Emerging Players: Establish a beachhead in Peru's artisanal mining segment, where SUNAT valuation complexity deters full-line multinationals and compact diesel configurations face limited certified competition. Target GPS-integrated trenching specifications for Lima's infrastructure departments, using local assembly partnerships to circumvent customs duty fragmentation. For Investors and Strategic Acquirers: Long-term, this sits as a replacement-cycle play because ANFAVEA Stage V mandates force equipment turnover ahead of mechanical end-of-life across Brazil's southeastern states. Acquisition candidates include regional rental fleet operators with backward-integrated maintenance capabilities and established municipal tender relationships. Monitor São Paulo metro expansion contract awards as inflection signals for electric variant penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Remanufacturing Localization | Captures aftermarket value from aging fleet bases in Minas Gerais construction clusters. |
| Telematics Platform Integration | Enables outcome-based contracting for São Paulo municipal cubic-meters-moved tenders. |
| Electric Variant Certification | Secures ANFAVEA and OSH Act dual approval for tunnel ventilation-constrained projects. |
| Zero-Tail-Swing Capacity Expansion | Addresses alley-width constraints in Rio de Janeiro's residential subdivision boom. |
| Dealer Network Densification | Closes parts availability gaps in northern Brazil and Andean secondary cities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with equipment procurement managers, rental fleet operators, and municipal infrastructure directors across São Paulo, Rio de Janeiro, and Johannesburg; and secondary validation through ANFAVEA production statistics, South African Department of Labour OSH Act certification registries, and customs valuation rulings from Peru's SUNAT. Bottom-up equipment shipment tallies by powertrain and weight class were triangulated against top-down construction expenditure forecasts for Brazil's southeastern states.
Forecast inputs considered ANFAVEA emission tier enforcement timelines, OSH Act amendment implementation pacing, and electric charging infrastructure buildout assumptions across the analysis window. Segmentation modeling spanned powertrain architecture, operating weight class, end-use intensity, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle compression and municipal procurement volume projections, with cross-checking against residential subdivision permitting data and mining sector capital expenditure disclosures.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Chilean copper price volatility, or South African electricity grid reliability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution elasticities. Cross-checking against OEM order backlogs and rental fleet utilization surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Global Crane Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
GCC Crane Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Global Wheel Aligner Equipment Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Sandblasting Machines Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Snow Clearing Vehicles Market