
 Hydraulic Cylinders Market | 2026-2036
Hydraulic Cylinders Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Cylinders Market Intelligence
Composite-reinforced piston rods is pivoting traditional chrome-plated steel economics toward lighter, corrosion-resistant architectures. Parker Hannifin Corporation leverages integrated motion control portfolios to anchor premium positioning across aerospace and industrial hydraulics. Bosch Rexroth AG dominates intelligent cylinder development with embedded sensor platforms for predictive maintenance. Eaton Corporation sustains broad geographic coverage through extensive distributor networks serving mobile and stationary equipment sectors.
A hydraulic cylinder is a mechanical actuator that converts pressurized fluid energy into linear force and motion, typically comprising a cylindrical barrel, piston, and piston rod with operating pressures ranging from 3,000 to 10,000 psi depending on duty cycle. Its primary purpose is to generate controlled pushing, pulling, or lifting forces in heavy machinery, industrial presses, and mobile equipment where electromechanical alternatives cannot deliver comparable power density. Welded cylinders occupy the highest-margin tier in construction and mining applications where structural integrity under shock loading commands premium pricing. Telescopic configurations represent the fastest-expanding product category in dump truck and refuse collection fleets requiring extended stroke lengths within constrained mounting envelopes. Electro-hydraulic technology is displacing conventional valve-controlled architectures in precision agricultural machinery where variable rate control reduces fuel consumption.
ISO 4413 fluid power standards govern safety and performance requirements for hydraulic systems across international trade, while the EU F-Gas Regulation restricts fluorinated greenhouse gas use in seal manufacturing, compelling European suppliers to reformulate elastomer compounds. China's GB standards and NMPA-equivalent industrial safety directives mandate pressure testing protocols for cylinders deployed in mining and infrastructure projects. India's BIS certification requirements for construction equipment components are tightening market access for imported hydraulic assemblies. Stakeholders must monitor evolving regional carbon-border mechanisms and material traceability mandates that will reshape sourcing strategies and compliance costs across cylinder supply chains.
Market Dynamics
Composite-reinforced piston rods and embedded sensor architectures are compressing replacement cycles while elevating performance benchmarks across construction, mining, and agricultural equipment fleets. Equipment OEMs now specify predictive-maintenance-ready cylinders as standard, forcing suppliers to reconfigure R&D roadmaps and manufacturing footprints.
Growth Catalysts
- EU F-Gas Regulation:Seal manufacturers are reformulating elastomer compounds to eliminate fluorinated greenhouse gases, opening procurement windows for compliant European suppliers in cross-border infrastructure tenders.
- China's heavy machinery manufacturing belt:Xuzhou and Changzhou production clusters are scaling welded cylinder output to serve Asia-Pacific mining corridor fleet expansions.
- Electro-hydraulic variable rate control:Precision agricultural machinery OEMs are retrofitting conventional valve architectures to reduce fuel consumption and enable sub-inch implement positioning.
Market Restraints
- Chrome-plated steel input volatility:Piston rod substrate costs fluctuate with stainless steel scrap pricing and plating chemical supply constraints.
- Seal compound concentration:Fluorocarbon elastomer production concentrates among a handful of European and Japanese chemical suppliers, creating single-source vulnerability.
- Electromechanical substitution in sub-5-ton equipment:Linear actuator advances are capturing material handling and light assembly applications below hydraulic power-density thresholds.
Strategic Opportunities
- India BIS certification tightening:Construction equipment component mandates are creating localized assembly opportunities for foreign cylinder suppliers willing to establish domestic testing facilities.
- Telescopic refuse collection fleets:Extended-stroke configurations within constrained mounting envelopes are penetrating municipal waste management procurement in Southeast Asian megacities.
- ISO 4413 compliance as competitive wedge:Third-party certified safety and performance documentation is differentiating suppliers in international mining and infrastructure tenders.
Industry Challenges
- Embedded sensor integration complexity:Cylinder manufacturers lack in-house electronics firmware capabilities, forcing partnership dependencies with industrial IoT specialists.
- Pressure testing protocol fragmentation:China's GB standards, India's BIS requirements, and ISO 4413 create overlapping certification burdens for multi-destination exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Cylinders Market |
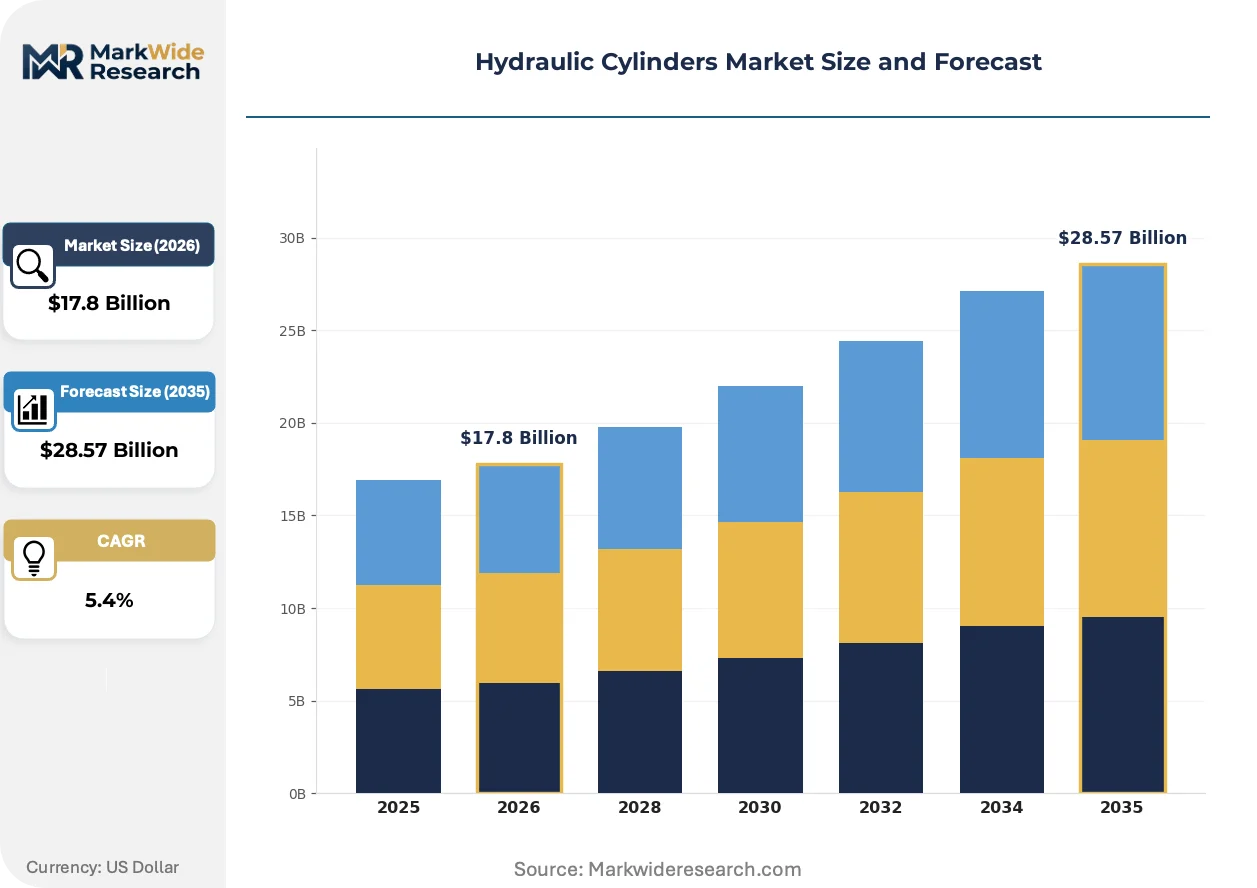
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $28.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tie Rod, Welded, Mill Type, Telescopic Technology: Double Acting, Single Acting, Electro-Hydraulic, Non-Return Valve Application: Construction Equipment, Agricultural Machinery, Material Handling, Marine Equipment End User: Manufacturers, Maintenance Providers, Equipment Rental Firms, Infrastructure Developers |
| Companies Covered | Eaton Corporation, Wipro Infrastructure Engineering, Parker Hannifin Corporation, SMC Corporation, Liebherr Group, Bosch Rexroth AG, HYDAC International, Ligon Industries, Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Cylinders Market Strategic Shifts & Innovations
Intelligent cylinder architectures and material science advances are redefining lifecycle economics and service models. Equipment operators now demand condition-monitoring capabilities as table stakes, compressing the viable supplier set to technology-forward manufacturers.
Embedded sensor platforms with edge-computing firmware are automating predictive maintenance workflows in mining and construction fleets. Komatsu and Caterpillar procurement specifications now require real-time rod position, temperature, and pressure telemetry as standard. This capability compression is automating traditional scheduled maintenance intervals and shifting supplier revenue toward data-enabled service contracts.
The EU F-Gas Regulation is compelling seal compound reformulation across European supply chains. Elastomer manufacturers must eliminate perfluorinated feedstocks while maintaining extrusion resistance and temperature performance. Cylinder assemblers serving EU infrastructure projects are qualifying alternative hydrogenated nitrile and thermoplastic polyurethane compounds to maintain regulatory access.
Buyer concentration among top-ten construction equipment OEMs is consolidating procurement authority and compressing supplier margins. Tier-one manufacturers now mandate multi-year total cost of ownership guarantees, shifting risk onto cylinder producers. This concentration is most visible in China's Xuzhou manufacturing cluster, where Sany and XCMG procurement teams negotiate direct with rod and seal suppliers, bypassing traditional distribution layers.
Hydraulic Cylinders Market Segmentation
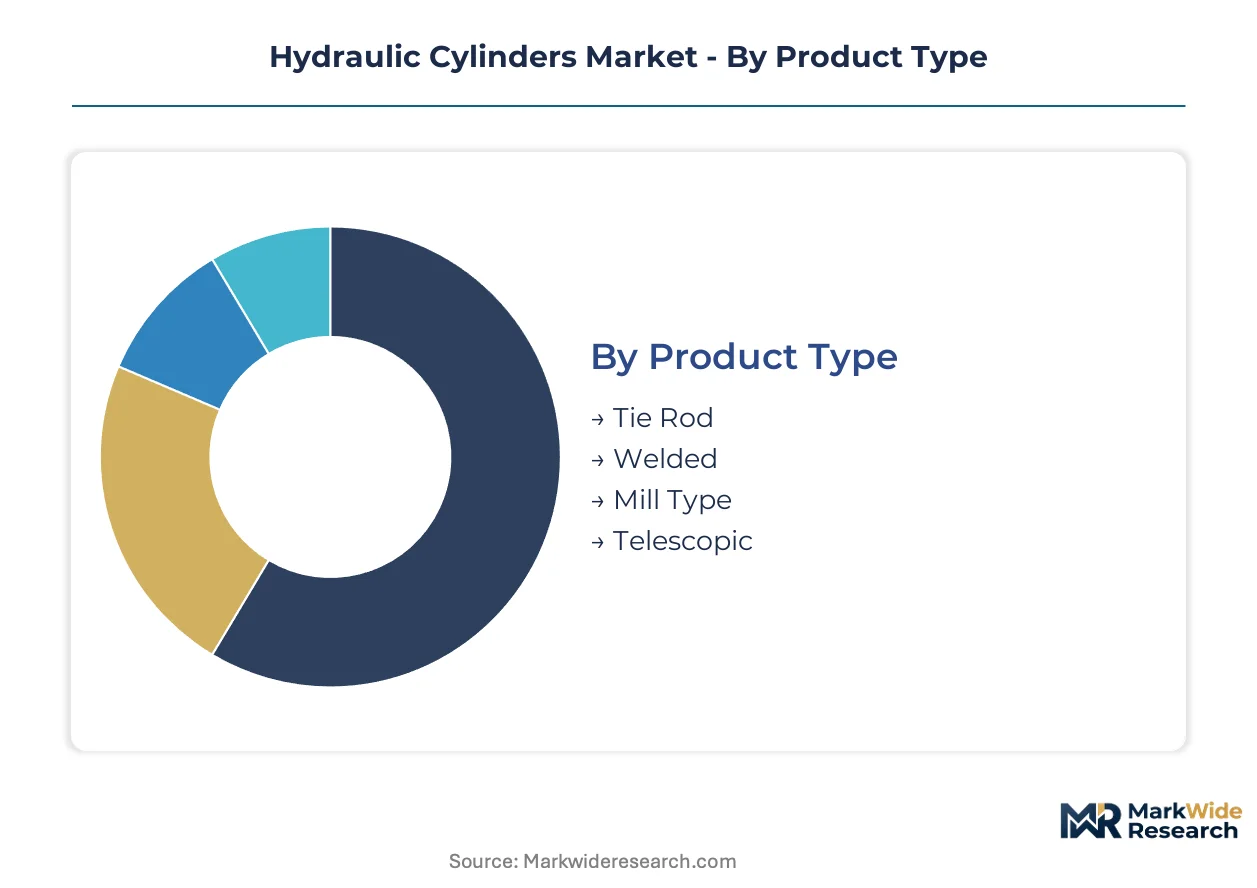
Segmentation in hydraulic cylinders reveals how structural design, actuation technology, and end-use intensity create divergent margin profiles across supplier portfolios. Equipment OEMs now specify performance tiers that cross-cut traditional product categories, forcing manufacturers to configure modular platforms spanning multiple segment boundaries.
Product Type:
Structural integrity requirements vary sharply across mounting configurations and duty cycles, with welded architectures commanding premium positioning in shock-loaded environments.
- Welded:Heavy-wall barrel construction with integral end caps eliminates threaded joint failure modes under impulse loading. Demand concentrates in Chinese mining corridor fleet expansions around Xuzhou and Changzhou, where Sany and XCMG procurement teams negotiate direct with rod suppliers. Structural integrity under shock loading commands premium pricing in construction and mining applications.
- Telescopic:Nested multi-stage rods extend stroke lengths within constrained mounting envelopes through differential area staging. Municipal waste management procurement in Southeast Asian megacities is climbing the fastest for extended-stroke refuse collection configurations. Dump truck and refuse fleet operators prioritize collapsed-length minimization over single-stage simplicity.
- Tie Rod:Threaded steel rods clamp cast end caps to standardized tube stock, enabling field serviceability and modular repair. Agricultural implement manufacturers in India's Punjab and Haryana states specify tie rod architectures for seasonal overhaul accessibility.
- Mill Type:Flanged heavy-duty construction withstands continuous cycling in metal forming and press applications. Steel mill maintenance departments in Germany's Ruhr region and Japan's Chiba prefecture specify mill type cylinders for rolling stock automation.
Welded cylinders lead on scale; Telescopic configurations lead on momentum.
Technology:
Actuation physics and control integration determine energy efficiency, positioning precision, and maintenance automation potential across equipment categories.
- Electro-Hydraulic:Servo-controlled variable displacement pumps replace conventional valve throttling, cutting parasitic losses and enabling sub-inch implement positioning. Precision agricultural machinery OEMs in the US Corn Belt and Ukraine's Black Earth region are retrofitting conventional architectures to reduce fuel consumption and enable real-time rate control.
- Double Acting:Pressurized fluid applies force in both extension and retraction strokes through dual porting, delivering balanced load handling. Construction equipment fleets across Australia's Pilbara mining region and Brazil's Carajás corridor specify double acting cylinders for excavator boom and bucket control.
- Single Acting:Gravity or spring return simplifies circuit design for lift-and-lower applications with unidirectional load requirements. Forklift mast elevation systems in warehouse automation deployments favor single acting simplicity for vertical staging.
- Non-Return Valve:Pilot-operated check valves maintain position under load without continuous pressure application. Aerial work platform manufacturers incorporate non-return valve cylinders for personnel lift safety compliance.
Double Acting dominates installed base; Electro-Hydraulic gains share fastest in precision applications.
Application:
Equipment duty cycles and environmental exposure create divergent specifications for seal compounds, rod coatings, and sensor integration.
- Construction Equipment:Excavators, loaders, and cranes demand high-pressure cycling resistance with contamination-tolerant sealing. Australia's infrastructure stimulus and Indonesia's trans-island highway projects are expanding fleet procurement with predictive-maintenance-ready cylinder specifications.
- Agricultural Machinery:Seasonal use patterns with extended storage periods require corrosion-resistant rod finishes and biodegradable fluid compatibility. Ukraine's grain belt and Argentina's Pampas region are modernizing harvester hydraulic systems for precision farming adoption.
- Material Handling:High-cycle palletizing and conveyor systems prioritize speed consistency and position repeatability. Automated warehouse deployments in the Netherlands and Singapore specify servo-hydraulic actuation for throughput optimization.
- Marine Equipment:Salt spray exposure and submersion risk mandate stainless steel construction and specialized wiper seal geometries. Offshore platform suppliers in Norway's Stavanger cluster and Brazil's Macaé basin specify marine-grade cylinders for subsea handling systems.
Construction Equipment leads on scale; Agricultural Machinery leads on technology upgrade intensity.
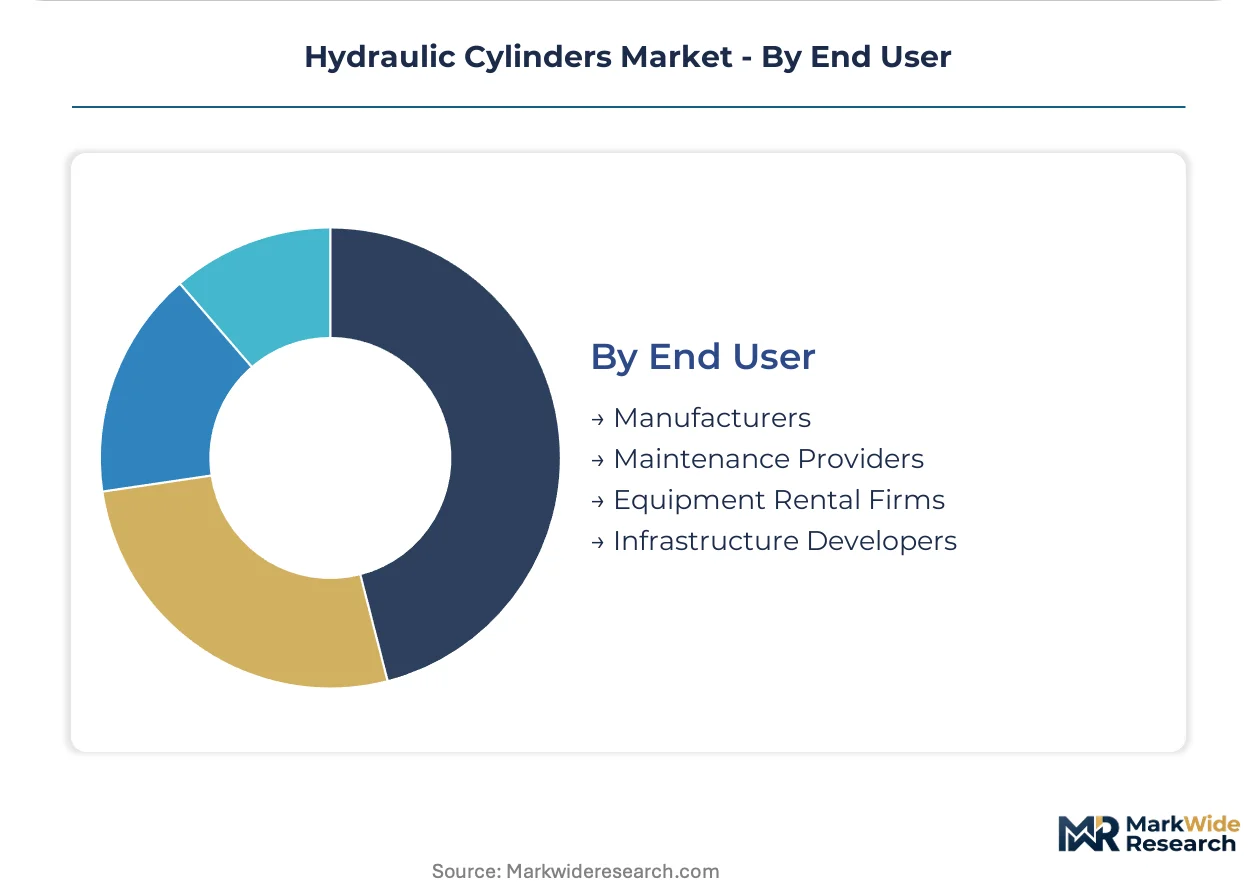
End User:
Procurement authority and lifecycle cost accountability shape contract structures from component supply to full-system performance guarantees.
- Manufacturers:OEM engineering teams specify cylinder performance curves, port configurations, and sensor integration for platform-specific integration. Caterpillar and Komatsu procurement specifications now require real-time telemetry as standard for new equipment platforms.
- Maintenance Providers:Independent service shops manage aftermarket replacement and resealing operations with rapid turnaround requirements. Regional hydraulic service networks in Texas and Alberta maintain welded cylinder rebuild capabilities for oilfield equipment.
- Equipment Rental Firms:Fleet operators prioritize interchangeability and rapid field serviceability to minimize downtime across mixed manufacturer populations. United Rentals and Sunbelt specifications drive standardization in cylinder port and mounting geometries.
- Infrastructure Developers:Project owners with multi-year construction horizons negotiate total cost of ownership guarantees and spare parts availability commitments. Saudi Arabia's NEOM project and India's Delhi-Mumbai Industrial Corridor procurement teams mandate 15-year component traceability.
Manufacturers lead on procurement volume; Infrastructure Developers lead on contract sophistication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xuzhou and Changzhou anchor the hydraulic cylinder production map, with China's heavy machinery manufacturing belt supplying welded cylinder output for Asia-Pacific mining fleet expansions. Equipment procurement specifications now mandate predictive-maintenance-ready cylinders as standard across construction and agricultural machinery deployments. Regulatory fragmentation between ISO 4413, China's GB standards, and India's BIS certification is reshaping supplier compliance investments and regional assembly strategies.
China
Construction equipment fleet expansion across Inner Mongolia and Shanxi coal corridors is absorbing record welded cylinder volumes from Xuzhou-based fabricators. GB standards pressure testing protocols for mining applications now exceed ISO 4413 baselines, compelling foreign suppliers to establish domestic certification partnerships. Changzhou specialty manufacturers are scaling telescopic configurations for municipal waste fleets in Southeast Asian export markets.
United States
Precision agricultural machinery OEMs in Iowa and Illinois are retrofitting electro-hydraulic variable rate control systems to reduce fuel consumption in sub-inch implement positioning. EPA emissions compliance for off-road equipment is accelerating sensor-integrated cylinder specifications across Corn Belt harvester fleets. Texas and Alberta regional hydraulic service networks maintain welded cylinder rebuild capabilities for Permian Basin oilfield equipment.
Germany
Ruhr region steel mill maintenance departments specify mill type cylinders for rolling stock automation in continuous casting operations. EU F-Gas Regulation seal compound reformulation is compelling elastomer manufacturers to eliminate perfluorinated feedstocks while maintaining extrusion resistance. Baden-Württemberg industrial automation clusters are qualifying hydrogenated nitrile alternatives for EU infrastructure project compliance.
India
BIS certification tightening for construction equipment components is creating localized assembly opportunities for foreign cylinder suppliers establishing domestic testing facilities. Punjab and Haryana agricultural implement manufacturers specify tie rod architectures for seasonal overhaul accessibility. Delhi-Mumbai Industrial Corridor procurement teams mandate 15-year component traceability from hydraulic subsystem vendors.
Japan
Chiba prefecture steel mill automation departments source mill type cylinders for continuous galvanizing line tension control. METI industrial efficiency directives are promoting embedded sensor platforms for predictive maintenance in heavy equipment fleets. Kanto region construction machinery OEMs now require real-time rod position telemetry as standard for new excavator platforms.
Hydraulic Cylinders Market Key Industry Players
Strategic partnerships dominate the current landscape as cylinder manufacturers lacking in-house electronics firmware capabilities seek industrial IoT specialists for embedded sensor integration. The vendor base stratifies across three tiers: diversified motion control conglomerates with integrated portfolios, specialized hydraulic component fabricators with regional density, and captive in-house production arms of major equipment OEMs. Technology licensing and backward integration into rod and seal supply represent the two most visible competitive vectors reshaping procurement relationships.
Among diversified motion control conglomerates, Parker Hannifin Corporation and Eaton Corporation exemplify portfolio breadth across aerospace and industrial hydraulics. Bosch Rexroth AG occupies a position within the intelligent cylinder development tier, with embedded sensor platforms representing the predictive maintenance archetype. Wipro Infrastructure Engineering and SMC Corporation sit within the specialized fabricator tier, with geographic naming conventions suggesting Asia-Pacific operational density. Caterpillar Inc. and Liebherr Group represent the captive production model, with equipment OEMs maintaining in-house cylinder supply for platform integration control.
| Leading Market Players |
|---|
| Eaton Corporation |
| Wipro Infrastructure Engineering |
| Parker Hannifin Corporation |
| SMC Corporation |
| Liebherr Group |
| Bosch Rexroth AG |
| HYDAC International |
| Ligon Industries |
| Caterpillar Inc. |
| Others |
Cost & Logistics Intelligence
Top-ten construction equipment OEM procurement concentration is compressing supplier margins and mandating multi-year total cost of ownership guarantees across welded and telescopic cylinder categories. Sany and XCMG procurement teams in China's Xuzhou cluster now negotiate direct with rod and seal suppliers, bypassing traditional distribution layers and forcing price transparency down to raw material inputs.
Pricing Analysis
Chrome-plated steel substrate volatility and fluorocarbon elastomer supply constraints drive input-cost pass-through mechanics across all product tiers. Three-tier pricing structure across premium, standard, and economy levels separates predictive-maintenance-ready sensor-integrated cylinders from conventional welded architectures. Cost compression in standard-tier welded cylinders is intensifying because buyer consolidation extracts volume discounts. Maintenance providers and independent service shops exhibit highest price sensitivity; aerospace and marine equipment OEMs demonstrate lowest sensitivity due to certification-grade requirements.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and European fluorocarbon elastomer manufacturers controlling seal compound formulations. Manufacturing gravity centers on China, Germany, and Japan for precision-machined barrel and rod components. Raw material dependencies span stainless steel scrap for piston rod substrates, hydrogenated nitrile for EU F-Gas Regulation compliance, and specialized chrome plating chemicals. Tariff exposure on Chinese-origin steel inputs creates structural risk for Western assemblers. Distribution runs through authorized distributor networks serving mobile equipment fleets and direct OEM supply agreements for construction machinery platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydraulic cylinders market functions as a stable compounder anchored by irreplaceable power density requirements in heavy machinery applications where electromechanical alternatives cannot compete.
For Market Incumbents: Hedge against electromechanical substitution in sub-5-ton equipment by deepening sensor integration partnerships with industrial IoT specialists. Secure backward integration into composite-reinforced piston rod supply to defend margin position against chrome-plated steel volatility. Prioritize ISO 4413 third-party certification investments to differentiate in international mining tenders. For New Entrants and Emerging Players: E-commerce procurement platforms serving independent maintenance providers offer the lowest barrier to customer access in this fragmented aftermarket. Target India's BIS certification tightening by establishing localized testing facilities in Pune or Chennai industrial corridors. Pursue municipal waste management procurement in Southeast Asian megacities for telescopic configuration market entry. For Investors and Strategic Acquirers: Diversified motion control conglomerates are the most active acquirer in this space, seeking embedded sensor firmware capabilities through technology tuck-ins. Five-to-ten year viability rests on predictive maintenance service contract monetization displacing component-only revenue. Monitor Komatsu and Caterpillar procurement specification releases for real-time telemetry mandates as inflection indicators for intelligent cylinder adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rod Supply | Xuzhou and Changzhou fabricators secure substrate cost control against stainless scrap volatility. |
| Embedded Sensor Platform Partnership | Cylinder manufacturers access predictive maintenance firmware through industrial IoT specialist alliances. |
| EU F-Gas Seal Compound Reformulation | Hydrogenated nitrile qualification maintains regulatory access for European infrastructure tenders. |
| India BIS Certification Localization | Foreign suppliers establish domestic testing facilities to capture Delhi-Mumbai Industrial Corridor procurement. |
| Telescopic Configuration Scale-Up | Changzhou specialty manufacturers target Southeast Asian municipal waste fleet replacement cycles. |
Research Approach
Bottom-up construction and mining equipment fleet modeling reconciled against top-down hydraulic component production tracking forms the analytical core of this study. Primary interviews with maintenance directors at Australian Pilbara mining operations, OEM procurement teams at Sany and XCMG, aftermarket service heads in Texas and Alberta, and plant engineers at Ruhr region steel mills combined with secondary validation from SEC 10-K filings of diversified motion control conglomerates, customs trade data on hydraulic component imports, ISO certification registries, and EU F-Gas Regulation compliance databases. Triangulation between demand-side equipment deployment and supply-side manufacturing capacity ensures statistical integrity.
Input-output matrices mapping cylinder specifications to end-use equipment categories across product type, actuation technology, application intensity, and procurement authority dimensions structure the projection framework. CAGRs derive from equipment replacement cycle analysis, fleet expansion trajectories in Asia-Pacific mining corridors, and technology substitution elasticity estimates for electro-hydraulic architectures. Industry-specific forecast inputs include GB standards pressure testing protocol evolution and India's BIS certification implementation timelines across the analysis window.
The model assumes a particular technology adoption path for embedded sensor platforms; alternative pathways for electromechanical actuator substitution in light-duty applications would alter the outlook. Forecasts reflect assumptions regarding ISO 4413 international harmonization, EU F-Gas seal compound transition costs, and chrome-plated steel input price stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Mill Pulverizer Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
Mini Excavators Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Cold Heading Machine Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Felling Heads Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Cutter Suction Dredger (CSD) Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Blanking Machine Market
Construction Equipment
Grinding Machinery Market