
 Global Compact Construction Equipment Market | 2026-2036
Global Compact Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Compact Construction Equipment Market Intelligence
The proliferation of equipment-as-a-service and long-term leasing models is rewriting the competitive landscape for compact machinery. This trend lowers the barrier to entry for smaller contractors, intensifying competition beyond outright sales. Caterpillar Inc. leverages its extensive global dealer network to offer flexible financing and rental options. Bobcat Company differentiates through a focus on specialized attachments and implements for its core loader products, catering to niche applications.
Compact construction equipment refers to mobile machinery with an operating weight typically under 10 metric tons, designed for maneuverability in confined job sites. Its primary purpose involves excavation, material handling, and site preparation for landscaping, utility, and small-scale building projects. Mini excavators and skid steer loaders constitute the largest product segments by volume. Demand from rental companies is a significant driver, favoring equipment with durable components and simplified maintenance schedules, particularly for hydraulic systems.
Engine emission mandates, such as the EPA's Tier 4 Final in the United States and Stage V in the European Union, are forcing a transition to cleaner diesel and electric powertrains. Operator safety rules from bodies like OSHA and compliance with CE marking for European market access govern equipment design, including cabin structures and visibility. Key strategic decisions for manufacturers will revolve around managing the total cost of ownership for electric versus diesel models to align with contractor procurement priorities.
Market Dynamics
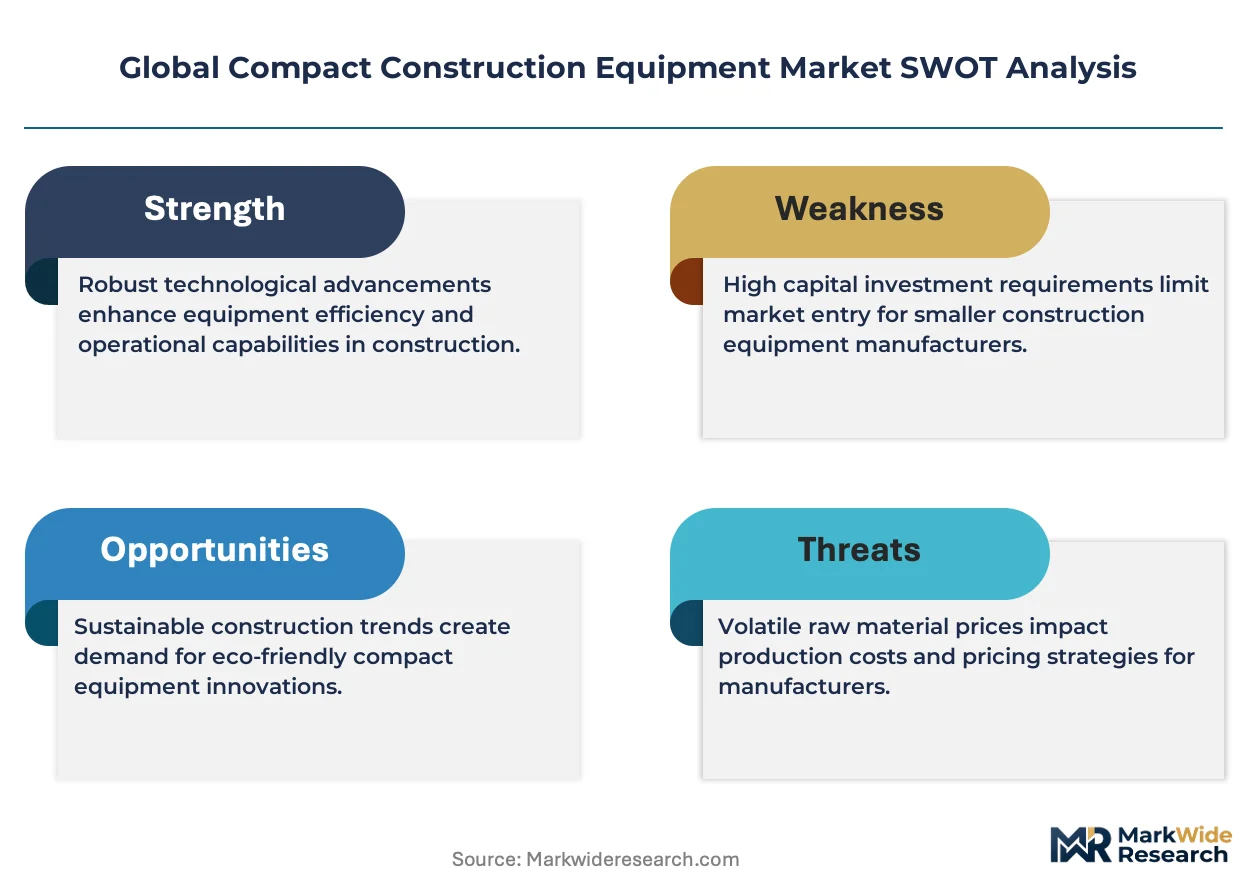
The fundamental market dynamic is the mandatory technological transition toward cleaner powertrains. This shift, enforced by emissions regulations like the EPA's Tier 4 standards and the EU's Stage V, is compelling a costly research and development pivot to electric models.
Growth Catalysts
- Urban Infrastructure Renewal:Government-backed initiatives to upgrade aging water, sewer, and utility lines in dense urban centers across the United States and Germany directly increase demand for compact excavators and loaders.
- Stringent Emissions Regulations:Fleet modernization is accelerated by mandates such as the EU's Stage V, which requires rental companies and contractors to replace older, non-compliant diesel equipment to operate in regulated zones.
- Residential Landscaping Expansion:The growth of professional landscaping and hardscaping services for new residential construction and property management creates a consistent volume demand for mini excavators and skid steers.
Market Restraints
- Electric Powertrain Cost Premium:The high upfront acquisition cost of battery-electric models compared to their diesel counterparts, driven by expensive lithium-ion battery packs, remains a significant barrier for smaller contractors.
- Hydraulic Component Bottlenecks:Supply chain concentration for critical hydraulic pumps and motors, primarily in Japan and Germany, exposes manufacturers to price volatility and potential lead-time extensions during periods of high demand.
- Rural Charging Infrastructure Deficit:The lack of reliable, high-capacity charging stations outside of major metropolitan areas limits the practical application and total addressable market for fully electric compact equipment.
Strategic Opportunities
- Equipment-as-a-Service Models:Developing subscription-based offerings that bundle machine access, telematics data, and preventive maintenance provides a recurring revenue stream and lowers the entry barrier for new customers.
- Niche Application Attachments:Engineering specialized implements for sectors like viticulture, forestry management, or indoor demolition opens new revenue streams and diversifies the customer base beyond traditional construction.
- Telematics Data Monetization:Aggregating and analyzing machine operational data allows for the sale of value-added services, such as predictive maintenance alerts and fleet efficiency consulting, to large rental houses.
Industry Challenges
- Specialized Technician Scarcity:A persistent shortage of service technicians proficient in both traditional diesel hydraulics and modern high-voltage electric systems creates service backlogs and increases operational downtime for end-users.
- Battery Lifecycle Management:Establishing cost-effective and scalable processes for the collection, recycling, and second-life repurposing of end-of-life lithium-ion battery packs presents a significant logistical and environmental challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Compact Construction Equipment Market |
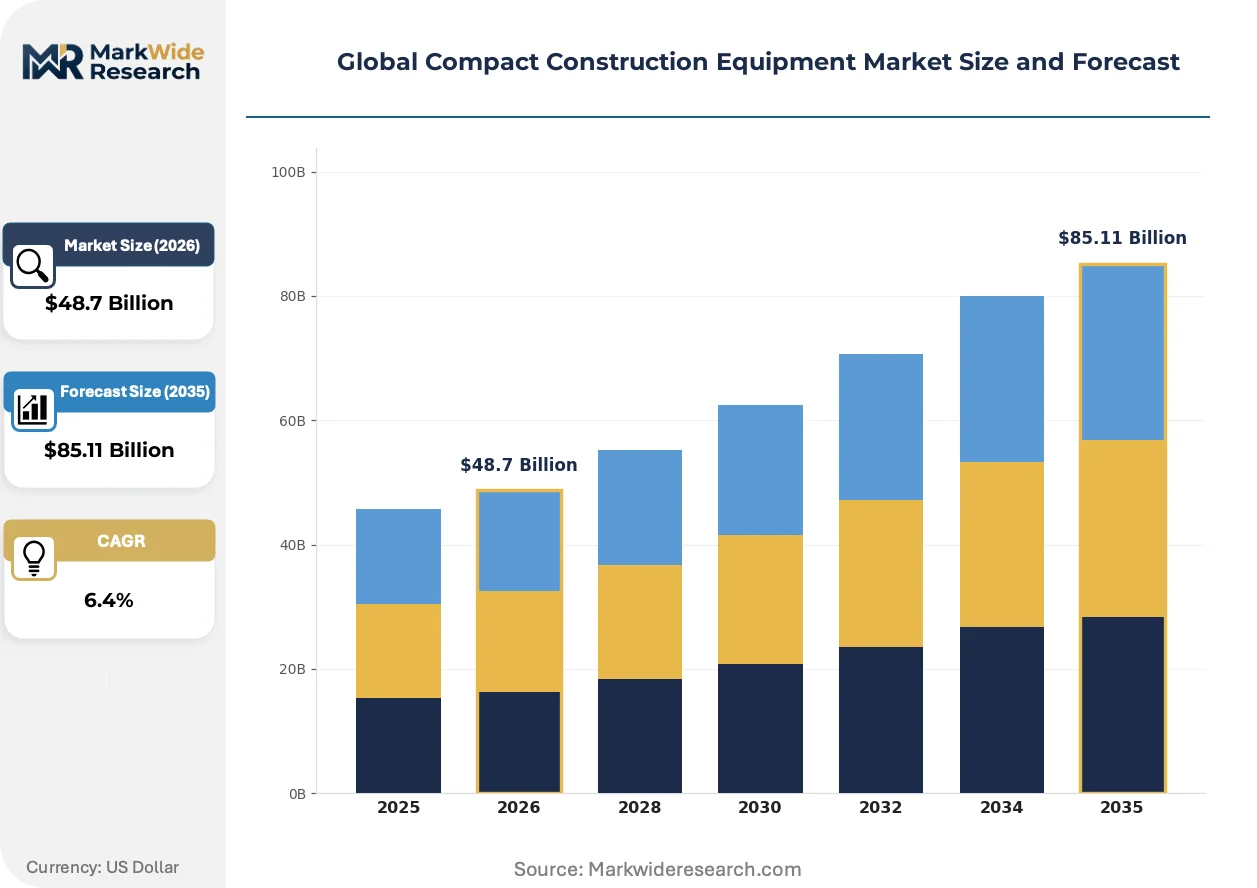
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Excavators, Skid Steer Loaders, Compact Track Loaders, Small Wheel Loaders, Compact Dumpers Technology: Hydraulic, Electric, Diesel, Battery Operated, Hybrid Application: Landscaping, Roadwork, Pipeline Installation, Site Development, Agricultural Operations End User: General Contractors, Rental Companies, Infrastructure Developers, Municipal Agencies |
| Companies Covered | Bobcat Company, Hitachi Construction Machinery Co. Ltd., Caterpillar Inc., Kubota Corporation, CNH Industrial N.V., Komatsu Ltd., JCB Ltd., Deere & Company, Volvo Construction Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Compact Construction Equipment Market Strategic Shifts & Innovations
Connectivity and data are transforming compact equipment from standalone iron into integrated nodes within a digital job site ecosystem. This evolution redefines value from machine performance alone to include uptime, utilization efficiency, and operational intelligence provided by onboard systems.
Onboard telematics and IoT sensors provide real-time data on machine health, location, and utilization. Large contractors and equipment rental companies are the primary adopters, seeking to maximize fleet uptime and reduce operating expenses. The basis of competition is migrating from raw engine power and breakout force to analytics that optimize total cost of ownership and enable predictive maintenance schedules.
European Union Stage V emissions standards represent a significant regulatory driver. The rules compel manufacturers to incorporate complex diesel particulate filters and selective catalytic reduction systems into engines, increasing both cost and maintenance requirements. This directly impacts all equipment sold into the EU, forcing a design choice between advanced after-treatment systems for diesel or accelerating the development of compliant electric alternatives.
A rental-first procurement mindset is becoming dominant among contractors. This behavioral shift favors flexible, short-term access over outright ownership, disrupting the traditional dealer sales channel and empowering national rental corporations. This asset-light preference is most visible in North American and Western European markets, where project-based work cycles make capital expenditure on machinery less attractive for small and mid-sized firms.
Global Compact Construction Equipment Market Segmentation
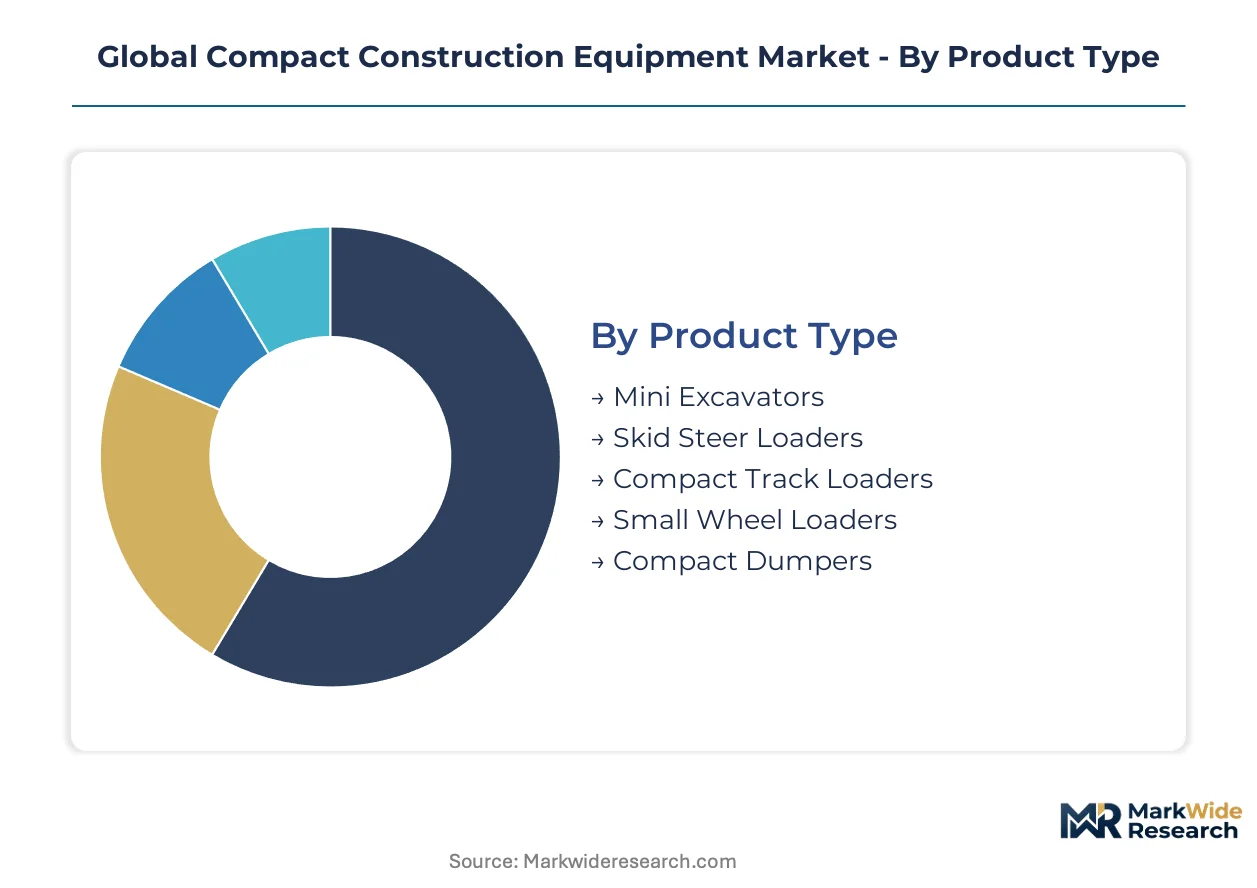
Understanding the segmentation of the global compact construction equipment market provides critical insights into purchasing patterns and technological adoption across diverse end-use sectors. This categorization helps manufacturers tailor product development and distribution strategies to meet specific customer requirements. Each segment reflects unique operational demands and regulatory pressures influencing procurement decisions.
Product Type:
The product type segmentation reveals distinct procurement cycles, with some equipment categories experiencing faster fleet modernization than others.
- Mini Excavators:These highly versatile machines, typically under 6 metric tons, feature a 360-degree rotating house and independent boom swing for precise operation. Demand concentrates in urban renewal projects across the United States and Germany, driven by their ability to operate in confined spaces and minimize disruption.
- Skid Steer Loaders:Compact, rigid-frame, engine-powered machines with lift arms are designed to attach a wide variety of tools for diverse tasks. Their demand is particularly strong in residential landscaping expansion and utility work, where maneuverability and attachment versatility are crucial for efficiency.
- Compact Track Loaders:Similar to skid steers but with rubber tracks, these machines offer superior traction and flotation on soft or uneven terrain.
- Small Wheel Loaders:Articulated machines designed for material handling and loading tasks in construction and agricultural settings.
- Compact Dumpers:Self-propelled machines primarily used for transporting bulk materials over short distances on job sites.
Mini Excavators dominate the installed base. Electric models of Skid Steer Loaders are where expansion concentrates.
Technology:
Technology segmentation highlights varying cost structures, influencing acquisition decisions for contractors.
- Diesel:These traditional internal combustion engines are often equipped with advanced after-treatment systems like DPFs and SCRs to meet stringent emissions standards. Demand remains high from contractors prioritizing lower upfront costs and established refueling infrastructure, particularly in rural areas.
- Electric:Battery-powered powertrains offer zero direct emissions and significantly reduced noise levels, making them ideal for indoor and urban operations. Demand is accelerating in regulated zones within the European Union and the United States, driven by stringent environmental mandates and corporate sustainability goals.
- Hydraulic:This core power transmission system uses pressurized fluid to actuate cylinders and motors across most compact equipment.
- Battery Operated:Refers specifically to equipment powered solely by onboard battery packs, distinct from hybrid systems.
- Hybrid:Combines a diesel engine with an electric motor and battery, optimizing fuel efficiency and reducing emissions during specific operational cycles.
Diesel technology currently accounts for the largest share of operational units. Electric powertrains exhibit the steepest expansion trajectory.
Application:
Application segmentation reveals the primary operational contexts that generate significant equipment volume.
- Landscaping:This segment involves earthmoving, grading, and material handling for residential and commercial outdoor spaces, including hardscaping and planting. This application drives consistent demand for mini excavators and skid steers, fueled by new residential construction and property maintenance services.
- Site Development:Encompassing initial ground preparation, excavation, and utility trenching for new building projects, this application is critical for commercial and residential construction. Demand is strong in urban expansion zones and infrastructure upgrades, where efficient and precise earthmoving is essential.
- Roadwork:Includes small-scale paving, patching, and shoulder maintenance on local roads and pathways.
- Pipeline Installation:Focuses on trenching and backfilling for water, sewer, and gas lines, particularly in urban environments.
- Agricultural Operations:Utilizes compact equipment for tasks like material handling, barn cleaning, and small-scale field work on farms.
Landscaping applications represent a mature and stable demand base. Pipeline Installation is gaining share rapidly due to urban utility upgrades.
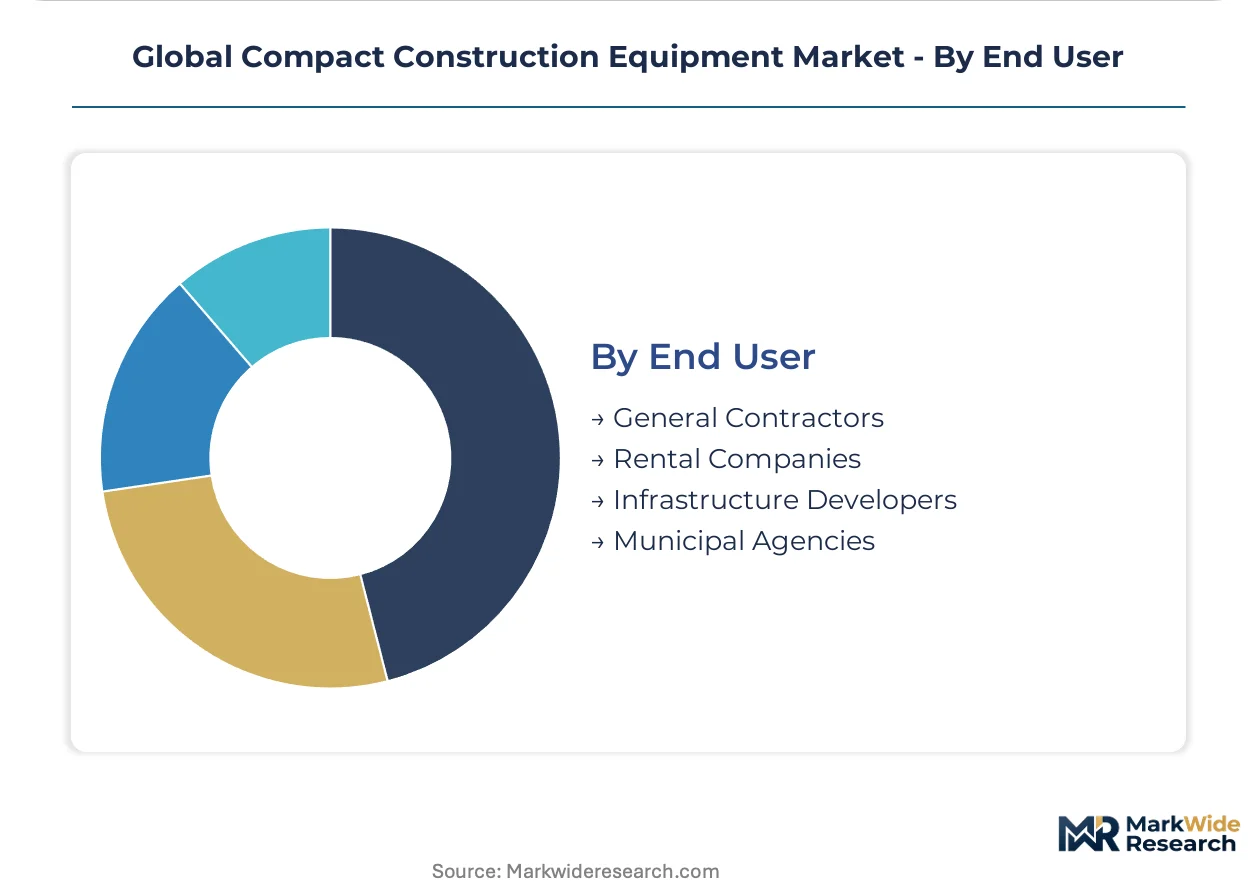
End User:
End user segmentation delineates the distinct customer types driving procurement decisions and equipment utilization patterns.
- Rental Companies:These businesses lease compact equipment to contractors on short-term or long-term agreements, providing flexible access to machinery. They are a significant demand driver, prioritizing durable components and simplified maintenance schedules to maximize fleet uptime and return on investment.
- General Contractors:Firms responsible for overall project management and execution often require a diverse fleet of compact equipment for various construction tasks. Their procurement decisions balance upfront cost with long-term reliability and the ability to meet diverse job site requirements.
- Infrastructure Developers:Entities involved in large-scale public works projects often require specialized compact equipment for utility and road construction.
- Municipal Agencies:Government bodies use compact equipment for public works, park maintenance, and local utility repairs.
Rental Companies are strategically critical due to their influence on equipment utilization and technology adoption. Infrastructure Developers represent a stable, project-driven demand channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global trade dynamics for compact construction equipment show a nuanced balance between regional production and consumption. While certain countries specialize in manufacturing key components, others drive significant end-market demand, influencing export volumes and technological adoption. This interplay shapes market growth and strategic investment.
United States
The United States exhibits strong demand for compact equipment, driven by urban infrastructure renewal and residential landscaping expansion. EPA's Tier 4 standards accelerate fleet modernization, compelling contractors to adopt cleaner equipment. Major metropolitan areas like New York City and Los Angeles drive demand for mini excavators in dense urban environments.
Germany
Germany's market for compact construction equipment benefits from urban renewal initiatives and critical utility line upgrades. EU's Stage V emissions standards accelerate the adoption of cleaner diesel and electric models. Berlin's extensive urban development projects consistently fuel demand for electric compact equipment in its low-emission zones.
Japan
Japan maintains a significant presence in the market, both as a hydraulic component manufacturer and consumer. METI regulations promote advanced manufacturing and efficiency standards for industrial machinery. The Kanto region, including Tokyo, sees consistent demand for mini excavators in urban maintenance and small-scale projects.
China
China's market expansion is propelled by rapid urbanization and infrastructure development in secondary cities. Its dual carbon goals actively encourage the transition to electric construction machinery. The Yangtze River Delta region experiences high demand for compact loaders due to extensive industrial and residential construction.
India
India's demand for compact equipment is rising due to significant government infrastructure pushes and residential construction. National emission standards for construction equipment are evolving, impacting procurement decisions for new fleets. Major infrastructure projects in states like Maharashtra drive procurement of compact equipment for efficient site preparation.
Global Compact Construction Equipment Market Key Industry Players
On the supply side, the industry is moderately concentrated, with a few large multinational corporations holding significant market share alongside numerous specialized regional players. This structure creates distinct competitive archetypes: global full-line providers, regional specialists focusing on niche applications, and emerging technology innovators. Dominant competitive moves include strategic partnerships for technology sharing and extensive geographic expansion to capture new markets.
Within the established global manufacturers, Caterpillar Inc. exemplifies a broad portfolio approach, leveraging its extensive dealer network for sales and service across various product types. Bobcat Company, known for its focus on skid steer loaders and specialized attachments, represents a niche-focused strategy, catering to specific application needs. Japanese-based Komatsu Ltd. occupies a position as a technology leader, particularly in advanced hydraulic systems and telematics integration, influencing overall industry standards. These entities collectively anchor the premium and high-volume segments of the market.
| Leading Market Players |
|---|
| Bobcat Company |
| Hitachi Construction Machinery Co. Ltd. |
| Caterpillar Inc. |
| Kubota Corporation |
| CNH Industrial N.V. |
| Komatsu Ltd. |
| JCB Ltd. |
| Deere & Company |
| Volvo Construction Equipment |
Cost & Logistics Intelligence
Under-utilized charging infrastructure in rural areas drives electric equipment pricing strategies. This affects supplier investment and contractor adoption rates.
Pricing Analysis
Rental companies anchor the per-unit transactional pricing model for compact construction equipment. After-sales service bundles and telematics integration create differentiation among manufacturers. Pricing softness reflects the high upfront cost of electric models and intense competition from equipment-as-a-service offerings. Smaller contractors exhibit the most price sensitivity, while large rental houses prioritize total cost of ownership.
Supply Chain Analysis
Lithium-ion battery pack sourcing forms a critical upstream dependency for electric compact equipment. China and Japan concentrate hydraulic component manufacturing, creating potential bottlenecks. Critical hydraulic pumps and motors, alongside battery cells, are key inputs for all equipment types. Single-source vulnerability for specialized components creates price volatility. Distribution runs through extensive global dealer networks and direct sales to large rental fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compact construction equipment market demands a robust substitution defense. Incumbents must navigate the threat of manual labor in emerging markets and specialized robotic solutions.
For Market Incumbents: Entrench existing dealer networks by expanding service capabilities for electric models. Invest in R&D for advanced battery management systems and rapid charging solutions to counter the electric powertrain cost premium. The rising cost of diesel after-treatment systems threatens market share. Control over proprietary telematics data offers a strong lever for customer retention.
For New Entrants and Emerging Players: Urban utility trenching and indoor demolition represent penetrable entry points for specialized electric compact equipment. Develop modular equipment platforms that allow rapid attachment customization for diverse tasks. Target municipal agencies with quiet, zero-emission solutions for regulated zones. Small-scale infrastructure contractors in European low-emission zones are an underserved segment.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among companies offering equipment-as-a-service models. The market's long-term viability hinges on successful transition to electric powertrains and circular economy practices for batteries. Specialized attachment manufacturers with strong intellectual property in niche applications represent attractive acquisition targets. Adoption rates of electric models by large rental companies will signal market readiness for broader electrification.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Electric Model Portfolio | Addresses stringent emissions regulations in the EU and US. |
| Develop Battery Recycling Partnerships | Manages environmental and logistical challenges of lithium-ion battery lifecycle. |
| Invest in Telematics Integration | Enhances fleet efficiency and enables predictive maintenance for rental companies. |
| Offer Equipment-as-a-Service | Lowers entry barrier for smaller contractors and generates recurring revenue. |
| Strengthen Dealer Service Networks | Ensures rapid maintenance and uptime for complex electric and diesel equipment. |
Research Approach
Operator-level perspectives from equipment fleet managers, rental company procurement heads, and construction project supervisors anchored the qualitative base. Primary interviews were combined with secondary validation from industry associations and regulatory body publications. Secondary sources included EPA and EU Commission reports, national construction statistics, and manufacturer annual reports. A bottom-up and top-down approach ensured data consistency and market sizing accuracy.
Scenario-bracketing evaluated market trajectories under varying regulatory and technological adoption rates across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and regional emission standards. CAGRs were derived from historical growth trends and projected impacts of electrification mandates. Key inputs were urban infrastructure spending and residential construction starts.
Practitioners should monitor changes in battery raw material prices and charging infrastructure development for early signals. Forecasts reflect assumptions regarding regulatory enforcement and contractor investment in electric fleets. Cross-checking against national equipment registration data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Rockbreakers Market
Construction Equipment
Global Excavator Attachments Market
Construction Equipment
Industrial Agitators Market
Construction Equipment
Excavation Equipment Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Shot Blasting Machine Market
Construction Equipment
Backhoe Bucket Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
United States Crane Market
Construction Equipment
Hammer Unions Market
Construction Equipment
BRICS Aerial Work Platforms Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Ceramic Tile Printing Machine Market
Construction Equipment
Global Riveting Equipment Market
Construction Equipment
Stud Welding Guns Market