
 Automated Material Handling (AMH) Equipment Market | 2026-2036
Automated Material Handling (AMH) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Material Handling (AMH) Equipment Market Intelligence
Aftermarket service revenue is reconfiguring margin pools across the AMH equipment landscape. Daifuku Co. Ltd leverages its installed base in airport baggage handling to secure long-term maintenance contracts. KION Group anchors its position through vertical integration into lift truck electrification and fleet management software. Jungheinrich AG differentiates via compact AGV designs purpose-built for narrow-aisle European warehousing.
Automated material handling equipment comprises integrated electromechanical systems—conveyor belts rated for specific load capacities, laser-guided AGVs with sub-centimeter positioning accuracy, and shuttle-based storage & retrieval systems operating at heights exceeding 40 meters—designed to transport, sort, and store goods with minimal human intervention in high-throughput facilities. Conveyor systems and storage & retrieval systems occupy the mature core of the installed base, generating steady replacement demand as facilities modernize aging steel-frame installations. Robotics and vision-based guidance represent the fastest-expanding technology pairing, with articulated arm systems and camera-guided vehicles displacing magnetic tape in greenfield e-commerce distribution centers where SKU variety and routing flexibility dominate operational priorities.
OSHA lockout/tagout standards and the EU Machinery Directive's safety integrity requirements compel North American and European facilities to upgrade legacy equipment with interlocked guarding and emergency stop architectures. Japan's METI energy-efficiency guidelines for industrial machinery shape motor and drive specifications in Asian manufacturing deployments. Stakeholders must weigh the capital efficiency of modular retrofits against full-system replacements as regulatory compliance windows tighten and labor availability constraints deepen.
Market Dynamics
OSHA lockout/tagout mandates and the EU Machinery Directive's safety integrity requirements are forcing facility operators to choose between modular retrofits of aging conveyor infrastructure and full-system replacement cycles.
Growth Catalysts
- E-commerce fulfillment density:SKU proliferation in omnichannel distribution networks drives demand for autonomous sortation systems capable of handling variable package dimensions without manual reconfiguration.
- OSHA workplace safety mandates:North American facilities must retrofit legacy equipment with interlocked guarding and emergency stop architectures, accelerating replacement timelines for pre-2010 conveyor installations.
- German industrial clustering:Automotive and chemical producers in Baden-Württemberg and North Rhine-Westphalia operate dense automated warehousing networks that generate sustained demand for shuttle-based storage and retrieval systems.
Market Restraints
- Steel and rare-earth input volatility:Permanent magnet costs for AGV drive motors fluctuate with Chinese export quotas, compressing margins on electrified fleet deployments.
- Technical limitation in mixed-load handling:Vision-guided systems struggle with transparent packaging and reflective surfaces, requiring human intervention in pharmaceutical and cosmetics distribution.
- EU Machinery Directive compliance friction:Safety certification timelines for retrofitted legacy equipment extend project delivery windows by four to eight months versus greenfield installations.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for electronics and automotive sectors are driving greenfield facility construction requiring integrated material handling infrastructure.
- Lithium-ion fleet conversion:Convergence of battery chemistry advances and opportunity-charging protocols enables 24/7 operation of electric lift trucks without battery swap infrastructure.
- Outcome-based maintenance contracts:Equipment-as-a-service models shift capital expenditure to operating budgets, opening mid-market facilities previously priced out of automation.
Industry Challenges
- Controls engineering talent scarcity:PLC programming and AGV fleet management expertise concentrates in automotive hubs, leaving food and beverage distributors dependent on system integrator availability.
- Legacy WMS integration complexity:Proprietary communication protocols in 1990s-era warehouse management systems require middleware development for real-time coordination with modern robotics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Material Handling (AMH) Equipment Market |
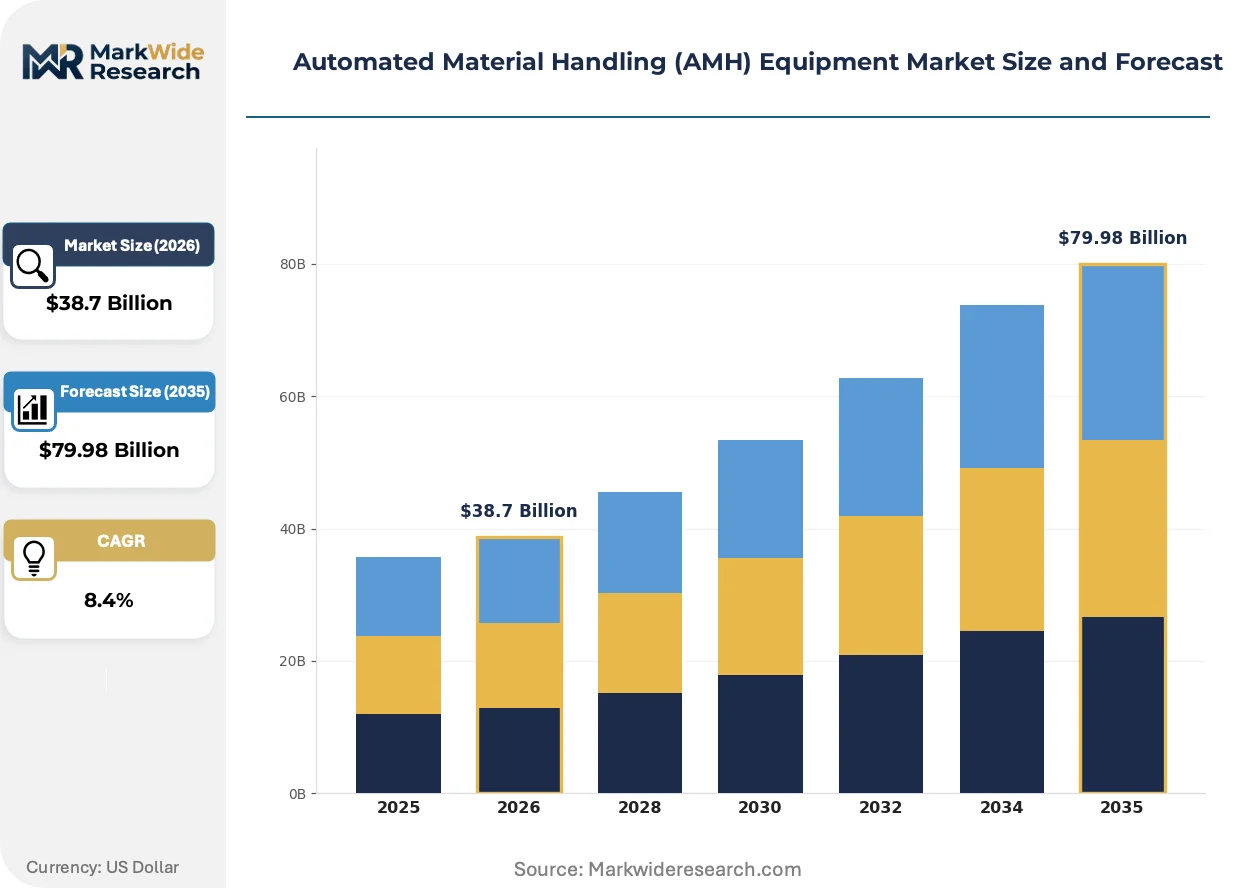
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Systems, Automated Guided Vehicles, Sortation Systems, Robotics, Storage & Retrieval Systems Technology: Laser Navigation, Magnetic Tape Guidance, Vision-Based Guidance, Ultrasonic Sensors, Radio Frequency Identification Application: Warehousing, Manufacturing Plants, Distribution Centers, Ports & Terminals, Airports End User: Third-Party Logistics Providers, Retailers, E-Commerce Companies, Food & Beverage Processors, Pharmaceuticals |
| Companies Covered | Daifuku Co. Ltd, KION Group, Jungheinrich AG, SSI Schaefer, Toyota Industries Corporation, Honeywell International Inc., Crown Equipment Corporation, Dematic, BEUMER Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Material Handling (AMH) Equipment Market Strategic Shifts & Innovations
Digital twin technology is compressing commissioning timelines and enabling predictive maintenance models that shift service revenue from reactive repair to uptime guarantees.
Digital twin platforms replicate physical conveyor and AGV operations in software environments before hardware deployment. E-commerce fulfillment operators in the Netherlands and Belgium are adopting these tools to simulate peak-season throughput scenarios. This capability is virtualizing the traditional pilot-plant validation phase, reducing commissioning risk for complex multi-vendor installations.
The EU Machinery Directive's 2023 update introduced mandatory cybersecurity assessments for networked safety controllers. Industrial facilities must now document threat modeling for Ethernet-connected emergency stop architectures. Automotive stamping plants in Germany and Slovakia are prioritizing suppliers with pre-certified safety PLC platforms to accelerate compliance timelines.
Buying committees now require total cost of ownership models spanning fifteen-year equipment lifecycles rather than upfront capital expenditure comparisons. Third-party logistics providers in the United Kingdom are unbundling maintenance contracts from original equipment manufacturers, sourcing independent service organizations for multi-brand fleet support. This pattern concentrates in contract logistics where margin pressure from retail clients demands granular cost visibility.
Automated Material Handling (AMH) Equipment Market Segmentation
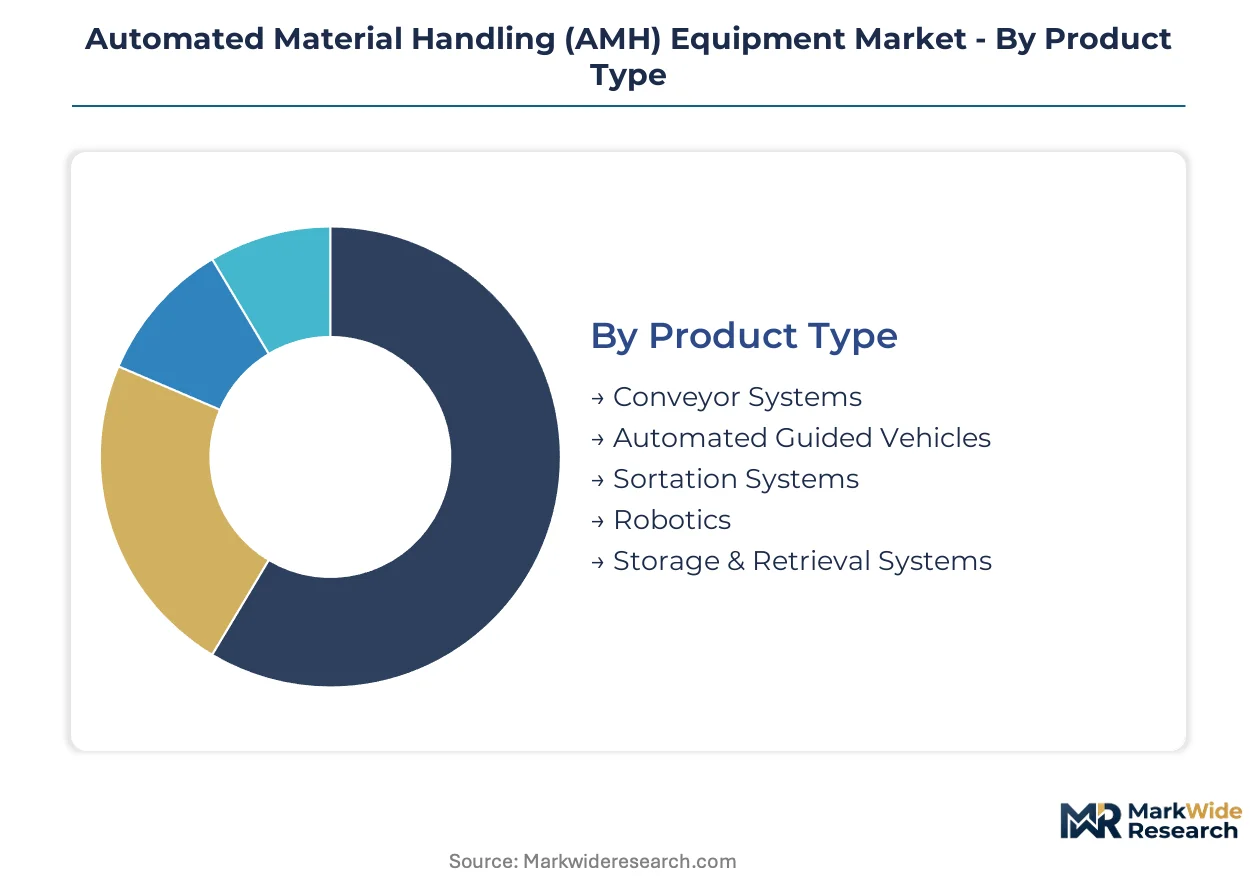
Segmentation in the Automated Material Handling Equipment Market reveals how technology maturity, application intensity, and end-user sophistication create distinct competitive arenas. Equipment specifications, navigation protocols, and facility types each shape procurement patterns and vendor positioning differently.
Product Type:
Mature steel-frame installations dominate the installed base while emerging robotics and autonomous platforms capture greenfield investment.
- Conveyor Systems:Belt and roller configurations rated for specific load capacities form the backbone of high-throughput facilities. German automotive stamping plants and Dutch e-commerce fulfillment centers drive replacement demand as OSHA and EU Machinery Directive compliance windows tighten.
- Robotics:Articulated arm systems and collaborative platforms integrate vision guidance for variable SKU handling. E-commerce distribution networks in Belgium and the United Kingdom deploy these for omnichannel fulfillment where package dimensions fluctuate unpredictably.
- Automated Guided Vehicles:Laser-guided and magnetic-tape variants transport palletized loads with sub-centimeter positioning accuracy. Food and beverage distributors favor compact designs for narrow-aisle European warehousing.
- Sortation Systems:Cross-belt and tilt-tray configurations route parcels by destination code. Airport baggage handling networks in Japan and Germany sustain demand for high-speed diverters.
- Storage & Retrieval Systems:Shuttle-based and crane-based architectures operate at heights exceeding 40 meters. Chemical producers in Baden-Württemberg deploy these for dense automated warehousing.
Conveyor systems handle the majority of throughput; robotics is the fastest mover on share.
Technology:
Navigation and sensing protocols segment by cost tier and deployment flexibility, with premium laser and vision systems displacing legacy magnetic infrastructure.
- Laser Navigation:LiDAR-based positioning enables dynamic path planning without physical infrastructure modification. German automotive plants prioritize this for flexible manufacturing lines where production layouts shift quarterly.
- Vision-Based Guidance:Camera arrays and machine learning algorithms interpret environmental features for navigation. E-commerce fulfillment centers in the Netherlands adopt these for SKU-proliferated environments where routing flexibility dominates.
- Magnetic Tape Guidance:Embedded floor tape provides deterministic routing at lowest capital cost. Mature installations in North American food processing retain this for predictable, high-volume lanes.
- Ultrasonic Sensors:Proximity detection supplements primary navigation for collision avoidance. Pharmaceutical cleanrooms specify these for redundant safety architectures.
- Radio Frequency Identification:Tag-based location tracking coordinates fleet movements and inventory positioning. Third-party logistics providers in the United Kingdom integrate this with warehouse management systems for real-time visibility.
Laser navigation commands the premium tier; vision-based guidance is expanding most quickly as camera costs decline.
Application:
Facility type determines equipment scale, throughput requirements, and regulatory exposure across the maturity spectrum.
- Distribution Centers:Omnichannel fulfillment networks combine conveyor, sortation, and robotics for variable package handling. Belgian and Dutch operators lead adoption of digital twin commissioning to compress deployment timelines.
- Warehousing:Automated storage and retrieval systems maximize cubic utilization in dense European facilities. German chemical and automotive clusters generate sustained demand for shuttle-based architectures.
- Manufacturing Plants:AGV fleets synchronize with production schedules for just-in-time component delivery. Japanese automotive assembly lines specify METI-compliant motor and drive configurations.
- Airports:Baggage handling systems integrate conveyor networks with automated sortation. Daifuku's installed base in this segment secures long-term maintenance contract revenue.
- Ports & Terminals:Heavy-duty AGVs and crane automation handle container movement. European port operators face EU Machinery Directive cybersecurity assessments for networked safety controllers.
Distribution centers concentrate the fastest technology refresh cycles; manufacturing plants represent the deepest installed base.
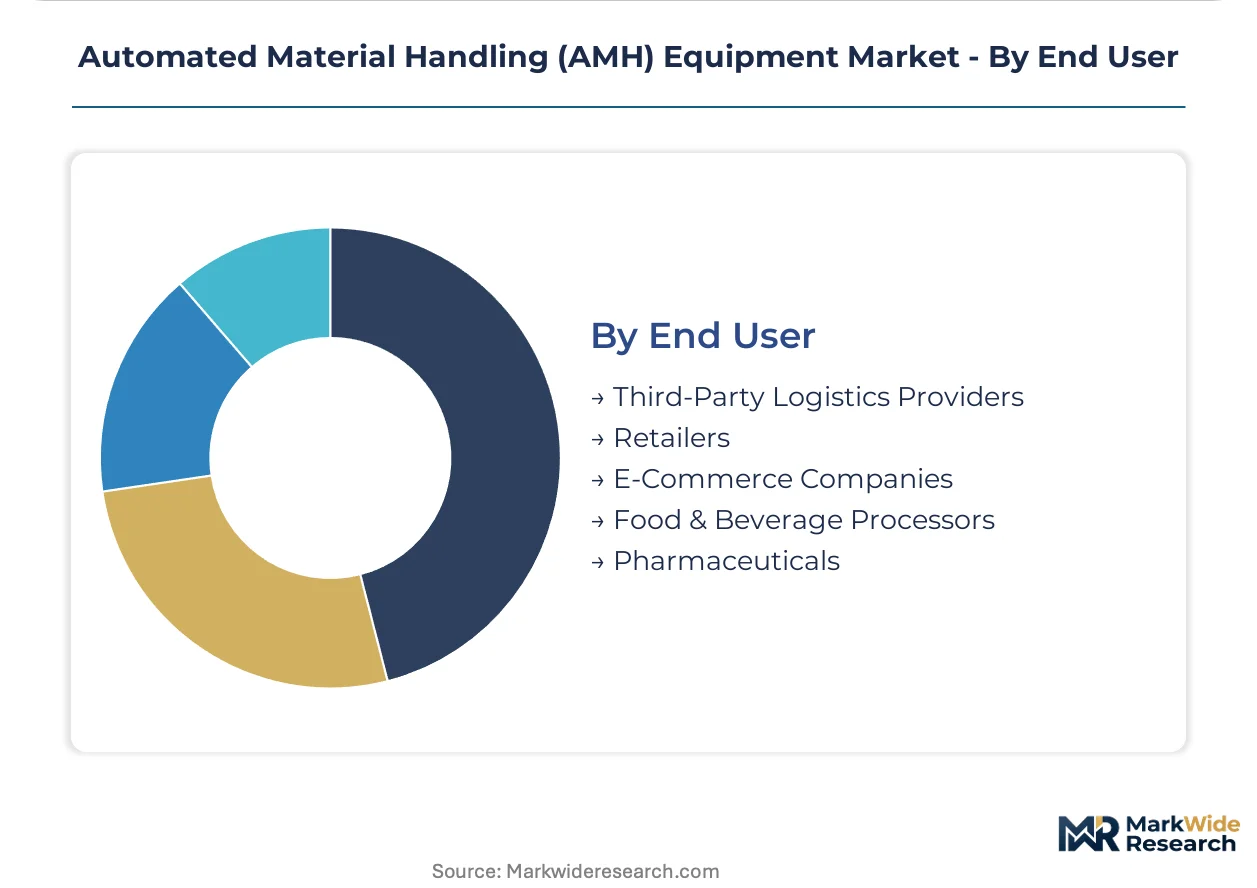
End User:
Customer sophistication and margin structure segment procurement between capital-owning operators and service-based intermediaries.
- E-Commerce Companies:Direct operators of fulfillment networks prioritize routing flexibility and peak-season throughput. These buyers require total cost of ownership models spanning fifteen-year equipment lifecycles.
- Third-Party Logistics Providers:Contract logistics operators unbundle maintenance from OEMs to source independent service organizations. UK-based 3PLs facing retail client margin pressure demand granular cost visibility.
- Retailers:Omnichannel operators retrofit legacy distribution infrastructure for online order fulfillment. OSHA lockout/tagout mandates accelerate replacement timelines for pre-2010 conveyor installations.
- Food & Beverage Processors:Hygienic design specifications and temperature-controlled environments constrain equipment selection. Vision-guided systems struggle with transparent packaging, requiring human intervention.
- Pharmaceuticals:Cleanroom compliance and batch traceability requirements drive specification intensity. Reflective packaging surfaces challenge camera-based guidance systems.
Third-party logistics providers dominate mid-market volume; e-commerce companies are gaining share fastest on greenfield automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, prioritizing precision and compliance over capital savings, while Indian and Mexican operators remain highly sensitive to upfront equipment costs despite accelerating automation interest.
United States
E-commerce fulfillment networks and automotive stamping plants drive equipment procurement across the Midwest and Southeast. OSHA lockout/tagout mandates accelerate replacement timelines for pre-2010 conveyor installations. Distribution centers in Ohio and Tennessee retrofit legacy infrastructure with interlocked guarding architectures.
Germany
Automotive and chemical producers in Baden-Württemberg and North Rhine-Westphalia sustain dense automated warehousing networks. The EU Machinery Directive's safety integrity requirements and 2023 cybersecurity assessments for networked controllers shape procurement specifications. Stuttgart-area stamping plants prioritize suppliers with pre-certified safety PLC platforms.
Japan
Airport baggage handling networks and automotive assembly lines anchor demand for high-reliability systems. METI energy-efficiency guidelines for industrial machinery shape motor and drive specifications in domestic manufacturing deployments. Nagoya-area automotive facilities specify compliant configurations for just-in-time component delivery.
India
The PLI scheme for electronics and automotive manufacturing drives greenfield facility construction requiring integrated material handling infrastructure. Central Electricity Authority regulations and state-level industrial safety codes influence equipment selection criteria. Gujarat and Maharashtra host emerging clusters of contract logistics automation.
Netherlands
E-commerce fulfillment operators adopt digital twin commissioning tools to simulate peak-season throughput scenarios before hardware deployment. REACH and CE marking requirements govern equipment import and installation protocols. Rotterdam-area distribution centers virtualize traditional pilot-plant validation for multi-vendor installations.
Automated Material Handling (AMH) Equipment Market Key Industry Players
Capability concentration sits with specialized automation architects; scale advantage sits with diversified industrial conglomerates. The market structure tiers between precision-engineering specialists serving regulated European facilities and volume-oriented suppliers capturing Asian greenfield expansion. Three archetypes dominate: integrated system providers, component-specialist vendors, and aftermarket service platforms. Competitive moves center on backward integration into battery and drive technologies and geographic expansion through local assembly partnerships.
Among Japanese industrial groups, Daifuku Co. Ltd and Toyota Industries Corporation occupy positions spanning airport logistics and manufacturing automation. German engineering houses KION Group and Jungheinrich AG exemplify the European precision tier, with the latter representing compact vehicle specialization for dense warehousing environments. Honeywell International Inc. anchors the diversified technology conglomerate archetype, sitting within a portfolio that crosses automation with building systems and software platforms.
| Leading Market Players |
|---|
| Daifuku Co. Ltd |
| KION Group |
| Jungheinrich AG |
| SSI Schaefer |
| Toyota Industries Corporation |
| Honeywell International Inc. |
| Crown Equipment Corporation |
| Dematic |
| BEUMER Group |
| Others |
Cost & Logistics Intelligence
Chinese permanent magnet suppliers and German precision-drive manufacturers anchor upstream cost structures, concentrating margin capture in aftermarket service tiers where Daifuku and KION Group lock in long-term maintenance contracts. Steel-frame conveyor fabricators in South Korea and Japan feed replacement cycles driven by OSHA and EU Machinery Directive compliance windows, while battery cell producers in China and South Korea shape electrification economics for AGV fleets.
Pricing Analysis
Aftermarket service contracts and extended warranty tiers generate lifetime value multiples exceeding original equipment sales. Three-tier pricing structure across premium laser-navigation systems, standard magnetic-tape configurations, and economy-grade roller conveyors reflects certification grade and integration complexity. Cost compression in entry-level AGV segments is intensifying because Chinese manufacturers are scaling LiDAR production. Third-party logistics providers exhibit highest price sensitivity, while German automotive stamping plants prioritize precision over capital savings.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn Industrial Internet, Jabil, and Benchmark Electronics holding capacity for safety PLC and motor drive assemblies. Component sourcing draws from China for rare-earth magnets, Germany for precision gearboxes, and Japan for servo motors. Single-source vulnerability in neodymium supply creates exposure to Chinese export quota shifts. Distribution runs through OEM direct sales for large installations, with system integrators and independent service organizations capturing mid-market retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from robotics-as-a-service platforms and autonomous mobile robot pure-plays that bypass traditional capital expenditure cycles. Defense requires locking in fleet management software ecosystems before point-solution vendors capture greenfield e-commerce deployments.
For Market Incumbents: Pre-empt robotics-as-a-service entrants by bundling predictive maintenance software with hardware contracts. Capture battery and drive technologies through backward integration to secure margin pools threatened by Chinese motor suppliers. Accelerate pre-certification of safety PLC platforms against EU Machinery Directive cybersecurity assessments before compliance windows tighten further.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-driven electronics manufacturing clusters where greenfield automation demand outpaces incumbent service capacity. Target narrow-aisle warehousing retrofits in European food and beverage distribution, a segment underserved by laser-guided AGV specialists. Lead with outcome-based uptime guarantees rather than capital equipment sales to bypass incumbent financing relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract logistics operators in the United Kingdom and Netherlands facing margin compression from retail clients. Five-to-ten year viability hinges on software-enabled fleet management differentiation versus hardware commoditization. Monitor lithium-ion battery cost curves as the inflection signal for electric lift truck conversion economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | KION Group's captive lithium-ion production secures 24/7 fleet operation economics against Chinese supplier volatility. |
| Digital Twin Platform Deployment | Dutch e-commerce operators compress commissioning timelines by simulating peak-season throughput before hardware installation. |
| Pre-Certified Safety PLC Investment | Stuttgart-area automotive plants accelerate EU Machinery Directive compliance by sourcing pre-validated networked controllers. |
| Outcome-Based Maintenance Contracts | Equipment-as-a-service models shift capital expenditure to operating budgets, opening mid-market facilities previously priced out. |
| India Manufacturing Cluster Partnership | Gujarat and Maharashtra greenfield facilities require integrated material handling infrastructure under PLI scheme incentives. |
Research Approach
Cross-validation between equipment procurement databases and regulatory filing archives anchors the qualitative findings across the analysis window. Primary interviews with maintenance directors at German automotive plants, aftermarket service heads at Japanese airport logistics operators, and plant engineers at Dutch e-commerce fulfillment centers were combined with secondary validation from OSHA enforcement records, EU Machinery Directive implementation guidance, and METI energy-efficiency compliance filings. Bottom-up triangulation against vendor shipment data and top-down reconciliation against facility automation investment surveys ensure coverage consistency.
Calibration against historical replacement cycles and regulatory compliance windows shapes the analytical framework. Segmentation dimensions span equipment type, navigation technology, facility application, and end-user sophistication across the modeling period. CAGRs derive from regression against installed base age profiles and greenfield capital expenditure intentions. Forecast inputs include rare-earth magnet price indices and battery chemistry advancement trajectories.
Stress conditions across neodymium export quota volatility, lithium-ion cell supply constraints, and EU cybersecurity assessment timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and labor availability constraints. Cross-checking against customs records for AGV and conveyor system trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Electric Single Beam Crane Market
Material Handling Equipment
Elevator Ropes Market
Material Handling Equipment
Low Clearance Loaders Market
Material Handling Equipment
Material Handling Monorails Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Global Forklift Market
Material Handling Equipment
Forklift Rental Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Trencher Attachments Market