
 Material Handling Integration Market | 2026-2036
Material Handling Integration Market Size, Share, and Industry Trends Forecast 2026-2036
Material Handling Integration Market Analytics
The EU Green Deal is shifting procurement priorities across European distribution networks toward energy-efficient automation. Daifuku Co., Ltd. leverages its deep vertical integration in automated storage and retrieval to dominate high-throughput e-commerce fulfillment. SSI Schaefer Group anchors its competitive position through specialized software-driven orchestration of heterogeneous equipment fleets. Jungheinrich AG differentiates via electric drive technology leadership and dense channel control across Central European warehouse operators.
Material handling integration encompasses the engineering, control software, and mechanical interfacing required to synchronize conveyors, automated guided vehicles, robotic arms, and pallet jacks into unified operational workflows. Typical implementations demand sub-second latency between supervisory control systems and field devices, with throughput specifications often exceeding 10,000 unit-load movements per hour in large-scale distribution applications. Automated Guided Vehicles represent the fastest-expanding product category as lithium-ion powertrains and AI-driven path optimization displace wire-guided legacy fleets. IoT Solutions and AI Integration together command the deepest margin pools, since predictive maintenance and real-time traffic management command recurring software licensing fees atop hardware sales.
OSHA workplace safety mandates and the EU Machinery Directive shape equipment guarding, emergency stop architectures, and functional safety ratings for integrated systems deployed across US and European facilities. CE marking requirements and ISO 3691-4 safety standards for driverless industrial trucks constrain market access for non-compliant suppliers and elevate R&D spending on sensor fusion and redundant braking. Stakeholders must monitor how rapidly evolving AI liability frameworks will reallocate risk between equipment OEMs, systems integrators, and end-user operators.
Market Dynamics
EU Green Deal carbon mandates are forcing warehouse operators to retire diesel-powered forklift fleets and retrofit facilities with electrified conveyor networks and regenerative-drive AGVs.
Growth Catalysts
- EU Green Deal decarbonization mandates:Warehouse operators across Germany, France, and the Netherlands face binding emissions targets that accelerate procurement of lithium-ion AGVs and energy-recovery conveyor systems.
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics distribution is driving demand for automated handling systems with validated environmental monitoring and track-and-trace integration.
- AI-driven path optimization:Machine learning algorithms reduce AGV fleet congestion by 40% in high-density storage environments, justifying premium system investments.
Market Restraints
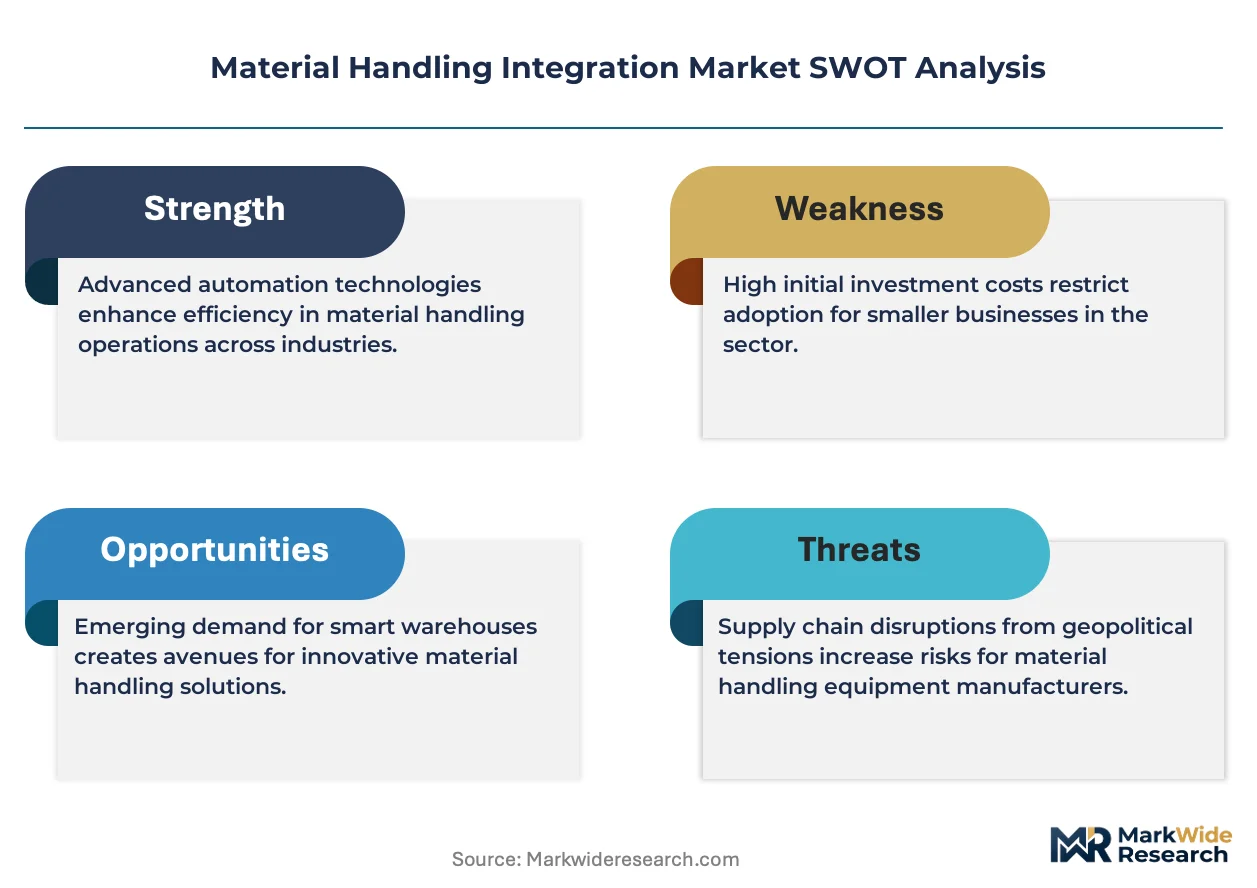
- Lithium-ion battery supply concentration:Cathode material processing and cell manufacturing cluster in China, exposing European integrators to geopolitical supply disruptions and forced technology transfer requirements.
- ISO 3691-4 compliance costs:Safety certification for autonomous mobile robots requires redundant lidar arrays and functional safety-rated controllers, adding 15-25% to hardware bills of materials.
- Wire-guided legacy fleet entrenchment:Existing magnetic tape and induction-loop installations in automotive assembly plants create switching friction against free-navigation AMR alternatives.
Strategic Opportunities
- India warehouse automation underpenetration:Third-party logistics providers in Mumbai and Bangalore are greenfielding distribution centers with native AGV integration, bypassing legacy retrofit constraints.
- Pharmaceutical serialization convergence:EU MDR and US DSCSA track-and-trace mandates create bundled demand for handling systems with integrated vision verification and aggregation software.
- 5G private network deployment:Ultra-reliable low-latency communication enables real-time AGV coordination at densities exceeding Wi-Fi capacity, unlocking new high-throughput configurations.
Industry Challenges
- Controls engineering talent scarcity:PLC programming and safety-certified system integration expertise concentrates in Germany and Japan, constraining deployment velocity in emerging markets.
- Heterogeneous fleet orchestration complexity:Mixed-vendor environments combining conveyors, robotic arms, and AGVs demand middleware development that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Material Handling Integration Market |
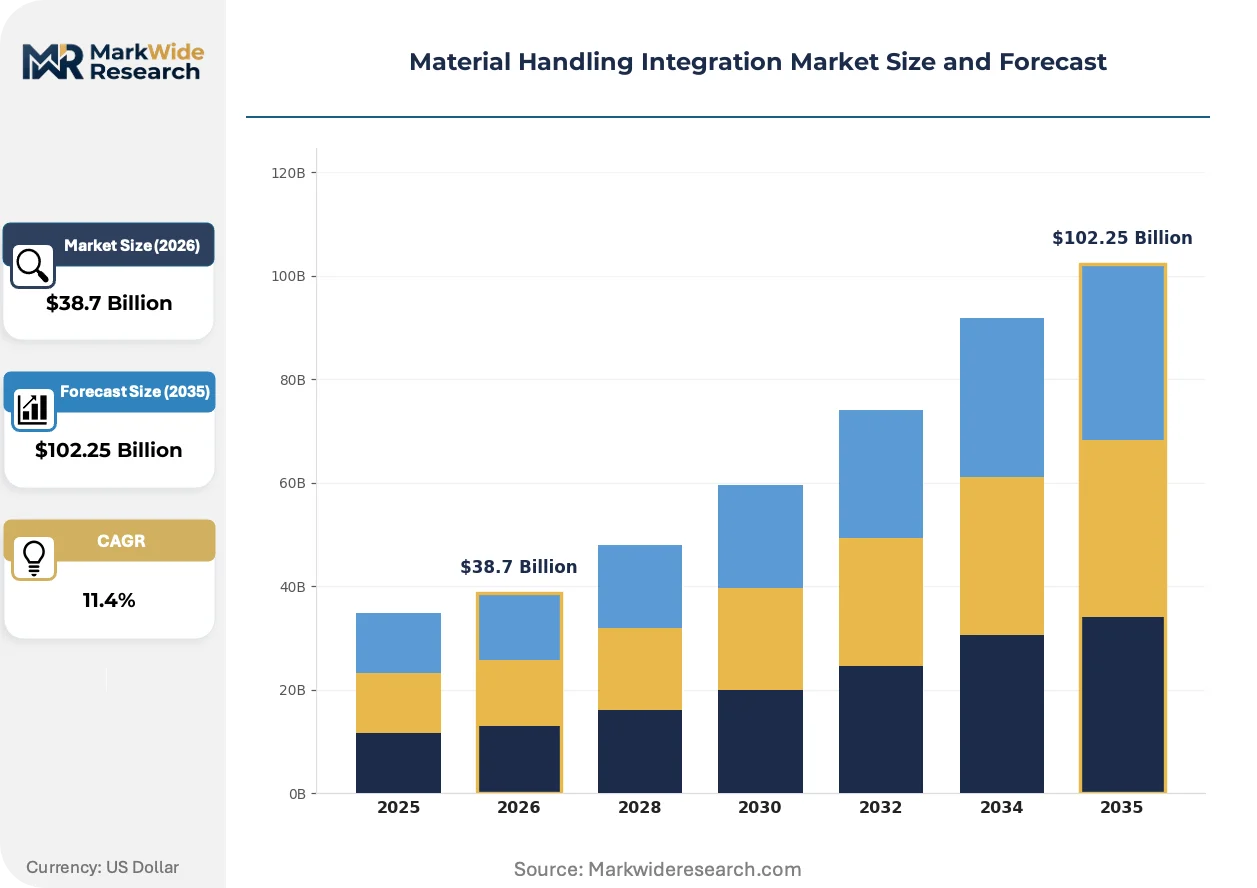
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Conveyor Systems, Robotic Arms, Pallet Jacks Technology: IoT Solutions, AI Integration, Cloud Systems, RFID Technology End User: Manufacturing Facilities, Warehouses, Distribution Centers, Retail Outlets Installation: On-site Installation, Remote Installation, Retrofit Solutions, Turnkey Solutions |
| Companies Covered | Daifuku Co., Ltd., Honeywell International Inc., KION Group, SSI Schaefer Group, TGW Logistics Group, Knapp AG, Fives, Jungheinrich AG, Murata Machinery Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Material Handling Integration Market Evolving Landscape
Software-defined orchestration is displacing hardwired control architectures across distribution facilities, compressing reconfiguration costs and enabling dynamic capacity scaling.
Edge-computing nodes with onboard AI accelerators are modularizing AGV control systems, allowing fulfillment centers to deploy heterogeneous robot fleets without centralized server infrastructure. E-commerce operators in Poland and the Czech Republic are adopting plug-and-play vehicle modules that reduce integration engineering from months to weeks. This architecture is modularizing the traditional systems integrator role toward software configuration rather than custom control panel fabrication.
The EU AI Act risk-classification framework imposes conformity assessment requirements on autonomous material handling systems with self-learning navigation capabilities. High-risk AI categorization triggers third-party auditing and post-market monitoring obligations for warehouse operators deploying adaptive fleet management. German automotive distribution hubs are responding by segregating deterministic zone-to-zone transport from AI-enabled dynamic routing to limit regulatory exposure.
Third-party logistics providers are unbundling equipment ownership from operational responsibility, contracting integrators for throughput-guaranteed service agreements rather than capital purchases. This model transfers utilization risk to vendors and aligns payment with carton-movement volumes. The shift is most visible in Benelux contract logistics, where DHL Supply Chain and Kuehne+Nagel facilities now favor opex-based automation procurement over traditional seven-year depreciation cycles.
Material Handling Integration Market Segmentation
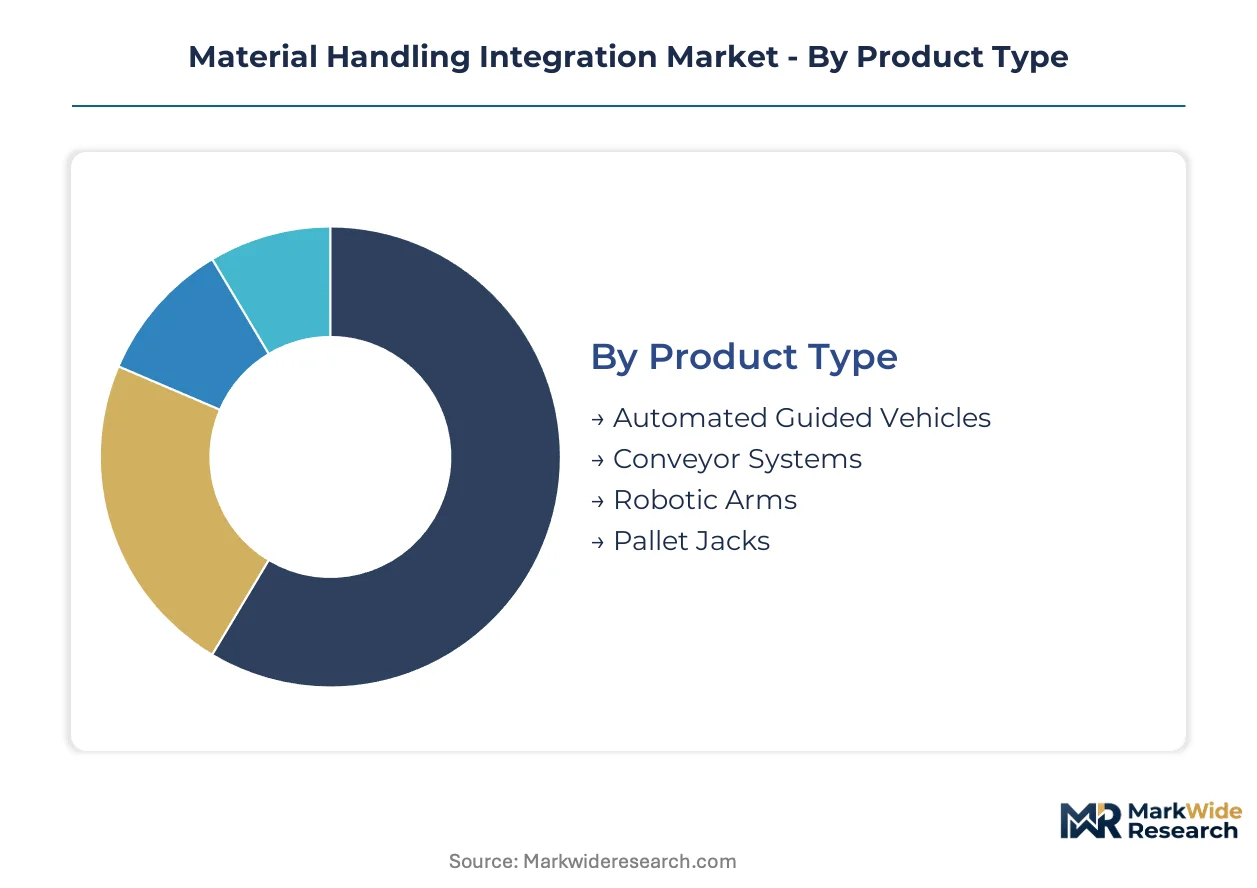
Material handling integration vendors configure solutions across four distinct axes: physical equipment, intelligence layer, operational setting, and deployment methodology. Procurement patterns diverge sharply between greenfield e-commerce fulfillment requiring native automation and legacy automotive plants demanding phased retrofit integration.
Product Type:
Standardized chassis platforms dominate high-volume conveyor deployments, while AGV and robotic arm configurations demand extensive application-specific engineering.
- Automated Guided Vehicles:Lithium-ion powertrains with AI path optimization displace wire-guided legacy fleets across German automotive distribution hubs. Pharmaceutical cold-chain operators in the Netherlands specify validated temperature-monitoring AGVs for biologics transport, driven by EU MDR track-and-trace mandates.
- Conveyor Systems:Modular belt and roller configurations with regenerative-drive motors recover braking energy for warehouse electrification targets. French and Belgian e-commerce fulfillment centers prioritize energy-recovery models to satisfy EU Green Deal carbon reduction commitments.
- Robotic Arms:Six-axis articulated units with vision-guided pick-and-place handle heterogeneous carton sizes in mixed-SKU environments.
- Pallet Jacks:Electric walkie and rider models with lithium-ion swaps serve low-throughput retail backrooms and small-format warehouses.
Leading the category by volume: Conveyor Systems. Expanding most quickly: Automated Guided Vehicles.
Technology:
Margin concentration pools in software layers commanding recurring licensing, while hardware sensor components face commoditization pressure.
- IoT Solutions:Edge-deployed sensor networks stream vibration, temperature, and motor current data to cloud analytics platforms. German warehouse operators bundle IoT subscriptions with maintenance contracts to satisfy ISO 3691-4 predictive safety monitoring requirements.
- AI Integration:Machine learning models optimize AGV fleet routing and predict conveyor component failures before functional degradation. Polish and Czech e-commerce hubs adopt plug-and-play AI modules that compress commissioning from months to weeks.
- Cloud Systems:Centralized warehouse execution software synchronizes heterogeneous equipment fleets through API-native orchestration.
- RFID Technology:UHF passive tags and fixed portal readers enable carton-level tracking without line-of-sight constraints.
Highest recurring revenue capture: IoT Solutions. Gaining share fastest: AI Integration.
End User:
Facility scale and SKU velocity determine automation sophistication, with pharmaceutical distribution demanding validated environmental controls absent in general retail.
- Manufacturing Facilities:Just-in-time assembly lines require synchronous conveyor-AGV handoffs with sub-second latency. Automotive plants in Stuttgart and Wolfsburg retrofit legacy magnetic-tape guided vehicles with free-navigation AMR alternatives.
- Warehouses:High-bay storage and retrieval operations integrate automated stacker cranes with shuttle systems for dense inventory positioning. German pharmaceutical distributors specify validated warehouse management integration for EU MDR serialization compliance.
- Distribution Centers:Cross-dock and fulfillment operations prioritize throughput velocity over storage density.
- Retail Outlets:Backroom automation and micro-fulfillment centers handle last-mile consolidation for omnichannel order streams.
Deepest automation penetration: Manufacturing Facilities. Steepest expansion trajectory: Distribution Centers.
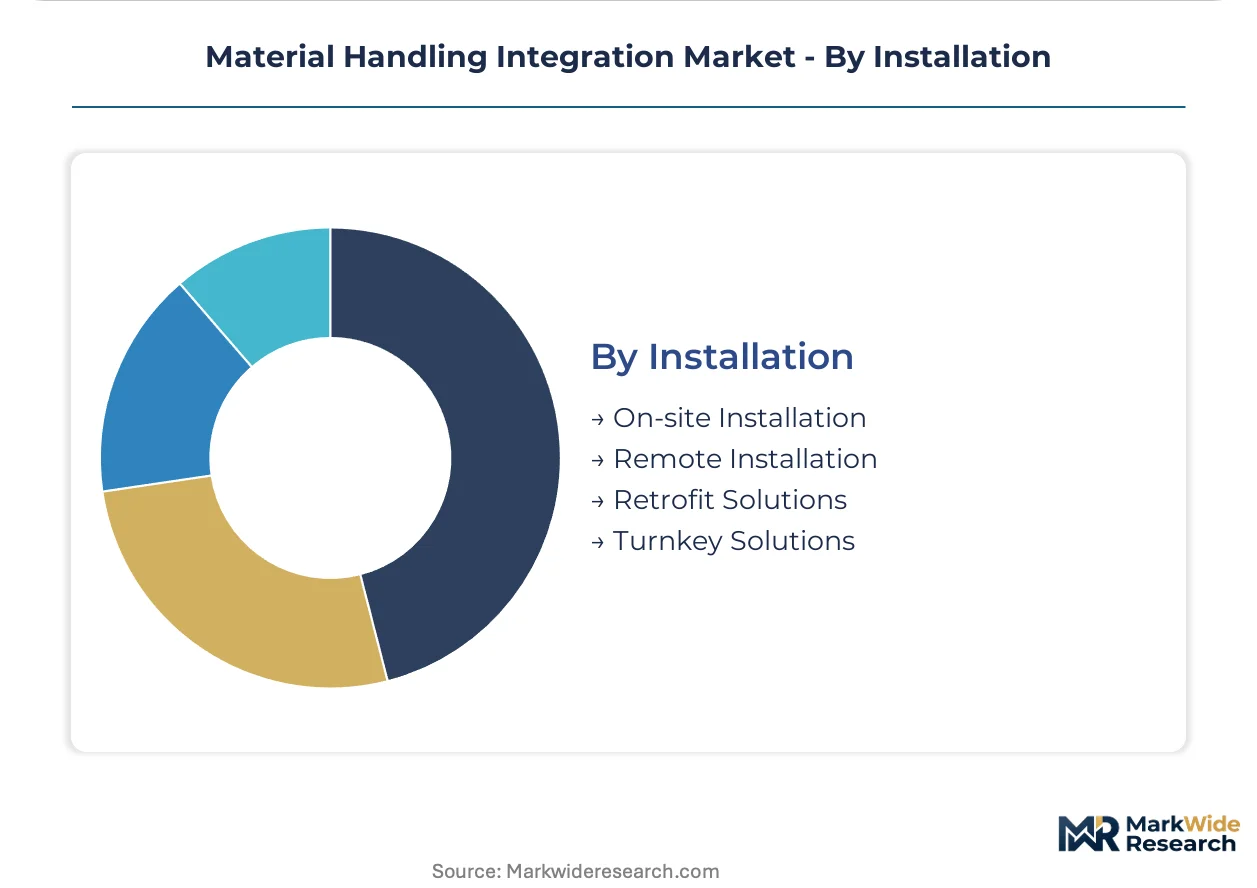
Installation:
Deployment risk allocation shifts between capital ownership models and throughput-guaranteed service contracts across European contract logistics.
- On-site Installation:Commissioning teams deploy hardware with localized PLC programming and safety certification. German integrators concentrate controls engineering talent for ISO 3691-4 functional safety validation.
- Remote Installation:Cloud-configured AGV fleets reduce on-site engineering through pre-calibrated vehicle modules. Benelux 3PL providers favor remote deployment to accelerate opex-based automation procurement.
- Retrofit Solutions:Phased integration preserves operational continuity in legacy facilities with constrained downtime windows.
- Turnkey Solutions:Single-vendor responsibility for design, installation, and performance guarantees transfers utilization risk.
Dominant procurement model: Turnkey Solutions. Climbing the fastest: Remote Installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the most concentrated material handling integration activity worldwide, with automotive distribution hubs retrofitting legacy magnetic-tape guided vehicles with free-navigation alternatives. The city's dense cluster of systems integrators and controls engineering talent compresses commissioning timelines for high-throughput conveyor-AGV synchronization.
Germany
Automotive and pharmaceutical distribution hubs in Wolfsburg and Mannheim drive retrofit demand for integrated robotic and IoT-enabled handling platforms. EU Green Deal decarbonization mandates force warehouse operators toward lithium-ion AGV fleets and regenerative-drive conveyor systems. Stuttgart's engineering corridor concentrates PLC programming expertise for ISO 3691-4 functional safety validation.
United States
E-commerce fulfillment centers across Pennsylvania and Ohio expand automated material handling footprints to manage SKU proliferation and same-day delivery windows. OSHA workplace safety mandates shape equipment guarding and emergency stop architectures for integrated systems. The Midwest automotive belt around Detroit retrofit legacy wire-guided fleets with AI-path-optimized alternatives.
China
Lithium-ion battery supply concentration in cathode material processing and cell manufacturing clusters exposes European integrators to geopolitical supply disruptions. Ningbo and Shenzhen port logistics zones deploy high-density AGV coordination for container handling and cross-dock operations. MIIT industrial automation directives accelerate domestic controller and sensor module substitution.
Netherlands
Benelux contract logistics providers favor opex-based automation procurement over traditional seven-year depreciation cycles. EU MDR track-and-trace mandates create bundled demand for handling systems with integrated vision verification in Rotterdam pharmaceutical distribution. DHL Supply Chain and Kuehne+Nagel facilities now contract integrators for throughput-guaranteed service agreements.
India
Third-party logistics providers in Mumbai and Bangalore greenfield distribution centers with native AGV integration, bypassing legacy retrofit constraints. PLI scheme incentives for advanced manufacturing equipment reduce capital barriers for automation adoption. The Delhi-NCR corridor concentrates warehousing demand from e-commerce operators seeking last-mile consolidation infrastructure.
Material Handling Integration Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive controls engineering capabilities. Japanese and German fabricators dominate high-throughput e-commerce fulfillment through deep backward integration into automated storage and retrieval hardware. Three archetypes define positioning: software-driven orchestration specialists, electric drive technology leaders, and diversified logistics automation conglomerates. M&A activity concentrates on middleware developers bridging heterogeneous fleet environments, while capacity expansion targets Indian and Southeast Asian greenfield warehousing corridors.
Among Japanese fabricators, Daifuku Co., Ltd. and Murata Machinery Ltd. exemplify the diversified conglomerate archetype with captive production of automated storage infrastructure. SSI Schaefer Group anchors the German specialist tier through software-driven orchestration capabilities. These three occupy positions spanning the full integration stack from mechanical chassis to warehouse execution software, representing the structural tilt toward vertically integrated solution providers.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Honeywell International Inc. |
| KION Group |
| SSI Schaefer Group |
| TGW Logistics Group |
| Knapp AG |
| Fives |
| Jungheinrich AG |
| Murata Machinery Ltd. |
| Others |
Value Network & Pricing Analysis
Controls engineering talent concentration in Germany and Japan creates labor-cost differentials that widen pricing-tier spreads between ISO 3691-4 certified integrators and uncertified competitors serving emerging markets. European warehouse operators absorb premium pricing for functional safety validation while Indian greenfield projects capture cost advantages through remote deployment architectures.
Pricing Analysis
Throughput-guaranteed service agreements anchor value-based pricing in Benelux contract logistics, where DHL Supply Chain and Kuehne+Nagel pay per carton-movement rather than capital outlay. Three-tier pricing structure across premium, standard, and economy levels separates certified European integrators from Asian hardware suppliers and regional maintenance providers. Cost compression in economy-tier conveyor hardware is intensifying because Chinese controller and sensor module substitution accelerates under MIIT directives. Pharmaceutical cold-chain operators show least price sensitivity given EU MDR compliance requirements, while retail backroom buyers drive hardest bargains on electric pallet jack procurement.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for turnkey warehouse execution systems, while distributor networks serve mid-market retrofit projects. Lithium-ion battery cell manufacturing concentrates in China, South Korea, and Japan, exposing European AGV integrators to cathode material processing bottlenecks. Control system hardware draws from Taiwanese semiconductor foundries and German precision motor suppliers. Single-source vulnerability in PLC programming talent constrains deployment velocity outside Stuttgart and Wolfsburg engineering corridors. Distribution runs through systems integrators with captive controls engineering capabilities rather than component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The material handling integration market is accelerating into a vertical-integration race. Players are pursuing backward integration into automated storage hardware and AI-driven orchestration software to capture margin pools beyond mechanical chassis fabrication.
For Market Incumbents: Anchor competitive position through captive production of automated storage infrastructure and warehouse execution software stacks. Deepen backward integration into lithium-ion powertrain engineering to offset battery supply concentration risk. ISO 3691-4 certification investment creates switching costs against emerging Asian controller suppliers. Defend against software-defined orchestration disruptors by acquiring middleware developers bridging heterogeneous fleet environments. For New Entrants and Emerging Players: AI-driven path optimization modules offer technology-first wedge into Polish and Czech e-commerce fulfillment hubs seeking plug-and-play deployment. Greenfield warehouse automation in Mumbai and Bangalore presents most penetrable geography, bypassing legacy magnetic-tape retrofit constraints. Target pharmaceutical serialization convergence as entry vector, bundling vision verification with EU MDR track-and-trace compliance. Cloud-configured AGV fleets enable remote deployment go-to-market without Stuttgart-based controls engineering. For Investors and Strategic Acquirers: Re-rating potential sits with software-driven orchestration specialists given 5G private network deployment catalysts unlocking ultra-reliable low-latency AGV coordination. Long-term viability favors vendors with recurring IoT subscription revenue atop hardware sales rather than project-based integrators. Acquisition target archetype: middleware developers with API-native fleet synchronization capabilities. Signal to watch: throughput-guaranteed service agreement penetration exceeding traditional capital purchase models in European contract logistics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powertrain Engineering | Captive lithium-ion AGV production reduces exposure to Chinese cathode supply disruptions. |
| Software-Defined Orchestration Platform | API-native fleet synchronization displaces hardwired PLC architectures in Polish fulfillment centers. |
| ISO 3691-4 Certification Investment | Functional safety validation creates switching costs against non-compliant Asian controller suppliers. |
| Throughput-Guaranteed Service Agreements | Opex-based procurement transfers utilization risk from Benelux 3PL operators to integrators. |
| 5G Private Network Deployment | Ultra-reliable low-latency communication enables AGV densities exceeding Wi-Fi capacity limits. |
Research Methodology
Independent corroboration across systems integrator engineering directors, warehouse operations executives at DHL Supply Chain and Kuehne+Nagel, pharmaceutical distribution compliance officers, and automotive plant logistics managers underwrites the qualitative findings. Secondary validation draws from EU Machinery Directive implementation guidance, OSHA workplace safety enforcement patterns, MIIT industrial automation directives, and SEC filings of publicly traded logistics automation conglomerates. Bottom-up equipment shipment tallies triangulate against top-down warehouse automation capex surveys.
Comparable-period anchoring to historical AGV deployment cycles and conveyor retrofit timelines structures the forecast framework across the analysis window. Segmentation dimensions span product type, intelligence layer technology, end-user facility category, and deployment methodology. CAGRs derive from logistic curve modeling of automation penetration rates against labor cost differentials. Forecast inputs include lithium-ion battery cost trajectories and EU Green Deal carbon mandate enforcement timelines.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations affecting Chinese controller exports and unanticipated AI liability framework reallocations between OEMs and operators. Forecasts reflect assumptions about 5G private network rollout pace and PLC programming talent supply elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Container Handling Equipment Market
Material Handling Equipment
High-Precision Gear Reducer Market
Material Handling Equipment
Low-Level Order Picker Pallet Truck Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Electric Hoist Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Pug Mill Mixers Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Sweep Depalletizers Market