
 Global High Temperature Insulation Materials Market | 2026-2036
Global High Temperature Insulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Temperature Insulation Materials Market Intelligence
Aftermarket service revenue for furnace relining and thermal audit consulting is reconfiguring how insulation suppliers capture lifetime value from industrial accounts. Morgan Advanced Materials leverages its technical service network to anchor long-term contracts across European foundries. RHI Magnesita GmbH competes through captive supply of refractory bricks and installation expertise. Unifrax specializes in ceramic fiber systems for petrochemical clients requiring rapid turnaround maintenance.
High temperature insulation materials are engineered thermal barriers, typically composed of alumina-silica ceramic fibers, calcium silicate hydrates, or microporous silica matrices, designed to withstand continuous operating temperatures exceeding 1,000 degrees Celsius while minimizing heat flux in industrial process equipment. These materials function primarily to reduce energy consumption, protect structural components, and stabilize thermal profiles in furnaces, kilns, and reaction vessels. Ceramic fiber dominates installed volume due to its flexibility and low thermal mass, though microporous insulation commands premium positioning where space constraints and peak temperature performance justify higher material costs. Refractory bricks retain substantial share in metal processing and glass factory applications where mechanical abrasion resistance and dimensional stability under cyclic thermal loading remain non-negotiable.
EPA emissions rules and OSHA workplace exposure limits for respirable crystalline silica are tightening product specifications and accelerating substitution toward biosoluble fiber formulations in the United States. The EU Green Deal industrial decarbonization targets and REACH chemical registration requirements are reshaping material composition standards and import compliance obligations across European manufacturing. China's MEE air quality enforcement and GB standards for industrial energy efficiency are driving similar upgrade cycles in Asian production bases. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D pipelines.
Market Dynamics
Industrial furnace operators in Germany, China, and the United States are retrofitting aging infrastructure under tightening emissions mandates, compressing replacement cycles and forcing material specification upgrades across the installed base.
Growth Catalysts
- EU Green Deal industrial decarbonization targets:European metal processors must achieve 55% emissions reductions by 2030, mandating ceramic fiber upgrades in blast furnaces and heat treatment equipment.
- EPA respirable crystalline silica rules:OSHA workplace exposure limits below 50 micrograms per cubic meter are accelerating biosoluble fiber substitution in US manufacturing facilities.
- China's GB standards for industrial energy efficiency:MEE enforcement of mandatory energy audits is driving replacement of legacy refractory brick with microporous silica systems in steel mills across Hebei and Jiangsu provinces.
Market Restraints
- Alumina-silica raw material volatility:Bauxite and zirconia supply concentration in Guinea and Australia exposes ceramic fiber producers to price swings and freight cost spikes.
- REACH chemical registration complexity:ECHA substance evaluation timelines extending 18-24 months delay new fiber formulation launches in European markets.
- Mechanical abrasion limitations:Ceramic fiber mats fail in glass furnace regenerator chambers where refractory brick retains structural integrity under cyclic thermal loading.
Strategic Opportunities
- India's PLI scheme for specialty steel:Government production-linked incentives for electric arc furnace capacity expansion create captive demand for high-grade insulation in Maharashtra and Gujarat.
- Hydrogen-ready furnace engineering:Convergence of ceramic fiber systems with hydrogen burner retrofits opens specification windows in German and Dutch chemical processing clusters.
- Digital thermal audit platforms:Remote monitoring service contracts bundled with material supply are displacing transactional component sales in US petrochemical maintenance cycles.
Industry Challenges
- Refractory installation technician shortage:Specialized furnace lining crews with ceramic fiber certification command 40% wage premiums, constraining project execution velocity.
- Legacy brick-to-fiber retrofit engineering:Structural steel modifications required for lower-density insulation systems extend downtime windows beyond planned maintenance schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Temperature Insulation Materials Market |
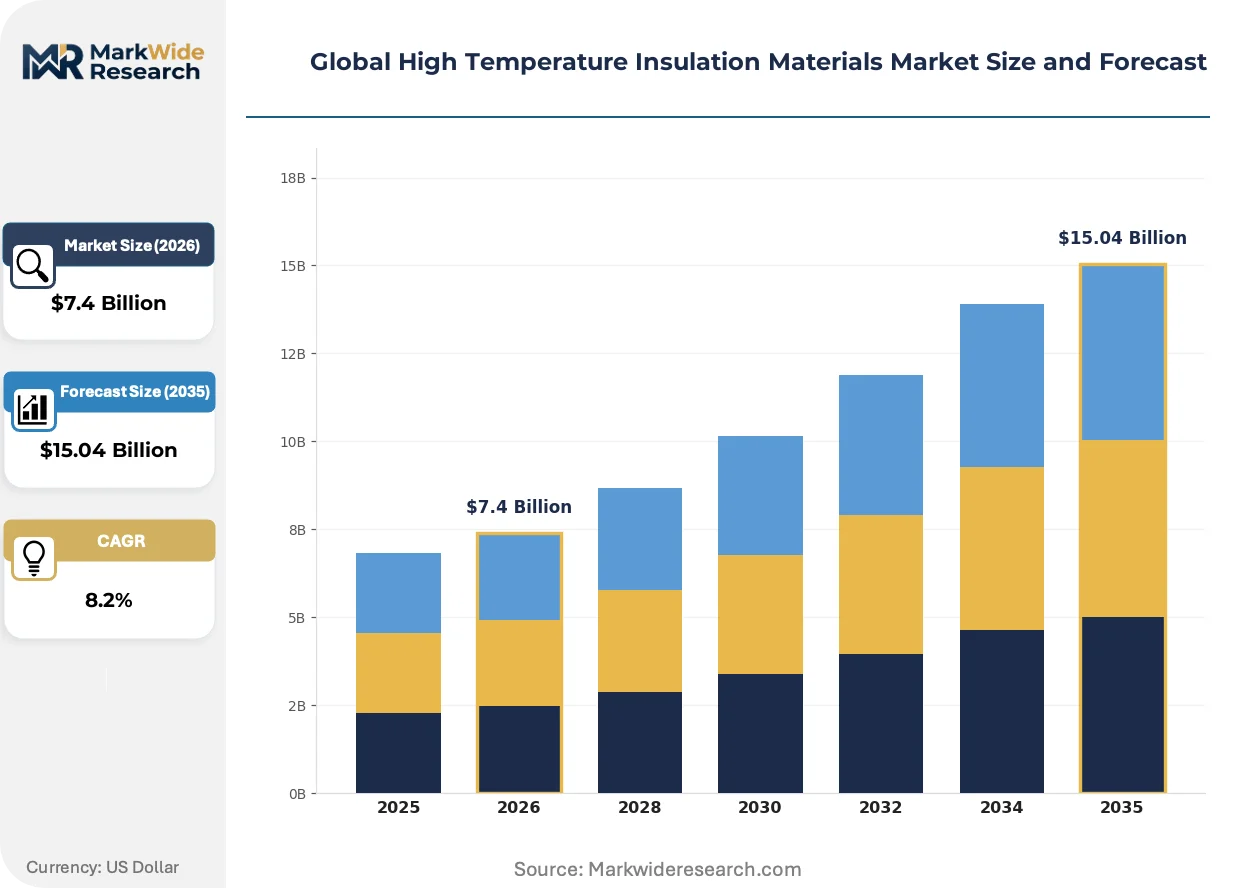
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $15.04 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Fiber, Calcium Silicate, Refractory Bricks, Vermiculite, Microporous Insulation Technology: Vacuum Insulation, Aerogel, Fiberglass, Foam Glass, Intumescent Coatings Application: Power Generation, Petrochemical Plants, Metal Processing, Industrial Furnaces, Kilns End User: Energy Producers, Chemical Manufacturers, Foundries, Heat Treatment Facilities, Glass Factories |
| Companies Covered | Morgan Advanced Materials, 3M, Luyang Energy-saving Materials Co., Ltd., RHI Magnesita GmbH, Etex Group, Unifrax, Promat, Alkegen, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Temperature Insulation Materials Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are converging to reshape product portfolios, with digital integration emerging as the dominant vector for competitive differentiation.
Smart thermal monitoring systems embedded in ceramic fiber modules are digitizing furnace performance optimization. Steel mills in the Ruhr region and glass manufacturers in Ohio are deploying sensor-integrated linings that transmit real-time heat flux data to predictive maintenance platforms. Equipment uptime improvements of 8-12% are compressing total cost-of-ownership calculations and repositioning insulation from commodity purchase to operational technology investment.
REACH Annex XVII restrictions on refractory ceramic fibers are forcing reformulation across European supply chains. ECHA classification of traditional alumino-silicate wools as Category 1B carcinogens is triggering mandatory substitution timelines in France, Germany, and Italy. Biosoluble alkaline earth silicate fibers are capturing specification share in foundry and petrochemical applications where fiber release exposure risk exceeds regulatory thresholds.
Integrated service contracting is displacing component-only procurement in heavy industrial accounts. Morgan Advanced Materials and RHI Magnesita now anchor multi-year agreements covering thermal audit consulting, installation supervision, and predictive relining schedules. This bundling concentrates buyer relationships with full-service providers and marginalizes pure material distributors in German and US metal processing markets.
Global High Temperature Insulation Materials Market Segmentation
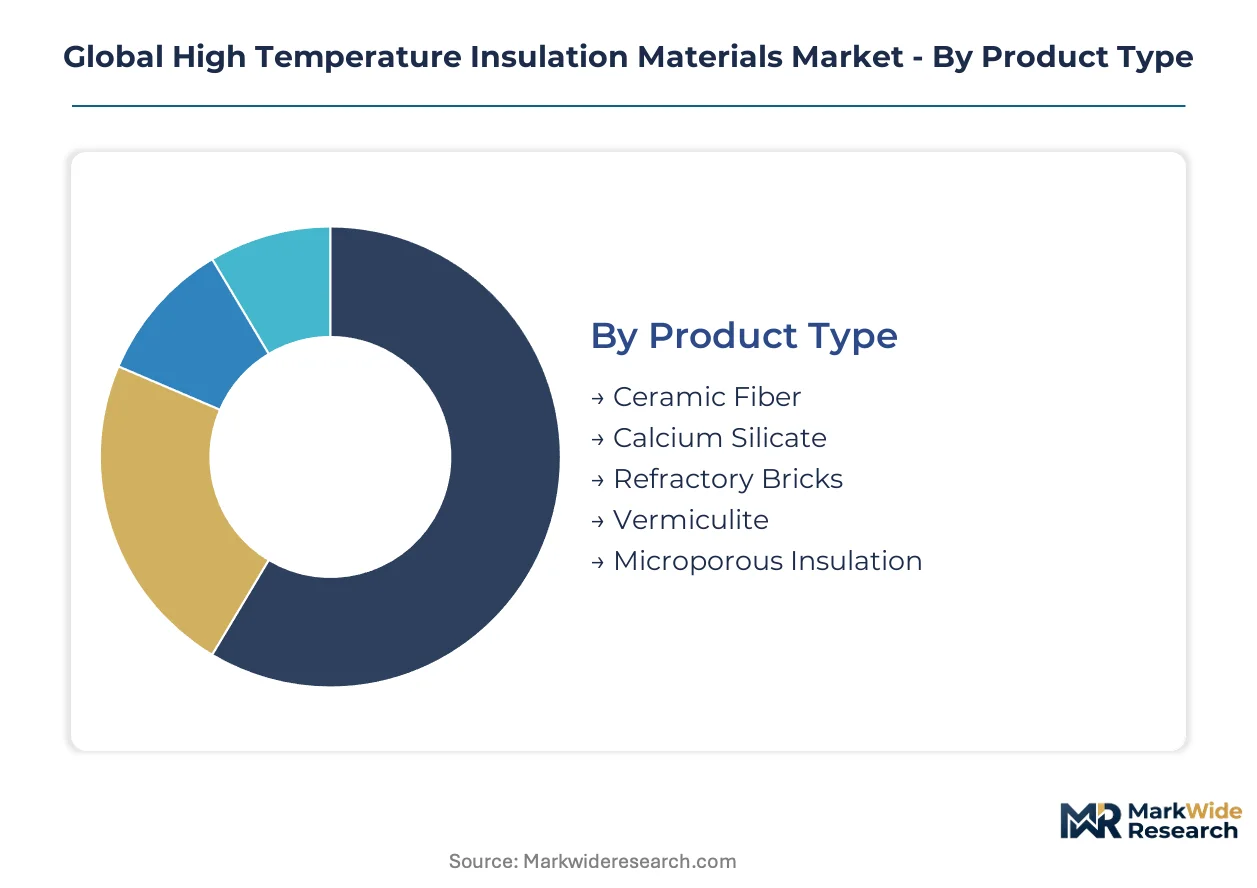
Material specification choices in high temperature insulation directly determine aftermarket service intensity, with ceramic fiber systems generating recurring relining contracts while refractory brick installations anchor long-term technical partnerships. Segmentation reveals how product-service bundling concentrates buyer relationships and reshapes competitive positioning across industrial verticals.
Product Type:
After-sales service intensity varies dramatically by material density and thermal cycling tolerance, with low-mass fiber systems demanding frequent inspection protocols versus monolithic brick structures requiring specialized installation crews.
- Ceramic Fiber:Alumina-silicate wool matrices offer flexibility and minimal thermal mass, enabling rapid furnace heat-up cycles. Foundries in Germany and petrochemical maintenance crews in Texas concentrate procurement here, driven by OSHA silica exposure rules forcing biosoluble formulation upgrades.
- Microporous Insulation:Silica-based nanoporous structures deliver peak thermal performance in constrained spaces. Demand clusters in Chinese steel mill retrofits across Hebei province, where GB energy efficiency mandates justify premium material costs for blast furnace upgrades.
- Refractory Bricks:Dense alumina or magnesia-carbon compositions withstand mechanical abrasion in glass furnace regenerators.
- Calcium Silicate:Hydrated calcium silicate boards serve moderate-temperature piping and equipment insulation.
- Vermiculite:Expanded mica-based material provides cost-effective backup insulation in kilns and ovens.
Ceramic Fiber holds the largest share; momentum sits with Microporous Insulation.
Technology:
Process integration requirements separate technologies by capital intensity and retrofit complexity, with vacuum-formed systems commanding premium positioning against spray-applied alternatives.
- Aerogel:Silica-based superinsulating solids with nanoscale porosity enable radical space reduction in offshore platform piping. Norwegian North Sea operators and Singapore refinery expansion projects specify these systems where footprint constraints override material costs.
- Vacuum Insulation:Evacuated panel systems eliminate gas conduction for peak thermal resistance per unit thickness. Cold storage integration in Dutch chemical clusters and cryogenic LNG terminal projects in Qatar drive specification growth.
- Fiberglass:Continuous filament glass wool serves moderate-temperature industrial applications.
- Foam Glass:Cellular glass structures provide moisture-resistant insulation in chemical processing.
- Intumescent Coatings:Expandable fire-resistant layers protect structural steel in hydrocarbon fire scenarios.
Aerogel claims the steepest expansion trajectory; Vacuum Insulation dominates installed value in premium applications.
Application:
Temperature severity and thermal shock frequency segment applications by material durability requirements, with metal processing tolerating fiber flexibility while glass manufacturing demands dimensional stability.
- Metal Processing:Blast furnaces, electric arc furnaces, and heat treatment equipment require insulation systems surviving thermal cycling above 1,500 degrees Celsius. German Ruhr region steelmakers and Indian Maharashtra specialty steel projects under PLI incentives anchor demand for integrated ceramic fiber and refractory solutions.
- Industrial Furnaces:General heat treatment and thermal processing equipment spans diverse temperature ranges and atmospheres. US Midwest automotive component suppliers and Chinese Jiangsu province machinery manufacturers drive specification diversity here.
- Petrochemical Plants:Cracking furnaces and process heaters demand chemical resistance alongside thermal performance.
- Power Generation:Boiler and turbine insulation systems prioritize energy efficiency in utility-scale operations.
- Kilns:Ceramic and cement manufacturing equipment requires abrasion-resistant lining systems.
Metal Processing captures the greatest volume; Industrial Furnaces are gaining share fastest.
End User:
Procurement sophistication divides end users by technical specification authority, with integrated energy producers driving standardization while fragmented foundries rely on distributor channels.
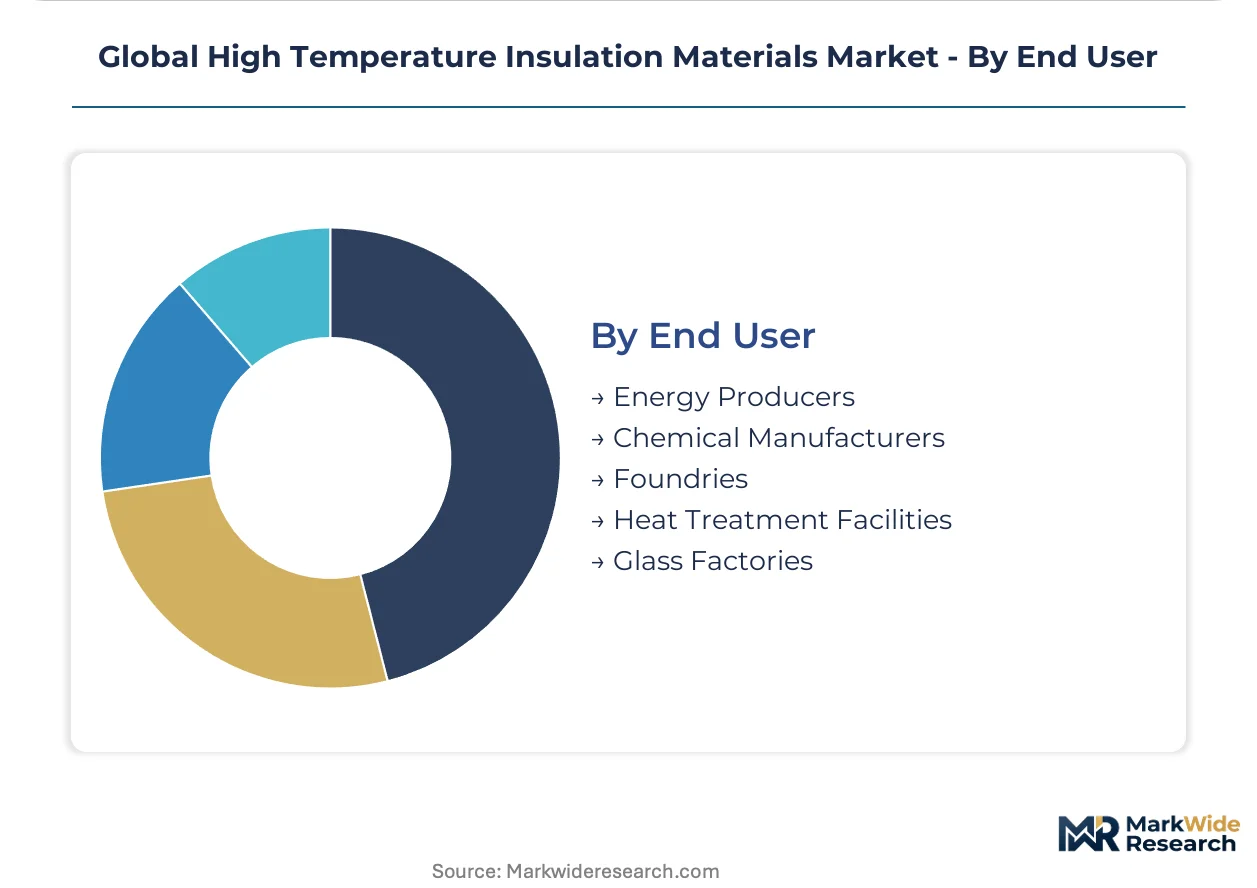
- Foundries:Ferrous and non-ferrous casting operations require crucible, ladle, and pouring line insulation with rapid replacement cycles. Italian Lombardy aluminum die-casters and Ohio investment casting facilities concentrate demand for ceramic fiber module systems with embedded thermocouple monitoring.
- Chemical Manufacturers:Process vessel and reactor insulation must withstand corrosive atmospheres and thermal shock. German BASF Ludwigshafen complex and US Gulf Coast ethylene producers specify multi-layer systems combining microporous core with chemical-resistant facing.
- Energy Producers:Utility and independent power operators prioritize boiler efficiency and emissions compliance.
- Heat Treatment Facilities:Commercial thermal processing services demand flexible furnace configurations.
- Glass Factories:Melting furnace regenerators and forehearths require dimensionally stable refractory systems.
Foundries represent the most fragmented customer base; Chemical Manufacturers concentrate the highest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Buyers in China and India negotiate aggressively on material costs, while German and US operators prioritize thermal performance and compliance certification over unit pricing.
United States
Petrochemical maintenance cycles and steel mill retrofits drive specification volume. OSHA respirable crystalline silica exposure limits below 50 micrograms per cubic meter are accelerating biosoluble fiber substitution. Gulf Coast ethylene producers in Texas and Louisiana anchor demand for integrated ceramic fiber systems with embedded thermal monitoring.
Germany
Ruhr region steelmakers and foundries concentrate procurement of advanced ceramic fiber modules. EU Green Deal industrial decarbonization targets mandate 55% emissions reductions by 2030, forcing blast furnace upgrades. BASF Ludwigshafen complex and surrounding chemical clusters specify multi-layer microporous insulation for process vessel applications.
China
Hebei and Jiangsu province steel mills dominate volume demand under GB standards for industrial energy efficiency. MEE air quality enforcement compresses replacement cycles for legacy refractory brick. Yangtze River Delta machinery manufacturers and Sichuan-Chongqing industrial bases drive specification diversity for heat treatment equipment.
India
PLI scheme incentives for specialty steel production create captive demand in Maharashtra and Gujarat electric arc furnace projects. BIS certification requirements and energy audit mandates reshape material specifications. Lombardy-equivalent foundry density in Pune-Nashik corridor concentrates ceramic fiber module procurement.
Global High Temperature Insulation Materials Market Key Industry Players
Capability concentration sits with full-service technical providers; scale advantage sits with diversified materials conglomerates. The market structures around three tiers: integrated solution architects bundling installation and monitoring services, captive refractory producers with in-house mining and brick fabrication, and specialized ceramic fiber fabricators serving maintenance-intensive verticals. Dominant competitive moves include backward integration into raw material mining and forward integration into predictive thermal audit platforms.
Among UK-origin advanced materials groups, Morgan Advanced Materials and Unifrax occupy positions emphasizing technical service networks and rapid-turnaround maintenance specialization respectively. RHI Magnesita GmbH represents the Austrian-German refractory archetype with captive supply integration. These three exemplify how geographic origin and corporate structure correlate with strategic positioning across the ceramic fiber-to-brick spectrum.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| 3M |
| Luyang Energy-saving Materials Co., Ltd. |
| RHI Magnesita GmbH |
| Etex Group |
| Unifrax |
| Promat |
| Alkegen |
| Saint-Gobain |
| Others |
Cost & Logistics Intelligence
Hebei province's refractory brick manufacturing clusters anchor global alumina-silicate supply, with blast furnace retrofit demand from Jiangsu steel mills transmitting pricing power upstream to raw material processors. Bauxite cost pass-through mechanisms intensify when Guinea-Australia freight corridors experience volatility, compressing margins for ceramic fiber fabricators serving European foundries under EU Green Deal compliance deadlines.
Pricing Analysis
Aftermarket service revenue tiers covering thermal audit consulting and predictive relining schedules now drive lifetime value capture for insulation suppliers. Three-tier pricing structure across premium microporous systems, standard ceramic fiber modules, and economy-grade refractory brick separates specification-grade buyers from cost-optimized procurement. Pricing pressure stems from India's PLI scheme incentivizing aggressive volume procurement for electric arc furnace projects. Foundries in Lombardy and Pune-Nashik corridors exhibit highest price sensitivity, while German chemical clusters prioritize thermal performance certification over unit economics.
Supply Chain Analysis
Supplier-financing facilities extending 90-120 day payment terms have become standard for furnace lining contractors bidding on multi-year maintenance contracts. Raw material supply concentrates in China, Australia, and Guinea for bauxite and zirconia feedstocks. Manufacturing draws from alumina-silicate wool, calcium silicate hydrate, and microporous silica matrices as core inputs. Single-source vulnerability persists for high-purity alumina grades used in premium ceramic fiber formulations. Distribution runs through technical service networks bundling installation supervision with material supply, marginalizing pure component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High temperature insulation materials sit in early-cycle expansion as industrial decarbonization mandates force replacement of legacy refractory systems across metal processing and chemical manufacturing verticals.
For Market Incumbents: Entrench market position by deepening captive supply of refractory raw materials and embedding predictive thermal monitoring into multi-year service contracts. Biosoluble fiber substitution timelines under OSHA and REACH rules threaten traditional alumina-silicate product lines. Certification investment in ECHA-compliant alkaline earth silicate formulations anchors defense against regulatory displacement. For New Entrants and Emerging Players: Hydrogen-ready furnace engineering contracts in Dutch and German chemical clusters represent the most penetrable entry point for specialized ceramic fiber system providers. India's Maharashtra-Gujarat electric arc furnace buildout under PLI incentives offers second-mover advantage for technical service bundlers. Partner with regional installation crews holding ceramic fiber certification to bypass technician shortage constraints. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors full-service providers integrating material supply with digital thermal audit platforms. Five-to-ten year viability hinges on hydrogen furnace retrofit exposure and REACH-compliant formulation pipelines. Monitor ECHA substance evaluation timelines for biosoluble fiber classification decisions as inflection indicator for portfolio rebalancing toward compliant chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Mining | Captive alumina supply secures margin stability against Guinea-Australia freight volatility. |
| Digital Thermal Audit Platform Launch | Remote monitoring contracts with US Gulf Coast petrochemical operators displace transactional sales. |
| Biosoluble Fiber Formulation Certification | ECHA-compliant alkaline earth silicate products capture specification share in European foundries. |
| Hydrogen Furnace Engineering Partnership | German-Dutch chemical cluster retrofits open specification windows for integrated system providers. |
| Regional Installation Crew Acquisition | Certified furnace lining technicians in Hebei and Jiangsu provinces accelerate project execution velocity. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at German Ruhr region steelmakers, procurement leads at US Gulf Coast ethylene producers, maintenance directors at Chinese Hebei province mills, and technical R&D directors at ceramic fiber manufacturers. Secondary validation drew from EPA emissions filings, ECHA REACH registration databases, China's MEE air quality enforcement records, and SEC 10-K disclosures from listed materials conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across material grades and application verticals.
Calibration against historical replacement cycle data and regulatory compliance deadline schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material density tier, temperature performance specification, end-use industry vertical, and regional regulatory cluster. CAGRs derived from installed base turnover rates and mandated upgrade timelines. Forecast inputs incorporated EU Green Deal decarbonization targets and OSHA silica exposure rule enforcement intensity.
Practitioners should monitor ECHA substance evaluation outcomes and MEE air quality enforcement patterns for early signals of substitution acceleration or compliance delay. Forecasts reflect assumptions on regulatory timeline adherence and raw material supply continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Impact Sound Insulation Acoustic Mat Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Global Insulation Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market