
 Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market | 2026-2036
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market Outlook
Epoxy-polyurethane hybrid chemistry is repositioning product economics away from traditional silicone-dominated specifications in high-temperature insulation zones. Akzo Nobel N.V. leverages its marine coatings heritage to anchor specification authority in offshore platform applications. Hempel A/S specializes in extreme-service formulations that sustain performance across North Sea and Gulf of Mexico operating environments.
Corrosion Under Insulation and Spray-On Insulation Coatings comprise protective film systems applied beneath or within thermal insulation layers to prevent electrochemical degradation of carbon steel substrates operating between minus 40 and 650 degrees Celsius; these coatings typically incorporate glass-flake or aluminum-pigmented barriers to block chloride ingress and moisture wicking. The epoxy product category dominates specification sheets in oil and gas infrastructure due to its adhesion strength and chemical resistance, while polyurethane variants capture margin pools in cryogenic LNG applications where flexibility under thermal cycling proves critical. Marine application volumes trail industrial segments but exhibit faster specification growth as floating production storage and offloading vessels multiply.
The EPA enforces VOC content limits under 40 CFR Part 59 Subpart D that constrain solvent-borne formulation options and redirect R&D toward water-reducible and high-solids platforms. OSHA's Process Safety Management standard indirectly amplifies CUI inspection frequency in covered chemical facilities, sustaining recurring maintenance demand for coating reapplication. NACE International SP0198 provides the technical baseline for coating selection beneath thermal insulation, and compliance with this standard governs contractor qualification across downstream energy projects. Stakeholders must monitor how carbon-border adjustment mechanisms and facility decarbonization timelines reshape capital allocation between new construction coatings and retrofit maintenance programs.
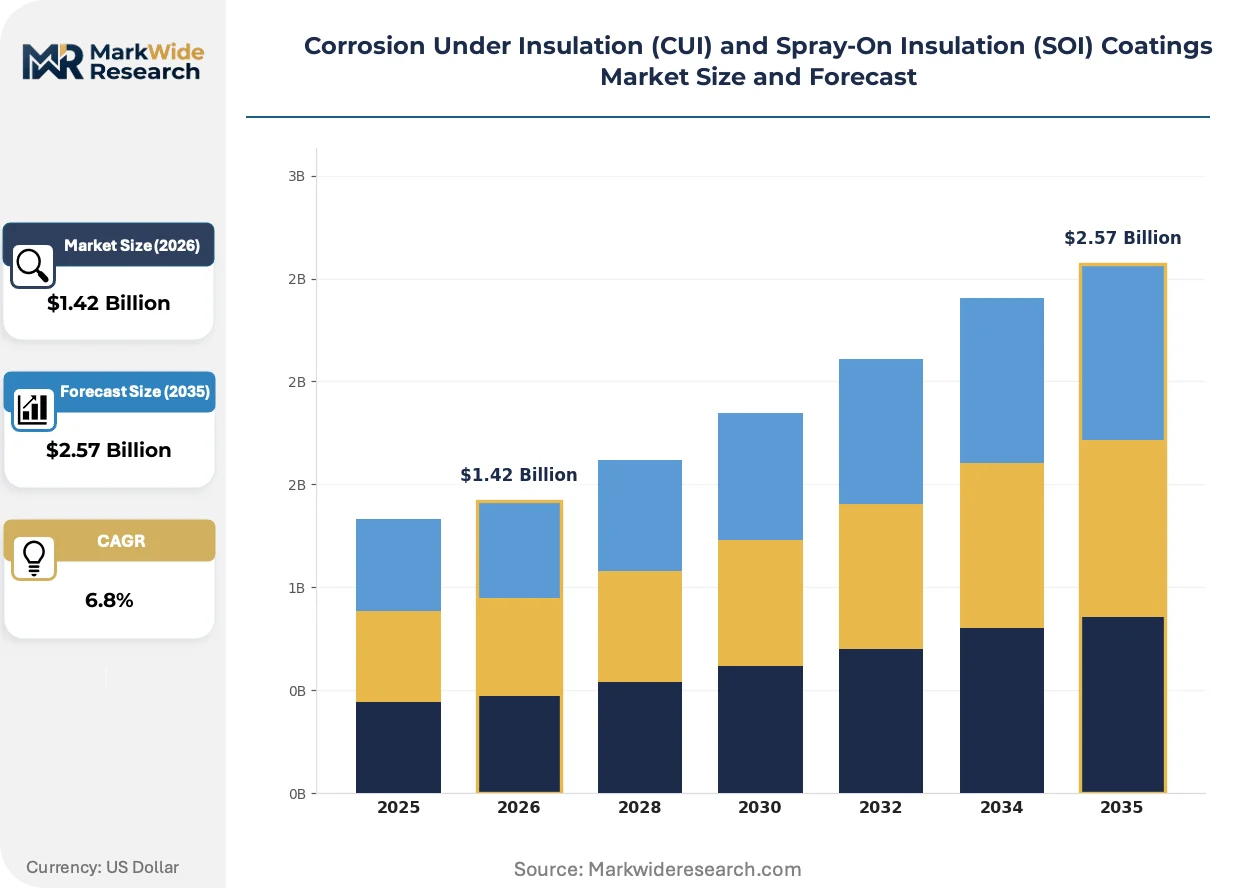
Market Dynamics
Epoxy-polyurethane hybrid chemistry is forcing rapid specification migration away from silicone-dominated systems in high-temperature insulation zones across Gulf Coast petrochemical clusters. Reformulation pressure from VOC limits compresses product development cycles while expanding addressable application ranges.
Growth Catalysts
- EPA Subpart D Compliance:Tightened volatile organic compound limits under 40 CFR Part 59 Subpart D compel coating manufacturers toward water-reducible and high-solids platforms, expanding specification eligibility in federally regulated facilities.
- Floating Production Vessel Expansion:Offshore oil platforms and FPSO multiplication in the Gulf of Mexico generates specification velocity for marine-grade CUI-resistant systems with salt-spray durability.
- NACE SP0198 Standardization:Widespread contractor qualification requirements tied to NACE International SP0198 cement coating selection protocols as mandatory technical baselines across downstream energy projects.
Market Restraints
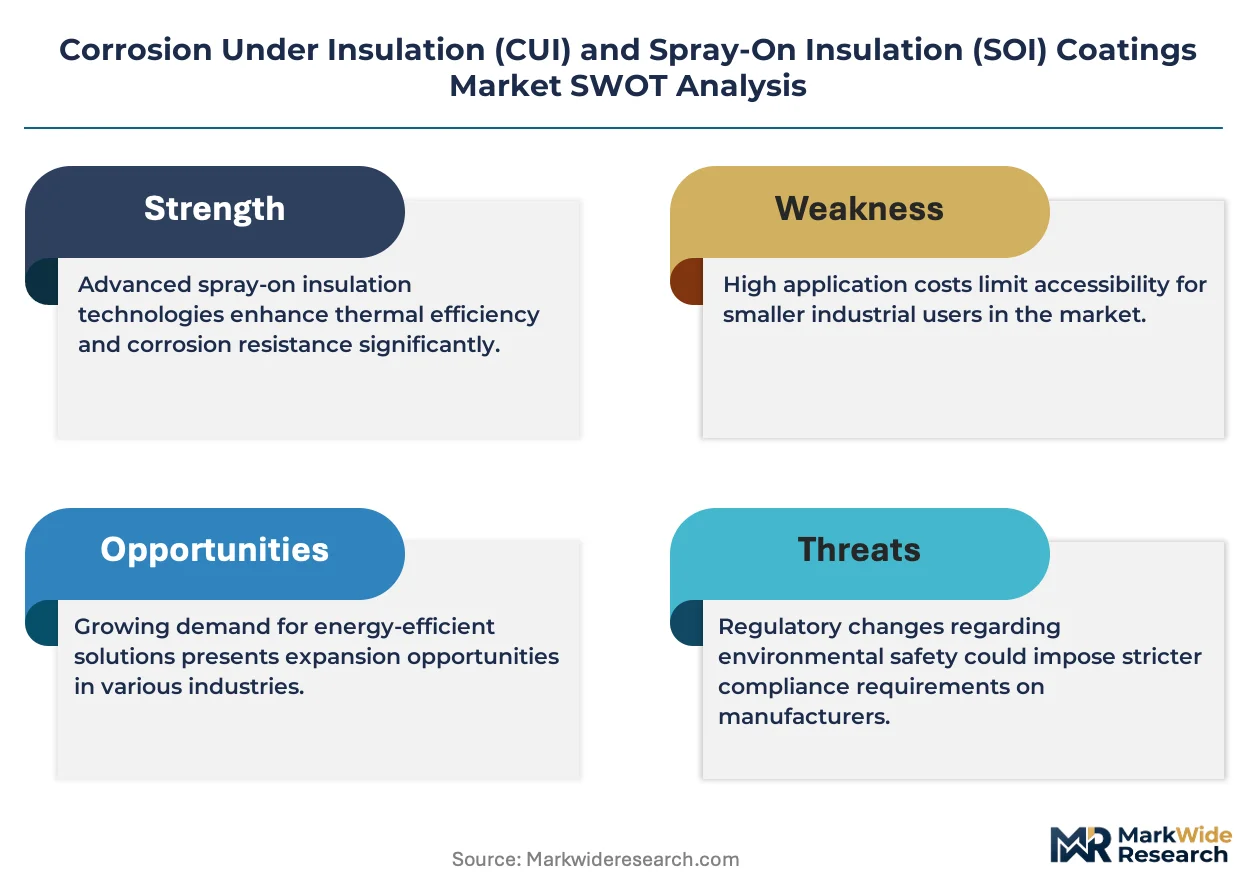
- Petrochemical Feedstock Volatility:Epoxy resin and isocyanate input cost swings compress formulation margins and destabilize pricing predictability for polyurethane variants.
- Specialized Applicator Concentration:Certified CUI coating contractors cluster in Texas and Louisiana, creating bottleneck risk for project scheduling in secondary markets.
- Cryogenic Substitution Limits:Polyurethane flexibility advantages in LNG applications face technical ceilings below minus 196 degrees Celsius where alternative metallurgical solutions displace organic coatings.
Strategic Opportunities
- Carbon Capture Infrastructure:Pipeline and vessel networks for CO2 transport require novel thermal insulation coatings rated for supercritical fluid exposure, opening specification white space.
- European F-Gas Regulation Tailwind:ECHA restrictions on high-global-warming-potential blowing agents in insulation materials create demand for compatible coating systems in EU industrial retrofits.
- Digital Inspection Integration:Convergence of drone-based thermography with predictive maintenance platforms enables coating condition monitoring as a subscription service revenue stream.
Industry Challenges
- Certified Coating Inspector Scarcity:NACE-recognized CUI specialists remain concentrated in legacy oil hubs, constraining quality assurance throughput for distributed renewable chemical projects.
- Legacy Insulation Removal Protocols:Asbestos-containing thermal wrap abatement in aging Gulf Coast refineries adds cost and timeline risk to coating retrofit programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Silicone, Acrylic Application: Industrial, Commercial, Residential, Marine End User: Oil & Gas, Chemicals, Power Generation, Utilities Installation Method: Spray, Brush, Roller, Injection |
| Companies Covered | The Sherwin-Williams Company, Kansai Paint Co. Ltd., Akzo Nobel N.V., RPM International Inc., Nippon Paint Co. Ltd., PPG Industries Inc., Hempel A/S, Carboline Company, Jotun A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market Strategic Shifts
Coating chemistry convergence with smart insulation systems is compressing the traditional separation between passive protection and active monitoring layers. Specification authority is migrating toward integrated system providers rather than discrete material suppliers.
Nano-engineered glass flake dispersions are integrating into epoxy matrices to create tortuous moisture pathways that extend coating service life beneath thermal insulation. Offshore platform operators in the Gulf of Mexico specify these systems for splash zone and sub-deck applications where chloride ingress resistance determines asset integrity. The technology is integrating condition-based maintenance protocols by enabling longer inspection intervals without compromising substrate protection.
REACH restrictions on chromium(VI) compounds in corrosion inhibitors force reformulation of traditional wash primers and pretreatment chemistries across European industrial maintenance markets. Coating manufacturers redirect R&D toward titanate and silane-based adhesion promoters that satisfy ECHA authorization requirements. Marine and chemical processing segments in Germany and the Netherlands absorb compliance costs through premium pricing for certified low-hazard systems.
Asset owner engineering teams now bundle coating specification with insulation contractor selection rather than treating these as sequential procurement decisions. Integrated package contracting displaces discrete material purchasing in Texas and Louisiana petrochemical expansions. This consolidation concentrates specification influence among turnkey insulation system providers with in-house coating formulation partnerships.
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market Segmentation
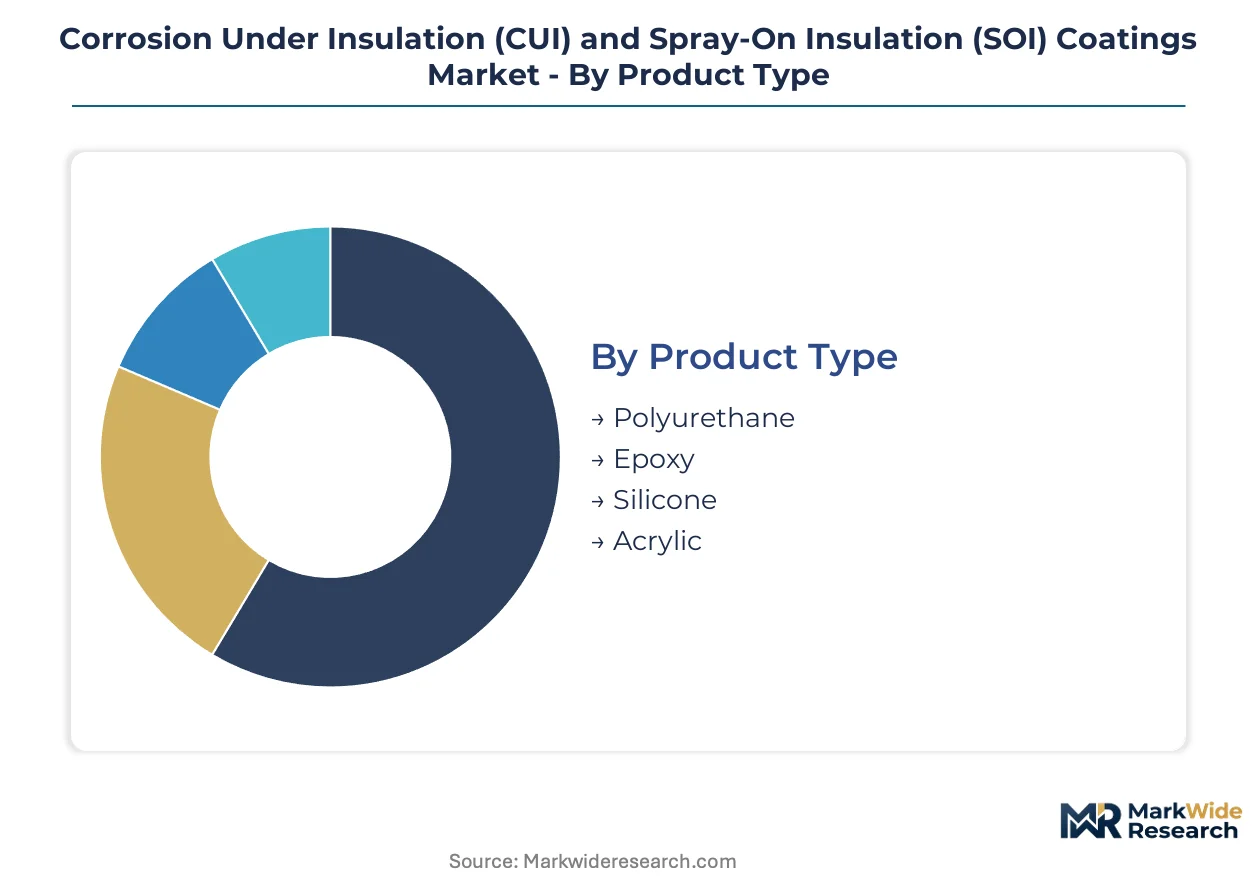
Segmentation in the CUI and SOI coatings market reveals how specification authority migrates between material science capabilities and application environment demands. Each dimension exposes distinct margin structures and technical barriers to entry.
Product Type:
Customization intensity spans from commodity acrylics to engineered polyurethane hybrids, with formulation complexity determining pricing power and specification loyalty.
- Epoxy:Glass-flake reinforced thermosetting systems dominate carbon steel protection in high-temperature insulation zones. Demand concentrates in Texas and Louisiana petrochemical clusters where NACE SP0198 compliance governs contractor qualification and reapplication cycles sustain recurring revenue.
- Polyurethane:Flexible aliphatic and aromatic variants capture cryogenic LNG infrastructure specifications requiring thermal cycling durability. Gulf of Mexico floating production vessels specify these systems for sub-deck applications where substrate movement and chloride ingress create simultaneous stress.
- Silicone:High-temperature stable formulations service exhaust stack and furnace applications up to 650 degrees Celsius.
- Acrylic:Water-reducible platforms address low-temperature commercial HVAC insulation with simplified application protocols.
Leading the category by volume: Epoxy. Expanding most quickly: Polyurethane variants in cryogenic service.
Application:
Specification velocity correlates with asset criticality and regulatory inspection frequency across operating environments.
- Industrial:Downstream oil refineries and chemical processing plants drive specification intensity through OSHA Process Safety Management mandates. Gulf Coast facilities in Texas and Louisiana generate concentrated demand for thermal insulation coating systems rated for continuous hydrocarbon exposure.
- Marine:Floating production storage and offloading vessels multiply in the Gulf of Mexico, creating specification velocity for salt-spray durable CUI-resistant systems. Offshore platform operators bundle coating procurement with insulation contractor selection to compress project timelines.
- Commercial:Building envelope applications favor water-reducible acrylic and hybrid systems with lower VOC profiles.
- Residential:Spray-foam insulation compatibility drives specification for low-odor, fast-cure coating platforms.
Industrial applications anchor volume share. Marine specifications gain share fastest on FPSO deployment schedules.
End User:
Capital allocation cycles and maintenance protocols create divergent procurement patterns across infrastructure categories.
- Oil & Gas:Upstream offshore platforms and downstream refineries sustain the largest addressable market through continuous corrosion management programs. EPA 40 CFR Part 59 Subpart D compliance redirects specification toward high-solids and water-reducible platforms in federally regulated facilities.
- Chemicals:Process Safety Management covered facilities require documented CUI inspection protocols that generate predictable reapplication demand. Texas and Louisiana chemical clusters concentrate specification authority among turnkey insulation system providers.
- Power Generation:Combined cycle gas turbine insulation drives high-temperature coating specifications.
- Utilities:Pipeline network integrity programs sustain maintenance coating volumes across transmission infrastructure.
Oil & Gas commands the largest volume position. Chemicals demonstrates the steepest expansion trajectory on capacity additions.
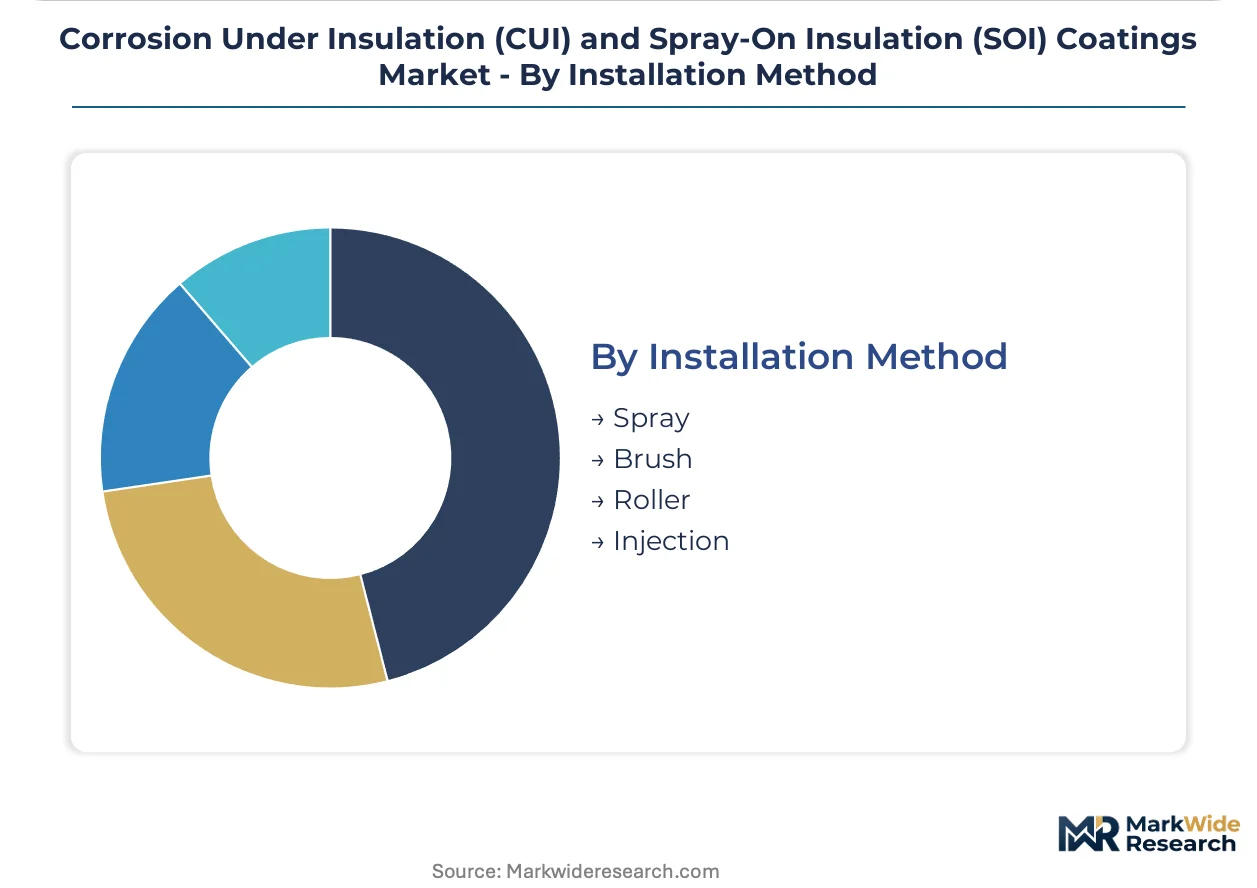
Installation Method:
Application technology selection determines labor productivity and coating performance consistency in field conditions.
- Spray:Airless and plural-component equipment dominates large-area industrial applications where film thickness uniformity governs service life. Offshore platform projects in the Gulf of Mexico specify spray application for sub-deck and splash zone coverage where access constraints favor mechanized deployment.
- Brush:Detail work and touch-up protocols sustain demand in maintenance programs with localized coating failure.
- Roller:Commercial and residential SOI applications favor roller application for simplified contractor qualification.
- Injection:Cavity fill and void penetration specifications in complex geometries drive specialized equipment requirements.
Spray application leads by installed volume. Injection methods climb fastest on infrastructure remediation projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast Opportunity Zones and petrochemical special economic districts concentrate CUI coating demand through accelerated depreciation incentives for corrosion management infrastructure. Texas and Louisiana anchor North American specification volume. Rotterdam Antwerp and Singapore Jurong Island chemical clusters generate comparable coating procurement intensity.
United States
Offshore platform operators in the Gulf of Mexico specify marine-grade CUI-resistant systems for floating production storage and offloading vessels. EPA 40 CFR Part 59 Subpart D compliance redirects formulation toward water-reducible and high-solids platforms in federally regulated facilities. Houston and Lake Charles petrochemical clusters sustain concentrated demand for thermal insulation coating reapplication cycles.
Germany
REACH restrictions on chromium(VI) compounds in corrosion inhibitors force reformulation of traditional wash primers across industrial maintenance markets. ECHA authorization requirements redirect R&D toward titanate and silane-based adhesion promoters. Düsseldorf and Ludwigshafen chemical processing segments absorb compliance costs through premium pricing for certified low-hazard systems.
Netherlands
Rotterdam port infrastructure and Antwerp chemical cluster expansions generate specification velocity for salt-spray durable coating systems. ECHA restrictions on high-global-warming-potential blowing agents in insulation materials create demand for compatible coating systems in EU industrial retrofits. Amsterdam engineering consultancies bundle coating specification with insulation contractor selection.
Singapore
Jurong Island petrochemical complex expansions sustain Southeast Asian demand for high-temperature insulation zone protection. The country's national environmental regulator enforces VOC content limits that constrain solvent-borne formulation options. Tuas marine terminal developments specify CUI-resistant systems for vessel hull and sub-deck applications.
Saudi Arabia
SABIC affiliate facilities and downstream refinery expansions in Jubail Industrial City drive specification intensity for thermal insulation coatings. The national standards body mandates compliance with NACE International SP0198 for coating selection beneath thermal insulation. Ras Tanura and Yanbu petrochemical clusters concentrate contractor qualification among turnkey insulation system providers.
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with formulation-integrated players capturing premium specification authority in offshore applications. The vendor base organizes around three strategic archetypes: marine heritage specialists with salt-spray durability credentials, industrial maintenance incumbents with NACE-certified applicator networks, and regional coating formulators serving localized petrochemical clusters. Competitive moves concentrate on strategic partnerships with insulation contractors and portfolio diversification into cryogenic service formulations.
Within the marine heritage tier, Hempel A/S and Jotun A/S exemplify specification authority anchored in North Sea and Gulf of Mexico operating environments. Akzo Nobel N.V. occupies a position derived from marine coatings heritage that translates into offshore platform specification influence. Among diversified industrial incumbents, PPG Industries Inc. and RPM International Inc. represent scale-driven positions with broad formulation portfolios spanning epoxy and polyurethane chemistries.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| Kansai Paint Co. Ltd. |
| Akzo Nobel N.V. |
| RPM International Inc. |
| Nippon Paint Co. Ltd. |
| PPG Industries Inc. |
| Hempel A/S |
| Carboline Company |
| Jotun A/S |
| Others |
Value Chain & Pricing Dynamics
Epoxy resin and isocyanate feedstock costs cascade through formulation margins to downstream pricing tiers, with Gulf Coast petrochemical cluster proximity compressing logistics premiums for Texas and Louisiana buyers while distant markets absorb elevated landed costs.
Pricing Analysis
Short lead-time premiums for certified NACE SP0198-compliant coating systems command pricing advantages over spot inventory in maintenance turnaround windows. Three-tier pricing structure across premium, standard, and economy levels separates glass-flake reinforced epoxies from commodity acrylics based on certification grade and thermal service rating. Pricing pressure stems from petrochemical feedstock volatility compressing formulation margins. Downstream oil refineries exhibit lowest price sensitivity due to asset-criticality mandates, while commercial HVAC contractors demonstrate highest sensitivity to unit cost fluctuations.
Supply Chain Analysis
Certified CUI coating applicator scarcity in Texas and Louisiana concentrates workforce availability bottlenecks, constraining project throughput despite raw material abundance. Manufacturing gravity centers on the United States, Germany, and Singapore, with formulation production drawing from epoxy resin feedstocks, isocyanate precursors, and glass-flake barrier additives. Single-source vulnerability runs through specialized titanate and silane-based adhesion promoters subject to REACH authorization timelines. Distribution runs through turnkey insulation system providers bundling coating procurement with contractor deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified applicator scarcity props pricing power for qualified coating systems, with NACE-recognized inspector concentration in legacy oil hubs creating structural supply constraints that sustain margin premiums across the analysis window.
For Market Incumbents: To counter cryogenic polyurethane substitution limits below minus 196 degrees Celsius, anchor specification authority through backward integration into glass-flake dispersion manufacturing and deepen NACE-certified applicator network density in secondary markets beyond Texas and Louisiana. Prioritize R&D investment in nano-engineered barrier technologies that extend inspection intervals without compromising substrate protection. For New Entrants and Emerging Players: Capture specification white space in carbon capture infrastructure thermal insulation coatings rated for supercritical CO2 fluid exposure, where incumbent formulation portfolios remain underdeveloped. Target European industrial retrofits driven by ECHA F-Gas Regulation restrictions on high-global-warming-potential blowing agents. Deploy digital inspection integration partnerships as differentiated go-to-market positioning against traditional material suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor turnkey insulation system providers with in-house coating formulation partnerships in the United States Gulf Coast, where petrochemical capacity additions sustain recurring reapplication demand. Long-term viability hinges on integrated system provider consolidation displacing discrete material purchasing. Monitor EPA 40 CFR Part 59 Subpart D enforcement intensity as inflection indicator for water-reducible platform adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass-Flake Manufacturing | Captive supply of nano-engineered barrier additives secures formulation differentiation against commodity epoxy competitors. |
| NACE-Certified Applicator Network Expansion | Qualified inspector density in secondary markets decompresses project scheduling bottlenecks and captures maintenance turnaround revenue. |
| Cryogenic Service Formulation Development | Polyurethane variants rated for LNG thermal cycling capture margin pools in floating production vessel specifications. |
| Digital Inspection Platform Partnership | Drone-based thermography convergence enables coating condition monitoring as subscription service revenue stream. |
| Turnkey Insulation System Provider Acquisition | Specification authority migration toward integrated system providers concentrates procurement influence among bundled solution vendors. |
Study Parameters
Trade association filings, customs and import-export records, and SEC financial disclosures formed the secondary backbone, cross-referenced with primary interviews involving coating formulation chemists, petrochemical facility maintenance directors, NACE-certified inspection contractors, and thermal insulation system procurement leads at downstream energy operators. Bottom-up and top-down triangulation validated volume estimates across product type, application environment, and end-user industry segments.
Bottom-up modeling anchored demand forecasts in asset-level coating reapplication cycles and new construction specifications, while top-down analysis cross-checked aggregate market sizing against petrochemical capacity expansion pipelines and offshore platform deployment schedules. Segmentation dimensions included chemistry type, thermal service rating, installation method, and regional regulatory cluster. CAGRs derived from trend extrapolation of specification migration patterns and compliance-driven reformulation cycles, with inputs from EPA enforcement trajectory and ECHA authorization timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon-border adjustment mechanism implementation and facility decarbonization capital allocation shifts. Forecasts reflect documented assumptions regarding NACE SP0198 standardization velocity and VOC limit enforcement intensity. Material deviation in EPA Subpart D compliance timelines or REACH chromium(VI) compound restriction scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
North America Phase Change Materials Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Global Glass Insulation Market
Insulation Materials
Passive Fire Protection Materials Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
Mineral Wool Insulation Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
High Temperature Insulation Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Phase Change Thermal Interface Materials Market