
 Extruded Polystyrene (XPS) Insulation Material Market | 2026-2036
Extruded Polystyrene (XPS) Insulation Material Market Size, Share, and Industry Trends Forecast 2026-2036
Extruded Polystyrene (XPS) Insulation Material Market Foresight
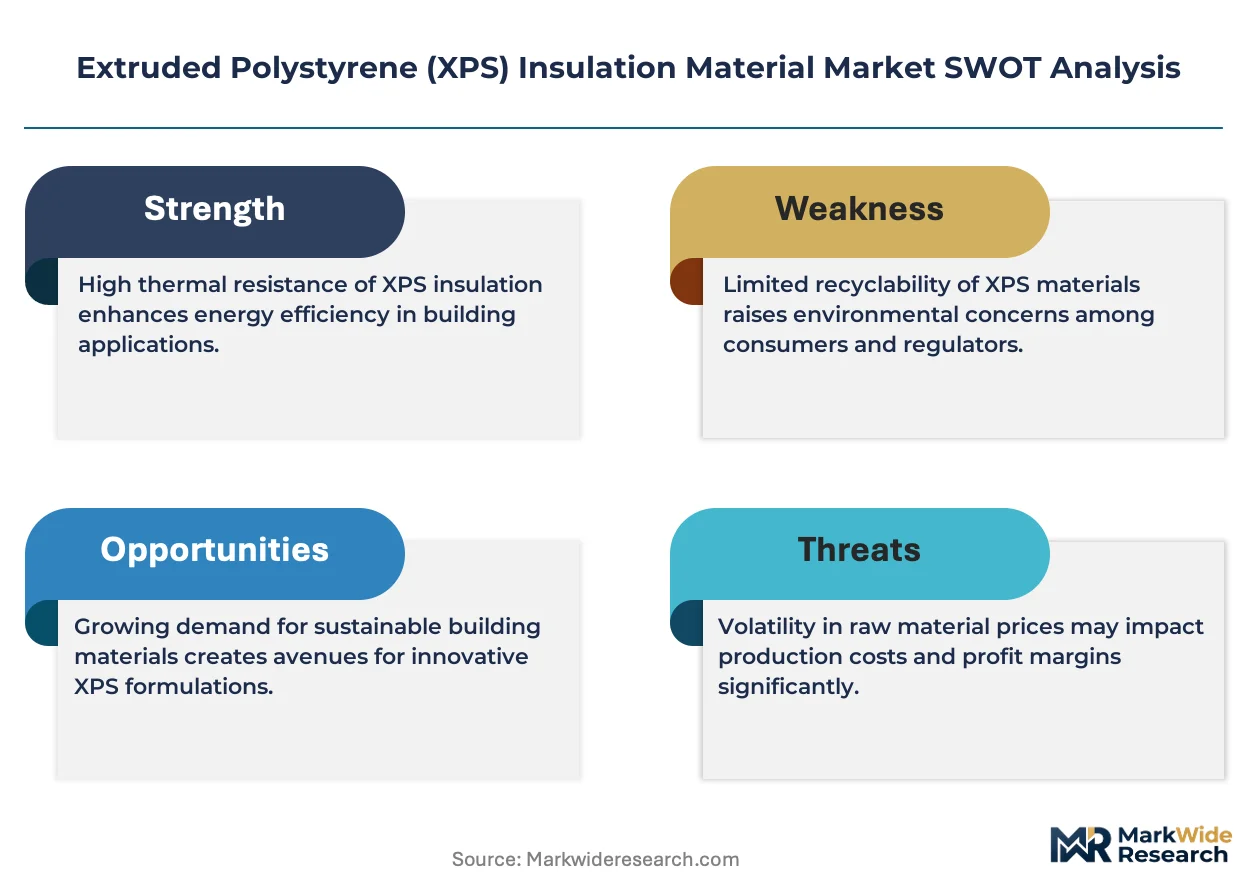
Polyisocyanurate foam is repositioning competitive dynamics in high-performance envelopes, forcing XPS producers to emphasize compressive strength and moisture resistance. BASF SE leverages integrated styrene monomer supply to protect margin structures across European plants. Owens Corning anchors North American distribution through captive roofing system channels. Kingspan Group specializes in laminated board configurations that bundle insulation with weatherproof membranes.
Extruded polystyrene insulation material is a closed-cell thermoplastic foam produced through continuous extrusion of polystyrene resin with blowing agents, yielding a rigid product with compressive strength typically ranging from 25 to 700 kPa and thermal conductivity near 0.034 W/m·K. Manufacturers engineer these properties primarily to reduce heat transfer in building envelopes, foundation systems, and cold chain infrastructure. Rigid foam and laminated boards command the dominant share of value given their specification in below-grade and inverted roof assemblies where moisture resistance commands premium positioning. Specialty panels represent the fastest-expanding category as producers integrate facers and coatings that accelerate installation speed on modular construction sites.
EPA regulations under the AIM Act restrict hydrofluorocarbon blowing agents, compelling reformulation toward lower-GWP alternatives such as hydrofluoroolefins or CO2 blends. EU REACH and F-Gas Regulation impose parallel constraints on chemical inputs, while CE marking mandates thermal performance disclosure that shapes procurement specifications across member states. Stakeholders must monitor divergence between North American and European chemical compliance pathways to avoid stranded inventory in cross-border projects.
Market Dynamics
The XPS insulation market is being restructured by the EU F-Gas Regulation's phase-down of hydrofluorocarbon blowing agents, forcing producers to reformulate production lines around lower-GWP alternatives while maintaining thermal performance benchmarks.
Growth Catalysts
- Germany's Building Energy Act (GEG):Deep retrofit mandates for existing residential stock are sustaining above-average consumption of rigid foam boards in facade and basement applications.
- Cold chain infrastructure expansion:Food processing and pharmaceutical logistics operators are specifying XPS for floor insulation in automated distribution centers requiring compressive load-bearing capacity.
- CE marking thermal disclosure:Standardized performance documentation is reducing procurement friction across EU member states and accelerating specification decisions.
Market Restraints
- Styrene monomer supply concentration:European producers face input cost volatility tied to benzene-cracker output decisions at integrated petrochemical complexes in the ARA region.
- Polyisocyanurate substitution:High-performance envelope specifications increasingly favor PIR foam where thermal conductivity below 0.024 W/m·K outweighs compressive strength requirements.
- REACH chemical registration burden:Novel blowing agent chemistries face extended authorization timelines that delay product launches by 18-36 months.
Strategic Opportunities
- Modular construction integration:Factory-built volumetric units require laminated board configurations that bundle insulation with weatherproof membranes, cutting on-site labor hours.
- Below-grade foundation systems:Inverted roof and plaza deck assemblies in dense urban cores specify XPS for moisture resistance where EPS degrades.
- CO2-blown product lines:Producers mastering supercritical carbon dioxide extrusion can access green public procurement frameworks in France and the Netherlands.
Industry Challenges
- Blowing agent transition engineering:Reformulating extrusion lines for hydrofluoroolefin or CO2 systems requires process engineers with scarce polymer foam expertise.
- Cross-border compliance divergence:The US EPA AIM Act and EU F-Gas Regulation impose incompatible chemical phase-down schedules, complicating inventory planning for multinational projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extruded Polystyrene (XPS) Insulation Material Market |
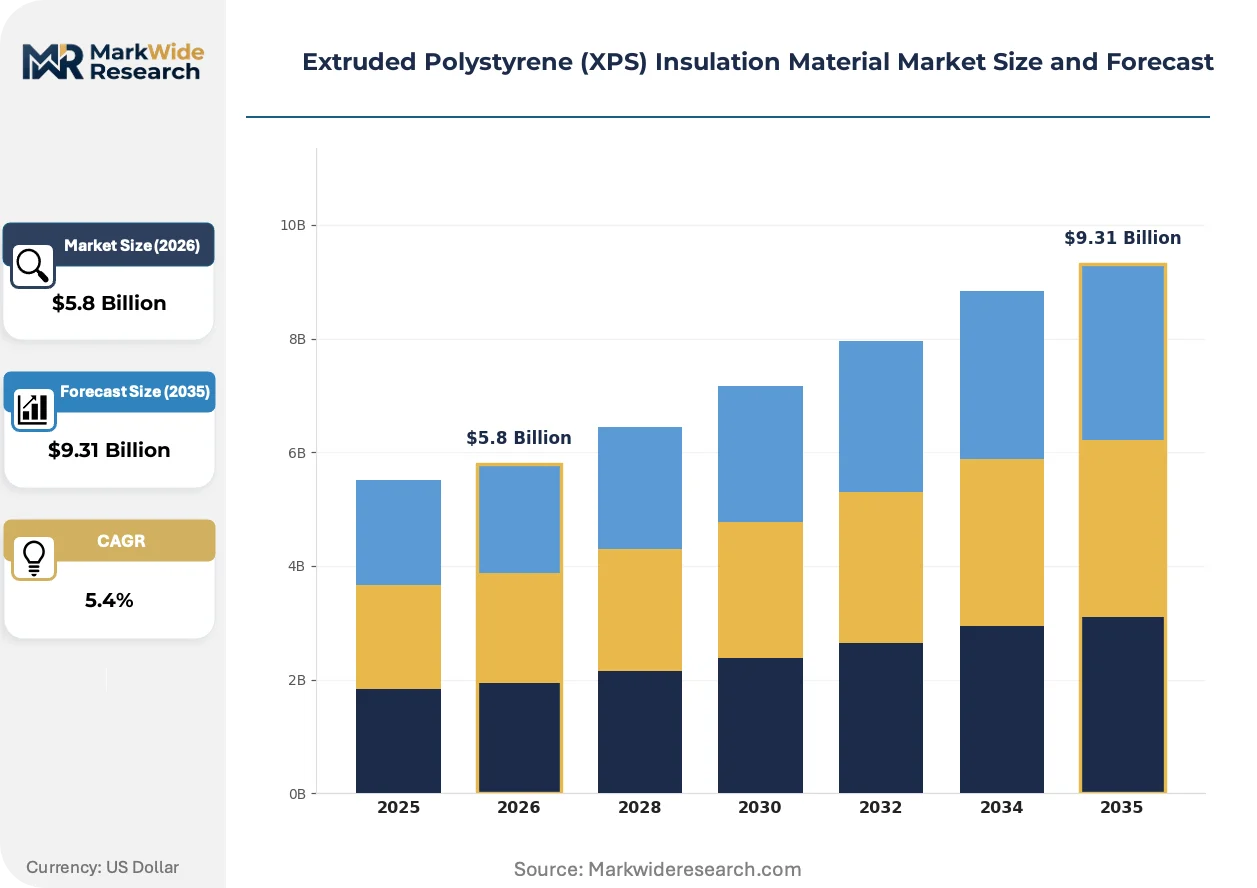
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Sheets, Rigid Foam, Laminated Boards, Specialty Panels Application: Building Insulation, Cold Storage, Roof Insulation, Foundation Protection Thickness: Thin, Medium, Thick, Extra Thick End User: Construction, HVAC, Agriculture, Industrial |
| Companies Covered | Saint-Gobain, Synthos, BASF SE, Emirates Extruded Polystyrene, Austrotherm, Kingspan Group, DuPont, Jackon Insulation GmbH, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extruded Polystyrene (XPS) Insulation Material Market Shifts & Advancements
Extrusion technology and facer integration are converging to produce installation-ready board systems that compress project timelines for envelope contractors facing skilled labor constraints.
Graphite-enhanced polystyrene resin is integrating into high-performance XPS formulations to reduce thermal conductivity without increasing board thickness. Deep retrofit contractors in Germany and Austria are specifying these products where facade cavity depths face regulatory maximums. The technology is integrating compressive strength and lambda-value improvements into a single specification layer that displaces multi-material buildups.
The EU F-Gas Regulation's 2024 step-down in HFC quota allocation is compelling producers to validate hydrofluoroolefin blowing agents through accelerated aging protocols. Manufacturing lines in Belgium and Poland are completing qualification runs for HFO-1234ze formulations that maintain dimensional stability across freeze-thaw cycles. Below-grade foundation segments are absorbing most reformulation costs given limited substitute materials for moisture-resistant rigid foam.
Specification decisions are consolidating around single-source envelope system providers that bundle insulation with membrane and fastening solutions. General contractors on German commercial projects are awarding package contracts to suppliers with in-house technical field support. This pattern concentrates procurement volume with integrated system houses and marginalizes standalone board distributors lacking installation training capabilities.
Extruded Polystyrene (XPS) Insulation Material Market Segmentation
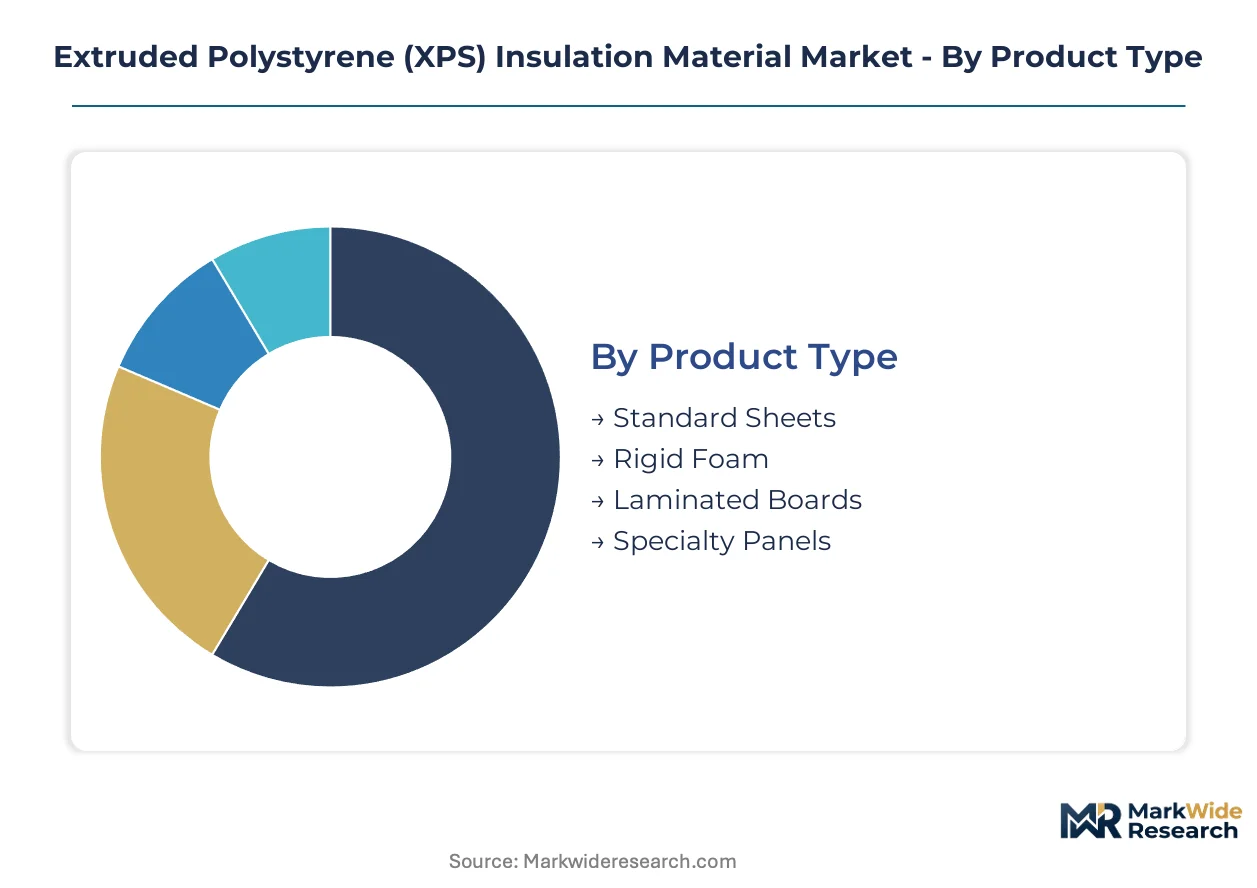
Segmentation in the XPS insulation market tracks how material specifications align with performance mandates in energy-efficient construction. Product architecture and application context determine procurement patterns across residential retrofits and commercial cold chain infrastructure.
Product Type:
Customization intensity varies from commodity sheets to engineered laminates, with specification depth escalating toward system-integrated formats.
- Rigid Foam:Continuous-extruded closed-cell boards with compressive strength from 25 to 700 kPa serve below-grade foundation systems across Germany's deep retrofit programs. Moisture resistance specifications in basement applications sustain premium positioning against expanded polystyrene alternatives.
- Laminated Boards:Factory-bonded configurations integrating weatherproof membranes accelerate envelope installation on modular construction sites. Kingspan Group and similar system houses bundle these products with technical field support to capture general contractor package awards.
- Standard Sheets:Basic extruded boards without facers or coatings serve cost-sensitive above-grade wall applications where compressive loads remain minimal.
- Specialty Panels:Custom-dimensioned products with pre-applied coatings target automated distribution center flooring requiring precise load-bearing tolerances.
Leading the category by volume: Rigid Foam. Growing fastest: Laminated Boards.
Application:
End-use concentration tracks regulatory pressure points, with building codes and food safety mandates driving specification intensity.
- Building Insulation:Façade and basement applications dominate consumption as Germany's Building Energy Act mandates thermal upgrades to existing residential stock. Rigid foam boards specified in cavity wall systems face maximum depth constraints that favor graphite-enhanced formulations.
- Roof Insulation:Inverted membrane assemblies over occupied space require moisture-resistant rigid foam where prolonged ponding conditions degrade expanded polystyrene. Urban plaza deck specifications in dense European cores sustain above-average pricing.
- Cold Storage:Automated distribution center floors specify high-compressive-strength XPS for pallet racking loads in pharmaceutical and fresh food logistics chains.
- Foundation Protection:Perimeter drainage and waterproofing systems employ tapered boards to direct groundwater away from structural elements.
Highest specification intensity: Roof Insulation. Expanding most quickly: Cold Storage.
Thickness:
Dimensional stratification reflects thermal performance targets against installation constraints in retrofit versus new construction.
- Thick:Boards from 80 to 120 mm achieve U-values required by EU Green Deal trajectory without multi-layer buildups. Deep retrofit contractors in Austria and Germany specify these dimensions where facade cavity depths face regulatory maximums.
- Medium:40 to 80 mm products balance thermal performance with handling logistics on residential construction sites.
- Thin:Sub-40 mm boards serve interior insulation upgrades where floor-to-ceiling height loss must be minimized.
- Extra Thick:Custom-extruded panels above 120 mm address passive house standards and specialized cold chain flooring.
Dominant specification tier: Thick. Steepest expansion trajectory: Extra Thick.
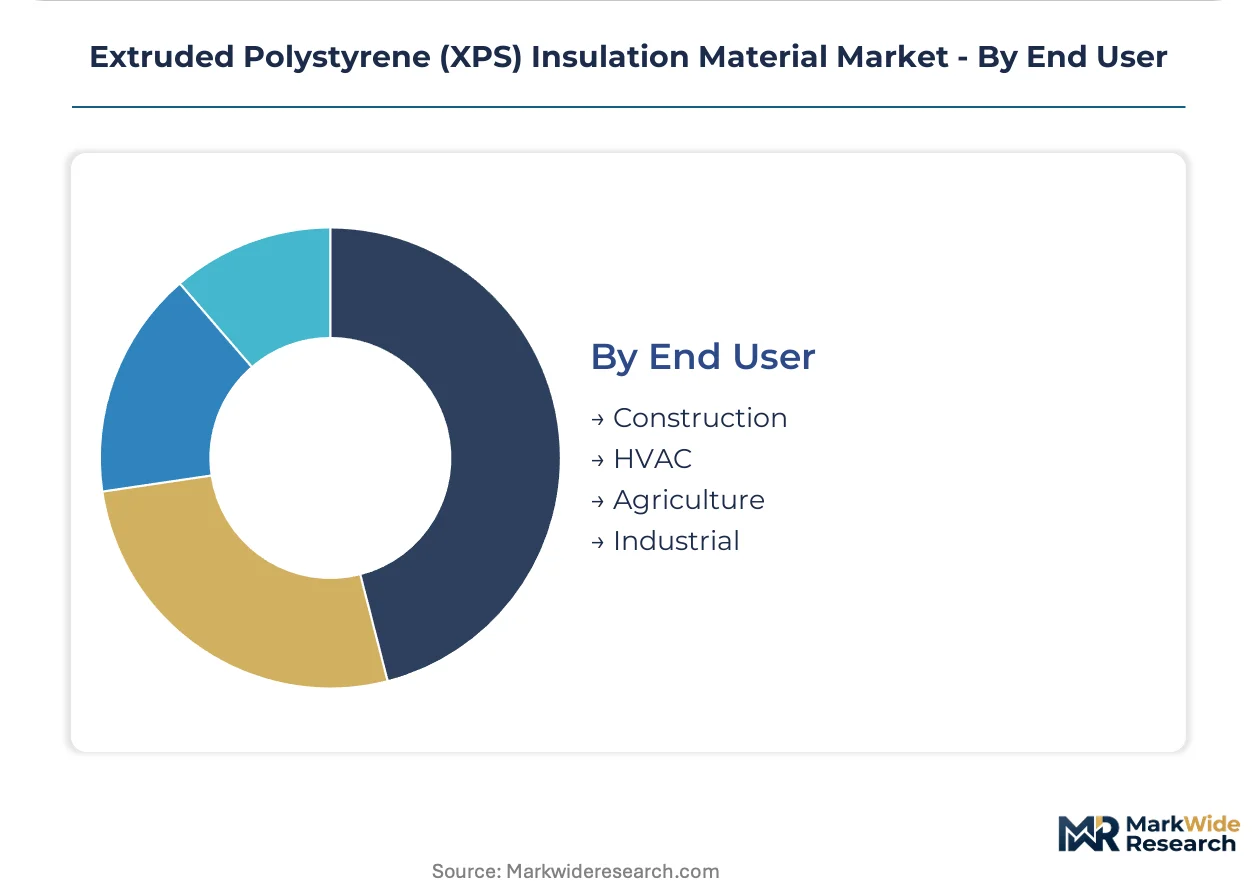
End User:
Procurement sophistication escalates from trade contractor spot buying to integrated system house specifications with embedded technical service.
- Construction:General contractors on German commercial projects award package contracts to envelope system providers with in-house installation training. This procurement pattern concentrates volume with integrated suppliers and marginalizes standalone distributors.
- HVAC:Mechanical contractors specify XPS for ductwork insulation and equipment pads where compressive strength and moisture resistance outperform fiberglass alternatives.
- Agriculture:Greenhouse operators and livestock facility builders employ rigid foam for perimeter foundation insulation in controlled-environment structures.
- Industrial:Food processing and pharmaceutical manufacturers specify XPS for floor insulation in cleanroom environments requiring washdown resistance.
Leading demand source: Construction. Gaining share fastest: Industrial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for extruded polystyrene insulation concentrates in Germany, where deep retrofit mandates and stringent building codes sustain above-average consumption of rigid foam boards across residential and commercial envelopes.
Germany
The Building Energy Act mandates thermal upgrades to existing residential stock, driving specification of thick rigid foam boards in facade and basement applications. The F-Gas Regulation accelerates reformulation toward hydrofluoroolefin blowing agents. Industrial clusters in North Rhine-Westphalia host extrusion facilities serving Central European distribution networks.
United States
Cold chain infrastructure expansion and commercial roofing retrofits sustain demand for high-compressive-strength XPS in automated distribution centers. The EPA AIM Act restricts hydrofluorocarbon blowing agents, compelling parallel reformulation efforts. Manufacturing concentration in the Ohio River Valley supplies Midwest and Southeast construction markets.
France
Green public procurement frameworks prioritize CO2-blown insulation products in state-funded renovation programs. The EU Green Deal trajectory tightens thermal performance requirements for new construction. The Paris metropolitan area concentrates specification activity for high-performance envelope systems in dense urban cores.
Poland
Rapid residential construction growth and EU cohesion fund infrastructure investments expand addressable market for cost-competitive rigid foam boards. CE marking thermal disclosure requirements align procurement specifications with Western European standards. Manufacturing facilities in Silesia serve cross-border projects into Germany and Czechia.
United Arab Emirates
Large-scale commercial and hospitality developments specify moisture-resistant rigid foam for below-grade and roof applications in extreme climate conditions. Emirates Extruded Polystyrene anchors regional supply capacity. Dubai and Abu Dhabi construction markets prioritize fast-track envelope installation through system-integrated board configurations.
Extruded Polystyrene (XPS) Insulation Material Market Competitive Landscape
Reformulation for lower-GWP blowing agents dominates the current landscape as producers reengineer extrusion lines to maintain thermal performance benchmarks under tightening chemical regulations. The vendor base spans integrated petrochemical conglomerates, specialized insulation system houses, and regional extrusion specialists. Three archetypes define competitive positioning: styrene monomer-integrated producers protecting margin structures, system houses bundling insulation with weatherproof membranes, and regional fabricators serving protected geographic markets. M&A activity and capacity expansion for CO2-blown product lines represent the dominant competitive moves.
Among integrated chemical producers, BASF SE leverages captive styrene supply to anchor European manufacturing positions. Owens Corning exemplifies the North American system-house model with distribution through captive roofing channels. Kingspan Group occupies a position as a laminated board specialist bundling insulation with technical field support for modular construction integration.
| Leading Market Players |
|---|
| Saint-Gobain |
| Synthos |
| BASF SE |
| Emirates Extruded Polystyrene |
| Austrotherm |
| Kingspan Group |
| DuPont |
| Jackon Insulation GmbH |
| Owens Corning |
| Others |
Supply & Pricing Matrix
Performance-grade bifurcation between graphite-enhanced formulations and commodity-grade boards splits procurement behavior across German deep retrofit programs and cost-sensitive Polish residential construction. This divergence concentrates margin capture with integrated system houses bundling technical field support while compressing distributor markups on unlaminated sheet products.
Pricing Analysis
Volume-vs-margin split separates project-based contracting for modular construction packages from spot-market transactions in above-grade residential applications. Three-tier pricing structure across premium graphite-enhanced, standard HFO-blown, and economy-grade CO2-blown levels tracks certification tier and compressive strength rating. Pricing pressure stems from polyisocyanurate substitution in high-performance envelopes where lambda values below 0.024 W/m·K outweigh moisture resistance. General contractors on German commercial projects exhibit lowest price sensitivity given package procurement consolidation, while Polish trade contractors drive aggressive spot-market negotiation.
Supply Chain Analysis
Single-source vulnerability sits with benzene-cracker output decisions at integrated petrochemical complexes in the ARA region, tethering European styrene monomer supply to refinery operating rates. Manufacturing concentration clusters in Germany, Belgium, and Poland feed Central European distribution networks. Raw material dependencies encompass styrene monomer, hydrofluoroolefin blowing agents, and graphite particulate additives. Tariff exposure on HFO imports from North American suppliers compounds reformulation cost structures. Distribution runs through captive roofing system channels at integrated building materials conglomerates and independent insulation distributors serving trade contractor spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extruded polystyrene supply constraints around qualified HFO-blowing-agent capacity and polymer foam process engineering expertise prop pricing power for incumbent system houses. Reformulation bottlenecks limit rapid capacity expansion, sustaining margin structures for producers with validated low-GWP product lines.
For Market Incumbents: Deploy captive styrene supply integration to buffer margin compression from benzene price volatility. BASF SE's European plant network exemplifies backward integration protecting cost structures against ARA region cracker output fluctuations. Accelerate HFO-1234ze qualification runs to preempt REACH authorization delays that strand competitor inventory. Channel control through in-house technical field support consolidates procurement volume against standalone distributors lacking installation training capabilities. For New Entrants and Emerging Players: Automated distribution center flooring specifications in Central European cold chain expansion represent the most penetrable white-space target. High-compressive-strength specialty panels for pharmaceutical logistics chains face limited incumbent specialization. CO2-blown product lines accessing French and Dutch green public procurement frameworks offer regulatory-aligned market entry. Go-to-market positioning should emphasize load-bearing tolerance certification and washdown resistance for cleanroom environments. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated building materials conglomerates seeking envelope system bundling capabilities. Long-term viability over the next decade hinges on successful HFO transition completion and modular construction integration depth. Acquisition target archetypes include regional extrusion specialists with validated low-GWP formulations and laminated board fabrication expertise. The signal to watch is F-Gas Regulation quota step-down enforcement accelerating consolidation among reformulation-lagged producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Styrene Monomer | Captive supply from benzene crackers in ARA region buffers margin volatility. |
| HFO-1234ze Formulation Qualification | Accelerated aging protocol completion secures regulatory compliance ahead of F-Gas step-down. |
| CO2-Blown Capacity Expansion | Supercritical carbon dioxide extrusion mastery unlocks green procurement frameworks in France and Netherlands. |
| Laminated Board System Bundling | Factory-bonded membrane integration captures general contractor package awards on modular construction sites. |
| Technical Field Support Investment | In-house installation training capabilities marginalize standalone distributors in German commercial procurement. |
Research Methodology
Independent corroboration across plant managers at extrusion facilities, procurement leads at German general contracting firms, and distribution channel partners in Central Europe underwrites the qualitative findings. Primary interviews with technical R&D directors at blowing agent suppliers and envelope system specification consultants were combined with secondary validation. Secondary sources encompassed customs and trade data tracking styrene monomer flows, Cefic chemical industry reports, and SEC 10-K filings from publicly traded building materials conglomerates. Bottom-up volume modeling across product thickness tiers and top-down value reconciliation anchored the market size estimates.
Comparable-period anchoring to historical consumption patterns in German deep retrofit programs and Polish residential construction growth established the forecast baseline. Segmentation dimensions modeled encompassed product architecture, application context, thickness specification, and end-user procurement sophistication. CAGRs were derived from regression analysis against building code stringency indices and cold chain infrastructure investment pipelines. Industry-specific forecast inputs included F-Gas Regulation phase-down schedules and EU Green Deal thermal performance trajectory assumptions.
Revisions become necessary when REACH authorization timelines for novel blowing agents extend beyond current projections or when polyisocyanurate substitution rates accelerate in high-performance envelope specifications. Forecasts reflect assumptions regarding HFO supply chain maturity and modular construction adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Low Smoke Halogen-Free Cable Materials Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Technical Foam Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Thin Insulation Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Cold-Air Diffusion Market
Insulation Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market
Insulation Materials
Fire Retardant Flexible Cable Market
Insulation Materials
EV Battery Thermal Insulation Materials Market