
 Impact Sound Insulation Acoustic Mat Market | 2026-2036
Impact Sound Insulation Acoustic Mat Market Size, Share, and Industry Trends Forecast 2026-2036
Impact Sound Insulation Acoustic Mat Market Analysis
REACH compliance is decoupling commodity suppliers from profitable European contracts. REGUPOL BSW GmbH leverages captive rubber recycling operations to absorb REACH testing costs without margin erosion. Saint-Gobain anchors its position through building-science R&D labs in France that pre-certify composite mats against evolving acoustic standards. Getzner Werkstoffe GmbH specializes in polyurethane-bound recycled tire formulations that navigate Germany's Bauministerium energy-efficiency requirements.
Impact sound insulation acoustic mats are multi-layer elastomeric or fibrous assemblies, typically 3-12 mm thick, engineered to reduce structure-borne noise transmission through floor-ceiling assemblies by 15-25 dB. Rubber mats dominate commercial flooring applications where point-load durability and long-term compression set resistance justify premium positioning. Composite mats represent the fastest-growing product category as architects demand single-layer solutions that combine acoustic, thermal, and moisture-barrier functions. Foam mats occupy the volume-driven residential segment where contractors prioritize low material cost and rapid installation.
EMA building-product guidelines, CE marking under the Construction Products Regulation, and Germany's DIN 4109 airborne/impact sound standards collectively shape product development priorities and market access conditions across Europe. ECHA substance restrictions on legacy flame retardants are forcing reformulation cycles that favor halogen-free alternatives in mat binders and facing layers. Stakeholders must monitor how EU AI Act documentation requirements for smart building certification systems will reshape acoustic performance verification workflows.
Market Dynamics
Composite acoustic mat technology is unifying thermal, moisture, and acoustic functions into single-layer assemblies, compressing contractor procurement cycles and displacing multi-product stacking approaches in European residential renovation projects.
Growth Catalysts
- EU Green Deal building renovation targets:Germany's DIN 4109 standards now mandate stricter impact sound ratings, forcing residential developers to specify thicker rubber-composite mats in retrofit applications.
- Polyurethane-bound recycled tire formulations:These formulations navigate Germany's Bauministerium energy-efficiency requirements while absorbing REACH testing costs through captive rubber recycling operations.
- China's high-rise residential construction:Cost-competitive foam and felt mat solutions concentrate demand in new floor area construction across Chinese metropolitan towers.
Market Restraints
- ECHA substance restrictions on legacy flame retardants:These restrictions force reformulation cycles that extend product development timelines and raise compliance costs for mat binders and facing layers.
- Rubber raw material concentration in Southeast Asian processing hubs:Supply vulnerability concentrates in tire crumb and synthetic rubber feedstock channels, exposing manufacturers to freight volatility.
- Technical ceiling on multi-function integration:Current composite mats face performance trade-offs between acoustic dampening and thermal conductivity that limit single-layer substitution in extreme climate zones.
Strategic Opportunities
- EU AI Act documentation requirements:Smart building certification systems will reshape acoustic performance verification workflows, creating first-mover advantage for mat suppliers with embedded sensor compatibility.
- Halogen-free binder chemistry convergence:Building-science R&D labs in France are pre-certifying composite mats against evolving standards, opening premium positioning in specification-driven markets.
- Direct contractor channel digitization:Digital procurement platforms are disintermediating traditional distributor networks in residential construction, enabling margin capture by mat manufacturers with installation training capabilities.
Industry Challenges
- CE marking timeline compression under Construction Products Regulation:Extended laboratory testing queues for acoustic performance certification delay product launches and tie up working capital.
- Multi-standard compliance complexity:EMA building-product guidelines, DIN 4109 airborne standards, and evolving EU Green Deal metrics create overlapping documentation burdens that strain quality assurance teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impact Sound Insulation Acoustic Mat Market |
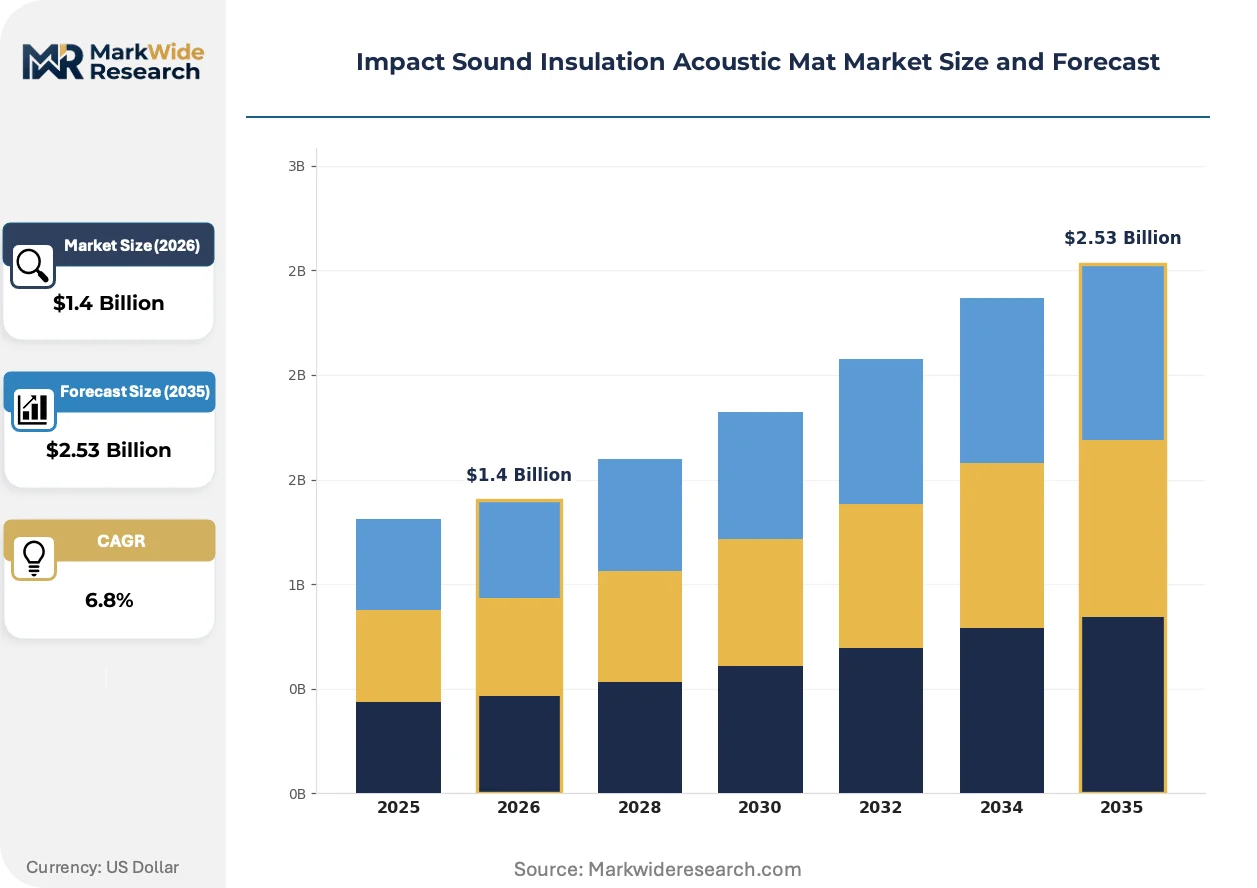
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Mats, Rubber Mats, Felt Mats, Composite Mats Application: Residential Flooring, Commercial Flooring, Industrial Applications, Vehicle Interiors End User: Homeowners, Contractors, Architects, Manufacturers Distribution Channel: Online Retailers, Specialty Stores, Distributors, Direct Sales |
| Companies Covered | REGUPOL BSW GmbH, JCW Acoustic Flooring, Saint-Gobain, Getzner Werkstoffe GmbH, Hush Acoustics Ltd, Owens Corning, Fletcher Insulation, KRAIBURG Relastec GmbH & Co. KG, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impact Sound Insulation Acoustic Mat Market Emerging Trajectories
Material science breakthroughs and regulatory documentation mandates are converging to reshape product architecture and buyer engagement models across the acoustic mat value chain.
Multi-layer elastomeric assemblies with integrated thermal breaks are unifying previously separate building envelope functions. Architects in Nordic countries specify these hybrids for passive house retrofits. This unification compresses contractor material procurement from three suppliers to one, squeezing standalone thermal insulation and vapor barrier producers.
REACH compliance is decoupling commodity suppliers from profitable European contracts through substance testing cost escalation. Industrial consequence falls heaviest on small-format foam mat producers lacking captive laboratory capacity. German mid-cap specialists respond by consolidating rubber recycling operations in-house to absorb ECHA testing overhead without margin erosion.
Specification-driven procurement now dominates commercial flooring decisions, compressing traditional distributor influence. General contractors in France and Benelux markets increasingly source direct from manufacturers with building-science R&D credentials. This channel shift rewards mat producers with pre-certified test data libraries and on-site acoustic engineering support capabilities.
Impact Sound Insulation Acoustic Mat Market Segmentation
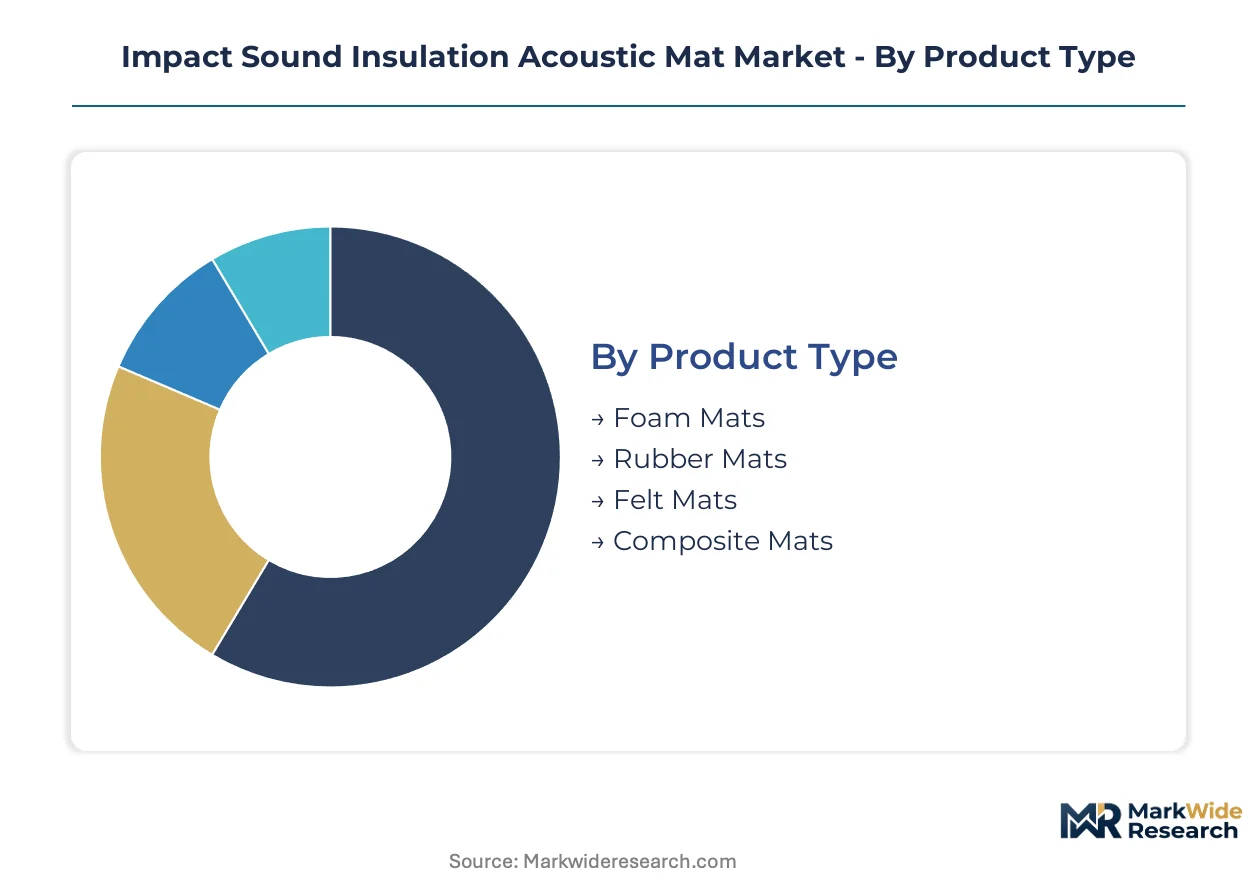
Acoustic mat segmentation reveals divergent value capture strategies across material chemistry and buyer sophistication. Product architecture separates premium specification-driven contracts from high-volume residential procurement, while channel structure determines margin retention for manufacturers navigating distributor disintermediation.
Product Type:
Foam mats dominate unit volume through cost-positioning in multi-family residential towers, while rubber-composite hybrids command specification premiums in commercial retrofit markets.
- Foam Mats:Lightweight polyethylene or polyurethane open-cell structures, typically 3-8 mm thick, optimized for rapid installation in high-rise residential construction. Demand concentrates in Chinese metropolitan towers where contractors prioritize low material cost and minimal labor hours over extended service life. ECHA substance restrictions on legacy flame retardants are forcing reformulation cycles that favor halogen-free alternatives in mat binders.
- Rubber Mats:Dense elastomeric sheets from recycled tire crumb or virgin SBR, engineered for point-load durability and compression set resistance in commercial flooring assemblies. German developers specify thicker rubber-composite mats to meet stricter airborne and impact noise mandates under DIN 4109 standards and EU Green Deal building renovation targets. REACH compliance costs decouple commodity suppliers from profitable European contracts.
- Felt Mats:Compressed synthetic or natural fiber batts offering intermediate acoustic performance at moderate price points, common in Nordic residential retrofits where moisture management competes with sound dampening priorities.
- Composite Mats:Multi-layer assemblies unifying thermal, moisture-barrier, and acoustic functions into single-specification products, gaining traction among architects seeking procurement simplification.
Today's leader: Rubber Mats. Tomorrow's challenger: Composite Mats.
Application:
End-use segmentation tracks construction cycle timing, with residential flooring absorbing volume during new-build phases and commercial flooring driving retrofit replacement demand.
- Residential Flooring:Subfloor preparation in multi-family and single-family construction, where foam and felt solutions dominate due to cost sensitivity and speed of installation.
- Commercial Flooring:Office, hospitality, and healthcare installations where rubber and composite mats justify premium positioning through durability warranties and acoustic certification requirements.
- Industrial Applications:Manufacturing facilities and logistics centers requiring heavy-load bearing capacity and chemical resistance, specifying dense rubber formulations with reinforced facing layers.
- Vehicle Interiors:Automotive OEM and aftermarket applications for cabin noise reduction, utilizing lightweight foam composites meeting OEM flammability specifications.
Residential Flooring holds installed base dominance. Commercial Flooring shows steepest specification-value expansion.
End User:
Buyer sophistication creates tiered engagement models, with architects and contractors controlling specification authority while homeowners and manufacturers represent price-sensitive volume channels.
- Homeowners:Retail purchasers of DIY-friendly foam mat solutions, primarily through online and big-box channels, prioritizing visible price and installation simplicity over technical performance data.
- Contractors:General and specialty trade contractors responsible for material procurement in new construction and renovation, increasingly sourcing direct from manufacturers with embedded installation training capabilities.
- Architects:Specification professionals driving commercial and high-end residential decisions, demanding pre-certified test data libraries and building-science R&D credentials from mat suppliers.
- Manufacturers:Tier-1 and Tier-2 suppliers to automotive, appliance, and equipment OEMs integrating acoustic mats into finished products, requiring batch consistency and supply security documentation.
Architects control premium specification flow. Contractors are consolidating procurement influence through direct channel digitization.
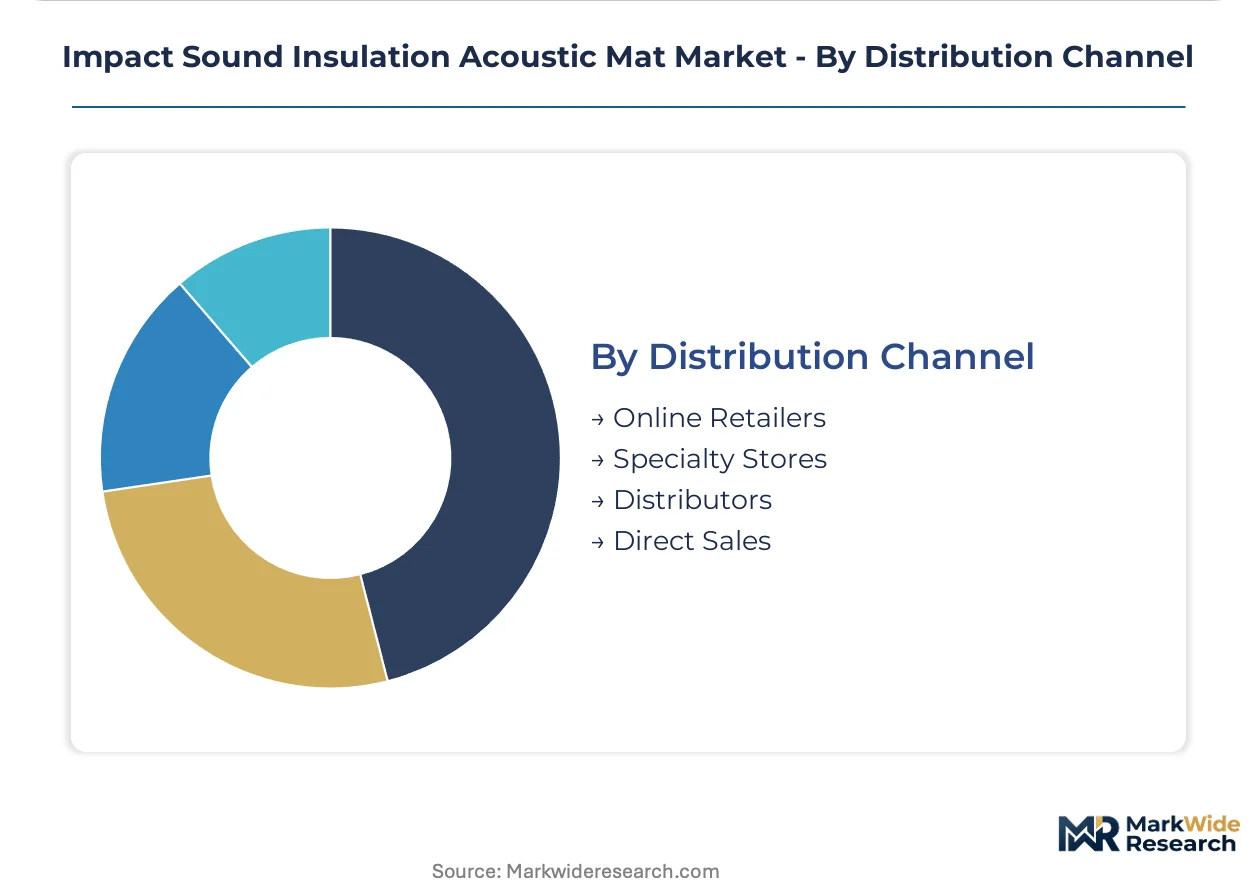
Distribution Channel:
Channel structure determines margin capture, with direct sales and specialty stores retaining value-added services while online platforms and distributors compete on transaction efficiency.
- Online Retailers:E-commerce platforms serving homeowner DIY segment and small contractors, offering price transparency and rapid fulfillment but limited technical support or acoustic engineering consultation.
- Specialty Stores:Regional building material suppliers with acoustic product expertise, maintaining relationships with local contractor networks and providing on-site specification assistance.
- Distributors:National and regional wholesale networks handling inventory aggregation and logistics for multi-site construction projects, facing margin compression from manufacturer direct engagement.
- Direct Sales:Manufacturer-to-contractor and manufacturer-to-architect relationships, enabled by digital procurement platforms and installation certification programs that disintermediate traditional distribution.
Direct Sales channels gain specification-driven share. Distributors defend position through project financing and logistics bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acoustic mat manufacturing clusters concentrate near recycled rubber processing hubs and dense urban construction zones. Technical workforce pools in polymer chemistry and building acoustics anchor regional competitive advantage across three continents.
Germany
Residential retrofit contractors in Berlin and Hamburg specify thicker rubber-composite mats to meet DIN 4109 airborne and impact noise mandates. The EU Green Deal building renovation targets tighten compliance timelines through 2030. Bavaria's industrial corridor hosts captive rubber recycling operations that absorb REACH testing costs without margin erosion.
China
High-rise residential towers in Shanghai and Shenzhen concentrate demand for cost-competitive foam and felt mat solutions. The country's dual carbon goals pressure developers toward lower-embodied-carbon flooring assemblies. Yangtze River Delta manufacturing bases supply volume-driven residential segments across East Asian metropolitan construction.
United States
Commercial office renovation in New York and Los Angeles drives specification-grade rubber mat procurement. EPA and OSHA workplace noise guidelines shape material selection in healthcare and hospitality flooring. Southeast construction corridors absorb volume from residential multi-family expansion near Atlanta and Charlotte.
France
Architects in Paris and Lyon specify composite mats that unify thermal, moisture-barrier, and acoustic functions into single-layer assemblies. EMA building-product guidelines and CE marking requirements pre-certify products through building-science R&D labs in Île-de-France. Passive house retrofits in Nordic-adjacent regions accelerate hybrid mat adoption.
United Kingdom
London developers face stricter Building Regulations Part E sound insulation requirements in high-density residential conversion projects. HSE workplace noise exposure limits influence commercial flooring specification in Manchester and Birmingham industrial zones. Midlands manufacturing clusters serve distribution networks across England and Ireland.
Impact Sound Insulation Acoustic Mat Market Vendor Landscape
The competitive structure tilts toward mid-cap specialists with captive raw material processing. German and Austrian fabricators dominate premium specification channels through building-science credentials. Three archetypes anchor positioning: vertically integrated rubber recyclers, multi-material composite developers, and volume-focused foam producers. Strategic moves concentrate on backward integration into tire crumb supply and direct contractor channel digitization.
Among German-based specialists, REGUPOL BSW GmbH and Getzner Werkstoffe GmbH exemplify the captive-recycling archetype. Saint-Gobain occupies a position representing multi-national building-material conglomerates with R&D laboratory infrastructure. These three sit within distinct competitive vectors—recycling integration, research pre-certification, and scale manufacturing—rather than direct product overlap.
| Leading Market Players |
|---|
| REGUPOL BSW GmbH |
| JCW Acoustic Flooring |
| Saint-Gobain |
| Getzner Werkstoffe GmbH |
| Hush Acoustics Ltd |
| Owens Corning |
| Fletcher Insulation |
| KRAIBURG Relastec GmbH & Co. KG |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
German residential developers' DIN 4109 compliance mandates for thicker rubber-composite mats are forcing supply-side capacity reallocation toward premium formulations, compressing margins on standardized foam products while elevating pricing power for REACH-certified specialists with captive recycling operations.
Pricing Analysis
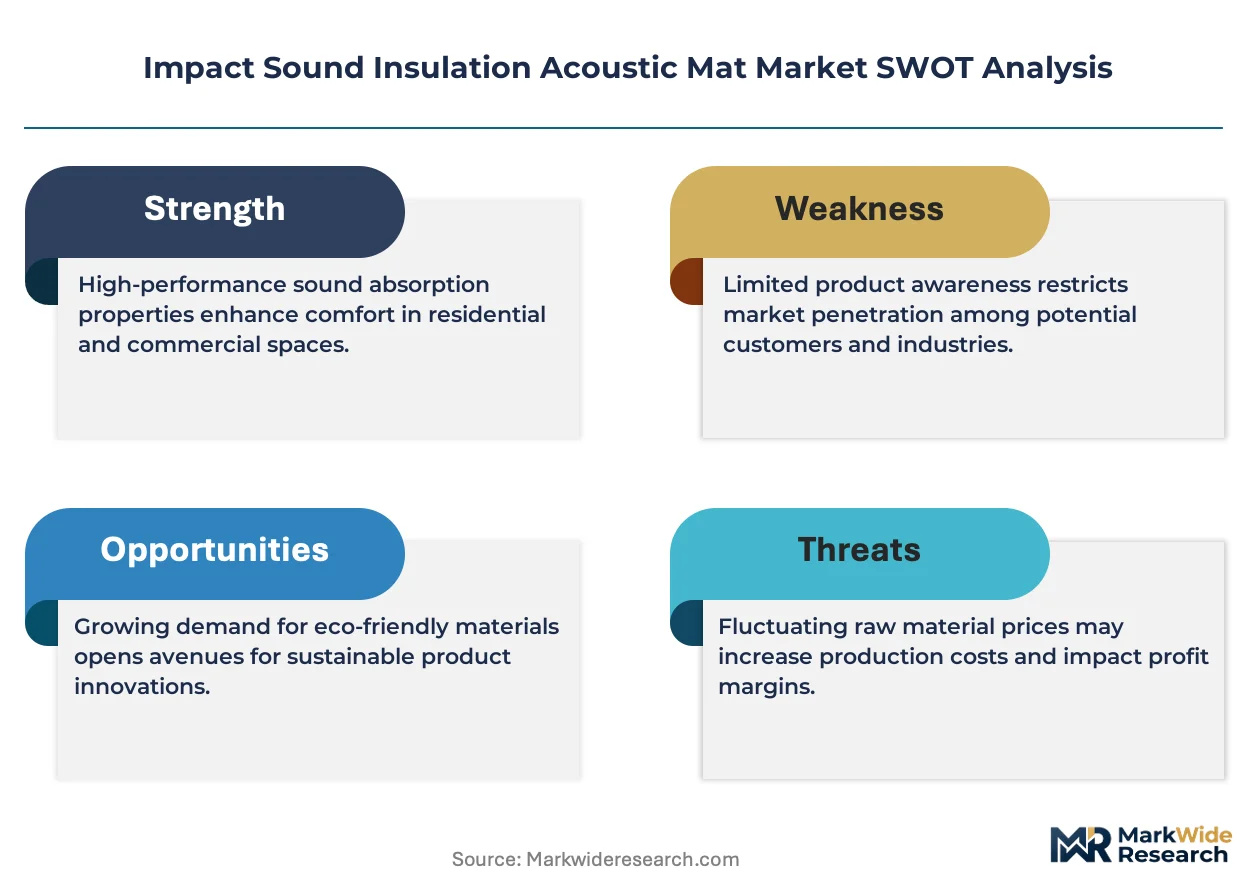
Bundled specification services versus unbundled material-only transactions define pricing architecture across the acoustic mat value chain. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and installation support depth, with DIN 4109 pre-certified rubber-composite mats commanding substantial premiums over uncertified foam alternatives. Price differentiation stems from REACH compliance documentation costs and acoustic engineering consultation bundling. Cost compression in economy foam tiers is intensifying because Chinese manufacturing overcapacity floods spot markets with undifferentiated polyethylene products. Homeowner DIY segments exhibit acute price sensitivity, while architect-driven commercial specifications prioritize performance guarantees over unit economics.
Supply Chain Analysis
Direct-to-contractor digital procurement platforms handle specification-grade demand, disintermediating traditional distributor networks in German and French metropolitan construction corridors. Geographic supply concentration centers on Germany, China, and the United States, with Bavaria's industrial corridor hosting captive tire crumb processing and Yangtze River Delta bases serving volume-driven residential segments. Raw material dependencies draw from recycled tire crumb, virgin SBR synthetic rubber, and polyurethane binder chemistries. Single-source vulnerability concentrates in Southeast Asian tire crumb processing hubs, exposing manufacturers to freight volatility and regulatory inspection delays. Distribution runs through manufacturer-direct channels for premium specifications and regional wholesale networks for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-compliant European premium positioning and cost-optimized Chinese volume manufacturing, with regulatory compliance cost differentials exceeding raw material spreads by substantial margins.
For Market Incumbents: Lock in architect specification relationships through embedded acoustic engineering support and pre-certified test data libraries that small-format foam competitors cannot replicate. Deepen backward integration into tire crumb supply channels to absorb ECHA testing overhead without margin erosion, while expanding direct digital procurement platforms to capture distributor-disintermediated contractor demand in French and Benelux markets. For New Entrants and Emerging Players: Direct contractor channel digitization offers the most penetrable entry vector, targeting mid-size German residential retrofit contractors underserved by incumbent technical sales forces. White-space concentrates in halogen-free binder chemistry formulations navigating ECHA substance restrictions, and in Nordic passive house retrofit markets demanding thermal-acoustic hybrid functionality. Pursue specification-grade positioning through building-science R&D partnerships rather than commodity volume competition. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing captive rubber recycling operations and DIN 4109 pre-certification infrastructure, as REACH compliance barriers widen competitive moats against undifferentiated Asian imports. Long-term viability hinges on embedded sensor compatibility for EU AI Act documentation workflows. Monitor CE marking laboratory testing queue compression as an inflection indicator for working capital stress among specification-dependent players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tire Crumb Supply | Captive recycling operations absorb REACH testing costs that decouple commodity competitors from European contracts. |
| Building-Science R&D Laboratory Investment | Pre-certification against evolving DIN 4109 standards anchors specification-driven procurement in German retrofit markets. |
| Direct Contractor Channel Digitization | Digital procurement platforms disintermediate distributor networks and enable margin capture through installation training bundling. |
| Halogen-Free Binder Chemistry Development | ECHA substance restrictions on legacy flame retardants force reformulation cycles favoring compliant specialists. |
| Embedded Sensor Compatibility Engineering | EU AI Act documentation requirements for smart building certification reshape acoustic performance verification workflows. |
Methodological Framework
Direct dialogue with acoustic product specification managers, residential construction procurement directors, building-science R&D laboratory directors, and REACH compliance consultants grounded qualitative findings in operational reality. Secondary validation drew from ECHA substance restriction databases, DIN 4109 standard revision documentation, EU Green Deal building renovation target disclosures, and Construction Products Regulation CE marking certification records. Bottom-up and top-down triangulation cross-checked manufacturer capacity announcements against regional construction permit data and acoustic mat import trade statistics.
Bottom-up volume modeling by product type, application end-use, and buyer sophistication tier integrated with top-down macro construction spending elasticity estimates across the projection horizon. Segmentation dimensions incorporated material chemistry, specification authority level, and distribution channel structure. CAGRs were derived from regression analysis of historical price-volume relationships and regulatory compliance cost trajectories. Industry-specific forecast inputs included EU Green Deal renovation target implementation timelines and ECHA substance restriction phase-out schedules.
The model assumes a particular technology adoption path; alternative pathways for multi-layer thermal-acoustic hybrid mat unification would alter the outlook if passive house retrofit incentives accelerate faster than baseline assumptions. Forecasts reflect documented assumptions about REACH compliance cost pass-through rates and contractor procurement digitization velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
Insulation Products Market
Insulation Materials
Mineral Wool Insulation Market
Insulation Materials
Mineral Wool Board Insulation Market
Insulation Materials
Silver Ion Antibacterial Insulation Cup Market
Insulation Materials
Americas Pipe Insulation Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Global Electrical Insulation Materials Market
Insulation Materials
Flexible Insulation Market