
 North America Hydrocarbon Fire Intumescent Coating Services Market | 2026-2036
North America Hydrocarbon Fire Intumescent Coating Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hydrocarbon Fire Intumescent Coating Services Market Intelligence
Modular service bundling is decoupling inspection from application contracts across the North American hydrocarbon fireproofing sector. Painters USA, Inc. leverages its regional facility network to anchor maintenance-driven recurring revenue in Gulf Coast industrial corridors. Hempel A/S competes through specialized marine-to-land technology transfer, while US Coatings dominates turnaround scheduling with in-house production of intumescent formulations.
North America hydrocarbon fire intumescent coating services encompass the engineered application of reactive polymer systems that expand under thermal exposure to form insulating char layers, typically achieving dry-film thicknesses of 3–15 millimeters on structural steel exposed to pool-fire and jet-fire scenarios. These coatings protect load-bearing members from rapid temperature rise during hydrocarbon combustion events, preserving structural integrity for specified durations per UL 1709 and ASTM E1529 protocols. Application services command the largest share of value within the service type dimension, driven by the labor-intensive surface preparation and spray-applied installation requirements on complex geometries, while oil and gas verticals concentrate margin pools due to the premium certification and insurance-backed warranty structures demanded by offshore and downstream operators. Water-based formulations are gaining share in indoor and confined-space projects where VOC emissions trigger OSHA and EPA compliance thresholds.
OSHA Process Safety Management standards, EPA National Emission Standards for Hazardous Air Pollutants, and NFPA fire protection codes collectively mandate documented coating integrity across U.S. petrochemical facilities, creating recurring inspection and reapplication obligations. Canadian regulators under CSA S16 and provincial fire codes enforce parallel requirements for oil sands processing and LNG export infrastructure. Stakeholders must monitor evolving API and NFPA revision cycles to anticipate shifts in required fire-resistance ratings and certification scopes.
Market Dynamics
Modular service unbundling is fragmenting the North American hydrocarbon fireproofing value chain, as Gulf Coast operators separate inspection contracts from application work to compress turnaround timelines and sharpen price transparency.
Growth Catalysts
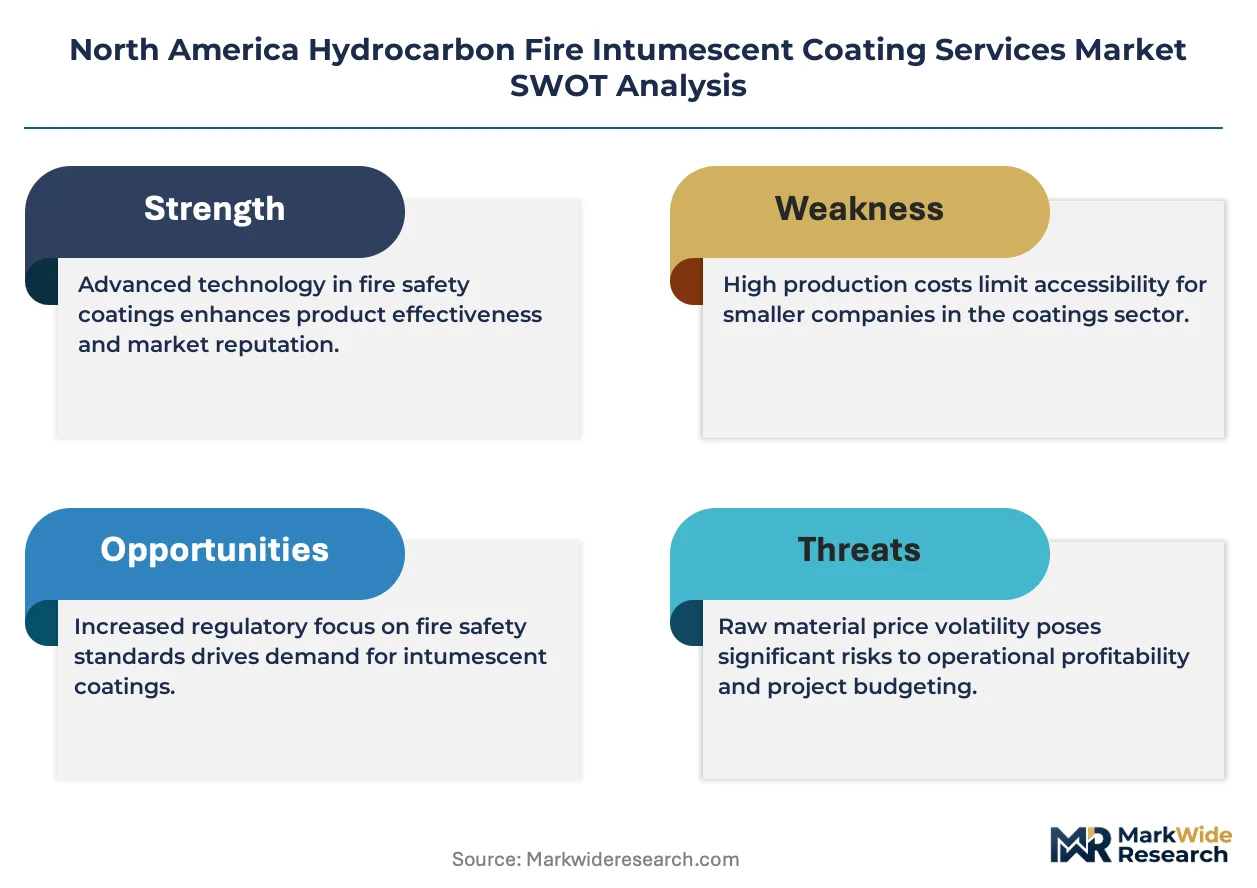
- NFPA 291 Revisions:Tighter fireproofing requirements for hydrocarbon-exposed steel are mandating thicker intumescent applications across Texas and Louisiana refineries.
- Offshore Platform Expansion:Gulf of Mexico operators are expanding certified coating procurement for subsea and topside structural protection.
- Water-Based Formulation Advances:Reduced VOC emissions are enabling indoor application projects previously blocked by OSHA air quality thresholds.
Market Restraints
- Epoxy Resin Price Volatility:Feedstock fluctuations for intumescent binders squeeze applicator margins during long-duration contracts.
- Specialized Applicator Concentration:Certified contractors cluster along the Texas-Louisiana corridor, creating regional supply bottlenecks during simultaneous turnaround seasons.
- Cementitious Fireproofing Substitution:Lower-cost spray-applied cement systems capture budget-constrained midstream storage projects.
Strategic Opportunities
- Canadian Oil Sands Infrastructure:Alberta thermal extraction and LNG export facilities under CSA S16 enforcement create underpenetrated demand for certified applicators.
- Drone-Assisted Inspection Convergence:UAV-based dry-film thickness verification is compressing inspection cycles and enabling predictive maintenance contracts.
- EPA NESHAP Alignment:Hazardous air pollutant tracking mandates are converting episodic reapplication into recurring compliance-driven revenue streams.
Industry Challenges
- Spray-Application Technician Shortage:Skilled operators capable of achieving UL 1709-certified thickness tolerances on complex geometries remain scarce.
- API RP 2021 Certification Timelines:Extended third-party validation cycles delay project mobilization and compress contractor utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hydrocarbon Fire Intumescent Coating Services Market |
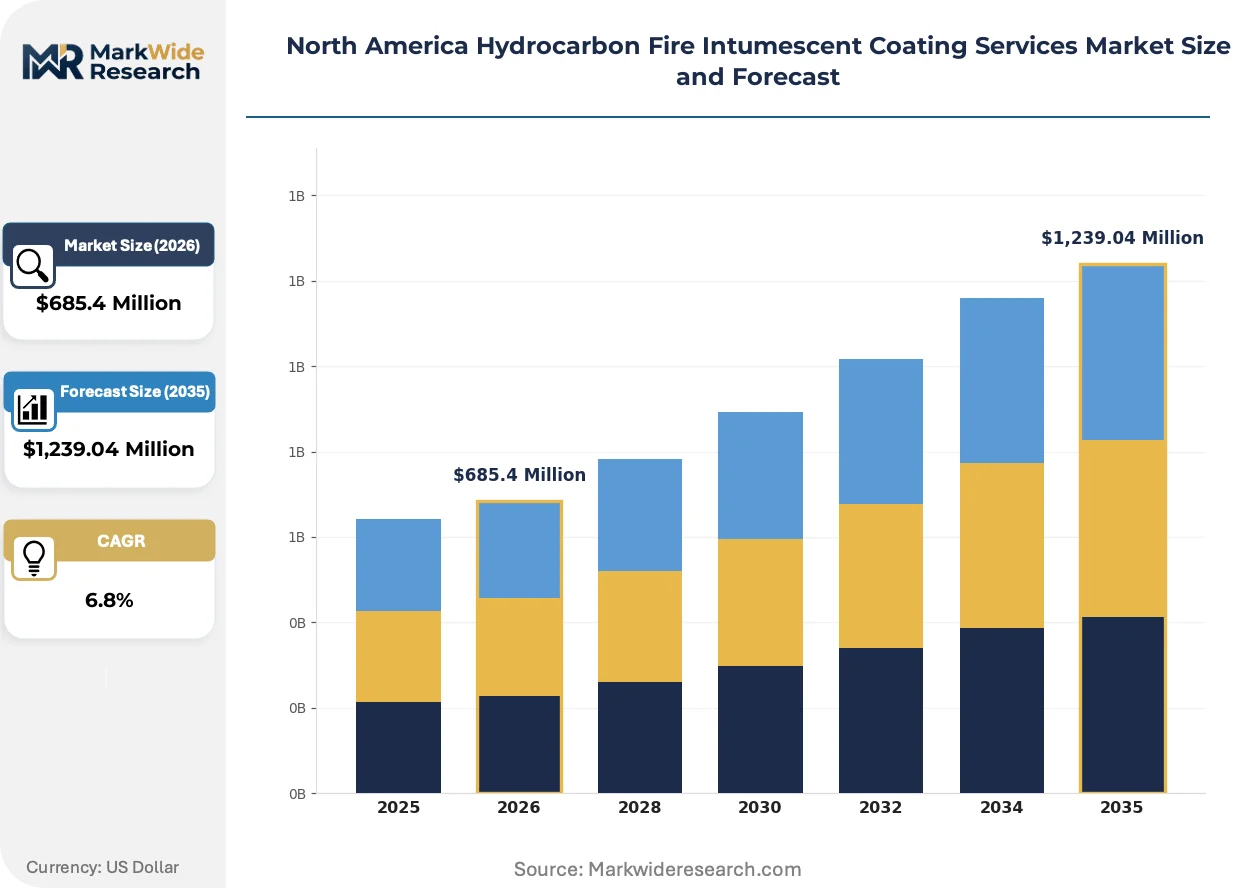
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Application, Testing, Maintenance Industry Vertical: Construction, Oil & Gas, Transportation, Power Generation Coating Type: Water-Based, Solvent-Based, Epoxy, Intumescent End User: Contractors, Architects, Engineers, Facility Managers |
| Companies Covered | Contego International, Inc., Donalco, Painters USA, Inc., Fire Barrier Experts, Aries Contracting, Performance Painting, US Coatings, Brand Industrial Services, Hempel A/S, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hydrocarbon Fire Intumescent Coating Services Market Strategic Shifts & Innovations
Digital workflow integration and formulation chemistry advances are compressing project timelines while expanding the addressable project universe beyond traditional outdoor steel structures.
Robotic spray application systems are automating thickness control on repetitive structural members like I-beams and columns. Offshore fabricators in the Gulf of Mexico are piloting these units for platform jacket fireproofing. The technology is automating labor cost structures and reducing rework rates on geometrically complex joints.
OSHA Process Safety Management enforcement is tightening documented coating integrity requirements across U.S. petrochemical facilities. Facility operators must now maintain continuous inspection records traceable to individual applicator certifications. Downstream refineries in Texas are responding by embedding coating condition monitoring into their mechanical integrity programs.
Service unbundling is fragmenting traditional turnkey contracts into discrete inspection, surface preparation, and application work packages. Industrial facility managers are awarding these elements to separate specialists to sharpen accountability and compress total project duration. This pattern is most visible in Louisiana chemical corridor turnarounds where schedule risk carries premium penalty clauses.
North America Hydrocarbon Fire Intumescent Coating Services Market Segmentation
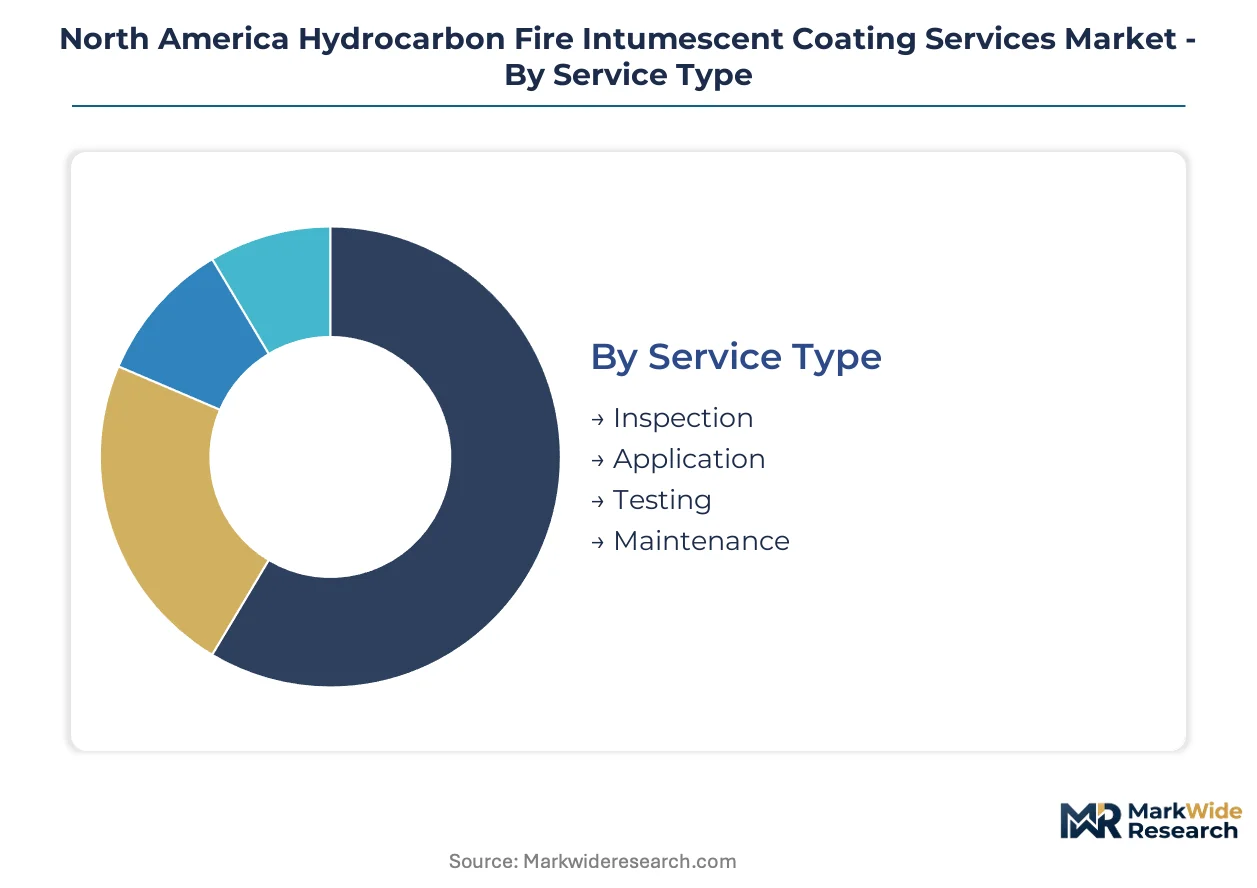
Service unbundling and formulation chemistry advances are fragmenting procurement patterns across the North American hydrocarbon fireproofing sector. Segmentation clarity enables operators to match capital intensity and technical risk to appropriate contractor capabilities.
Service Type:
Application services demand the highest upfront capital commitment due to spray equipment fleets and certified technician training infrastructure.
- Application:Spray-applied intumescent systems require pneumatic plural-component rigs and UL 1709-certified applicators achieving 3–15 millimeter dry-film tolerances on complex structural geometries. Gulf Coast refineries in Texas and Louisiana concentrate procurement for turnaround-driven volume surges.
- Inspection:Drone-assisted dry-film thickness verification and char-layer integrity assessment are compressing cycle times. OSHA Process Safety Management mandates are converting episodic checks into recurring compliance revenue streams.
- Testing:Third-party validation of fire-resistance ratings per ASTM E1529 protocols.
- Maintenance:Reapplication scheduling tied to EPA NESHAP tracking and mechanical integrity programs.
Most installed capacity flows through Application. Expansion is steepest in Inspection.
Industry Vertical:
Margin profiles diverge sharply based on certification burden and insurance-backed warranty requirements.
- Oil & Gas:Offshore platform operators in the Gulf of Mexico and downstream refineries demand premium certified coating packages with API RP 2021 compliance. NFPA 291 revisions are mandating thicker applications across hydrocarbon-exposed steel infrastructure.
- Construction:Commercial and industrial building projects specify intumescent systems for atrium steel and concealed structural members.
- Power Generation:LNG export terminals and thermal power facilities require jet-fire rated formulations.
- Transportation:Pipeline compressor stations and rail loading facilities specify rapid-cure systems for minimized downtime.
Highest value-per-square-foot concentrates in Oil & Gas. Construction volumes are expanding most quickly as water-based formulations penetrate indoor specifications.
Coating Type:
Formulation selection hinges on VOC exposure thresholds and substrate compatibility.
- Water-Based:Acrylic and vinyl acetate copolymer systems enable indoor and confined-space projects where OSHA air quality thresholds previously blocked solvent alternatives. Reduced emissions profiles are penetrating Texas chemical corridor maintenance cycles.
- Solvent-Based:Epoxy and alkyd hybrid systems dominate outdoor offshore applications requiring rapid cure and humidity tolerance.
- Epoxy:High-build formulations for subsea and immersion service.
- Intumescent:Reactive polymer systems expanding to insulating char under thermal exposure.
Legacy installed base remains solvent-heavy. Water-Based formulations are gaining share fastest on regulatory tailwinds.
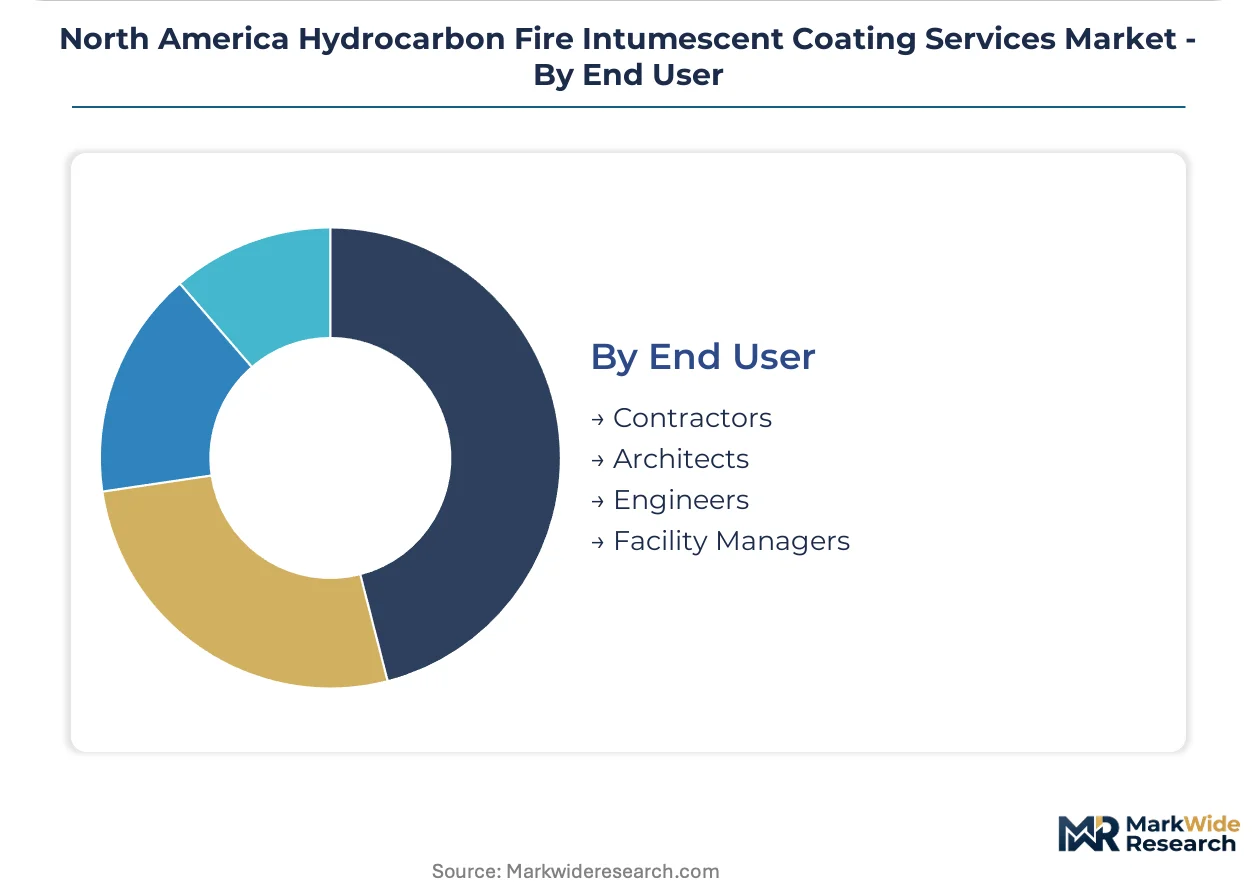
End User:
Procurement authority is fragmenting as facility operators unbundle turnkey contracts.
- Contractors:Specialty fireproofing applicators in the Texas-Louisiana corridor control mobilization schedules and certified labor pools. Turnaround penalty clauses are sharpening price transparency demands.
- Facility Managers:Petrochemical operators are embedding coating condition monitoring into mechanical integrity programs with continuous documentation traceable to individual applicator certifications.
- Architects:Specification authority for new commercial and industrial construction.
- Engineers:Structural and fire protection engineering firms validating fire-resistance ratings.
Contractors command the largest procurement volume. Facility Managers are expanding their specification influence fastest through compliance-driven recurring obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American hydrocarbon fireproofing industry traces its commercial scale to post-World War II Gulf Coast petrochemical construction, when Texas and Louisiana refineries pioneered certified intumescent application protocols for hydrocarbon-exposed steel.
United States
Texas and Louisiana dominate procurement volumes, with Houston and Lake Charles anchoring turnaround-driven demand surges. OSHA Process Safety Management standards mandate documented coating integrity across petrochemical facilities, converting episodic maintenance into recurring compliance obligations. The Gulf Coast chemical corridor concentrates certified applicator capacity, though regional bottlenecks emerge during simultaneous turnaround seasons.
Canada
Alberta oil sands thermal extraction and British Columbia LNG export infrastructure create underpenetrated demand pools for certified fireproofing services. CSA S16 and provincial fire codes enforce requirements parallel to U.S. standards, with Alberta's regulator mandating documented structural protection for bitumen processing vessels. Calgary and Edmonton serve as procurement hubs for oil sands maintenance cycles.
Mexico
Refinery modernization at Dos Bocas and Salamanca drives specification of hydrocarbon-rated intumescent systems for new crude processing capacity. Mexican federal environmental regulations align with EPA NESHAP frameworks for hazardous air pollutant tracking, creating compliance-driven reapplication schedules. Tamaulipas and Veracruz host emerging applicator networks serving Pemex downstream operations.
North America Hydrocarbon Fire Intumescent Coating Services Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification burden and warranty backing. The North American hydrocarbon fireproofing sector exhibits moderate concentration, with regional specialists commanding Gulf Coast procurement against diversified coating multinationals. Three archetypes dominate: certified turnaround specialists with in-house formulation production, marine-to-land technology transferors, and diversified industrial services conglomerates. Capacity expansion and modular service unbundling represent the dominant competitive vectors, as operators separate inspection contracts to compress project timelines.
Among Gulf Coast-based specialists, Painters USA, Inc. and US Coatings exemplify the certified turnaround archetype, leveraging regional facility networks to anchor maintenance-driven recurring revenue. Hempel A/S represents the marine-to-land transferor position, competing through specialized technology migration from offshore platform applications. These three entities occupy distinct margin tiers based on certification scope and captive production capabilities.
| Leading Market Players |
|---|
| Contego International, Inc. |
| Donalco |
| Painters USA, Inc. |
| Fire Barrier Experts |
| Aries Contracting |
| Performance Painting |
| US Coatings |
| Brand Industrial Services |
| Hempel A/S |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up Gulf Coast specialists anchor supply concentration along the Texas-Louisiana corridor, translating certified applicator scarcity into pricing power during simultaneous turnaround seasons while compressing margins through epoxy resin feedstock volatility.
Pricing Analysis
Project-based contracting with penalty-clause exposure dominates procurement, separating premium API RP 2021-certified packages from standard maintenance cycles and economy-grade cementitious substitutions. Price differentiation hinges on UL 1709 certification tier and in-house formulation production. Cost compression in economy tiers intensifies as cementitious systems capture budget-constrained midstream storage projects. Facility managers in Louisiana chemical corridors exhibit highest price sensitivity due to turnaround penalty exposure, while offshore platform operators in the Gulf of Mexico show lowest sensitivity given insurance-backed warranty requirements.
Supply Chain Analysis
Skilled spray-application technicians cluster disproportionately in Houston and Lake Charles, creating workforce bottlenecks that constrain mobilization capacity during peak seasons. Raw material sourcing draws from epoxy resin suppliers in the United States, titanium dioxide feedstock from Canada, and intumescent additive specialists in Mexico. Single-source vulnerability concentrates in certified third-party validation laboratories for ASTM E1529 fire-resistance testing. Distribution runs through specialty industrial services distributors serving refinery and petrochemical facility operators directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canadian oil sands infrastructure presents a geographic-arbitrage opportunity, as Alberta's CSA S16 enforcement creates demand premiums above Texas-Louisiana pricing levels while certified applicator density remains thin.
For Market Incumbents: Deploy captive formulation production to compress material cost exposure and accelerate turnaround response times. Cementitious fireproofing substitution threatens midstream storage margins; defend through UL 1709 certification investment and embedded coating condition monitoring contracts. Add certified technician training capacity in Calgary to capture Alberta thermal extraction cycles. For New Entrants and Emerging Players: Drone-assisted inspection platforms offer the most penetrable entry vector, converting OSHA Process Safety Management mandates into recurring revenue without heavy spray-equipment capital. Target Alberta LNG export terminals and British Columbia coastal facilities where CSA enforcement outpaces certified applicator supply. Lead with predictive maintenance software bundled with UAV-based dry-film thickness verification. For Investors and Strategic Acquirers: Marine-to-land technology transferors are the most active acquirer in this space, seeking Gulf Coast application capacity to complement offshore platform expertise. Five-to-ten year viability rests on EPA NESHAP compliance-driven reapplication frequency expansion. Monitor NFPA 291 revision cycles for fire-resistance rating threshold increases that would trigger systemic reapplication demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intumescent Formulation Production | In-house binder manufacturing insulates margins from epoxy resin volatility and accelerates turnaround mobilization. |
| Drone-Assisted Inspection Platform Deployment | UAV-based dry-film thickness verification compresses OSHA-mandated inspection cycles into predictive maintenance contracts. |
| Canadian Certified Applicator Network Expansion | Calgary-anchored capacity captures Alberta oil sands and British Columbia LNG infrastructure under CSA S16 enforcement. |
| Water-Based Formulation R&D Investment | Reduced VOC profiles unlock indoor chemical corridor projects previously blocked by OSHA air quality thresholds. |
| API RP 2021 Certification Acceleration Program | Shortened third-party validation timelines improve contractor utilization rates during peak turnaround seasons. |
Research Approach
Multiple input streams — certified applicator interviews, refinery procurement lead consultations, and coating formulation technical director exchanges — were reconciled against EPA NESHAP compliance databases, OSHA Process Safety Management inspection records, and API RP 2021 certification registries. Secondary validation incorporated UL 1709 test data, ASTM E1529 fire-resistance documentation, and Gulf Coast industrial construction permit filings. Bottom-up project pipeline aggregation and top-down petrochemical facility inventory analysis were cross-checked for triangulation.
Data-stream reconciliation enabled modeling across service type, coating formulation chemistry, and industry vertical dimensions throughout the forecast period. CAGRs were derived from facility construction permit trajectories, turnaround cycle frequencies, and regulatory revision impact assessments. Modeled inputs included NFPA 291 adoption timelines, offshore platform decommissioning-replacement ratios, and water-based formulation penetration curves in indoor applications.
The model assumes a particular technology adoption path; alternative pathways for robotic spray application would alter the outlook if offshore fabricator pilot programs achieve commercial scale faster than projected. Practitioners should monitor API revision cycles, epoxy resin futures pricing, and Canadian oil sands project sanctioning rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Inorganic Antimicrobial Coatings Market
Coatings
Antimicrobial Coil Coating Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
E-Coat Market
Coatings
Textile Coatings Market
Coatings
CVD Coating Technology Market
Coatings
Russia Protective Coatings Market
Coatings
Thermal Barrier Coatings Market
Coatings
Waterborne Automobile Coating Market
Coatings
Heavy Duty Glass Coating Market
Coatings
US Concrete Floor Coatings Market
Coatings
Zero Friction Coatings Market
Coatings
US Protective Coatings Market
Coatings
Fire Retardant Coatings Market
Coatings
North America Epoxy Powder Coatings Market
Coatings
Japan Automotive OEM Coatings Market