
 North America Flexible Foam Market | 2026-2036
North America Flexible Foam Market Size, Share, and Industry Trends Forecast 2026-2036
North America Flexible Foam Market Analysis
Mexico's Querétaro corridor is narrowing the supply deficit for automotive-grade polyurethane slabs as foreign producers add cut-and-sew capacity near OEM assembly plants. Covestro leverages its Baytown, Texas, polyol complex to sustain backward integration into flexible foam systems for North American automotive seating. Huntsman International anchors its regional position through MDI supply agreements with Tier-1 converters in Michigan and Ontario. Dow competes on polyethylene foam formulations for protective packaging, where e-commerce fulfillment centers drive specification intensity.
North America flexible foam encompasses cellular polymer structures with open-cell or closed-cell architectures, typically produced via continuous slabstock or molded reaction injection processes using polyols, isocyanates, and controlled blowing agents; these materials deliver controlled resilience, energy absorption, and acoustic dampening across industrial and consumer applications. Polyurethane foam dominates value generation due to its tunable density range and established supply base, while memory foam commands premium positioning in bedding and healthcare cushioning where pressure redistribution defines specification. Latex foam retains share in natural-origin consumer goods segments, though synthetic polyol economics constrain expansion in price-sensitive furniture channels.
The EPA enforces VOC limits under TSCA Title VI, pushing manufacturers toward hydrofluoroolefin and water-blown alternatives that alter cell structure and durability profiles. Health Canada applies CHPSA flammability standards to upholstered furniture, creating cross-border compliance complexity for producers serving both US and Canadian retail channels. California's TB 117-2013 smolder-resistant standard continues to influence national formulation practices through de facto adoption by mass-market retailers. Stakeholders must monitor state-level chemical disclosure laws as they proliferate beyond existing frameworks, since preemptive transparency investments will determine market access speed across diverging regulatory timelines.
Market Dynamics
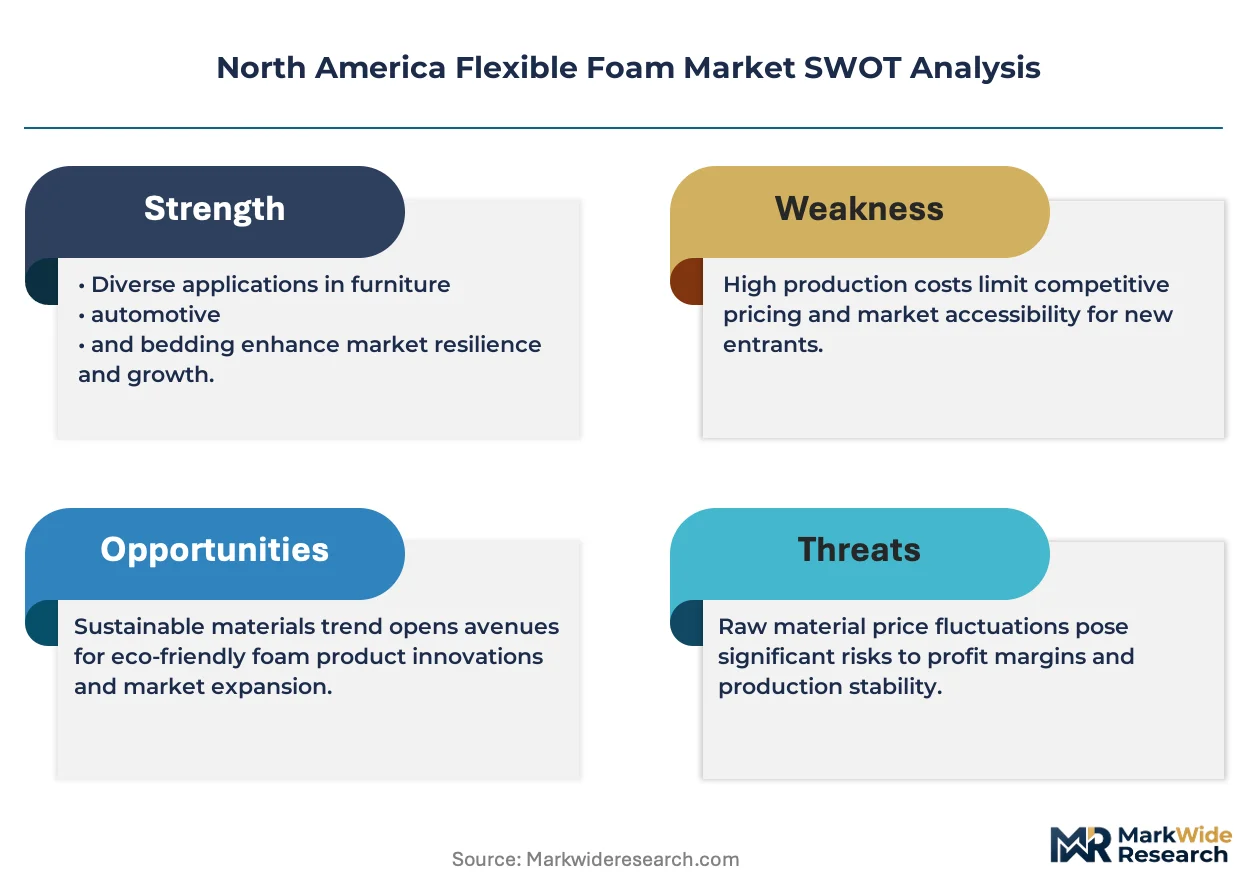
EPA's updated VOC emission thresholds under TSCA Title VI are forcing wholesale reformulation of conventional blowing agents across North American flexible foam production, compressing margins for converters while accelerating adoption of hydrofluoroolefin and water-blown alternatives.
Growth Catalysts
- Automotive seating localization:Mexico's Querétaro automotive cluster is drawing Tier-1 suppliers to establish cut-and-sew fabrication capacity adjacent to OEM final assembly plants.
- TSCA Title VI compliance:The EPA's revised VOC thresholds are creating first-mover advantages for producers with certified low-emission formulation capabilities.
- Viscoelastic grade specification:Detroit and Toronto automotive programs are absorbing higher volumes of memory foam grades for premium seating applications.
Market Restraints
- Polyol-isocyanate input volatility:MDI and TDI pricing swings compress converter margins, particularly for small-batch furniture producers lacking long-term supply agreements.
- Supply concentration risk:Gulf Coast petrochemical complexes dominate North American polyol production, exposing the value chain to hurricane-related disruption.
- Cross-border regulatory friction:Health Canada's CHPSA flammability standards diverge from California's TB 117-2013, forcing dual-certification costs for producers serving both markets.
Strategic Opportunities
- Healthcare pressure-redistribution:Medical device OEMs are specifying higher-density viscoelastic grades for patient positioning surfaces in long-term care facilities.
- E-commerce protective packaging:Fulfillment centers are driving specification intensity for polyethylene foam formats with custom die-cut configurations.
- Water-blown system convergence:Advancements in surfactant chemistry are enabling water-blown polyurethane to match HFC-blown performance in automotive seating durability tests.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required to balance blowing agent transitions with cell-structure integrity is concentrating among a shrinking pool of experienced compounders.
- Legacy equipment retooling:Continuous slabstock lines designed for CFC-era chemistry require substantial capital modification to process next-generation blowing agents without throughput loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Flexible Foam Market |
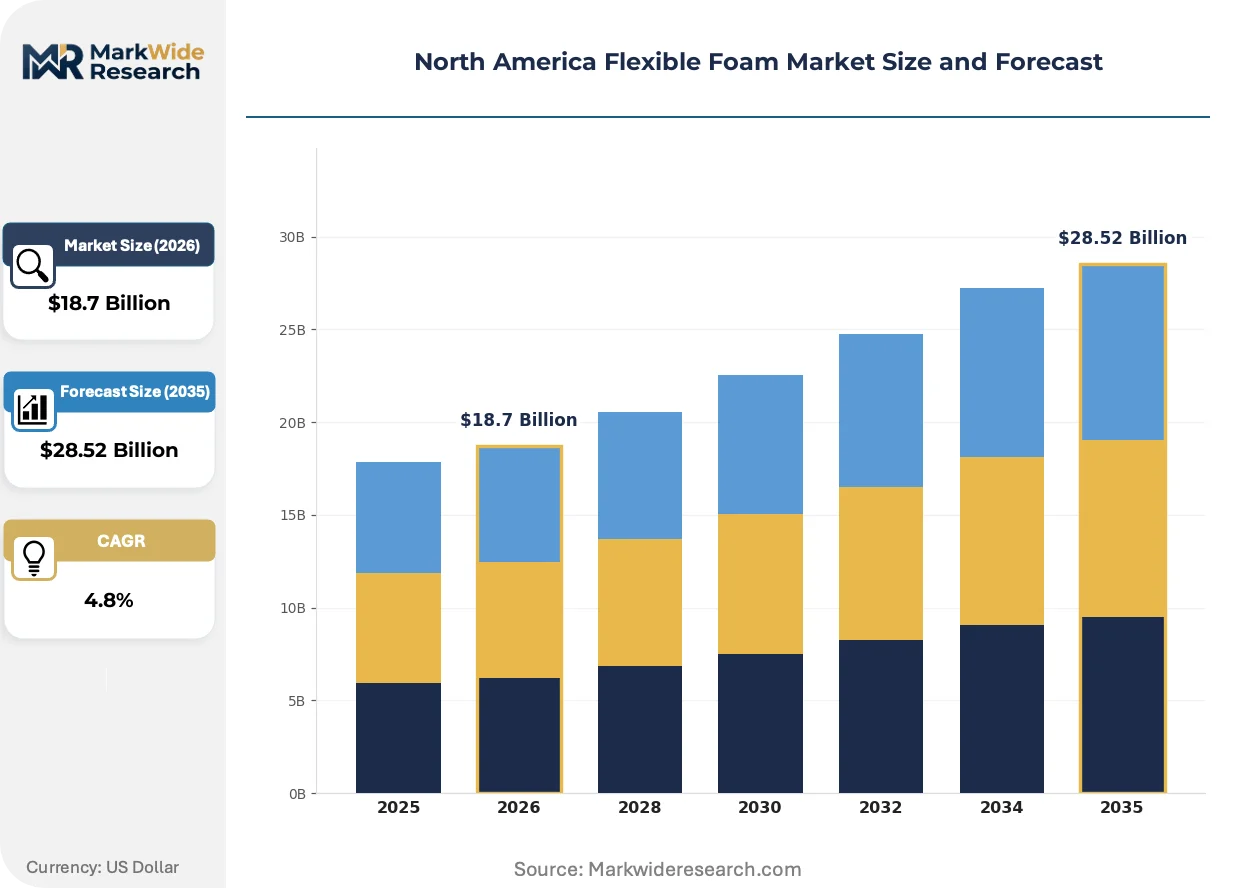
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Latex Foam, Memory Foam, Polyethylene Foam Application: Furniture, Automotive, Packaging, Bedding End User: Consumer Goods, Construction, Healthcare, Automotive Manufacturers Form: Flexible, Rigid, Composite, Laminated |
| Companies Covered | Covestro, BASF, Dow, VPC Group, Rogers Corporation, Huntsman International, Carpenter Co, FXI, Recticel, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Flexible Foam Market Emerging Trajectories
Digital process control systems are virtualizing quality assurance workflows across North American foam fabrication, compressing defect rates while enabling real-time density and resilience monitoring that was previously laboratory-bound.
Machine-vision cell-structure analysis is virtualizing manual inspection protocols that historically required destructive sampling. Tier-1 automotive seating suppliers in Michigan and Ontario are deploying these systems at line speed, eliminating batch-hold delays. The technology is compressing quality assurance cycle times from hours to seconds while generating datasets that feed back into blowing agent optimization.
The EPA's TSCA Title VI enforcement is tightening volatile organic compound thresholds for composite wood products, with spillover effects on foam adhesives and laminates used in upholstered furniture. Manufacturers serving California's mass-market retail channels are extending TB 117-2013 smolder-resistant formulations nationwide to preempt inventory fragmentation. Health Canada's parallel CHPSA standards are creating compliance complexity for cross-border producers, particularly in Quebec and Ontario distribution corridors.
Buyers in the bedding channel are consolidating supplier relationships around vertically integrated producers capable of delivering certified low-VOC slabs with chain-of-custody documentation. Retail purchasing teams at national mattress brands are compressing vendor panels from twelve to four qualified sources, favoring converters with in-house polyol blending and blowing agent certification. This concentration is most visible in the US Southeast, where regional distributors are losing shelf space to direct mill relationships.
North America Flexible Foam Market Segmentation
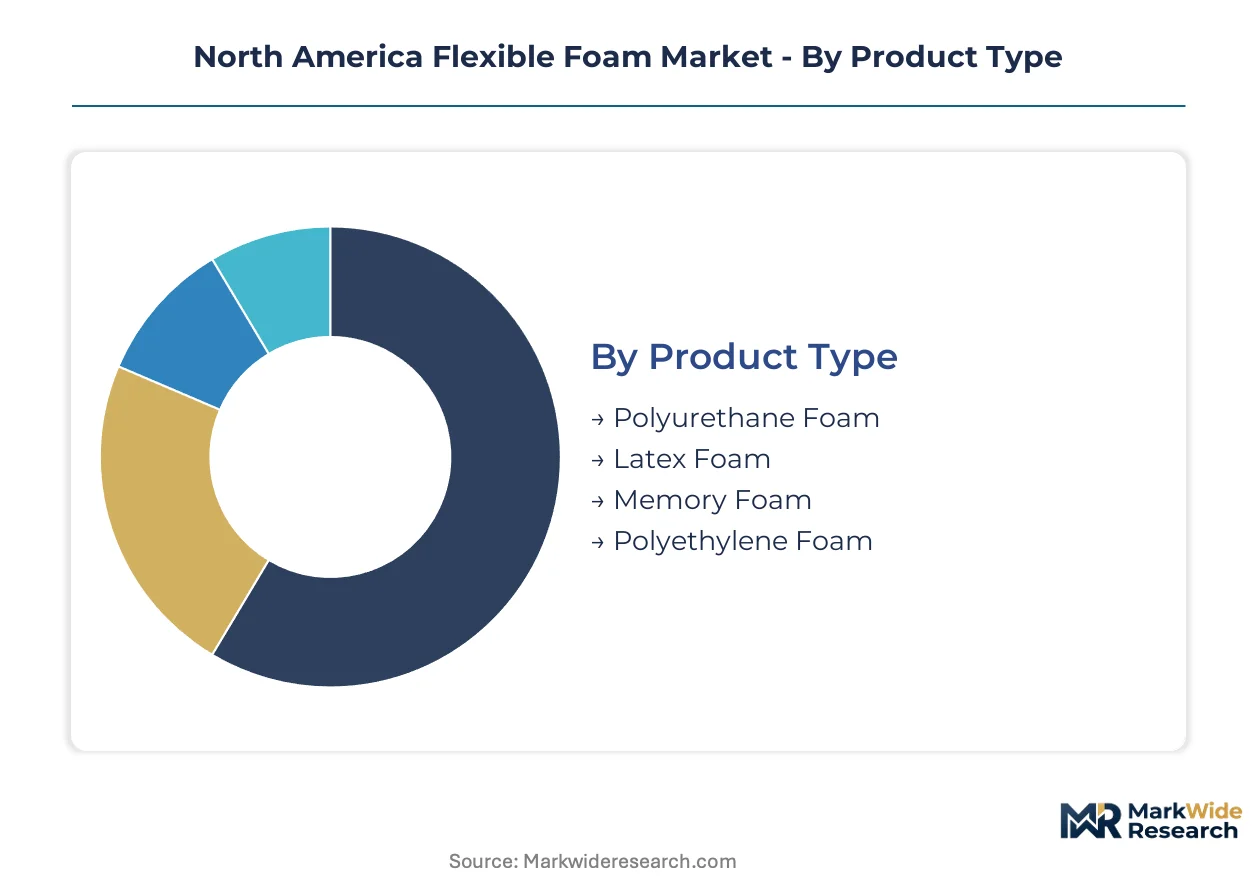
Segmentation in North American flexible foam production determines formulation chemistry, blowing agent selection, and certification requirements. Each category creates distinct margin profiles and technical service intensities that shape supplier-buyer relationships across automotive, bedding, and protective packaging channels.
Product Type:
After-sales service intensity varies sharply across foam chemistries, with polyurethane systems demanding ongoing technical support for blowing agent transitions while polyethylene formats require minimal field engineering.
- Polyurethane Foam:Open-cell structures produced from polyol-isocyanate reactions dominate automotive seating and furniture cushioning. Detroit and Toronto OEM programs specify certified low-VOC grades that comply with EPA TSCA Title VI thresholds, forcing converters to maintain formulation chemists for batch optimization.
- Memory Foam:Viscoelastic polyurethane variants with slow recovery characteristics command premium positioning in healthcare pressure-redistribution surfaces and luxury bedding. Long-term care facilities in Michigan and Ontario are specifying higher-density grades for patient positioning equipment, requiring suppliers to validate durability under clinical cleaning protocols.
- Latex Foam:Natural rubber-derived cellular structures retain share in eco-positioned consumer goods segments, though synthetic polyol economics limit expansion in price-sensitive furniture channels.
- Polyethylene Foam:Closed-cell structures deliver energy absorption for protective packaging applications. E-commerce fulfillment centers across the US Southeast are driving specification intensity for custom die-cut configurations with minimal technical service requirements.
By volume, polyurethane foam leads. By growth pace, memory foam is gaining share fastest in automotive and medical applications.
Application:
Application segmentation tracks directly to end-use durability requirements and regulatory exposure, with automotive and bedding facing the most stringent certification burdens.
- Automotive:Seating programs in Detroit, Toronto, and Querétaro absorb viscoelastic and conventional polyurethane grades for cushion and trim applications. Mexico's Querétaro cluster is localizing cut-and-sew fabrication capacity adjacent to OEM assembly plants, compressing logistics costs for Tier-1 suppliers.
- Bedding:Mattress and pillow production concentrates around certified low-VOC supply chains with chain-of-custody documentation. National retail brands are consolidating vendor panels from twelve to four qualified sources, favoring converters with in-house polyol blending capabilities.
- Furniture:Upholstered seating and cushioning applications span residential and commercial channels. California's TB 117-2013 smolder-resistant standard shapes nationwide formulation practices through de facto adoption by mass-market retailers.
- Packaging:Protective foam formats serve electronics, appliance, and industrial equipment shipping requirements. Fulfillment center automation is driving specification intensity for polyethylene foam with precise die-cut tolerances.
Automotive generates the highest per-unit value. Bedding shows the steepest supplier consolidation trajectory.
End User:
End user categories determine procurement sophistication, with automotive manufacturers and healthcare institutions imposing the most rigorous quality systems.
- Automotive Manufacturers:OEM seating programs specify density, resilience, and emissions certification with zero-defect quality protocols. Tier-1 suppliers in Michigan and Ontario are deploying machine-vision cell-structure analysis at line speed to eliminate batch-hold delays.
- Healthcare:Medical device OEMs and long-term care facilities specify pressure-redistribution surfaces with clinical durability validation. Higher-density viscoelastic grades are penetrating patient positioning equipment as facilities upgrade aging mattress inventories.
- Consumer Goods:Retail mattress brands and furniture chains drive consolidation toward vertically integrated foam producers. Direct mill relationships are displacing regional distributors in the US Southeast procurement landscape.
- Construction:Building and infrastructure applications utilize foam for insulation, sealant backing, and acoustic dampening. This channel faces less stringent VOC regulation than furniture or automotive segments.
Healthcare commands the highest specification intensity. Consumer goods is experiencing the fastest procurement consolidation.
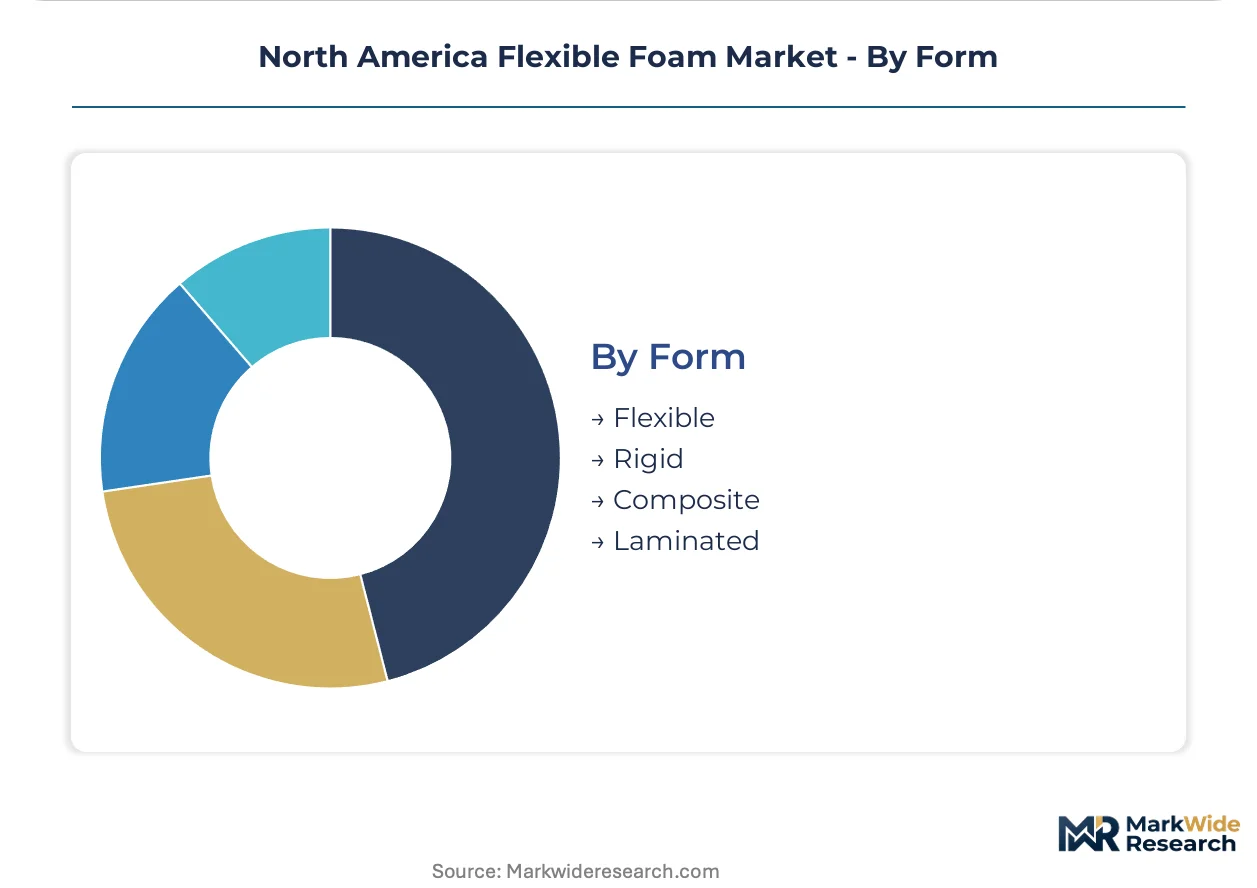
Form:
Form segmentation governs processing equipment requirements and downstream fabrication flexibility, with flexible formats dominating continuous slabstock production.
- Flexible:Open-cell structures produced via continuous slabstock or molded reaction injection processes serve seating, bedding, and cushioning applications. Water-blown system advancements are enabling performance parity with HFC-blown alternatives in automotive durability tests.
- Rigid:Closed-cell structures deliver thermal insulation and structural support in construction and appliance applications. This form requires distinct blowing agent chemistries and processing parameters from flexible foam production.
- Composite:Multi-material assemblies combine foam cores with fabric, film, or fiber reinforcements. Automotive headliners and interior trim panels utilize composite constructions for acoustic and aesthetic performance.
- Laminated:Bonded layer structures integrate foam substrates with adhesives to achieve combined property profiles. EPA TSCA Title VI spillover effects on composite wood products are extending to foam adhesives and laminates in upholstered furniture.
Flexible foam dominates production volume. Composite formats are climbing fastest in automotive interior applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA's TSCA Title VI enforcement anchors North American flexible foam regulation, with emission thresholds cascading through automotive seating and bedding supply chains. The region's production concentrates around Gulf Coast petrochemical corridors and automotive assembly clusters. Mexico's manufacturing localization is compressing lead times for Tier-1 suppliers.
United States
Detroit's automotive seating programs specify certified low-VOC viscoelastic grades for premium cushion applications. EPA's updated TSCA Title VI thresholds are forcing reformulation of conventional blowing agents across Michigan and Ohio fabrication centers. Covestro's Baytown polyol complex sustains backward integration into flexible foam systems for regional automotive supply.
Canada
Toronto-area OEM programs absorb higher volumes of memory foam grades for luxury seating configurations. Health Canada's CHPSA flammability standards diverge from California TB 117-2013, creating dual-certification costs for Ontario and Quebec converters. Machine-vision cell-structure analysis is eliminating batch-hold delays at Tier-1 suppliers in Windsor and Oshawa.
Mexico
Querétaro's automotive cluster is drawing foreign producers to localize cut-and-sew fabrication adjacent to OEM final assembly plants. Mexico's environmental regulator enforces NOM-085-SEMARNAT-2011 VOC limits that align with US thresholds for cross-border supply chains. Tier-1 suppliers are compressing logistics costs by positioning foam fabrication within 50 kilometers of assembly plants.
North America Flexible Foam Market Vendor Landscape
Capability concentration sits with integrated polyol producers; scale advantage sits with diversified chemical conglomerates. The market structures around three tiers: multinational resin suppliers with captive foam formulation, regional converters with specialized molding expertise, and commodity fabricators competing on throughput. Strategic moves center on water-blown system certification and geographic proximity to automotive assembly clusters.
Among integrated chemical suppliers, Covestro, Dow, and Huntsman International exemplify the capability-driven tier. Covestro anchors its position through Gulf Coast polyol production. Dow competes on polyethylene foam formulations for protective packaging channels. Huntsman International occupies a position defined by MDI supply relationships with Tier-1 converters in Michigan and Ontario.
| Leading Market Players |
|---|
| Covestro |
| BASF |
| Dow |
| VPC Group |
| Rogers Corporation |
| Huntsman International |
| Carpenter Co |
| FXI |
| Recticel |
| Others |
Supply Flow & Price Mechanics
Gulf Coast polyol overcapacity is compressing input costs for flexible foam converters while simultaneously eroding supplier pricing power in commodity-grade segments. This utilization dynamic rewards integrated producers with captive polyol supply while forcing toll converters toward volume-based contract structures to defend margin.
Pricing Analysis
Geographic price spreads between Michigan-Ontario automotive corridors and Mexico's Querétaro cluster reflect logistics premiums and cross-border certification burdens. Three-tier pricing structure across premium viscoelastic, standard polyurethane, and economy polyethylene levels stratifies by VOC certification grade and volume commitment scale. Pricing pressure stems from MDI-TDI input volatility and converter margin compression, with small-batch furniture producers exhibiting highest price sensitivity versus automotive OEMs locking in long-term offtake agreements.
Supply Chain Analysis
Export-control regimes on advanced surfactant catalysts limit technology transfer for water-blown system optimization between US and certain Asian manufacturing hubs. Supply concentrates around US Gulf Coast petrochemical corridors, Ontario chemical processing zones, and emerging Mexican fabrication clusters near Querétaro. Raw material dependencies center on MDI, TDI, and specialty polyols. Single-source vulnerability from hurricane-exposed Gulf Coast polyol production threatens continuity. Distribution runs through direct mill relationships displacing regional distributors in bedding and automotive channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive OEMs and national mattress brands, compressing vendor panels and demanding certified low-VOC supply chains with full documentation.
For Market Incumbents: Harden formulation certification capabilities to meet EPA TSCA Title VI and Health Canada CHPSA dual-compliance requirements without batch-hold delays. Deepen backward integration into polyol blending to offset MDI-TDI price volatility and defend margin position against integrated chemical suppliers. For New Entrants and Emerging Players: Pursue white-space opportunities in healthcare pressure-redistribution surfaces and water-blown automotive seating systems where formulation expertise scarcity limits incumbent response speed. Target long-term care facilities in Michigan and Ontario with clinical-validated viscoelastic grades as the most penetrable segment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across water-blown system conversion and machine-vision quality infrastructure, favoring scaled players over fragmented toll converters. Acquisition targets with in-house polyol blending and EPA-certified low-VOC capabilities offer strongest five-to-ten-year viability. Watch surfactant chemistry breakthroughs enabling water-blown performance parity as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Blending | Covestro's Baytown complex demonstrates margin defense against MDI-TDI volatility. |
| Water-Blown System Certification | Surfactant advances enable performance matching HFC-blown durability in automotive tests. |
| Machine-Vision Quality Deployment | Tier-1 suppliers in Windsor eliminate batch-hold delays through real-time cell-structure analysis. |
| Querétaro Proximity Manufacturing | Tier-1 suppliers compress logistics costs by positioning fabrication within 50 kilometers of OEM assembly. |
| Dual-Certification Compliance Investment | Converters serving US-Canada channels reduce inventory fragmentation through unified TB 117-2013 and CHPSA formulations. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive seating procurement directors, foam formulation chemists, Tier-1 supplier plant managers, and mattress brand supply chain executives. Secondary validation drew from EPA TSCA Title VI regulatory filings, Health Canada CHPSA standards documentation, customs trade data on polyol-isocyanate flows, and SEC disclosures from integrated chemical producers. Bottom-up volume modeling triangulated against top-down value estimates derived from production capacity and regional utilization rates.
Calibration against historical price elasticity and substitution patterns across automotive, bedding, and packaging channels anchored the analytical framework over the projection horizon. Segmentation dimensions spanned foam chemistry type, application durability tier, blowing agent technology, and regional production cluster. CAGRs were derived from slope analysis of normalized growth curves adjusted for regulatory phase-in schedules and automotive platform cycle timing. Forecast inputs incorporated MDI-TDI price correlation coefficients and surfactant technology maturity indices.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, e-commerce fulfillment center buildout rates, or construction spending would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology adoption curves. Material shifts in EPA TSCA Title VI implementation timelines or breakthrough water-blown performance validation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
Dielectric Fluid Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
Passive Fire Protection Materials Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Phase Change Thermal Interface Materials Market