
 France Foam Insulation Market | 2026-2036
France Foam Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
France Foam Insulation Market Foresight
Mineral wool is consolidating share in French fire-rated assemblies, yet polyurethane foam retains cost advantages in cold-storage and pitched-roof applications. Huntsman Corporation leverages its European polyol supply chain to serve French panel manufacturers. BASF SE anchors its position through system house partnerships with regional applicators. Recticel Group specializes in rigid board solutions for the renovation segment where Parisian contractors face strict facade-access constraints.
France foam insulation comprises synthetic or bio-based cellular plastics manufactured through blowing-agent expansion, with closed-cell polyurethane achieving thermal conductivity values near 0.022 W/m·K for demanding building envelopes. The material's primary purpose is reducing heat transfer in structures while managing moisture vapor diffusion. Spray foam leads in retrofit applications where irregular cavities complicate board installation, while board foam dominates new commercial construction for dimensional predictability. Polystyrene foam maintains volume in below-grade waterproofing assemblies due to compressive strength and moisture resistance.
France's RE2020 regulation and the EU F-Gas Regulation constrain hydrofluorocarbon blowing agents, pushing formulators toward hydro-olefin and water-blown alternatives. ANSM and the French Ministry of Ecological Transition enforce fire-reaction class requirements that differentiate product eligibility across occupancy types. Stakeholders must monitor pending revisions to the European Construction Products Regulation and assess bio-based feedstock scalability before committing capital to next-generation production lines.
Market Dynamics
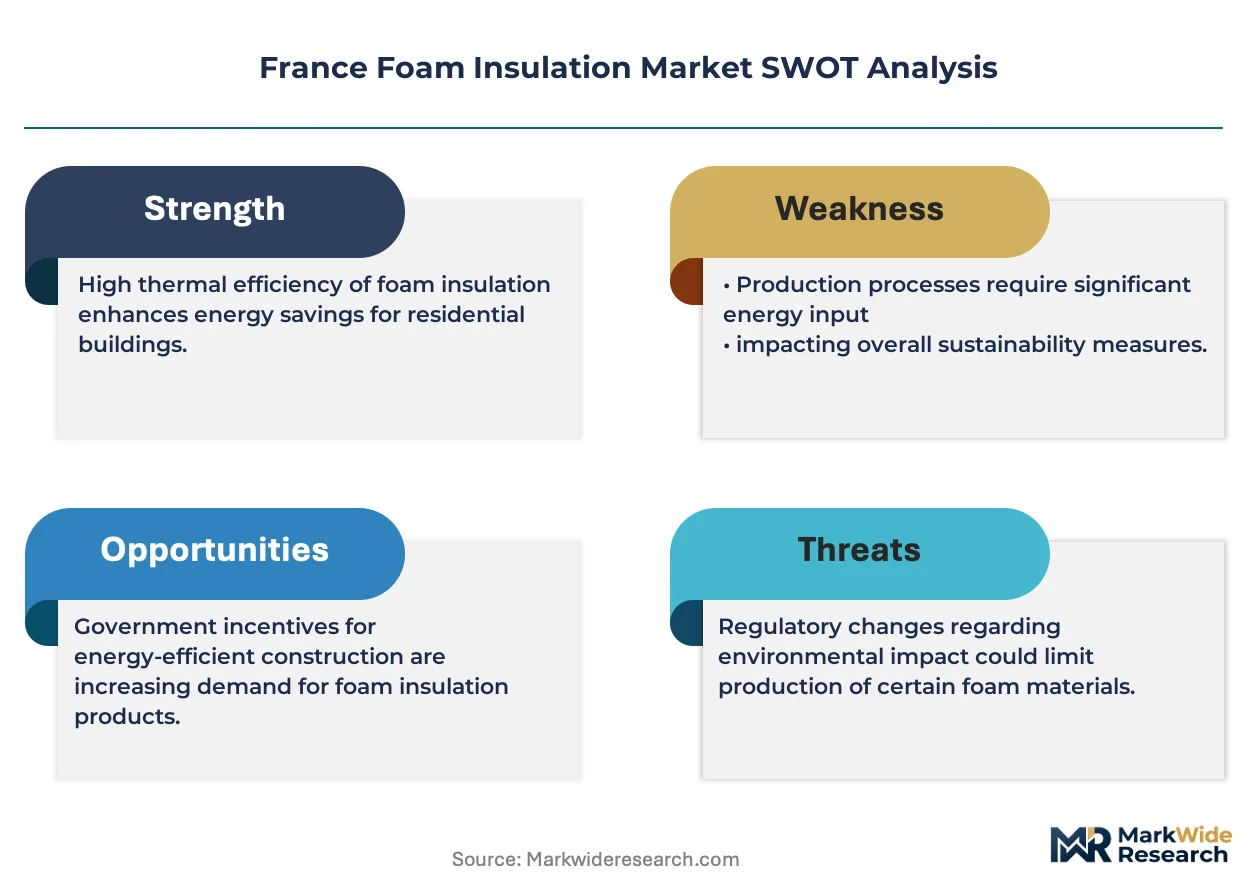
France's RE2020 environmental regulations are compressing thermal performance requirements for new construction, forcing formulators to abandon hydrofluorocarbon blowing agents before supply chains for hydro-olefin alternatives mature. This regulatory compression is reshaping competitive positioning among system houses and raw material suppliers.
Growth Catalysts
- RE2020 Thermal Mandates:New construction in Ile-de-France must meet stricter U-value thresholds, expanding addressable volume for high-performance closed-cell systems in residential envelopes.
- Paris Metropolitan Retrofit Surge:Aging Haussmann-era building stock drives spray foam demand where irregular masonry cavities resist board installation and facade access constraints dominate.
- Hydro-Olefin Transition:Fourth-generation blowing agents with GWP under 10 are unlocking regulatory compliance for polyurethane formulators serving cold-storage and refrigerated transport segments.
Market Restraints
- Polyol Supply Concentration:European polyol production clusters in Belgium and the Netherlands expose French system houses to cross-border logistics friction and input cost volatility.
- Mineral Wool Substitution:Fire-rated assemblies in high-rise residential and commercial towers increasingly specify non-combustible insulation, constraining polyurethane share in vertical envelope applications.
- F-Gas Phase-Down Timeline:The EU F-Gas Regulation's accelerated HFC quota reductions are compressing reformulation windows before next-generation catalyst systems achieve scale.
Strategic Opportunities
- Bio-Based Feedstock Integration:Castor-oil derived polyols and lignin-based systems offer pathways to reduce Scope 3 emissions for sustainability-mandated commercial developers in Lyon and Bordeaux.
- Prefabricated Panel Partnerships:Offsite construction growth creates captive demand for rigid board insulation in modular residential units manufactured in Rhone-Alpes industrial corridors.
- MaPrimeRenov Incentive Uptake:The national renovation subsidy scheme is expanding eligible measures to include deep energy retrofits, channeling homeowner capital toward high-performance envelope upgrades.
Industry Challenges
- Certified Applicator Shortage:Spray foam installation requires ANSM-recognized fire-reaction training and equipment certification, constraining crew availability during peak renovation seasons.
- Reformulation Capital Burden:Water-blown and hydro-olefin system development demands pilot-line investment and extended product qualification timelines before commercial rollout.
- Moisture Management Complexity:Building physics modeling for hybrid insulation assemblies requires specialized engineering capability that smaller regional contractors rarely maintain in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Foam Insulation Market |
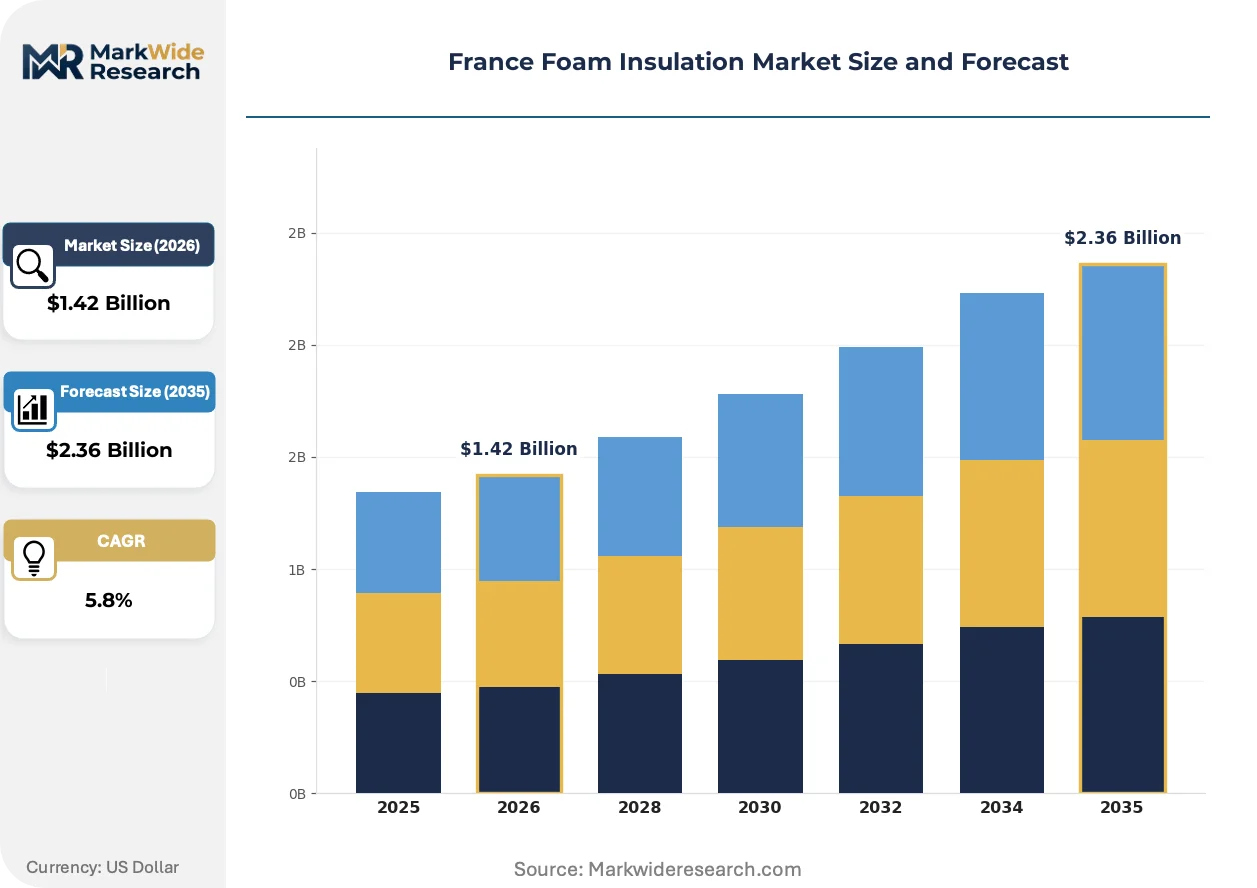
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Polystyrene Foam, Phenolic Foam, Polyisocyanurate Foam, Melamine Foam Form: Spray Foam, Board Foam, Loose Fill Foam, Injected Foam Application: Wall Insulation, Roof Insulation, Floor Insulation, HVAC Systems, Cold Storage End User Industry: Commercial Buildings, Residential Properties, Hospitality Sector, Transportation Facilities |
| Companies Covered | Kingspan Group, Huntsman Corporation, BASF SE, Armacell International S.A., Recticel Group, Saint-Gobain Group, Knauf Insulation, Owens Corning, Dow, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Foam Insulation Market Shifts & Advancements
Formulation chemistry and installation methodology are converging around low-global-warming-potential systems that satisfy both RE2020 thermal mandates and tightening fire-reaction classifications. Three developments are restructuring how value flows through the supply chain.
Hybrid water-hydro-olefin blowing agent systems are unifying thermal performance and environmental compliance in a single formulation platform. Large commercial envelope contractors in the Paris region are specifying these systems for deep retrofit projects where both U-value targets and carbon accounting requirements apply. The technology is compressing the competitive advantage window held by early HFO adopters while raising barriers for formulators still dependent on legacy HFC infrastructure.
ANSM and the French Ministry of Ecological Transition are tightening fire-reaction class requirements for multi-occupancy residential buildings above 28 meters. The regulation is forcing polyurethane suppliers to invest in intumescent coating partnerships or mineral wool hybrid systems for high-rise applications. Panel manufacturers serving the Grand Paris Express transit-oriented development corridor are responding by diversifying insulation specifications across occupancy types.
Building owners are consolidating envelope procurement under single-source performance contracts that bundle design, material supply, and installation quality assurance. General contractors on public-sector projects are ceding specification authority to energy service companies that guarantee thermal outcomes over multi-year horizons. This shift is most visible in the social housing sector where Ile-de-France Habitat and similar landlords are aggregating renovation programs at portfolio scale.
France Foam Insulation Market Segmentation
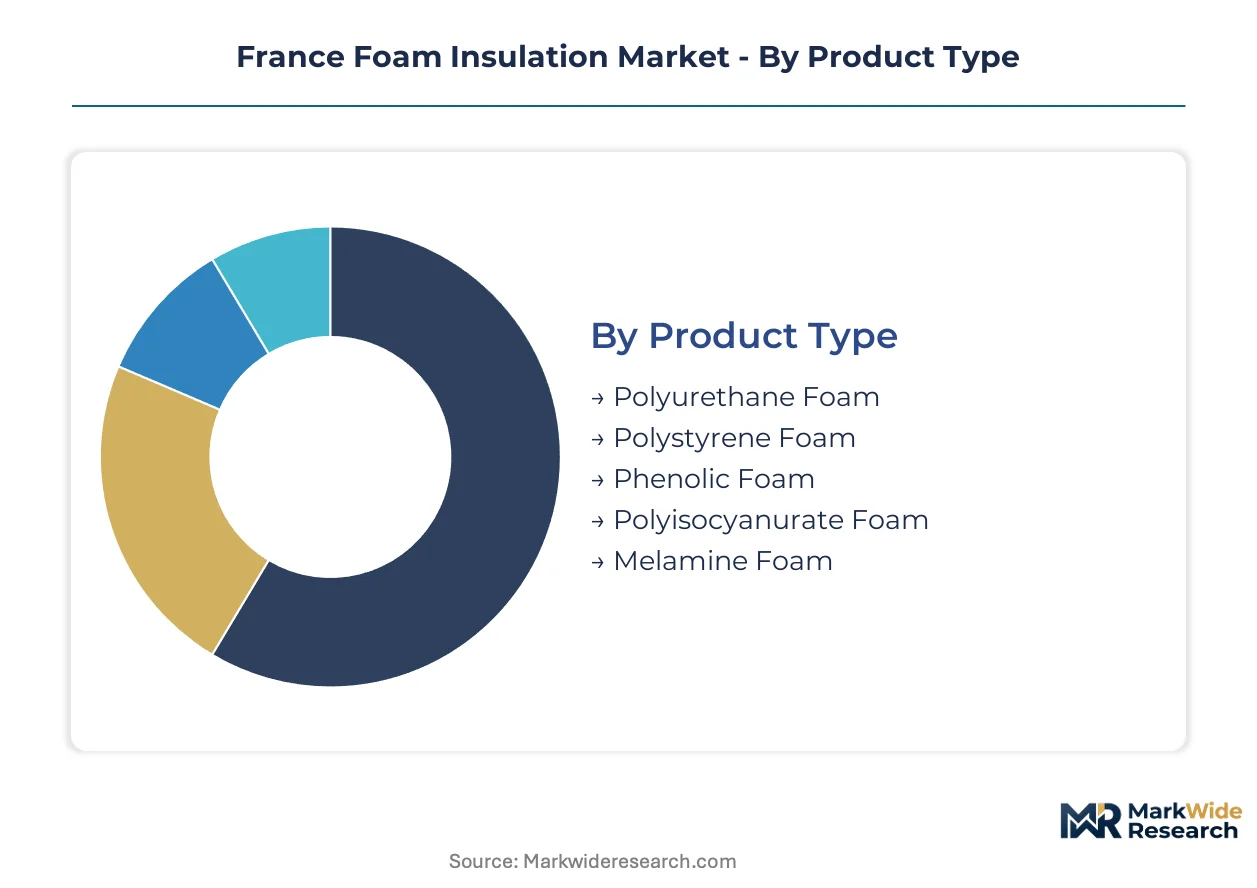
France's foam insulation market fragments across material chemistry, physical form, building application, and end-user verticals. Each dimension carries distinct regulatory exposure, installation capability requirements, and margin profiles that shape supplier positioning.
Product Type:
Buyers differentiate primarily by thermal conductivity requirements and fire-reaction classification needs, with RE2020 compliance timelines compressing specification windows.
- Polyurethane Foam:Closed-cell systems achieve thermal conductivity near 0.022 W/m·K through hydro-olefin blowing agents, making them indispensable for Parisian deep retrofits where irregular masonry cavities resist alternative materials. Demand concentrates in Ile-de-France commercial envelopes where ANSM fire-reaction training requirements constrain installer availability.
- Polystyrene Foam:Expanded and extruded variants deliver compressive strength above 200 kPa for below-grade waterproofing assemblies, with moisture resistance driving specification in Rhone-Alpes infrastructure projects. Volume sits with board formats for new construction where dimensional predictability outweighs thermal performance premiums.
- Phenolic Foam:Low-smoke emission characteristics serve hospital and transit infrastructure fire-rated assemblies, though limited French production capacity elevates landed costs versus polyurethane alternatives.
- Polyisocyanurate Foam:Higher service temperature tolerance positions the material in industrial process equipment and commercial roofing where thermal bridging penalties are severe.
- Melamine Foam:Open-cell acoustic absorption properties dominate media room and auditorium specifications, with lightweight handling reducing facade-access equipment requirements in dense urban renovation.
Volume sits with polyurethane systems; growth tilts toward phenolic and polyisocyanurate as fire-reaction classifications tighten in high-rise residential.
Form:
Installation methodology determines labor cost structure and project scheduling flexibility, with contractor capability gaps creating segment-specific supply constraints.
- Spray Foam:Two-component polyurethane systems expand to fill irregular cavities in Haussmann-era masonry, requiring ANSM-recognized applicator certification that limits crew availability during peak renovation seasons. Demand clusters in Paris metropolitan retrofits where facade access constraints eliminate board alternatives.
- Board Foam:Rigid panels enable dimensional precision in offsite modular construction manufactured in Rhone-Alpes industrial corridors, with Grand Paris Express transit-oriented developments specifying prefabricated envelope assemblies.
- Loose Fill Foam:Cellulose and fiberglass blends serve attic floor applications in rural residential stock where blown-in installation minimizes labor intensity.
- Injected Foam:Cavity wall systems penetrate existing masonry without facade demolition, capturing share in Bordeaux and Lyon heritage districts where exterior alteration restrictions apply.
Board formats dominate new construction volume; spray systems expand most quickly in the renovation segment as MaPrimeRenov subsidies deepen.
Application:
Building envelope position dictates moisture management complexity and regulatory scrutiny intensity, with thermal bridge penalties varying dramatically across assembly types.
- Wall Insulation:External thermal insulation composite systems face strict facade-access regulations in Paris, driving internal insulation alternatives where space penalties are acceptable. RE2020 U-value thresholds force high-performance material specification in Ile-de-France new construction.
- Roof Insulation:Pitched-roof applications favor spray foam for rafter-level continuity, while flat commercial roofing specifies rigid boards for membrane compatibility. Cold-storage facilities demand vapor-tight assemblies where polyurethane dominates.
- Floor Insulation:Below-slab and screed applications prioritize compressive strength, with polystyrene boards specified for ground-contact moisture resistance.
- HVAC Systems:Ductwork insulation requires fire-reaction class M1 certification, with phenolic and melamine foams capturing specification in hospital and airport infrastructure.
- Cold Storage:Refrigerated warehouses and transport containers demand thermal conductivity below 0.025 W/m·K, locking in polyurethane and polyisocyanurate systems despite premium pricing.
Wall assemblies generate the largest absolute volume; cold storage and HVAC applications gain share fastest as food logistics and healthcare infrastructure expand.
End User Industry:
Procurement sophistication and sustainability mandate intensity vary sharply across verticals, with public-sector aggregation creating scale advantages for qualified suppliers.
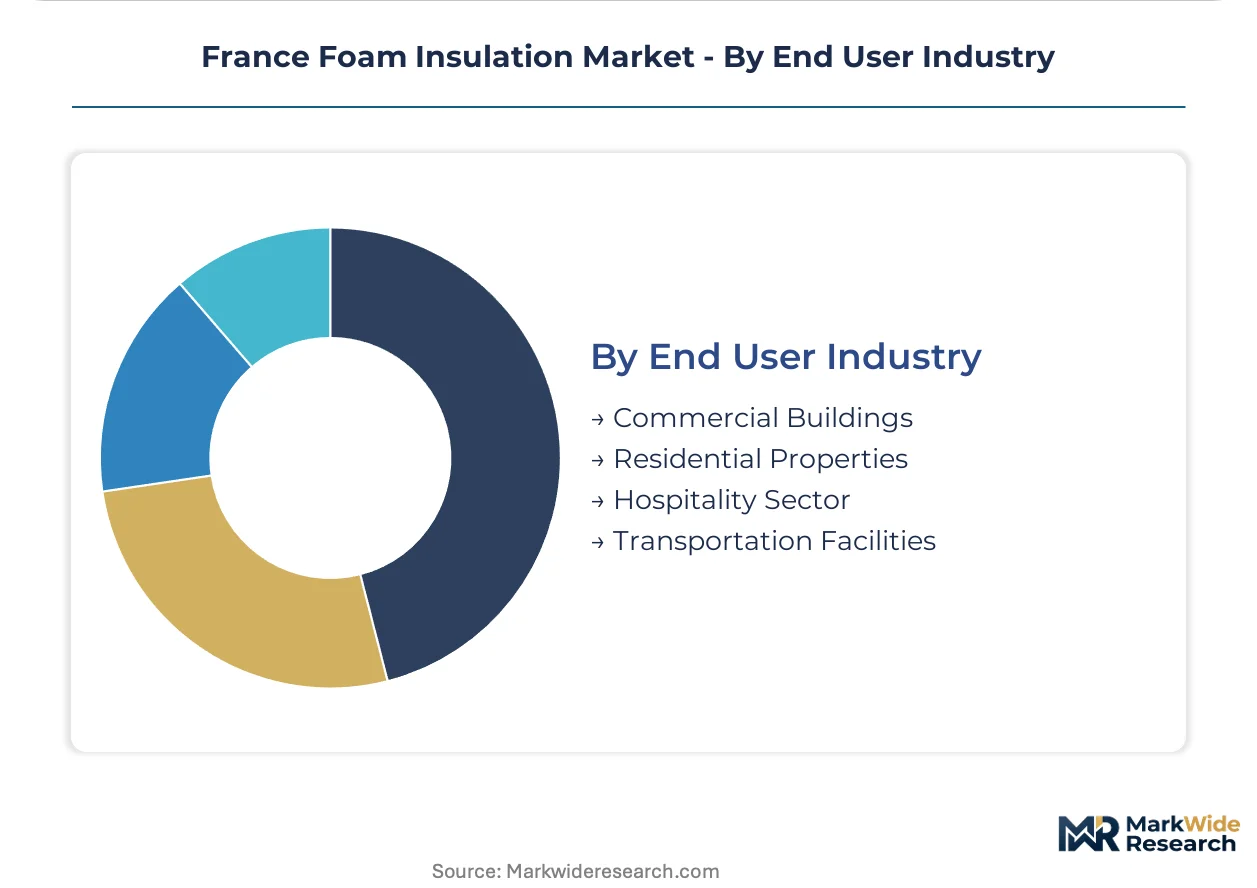
- Commercial Buildings:Office and retail developers face RE2020 thermal performance mandates and CSRD carbon disclosure requirements, consolidating envelope procurement under energy performance contracting. Social housing landlords like Ile-de-France Habitat aggregate renovation programs at portfolio scale.
- Residential Properties:Single-family and multi-family homeowners access MaPrimeRenov subsidies for deep energy retrofits, with spray foam capturing irregular cavity applications in aging Parisian stock.
- Hospitality Sector:Hotel operators prioritize acoustic separation and fire safety, specifying hybrid insulation assemblies that combine thermal and sound attenuation performance.
- Transportation Facilities:Grand Paris Express stations and airport terminals demand fire-reaction class A2 specifications, constraining polyurethane share and elevating mineral wool hybrids in public procurement.
Commercial buildings anchor current volume; residential renovation climbs the steepest trajectory as subsidy schemes widen eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France concentrates over one-third of French foam insulation demand, driven by Paris metropolitan retrofit intensity and RE2020 compliance deadlines for new construction. Regional variation reflects building stock age, industrial density, and subsidy accessibility.
Île-de-France
Haussmann-era masonry retrofits and Grand Paris Express transit-oriented developments drive spray foam and rigid board demand. ANSM fire-reaction training requirements constrain certified applicator availability during peak seasons. Saint-Ouen and Aubervilliers industrial zones host panel manufacturing clusters serving the capital's envelope contractors.
Auvergne-Rhône-Alpes
Prefabricated modular construction growth in Lyon and Grenoble creates captive demand for rigid board insulation in offsite residential units. MaPrimeRenov subsidy uptake in Rhône-Alpes exceeds national averages for deep energy retrofits. Villeurbanne and Vénissieux industrial corridors concentrate system house distribution hubs.
Provence-Alpes-Côte d'Azur
Tourism sector hospitality renovations in Nice and Marseille prioritize acoustic and thermal performance for premium positioning. RE2020 thermal mandates apply to coastal new construction despite milder climate zones. Aix-en-Provence contractors specialize in heritage-compatible internal insulation for protected façades.
Hauts-de-France
Aging industrial and social housing stock in Lille and Roubaix drives renovation volume for cost-sensitive polyurethane systems. Cold-storage logistics expansion near Calais and Dunkirk locks in high-performance foam specifications for refrigerated warehouses. Regional training centers address certified applicator shortages.
Nouvelle-Aquitaine
Bordeaux metropolitan growth and wine industry cold-chain infrastructure sustain demand across residential and commercial segments. Bio-based feedstock research clusters near Pau explore castor-oil polyol scalability. Arcachon Basin contractors navigate strict exterior alteration restrictions in heritage districts.
France Foam Insulation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with system houses controlling specification authority in spray-applied polyurethane while board manufacturers compete on dimensional precision and logistics reliability. The supplier base exhibits moderate concentration, with European multinationals anchoring raw material supply and regional applicators capturing installation value. Three archetypes dominate: integrated chemical producers supplying polyol and isocyanate feedstocks; system houses formulating finished foam products; and specialized board fabricators serving prefabrication and modular construction. Competitive moves center on hydro-olefin blowing agent reformulation partnerships and prefabricated panel supply agreements with offsite constructors.
Among integrated chemical producers, Huntsman Corporation and BASF SE exemplify the feedstock-to-system supply chain archetype, leveraging European polyol manufacturing clusters to serve French formulators. Recticel Group occupies a specialist position in rigid board solutions, particularly where renovation contractors face Parisian façade-access constraints. These three entities represent distinct competitive vectors: upstream chemical integration, formulation system expertise, and application-specific product development.
| Leading Market Players |
|---|
| Kingspan Group |
| Huntsman Corporation |
| BASF SE |
| Armacell International S.A. |
| Recticel Group |
| Saint-Gobain Group |
| Knauf Insulation |
| Owens Corning |
| Dow |
| Others |
Supply & Pricing Matrix
Hydro-olefin blowing agent costs cascade through polyurethane system houses into three distinct pricing tiers serving Parisian deep-retrofit contractors, Rhone-Alpes modular manufacturers, and cost-sensitive social housing aggregators. ANSM fire-reaction certification premiums separate certified applicator networks from uncertified competitors, compressing margins for formulators caught between raw material volatility and fixed-price public procurement contracts.
Pricing Analysis
Volume concentrates in standard-grade board formats for new construction, while margins concentrate in certified spray systems for irregular-cavity retrofits. Price differentiation hinges on ANSM fire-reaction class and hydro-olefin blowing agent content, with M1-certified systems commanding substantial premiums over uncertified alternatives. Cost compression in water-blown formulations is intensifying because European polyol supply clusters expose French formulators to cross-border logistics friction. Social housing aggregators exhibit highest price sensitivity; cold-storage operators show least sensitivity due to thermal performance lock-in.
Supply Chain Analysis
Certified applicator shortages in Belgium and the Netherlands constrain polyol formulation capacity serving French system houses. Raw material supply draws from German isocyanate production, Dutch polyol clusters, and Italian catalyst specialists. Single-source vulnerability sits with hydro-olefin blowing agent patents held by limited chemical producers. Distribution runs through regional system houses to certified installation crews, bypassing traditional merchant distribution for spray-applied segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race. Players are pursuing backward control over polyol supply to secure reformulation timelines ahead of F-Gas quota reductions.
For Market Incumbents:Cement specification authority by acquiring ANSM-recognized training centers and expanding captive applicator networks in Ile-de-France. Mineral wool substitution in high-rise fire-rated assemblies threatens polyurethane share; defend through intumescent coating partnerships or hybrid system development. Priority lever: lock in hydro-olefin supply agreements before quota compression accelerates.
For New Entrants and Emerging Players:Heritage district contractors in Bordeaux and Lyon face strict exterior alteration restrictions that injected foam systems address without facade demolition. White space sits with bio-based polyol formulations for sustainability-mandated commercial developers in secondary cities. Go-to-market angle: castor-oil derived systems with Scope 3 emissions documentation for CSRD-compliant procurement.
For Investors and Strategic Acquirers:Hydro-olefin patent cliff expiration is the leading indicator that formulation chemistry competition will intensify and margin structures will compress. Long-term viability favors vertically integrated players controlling both feedstock supply and certified installation networks. Target acquisition profile: regional system houses with ANSM training infrastructure and established Grand Paris Express contractor relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Supply | Secures reformulation feedstock ahead of F-Gas quota reductions. |
| ANSM Certification Program Expansion | Captures scarce applicator capacity in peak Ile-de-France renovation seasons. |
| Bio-Based Feedstock Partnership | Addresses CSRD carbon disclosure requirements for Lyon and Bordeaux developers. |
| Prefabricated Panel Supply Agreement | Locks in rigid board volume from Rhone-Alpes modular construction growth. |
| Intumescent Coating Technology Licensing | Enables high-rise fire-rated assembly compliance without mineral wool substitution. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with polyurethane system house technical directors, ANSM-certified applicator network managers, social housing procurement leads, and commercial envelope contractors. Bottom-up volume estimates triangulated against top-down construction activity indices from the French Ministry of Ecological Transition and RE2020 compliance tracking databases.
Granularity-level modeling distinguished hydro-olefin from water-blown formulation chemistry, spray versus board installation methodology, and Ile-de-France versus secondary regional demand clusters. CAGRs derived from segment-level volume trajectories calibrated to RE2020 implementation timelines and MaPrimeRenov subsidy uptake curves. Industry-specific forecast inputs incorporated ANSM fire-reaction class revision schedules and European polyol production capacity announcements.
Revisions become necessary when RE2020 thermal mandate enforcement intensity shifts, F-Gas quota allocations change, or hydro-olefin supply concentration breaks. Forecasts reflect assumptions about certified applicator training pipeline throughput and bio-based feedstock cost parity timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Multi-Layer Cryogenic Insulation Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Radiation Shielding Materials Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Active Insulation Market
Insulation Materials
OEM Insulation Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Thin Insulation Market
Insulation Materials
US Industrial Insulation Market
Insulation Materials
Global Extruded Polypropylene Foam Market