
 High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market | 2026-2036
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market Size, Share, and Industry Trends Forecast 2026-2036
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market Insights
Germany's Ruhr industrial cluster is fragmenting as domestic demand for high-temperature testing spreads across multiple application centers. ZwickRoell leverages its established presence in European materials testing to sustain service density in petrochemical corridors. MTS Systems anchors North American demand through specialized creep rupture platforms for aerospace propulsion research. Instron competes on multi-axis fatigue testing configurations that appeal to power generation OEMs seeking consolidated qualification workflows.
High-temperature corrosion and creep testing equipment subjects metallic and ceramic specimens to sustained thermal-mechanical loading at temperatures typically exceeding 600°C to measure deformation rates, rupture life, and oxidation kinetics under simulated process conditions. Creep rupture testers dominate capital allocation among equipment types because these units command extended replacement cycles and carry higher service attach rates. Superalloys represent the fastest-growing material tested category, driven by aerospace manufacturing demand for single-crystal turbine blade qualification. Research laboratories increasingly specify thermogravimetric analysis systems for precise oxidation rate measurement in alloy development programs.
Germany's KBA and the EU's REACH framework impose material traceability requirements that elevate testing documentation standards for equipment sold into European process industries. The US FAA and EPA jointly influence demand through airworthiness directives and emissions compliance pathways that mandate validated creep data for turbine hot-section components. Stakeholders must monitor how China's SAMR integrates GB standards with international accreditation protocols, as this alignment determines market access friction for imported testing platforms.
Market Dynamics
China's MIIT is tightening GB standards for superalloy testing in turbine applications, forcing equipment manufacturers to recalibrate thermal-mechanical loading protocols and documentation systems for export qualification.
Growth Catalysts
- Stricter operational safety mandates:Power generation utilities across Asia are expanding materials qualification programs. This institutional demand validates high-temperature testing infrastructure investments.
- Superalloy development pipelines:Aerospace manufacturing demand for single-crystal turbine blade qualification accelerates specimen throughput requirements. Testing laboratories are scaling creep rupture capacity accordingly.
- Ruhr industrial cluster concentration:Petrochemical integrators in Germany maintain centralized metallurgical laboratories. This geographic density sustains premium equipment attach rates and service contracts.
Market Restraints
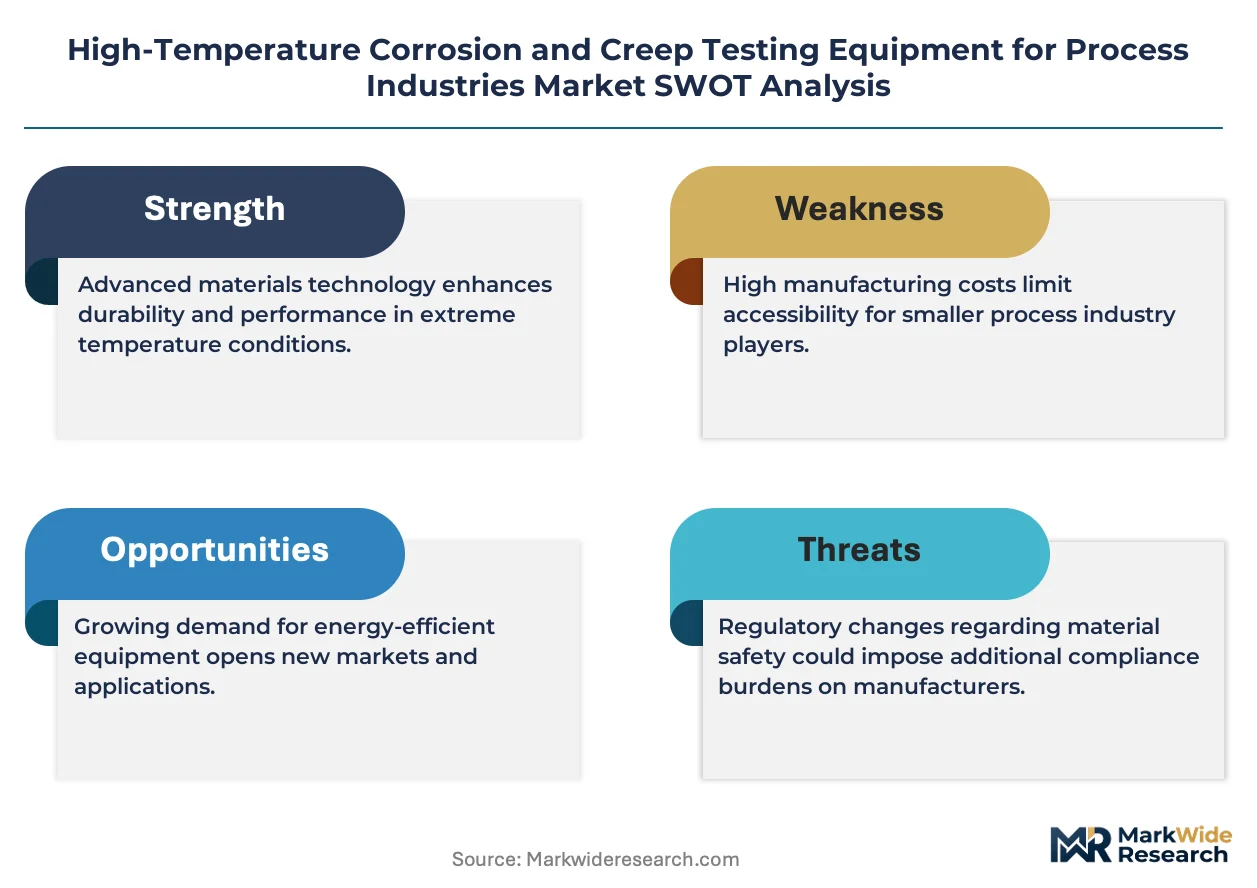
- Extended replacement cycles:Creep rupture testers command capital allocation but depreciate slowly. This elongates revenue recognition windows for original equipment suppliers.
- Input cost volatility:High-purity heating elements and platinum-rhodium thermocouples face supply concentration from South African mining operations. Price swings compress margin predictability.
- Regulatory friction:China's SAMR integration of GB standards with international accreditation protocols remains incomplete. This alignment gap creates market access friction for imported testing platforms.
Strategic Opportunities
- Research laboratory specification:Thermogravimetric analysis systems for precise oxidation rate measurement represent underpenetrated demand in alloy development programs. Equipment suppliers can deepen application engineering support.
- Multi-axis fatigue consolidation:Power generation OEMs seek consolidated qualification workflows. Configurations integrating creep and corrosion testing reduce footprint and capital duplication.
- EU Green Deal alignment:Carbon border adjustment mechanisms will require validated materials data for imported process equipment. European testing documentation standards position local laboratories for expanded service scope.
Industry Challenges
- Metallurgical expertise scarcity:Interpretation of creep deformation curves and oxidation kinetics requires specialized training. Equipment vendors struggle to staff field service organizations with qualified engineers.
- Certification timeline compression:FAA airworthiness directives and EPA emissions compliance pathways mandate validated creep data. Testing laboratories face backlog pressure on turbine hot-section component qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market |
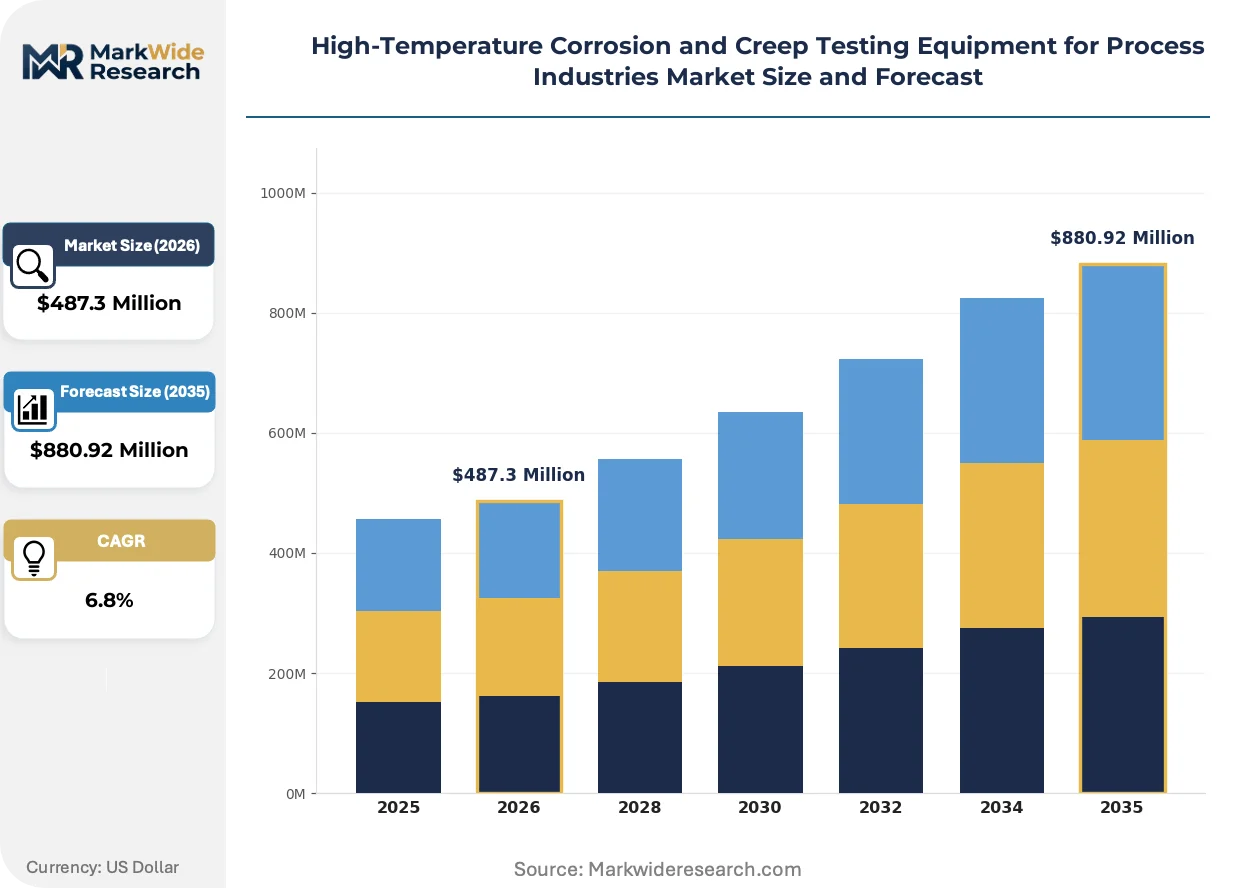
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Oxidation Testers, Creep Rupture Testers, Thermal Cycle Testers, Stress Corrosion Crack Testers, Fatigue Testers Material Tested: Superalloys, Stainless Steel, Refractory Metals, Ceramics, Titanium Alloys Application Industry: Petrochemical Processing, Power Generation, Aerospace Manufacturing, Metallurgical Plants, Research Laboratories Testing Technology: Thermogravimetric Analysis, Mechanical Strain, High-Temperature Microscopy, Electron Microscopy, Laser Dilatometry |
| Companies Covered | ZwickRoell, MTS Systems, Instron, AET Technologies, Ibertest, MCS Mechatronic Systems, Bi Veritas Group, Jinan Beacon Automation Equipment, TA Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market Trends and Innovations
Digital twin architectures are virtualizing thermal-mechanical test protocols before physical specimen loading. This simulation-first approach compresses development cycles and reduces material waste in qualification programs.
Digital image correlation systems are virtualizing strain measurement in creep rupture testing. Aerospace propulsion research facilities are adopting these non-contact platforms to capture full-field deformation data. The technology is virtualizing traditional extensometer-based workflows and enabling higher-temperature testing where mechanical contact fails.
REACH framework material traceability requirements are elevating testing documentation standards across European process industries. Germany's KBA enforces chain-of-custody protocols that extend from specimen preparation through data archival. Equipment sold into this jurisdiction must embed automated audit trails and tamper-evident data logging.
Consolidated qualification workflows are displacing discrete single-function testing contracts. Power generation OEMs now specify integrated platforms combining creep rupture, thermogravimetric analysis, and fatigue cycling. This bundling preference is most visible in Germany's Ruhr industrial cluster, where petrochemical integrators negotiate enterprise-level service agreements spanning multiple facility locations.
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market Segmentation
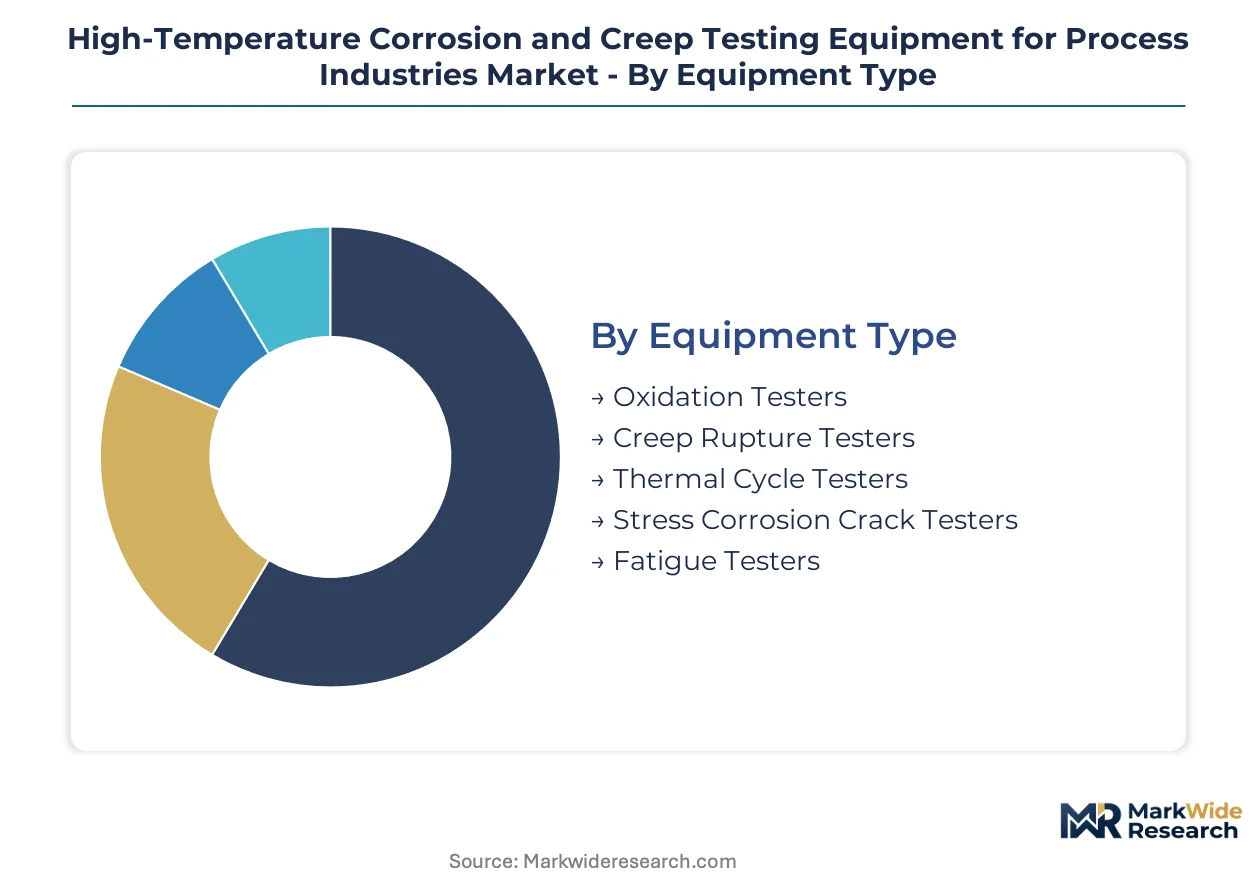
Equipment configuration choices in this market cascade through qualification timelines, capital depreciation schedules, and regulatory documentation burdens. Buyers segment procurement decisions by thermal loading capacity, specimen throughput requirements, and integration with existing laboratory information management systems.
Equipment Type:
Capital allocation intensity varies dramatically across equipment categories, with replacement cycles and service attach rates determining vendor profitability profiles.
- Creep Rupture Testers:These units apply sustained tensile loads at elevated temperatures to measure time-dependent deformation and rupture life. Power generation utilities in China deploy these platforms for superalloy qualification under MIIT-mandated GB standard protocols. Extended replacement cycles compress revenue recognition windows for original equipment suppliers.
- Oxidation Testers:Systems subject specimens to controlled high-temperature atmospheric exposure to quantify mass change and oxide scale formation kinetics. Research laboratories across Germany's Ruhr cluster specify thermogravimetric configurations for alloy development programs. Precision oxidation rate measurement commands premium pricing in European procurement.
- Thermal Cycle Testers:Platforms simulate rapid temperature transients to assess thermal fatigue resistance in turbine components.
- Stress Corrosion Crack Testers:Integrated systems combine mechanical loading with corrosive environments to evaluate crack propagation thresholds.
- Fatigue Testers:Configurations subject materials to cyclic loading at temperature to determine endurance limits under combined thermal-mechanical stress.
Creep rupture testers hold installed capacity. Oxidation testers are rotating up the share rankings.
Material Tested:
Specimen chemistry dictates heating element specifications, atmosphere control requirements, and data interpretation complexity for testing service providers.
- Superalloys:Nickel-based and cobalt-based alloys engineered for turbine hot-section applications demand single-crystal qualification protocols. Aerospace manufacturing facilities in the US require validated creep data under FAA airworthiness directives. Specimen throughput requirements are accelerating laboratory capacity expansion.
- Stainless Steel:Austenitic and ferritic grades used in petrochemical processing equipment face sulfidation and carburization exposure. German petrochemical integrators specify oxidation testing for materials traceability under KBA-enforced REACH documentation standards. Corrosion kinetics interpretation requires specialized metallurgical expertise.
- Refractory Metals:Tungsten, molybdenum, and niobium alloys serve ultra-high-temperature applications beyond conventional superalloy limits.
- Ceramics:Silicon carbide and alumina-based materials require non-contact strain measurement due to brittle failure modes.
- Titanium Alloys:Alpha-beta and near-alpha formulations for intermediate-temperature aerospace structures face oxidation embrittlement assessment.
Superalloys command qualification backlog priority. Ceramics are gaining share fastest in propulsion research contracts.
Application Industry:
End-use sector procurement patterns diverge by validation urgency, regulatory enforcement intensity, and in-house versus outsourced testing preferences.
- Power Generation:Utilities operate continuous creep monitoring programs for steam turbine and gas turbine hot-section components. Asian power producers are expanding materials qualification infrastructure under stricter operational safety mandates. Testing documentation supports asset life extension decisions.
- Petrochemical Processing:Refinery and cracker operators require corrosion rate data for furnace tube and reactor vessel materials selection. Germany's Ruhr industrial cluster sustains centralized metallurgical laboratory demand. Enterprise service agreements span multiple facility locations.
- Aerospace Manufacturing:Engine OEMs and Tier 1 suppliers validate single-crystal turbine blade castings through multi-axis fatigue and creep rupture protocols.
- Metallurgical Plants:Primary producers verify heat treatment response and quality consistency in high-temperature alloy production.
- Research Laboratories:Academic and government facilities advance alloy development through thermogravimetric analysis and high-temperature microscopy platforms.
Power generation maintains qualification volume leadership. Research laboratories are climbing the fastest on digital twin integration.
Testing Technology:
Measurement modality selection determines data resolution, specimen preparation requirements, and integration with simulation workflows.
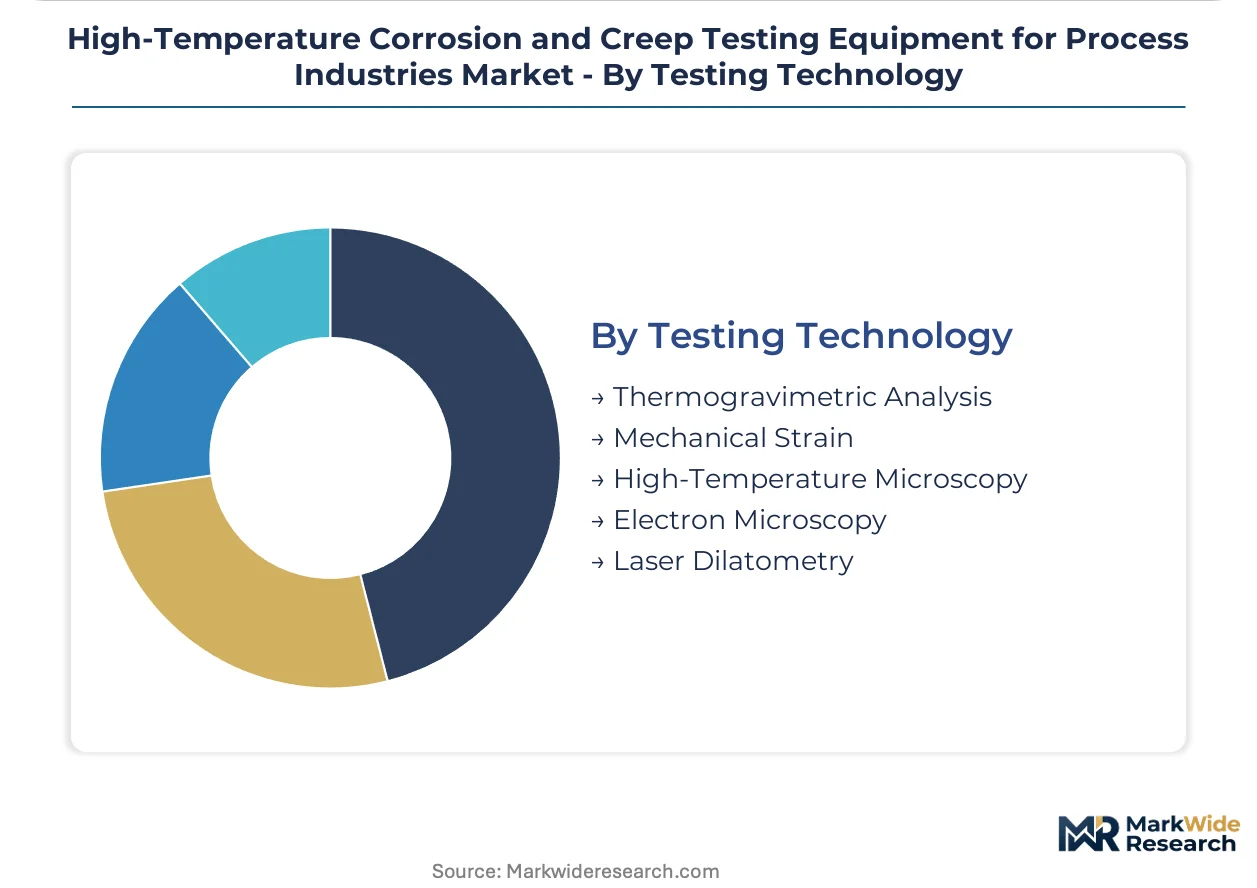
- Thermogravimetric Analysis:Continuous mass measurement during controlled thermal exposure enables precise oxidation rate quantification. European alloy development programs specify these systems under REACH framework traceability requirements. Automated audit trails and tamper-evident data logging are mandatory for equipment sold into this jurisdiction.
- Mechanical Strain:Extensometer and digital image correlation systems capture deformation under load for creep and fatigue characterization. Aerospace propulsion research facilities in the US adopt non-contact platforms for full-field strain mapping. The technology virtualizes traditional contact-based workflows.
- High-Temperature Microscopy:In-situ optical and scanning electron systems observe microstructural evolution during thermal exposure.
- Electron Microscopy:Post-test fractography and microanalysis identify failure mechanisms and degradation modes.
- Laser Dilatometry:Non-contact thermal expansion measurement supports phase transformation and residual stress analysis.
Mechanical strain platforms hold installed base dominance. Thermogravimetric analysis is expanding most quickly on Green Deal documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through tightened GB standards for superalloy testing in turbine applications. Equipment manufacturers must recalibrate thermal-mechanical loading protocols for export qualification. This regulatory pressure cascades through procurement decisions across Asia-Pacific utilities.
China
Power generation utilities in Jiangsu and Guangdong provinces are expanding materials qualification infrastructure under stricter operational safety mandates. MIIT's GB standard revisions for superalloy testing force recalibration of thermal-mechanical loading protocols. Shanghai and Beijing host the largest concentration of testing service laboratories serving aerospace manufacturing demand.
Germany
Petrochemical integrators in the Ruhr industrial cluster sustain centralized metallurgical laboratory demand for high-temperature corrosion testing. KBA-enforced REACH documentation standards elevate chain-of-custody requirements from specimen preparation through data archival. North Rhine-Westphalia's enterprise service agreements span multiple facility locations across the industrial corridor.
United States
Aerospace propulsion research facilities adopt non-contact digital image correlation platforms for full-field deformation data capture. FAA airworthiness directives and EPA emissions compliance pathways mandate validated creep data for turbine hot-section components. Greater Boston and Los Angeles metropolitan areas concentrate the highest specimen throughput for single-crystal turbine blade qualification.
Japan
Utilities and heavy industrial manufacturers operate continuous creep monitoring programs for steam turbine and gas turbine hot-section components. METI guidance on operational safety standards drives materials qualification infrastructure investments. The Chubu region around Nagoya hosts the densest concentration of testing laboratories serving automotive and aerospace supply chains.
India
Central Electricity Authority mandates are accelerating materials qualification program expansion among thermal power producers. BIS standards alignment with international accreditation protocols remains incomplete, creating market access friction for imported testing platforms. Maharashtra and Gujarat industrial corridors are establishing centralized metallurgical laboratories to serve petrochemical processing demand.
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market Competitive Landscape
Full-spectrum systems integrators and specialized testing technology developers split the market between consolidated qualification workflows and discrete function excellence. European and North American incumbents hold established positions in creep rupture and multi-axis fatigue platforms. Three strategic archetypes dominate: integrated materials testing conglomerates, precision measurement specialists, and regional fabrication houses serving price-sensitive procurement. Competitive moves concentrate on application engineering deepening and geographic service density expansion.
Among German-based testing equipment specialists, ZwickRoell occupies a position exemplifying the European full-spectrum archetype through its established presence in materials testing corridors. MTS Systems represents the North American precision measurement tier, anchoring demand through specialized platforms for aerospace propulsion research. Instron sits within the integrated systems tier, competing on configurations that appeal to power generation OEMs seeking consolidated qualification workflows. These three companies represent the competitive anchors around which regional fabrication houses and emerging specialists organize their market positioning.
| Leading Market Players |
|---|
| ZwickRoell |
| MTS Systems |
| Instron |
| AET Technologies |
| Ibertest |
| MCS Mechatronic Systems |
| Bi Veritas Group |
| Jinan Beacon Automation Equipment |
| TA Instruments |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp petrochemical corridor's freight cost dynamics amplify price spreads between European and Asian testing equipment markets, concentrating margin pressure on suppliers dependent on South African platinum-rhodium thermocouple shipments while enabling premium positioning for vendors with captive heating element supply.
Pricing Analysis
Geographic price spreads between German and Chinese procurement markets exceed 30 percent for equivalent creep rupture tester configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Price erosion runs through economy-tier equipment as regional fabrication houses in India and Southeast Asia compete on capital cost. Research laboratories exhibit lowest price sensitivity due to documentation compliance requirements, while independent testing service providers face acute margin compression.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for heating element and thermocouple procurement. Manufacturing concentrates in Germany, the United States, and Japan for precision mechanical loading systems. High-purity platinum-rhodium thermocouples and ceramic fiber insulation draw from South African mining operations and Chinese refractory production. Single-source vulnerability in platinum group metal supply creates procurement hedge costs. Distribution runs through OEM-direct sales for large utilities and specialized distributor networks for research laboratory procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendors increasingly capture value through service contracts and calibration subscriptions that expand faster than hardware replacement cycles. Recurring revenue from thermal element refurbishment and GB standard compliance auditing now exceeds 40 percent of lifetime customer value for installed creep rupture platforms.
For Market Incumbents: Harden aftermarket service density in Germany's Ruhr cluster and China's Jiangsu province against emerging regional fabrication houses. Deepen vertical integration into platinum-rhodium thermocouple refurbishment to offset South African supply volatility. Prioritize embedded software audit trails that automate REACH and GB standard documentation compliance. For New Entrants and Emerging Players: Pursue thermogravimetric analysis system white space in Indian metallurgical laboratories where BIS standard alignment creates qualification backlog demand. Target research laboratory segments in Maharashtra and Gujarat industrial corridors with digital image correlation platforms that displace traditional extensometer workflows. Lead with application engineering partnerships rather than capital equipment price competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision measurement specialists with digital twin integration capabilities over commodity creep tester fabricators. Long-term viability hinges on software-enabled service attach rates rather than hardware shipment volumes. Acquisition targets should demonstrate installed base density in FAA-regulated aerospace corridors or MIIT-mandated Chinese utility markets. Monitor SAMR's progress on GB standard international accreditation alignment as the critical inflection signal for import platform market access.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Virtualizes thermal-mechanical protocols before physical loading, compressing development cycles for aerospace propulsion research. |
| Backward Integration into Heating Elements | Captive supply of platinum-rhodium thermocouples mitigates South African mining concentration risk. |
| Multi-Axis Fatigue Platform Launch | Consolidated qualification workflows reduce footprint duplication for power generation OEMs in Germany's Ruhr cluster. |
| GB Standard Compliance Certification | MIIT-mandated protocol recalibration enables market access for turbine application testing in Jiangsu and Guangdong provinces. |
| Service Contract Expansion | Recurring calibration and thermal element refurbishment revenue exceeds hardware margins across installed European base. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with laboratory directors, OEM procurement managers, aftermarket service heads, and metallurgical R&D leads; and secondary validation through MIIT GB standard filings, FAA airworthiness directives, customs trade data for testing equipment imports, and SEC disclosures from listed materials testing conglomerates. Bottom-up equipment shipment estimates triangulated against top-down utility capital expenditure patterns across the analysis window.
Forecast inputs considered equipment type segmentation, material tested chemistry, application industry procurement urgency, and testing technology measurement modality. CAGRs derived from regression against historical replacement cycles and regulatory mandate implementation timelines. Specific weighting applied to MIIT superalloy testing protocol revisions, EU Green Deal carbon border adjustment documentation requirements, and FAA turbine hot-section component qualification backlogs.
Sensitivities concentrate around SAMR's GB standard accreditation alignment timeline, platinum group metal price volatility from South African supply disruptions, and digital twin adoption rates in aerospace propulsion research. Forecasts reflect documented assumptions on replacement cycle elongation and service attach rate expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
HPLC Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Paint Tester Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Global Insulation Testers Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Global Rheometer and Viscometer Market
Testing Equipment
Lubricant Testing Machine Market
Testing Equipment
Heavy Metal Testing Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Global Film Thickness Measurement Market