
 Low Temperature Insulation Materials Market | 2026-2036
Low Temperature Insulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Low Temperature Insulation Materials Market Foresight
Aerogel is consolidating share against traditional polyurethane in sub-zero pipeline jackets as operators prioritize thinner insulation profiles for constrained footprints. Owens Corning leverages its fiberglass manufacturing scale to supply standardized cryogenic board stock for North American LNG builders. BASF SE anchors European demand through formulated polyurethane systems engineered for ammonia and hydrogen transport protocols. Huntsman Corporation specializes in spray-applied variants that reduce installation labor at remote Arctic production sites.
Low temperature insulation materials are engineered thermal barriers designed to maintain temperatures below ambient, typically incorporating closed-cell foams, inorganic fibers, or nanoporous solids with thermal conductivity values below 0.025 W/m·K at cryogenic conditions. These materials prevent heat ingress into storage vessels, transfer lines, and process equipment handling liquefied gases such as natural gas, nitrogen, and hydrogen. Aerogel segments command premium positioning due to extreme low-density structures that deliver maximum thermal resistance per unit thickness. Polyurethane retains volume leadership in industrial refrigeration where cost-per-R-value metrics dominate procurement decisions. Fiberglass occupies mature utility in HVAC cold-side distribution where code-minimum specifications limit specification upgrades.
The EPA enforces hydrofluorocarbon phaseout timelines under the AIM Act that compel reformulation of foam blowing agents across domestic production. OSHA maintains permissible exposure limits for isocyanates during spray foam application, shaping contractor certification requirements and product liability frameworks. ASTM C177 and C518 thermal conductivity standards govern material qualification for US LNG infrastructure approvals. Stakeholders must monitor evolving hydrogen liquefaction temperature thresholds as next-generation transport protocols test existing insulation performance boundaries.
Market Dynamics
EPA enforcement of hydrofluorocarbon phasedown timelines under the AIM Act is forcing immediate reformulation across polyurethane foam production, compressing supplier transition windows and elevating compliance costs for domestic manufacturers serving LNG infrastructure.
Growth Catalysts
- Liquefaction capacity expansion:US Gulf Coast petrochemical corridors are commissioning new LNG export terminals requiring cryogenic-grade insulation for storage tanks and transfer lines.
- REACH F-Gas Regulation:European chemical policy is accelerating adoption of lower-GWP blowing agent alternatives in formulated polyurethane systems for hydrogen transport infrastructure.
- Aerogel thermal performance:Nanoporous silica structures with conductivity below 0.020 W/m·K are penetrating sub-zero pipeline jackets where space constraints dominate engineering specifications.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs fluctuate with crude oil derivatives, compressing margin predictability for spray-applied insulation contractors.
- Silica precursor concentration:Aerogel manufacturing depends on concentrated tetraethyl orthosilicate supply chains centered in Germany and China, creating geographic vulnerability.
- Technical thickness limitations:Fiberglass board stock requires 40-60% greater thickness than aerogel to achieve equivalent R-values at cryogenic temperatures, restricting retrofit applications.
Strategic Opportunities
- Hydrogen liquefaction protocols:Next-generation transport standards testing insulation performance at -253°C are opening specification windows for advanced nanoporous materials.
- Arctic production logistics:Remote LNG extraction sites in northern Canada and Alaska favor spray-applied polyurethane variants that minimize installation labor requirements.
- EU Green Deal industrial decarbonization:Carbon border adjustment mechanisms are incentivizing thermal efficiency upgrades in European cold chain infrastructure.
Industry Challenges
- Certified installer scarcity:OSHA-mandated isocyanate exposure training programs are creating bottlenecks for spray foam contractor certification, extending project timelines.
- ASTM qualification delays:Thermal conductivity testing under C177 and C518 standards requires 90-120 day laboratory cycles, slowing material approval for time-sensitive LNG construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Temperature Insulation Materials Market |
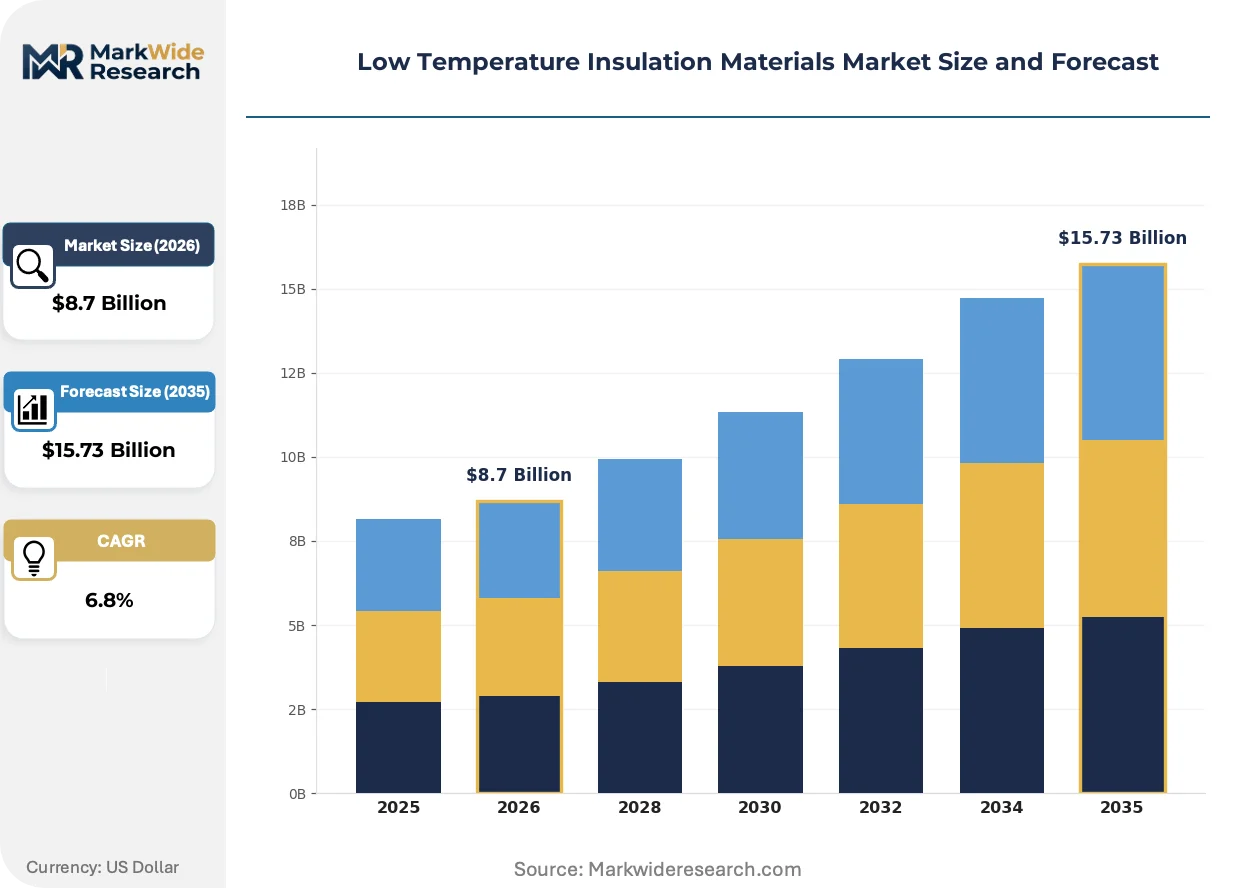
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyurethane, Polystyrene, Fiberglass, Aerogel Application: Cryogenics, LNG Transportation, Industrial Refrigeration, HVAC End User: Oil & Gas, Chemical Processing, Aerospace, Manufacturing Distribution Channel: Direct Sales, Online Retail, Distributors, Others |
| Companies Covered | Owens Corning, BASF SE, Huntsman Corporation, Kingspan Group plc, Johns Manville Corporation, Saint-Gobain, Aspen Aerogels Inc., Knauf Insulation, Rockwool International A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Temperature Insulation Materials Market Shifts & Advancements
Material science advances and regulatory chemistry mandates are converging to reshape formulation priorities across cryogenic insulation supply chains, with performance density and environmental compliance emerging as dual specification imperatives.
Vacuum-insulated panel technology is modularizing around standardized envelope dimensions for LNG storage tank retrofits. Cryogenic terminal operators in Texas and Louisiana are piloting prefabricated panel systems that reduce field installation time by half compared to conventional multi-layer insulation. This modularization is compressing project schedules and enabling faster capacity commissioning cycles.
EPA AIM Act enforcement is eliminating HFC-245fa and HFC-365mfc from domestic polyurethane blowing agent portfolios by 2025. Domestic foam producers are accelerating transitions to hydrofluoroolefin and hydrocarbon alternatives, though thermal conductivity penalties of 5-8% are forcing compensatory density increases. Gulf Coast LNG builders are absorbing reformulated products under expedited qualification protocols.
Engineering-procurement-construction firms are consolidating insulation specifications across multi-train LNG projects to secure volume pricing and reduce qualification overhead. Tier-one EPC contractors in Houston and Bechtel-operated developments are standardizing on pre-approved material lists, compressing supplier diversity and elevating incumbent fiberglass and polyurethane producers with established ASTM certifications.
Low Temperature Insulation Materials Market Segmentation
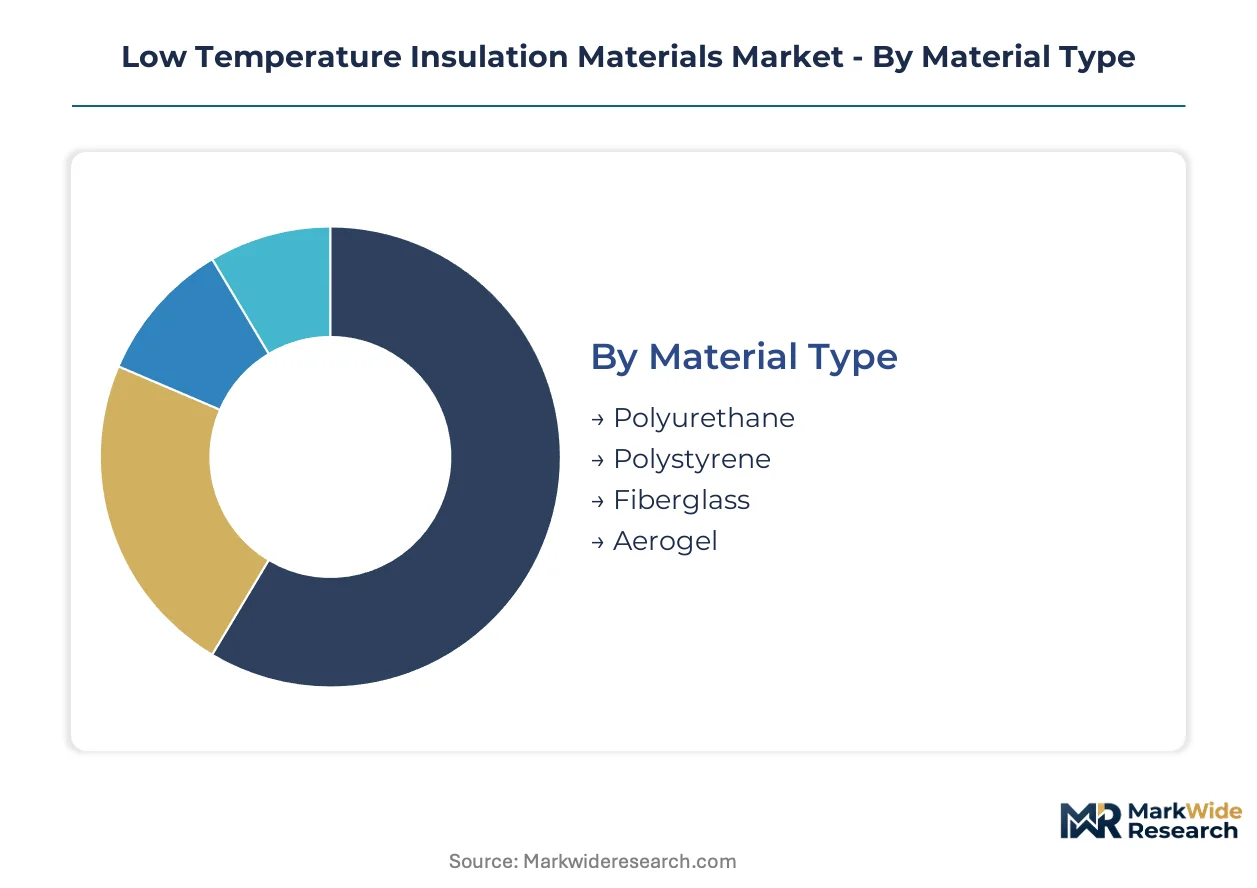
Material selection in low temperature insulation hinges on thermal conductivity thresholds, installation constraints, and regulatory compliance timelines. Procurement patterns diverge sharply between standardized bulk orders for industrial refrigeration and engineered specifications for cryogenic infrastructure. Understanding segment boundaries clarifies where formulation investments concentrate versus where cost-per-R-value dominates.
Material Type:
Customization intensity spans from commodity foams with limited formulation latitude to aerogel systems requiring precise density engineering for each application.
- Polyurethane:Closed-cell foam structures dominate industrial refrigeration and LNG jacketing through superior thermal resistance per dollar. US Gulf Coast terminal builders specify spray-applied variants to compress installation schedules at multi-train liquefaction facilities.
- Aerogel:Silica-based nanoporous solids achieve conductivity below 0.020 W/m·K in profiles under 10mm, enabling retrofit of space-constrained sub-zero pipelines. Demand concentrates in Arctic LNG corridors where footprint restrictions override first-cost considerations.
- Fiberglass:Mature inorganic fiber boards supply HVAC cold-side distribution and secondary containment applications where code-minimum specifications limit premium material uptake.
- Polystyrene:Expanded and extruded variants serve secondary cold chain packaging and temporary cryogenic shielding where disposability outweighs thermal performance optimization.
Most installed capacity flows through polyurethane systems. Expansion is steepest in aerogel as hydrogen liquefaction protocols test thinner insulation boundaries.
Application:
Volume concentration sits with mature thermal management systems, while emerging transport infrastructure drives specification innovation at the margin.
- Cryogenics:Storage vessels and transfer lines handling liquefied natural gas, nitrogen, and hydrogen demand multi-layer insulation with vacuum barriers. Terminal operators in Texas and Louisiana specify prefabricated panel systems to halve field installation duration.
- LNG Transportation:Marine cargo containment and over-the-road tanker systems require flexible insulation blankets that withstand mechanical fatigue and thermal cycling. Shipbuilders in South Korea and Japan prioritize weight reduction for fuel efficiency compliance.
- Industrial Refrigeration:Cold storage warehouses and food processing facilities specify polyurethane board stock where cost-per-R-value metrics govern procurement. EPA AIM Act reformulation is elevating compliance costs for domestic foam producers.
- HVAC:Commercial building cold-side distribution employs fiberglass duct insulation where thermal bridging standards remain below cryogenic thresholds. Code cycles in California and New York are tightening minimum R-value requirements.
Procurement volume clusters in industrial refrigeration. Specification complexity is climbing fastest in LNG transportation as marine decarbonization mandates reshape cargo system design.
End User:
Capital intensity and technical specification authority vary dramatically across buyer categories, from integrated energy majors to fragmented maintenance contractors.
- Oil & Gas:Supermajors and midstream operators command standardized material lists across liquefaction, regasification, and pipeline assets. Engineering-procurement-construction firms in Houston consolidate specifications to secure volume pricing.
- Chemical Processing:Petrochemical complexes require corrosion-resistant insulation for ammonia and hydrogen transport protocols. European producers under REACH F-Gas Regulation are accelerating lower-GWP formulation adoption.
- Aerospace:Satellite propellant storage and launch vehicle tankage demand ultra-lightweight insulation with launch vibration tolerance. NASA and ESA procurement cycles drive qualification timelines exceeding 24 months.
- Manufacturing:Discrete production facilities specify maintenance-grade materials through distributor networks rather than direct manufacturer relationships. Semiconductor fabs in Taiwan and South Korea represent a premium subsegment for ultra-pure thermal barriers.
Contract value concentrates with oil and gas operators. Technical specification evolution is most rapid in chemical processing as hydrogen economy infrastructure scales.
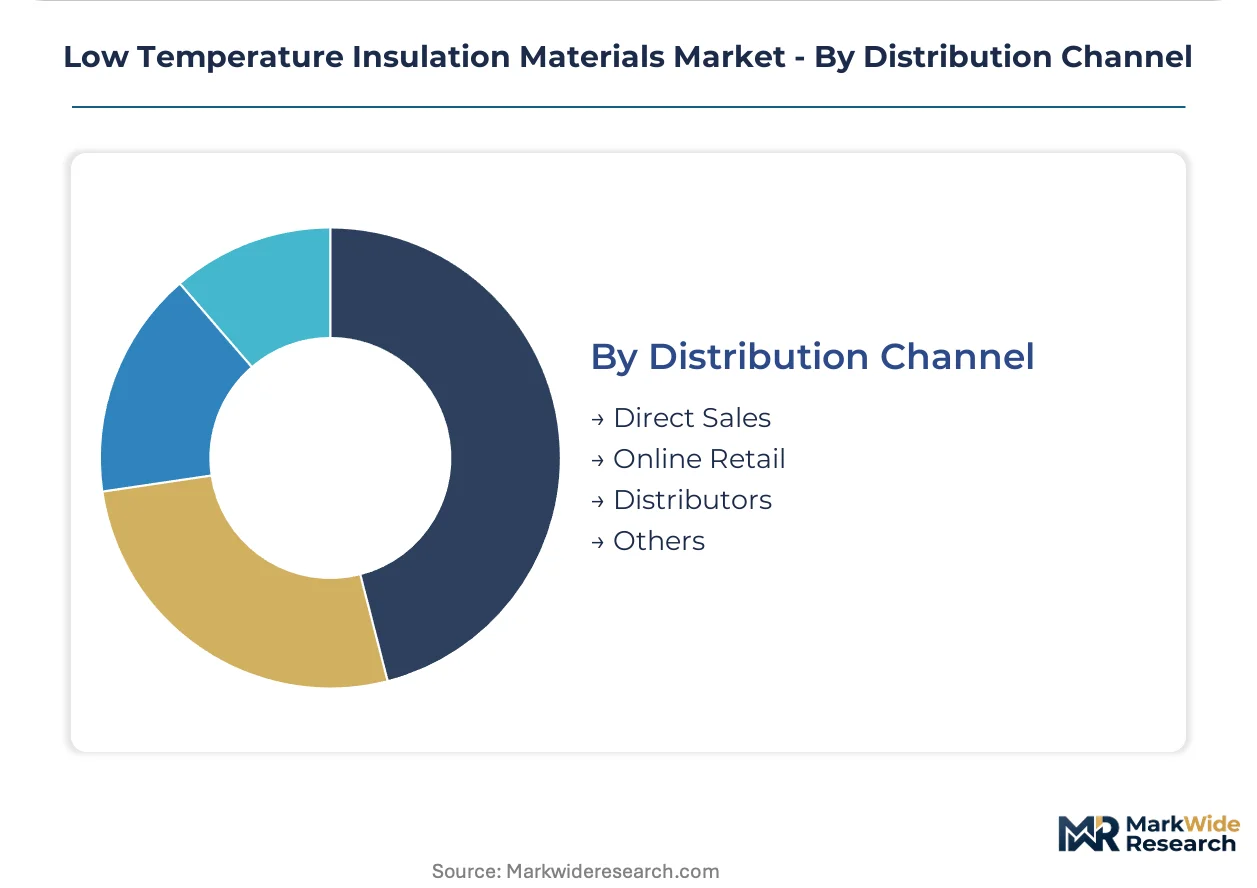
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic proximity to installation sites.
- Direct Sales:Large-format LNG projects and multi-site industrial refrigeration contracts bypass intermediaries for manufacturer-engineer collaboration. Owens Corning and BASF SE maintain dedicated account teams for Gulf Coast terminal developers.
- Distributors:Regional stocking locations serve maintenance contractors and smaller industrial facilities requiring rapid material availability. Networks in the US Midwest and German Ruhr region carry pre-cut fiberglass and polyurethane board inventory.
- Online Retail:E-commerce platforms capture standardized HVAC and cold chain packaging orders below pallet quantities. Amazon Business and specialized industrial marketplaces are compressing lead times for replacement stock.
- Others:Cooperative purchasing agreements and government supply schedules serve municipal cold storage and defense cryogenic applications through non-standard contracting vehicles.
Revenue volume flows predominantly through direct sales relationships. Digital channel penetration is expanding most quickly in HVAC maintenance and replacement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Gulf Coast petrochemical corridors anchor global demand for cryogenic-grade insulation materials as liquefaction capacity expansion accelerates across Texas and Louisiana terminal complexes.
United States
EPA enforcement of AIM Act hydrofluorocarbon phasedown timelines is forcing immediate polyurethane foam reformulation across domestic production. OSHA maintains permissible exposure limits for isocyanates during spray foam application, shaping contractor certification requirements. Houston-based engineering-procurement-construction firms are consolidating insulation specifications across multi-train LNG projects to secure volume pricing.
Germany
REACH F-Gas Regulation accelerates adoption of lower-GWP blowing agent alternatives in formulated polyurethane systems for hydrogen transport infrastructure. ECHA chemical policy mandates are redirecting formulation strategies toward compliant chemistries. Ruhr region distribution networks carry pre-cut fiberglass and polyurethane board inventory for rapid industrial facility supply.
China
Dual carbon goals under MEE oversight are tightening thermal efficiency standards for cold chain infrastructure nationwide. GB standards govern material qualification for domestic LNG and hydrogen liquefaction projects. Yangtze River Delta manufacturing clusters are scaling aerogel precursor production to reduce import dependency on German and Chinese silica supply chains.
Japan
METI industrial decarbonization frameworks are incentivizing thermal efficiency upgrades in chemical processing and hydrogen economy infrastructure. JIS standards provide baseline qualification for cryogenic insulation in satellite propellant storage and launch vehicle applications. Osaka-Kansai industrial corridors host specialized fabricators serving aerospace and marine LNG containment systems.
South Korea
MFDS oversight of industrial chemical safety intersects with shipbuilder demand for lightweight insulation blankets in marine cargo containment. Seoul Capital Area engineering offices coordinate specification standards for weight-reduced thermal systems. Busan-Ulsan shipbuilding clusters prioritize fuel efficiency compliance through advanced insulation materials in LNG carrier construction.
Low Temperature Insulation Materials Market Competitive Landscape
Capacity expansion dominates the current landscape as incumbent producers scale fiberglass and polyurethane output to serve Gulf Coast LNG terminal construction schedules. The vendor base separates into three distinct tiers: multinational chemical conglomerates with formulated system portfolios, specialized aerogel manufacturers with nanoporous technology platforms, and regional insulation fabricators serving maintenance and retrofit segments. Consolidation pressure is elevating incumbent producers with established ASTM certifications while compressing qualification windows for new entrants.
Among multinational chemical conglomerates, BASF SE and Huntsman Corporation exemplify the formulated systems archetype through their polyurethane and specialty chemical positioning. Owens Corning represents the scale-driven fiberglass manufacturing segment supplying standardized cryogenic board stock. Aspen Aerogels Inc. occupies the premium nanoporous materials tier where extreme thermal performance commands specification priority in space-constrained applications.
| Leading Market Players |
|---|
| Owens Corning |
| BASF SE |
| Huntsman Corporation |
| Kingspan Group plc |
| Johns Manville Corporation |
| Saint-Gobain |
| Aspen Aerogels Inc. |
| Knauf Insulation |
| Rockwool International A/S |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators in the US Midwest and German Ruhr region anchor regional distribution networks, translating concentrated silica precursor supply into pricing discipline that shields established polyurethane formulators from spot-market volatility while compressing margins for uncontracted aerogel entrants.
Pricing Analysis
Input-cost pass-through from petrochemical feedstocks governs polyurethane pricing dynamics, with polyol and isocyanate fluctuations compressing margin predictability for spray-applied contractors serving Gulf Coast LNG terminals. Three-tier pricing structure across premium aerogel, standard polyurethane, and economy fiberglass levels reflects certification-grade differentiation under ASTM C177 and C518 standards. Pricing pressure stems from EPA AIM Act reformulation costs elevating domestic foam production expenses. Industrial refrigeration buyers exhibit highest price sensitivity due to cost-per-R-value procurement metrics, while cryogenic infrastructure operators prioritize thermal performance over first-cost considerations.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore operate hub-and-spoke patterns that consolidate material flows for LNG terminal construction schedules. Manufacturing concentrates in the United States, Germany, and China, with Yangtze River Delta clusters scaling aerogel precursor production to reduce import dependency. Tetraethyl orthosilicate, methylene diphenyl diisocyanate, and glass fiber feedstock constitute critical input dependencies. Single-source vulnerability in German and Chinese silica precursor supply chains creates geographic concentration risk. Distribution runs through direct sales relationships for large-format projects and regional distributor networks for maintenance-grade orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by liquefaction capacity expansion across US Gulf Coast corridors, where multi-train terminal construction generates recurring demand cycles resistant to short-term industrial volatility.
For Market Incumbents: Deploy ASTM certification leverage to consolidate specification authority across engineering-procurement-construction procurement lists, compressing qualification windows for aerogel challengers while accelerating capacity additions in Texas and Louisiana to match terminal construction timelines. Backward integration into tetraethyl orthosilicate supply mitigates geographic concentration risk from German and Chinese precursor dependencies. For New Entrants and Emerging Players: E-commerce platforms targeting HVAC maintenance and replacement segments offer the most penetrable route, capturing standardized orders below pallet quantities where incumbent direct-sales infrastructure lacks cost efficiency. Digital-channel penetration in cold chain packaging and semiconductor fab thermal barriers bypasses entrenched distributor relationships. Specialty aerogel variants for hydrogen liquefaction at -253°C represent specification white space where performance premiums override incumbent volume advantages. For Investors and Strategic Acquirers: Chemical conglomerates with formulated systems portfolios are the most active acquirer in this space, seeking nanoporous technology platforms to anchor hydrogen economy positioning. The five-to-ten year viability window favors targets with established REACH F-Gas Regulation compliance and AIM Act-ready blowing agent portfolios. Watch hydrogen liquefaction protocol finalization as the inflection signal that reallocates specification share toward extreme-performance materials.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Gulf Coast terminal builders require scaled cryogenic board stock supply for multi-train liquefaction schedules. |
| Backward Integration | Captive tetraethyl orthosilicate production reduces German and Chinese supply chain vulnerability for aerogel manufacturers. |
| Green Manufacturing Transition | Hydrofluoroolefin and hydrocarbon blowing agent adoption satisfies EPA AIM Act mandates with 5-8% thermal conductivity trade-offs. |
| Long-term Supply Agreement | Pre-approved material lists with Houston EPC firms lock in volume pricing across standardized LNG project specifications. |
| Joint Venture | Ruhr region distribution partnerships accelerate REACH-compliant polyurethane supply for European hydrogen transport infrastructure. |
Research Methodology
Multiple input streams — technical specification interviews, regulatory compliance documentation, and trade flow databases — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged plant managers at Gulf Coast LNG terminals, procurement leads at European chemical processing facilities, EPC contractor specification engineers, and aerogel R&D directors. Secondary validation drew from EPA AIM Act filings, ECHA REACH registrations, ASTM thermal conductivity test records, and customs data tracking tetraethyl orthosilicate import flows.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling volume and value trajectories by material type, application severity, end-use capital intensity, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against macro infrastructure investment patterns. Hydrogen liquefaction temperature thresholds and LNG capacity commissioning schedules served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for vacuum-insulated panel modularization would alter the outlook if prefabricated systems achieve faster field-installation penetration than projected. Forecasts reflect documented assumptions around EPA enforcement timelines and REACH F-Gas Regulation implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Active Insulation Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
Insulation Products Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Fire Retardant Flexible Cable Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Global Glass Insulation Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
OEM Insulation Market
Insulation Materials
Global Microporous Insulation Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Global Calcium Silicate Insulation Market