
 Global Silica-Based Matting Agents Market | 2026-2036
Global Silica-Based Matting Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silica-Based Matting Agents Market Foresight
Technical service contracts for particle size optimization and dispersion guidance is consolidating into core silica supply agreements, shifting vendor relationships from transactional chemical sales to embedded performance partnerships. Evonik Industries AG leverages its fumed silica R&D depth to sustain premium positioning in automotive refinish systems. PPG Industries anchors North American supply through captive consumption and external merchant sales. Wacker Chemie AG differentiates via integrated silicone-silica technology platforms that span matting and rheology control.
Silica-based matting agents are synthetic amorphous silicon dioxide particles engineered to specific surface areas between 100 and 400 m²/g, manufactured through flame hydrolysis or wet precipitation to scatter light and reduce gloss in cured films. Precipitated silica dominates volume in architectural paints where cost sensitivity structures procurement, while fumed silica commands margin pools in electronics-grade coatings requiring ultra-low ionic contamination. The cosmetics application segment is expanding fastest as matte-finish skincare formulations displace talc and starch alternatives under clean-label pressure.
REACH registration requirements in Europe, EPA TSCA Section 5 scrutiny in the United States, and China's GB standards for volatile organic compound limits in coatings collectively elevate compliance costs and favor suppliers with established regulatory dossiers. ECHA's evolving nanomaterial reporting obligations specifically target amorphous silica particle dimensions, forcing reformulation investments across the value chain. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied carbon tracking reshape raw material sourcing decisions for precipitated silica feedstocks.
Market Dynamics
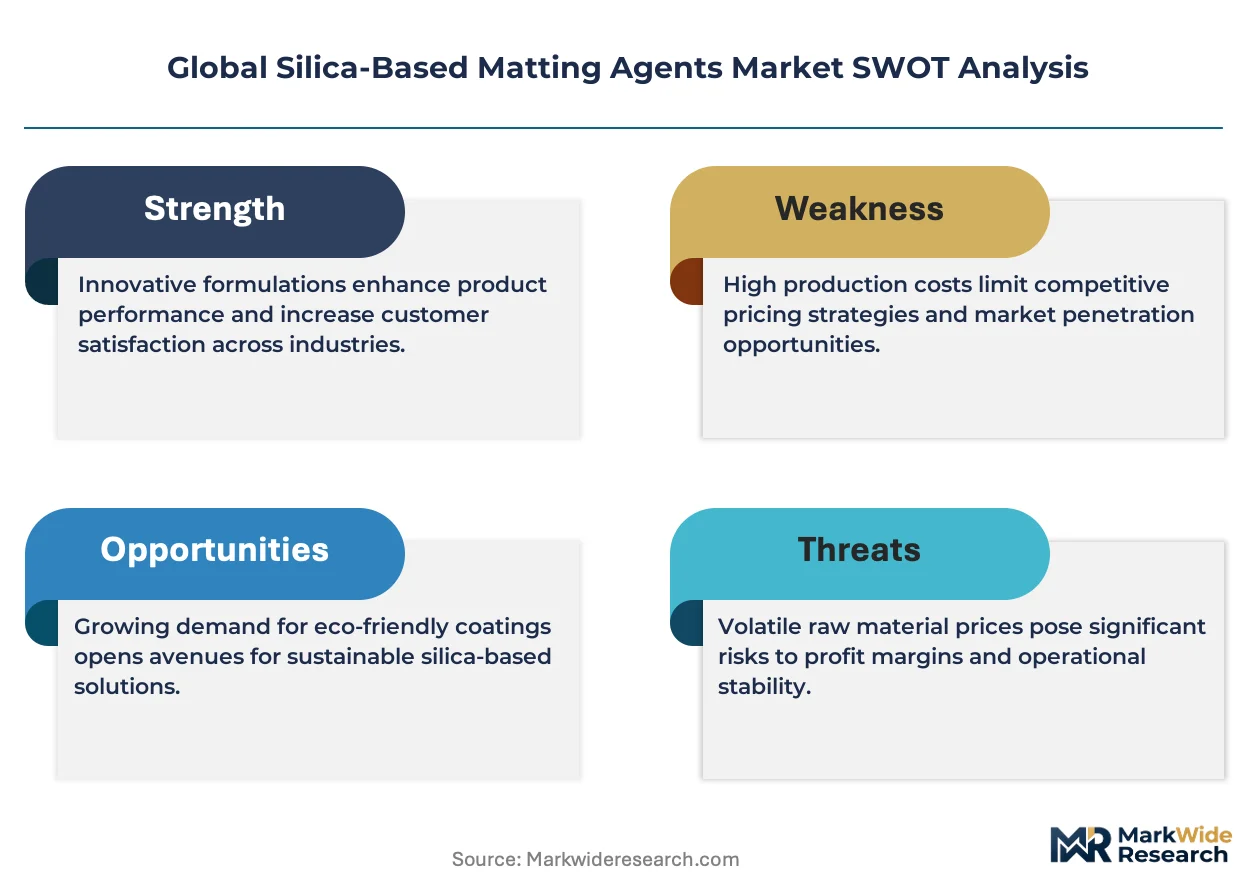
REACH registration dossiers and ECHA nanomaterial reporting obligations are forcing precipitated silica producers into multi-year reformulation cycles, consolidating procurement around suppliers with pre-validated regulatory packages.
Growth Catalysts
- Automotive low-VOC mandates:OEM clearcoat specifications in Germany and China are eliminating solvent-heavy alternatives, pulling silica matting agents into factory-applied finishes at specification level.
- REACH Article 33 supply chain disclosure:Downstream coatings formulators face downstream user obligations that favor pre-registered amorphous silica grades with established safety data sheets.
- Cosmetics clean-label substitution:Skincare brands are eliminating talc and starch from matte-finish formulations, redirecting formulation spend toward precipitated silica with verified particle morphology.
Market Restraints
- Sodium silicate feedstock volatility:Energy-intensive precipitation processes expose margins to natural gas price swings in German and Chinese manufacturing clusters.
- Fumed silica supply concentration:Flame hydrolysis capacity concentrates among integrated chemical majors, limiting merchant availability for specialty electronics-grade coatings.
- Organic matting agent substitution:Polymer-based alternatives with lower density are capturing volume in high-build architectural paints where gloss reduction targets are modest.
Strategic Opportunities
- India coatings manufacturing expansion:Domestic paint production capacity additions near Mumbai and Chennai create demand for technical service partnerships around dispersion optimization.
- Waterborne industrial wood coatings:Furniture manufacturers in Italy and Poland are converting solvent-based lines, opening specification windows for silica grades with proven compatibility.
- EU Green Deal embodied carbon tracking:Precipitated silica producers with renewable energy sourcing can differentiate in sustainability-scorecard procurement processes.
Industry Challenges
- Particle size distribution control:Tightening specifications for automotive refinish color matching require investments in laser diffraction quality systems and technician training.
- Multi-jurisdiction dossier maintenance:Simultaneous EPA TSCA Section 5 notifications, ECHA updates, and China MEE filings strain regulatory affairs bandwidth at mid-scale suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silica-Based Matting Agents Market |
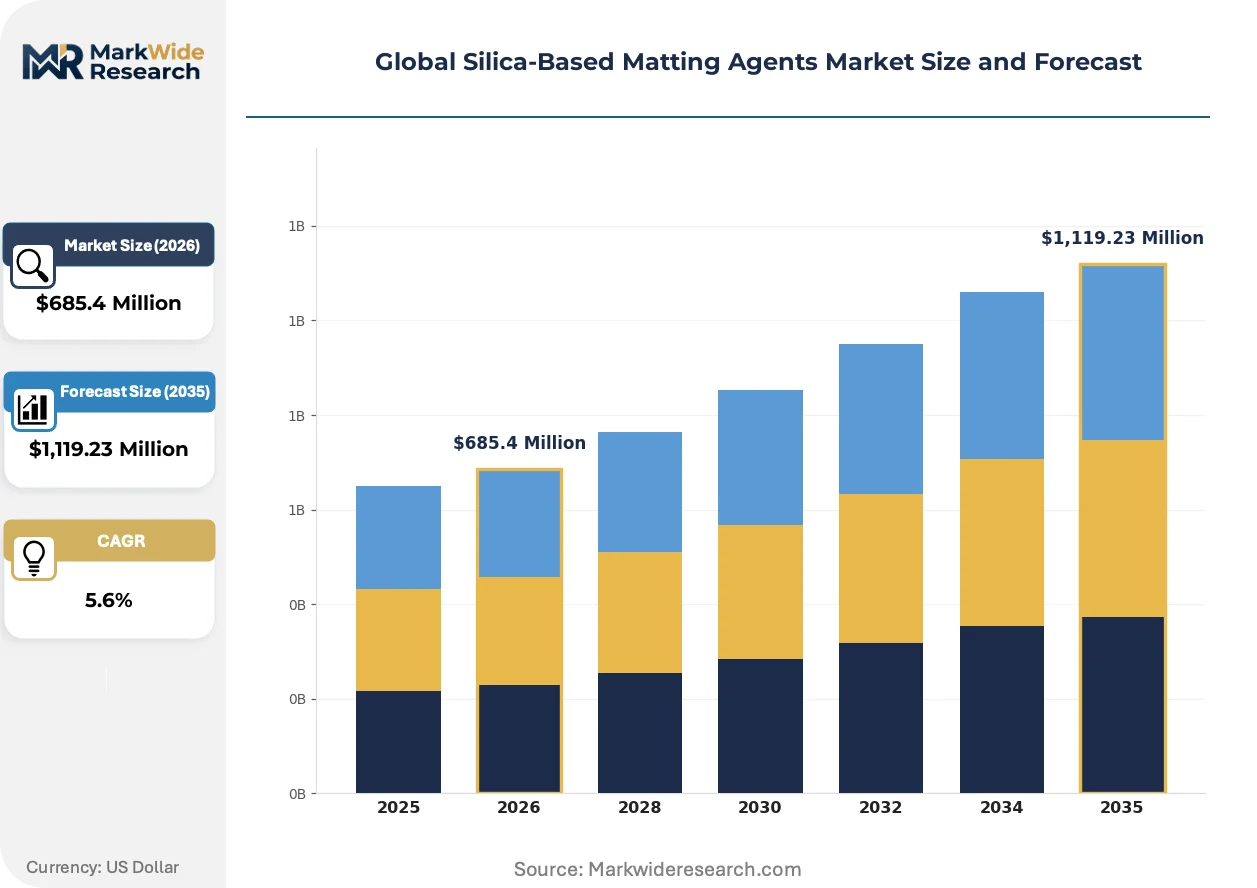
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,119.23 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fumed Silica, Precipitated Silica, Colloidal Silica, Silica Gel Application: Paints & Coatings, Printing Inks, Plastics, Cosmetics End User Industry: Construction, Packaging Manufacturing, Personal Care, Electronics Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Wholesalers |
| Companies Covered | Evonik Industries AG, PPG Industries, Wacker Chemie AG, W. R. Grace & Co.-Conn., BASF SE, BYK Additives & Instruments, Lubrizol Corporation, Imerys, PQ Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silica-Based Matting Agents Market Shifts & Advancements
Formulation science is pivoting from commodity particle supply toward engineered surface chemistry, with dispersion stability and compatibility testing becoming embedded in commercial relationships rather than post-sale support.
Surface-modified precipitated silica with controlled hydrophobicity is decentralizing technical service capabilities from centralized R&D labs to regional application centers. Automotive refinish distributors in Germany and the United States are installing in-house dispersion testing to accelerate color-matching workflows. This capability shift is compressing the traditional three-week sample evaluation cycle into same-day formulation guidance.
ECHA's 2022-2023 updates to nanomaterial reporting guidance for synthetic amorphous silica are forcing reformulation investments across European coatings value chains. Downstream formulators face customer disclosure obligations that disqualify unregistered raw material grades. Waterborne industrial coatings in Italy and Poland represent the most affected segment, with manufacturers accelerating supplier qualification processes ahead of enforcement phase-in.
Coatings procurement departments are consolidating vendor panels around integrated performance partnerships rather than spot chemical purchasing. Tier-one automotive suppliers in Germany now require silica vendors to embed particle optimization guidance into master supply agreements. This behavioral shift is most pronounced in OEM clearcoat specifications, where formulation stability over 18-month production cycles has become a contractual performance metric.
Global Silica-Based Matting Agents Market Segmentation
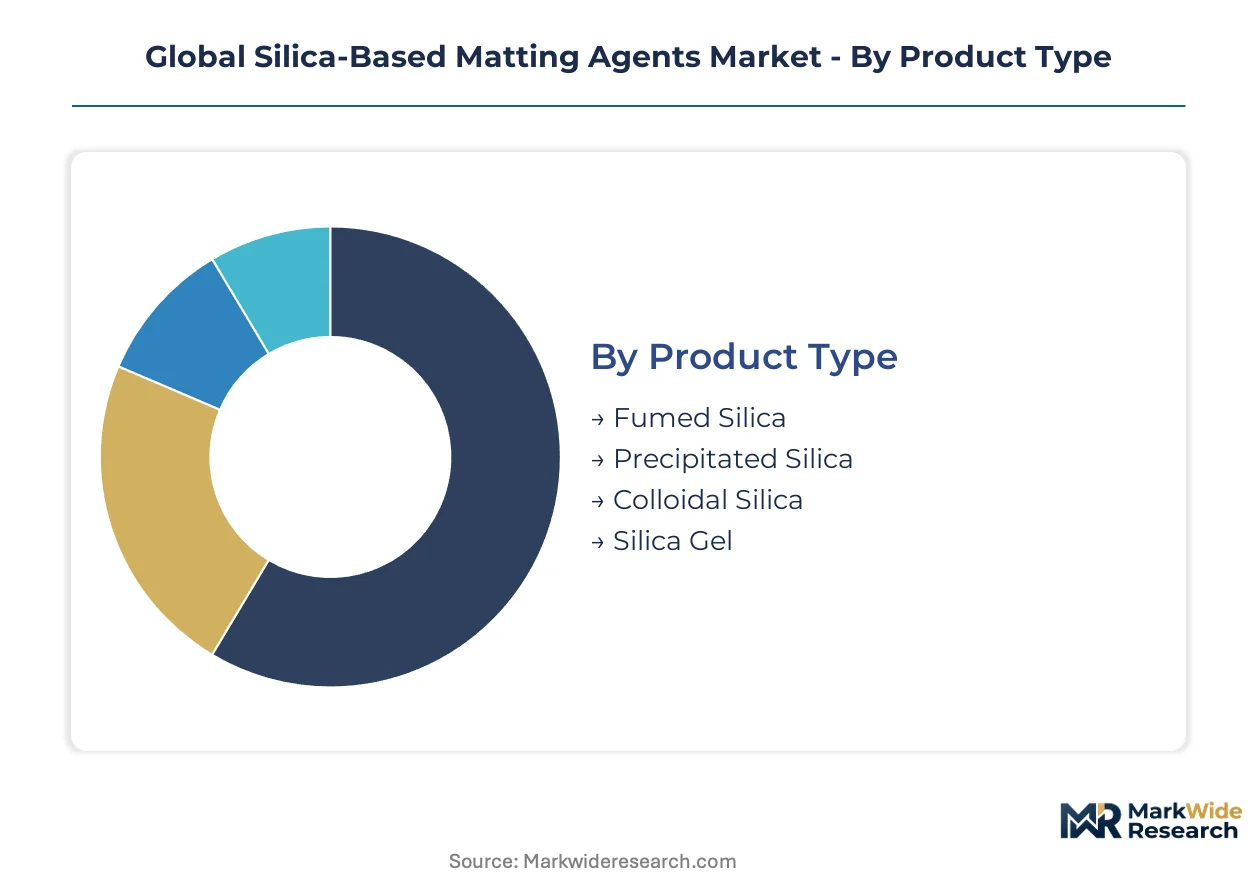
Silica-based matting agents exhibit distinct performance profiles across manufacturing processes and end-use specifications. Procurement decisions pivot on surface area requirements, ionic contamination thresholds, and dispersion compatibility rather than commodity pricing alone.
Product Type:
Surface chemistry and particle architecture define competitive positioning across production methods.
- Fumed Silica:Synthetic amorphous silicon dioxide produced through flame hydrolysis delivers surface areas between 200-400 m²/g with ultra-low residual ion content. Electronics-grade coatings in Germany and Japan specify fumed grades for high-gloss reduction in display and semiconductor applications where metallic contamination risks are non-negotiable.
- Precipitated Silica:Wet precipitation from sodium silicate solutions generates controlled pore structures at 100-300 m²/g surface areas with tunable particle size distributions. Architectural paint manufacturers in China and India prioritize precipitated grades for cost-optimized matting efficiency in high-volume waterborne formulations.
- Colloidal Silica:Nanometer-scale dispersed particles in aqueous suspension enable thin-film matting in precision coatings where dry powder incorporation creates defects.
- Silica Gel:Macroporous amorphous silica with rigid structural integrity serves specialized applications requiring adsorption capacity alongside optical scattering.
Precipitated silica leads on scale; fumed silica leads on momentum.
Application:
Formulation complexity and regulatory exposure structure demand patterns across downstream industries.
- Paints & Coatings:Industrial, automotive, and decorative coatings represent the dominant volume sink, with OEM clearcoats in Germany and China driving specification-grade procurement under tightening VOC limits. Waterborne architectural paints in India and Brazil absorb commodity precipitated silica for cost-sensitive matte finishes.
- Cosmetics:Skincare and color cosmetic formulations are climbing the fastest as clean-label pressures displace talc and starch alternatives. Precipitated silica with verified particle morphology commands premium positioning in matte-finish foundations and sun care products sold through European and North American retailers.
- Printing Inks:UV-curable and solvent-based ink systems employ controlled particle sizes to manage gloss in packaging graphics.
- Plastics:Masterbatch incorporation for film and sheet applications requires surface-treated grades compatible with polyolefin and engineering resin matrices.
Coatings applications anchor volume concentration; cosmetics applications demonstrate steepest expansion trajectory.
End User Industry:
Capital intensity and specification rigor differentiate procurement behavior across industrial segments.
- Construction:Decorative and protective coatings for residential and commercial buildings generate sustained baseline demand, with infrastructure investment cycles in China and India determining regional volume swings. Precipitated silica dominates this segment where cost-per-unit-gloss-reduction drives supplier selection.
- Electronics:Display coatings, semiconductor packaging, and printed circuit board finishes require fumed silica grades with sub-ppm metallic contamination profiles. Japanese and South Korean electronics manufacturers enforce qualification protocols that lock in supplier relationships across multi-year production cycles.
- Packaging Manufacturing:Flexible and rigid packaging inks employ matting agents for shelf-appeal differentiation in food and consumer goods segments.
- Personal Care:Cosmetic and toiletry brands source precipitated silica through toll manufacturers and contract formulators with established clean-label credentials.
Construction leads on scale; electronics leads on margin capture.
Distribution Channel:
Technical service requirements and order scale determine channel selection across customer tiers.
- Direct Sales:Tier-one coatings manufacturers and multinational personal care brands negotiate master supply agreements embedding particle optimization guidance and regulatory dossier maintenance. Evonik Industries AG and Wacker Chemie AG deploy technical service teams directly to automotive OEM formulation labs in Germany and the United States.
- Distributors:Regional chemical distributors aggregate demand from mid-scale coatings formulators and compounders, warehousing standard grades for just-in-time delivery across European and North American manufacturing clusters.
- E-commerce Platforms:Specialty chemical marketplaces and direct manufacturer portals serve research-scale buyers and small-batch formulators with credit-card purchasing and rapid sample fulfillment.
- Wholesalers:Bulk commodity precipitated silica moves through construction chemical wholesalers serving architectural paint manufacturers in emerging markets.
Direct sales leads on value concentration; e-commerce platforms gain share fastest in sample and pilot-scale procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as compliance cost gaps between jurisdictions widen. Manufacturers are relocating precipitation capacity toward regions with streamlined chemical registration frameworks while maintaining fumed silica expertise in established regulatory jurisdictions.
Germany
Automotive OEM clearcoat specifications in Stuttgart and Wolfsburg drive premium-grade silica consumption. REACH Article 33 downstream user obligations force coatings formulators toward pre-registered amorphous silica grades. The North Rhine-Westphalia chemical cluster hosts integrated precipitation facilities serving architectural paint manufacturers across the Rhine-Ruhr industrial corridor.
China
Dual carbon goals and GB standards for VOC limits in coatings are accelerating waterborne formulation adoption in Shanghai and Guangdong manufacturing bases. MEE enforcement of nanomaterial reporting obligations targets synthetic amorphous silica dimensions. The Yangtze River Delta concentration of automotive assembly plants pulls specification-grade matting agents into factory-applied finish systems.
United States
EPA TSCA Section 5 scrutiny of new chemical substances elevates procurement preference for existing silica grades with established safety profiles. Automotive refinish distributors in Michigan and Ohio are installing in-house dispersion testing capabilities. The Gulf Coast petrochemical corridor supplies sodium silicate feedstocks to regional precipitation operations serving architectural coatings manufacturers.
India
Domestic paint production capacity additions near Mumbai and Chennai create demand for technical service partnerships around particle size optimization. BIS certification requirements for imported chemical raw materials favor suppliers with established Indian regulatory dossiers. The Gujarat chemical belt is attracting precipitation capacity investments targeting cost-sensitive waterborne architectural formulations.
Japan
Electronics-grade coatings for display and semiconductor applications specify fumed silica with sub-ppm metallic contamination thresholds. METI industrial standards for chemical substances enforce qualification protocols that lock in multi-year supplier relationships. The Kyushu semiconductor manufacturing cluster consumes ultra-high-purity grades for printed circuit board finishes and packaging applications.
Global Silica-Based Matting Agents Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical majors commanding fumed silica capacity while precipitation specialists serve cost-optimized architectural markets. The vendor base concentrates around three tiers: multinational diversified chemicals with captive raw material integration, regional precipitation specialists with flexible toll manufacturing arrangements, and application-focused formulators with embedded technical service capabilities. Dominant competitive moves include backward integration into sodium silicate production and geographic expansion through regional application center establishment.
Within the integrated chemical tier, Evonik Industries AG and Wacker Chemie AG exemplify divergent strategic positioning. Evonik leverages German R&D depth in fumed silica to occupy premium positioning in automotive and electronics specifications. Wacker Chemie anchors Bavarian manufacturing with integrated silicone-silica technology platforms spanning matting and rheology control functions. PPG Industries represents the captive consumption model, anchoring North American supply through internal coatings manufacturing demand alongside selective merchant sales.
| Leading Market Players |
|---|
| Evonik Industries AG |
| PPG Industries |
| Wacker Chemie AG |
| W. R. Grace & Co.-Conn. |
| BASF SE |
| BYK Additives & Instruments |
| Lubrizol Corporation |
| Imerys |
| PQ Corporation |
| Others |
Supply & Pricing Matrix
Sodium silicate feedstock costs cascade through three distinct pricing tiers, with energy-intensive precipitation processes in Germany and China compressing margins at the economy-grade architectural paint level while fumed silica producers in Bavaria and Japan maintain premium positioning through captive raw material integration and technical service bundling.
Pricing Analysis
Distributor margins of 12-18 percent separate standard-grade precipitated silica from direct-to-OEM fumed silica contracts, with price differentiation resting on REACH registration status and particle size distribution certification. Three-tier pricing structure across premium, standard, and economy levels reflects automotive clearcoat specifications, electronics-grade ionic purity thresholds, and cost-per-unit-gloss-reduction targets in architectural formulations. Pricing pressure stems from organic polymer matting agent substitution in high-build paints, with construction sector buyers exhibiting highest price sensitivity and semiconductor manufacturers showing least elasticity due to contamination risk aversion.
Supply Chain Analysis
Dual-sourcing requirements from Tier-one automotive coatings manufacturers in Stuttgart and Wolfsburg mandate qualification of at least two silica suppliers per production site, dispersing procurement across German precipitation specialists and Japanese fumed silica producers. Raw material dependencies center on sodium silicate from Gulf Coast petrochemical corridors, metallurgical-grade silicon from Norway and Brazil, and natural gas feedstocks for flame hydrolysis operations. Single-source vulnerability concentrates in electronics-grade fumed silica, where flame hydrolysis capacity locks into integrated chemical majors. Distribution runs through direct technical service partnerships for automotive OEMs and regional chemical distributors for mid-scale architectural formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive low-VOC mandates across German and Chinese manufacturing bases provide durable demand underpinning, positioning silica-based matting agents as a stable compounder with specification-grade pricing power.
For Market Incumbents: Deepen backward integration into sodium silicate production to defend margin position against feedstock volatility, while expanding regional application centers in India's Gujarat chemical belt to capture technical service premiums from domestic paint capacity additions. Organic polymer substitution in high-build architectural coatings and mid-scale precipitated silica producers with incomplete REACH dossiers represent the primary threats requiring defensive positioning. For New Entrants and Emerging Players: The price-point gap between premium fumed silica and economy precipitated grades creates white-space opportunity in surface-modified precipitated silica for waterborne industrial wood coatings, where Italian and Polish furniture manufacturers seek proven dispersion compatibility without electronics-grade contamination premiums. Target toll manufacturing partnerships with established regulatory dossiers rather than greenfield capacity investments, leveraging existing precipitation infrastructure in China's Yangtze River Delta. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale precipitated silica producers face simultaneous EPA TSCA Section 5 notification burdens, ECHA nanomaterial reporting obligations, and China MEE filing requirements without dedicated regulatory affairs bandwidth. Acquisition candidates with pre-validated multi-jurisdiction dossiers and established technical service capabilities in automotive or cosmetics verticals offer strongest long-term viability within a five-to-ten year holding window. The signal to watch is enforcement phase-in timing for ECHA's nanomaterial guidance updates, which will accelerate supplier qualification windows and compress valuation multiples for non-compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate | Captive feedstock supply insulates margins from natural gas price volatility in German manufacturing clusters. |
| Regional Application Center Establishment | Technical service proximity accelerates dispersion optimization for automotive refinish distributors in Michigan and Ohio. |
| Surface Modification R&D Investment | Controlled hydrophobicity development targets waterborne industrial wood coating specifications in Italy and Poland. |
| Long-term Supply Agreement with OEMs | Master service contracts embedding particle optimization guidance lock in specification-grade procurement from Stuttgart clearcoat operations. |
| Green Manufacturing Transition | Renewable energy sourcing for precipitation facilities differentiates producers in EU Green Deal embodied carbon scorecards. |
Research Methodology
Bottom-up coatings formulation modeling reconciled against top-down silica production capacity tracking forms the analytical core, combining primary interviews with plant managers at precipitation facilities, procurement leads at Tier-one automotive coatings manufacturers, distribution channel partners in European chemical wholesale networks, and technical R&D directors at fumed silica operations. Secondary validation draws from customs and trade data, Cefic and ACC industry reports, SEC 10-K filings from listed chemical majors, and ECHA registration dossier databases. Triangulation across these sources ensures volume and value estimates reflect actual procurement patterns rather than stated capacity alone.
Historical trendline analysis of automotive OEM specification adoption, cosmetics clean-label formulation shifts, and waterborne architectural paint conversion rates informs the projection framework across the analysis window. Segmentation dimensions include manufacturing process tier, end-use application rigor, regional regulatory cluster, and distribution channel complexity. CAGRs derive from fitted growth curves adjusted for enforcement timelines of REACH Article 33 downstream user obligations and China GB standards for VOC limits. Industry-specific forecast inputs incorporate automotive production cycle durations and cosmetics retailer clean-label commitment trajectories.
Caveats apply where ECHA nanomaterial reporting enforcement intensity, natural gas price volatility in German and Chinese manufacturing clusters, or organic matting agent substitution rates in high-build paints could materially shift the outlook. Deviation in automotive OEM low-VOC mandate adoption timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Flux Injection System Market
Additives
North America Paints and Coatings Additives Market
Additives
United States Betaine Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Paint Additives Market
Additives
Global Corrosion Inhibitor Market
Additives
Feed Additives Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Disodium Guanylate Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Global Carboxylic Acids Based Esters Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
Potting Mix Additives Market
Additives
Anti Crystallizing Agents Market
Additives
Propyl Gallate Market
Additives
Isobutyl Acetate Market