
 North America Extruded Polystyrene (XPS) Insulation Material Market | 2026-2036
North America Extruded Polystyrene (XPS) Insulation Material Market Size, Share, and Industry Trends Forecast 2026-2036
North America Extruded Polystyrene (XPS) Insulation Material Market Analytics
High-compressive-strength XPS grades above 40 psi is unwinding legacy commodity positioning across the North American insulation trade. Owens Corning leverages its roofing and asphalt adjacent businesses to bundle membrane and insulation packages for commercial contractors. Dow Inc. anchors the Great Lakes manufacturing corridor with resin-to-foam vertical integration that insulates feedstock cost swings. Kingspan Insulation LLC differentiates through controlled-environment panel systems that extend XPS into cold-chain and data center construction niches.
Extruded polystyrene insulation material consists of closed-cell thermoplastic foam manufactured through continuous extrusion of polystyrene resin with blowing agents, yielding moisture-resistant boards with typical thermal conductivity of 0.029 W/m·K and compressive strengths from 15 to 60 psi for load-bearing applications. The material serves primarily to reduce thermal bridging in building envelopes where moisture exposure would degrade open-cell alternatives. Flat boards dominate volume shipments across residential and light commercial channels where standardized dimensions minimize cutting waste on job sites. Foundation insulation within the Application dimension captures premium pricing relative to wall or roof categories due to below-grade moisture resistance requirements and code-mandated minimum R-values at footing depth. The Residential end user segment leads absolute consumption though Commercial and Institutional projects specify thicker boards and higher-density grades that concentrate margin pools.
The EPA's Significant New Alternatives Policy program governs blowing agent transitions while the Department of Energy's model energy codes and state-level stretch codes in California and New York ratchet minimum insulation performance. OSHA ventilation standards for spray-applied alternatives indirectly steer specification toward pre-formed XPS boards in confined retrofits. Building product certification through ICC-ES evaluation reports and NFPA 285 fire assembly testing shape market access for exterior wall applications. Stakeholders must monitor state HFC phase-down schedules and emerging embodied carbon disclosure rules that could reweight material selection criteria across public procurement.
Market Dynamics
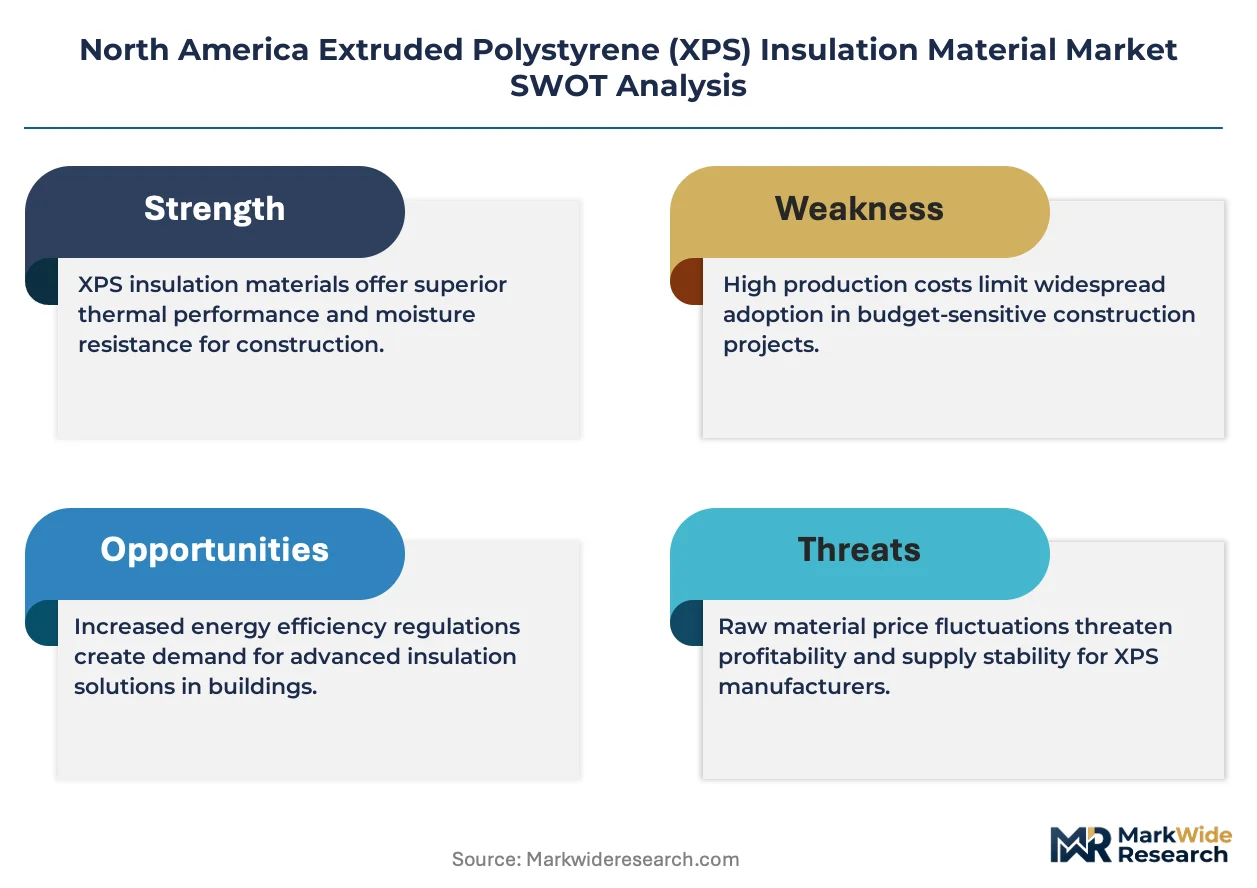
The EPA's phasedown of hydrofluorocarbon blowing agents under the AIM Act is forcing manufacturers to rebuild formulation chemistry around lower-global-warming-potential alternatives, compressing margins while opening first-mover advantages for compliant producers.
Growth Catalysts
- Energy code stringency:Texas, Florida, and California have ratcheted minimum R-value requirements for below-grade foundation systems, pulling specification toward high-compressive-strength XPS grades that resist moisture degradation.
- Residential construction permits:Single-family housing starts across the southern United States are absorbing more XPS boards for slab-edge and perimeter insulation where thermal bridging reduction is code-mandated.
- AIM Act implementation:The EPA's HFC phasedown schedule is accelerating R&D investment in hydrofluoroolefin and hydrocarbon blowing agent systems that maintain dimensional stability.
Market Restraints
- Benzene and styrene monomer volatility:Feedstock cost swings tied to Gulf Coast petrochemical capacity constrain margin predictability for non-integrated foam producers.
- Polyiso and mineral wool substitution:Commercial roofing contractors in fire-sensitive jurisdictions increasingly specify polyisocyanurate assemblies tested to NFPA 285 where XPS faces thickness penalties.
- California Title 24 friction:Embodied carbon disclosure requirements in public procurement are reweighting material selection criteria against petroleum-derived insulation in favor of bio-based alternatives.
Strategic Opportunities
- Cold-chain construction:Controlled-environment panel systems for data centers and food processing facilities extend XPS into specification-driven niches where thermal performance tolerances are tightest.
- Deep energy retrofits:The Department of Energy's Home Energy Rebate Programs under the Inflation Reduction Act channel federal incentives toward exterior wall insulation upgrades in legacy housing stock.
- Mid-rise multifamily:Type III construction in Seattle, Portland, and Vancouver is specifying thicker XPS ci-sheathing assemblies where continuous insulation mandates exceed wood-frame cavity limits.
Industry Challenges
- ICC-ES evaluation report timelines:Extended certification cycles for novel blowing agent formulations delay market access in jurisdictions requiring third-party validation of long-term thermal resistance.
- Refrigerant handling compliance:OSHA ventilation standards for hydrocarbon-based blowing agents require capital-intensive plant retrofits that smaller extruders struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Extruded Polystyrene (XPS) Insulation Material Market |
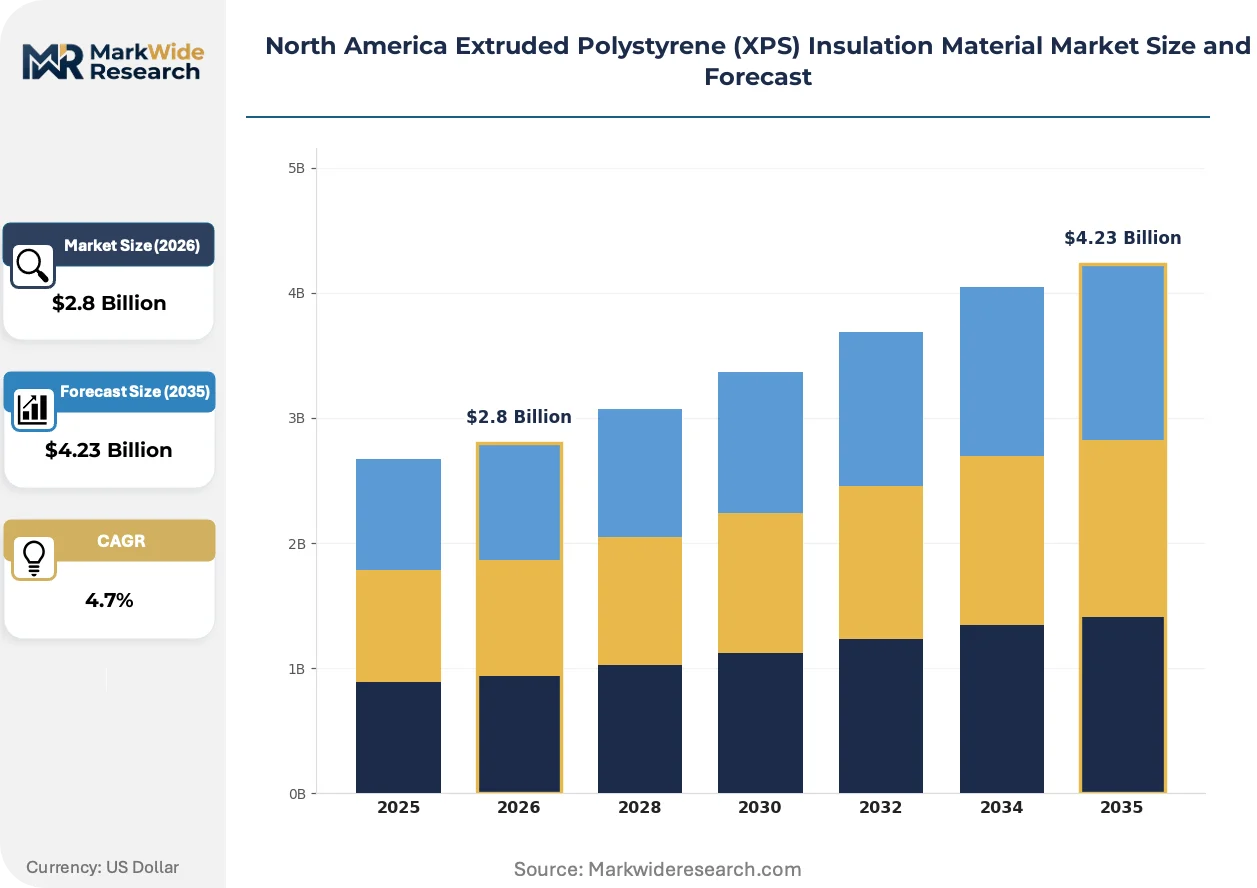
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Boards, Specialty Panels, Rigid Sheets, Foam Blocks Application: Wall Insulation, Roof Insulation, Foundation Insulation, HVAC Insulation End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Direct Sales, Wholesalers, Retailers, Online Platforms |
| Companies Covered | Owens Corning, Dow Inc., DuPont de Nemours, Inc., Kingspan Insulation LLC, Saint-Gobain North America, BASF Corporation, Rmax Operating LLC, Pactiv Evergreen Inc., Insulation Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Extruded Polystyrene (XPS) Insulation Material Market Evolving Landscape
Formulation chemistry and procurement patterns are diverging as regulatory deadlines harden and buyer sophistication increases. Three developments are compressing legacy positioning.
Carbon dioxide and hydrofluoroolefin hybrid blowing systems are displacing legacy HFC-134a formulations in continuous extrusion lines. Owens Corning and Dow Inc. have retrofitted Great Lakes and Gulf Coast plants to run next-generation chemistries that maintain 0.029 W/m·K thermal conductivity. This displacement is concentrating supply among capitalized producers capable of absorbing retooling costs.
The EPA's Significant New Alternatives Policy program governs the transition timeline for blowing agent alternatives while state-level stretch codes in New York and Washington accelerate adoption ahead of federal minimums. Manufacturers must maintain dual formulation capabilities to serve California's early phase-down against Texas's slower schedule. Foundation insulation grades face the tightest compliance windows due to below-grade durability testing requirements.
Specification authority is migrating from general contractors to envelope consultants who bundle continuous insulation with air barrier and cladding system warranties. This shift favors producers capable of delivering ICC-ES evaluated assemblies rather than commodity board. The trend is most visible in Pacific Northwest commercial projects where whole-building energy modeling drives material selection before bid release.
North America Extruded Polystyrene (XPS) Insulation Material Market Segmentation
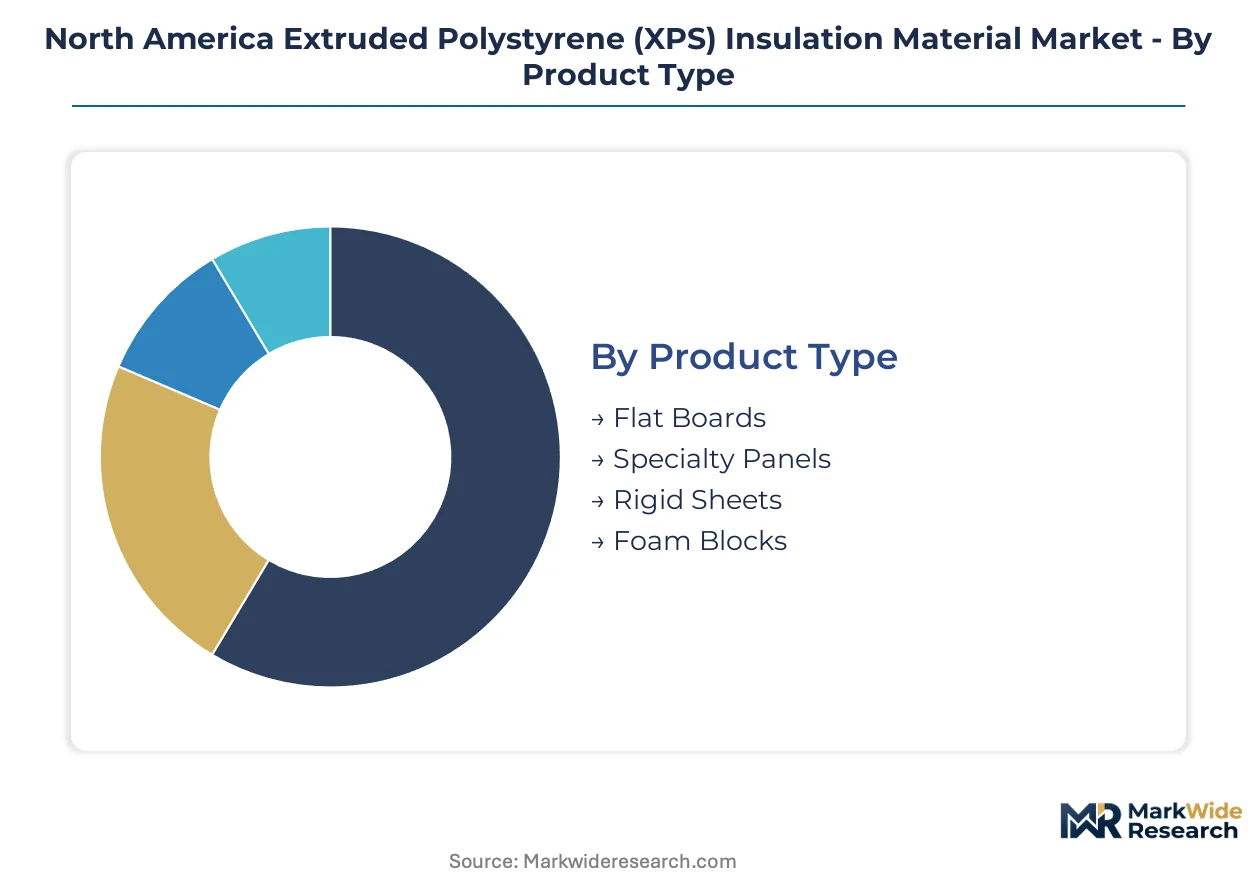
XPS insulation demand fragments across product geometries, building envelope positions, and buyer sophistication levels that dictate margin capture. Substitution threats from polyiso and mineral wool concentrate in specific application and end-user combinations, reshaping where extruded polystyrene defends its specification position.
Product Type:
Flat boards face the most intense substitution pressure from polyiso in commercial roofing assemblies, while specialty panels command defensible niches where dimensional precision outweighs cost competition.
- Flat Boards:Continuous extrusion yields standardized 2x8 and 4x8 foot dimensions with compressive strengths from 15 to 40 psi. Residential foundation contractors in Texas and Florida specify these for below-grade perimeter insulation where moisture resistance trumps first-cost sensitivity.
- Specialty Panels:Tongue-and-groove edges, ship-lap profiles, and pre-scored folding configurations serve data center and cold-chain construction. Controlled-environment projects in California specify these for thermal bridge elimination at panel joints.
- Rigid Sheets:Thin-gauge 1-inch and 1.5-inch thicknesses target cavity wall retrofits where space constraints limit insulation depth.
- Foam Blocks:Custom-cut geometries for ICF systems and geofoam applications in highway and civil construction.
Flat boards retain volume leadership; specialty panels hold the steepest expansion curve.
Application:
Foundation insulation commands the widest pricing premium due to below-grade durability testing requirements that polyiso and mineral wool struggle to satisfy.
- Foundation Insulation:Below-grade boards resist ground moisture and hydrostatic pressure with compressive strengths above 40 psi. Energy codes in California and New York mandate minimum R-values at footing depth that pull specification toward XPS.
- Wall Insulation:Continuous exterior sheathing in mid-rise multifamily construction faces NFPA 285 fire assembly testing where mineral wool captures share in Type III buildings.
- Roof Insulation:Commercial roofing assemblies specify tapered crickets and thermal barriers where polyiso's higher R-value per inch erodes XPS positioning in fire-sensitive jurisdictions.
- HVAC Insulation:Pre-formed duct board and plenum liners serve mechanical contractors in southern states where humidity control drives closed-cell requirements.
Foundation insulation captures the highest margin pool; wall insulation is climbing fastest on mid-rise multifamily code mandates.
End User:
Commercial and institutional buyers concentrate specification authority with envelope consultants who bundle continuous insulation into system warranties, compressing commodity board margins.
- Residential:Single-family builders in Texas, Florida, and California absorb volume shipments for slab-edge and basement insulation. Permit velocity in these states drives absolute consumption.
- Commercial:Office and retail developers specify thicker boards and higher-density grades through design-build contracts that concentrate procurement with national distributors.
- Industrial:Food processing and pharmaceutical facilities in the Great Lakes corridor demand controlled-environment panel systems with tight thermal performance tolerances.
- Institutional:K-12 and university projects in Washington and Oregon face stretch code requirements that accelerate adoption ahead of federal minimums.
Residential commands absolute volume; institutional procurement is expanding most quickly on public-sector embodied carbon disclosure rules.
Distribution Channel:
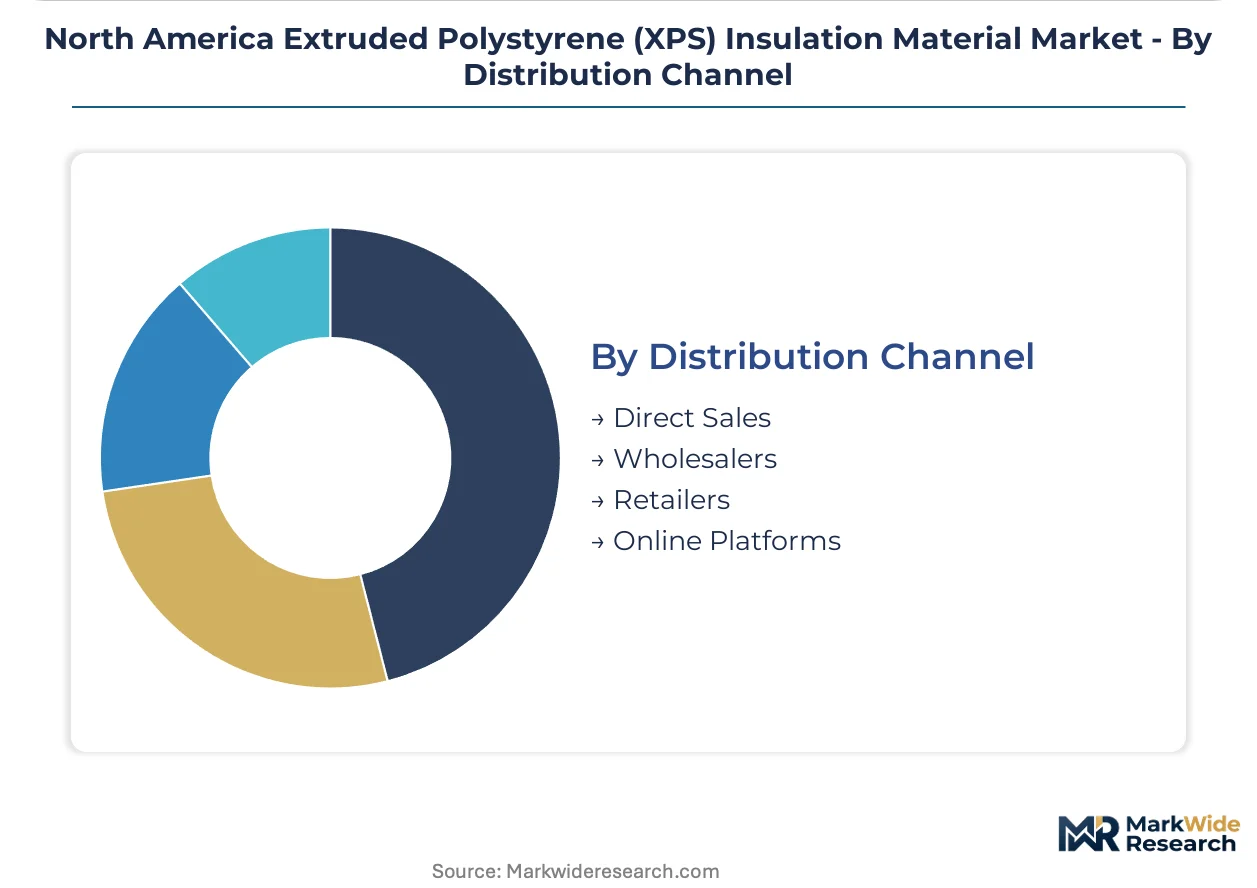
Channel selection correlates with buyer scale and specification complexity, with direct sales capturing the most technically demanding projects.
- Direct Sales:Manufacturers serve national homebuilders and commercial contractors with project-specific logistics and ICC-ES documentation bundles.
- Wholesalers:Regional distributors stock standard dimensions for residential contractors in fast-growth southern markets.
- Retailers:Big-box and specialty building material outlets serve renovation and repair demand with limited SKU depth.
- Online Platforms:E-commerce channels capture small-project buyers and remote geographies with extended delivery timelines.
Direct sales anchor the highest-value transactions; online platforms are gaining share fastest among renovation contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters along the Great Lakes and Gulf Coast corridors where resin supply and extrusion infrastructure overlap. Texas, Florida, and California absorb the bulk of demand growth driven by energy code escalation and residential permit velocity.
United States
Southern states dominate consumption as below-grade foundation systems absorb high-compressive-strength grades. The EPA's AIM Act HFC phasedown compels Gulf Coast extruders to retool for hydrofluoroolefin formulations. Dallas-Fort Worth and Houston anchor distribution networks serving residential contractors across the Sun Belt.
Canada
Cold-climate construction specifications favor XPS for frost-protected shallow foundations and below-slab insulation. Natural Resources Canada's energy code updates tighten thermal envelope requirements in Ontario and Quebec. The Greater Toronto Area concentrates demand for mid-rise multifamily continuous insulation assemblies.
Mexico
Industrial construction in Nuevo León and Mexico City Metro drives specification for controlled-environment panel systems. The country's national environmental regulator advances building energy efficiency standards that align with North American trade integration. Monterrey-based distributors serve cross-border manufacturing facilities with cold-chain insulation packages.
Pacific Northwest
Stretch codes in Washington and Oregon accelerate adoption ahead of federal minimums for mid-rise Type III construction. Seattle and Portland specify thicker continuous insulation sheathing where wood-frame cavity limits fall short of mandates. The region's envelope consultants bundle XPS into system warranties that concentrate procurement authority.
North America Extruded Polystyrene (XPS) Insulation Material Market Competitive Landscape
Concentration sits with integrated resin-to-foam producers and specialty panel system fabricators. The vendor base splits between commodity board extruders serving residential channels and specification-grade suppliers targeting commercial envelope consultants. Two archetypes dominate: vertically integrated chemical conglomerates with captive styrene supply, and building envelope specialists bundling insulation with air barrier warranties. Competitive moves center on formulation retooling for HFC compliance and geographic densification in fast-growth southern markets.
Among integrated chemical producers, Dow Inc. and BASF Corporation exemplify the resin-backed archetype with upstream control over feedstock costs. Owens Corning occupies a position bridging commodity and specification tiers through adjacent roofing and asphalt businesses that enable bundled membrane-insulation packages. Kingspan Insulation LLC represents the envelope-specialist vector, anchoring controlled-environment niches where thermal performance tolerances are tightest.
| Leading Market Players |
|---|
| Owens Corning |
| Dow Inc. |
| DuPont de Nemours, Inc. |
| Kingspan Insulation LLC |
| Saint-Gobain North America |
| BASF Corporation |
| Rmax Operating LLC |
| Pactiv Evergreen Inc. |
| Insulation Corporation of America |
| Others |
Value Network & Pricing Analysis
Sixty-day order-to-delivery windows for high-compressive-strength foundation grades concentrate pricing power with Gulf Coast and Great Lakes extruders who maintain captive styrene supply. This lead-time band tightens when EPA AIM Act compliance deadlines accelerate, forcing buyers toward qualified suppliers with validated ICC-ES reports and hydrofluoroolefin formulation capabilities.
Pricing Analysis
The EPA's AIM Act phasedown schedule dictates the pricing tier structure across the North American XPS trade. Three-tier pricing structure across premium, standard, and economy levels separates ICC-ES validated HFO-compliant boards from legacy HFC formulations and uncertified commodity grades. Price differentiation hinges on certification level and volume scale, with national homebuilders capturing standard-tier discounts against envelope consultants specifying premium validated assemblies. Cost compression in economy-tier flat boards is intensifying because polyiso substitution in commercial roofing erodes XPS positioning. Residential contractors in Texas and Florida exhibit highest price sensitivity, while data center developers specifying controlled-environment panels show least.
Supply Chain Analysis
Gulf Coast petrochemical corridor chokepoints underwrite North American XPS feedstock security, with benzene and styrene monomer flows tethered to Houston Ship Channel throughput and Corpus Christi export terminal capacity. Manufacturing draws from United States, Canada, and Mexico production bases, with resin supply resting on Texas and Louisiana crackers, Ontario aromatics complexes, and Altamira petrochemical infrastructure. Raw material dependencies span polystyrene resin, hydrofluoroolefin blowing agents, and flame-retardant additives. Single-source vulnerability concentrates in HFO blowing agent supply where limited global producers constrain formulation flexibility. Distribution runs through regional wholesalers serving Sun Belt residential contractors and direct sales channels capturing commercial envelope specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
First-mover advantage in hydrofluoroolefin formulation chemistry has compressed to a narrow window, rewarding producers who secured ICC-ES validation ahead of state-level phase-down deadlines. The capability gap sits with capital-intensive plant retrofits and dual-formulation flexibility to serve fragmented regulatory timelines.
For Market Incumbents: Consolidate specification authority by embedding XPS into envelope system warranties that bundle continuous insulation with air barrier and cladding packages. Acquire or partner with regional distributors in Texas and Florida to lock residential channel access before permit velocity peaks. Defend against polyiso substitution in commercial roofing by emphasizing below-grade durability testing where mineral wool and polyiso fail moisture resistance standards. For New Entrants and Emerging Players: Anchor in cold-chain construction niches where controlled-environment panel systems command specification-driven procurement with tight thermal performance tolerances. Target data center and food processing verticals in California and the Great Lakes corridor where envelope consultants bundle insulation into system warranties. Pursue go-to-market partnerships with national distributors lacking technical sales capability for specialty panel geometries. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because AIM Act compliance costs will strand sub-scale extruders without HFO retrofit capital or dual-formulation capabilities. Acquisition targets include regional foam producers with validated ICC-ES reports and established wholesale relationships in fast-growth southern markets. Watch state HFC phase-down acceleration as the inflection signal that compresses valuation multiples for non-compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Styrene Monomer | Captive feedstock supply insulates margin volatility from Gulf Coast petrochemical swings. |
| HFO Formulation Retrofit | EPA AIM Act compliance secures market access in California and New York ahead of federal deadlines. |
| ICC-ES Evaluation Report Investment | Third-party validation unlocks specification in jurisdictions requiring documented long-term thermal resistance. |
| Envelope System Warranty Bundling | Continuous insulation plus air barrier packages migrate procurement authority from contractors to consultants. |
| Cold-Chain Panel System Expansion | Data center and food processing niches defend margin pools against commodity board price erosion. |
Research Methodology
The analysis maps flat board, specialty panel, rigid sheet, and foam block sub-sectors, each validated through extrusion plant managers, residential contractor procurement leads, commercial envelope consultants, and regional distribution channel partners. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, American Chemistry Council resin production data, EPA Significant New Alternatives Policy program documentation, and state energy code adoption tracking. Bottom-up shipment estimates by product geometry and application triangulated against top-down construction spending and housing permit flows.
Consistency checks validated volume and value outputs against external benchmarks including Department of Energy model energy code adoption timelines and single-family housing start projections. The analytical framework modeled product type, application, end user, and distribution channel dimensions across the projection horizon. CAGRs derived from regression-based demand elasticity to construction activity and code stringency indices. Forecast inputs incorporated HFC phasedown schedules and thermal conductivity performance requirements for below-grade applications.
Decision-makers should treat outputs as directional under assumptions of steady AIM Act implementation and sustained southern U.S. residential permit velocity; material deviation in regulatory timelines or construction activity would warrant model refresh. Practitioners should keep alternative scenarios live as state-level stretch code adoption and embodied carbon disclosure rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Fire Retardant Flexible Cable Market
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Thin Insulation Market
Insulation Materials
Global High Temperature Insulation Materials Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Mineral Wool Insulation Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
Global Electrical Insulation Materials Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
Roofing Underlying Materials Market