
 Nanoporous Membranes Market | 2026-2036
Nanoporous Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoporous Membranes Market Intelligence
Membrane-as-a-service and predictive maintenance contracts is broadening revenue models beyond hardware sales. DuPont de Nemours Inc. leverages its fluoropolymer chemistry heritage to dominate high-performance reverse osmosis modules. TORAY INDUSTRIES, INC. anchors Asian supply chains through integrated polymer spinning and module assembly operations. Koch Separation Solutions specializes in custom-engineered systems for chemical processing clients with extreme pH and temperature requirements.
Nanoporous membranes are synthetic barriers with pore dimensions typically below 100 nanometers, fabricated from polymeric, ceramic, or composite substrates via phase inversion, sintering, or atomic layer deposition, and function to selectively separate molecules based on size exclusion, charge interaction, or adsorption affinity in liquid and gas streams. Polymeric membranes occupy the largest installed base due to lower capital cost and manufacturing flexibility, though ceramic variants command premium positioning in high-temperature and chemically aggressive environments. Water purification applications lead volume demand, while gas separation represents the fastest-expanding margin pool as hydrogen economy infrastructure scales.
EPA regulations under the Safe Drinking Water Act and EU REACH compliance frameworks shape material selection and end-of-life disposal protocols for membrane manufacturers serving North American and European utilities. China's MEE enforces discharge standards that drive ceramic membrane adoption in industrial wastewater treatment. India's CPCB mandates for zero liquid discharge plants accelerate demand for integrated ultrafiltration and reverse osmosis trains. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that threaten incumbent fluoropolymer membrane chemistries and create openings for bio-based and inorganic alternatives.
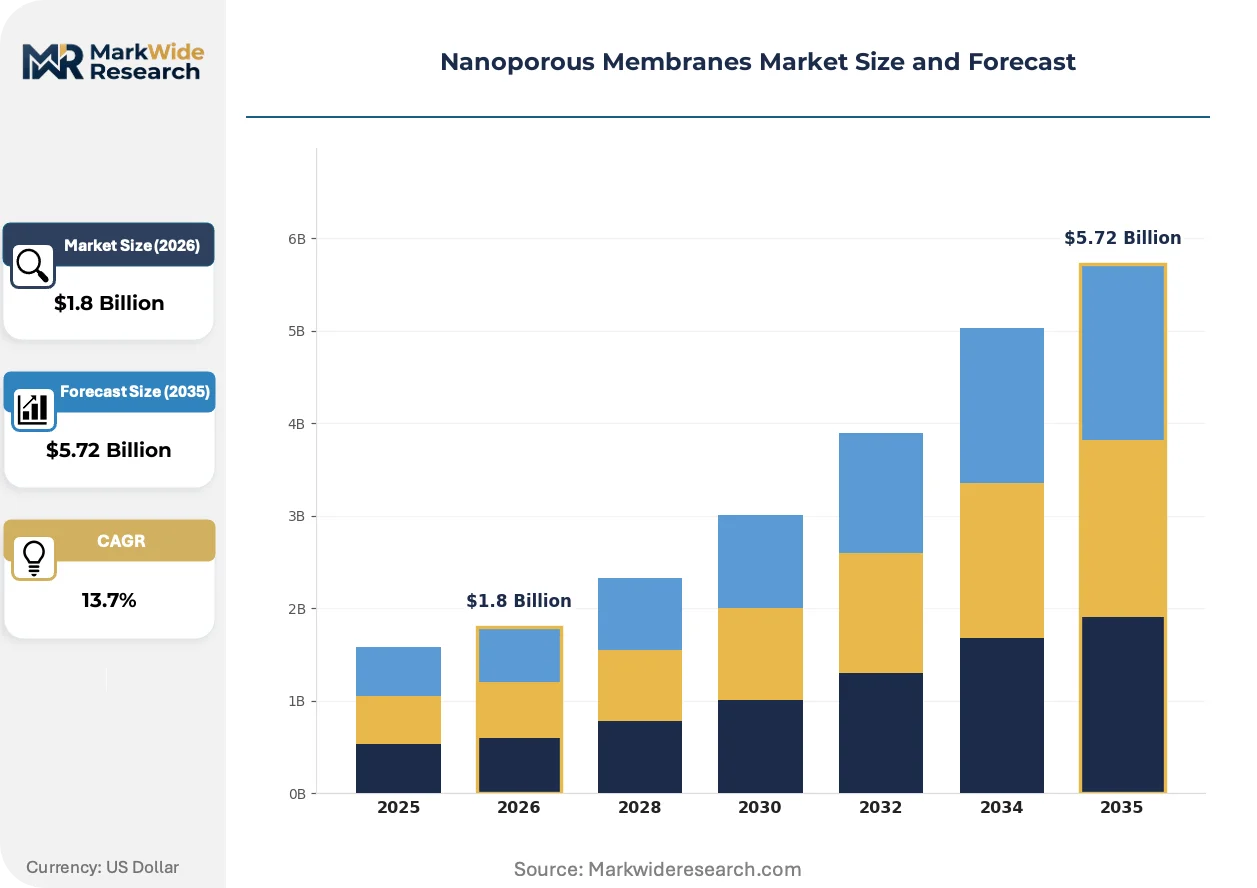
Market Dynamics
Stricter EPA and EU drinking water directives are compressing replacement cycles for conventional filtration infrastructure, forcing utilities toward ceramic and polymeric membrane systems with superior contaminant rejection.
Growth Catalysts
- Zero Liquid Discharge Mandates:India's CPCB regulations for industrial effluent treatment are accelerating integrated ultrafiltration-reverse osmosis train deployments across chemical processing clusters.
- Hydrogen Economy Buildout:Gas separation applications for hydrogen purification are pulling advanced nanoporous ceramic membranes into electrolyzer and fuel cell supply chains.
- REACH Compliance Deadlines:EU restrictions on per- and polyfluoroalkyl substances are creating replacement demand for bio-based and inorganic membrane chemistries in municipal water utilities.
Market Restraints
- Fluoropolymer Feedstock Concentration:Specialty fluoropolymer resin supply concentrates among a handful of chemical producers, exposing membrane manufacturers to input cost volatility and allocation risk.
- Ceramic Sintering Energy Intensity:High-temperature kiln operations for alumina and titania membranes carry substantial natural gas exposure, compressing margins when energy markets tighten.
- Incumbent PFAS Chemistry Lock-in:Decades of validation data for fluoropolymer membranes create regulatory friction for novel material substitutions, extending certification timelines.
Strategic Opportunities
- Membrane-as-a-Service Models:Predictive maintenance contracts and performance-guarantee leasing are opening recurring revenue streams beyond capital equipment sales in North American municipal markets.
- Atomic Layer Deposition Scaling:Precision coating techniques for tunable pore architectures are converging with roll-to-roll manufacturing, enabling cost-competitive thin-film composite production.
- Industrial Wastewater Retrofit Programs:China's MEE enforcement of discharge standards in steel and textile corridors is creating white space for ceramic membrane system integrators.
Industry Challenges
- Specialized Membrane Fabrication Talent:Phase inversion and interfacial polymerization expertise resides among a narrow cohort of process engineers, constraining production scaling.
- Multi-Train Integration Complexity:Ultrafiltration-reverse osmosis-nanofiltration sequencing for zero liquid discharge plants demands sophisticated controls integration with legacy distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoporous Membranes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Membranes, Ceramic Membranes, Metal Membranes, Composite Membranes Application: Filtration, Gas Separation, Water Purification, Desalination End User: Healthcare, Water Treatment, Food & Beverage, Chemical Processing Technology: Ultrafiltration, Nanofiltration, Reverse Osmosis, Microfiltration |
| Companies Covered | Alfa Laval AB, Applied Membranes Inc., AXEON Water Technologies Inc., DuPont de Nemours Inc., Koch Separation Solutions, inopor GmbH, Hunan Keensen Technology Co. Ltd, BASF SE, TORAY INDUSTRIES, INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoporous Membranes Market Strategic Shifts & Innovations
Material science advances and service model reinvention are restructuring how membrane value is captured, with chemistry, manufacturing process, and commercial terms evolving in parallel.
Graphene oxide and metal-organic framework membranes are expanding into desalination pre-treatment and pharmaceutical separations where conventional polyamide thin-film composites face fouling limitations. Water utilities in Australia and Singapore are piloting these materials for brackish water reverse osmosis trains. The technology is expanding into premium positioning where operational reliability justifies unit cost premiums over commodity polymeric alternatives.
EU F-Gas Regulation phase-down schedules are accelerating membrane material transitions in heating, ventilation, and air conditioning heat pump applications. Manufacturers must reformulate gas-selective barriers away from high-global-warming-potential fluorinated chemistries. The policy is compressing development timelines for hydrofluoroolefin-compatible and hydrocarbon-selective membrane architectures in German and French industrial refrigeration supply chains.
Performance-based contracting is displacing traditional capital purchase models among large industrial water users seeking to offload operational risk. Chemical processors and power generators in the United States are signing throughput-guarantee agreements with membrane system providers. The shift concentrates vendor selection criteria on demonstrated uptime metrics rather than initial equipment cost, favoring suppliers with predictive analytics capabilities and regional service infrastructure.
Nanoporous Membranes Market Segmentation
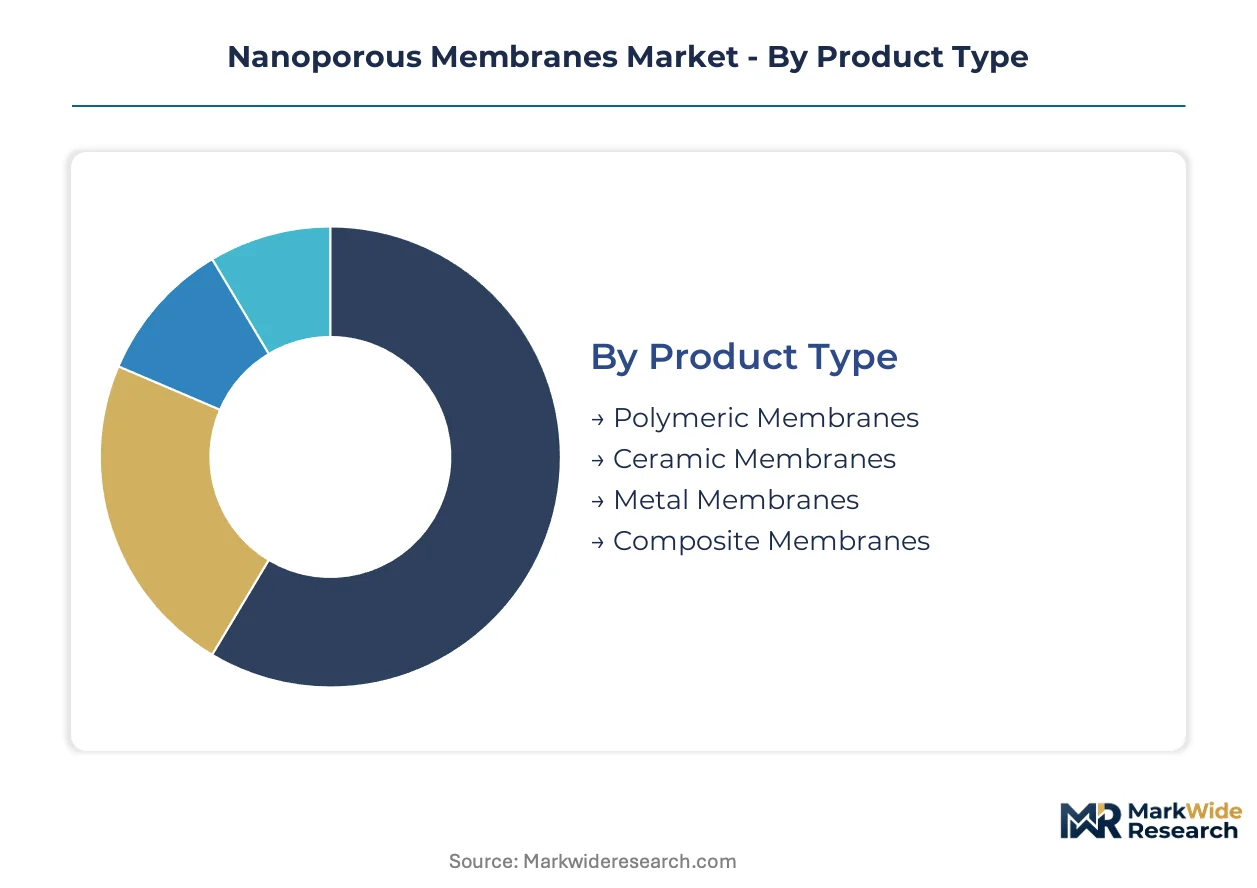
Membrane buyers select products through fundamentally different technical and economic lenses depending on their operational environment. Material chemistry, pore architecture, and separation mechanism each create distinct procurement criteria that suppliers must address through specialized positioning.
Product Type:
Cost tier separates buyers seeking capital efficiency from those prioritizing operational longevity in aggressive process conditions.
- Polymeric Membranes:Phase-inverted or interfacially polymerized thin films deliver the lowest installed cost per square meter of membrane area. Municipal utilities in India and Germany specify these for large-scale desalination trains where replacement economics favor disposable modules over extended service life.
- Ceramic Membranes:Sintered alumina, titania, or zirconia structures withstand pH extremes and thermal cycling beyond polymer limits. China's steel and textile corridors under MEE discharge enforcement are retrofitting ceramic ultrafiltration systems for industrial wastewater where chemical compatibility and thermal sterilization are mandatory.
- Metal Membranes:Porous stainless steel or nickel substrates serve specialized applications requiring mechanical robustness and electrical conductivity.
- Composite Membranes:Hybrid architectures combine selective layers with structural supports to optimize permeability and rejection simultaneously.
Volume sits with polymeric membranes; growth tilts toward ceramic membranes.
Application:
Application selection tracks the contaminant class and separation driving force required by the process stream.
- Water Purification:Ultrafiltration and nanofiltration trains remove particulates, pathogens, and dissolved organics from surface and groundwater sources. United States utilities under EPA Safe Drinking Water Act revisions are replacing granular media filters with membrane barriers for cryptosporidium and virus log removal.
- Gas Separation:Ceramic and polymer membranes separate hydrogen, carbon dioxide, and hydrocarbon streams based on molecular size and solubility differences. Electrolyzer manufacturers in Germany are qualifying nanoporous ceramic barriers for high-purity hydrogen production as the hydrogen economy scales.
- Filtration:Cross-flow and dead-end configurations clarify process streams across pharmaceutical and food processing operations.
- Desalination:Reverse osmosis and emerging forward osmosis systems reduce salinity for municipal and industrial water supply.
Water purification commands current installed base; gas separation is climbing the fastest.
End User:
End-user procurement patterns diverge between regulated utilities with long capital cycles and industrial processors with operational risk tolerance.
- Water Treatment:Municipal and industrial utilities specify membranes through competitive bidding with total cost of ownership evaluation. India's CPCB zero liquid discharge mandates are accelerating integrated membrane train deployments across chemical processing clusters.
- Chemical Processing:Specialty chemical and petrochemical producers demand custom-engineered systems for solvent recovery and catalyst retention. Koch Separation Solutions and comparable integrators configure membranes for extreme pH and temperature requirements in these accounts.
- Healthcare:Pharmaceutical manufacturing and medical device applications require validated sterile filtration with extractables documentation.
- Food & Beverage:Dairy, beverage, and ingredient processors employ membranes for concentration, clarification, and fractionation without thermal damage.
Water treatment absorbs the highest membrane volume; chemical processing delivers the steepest expansion trajectory.
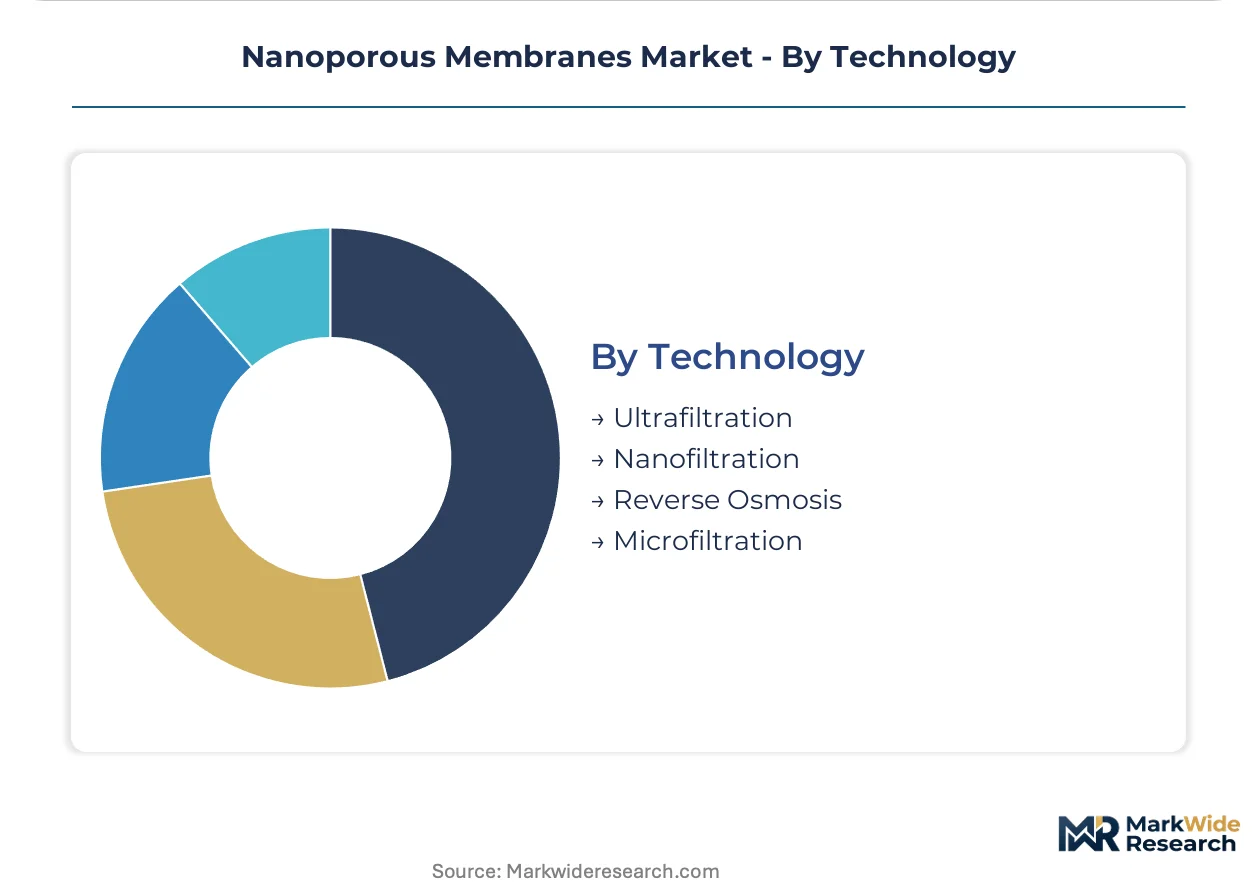
Technology:
Technology selection maps directly to the molecular weight cutoff or ion rejection specification demanded by the separation target.
- Reverse Osmosis:Dense polyamide thin-film composites reject dissolved salts and small organics through solution-diffusion transport. DuPont de Nemours leverages fluoropolymer chemistry heritage to dominate high-performance modules for seawater and brackish desalination.
- Ultrafiltration:Porous membranes with 1-100 nanometer pores retain macromolecules, colloids, and biological contaminants. TORAY INDUSTRIES anchors Asian supply chains through integrated polymer spinning and module assembly for this technology tier.
- Nanofiltration:Intermediate rejection between ultrafiltration and reverse osmosis targets divalent ions and organic micropollutants.
- Microfiltration:Largest pore size category removes suspended solids and bacteria in pre-treatment and clarification duties.
Reverse osmosis holds the largest revenue base; ultrafiltration is gaining share fastest in industrial retrofit applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian polymer spinning corridors while consumption tilts toward water-stressed industrial clusters in Germany, the United States, and India. Ceramic membrane fabrication clusters in Japan and Germany supply high-temperature systems to chemical processors worldwide. Polymeric module assembly scales fastest in China and South Korea to serve municipal desalination and industrial retrofit demand.
United States
Water utilities under EPA Safe Drinking Water Act revisions are replacing granular media filters with membrane barriers for cryptosporidium and virus log removal. The EPA's enforcement of stricter contaminant limits accelerates replacement cycles for conventional filtration infrastructure. Municipal procurement concentrates in California and Texas desalination corridors where brackish water reverse osmosis trains expand capacity.
Germany
Electrolyzer manufacturers are qualifying nanoporous ceramic barriers for high-purity hydrogen production as the hydrogen economy scales. EU REACH compliance deadlines and F-Gas Regulation phase-downs force material transitions away from fluorinated chemistries. Industrial membrane demand clusters in the Ruhr region and Bavarian chemical corridors where zero liquid discharge systems retrofit existing effluent treatment.
China
Steel and textile processors under MEE discharge enforcement are retrofitting ceramic ultrafiltration systems for industrial wastewater where chemical compatibility is mandatory. The Ministry of Ecology and Environment tightens effluent standards across manufacturing corridors. Procurement concentrates in the Yangtze River Delta and Pearl River Delta where integrated membrane train deployments accelerate.
India
Chemical processing clusters deploy integrated ultrafiltration-reverse osmosis trains to meet CPCB zero liquid discharge mandates for industrial effluent treatment. The Central Pollution Control Board enforces stricter discharge standards across Gujarat and Maharashtra industrial zones. Municipal desalination projects in Tamil Nadu and Karnataka drive polymeric membrane volume for coastal cities facing freshwater scarcity.
Japan
Integrated polymer spinning and module assembly operations anchor Asian supply chains for ultrafiltration technology tiers. METI supports hydrogen economy infrastructure buildout that pulls advanced nanoporous ceramics into electrolyzer supply chains. Manufacturing concentrates in the Kansai and Chubu regions where precision coating techniques converge with roll-to-roll production.
Nanoporous Membranes Market Key Industry Players
Capital-heavy producers compete with asset-light designers across membrane chemistry and module assembly. The vendor base separates into integrated polymer spinners, ceramic sintering specialists, and system integration houses. Three archetypes dominate: diversified materials conglomerates with fluoropolymer heritage, focused membrane technology pure-plays, and custom-engineered system integrators. Competitive moves concentrate on backward integration into specialty resin supply and predictive maintenance service model expansion.
Among diversified materials conglomerates, DuPont de Nemours Inc. and BASF SE occupy positions leveraging polymer chemistry heritage into high-performance module supply. TORAY INDUSTRIES, INC. exemplifies the integrated Asian producer archetype with captive polymer spinning through module assembly. Koch Separation Solutions represents the custom-engineered system integrator model serving chemical processors with extreme operating condition requirements.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Applied Membranes Inc. |
| AXEON Water Technologies Inc. |
| DuPont de Nemours Inc. |
| Koch Separation Solutions |
| inopor GmbH |
| Hunan Keensen Technology Co. Ltd |
| BASF SE |
| TORAY INDUSTRIES, INC. |
| Others |
Cost & Logistics Intelligence
Phase inversion and interfacial polymerization expertise concentrated in Japan and Germany widens pricing-tier spreads between commodity polymeric modules and precision-engineered ceramic systems, as labor-cost differentials compound raw material premiums.
Pricing Analysis
Cost-down pressure on standard polymeric membranes accelerates because Chinese manufacturers are scaling roll-to-roll production for municipal desalination tenders. Three-tier pricing structure across premium ceramic, standard polyamide thin-film composite, and economy polyethersulfone modules reflects performance certification grade and after-sales service bundling. Pricing pressure stems from fluoropolymer feedstock allocation risk squeezing margins on high-performance reverse osmosis modules. Municipal utilities in India exhibit highest price sensitivity through competitive bidding, while German chemical processors prioritize total cost of ownership over unit capital cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German ceramic sintering specialists for high-temperature alumina and titania membrane substrates. Manufacturing concentrates in China for polymeric module assembly, South Korea for precision coating equipment, and Japan for advanced polymer spinning. Raw material dependencies include specialty fluoropolymer resins, high-purity alumina powders, and precision coating chemicals. Tariff exposure on ceramic substrates shipped to North American utilities threatens cost competitiveness. Distribution runs through system integrators and direct OEM relationships with water treatment EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanoporous membranes market sits in a technology-transition phase as ceramic and metal-organic framework materials displace legacy fluoropolymer chemistries under tightening EU and EPA substance restrictions.
For Market Incumbents: Cement fluoropolymer chemistry positions through backward integration into specialty resin supply before REACH compliance deadlines force material transitions. Invest in atomic layer deposition scale-up to defend premium positioning against emerging graphene oxide competitors. Prioritize predictive maintenance service contracts to lock in municipal utility replacement cycles.
For New Entrants and Emerging Players: Capture white space in China's industrial wastewater retrofit corridor where MEE enforcement outpaces local ceramic membrane fabrication capacity. Target India's zero liquid discharge mandate deployments through membrane-as-a-service leasing models that offload operational risk from cash-constrained chemical processors. Lead with performance-guarantee contracting to bypass incumbent validation data advantages.
For Investors and Strategic Acquirers: Re-rating potential sits with atomic layer deposition equipment specialists given convergence with roll-to-roll membrane manufacturing. Long-term viability hinges on chemistry diversification away from PFAS-dependent revenue streams. Acquisition focus should center on ceramic sintering specialists with hydrogen economy qualifications. Watch for inflection in EU F-Gas Regulation enforcement timelines as signal for material transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin Supply | Secures input cost stability for DuPont and BASF ahead of REACH substance restrictions. |
| Atomic Layer Deposition Scale-Up | Enables TORAY INDUSTRIES to produce tunable pore architectures for hydrogen purification membranes. |
| Membrane-as-a-Service Launch | Transforms Koch Separation Solutions revenue toward recurring predictive maintenance contracts. |
| Ceramic Sintering Capacity Expansion | Positions inopor GmbH to capture China's MEE-driven industrial wastewater retrofit demand. |
| PFAS-Free Chemistry R&D Program | Anticipates EPA Safe Drinking Water Act revisions threatening incumbent fluoropolymer membrane lines. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with membrane module procurement managers at North American municipal utilities, technical directors at German chemical processing clusters, and plant engineers at China's steel and textile corridors combined with bottom-up validation. Secondary sources included EPA enforcement databases, EU ECHA substance restriction registers, India CPCB zero liquid discharge compliance records, and China MEE discharge standard filings. Top-down triangulation cross-checked against membrane system integrator order books and fluoropolymer resin import volumes.
Reconciliation of production capacity data, utility capital expenditure plans, and industrial effluent treatment retrofit pipelines shaped the analytical framework. Segmentation modeling tracked material chemistry tiers, application technology types, end-user industry verticals, and regional regulatory clusters across the analysis window. CAGRs derived from installed base replacement cycles, hydrogen economy infrastructure buildout curves, and zero liquid discharge mandate enforcement schedules. Industry-specific inputs included ceramic kiln natural gas cost sensitivity and fluoropolymer resin allocation risk premiums.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU F-Gas Regulation phase-down velocity and EPA PFAS substance restriction finalization. Forecasts embed assumptions around MEE enforcement consistency, hydrogen economy infrastructure commitment durability, and ceramic sintering energy cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
PVDF Membrane Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market
Membrane Materials
Nafion Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Global Ceramic Membrane Market
Membrane Materials
Polysulfone Market
Membrane Materials
Liquid Applied Membranes Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
SBS Modified Bitumen Membrane Market
Membrane Materials
North America Ceramic Membranes Market