
 Wire Insulation and Jacketing Compounds Market | 2026-2036
Wire Insulation and Jacketing Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Insulation and Jacketing Compounds Market Outlook
Cross-linked polyethylene is expanding its share of medium-voltage cable insulation as utilities seek longer service life and reduced thermal losses. Borealis GmbH leverages its Borlink technology platform to anchor European utility contracts with material traceability. Dow competes through integrated ethylene-to-compound manufacturing on the US Gulf Coast. DuPont differentiates via fluoropolymer grades that sustain performance above 150°C in aerospace harness applications.
Wire insulation and jacketing compounds are polymer formulations applied as protective layers around conductive cores, with thicknesses typically ranging from 0.25 mm to 4.0 mm depending on voltage class and environmental exposure. These compounds must achieve specified dielectric strength, abrasion resistance, and flammability ratings to ensure safe power transmission and signal integrity across operating temperatures from -40°C to 125°C or higher. Polyvinyl chloride dominates volume in building wire due to decades of formulation optimization and cost structure, while flame retardant grades command premium positioning in data center and mass transit specifications. Polyethylene compounds lead growth in submarine and renewable energy cabling where moisture resistance and dielectric properties determine system economics. Low smoke formulations are displacing conventional grades in rail and marine segments as evacuation safety standards tighten.
REACH registration requirements in Europe and RoHS substance restrictions are eliminating legacy plasticizers and heavy metal stabilizers from supply chains, forcing compounders to validate alternative chemistries through accelerated aging protocols. China's GB standards and SAMR certification processes govern halogen content and smoke density for domestic infrastructure projects, creating parallel compliance tracks for multinational suppliers. India's BIS marking mandate for cable compounds adds testing burden for imports while supporting domestic producers under PLI-linked capacity expansion. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and maintain formulation flexibility across customer portfolios.
Market Dynamics
Electric vehicle manufacturers are scaling purchases of high-temperature insulation grades, redirecting compounder R&D toward thermal stability above 150°C while REACH and RoHS compliance forces halogen-free formulation pivots across European supply chains.
Growth Catalysts
- EV Powertrain Thermal Requirements:Battery pack and motor winding applications demand cross-linked polyethylene and fluoropolymer grades that withstand sustained 150°C operation, pulling specialty compound volumes from conventional automotive wire.
- REACH Article 33 Enforcement:ECHA's Substances of Very High Concern screening is eliminating legacy phthalate plasticizers from building wire formulations, creating replacement demand for bio-based and trimellitate alternatives.
- China Renewable Grid Buildout:Domestic cable producers are expanding extrusion capacity for 220 kV and 500 kV transmission lines, concentrating medium-voltage compound procurement within state-owned utility procurement frameworks.
Market Restraints
- Ethylene Feedstock Volatility:Polyethylene compound margins compress when naphtha crackers in the US Gulf Coast and Middle East experience feedstock cost swings, forcing quarterly price renegotiations with cable producers.
- Fluoropolymer Supply Concentration:PTFE and FEP resin production clusters in Japan and select European sites, exposing aerospace harness suppliers to allocation risk during semiconductor industry demand surges.
- Legacy PVC Infrastructure Lock-in:Decades of building wire specification around plasticized PVC create technical friction for halogen-free alternatives that must match existing termination compatibility and installation handling.
Strategic Opportunities
- India PLI-Linked Cable Expansion:Domestic compounders can capture BIS-marked supply contracts as production-linked incentive schemes expand extrusion capacity for solar and railway electrification projects.
- Submarine Cable Dielectric Grades:Cross-linked polyethylene with enhanced moisture resistance is penetrating offshore wind interconnection projects, replacing mass-impregnated paper in 66 kV and 220 kV subsea links.
- EU Green Deal Procurement Mandates:Public infrastructure tenders are embedding recycled content thresholds and carbon footprint declarations, advantaging compounders with mass-balance certified polyethylene and bio-attributed PVC.
Industry Challenges
- Accelerated Aging Protocol Validation:Alternative plasticizers and stabilizers must demonstrate 25-year service life equivalence through thermal and electrical stress testing, extending new formulation qualification timelines.
- Multijurisdictional Formulation Tracking:Compounders must maintain parallel inventory streams to satisfy REACH substance restrictions, China's GB halogen standards, and India's BIS smoke density requirements without SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Insulation and Jacketing Compounds Market |
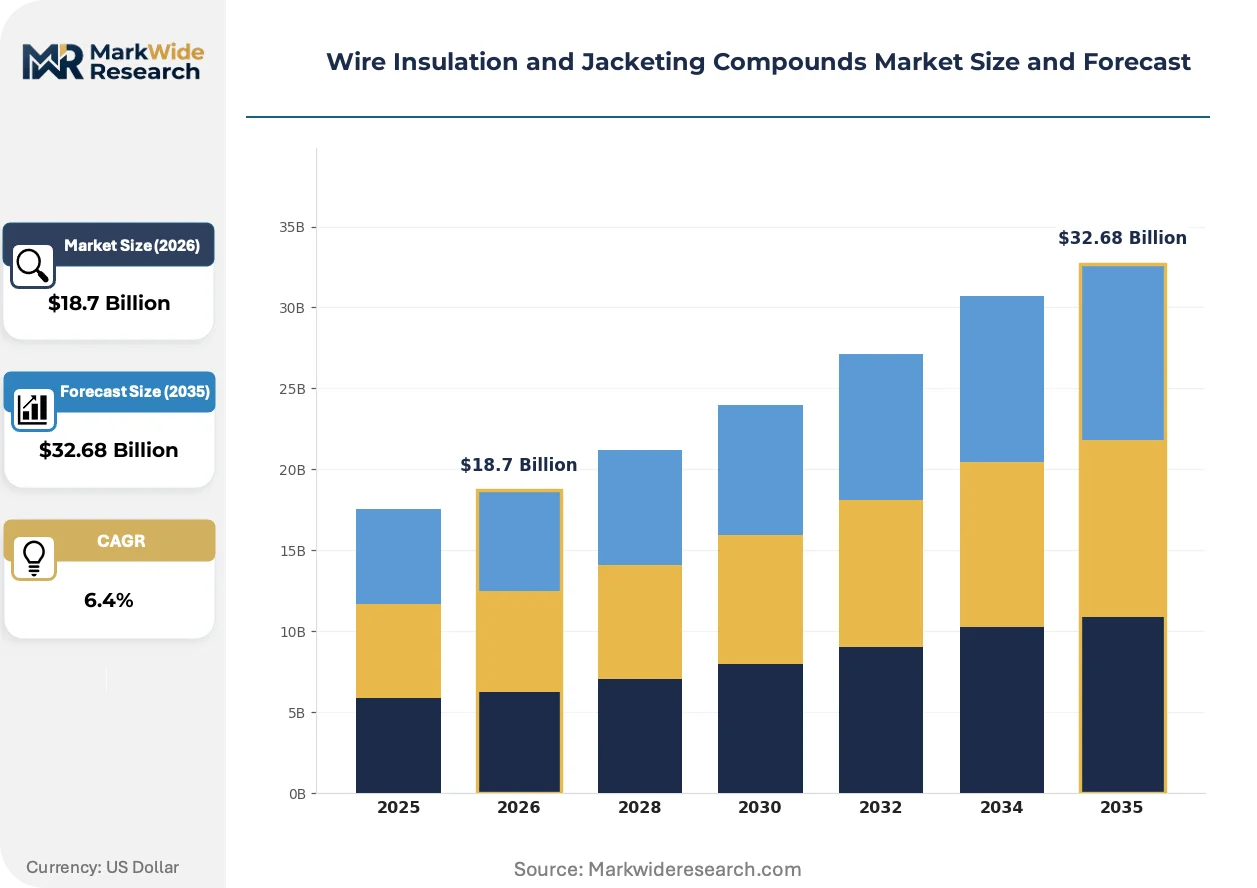
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyvinyl Chloride, Polyethylene, Rubber, Polypropylene Application: Electrical Wiring, Telecommunications, Automotive, Industrial Equipment End User: Telecom Providers, Automotive Manufacturers, Electrical Contractors, OEMs Performance Grade: Standard, Flame Retardant, Low Smoke, High Temperature |
| Companies Covered | Borealis GmbH, DuPont, Evonik Industries, Solvay, Dow, ExxonMobil, Teknor Apex, BASF SE, SCG Chemicals Public Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Insulation and Jacketing Compounds Market Strategic Shifts
Silane cross-linking chemistry and bio-attributed feedstocks are reconfiguring compound performance benchmarks and carbon accounting across utility, automotive, and renewable energy cable applications.
Silane-graft polyethylene technology enables medium-voltage cable producers to achieve moisture-resistant cross-linked structures without capital-intensive electron beam or steam-cure continuous vulcanization lines. European and Chinese utilities are specifying this material for 10 kV to 35 kV distribution networks where installation cost reduction matters. The technology is expanding into renewable energy collector systems where trench burial and direct earth contact demand enhanced water tree resistance.
REACH Annex XIV authorization requirements are phasing out medium-chain chlorinated paraffins and certain organotin stabilizers used in PVC jacketing compounds. Cable compounders are validating calcium-zinc and calcium-organic stabilizer packages through long-term thermal aging protocols. Building wire and data center cable segments face the steepest retooling burden as existing formulations lose their legal manufacturing basis.
Automotive OEMs are consolidating wire harness procurement under platform-level contracts that specify compound performance rather than supplier identity. Tier-1 harness producers must qualify multiple compound sources against identical thermal cycling and fluid resistance test matrices. This specification-driven sourcing is most pronounced in German and South Korean electric vehicle programs where single-source supply risk carries heavy liability exposure.
Wire Insulation and Jacketing Compounds Market Segmentation
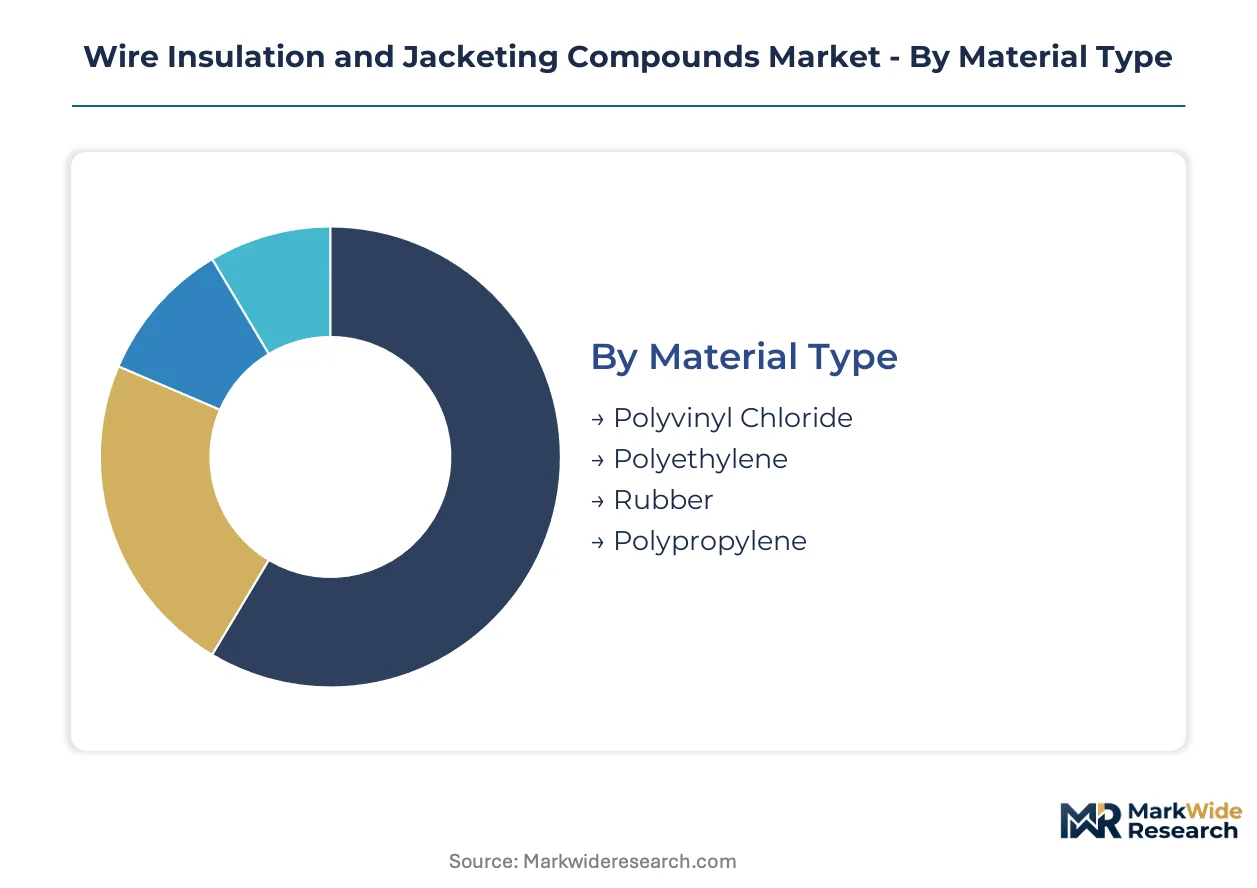
Compound selection across material grades and performance tiers determines manufacturing capital allocation, with silane cross-linking lines and halogen-free extrusion systems requiring distinct investment profiles. Procurement patterns diverge sharply between utility-scale cable producers and automotive harness suppliers, creating parallel demand channels with incompatible specification regimes.
Material Type:
Cross-linking infrastructure and compounding complexity separate high-capital segments from commodity formulations, with moisture-cure polyethylene systems demanding specialized grafting reactors.
- Polyvinyl Chloride:Plasticized formulations dominate building wire volumes through decades of optimized cost structures and established termination compatibility. REACH Article 33 enforcement is eliminating legacy phthalate plasticizers, forcing compounders to validate calcium-zinc stabilizer packages through accelerated aging protocols.
- Polyethylene:Silane-graft and peroxide-cross-linked grades command premium positioning in medium-voltage distribution and submarine cabling where moisture resistance determines service life. Chinese state-owned utilities are concentrating procurement for 220 kV transmission networks, pulling specialty compound volumes toward domestic cable producers.
- Rubber:Ethylene-propylene and chlorosulfonated polyethylene compounds serve mining and portable cord applications requiring abrasion resistance and flexibility at sub-zero temperatures.
- Polypropylene:Halogen-free formulations penetrate data center and mass transit jacketing where low smoke density specifications override cost considerations.
Polyvinyl chloride absorbs the bulk of installed compounding capacity; polyethylene is expanding most quickly.
Application:
Voltage class and environmental exposure create tiered performance requirements, with submarine and EV powertrain applications imposing the most stringent thermal and dielectric specifications.
- Electrical Wiring:Building wire and utility distribution cables represent the volume foundation, with low-voltage PVC formulations serving residential construction and cross-linked polyethylene penetrating 10 kV to 35 kV networks. India's BIS marking mandate and PLI-linked capacity expansion are redirecting procurement toward domestic compounders for solar and railway electrification projects.
- Automotive:Battery pack and motor winding applications demand fluoropolymer and cross-linked polyethylene grades sustaining 150°C operation, with German and South Korean OEMs consolidating harness procurement under platform-level performance contracts.
- Telecommunications:Fiber optic cable jacketing and copper data transmission lines require UV-stabilized polyethylene and flame retardant PVC formulations for outdoor and plenum installations.
- Industrial Equipment:Oil-resistant nitrile rubber and thermoplastic elastomer compounds serve factory automation and process control cabling where chemical exposure and continuous flexing coexist.
Electrical wiring commands the largest share of compound consumption; automotive applications are climbing the fastest.
End User:
Specification authority and procurement scale vary dramatically, with automotive OEMs dictating compound performance matrices while electrical contractors defer to distributor stock programs.
- Telecom Providers:National broadband buildouts and 5G backhaul networks drive demand for low-smoke halogen-free jacketing in data centers and central office facilities, with EU Green Deal procurement mandates embedding recycled content thresholds.
- Automotive Manufacturers:Tier-1 harness producers must qualify multiple compound sources against identical thermal cycling and fluid resistance test matrices, with single-source supply risk carrying heavy liability exposure in electric vehicle programs.
- Electrical Contractors:Price-sensitive procurement through wholesale distribution channels favors standardized PVC building wire formulations with established installation handling characteristics.
- OEMs:Original equipment manufacturers across appliance, medical device, and aerospace segments specify custom color-matched and performance-graded compounds in smaller batch quantities.
Electrical contractors absorb the bulk of standard-grade volumes; automotive manufacturers are gaining share fastest.
Performance Grade:
Regulatory divergence between jurisdictions fragments formulation strategies, with REACH, RoHS, and China's GB standards creating parallel compliance tracks.
- Standard:Conventional plasticized PVC and unmodified polyethylene formulations serve cost-optimized building wire and general-purpose cabling where baseline dielectric and mechanical properties suffice.
- Flame Retardant:Halogenated and halogen-free additive packages penetrate data center, mass transit, and high-rise construction specifications where UL 94 and IEC 60332 ratings determine market access.
- Low Smoke:Metal hydroxide-filled formulations displace conventional grades in rail, marine, and tunnel applications as evacuation safety standards tighten across European and Chinese infrastructure projects.
- High Temperature:Fluoropolymer and cross-linked polyethylene grades sustain performance above 125°C in aerospace harnesses, EV powertrains, and industrial motor leads, with PTFE and FEP resin supply concentrating in Japanese and European production sites.
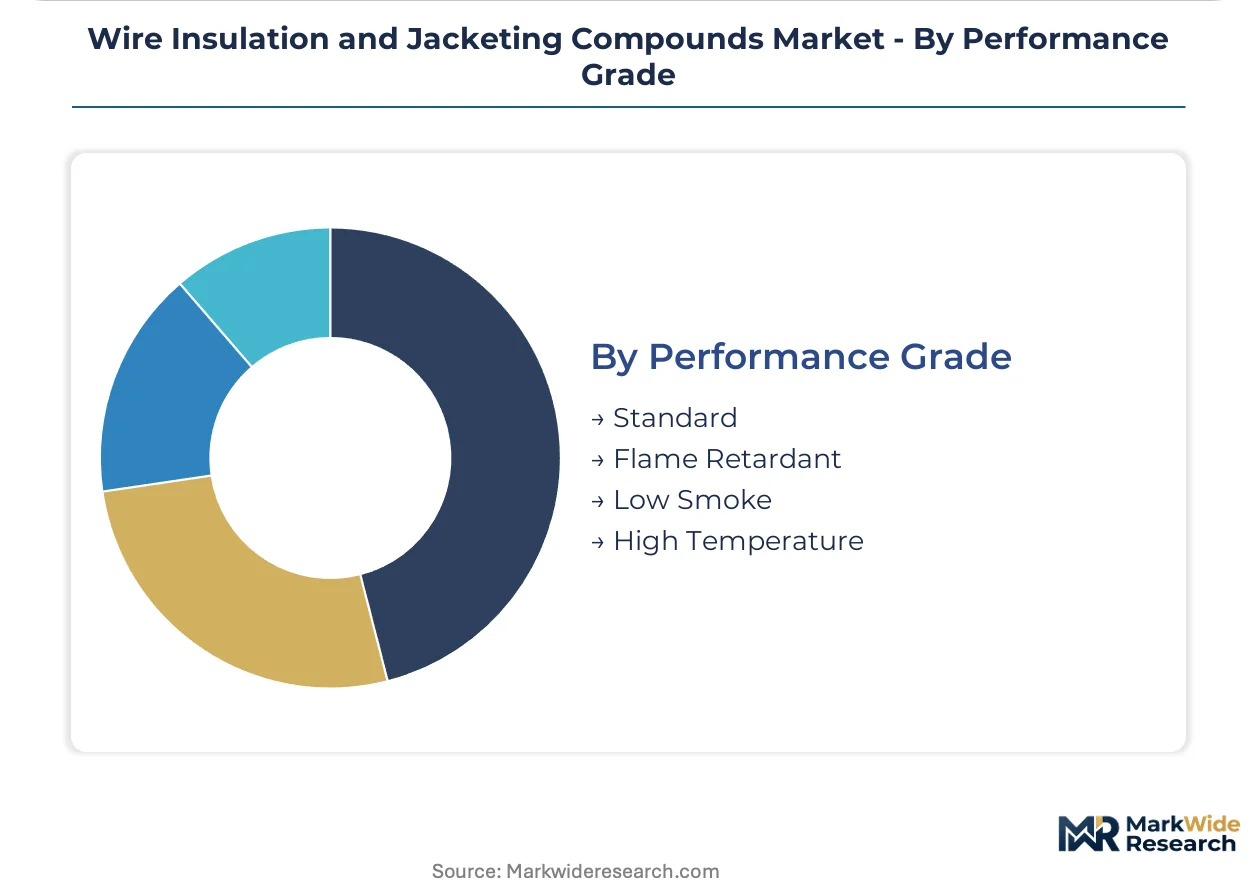
Standard grades absorb the bulk of production volume; low smoke formulations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's coastal provinces are concentrating compound manufacturing capacity for export-oriented cable producers serving renewable energy infrastructure projects.
China
State-owned utilities are expanding 220 kV and 500 kV transmission networks under the dual carbon goals, pulling medium-voltage compound procurement toward domestic cable producers. GB standards and SAMR certification govern halogen content and smoke density for infrastructure projects. Yangtze River Delta extrusion clusters are scaling silane cross-linking capacity for submarine wind interconnection cables.
United States
Integrated ethylene-to-compound manufacturing on the US Gulf Coast supports utility distribution cable demand as grid modernization accelerates. EPA and state-level environmental regulations are scrutinizing legacy plasticizer chemistries in building wire applications. Texas and Louisiana petrochemical corridors are expanding polyethylene compound output for renewable energy collector systems.
Germany
ECHA's REACH Article 33 enforcement is eliminating phthalate plasticizers from building wire formulations, forcing compounders to validate calcium-zinc stabilizer alternatives. EU Green Deal procurement mandates are embedding recycled content thresholds in public infrastructure tenders. Bavarian and North Rhine-Westphalian industrial zones are retooling halogen-free extrusion lines for rail and data center specifications.
India
BIS marking mandates and PLI-linked capacity expansion are redirecting procurement toward domestic compounders for solar and railway electrification projects. Central Electricity Authority regulations govern cable performance standards for grid infrastructure. Gujarat and Maharashtra manufacturing corridors are adding flame-retardant and low-smoke compound capacity under production-linked incentive schemes.
Japan
Fluoropolymer resin production clusters are supplying aerospace harness specifications requiring sustained performance above 150°C. METI industrial standards and JIS certification processes govern high-temperature compound qualifications for automotive and aviation applications. Kanto and Chubu industrial zones are allocating PTFE and FEP output between semiconductor and cable compound demand.
Wire Insulation and Jacketing Compounds Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical groups dominating polyethylene volumes while formulation specialists capture premium fluoropolymer and halogen-free niches. The vendor base organizes around three strategic archetypes: integrated resin-to-compound producers with ethylene feedstock control, independent compounders with silane-graft technology platforms, and specialty polymer suppliers with aerospace-grade certification. Capacity expansion and backward integration into ethylene cracking represent the dominant competitive moves, followed by technology licensing partnerships for moisture-cure cross-linking systems.
Among European integrated producers, Borealis GmbH and Evonik Industries occupy positions anchored by technology platforms and specialty additive expertise. Borealis leverages its Borlink technology for material traceability in utility contracts, while Evonik exemplifies the specialty chemical archetype with advanced stabilizer and modifier portfolios. Dow represents the Gulf Coast integrated model with captive ethylene supply. These three companies illustrate how geographic feedstock access and technology specialization create defensible positioning across standard and premium compound tiers.
| Leading Market Players |
|---|
| Borealis GmbH |
| DuPont |
| Evonik Industries |
| Solvay |
| Dow |
| ExxonMobil |
| Teknor Apex |
| BASF SE |
| SCG Chemicals Public Company Limited |
| Others |
Value Chain & Pricing Dynamics
Integrated petrochemical groups and family-owned compounders anchor supply-side ownership patterns, with feedstock-advantaged producers exercising pricing discipline through quarterly contract renegotiations while independent formulators absorb margin compression from ethylene volatility.
Pricing Analysis
Short lead-time premiums separate urgent procurement from scheduled offtake, with cable producers paying markups for silane-graft polyethylene when extrusion lines face unplanned downtime. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier—UL-listed and CE-marked compounds command 15-25% spreads over ungraded alternatives. Cost compression in commodity PVC runs through distributor channels as Chinese imports and domestic oversupply intensify competition. Electrical contractors demonstrate highest price sensitivity through wholesale stock programs, while automotive OEMs prioritize performance matrices over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with fluoropolymer resin production clustered in Japan and select European sites, exposing aerospace harness suppliers to allocation risk during semiconductor demand surges. Polyethylene compound manufacturing concentrates in the US Gulf Coast, China, and Germany, with naphtha cracker economics determining regional cost competitiveness. Raw material dependencies rest on ethylene feedstocks, plasticizer chemistries, and specialty stabilizer packages. Tariff exposure on Chinese-manufactured additives threatens margin stability for halogen-free formulators. Distribution runs through direct mill relationships for utility-scale cable producers and wholesale electrical distributors for building wire segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silane cross-linking chemistry is displacing conventional peroxide and electron-beam curing methods across medium-voltage cable applications, forcing compounders to retool grafting reactor capacity or surrender utility contracts to technology-advantaged rivals.
For Market Incumbents: Lock in long-term ethylene supply agreements on the US Gulf Coast before cracker expansion cycles tighten feedstock availability. Secure BIS marking certification for Indian PLI-linked cable projects ahead of domestic competitor scale-up. Prioritize backward integration into plasticizer production to defend margin position against REACH-driven formulation cost inflation. For New Entrants and Emerging Players: Digital channel partnerships with industrial procurement platforms offer low-friction entry into standardized PVC building wire segments bypassing entrenched distributor relationships. Target India's solar and railway electrification compound demand where BIS mandates and PLI incentives are concentrating procurement toward qualified domestic suppliers. Lead with silane-graft technology licensing rather than capital-intensive reactor buildouts. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent compounders with silane-graft technology platforms in Germany and China where REACH compliance costs and feedstock volatility are squeezing undercapitalized operators. Long-term viability hinges on exposure to EV powertrain and renewable energy cabling demand rather than legacy building wire commoditization. Watch for fluoropolymer resin allocation announcements from Japanese producers as early signal of aerospace harness supply tension.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Cracking | Gulf Coast producers secure feedstock cost advantage against naphtha volatility. |
| Silane-Graft Technology Licensing | European utilities specify moisture-cure systems for 10-35 kV distribution networks. |
| BIS Marking Certification Investment | Domestic compounders capture PLI-linked solar and railway cable contracts in India. |
| Halogen-Free Extrusion Line Retooling | German rail and data center specifications mandate low-smoke density compliance. |
| Long-Term Utility Supply Agreements | Chinese state-owned grid operators concentrate 220 kV compound procurement domestically. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cable compound plant managers, procurement leads at Tier-1 automotive harness producers, utility grid planning officers, and distribution channel partners. ECHA REACH substance databases, USITC import records, and China SAMR certification registries provided cross-validation. Bottom-up volume modeling triangulated against top-down ethylene consumption estimates and cable production statistics.
Data-stream reconciliation across material-grade consumption, end-use application splits, and regional production capacity informed the analytical framework. Segmentation dimensions included compound chemistry, voltage class, performance certification tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections and capacity expansion schedules. EV powertrain thermal requirements and renewable energy grid buildout trajectories served as primary demand-side forecast inputs.
The model holds under stable ethylene feedstock pricing and continued REACH enforcement; deviation in naphtha cracker operating rates or ECHA substance restriction timelines would shift volume trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Mineral Wool Board Insulation Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market
Insulation Materials
Technical Foam Market