
 High Temperature Insulation Market | 2026-2036
High Temperature Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Insulation Market Analysis
The gap between premium engineered solutions and commodity insulation is hardening as furnace operators face divergent total-cost-of-ownership pressures. Morgan Advanced Materials leverages its vertical integration in fused silica and alumina chemistry to command pricing power in aerospace-grade ceramic wool. RHI Magnesita anchors its position through captive magnesite sourcing and dense refractory know-how tied to steel-ladle applications. Unifrax differentiates via proprietary soluble-fiber formulations that address evolving occupational health standards.
High temperature insulation encompasses engineered materials designed to maintain thermal stability above 1000°C, typically comprising alumina-silica, zirconia, or magnesia-based matrices formed into fibers, bricks, or monolithic castables to protect equipment and reduce energy loss in extreme thermal environments. Ceramic wool and refractory fibers dominate volume flows into industrial furnaces and kilns, where lining replacement cycles generate recurring demand. Calcium silicate boards command premium placement in power generation boilers due to their compressive strength and hydrophobic performance, while insulating firebricks retain share in cement kiln preheater towers where mechanical abrasion dictates material selection.
EPA NESHAP standards for hazardous air pollutants from refractory manufacturing shape product formulation requirements in the United States, while REACH and EU F-Gas Regulation restrict certain binder chemistries and fluorinated blowing agents used in insulating foams. OSHA silica exposure limits and evolving ISO 11014 safety data sheet protocols further constrain material handling and installation practices across end-use sectors. Stakeholders must track regulatory divergence between jurisdictions to avoid stranded inventory and secure type-approval for next-generation low-biopersistence fiber platforms.
Market Dynamics
Steelmakers and petrochemical operators are accelerating furnace lining replacement cycles to meet tightening EPA emissions standards and EU F-Gas thermal efficiency mandates, compressing procurement timelines and favoring suppliers with soluble-fiber certification.
Growth Catalysts
- EPA NESHAP enforcement:Hazardous air pollutant standards for refractory manufacturing are forcing steel-ladle operators toward certified low-biopersistence fiber platforms.
- Ruhr industrial cluster retrofit cycles:German furnace operators are consolidating orders for ceramic fiber linings as aging reheating furnace infrastructure reaches replacement thresholds.
- Soluble-fiber chemistry advances:Next-generation alkaline earth silicate formulations are capturing share in aerospace heat-shielding applications where occupational exposure limits are most stringent.
Market Restraints
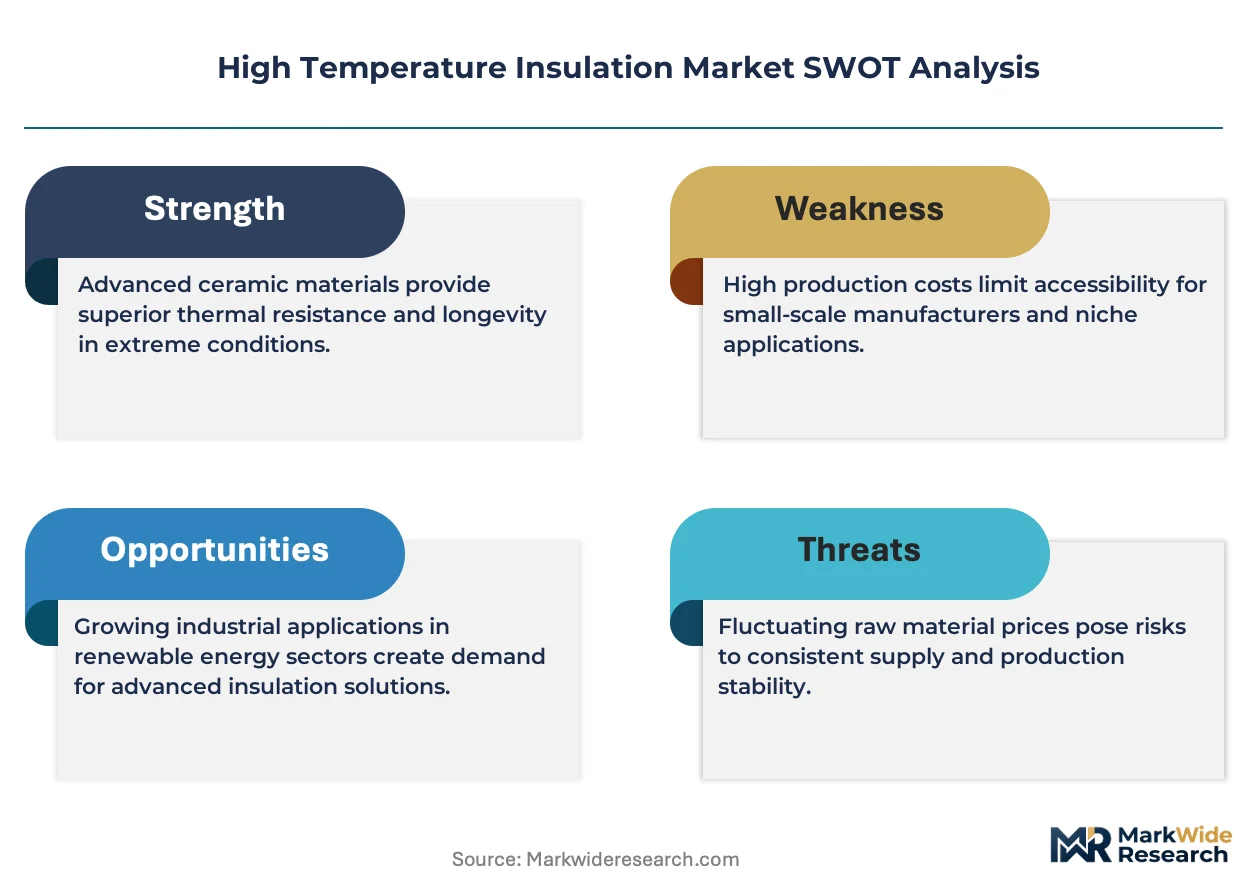
- Fused silica feedstock concentration:Premium alumina-silica chemistry depends on limited high-purity quartz deposits concentrated in select mining jurisdictions.
- REACH compliance friction:Registration requirements for novel binder chemistries extend product development timelines by 18-24 months for European market entry.
- Calcium silicate substitution in power generation:Boiler operators are specifying rigid microporous silica boards where compressive strength requirements exceed ceramic fiber capabilities.
Strategic Opportunities
- India cement kiln preheater towers:Insulating firebrick specifications remain underpenetrated as domestic producers lack dense refractory technical service networks.
- EU Green Deal carbon border adjustments:Thermal efficiency mandates for imported steel are creating pull-through demand for high-performance furnace linings at European mills.
- Digital thermal monitoring integration:Embedding fiber optic sensors within monolithic castables enables predictive maintenance contracts with aluminum smelter operators.
Industry Challenges
- Refractory installation technician scarcity:Specialized gunning and ramming skills for monolithic applications are retiring faster than apprenticeship programs replenish them.
- ISO 11014 safety data sheet harmonization:Divergent occupational exposure classification between OSHA silica limits and evolving EU carcinogen labeling creates inventory stranding risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Insulation Market |
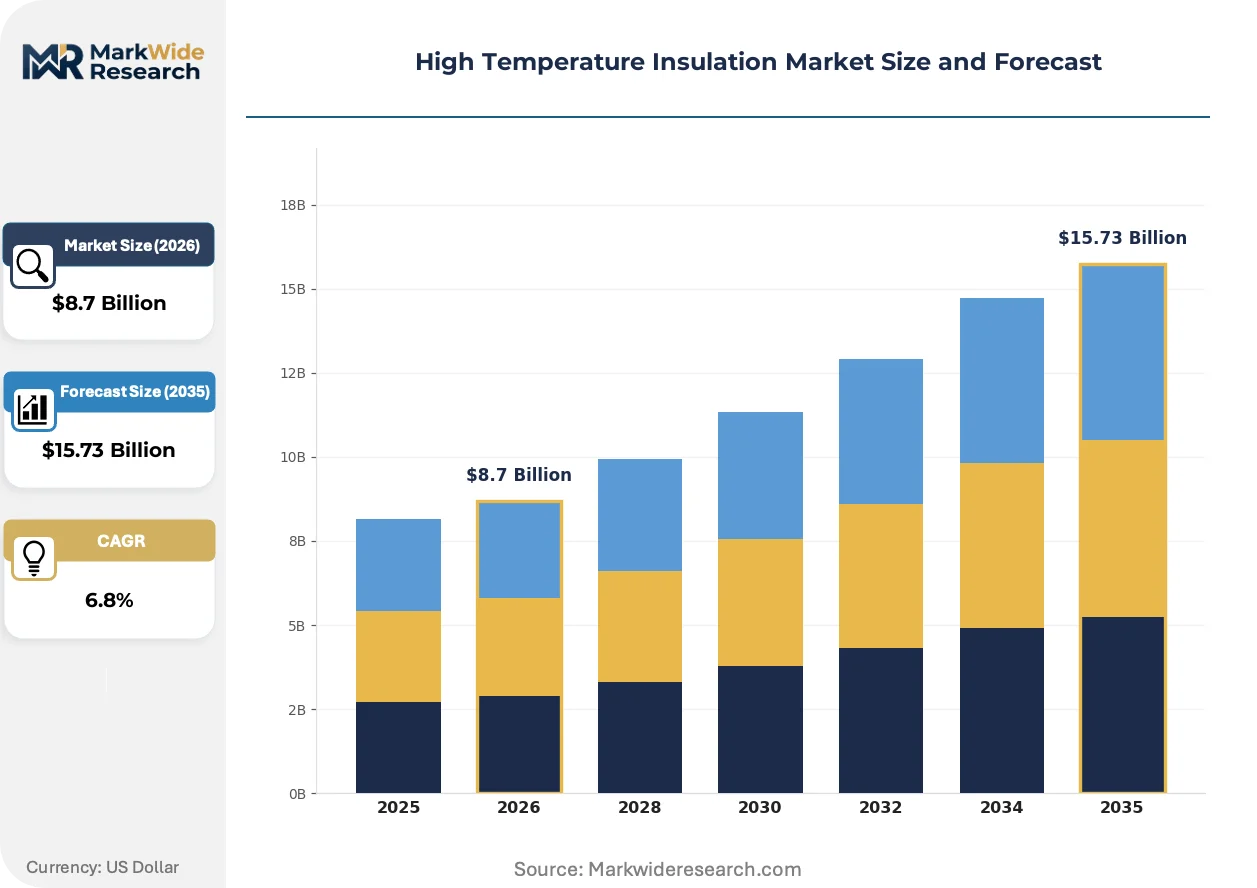
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refractory Fibers, Ceramic Wool, Insulating Firebricks, Calcium Silicate End User: Aerospace, Oil & Gas, Power Generation, Cement Form: Blankets, Boards, Foam, Castables Application: Industrial Furnaces, Boilers, Heat Exchangers, Kilns |
| Companies Covered | Morgan Advanced Materials, 3M, Luyang Energy-saving Materials Co., Ltd., RHI Magnesita, Unifrax, Promat, Etex Group, Pyrotek, Isolite Insulating Products Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Insulation Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reshape product roadmaps, with fiber durability and bio-safety properties now co-equal design priorities alongside thermal performance.
Soluble alkaline earth silicate fiber is overtaking traditional aluminosilicate ceramic wool in steel reheating furnace applications. European steelmakers facing EU F-Gas Regulation compliance deadlines are specifying these fibers for their reduced biopersistence profiles. The shift is compressing demand for legacy refractory ceramic fiber while elevating pricing power for certified soluble-fiber producers.
REACH restrictions on chromium-bearing binders are eliminating hexavalent chrome from monolithic castable formulations used in cement kiln nose rings. Manufacturers are reformulating with calcium aluminate cements that sacrifice some slag resistance for regulatory compliance. German cement operators are absorbing higher material costs to secure type-approval for plant expansions.
Steelmakers are unbundling furnace lining supply from installation services, awarding separate contracts to specialized applicators. This disintermediation fragments procurement relationships that previously bundled material and labor under single-source refractory suppliers. The pattern is most pronounced in Ruhr basin steel complexes where operators seek cost transparency through competitive tendering.
High Temperature Insulation Market Segmentation
Material selection in high temperature insulation hinges on thermal cycling severity, mechanical load conditions, and regulatory exposure limits. Furnace operators weigh installation labor intensity against energy recovery payback periods when specifying across product, form, and application dimensions.
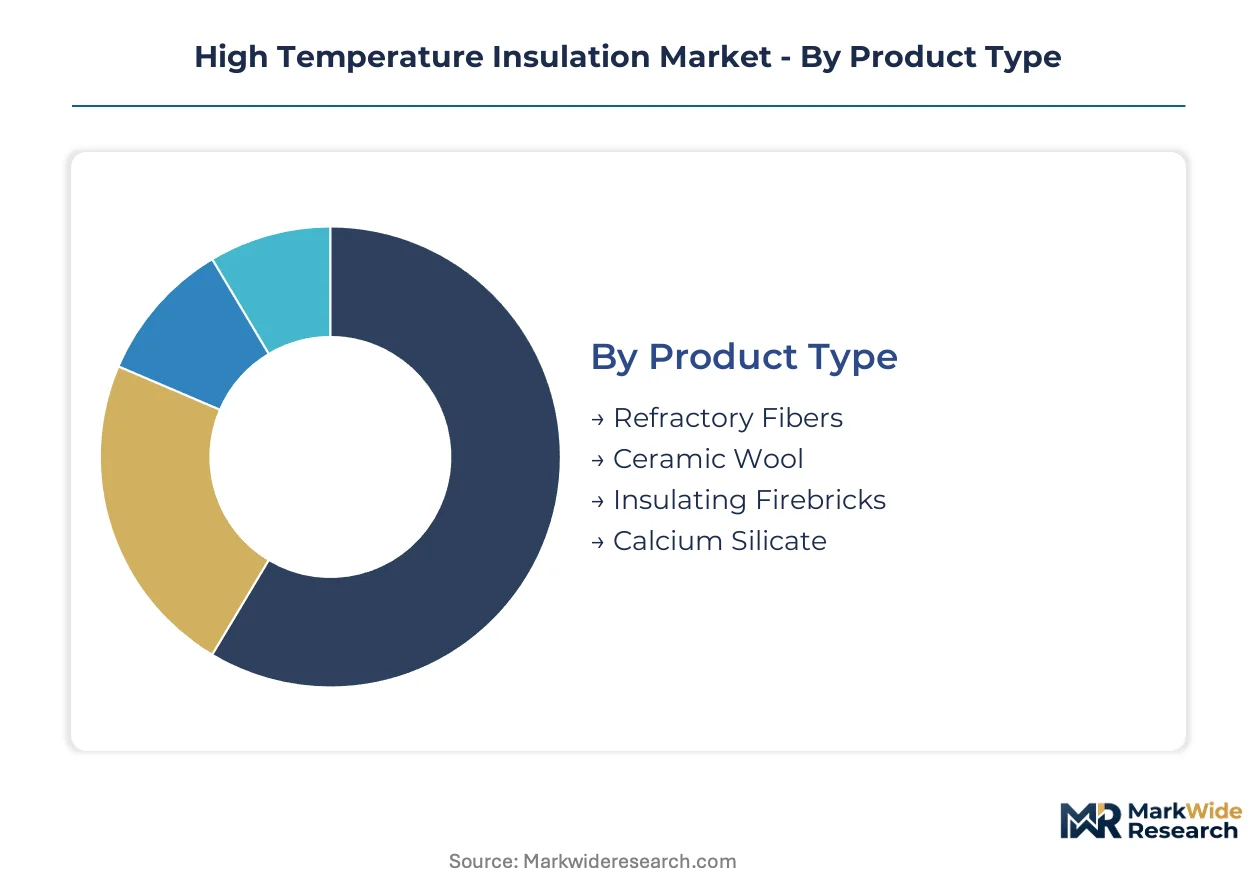
Product Type:
Cost tier stratification dominates procurement decisions, with operators trading thermal performance against replacement cycle economics.
- Ceramic Wool:Aluminosilicate fiber matrices deliver thermal stability up to 1260°C with low thermal mass. Steel reheating furnaces in Germany's Ruhr cluster specify certified low-biopersistence grades to satisfy EU F-Gas thermal efficiency mandates while meeting OSHA silica exposure protocols.
- Refractory Fibers:Engineered polycrystalline and amorphous silica fibers withstand continuous exposure above 1400°C. Aerospace heat shielding applications in the United States favor these formulations where FAA certification requirements intersect with EPA NESHAP hazardous air pollutant standards for manufacturing emissions.
- Insulating Firebricks:Dense alumina-silica or magnesia compositions resist mechanical abrasion in cement kiln preheater towers. Indian cement producers lack technical service networks for these specifications.
- Calcium Silicate:Hydrophobic boards with high compressive strength serve power generation boilers. Boiler operators in the United States specify these where steam exposure demands dimensional stability beyond ceramic fiber capabilities.
Volume sits with ceramic wool; growth tilts toward refractory fibers.
End User:
Application severity and regulatory scrutiny intensity separate customer segments by margin potential and technical service requirements.
- Steel:Integrated mills and mini-mills drive blanket and board consumption in reheating furnaces and ladles. Ruhr basin operators compress procurement timelines to meet EU F-Gas compliance deadlines.
- Petrochemical:Ethylene cracker furnaces and catalytic reformer units demand soluble-fiber linings. Refinery operators face EPA NESHAP enforcement for hazardous air pollutant emissions from refractory manufacturing.
- Cement:Rotary kiln nose rings and preheater towers specify dense castables and insulating firebricks. REACH restrictions on chromium-bearing binders force calcium aluminate cement reformulations.
- Aerospace:Heat shielding and engine compartment insulation require alkaline earth silicate fibers with reduced biopersistence. OEM specifications exceed occupational exposure limits enforced by OSHA.
- Power Generation:Utility boilers and HRSG units favor calcium silicate boards for steam drum insulation. FERC thermal efficiency standards influence material selection for gas turbine exhaust systems.
Steel commands current volume; aerospace climbs the fastest on soluble-fiber substitution.
Form:
Installation method and repair accessibility determine form selection, with monolithic options gaining where furnace geometry complicates modular fitting.
- Blankets:Flexible ceramic fiber rolls conform to curved furnace walls and irregular surfaces. Steel ladle operators specify these for gunning repairs where speed of application reduces downtime.
- Castables:Monolithic refractory mixes enable continuous lining without joints. Cement kiln nose rings in Germany absorb higher material costs for REACH-compliant calcium aluminate formulations.
- Boards:Rigid calcium silicate and microporous silica panels serve flat surfaces in power boilers. Compressive strength requirements exceed ceramic fiber capabilities in high-pressure steam environments.
- Foam:Lightweight insulating foams with restricted fluorinated blowing agents face EU F-Gas Regulation constraints. Alternative chemistries extend product development timelines.
Blankets retain installation share; castables expand most quickly on repair cycle compression.
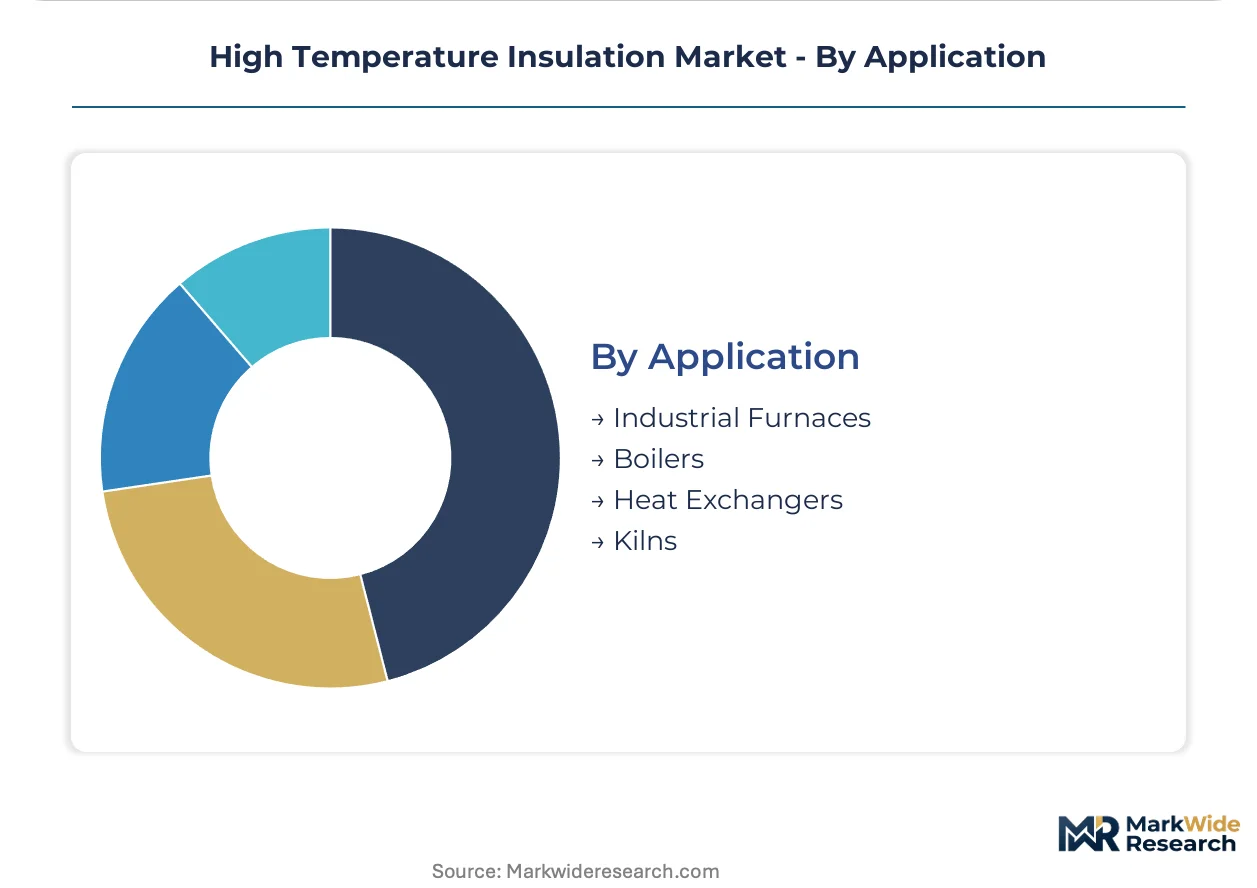
Application:
Operating temperature range and thermal shock frequency segment demand by material durability requirements and replacement predictability.
- Industrial Furnaces:Steel reheating and heat treatment units consume the largest ceramic fiber volumes. EPA emissions rules accelerate lining replacement cycles across United States integrated mills.
- Kilns:Cement and lime rotary kilns specify dense refractory zones at the burning region and insulating backup layers. Indian preheater towers remain underpenetrated by technical service networks.
- Boilers:Utility and industrial steam generators favor calcium silicate and microporous silica for steam drum and header insulation. FERC efficiency standards influence specification upgrades.
- Heat Exchangers:Petrochemical and refinery units demand fiber and castable combinations for reaction furnace tubes. Soluble-fiber certification compresses procurement timelines for EU F-Gas compliance.
Furnace applications anchor volume; kiln specifications gain share on emerging market capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial cluster in Germany concentrates furnace retrofit activity as steelmakers compress procurement timelines for EU F-Gas compliance. Aging reheating furnace infrastructure across this corridor generates concentrated demand for certified low-biopersistence fiber platforms.
United States
Integrated steel mills in the Great Lakes region accelerate lining replacement cycles to satisfy EPA NESHAP hazardous air pollutant standards. OSHA silica exposure limits constrain installation practices for ceramic fiber applications. Pittsburgh-area steel complexes award separate material and labor contracts to specialized applicators.
Germany
Ruhr basin furnace operators consolidate orders for soluble alkaline earth silicate fibers as REACH restrictions eliminate legacy binder chemistries. EU F-Gas Regulation thermal efficiency mandates compress replacement schedules for aging reheating infrastructure. Düsseldorf-area technical service networks support dense refractory specifications for cement kiln expansions.
India
Cement producers in Gujarat and Rajasthan specify insulating firebricks for rotary kiln preheater towers where domestic technical service networks remain underdeveloped. Central Electricity Authority efficiency standards influence boiler insulation upgrades at thermal power stations. Mumbai-Pune industrial corridor operators absorb higher material costs for REACH-compliant import formulations.
China
Steelmakers in the Yangtze River Delta source alumina-silica ceramic fiber for reheating furnace retrofits aligned with MIIT energy efficiency targets. GB standards for industrial furnace insulation shape product certification requirements. Shandong Peninsula refractory manufacturers expand soluble-fiber capacity to serve aerospace heat-shielding specifications.
Japan
Aerospace OEMs in the Nagoya industrial zone specify alkaline earth silicate fibers with reduced biopersistence for engine compartment insulation. METI industrial decarbonization roadmaps drive furnace efficiency investments at specialty steel producers. Osaka-Kobe manufacturing belt operators integrate digital thermal monitoring into monolithic castable installations.
High Temperature Insulation Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent total-cost-of-ownership pressures. The market structure hardens around a premium-engineered tier commanding pricing power through captive raw material sourcing and a commodity tier competing on installation speed and local service presence. Three archetypes dominate: vertically integrated refractory specialists with captive magnesite or fused silica reserves; fiber technology platforms with proprietary soluble-fiber certifications; and regional fabricators leveraging proximity to industrial clusters. Consolidation proceeds through selective acquisition of technical service networks, while portfolio diversification into predictive maintenance contracts reshapes customer retention economics.
Among UK-based engineered materials platforms, Morgan Advanced Materials occupies a position representing premium-tier ceramic wool suppliers with upstream control over alumina chemistry. Austrian-incorporated RHI Magnesita anchors the dense refractory specialist archetype through magnesite sourcing integration. Unifrax exemplifies the certified soluble-fiber platform model addressing evolving occupational health standards across multiple jurisdictions.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| 3M |
| Luyang Energy-saving Materials Co., Ltd. |
| RHI Magnesita |
| Unifrax |
| Promat |
| Etex Group |
| Pyrotek |
| Isolite Insulating Products Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation thermal efficiency mandates gate both qualified supply and premium-tier pricing access, compressing procurement timelines for certified low-biopersistence fiber platforms while elevating cost thresholds for REACH-compliant binder chemistries across German furnace retrofit cycles.
Pricing Analysis
Furnace uptime guarantees anchor value-based pricing for ceramic fiber linings, with suppliers bundling predictive maintenance contracts to capture recurring revenue streams. Three-tier pricing structure across premium, standard, and economy levels separates soluble-fiber certified grades from legacy aluminosilicate formulations and commodity calcium silicate boards. Price differentiation rests on REACH certification status and captive magnesite sourcing integration. Cost compression in standard-grade ceramic wool intensifies as regional fabricators absorb margin erosion to retain Ruhr basin steelmaker contracts. Mini-mill operators exhibit highest price sensitivity, while aerospace OEMs prioritize biopersistence certification over unit cost.
Supply Chain Analysis
Refractory installation technician scarcity across Germany, China, and India constrains monolithic castable deployment velocity and extends project completion windows. High-purity fused silica feedstock draws from limited quartz deposits in select mining jurisdictions, while magnesite concentrates in Austrian and Slovak captive reserves. Single-source vulnerability permeates premium alumina-silica chemistry supply. Distribution runs through technical service networks co-located with Ruhr, Yangtze River Delta, and Great Lakes industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. EPA NESHAP hazardous air pollutant standards create a barrier-to-entry moat for certified low-biopersistence fiber producers, elevating capital requirements for new formulation development and type-approval testing.
For Market Incumbents: Deepen captive magnesite sourcing integration to defend margin position against soluble-fiber substitution in steel reheating applications. Expand technical service networks in Gujarat and Rajasthan cement corridors before domestic producers close capability gaps. Prioritize REACH-compliant calcium aluminate cement R&D to offset chromium-bearing binder phase-outs. For New Entrants and Emerging Players: Digital thermal monitoring platforms offer the lowest-friction entry vector for predictive maintenance contracts with aluminum smelter operators. Target Indian cement kiln preheater tower specifications where dense refractory technical service networks remain underdeveloped. Lead with soluble-fiber certification to bypass legacy supplier incumbency in EU F-Gas compliance-driven procurement cycles. For Investors and Strategic Acquirers: Ruhr basin furnace operator consolidation of separate material and labor contracts is the leading indicator that technical service network acquisitions will reshape customer retention economics. Position for five-to-ten year holding periods aligned with EU Green Deal carbon border adjustment implementation. Track EPA NESHAP enforcement intensity as the signal for accelerated lining replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fused Silica Reserves | Captive alumina chemistry control secures pricing power for aerospace-grade ceramic wool specifications. |
| Soluble-Fiber Certification Investment | REACH-compliant alkaline earth silicate formulations capture EU F-Gas Regulation-driven procurement shifts. |
| Technical Service Network Acquisition | Dense refractory installation capabilities in India cement corridors address underpenetrated preheater tower demand. |
| Digital Thermal Monitoring Integration | Fiber optic sensor embedding enables predictive maintenance contracts with aluminum smelter operators. |
| Long-term Supply Agreement with Steelmakers | Compressed procurement timelines for EPA NESHAP compliance secure volume commitments from Great Lakes integrated mills. |
Methodological Framework
Document review covered trade association filings, customs data, and regulatory docket records, complemented by interviews with furnace engineering directors, refractory procurement leads at integrated steel mills, technical service network managers, and EHS compliance officers. Secondary validation drew from EPA NESHAP rulemaking documents, ECHA REACH registration databases, EU F-Gas Regulation implementation guidance, and SEC disclosures from capital-heavy producers. Bottom-up demand modeling triangulated against top-down industrial capacity assessments.
Cross-referencing historical replacement cycle patterns with panel input from procurement officers across the Ruhr, Great Lakes, and Yangtze River Delta clusters anchored the analytical framework. Segmentation dimensions spanned material chemistry grade, end-use severity tier, form factor installation method, and regional regulatory cluster. CAGRs derived from regression against industrial production indices and energy efficiency investment trajectories. Forecast inputs incorporated MIIT furnace retrofit targets and CEA boiler upgrade mandates.
The model holds under steady-state regulatory enforcement; deviation in EPA NESHAP implementation timing or REACH binder restriction acceleration would shift replacement cycle compression trajectories. Forecasts embed assumptions around soluble-fiber certification adoption curves and technical service network expansion rates. A small set of named triggers—EU carbon border adjustment scope expansion, OSHA silica limit revisions, and Indian domestic refractory capacity buildouts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Radiation Shielding Materials Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Multi-Layer Cryogenic Insulation Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
Italy Industrial Insulation Market