
 Microencapsulated Paraffin Phase Change Materials Market | 2026-2036
Microencapsulated Paraffin Phase Change Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Microencapsulated Paraffin Phase Change Materials Market Intelligence
ISO 9001 quality management certification is rotating as a baseline gate for suppliers bidding into construction and electronics cooling value chains, filtering out uncertified compounders. BASF SE leverages its polymer science heritage to sustain formulation leadership across melamine-formaldehyde shell systems. DuPont de Nemours anchors North American supply through captive resin production and direct OEM relationships with HVAC equipment manufacturers. Microtek Laboratories specializes in custom capsule diameter specifications for textile integrators requiring sub-100-micron thermal regulation fibers.
Microencapsulated paraffin phase change materials comprise paraffin wax cores surrounded by synthetic polymer shells, typically 1-1000 microns in diameter, engineered to store and release latent heat at defined temperature thresholds for passive thermal management. The shell chemistry—melamine-formaldehyde, urea-formaldehyde, or polyurethane—determines mechanical durability and compatibility with host matrices such as gypsum, concrete, or textile coatings. Building insulation applications lead volume absorption due to code-mandated envelope performance upgrades across temperate climate zones. Thermal energy storage for renewable energy systems represents the fastest-expanding segment as grid operators seek diurnal load balancing. Electronics cooling maintains premium margin pools where die-level temperature stability justifies higher capsule costs.
REACH registration requirements in Europe govern shell polymer chemistry and residual formaldehyde thresholds, while EPA Toxic Substances Control Act oversight in the United States shapes paraffin feedstock approval pathways for building product applications. China's GB standards for construction materials and Japan's JIS thermal performance protocols create multi-jurisdictional compliance burdens for multinational suppliers. Stakeholders must monitor evolving fire safety classifications for encapsulated paraffin in wall assemblies, as stricter reaction-to-fire ratings in Germany and France threaten substitution by inorganic phase change salts.
Market Dynamics
The EU F-Gas Regulation and national retrofit mandates are compressing specification timelines for thermal envelope materials, forcing compounders to accelerate shell chemistry validation cycles while construction developers demand latent heat storage at narrower temperature bands.
Growth Catalysts
- Building code tightening:Germany's passive house standards and France's RE2020 thermal regulations mandate latent heat storage in wall assemblies, pulling microencapsulated paraffin into gypsum board specifications.
- Grid-scale energy storage:Diurnal load balancing requirements from renewable integration are expanding thermal energy storage deployments for concentrated solar and district heating networks.
- ISO 9001 certification gating:Electronics OEMs now require quality management certification as a baseline procurement filter, channeling volume toward certified compounders and compressing uncertified supplier margins.
Market Restraints
- Formaldehyde residual thresholds:REACH registration and ECHA classification of melamine-formaldehyde shell precursors as substances of very high concern are elevating compliance costs and triggering reformulation cycles.
- Fire safety rating compression:Germany's DIN 4102 and France's reaction-to-fire classifications for wall assemblies are threatening substitution by inorganic phase change salts in high-rise applications.
- Paraffin feedstock volatility:Crude oil derivative pricing swings directly impact core material costs, compressing margin stability for non-integrated compounders.
Strategic Opportunities
- Textile thermal regulation:Sub-100-micron capsule specifications for fiber integration remain underpenetrated in performance apparel and medical textiles, offering white space beyond construction.
- Japan's carbon neutrality roadmap:METI subsidies for building energy efficiency and JIS thermal performance protocols are creating regulatory tailwinds for envelope material upgrades.
- Die-level electronics cooling:Semiconductor packaging thermal management demands temperature stability within tighter bands, justifying premium capsule costs in advanced node manufacturing.
Industry Challenges
- Multi-jurisdictional compliance burden:Simultaneous navigation of REACH shell chemistry requirements, EPA TSCA paraffin approvals, and China's GB construction standards strains regulatory affairs capacity.
- Capsule-matrix integration complexity:Mechanical durability failures during concrete mixing or textile coating processes require application-specific formulation support that stretches technical service resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microencapsulated Paraffin Phase Change Materials Market |
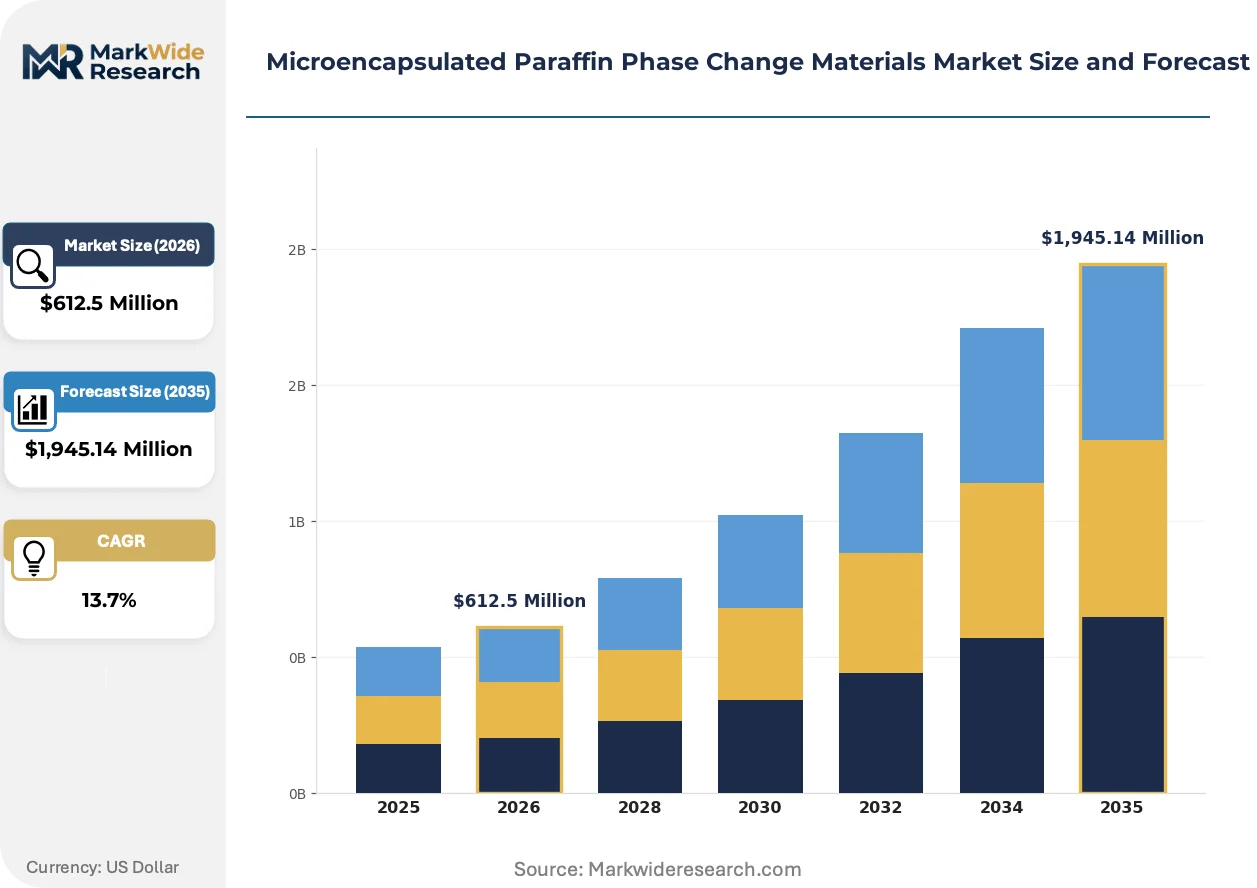
| Market Size in 2026 | $612.5 Million |
| Market Size in 2035 | $1,945.14 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microencapsulated Paraffin, Microencapsulated Salt Hydrates, Microencapsulated Fatty Acids, Microencapsulated Eutectics Application: Building Insulation, Thermal Energy Storage, Textiles, Electronics Cooling, Cold Chain Logistics End User Industry: Construction, Consumer Electronics, Packaging, HVAC Equipment Manufacturing, Renewable Energy Systems Packaging Type: Slurry, Powder, Granules, Emulsion, Capsule Form |
| Companies Covered | Henkel AG & Co. KGaA, DuPont de Nemours, BASF SE, 3M Company, Microtek Laboratories, Honeywell International, Rubitherm Technologies, Outlast Technologies, Croda International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microencapsulated Paraffin Phase Change Materials Market Strategic Shifts & Innovations
Shell chemistry innovation and procurement pattern shifts are fragmenting the competitive landscape, with melamine-formaldehyde systems facing pressure from bio-based alternatives and buyers consolidating supplier relationships around certified compounders.
Polyurethane shell systems are bifurcating from traditional melamine-formaldehyde formulations in building insulation applications. Passive house developers in Germany and Austria specify polyurethane-encapsulated paraffin for enhanced mechanical durability during gypsum board processing. This split is compressing market share for legacy shell chemistries in premium envelope segments while urea-formaldehyde alternatives capture cost-sensitive retrofit volume.
REACH registration requirements for shell polymer chemistry are tightening residual formaldehyde thresholds across European construction supply chains. ECHA's classification protocols are forcing compounders to submit extended safety data sheets and trigger reformulation investments. Building product manufacturers in France and Germany are responding by dual-sourcing from REACH-registered suppliers and demanding pre-certified capsule formulations.
Buyer concentration among large construction developers is consolidating procurement around vertically integrated compounders with captive resin production. Direct OEM relationships are displacing distributor channels for HVAC equipment manufacturers seeking thermal storage integration. This pattern is most visible in North American markets where equipment makers specify capsule-included heat exchanger assemblies rather than sourcing raw materials separately.
Microencapsulated Paraffin Phase Change Materials Market Segmentation

Segmentation in microencapsulated phase change materials determines formulation complexity, regulatory pathway, and integration cost across construction, electronics, and energy storage value chains. Shell chemistry and core composition dictate thermal performance thresholds, while packaging form factor shapes logistics and handling economics for compounders and end-users.
Product Type:
Premium margin pools concentrate in paraffin-based systems where latent heat storage density and temperature precision justify higher formulation costs against salt hydrate alternatives.
- Microencapsulated Paraffin:Hydrocarbon cores surrounded by synthetic polymer shells deliver defined phase transition temperatures between 18-60°C for passive thermal management. Building insulation specifications in Germany and Austria pull volume toward melamine-formaldehyde and polyurethane shell systems as passive house standards tighten envelope performance requirements.
- Microencapsulated Salt Hydrates:Inorganic salt cores store higher latent heat density per kilogram than organic alternatives but suffer from supercooling and phase separation during thermal cycling. Grid-scale thermal energy storage operators in Spain and Italy specify salt hydrate systems for concentrated solar plants where capital cost per megawatt-hour stored outweighs cycle stability concerns.
- Microencapsulated Fatty Acids:Bio-derived cores from vegetable oils offer renewable feedstock credentials for sustainability-focused textile integrators.
- Microencapsulated Eutectics:Binary or ternary mixtures enable custom melting point engineering for electronics cooling applications requiring sub-ambient temperature stability.
The dominant share belongs to microencapsulated paraffin, while microencapsulated salt hydrates are closing the gap fastest.
Application:
Volume concentration tracks building code enforcement intensity, with envelope performance mandates creating step-function demand spikes in specific national markets.
- Building Insulation:Gypsum board and wall assembly integration dominates current absorption as France's RE2020 thermal regulations and Germany's EnEV retrofit mandates compress specification timelines. Compounders face mechanical durability validation cycles for polyurethane-encapsulated paraffin during board manufacturing processes.
- Thermal Energy Storage:Diurnal load balancing for renewable integration drives fastest expansion as European grid operators deploy molten salt and encapsulated paraffin systems for concentrated solar and district heating networks. Danish and Swedish district heating cooperatives pilot seasonal storage configurations.
- Textiles:Sub-100-micron capsule specifications for fiber integration remain underpenetrated in performance apparel despite technical feasibility.
- Electronics Cooling:Die-level temperature stability requirements in semiconductor packaging justify premium capsule costs for advanced node manufacturing.
- Cold Chain Logistics:Temperature-sensitive pharmaceutical distribution demands passive thermal protection during last-mile delivery.
Building insulation commands the largest volume position, though thermal energy storage is expanding most quickly.
End User Industry:
Procurement authority concentrates with construction developers and HVAC equipment manufacturers who specify capsule-included assemblies rather than sourcing raw materials separately.
- Construction:Large European developers consolidate procurement around vertically integrated compounders with captive resin production and REACH-registered shell chemistry. Direct OEM relationships displace distributor channels for envelope material specifications.
- HVAC Equipment Manufacturing:North American equipment makers integrate thermal storage capsules directly into heat exchanger assemblies, compressing margins for non-integrated compounders. Carrier and Trane specify capsule-included components from approved supplier lists.
- Consumer Electronics:Smartphone and laptop thermal management demands thin-profile phase change materials for die-level heat spreading.
- Packaging:Temperature-controlled pharmaceutical and food logistics drive demand for disposable thermal buffering solutions.
- Renewable Energy Systems:Concentrated solar plant operators and district heating utilities specify large-format thermal storage configurations.
Construction holds the dominant procurement position, while HVAC equipment manufacturing is gaining share fastest through captive integration strategies.
Packaging Type:
Logistics economics and handling safety determine format selection, with slurry systems dominating construction integration and powder formats preferred for textile coating processes.
- Slurry:Aqueous suspensions of microencapsulated paraffin enable direct pumping into concrete mixing or gypsum board manufacturing without dust exposure. German construction chemical suppliers specify slurry delivery for automated dosing systems in wallboard plants.
- Powder:Dried capsule aggregates suit textile coating and dry-mix construction products where water content disrupts host matrix chemistry. Japanese fiber integrators require sub-100-micron powder specifications for thermal regulation yarn production.
- Granules:Intermediate particle size ranges balance flowability with surface area for bulk thermal storage applications.
- Emulsion:Oil-in-water dispersions serve specialized coating applications requiring film-forming properties.
- Capsule Form:Discrete macro-capsules enable manual handling for laboratory and prototyping environments.
Slurry formats dominate construction volume, while powder packaging is climbing the fastest on textile integration demand.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea-Baltic rail corridor and Rhine-Alpine freight axis position Germany as the logistics backbone for microencapsulated paraffin distribution across temperate European markets. Grid interconnectors between Denmark, Sweden, and Germany enable district heating networks to deploy thermal storage at scale.
Germany
Passive house standards and EnEV retrofit mandates drive specification of microencapsulated paraffin in gypsum board and wall assemblies. The F-Gas Regulation compresses timelines for envelope material upgrades. The Rhine-Main industrial cluster hosts compounders serving construction chemical distributors with REACH-registered shell formulations.
France
RE2020 thermal regulations mandate latent heat storage in new construction and major renovations. ECHA classification of formaldehyde precursors elevates compliance costs for melamine-formaldehyde shell systems. The Lyon-Grenoble corridor concentrates textile integrators piloting sub-100-micron capsules for performance apparel.
United States
HVAC equipment manufacturers specify capsule-included heat exchanger assemblies through direct OEM relationships. EPA TSCA oversight shapes paraffin feedstock approval pathways for building product applications. The Great Lakes manufacturing belt anchors captive resin production for North American supply security.
China
GB standards for construction materials create compliance entry barriers for multinational suppliers. Dual carbon goals accelerate building energy efficiency retrofits in tier-one cities. The Yangtze River Delta concentrates textile coating operations requiring powder-format microcapsules for fiber integration.
Japan
METI subsidies for building energy efficiency create procurement tailwinds for envelope material upgrades. JIS thermal performance protocols standardize testing methodologies for latent heat storage systems. The Nagoya-Osaka industrial corridor hosts compounders serving electronics cooling applications for semiconductor packaging.
Microencapsulated Paraffin Phase Change Materials Market Key Industry Players
Listed leaders compete with private specialists across shell chemistry expertise and regulatory certification depth. The vendor base splits between diversified chemical conglomerates with captive resin production and focused compounders serving niche diameter specifications. Three archetypes dominate: integrated polymer science conglomerates, custom capsule engineering boutiques, and construction chemical distributors with backward integration into encapsulation. Competitive moves concentrate on REACH registration acquisition and direct OEM relationship formation with HVAC equipment makers.
Among German-domiciled chemical conglomerates, BASF SE exemplifies polymer science heritage applied to melamine-formaldehyde and polyurethane shell systems. DuPont de Nemours anchors North American supply architecture through resin production integration. Microtek Laboratories occupies the custom specification tier, serving textile integrators requiring precise capsule diameter control for fiber embedding processes.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| DuPont de Nemours |
| BASF SE |
| 3M Company |
| Microtek Laboratories |
| Honeywell International |
| Rubitherm Technologies |
| Outlast Technologies |
| Croda International |
| Others |
Cost & Logistics Intelligence
Polyurethane shell chemistry substitution for melamine-formaldehyde systems is redrawing supply geography toward German and Austrian compounders while compressing pricing premiums for legacy formulations. This material transition concentrates procurement power with construction developers who specify REACH-registered alternatives, forcing non-integrated suppliers into margin erosion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 9001-certified compounders from REACH-registered suppliers and uncertified regional producers. Price differentiation hinges on shell chemistry complexity and captive resin production, with melamine-formaldehyde systems commanding premiums over urea-formaldehyde alternatives. Cost compression in standard tiers is intensifying because paraffin feedstock volatility transmits directly to non-integrated compounders. Construction developers exhibit highest price sensitivity, while electronics OEMs absorbing die-level thermal management costs show least.
Supply Chain Analysis
Strategic stockpiling of paraffin feedstock and shell polymer precursors dominates inventory strategy among German compounders facing crude oil derivative volatility. Manufacturing concentrates in Germany, the United States, and China, with captive resin production anchoring supply security for integrated conglomerates. The chain draws from petroleum refining byproducts and formaldehyde-based polymer precursors, exposing margins to energy commodity swings. Single-source vulnerability in melamine-formaldehyde shell chemistry elevates risk profiles. Distribution runs through construction chemical distributors in Europe and direct OEM relationships in North American HVAC channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large European construction developers and North American HVAC equipment manufacturers who consolidate procurement around vertically integrated compounders with captive resin production and REACH certification.
For Market Incumbents: Shield formulation leadership by accelerating polyurethane shell chemistry validation cycles before DIN 4102 fire safety ratings harden against organic phase change materials. Deepen backward integration into paraffin feedstock refining to insulate margins from crude oil volatility. Prioritize direct OEM relationship formation with Carrier and Trane specification teams over distributor channel maintenance.
For New Entrants and Emerging Players: Application-specific formulation support for textile integrators represents a service-layer gap where incumbents under-serve sub-100-micron capsule specifications. Target Japan's Nagoya-Osaka corridor for electronics cooling qualifications under JIS thermal performance protocols. Penetrate through technical service partnerships with fiber coating operations rather than commodity capsule supply.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap compounders with REACH-registered shell chemistry and existing textile industry relationships, positioned for METI subsidy capture in Japanese building efficiency retrofits. Long-term viability rests on regulatory certification depth rather than scale alone. Watch ECHA formaldehyde precursor classification thresholds as the inflection signal triggering consolidation among melamine-formaldehyde dependent suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Acquisition | ECHA shell chemistry compliance gates access to French RE2020 and German EnEV specification pipelines. |
| Backward Integration into Resin Production | Captive polymer supply secures margin stability against formaldehyde precursor cost volatility. |
| Direct OEM Relationship Formation | Carrier and Trane procurement consolidation displaces distributor channels for HVAC thermal storage. |
| Sub-100-Micron Capability Investment | Japanese textile integrators demand precise diameter control for thermal regulation fiber embedding. |
| Polyurethane Shell Reformulation | DIN 4102 reaction-to-fire ratings threaten melamine-formaldehyde substitution in high-rise envelopes. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, Cefic construction chemical reports, and ECHA registration databases. Interviews with plant managers at German compounders, procurement leads at HVAC equipment manufacturers, technical R&D directors, and distribution channel partners informed supply chain and pricing dynamics. Bottom-up capsule volume estimates triangulate against top-down construction chemical market sizing.
Segmentation dimensions modeled include shell chemistry type, application vertical, packaging format, and end-user industry procurement authority across the projection horizon. CAGRs derive from regression analysis of historical envelope material specification rates against building code enforcement intensity. Forecast inputs incorporate paraffin feedstock price elasticity and REACH registration timeline assumptions.
Forecasts assume regulatory continuity in EU F-Gas Regulation, REACH shell chemistry requirements, and EPA TSCA oversight; material policy shifts would require re-modeling. ECHA formaldehyde precursor reclassification or DIN 4102 rating compression for organic phase change materials represent primary revision triggers. Revision becomes warranted when substitution rates for inorganic salt hydrates in high-rise applications cross threshold penetration in German and French construction specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
North America Phase Change Materials Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Global Glass Insulation Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Global High Temperature Insulation Materials Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Global Molded Foams Market