
 Expanded Perlite Market | 2026-2036
Expanded Perlite Market Size, Share, and Industry Trends Forecast 2026-2036
Expanded Perlite Market Analysis
Vermiculite substitution in high-temperature insulation is consolidating expanded perlite's cost advantage across industrial applications. Imerys SA leverages captive mining assets in Greece to sustain raw material security for European customers. Hess Perlite anchors North American supply through vertically integrated quarry-to-bag operations. Gulf Perlite LLC differentiates via specialized grades for Middle Eastern construction markets.
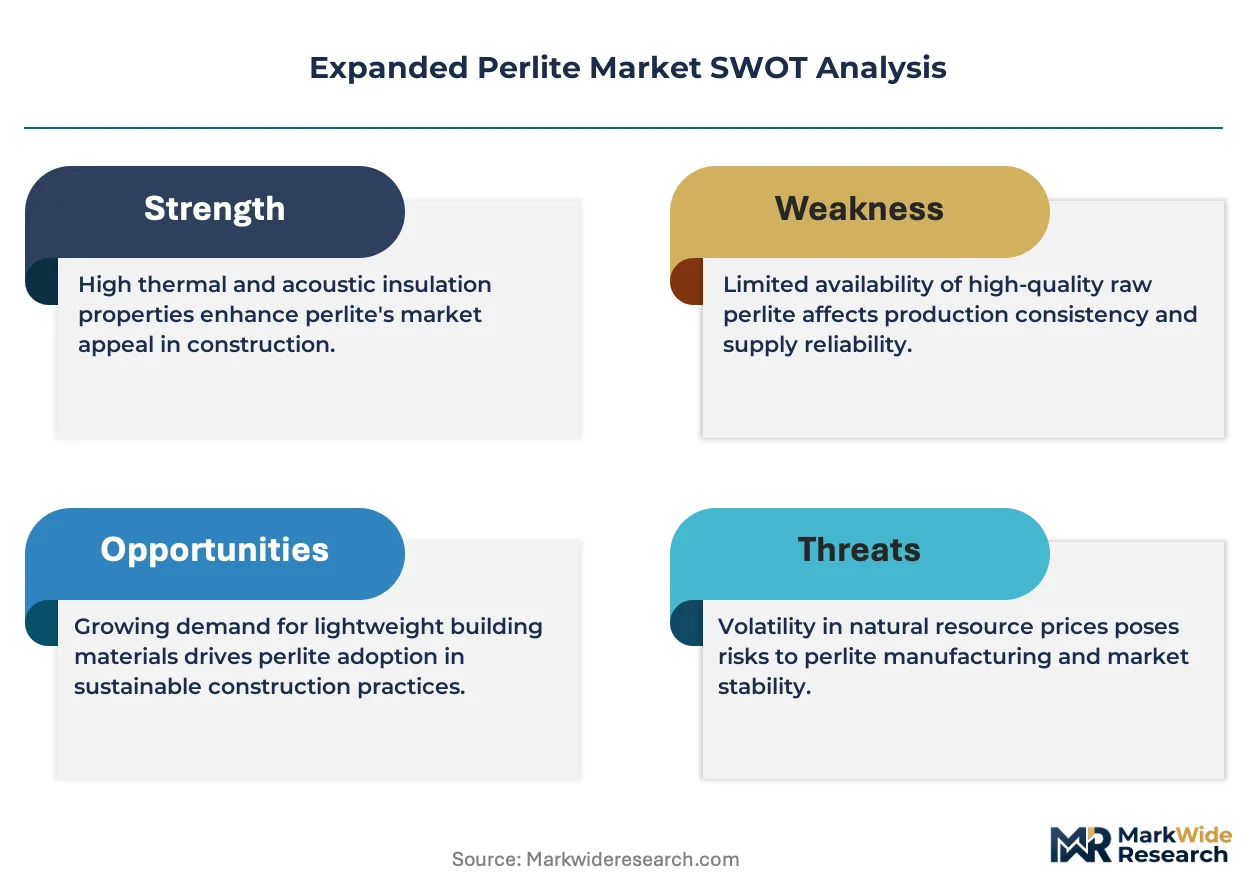
Expanded perlite is a volcanic glass that expands four to twenty times its original volume when heated above 871°C, creating a lightweight, porous structure with bulk densities ranging from 32 to 240 kg/m³. Its primary industrial purpose centers on thermal insulation, soil conditioning, and filtration media where low density and chemical inertness prove critical. Construction grade dominates volume flows, while horticultural grade commands premium positioning amid controlled-environment agriculture expansion. Insulation material applications capture the deepest margin pools as energy-efficiency codes tighten across developed economies.
EPA emissions standards and OSHA workplace exposure limits shape production facility compliance costs and product certification requirements in the United States. REACH chemical registration and CE marking directives govern European market access, while ISO 9001 quality frameworks underpin cross-border commercial trust. Stakeholders must monitor evolving building energy codes and agricultural input regulations to anticipate grade-mix shifts and regional demand rebalancing.
Market Dynamics
The EU Green Deal and tightening F-Gas Regulation are forcing insulation material substitution across European construction, compressing demand timelines for specification-grade expanded perlite while concentrating procurement authority among certified passive house developers.
Growth Catalysts
- Energy-efficiency mandates:The EU Green Deal's building renovation targets are mandating thermal performance upgrades across residential and commercial stock, pulling specification-grade perlite into retrofit specifications.
- Controlled-environment agriculture:Hydroponic and greenhouse operators are specifying horticultural-grade perlite for soilless growing media, creating premium volume channels distinct from commodity construction flows.
- Industrial heat containment:Foundries and petrochemical facilities are expanding high-temperature insulation specifications where perlite's cost position against vermiculite and ceramic fiber proves decisive.
Market Restraints
- Raw material geographic concentration:Commercial-grade perlite ore deposits cluster in Greece, Turkey, and the western United States, exposing processors to single-source supply risk and freight cost volatility.
- Expansion energy intensity:Kiln operations require sustained temperatures above 871°C, tying production economics to natural gas pricing and carbon cost exposure under EU ETS.
- Silica dust exposure limits:OSHA permissible exposure limits and REACH workplace substance classifications impose ventilation and PPE capital requirements that elevate facility compliance costs.
Strategic Opportunities
- Passive house construction clusters:Germany, Austria, and Belgium are concentrating certified building activity, creating demand density for specification-grade insulation with documented thermal performance.
- Filtration media specification:Biopharmaceutical and food-grade filtration applications are adopting perlite for depth filtration where inertness and particle size distribution prove critical.
- Green building certification alignment:LEED v4.1 and BREEAM material health credits are rewarding low-embodied-carbon insulation selections, positioning expanded perlite against synthetic foam alternatives.
Industry Challenges
- Kiln operator skill scarcity:Expansion furnace optimization requires experienced technicians capable of managing temperature gradients and particle residence times to achieve target bulk densities.
- Grade-specific certification timelines:Food-contact and pharmaceutical-grade perlite production requires HACCP and ISO 22000 validation cycles that extend market entry timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expanded Perlite Market |
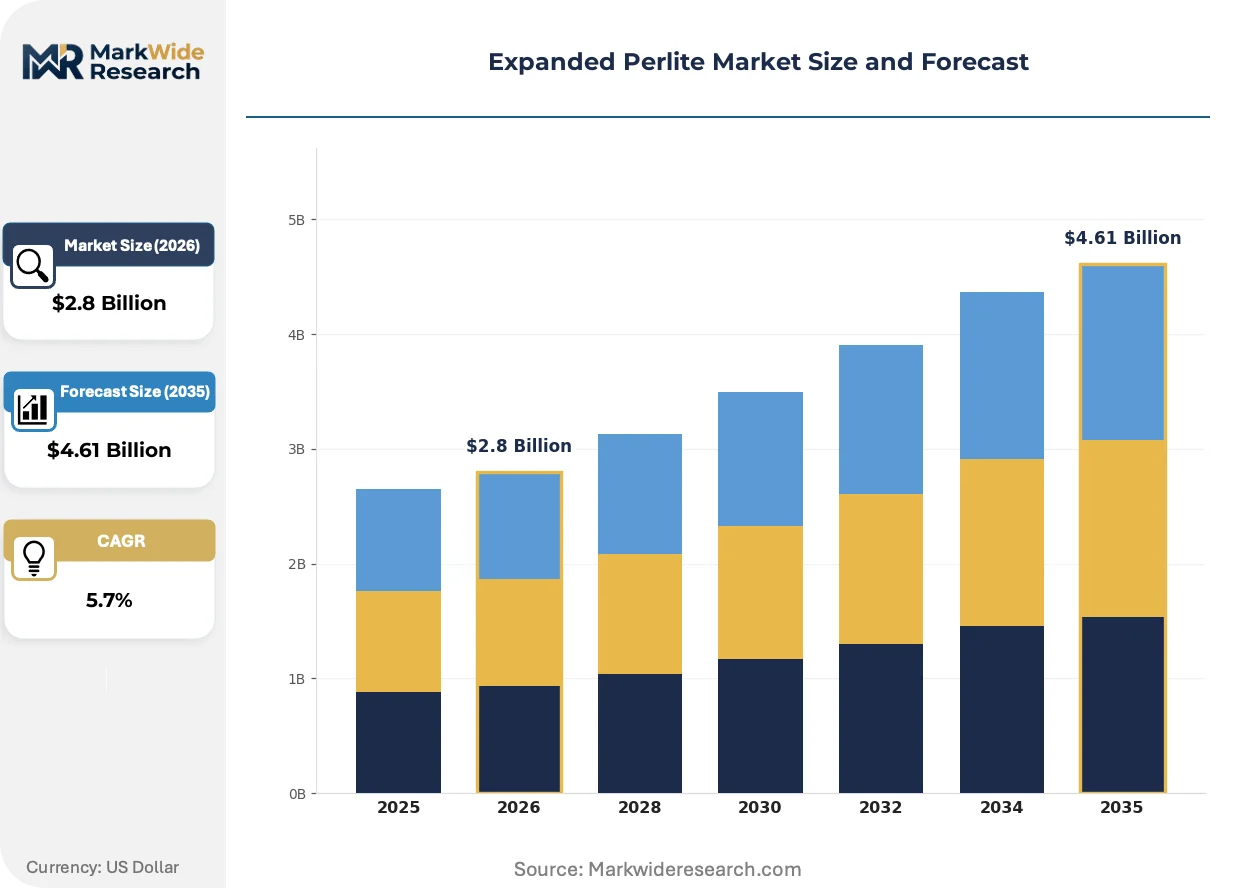
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horticultural Grade, Industrial Grade, Food Grade, Construction Grade Application: Soil Amendment, Insulation Material, Lightweight Fill, Filtration Aid End User: Agriculture, Construction, Food Processing, Chemical Industry Packaging Type: Bags, Bulk Containers, Pallets, Intermediate Bulk Containers |
| Companies Covered | Johns Manville, Gulf Perlite LLC, Imerys SA, Hess Perlite, Dicalite Management Group, Supreme Perlite Company, AUSPERL, Perlite-Hellas, Silbrico Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expanded Perlite Market Emerging Trajectories
Advanced expansion control technologies and regulatory chemistry restrictions are compressing product development cycles while fragmenting grade specifications across end-use verticals.
Precision microwave expansion is rewriting thermal processing economics in expanded perlite manufacturing. The technology replaces conventional rotary kilns with controlled electromagnetic heating, reducing energy consumption and enabling real-time density adjustment. Specialty insulation producers in Germany and Japan are piloting installations to serve specification-grade architectural markets. This process control is compressing batch-to-batch variability and enabling just-in-time grade switching that conventional kiln infrastructure cannot match.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents is mandating reformulation across polyurethane and polystyrene insulation supply chains. Perlite-based loose-fill and board products are capturing specification switches where thermal performance parity eliminates synthetic foam cost advantages. Nordic building codes are tightening fastest, pulling Nordic and Baltic distributors into forward contracting relationships with Greek and Turkish ore processors.
Buyers are consolidating procurement authority through tier-one distributor networks that bundle insulation specification with installation certification. Regional building material distributors in France and the Netherlands are absorbing specification risk by maintaining certified perlite inventories and training contractor networks on proper placement density. This channel concentration is compressing direct mill relationships and elevating distributor technical service capabilities as the primary competitive interface.
Expanded Perlite Market Segmentation
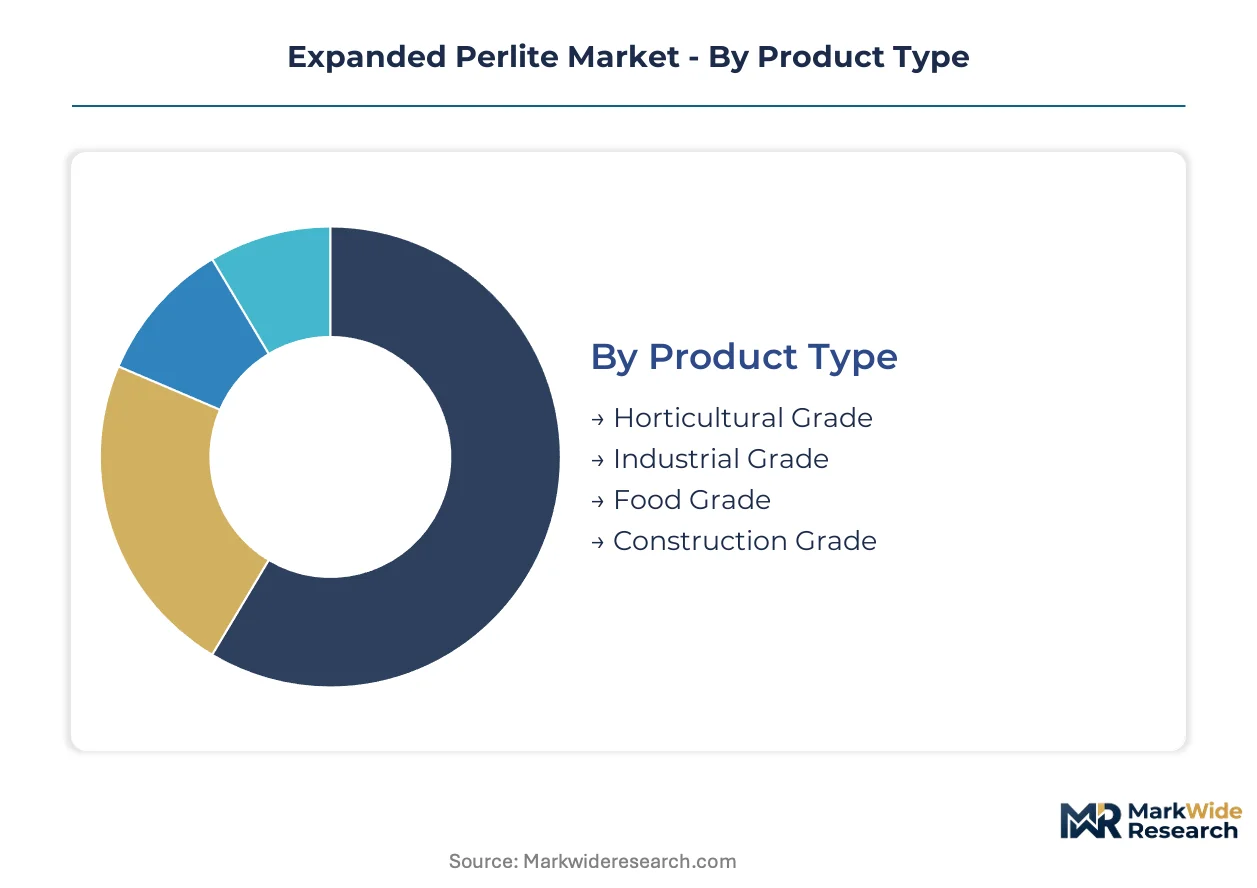
Expanded perlite's diverse physical properties create distinct value propositions across thermal performance, particle size distribution, and chemical purity requirements. Buyers prioritize different specifications based on end-use criticality, from passive house thermal targets to pharmaceutical filtration standards. Grade differentiation drives pricing spreads and supplier certification investments.
Product Type:
Cost tier separates commodity construction material from certified specialty grades requiring documented purity chains.
- Construction Grade:Coarse particle fractions with bulk densities of 80-120 kg/m³ dominate loose-fill cavity wall and flat roof insulation across German passive house developments. The EU Green Deal's building renovation targets are pulling specification-grade volumes into retrofit contracts requiring documented lambda values.
- Horticultural Grade:Fine-screened fractions between 0.5-4.0mm particle size provide aeration and drainage in soilless growing media. Dutch greenhouse operators and Spanish hydroponic facilities are expanding offtake amid controlled-environment agriculture investment.
- Industrial Grade:Intermediate density grades serve foundry ladle lining and cryogenic tank base fill where thermal shock resistance matters.
- Food Grade:Acid-washed and calcined material meets FDA and EFSA purity requirements for filtration aid applications in edible oil and beverage processing.
Construction Grade leads volumes today; Horticultural Grade is gaining share fastest.
Application:
Application choice tracks building code maturity and agricultural input intensity across regional markets.
- Insulation Material:Loose-fill, board, and sprayed applications exploit perlite's low thermal conductivity and fire resistance. Nordic building codes in Sweden, Finland, and Denmark are tightening U-value requirements fastest, compressing substitution timelines against synthetic foams.
- Soil Amendment:Volume concentrates in container nursery operations and greenhouse substrate blending where drainage and root aeration prove critical. Spanish Almería greenhouse clusters and Dutch Westland horticulture zones drive specification.
- Filtration Aid:Diatomaceous earth replacement in biopharmaceutical and food-grade depth filtration requires tight particle size distribution control and low heavy metal content.
- Lightweight Fill:Structural concrete admixture and geotechnical applications exploit density reduction without compressive strength sacrifice.
Insulation Material anchors revenue pools; Soil Amendment exhibits the steepest expansion trajectory.
End User:
Customer type determines certification burden and technical service intensity required from suppliers.
- Construction:General contractors and insulation specialists specify perlite for thermal envelope compliance in residential and commercial builds. German KfW funding programs and French RE2020 regulations are mandating performance documentation that favors certified suppliers.
- Agriculture:Commercial greenhouse operators and substrate blenders prioritize consistent particle size and low dust content for mechanized handling systems.
- Food Processing:Edible oil refiners and beverage clarifiers require HACCP-validated supply chains with batch traceability.
- Chemical Industry:Catalyst support and cryogenic insulation applications demand low alkali content and thermal stability certification.
Construction dominates procurement volumes; Agriculture is climbing the fastest on controlled-environment expansion.
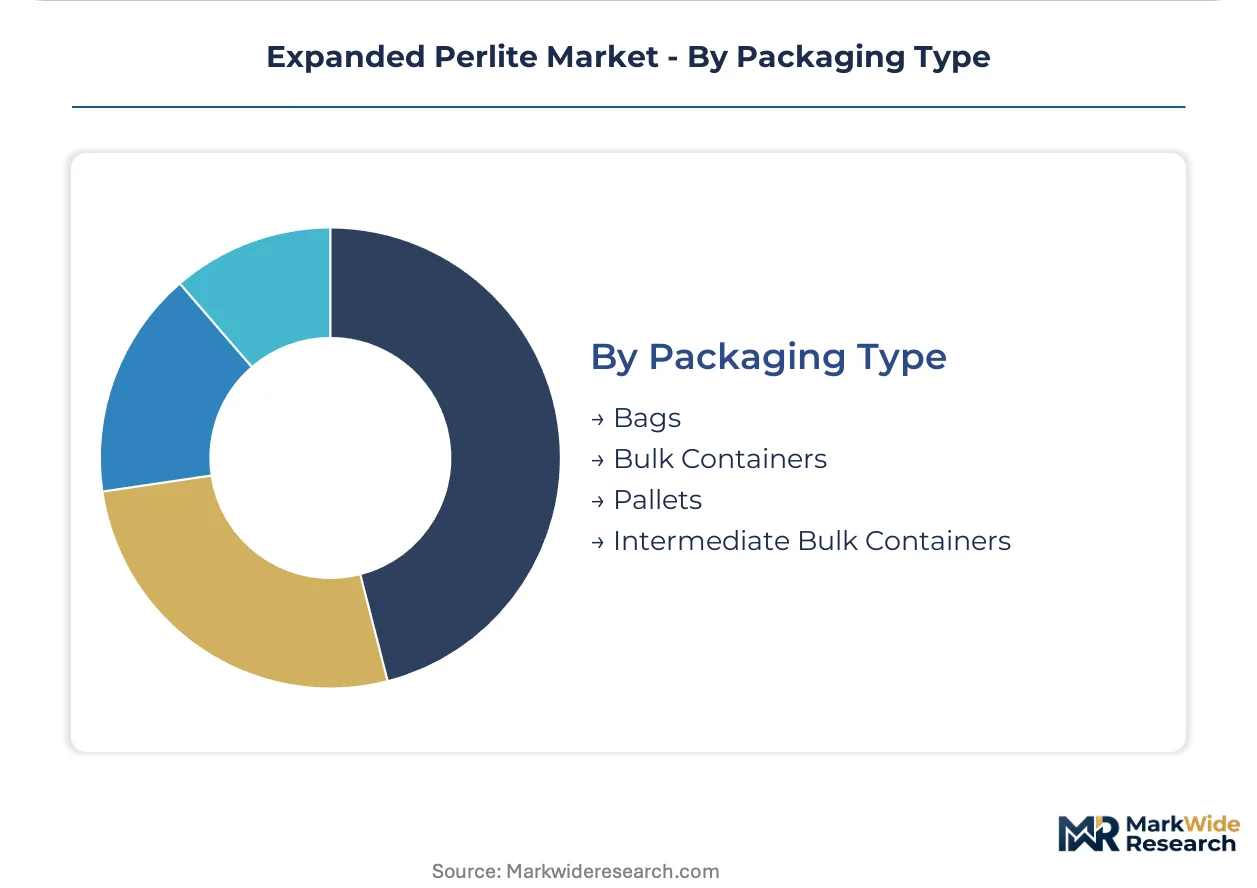
Packaging Type:
Packaging selection balances handling economics, contamination risk, and site logistics constraints.
- Bags:50-100lb multi-wall paper or polypropylene sacks serve retail garden centers and small-scale contractors requiring weather-protected storage. French and Italian building material distributors maintain palletized bag inventories for contractor pickup.
- Bulk Containers:Loose pneumatic delivery to silo systems minimizes packaging waste for large insulation contractors and substrate blenders.
- Intermediate Bulk Containers:1-2 cubic meter flexible or rigid totes bridge unit economics between bags and bulk for mid-scale greenhouse operations.
- Pallets:Unitized bag shipments enable forklift handling and inventory tracking for distributor warehouse operations.
Bags retain the widest addressable market; Bulk Containers are expanding most quickly on project-scale procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German passive house construction clusters anchor expanded perlite demand across the European insulation supply chain. KfW funding programs and RE2020-equivalent standards in neighboring markets are compressing specification timelines for certified thermal materials. Ore processors in Greece and Turkey face forward contracting pressure from Nordic distributors responding to tightening building codes.
Germany
Passive house certification programs in Bavaria and Baden-Württemberg are pulling specification-grade perlite into retrofit contracts requiring documented lambda values. The EU Green Deal's building renovation targets mandate thermal performance upgrades across residential stock. Stuttgart and Freiburg construction clusters concentrate procurement authority among certified developers.
United States
EPA emissions standards and OSHA silica exposure limits shape production facility compliance costs across western mining operations. The Inflation Reduction Act's energy-efficiency tax credits accelerate insulation specification in residential construction. Hess Perlite's vertically integrated quarry-to-bag operations in the Mountain West anchor North American supply security.
Greece
Imerys SA leverages captive mining assets on Milos Island to sustain raw material security for European customers. REACH chemical registration governs export market access while CE marking directives validate construction-grade certification. Aegean ore deposits concentrate commercial-grade perlite extraction for continental processor supply.
Netherlands
Dutch greenhouse operators in the Westland horticulture zone drive horticultural-grade perlite specification for soilless growing media. Controlled-environment agriculture investment expands substrate blender demand for fine-screened fractions. Rotterdam distributor networks bundle insulation specification with installation certification across Benelux markets.
United Arab Emirates
Gulf Perlite LLC differentiates via specialized grades for Middle Eastern construction markets facing extreme thermal cycling conditions. MOHAP and local building codes govern material import certification for high-performance envelope applications. Dubai and Abu Dhabi commercial development clusters specify lightweight fill and insulation for large-scale projects.
Expanded Perlite Market Vendor Landscape
Capacity expansion dominates the current landscape as ore processors respond to tightening European insulation demand timelines. The vendor base separates into three tiers: integrated miners with captive deposits, regional expansion specialists, and distribution-focused blenders. Strategic archetypes include backward-integrated quarry operators, specification-grade certification specialists, and channel-aggregating distributors. M&A activity and kiln technology licensing represent the dominant competitive moves as players secure thermal processing capabilities.
Among integrated mining and processing specialists, Imerys SA and Hess Perlite exemplify the backward-integrated archetype through captive ore control. Gulf Perlite LLC occupies a position within the regional specialization tier serving Middle Eastern construction specifications. These three entities represent distinct geographic anchoring strategies—European, North American, and Gulf-based respectively—while sharing a common reliance on vertical control over raw material security.
| Leading Market Players |
|---|
| Johns Manville |
| Gulf Perlite LLC |
| Imerys SA |
| Hess Perlite |
| Dicalite Management Group |
| Supreme Perlite Company |
| AUSPERL |
| Perlite-Hellas |
| Silbrico Corporation |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's building renovation mandates gate qualified supply access and premium-tier pricing power for specification-grade expanded perlite across European construction markets. Certified passive house developers command documented lambda values that commodity grades cannot match, compressing procurement timelines and elevating price premiums for validated thermal performance.
Pricing Analysis
Natural gas pass-through economics dominate expanded perlite production costs, with kiln operations requiring sustained temperatures above 871°C tying margin structures to energy market volatility. Three-tier pricing structure across specification-grade, construction-grade, and bulk horticultural levels separates certified insulation material from commodity cavity fill. Pricing pressure stems from EU ETS carbon cost exposure and freight rate volatility on Aegean ore shipments. General contractors exhibit highest price sensitivity on retrofit volumes, while pharmaceutical filtration buyers accept premium positioning for HACCP-validated supply chains.
Supply Chain Analysis
Return flows of spent perlite from filtration applications and demolition sites create limited but emerging circular material streams for lower-grade construction fill. Commercial-grade ore deposits concentrate in Greece, Turkey, and the western United States, exposing processors to single-source risk on Milos Island and Anatolian plateau extraction. Production draws from volcanic glass mining, natural gas feedstock, and specialized expansion furnace equipment. Single-source vulnerability on Greek ore dominates supply risk profiles. Distribution runs through tier-one building material distributors in Germany, France, and the Netherlands that bundle specification with installation certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's hydrofluorocarbon phasedown compounds insulation demand across retrofit construction, positioning expanded perlite as a structural beneficiary of synthetic foam substitution mandates.
For Market Incumbents: Lock in forward contracting relationships with Greek and Turkish ore processors before Nordic building code tightening accelerates procurement competition. Defend margin position by investing in precision microwave expansion technology that reduces energy intensity and enables real-time density adjustment for specification-grade markets. Ceramic fiber and aerogel insulation substitutes threaten premium positioning; counter with CE-marked thermal performance documentation and passive house certification alignment. For New Entrants and Emerging Players: The mid-tier price gap between specification-grade and bulk construction material creates white-space opportunity for regional expansion specialists serving horticultural substrate blenders. Target Dutch Westland greenhouse clusters and Spanish Almería hydroponic facilities with fine-screened fractions optimized for mechanized handling systems. Enter through toll-processing arrangements with captive ore holders rather than greenfield mining investment, leveraging existing kiln infrastructure for faster market access. For Investors and Strategic Acquirers: Roll-up economics work for regional expansion specialists because kiln operator skill scarcity and grade-specific certification timelines create durable moats against commoditization. Platform consolidation of Benelux and Nordic distributors with technical service capabilities captures channel concentration benefits. Long-term viability hinges on EU Green Deal implementation pace; monitor KfW funding program allocations and RE2020-equivalent regulation adoption across Austria, Belgium, and France for demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Ore Assets | Imerys SA's Milos Island deposits secure raw material security against Aegean supply concentration risk. |
| Precision Microwave Expansion Technology | German and Japanese pilot installations enable real-time density adjustment for specification-grade architectural markets. |
| Long-term Supply Agreement with Nordic Distributors | Forward contracting with Greek processors responds to Swedish and Finnish building code tightening timelines. |
| Joint Venture for Middle Eastern Specialization | Gulf Perlite LLC's extreme thermal cycling grades address Dubai commercial development cluster specifications. |
| Green Manufacturing Transition | EU ETS carbon cost exposure drives kiln energy efficiency investment and renewable natural gas sourcing. |
Methodological Framework
Coverage spans Western Europe, North America, and the Middle East, with primary inputs from each region combined with secondary validation. Interviews with perlite expansion plant managers, insulation contractor procurement leads, Dutch greenhouse substrate blenders, and Greek mining operations directors informed supply-side and demand-side perspectives. Secondary sources include EU customs trade data, SEC 10-K filings from listed industrial minerals companies, REACH chemical registration databases, and passive house certification body records. Bottom-up volume modeling triangulates against top-down construction spending and agricultural input intensity metrics.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. Segmentation dimensions modeled include grade tier, end-use application, packaging format, and regional production hub proximity to demand clusters. CAGRs derive from regression analysis of historical ore extraction rates, building permit issuance trends, and controlled-environment agriculture investment flows. Industry-specific forecast inputs incorporate EU Green Deal renovation target implementation schedules and F-Gas Regulation phasedown timelines.
Caveats apply where natural gas price volatility, Aegean shipping disruption, or REACH substance classification revisions could materially shift the outlook. Practitioners should monitor KfW funding disbursement rates and Nordic U-value code adoption for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
Asia-Pacific Insulation Materials Market
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Multi-Layer Cryogenic Insulation Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market