
 Global Insulation Market | 2026-2036
Global Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insulation Market Outlook
Retrofit service revenue is narrowing as manufacturers bundle installation with material sales to capture lifecycle value. Owens Corning leverages its roofing and insulation integration to control contractor channels across North America. Saint-Gobain sustains European leadership through mineral wool specialization and building chemistry adjacencies. BASF SE anchors polyurethane foam supply with in-house polyol production and chemical process expertise.
Insulation comprises engineered materials designed to reduce heat transfer between environments, with thermal conductivity ratings typically measured in watts per meter-kelvin and performance validated under ASTM C518 or ISO 8301 protocols. Its primary commercial purpose is to minimize energy consumption in climate-controlled enclosures and industrial process equipment. Fiberglass occupies the largest installed base due to cost position and fire resistance, while polyurethane foam captures premium margin pools in space-constrained commercial and industrial applications where higher R-values per inch determine specification. Mineral wool competes aggressively in fire-rated assemblies and acoustic treatment segments where building codes mandate non-combustible materials.
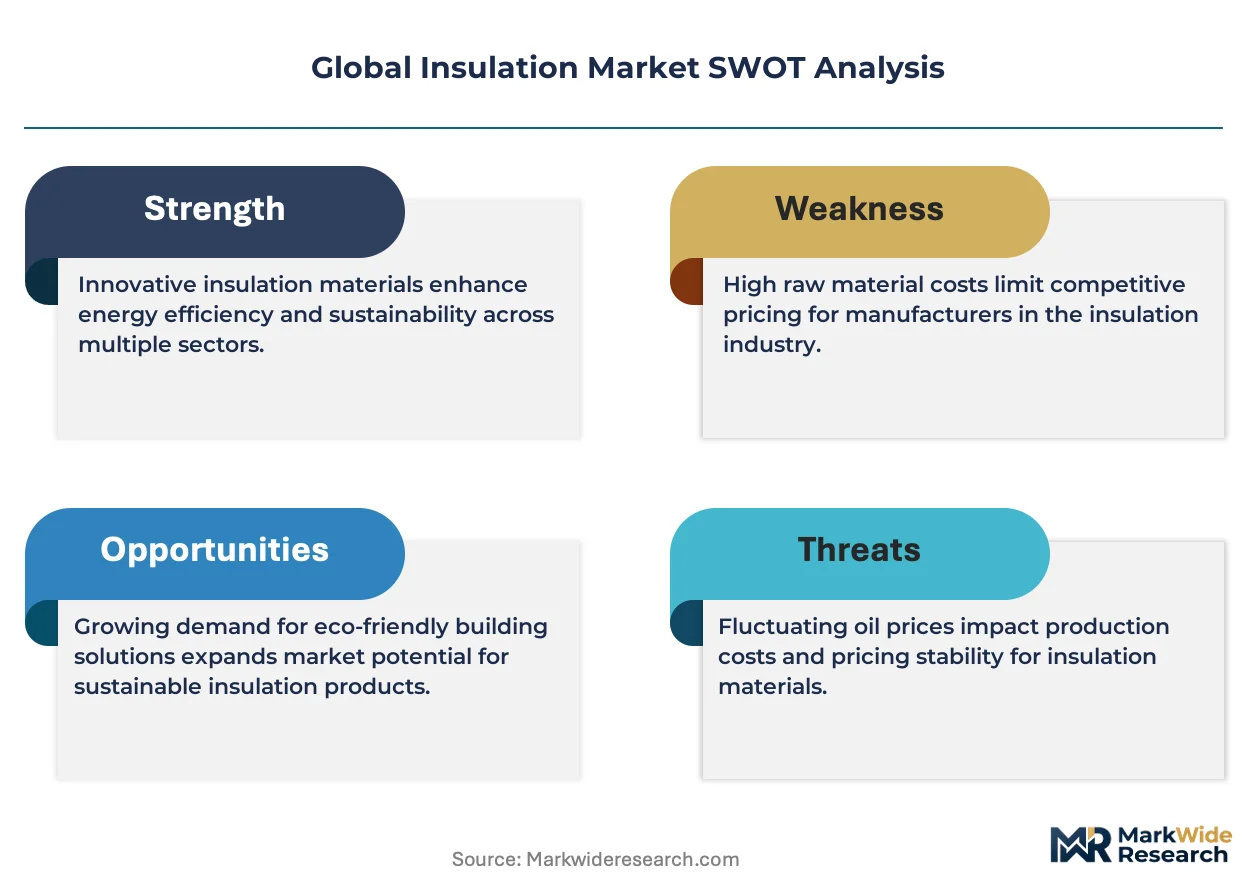
The EU Green Deal and REACH frameworks in Europe, the IRA energy efficiency tax credits administered by the US Department of Energy, and China's dual carbon goals enforced by MEE collectively redirect specification toward lower-embodied-carbon insulation products and verified thermal performance claims. These regulatory architectures create compliance cost differentials that favor producers with certified environmental product declarations and transparent supply chain documentation. Stakeholders must monitor evolving carbon border adjustments and embodied carbon disclosure requirements that will reshape competitive positioning in cross-border material procurement.
Market Dynamics
Carbon border adjustments and embodied carbon disclosure mandates are rewiring specification criteria across construction procurement, forcing insulation manufacturers to certify supply chains or forfeit specification in public and commercial tenders.
Growth Catalysts
- EU Green Deal enforcement:Mandatory building renovation targets in Germany and France are accelerating mineral wool and bio-based insulation demand in commercial retrofits.
- US IRA tax credits:The Department of Energy's efficiency rebates are pulling polyurethane foam into residential deep-energy retrofits that previously specified fiberglass.
- China's dual carbon goals:MEE enforcement of industrial energy intensity standards is expanding high-temperature insulation demand in steel and petrochemical process equipment.
Market Restraints
- MDI price volatility:Polyurethane foam producers face margin compression when benzene and crude oil derivatives spike, with limited pass-through in fixed-price construction contracts.
- Mineral wool supply concentration:European basalt and slag fiber capacity clusters in Poland and the Czech Republic, creating disruption risk from energy cost spikes or logistics bottlenecks.
- Fiberglass R-value ceiling:The material's thermal performance per inch hits physical limits that disqualify it from space-constrained commercial envelope assemblies.
Strategic Opportunities
- India's building code tightening:BIS energy conservation standards in commercial construction remain underenforced, creating first-mover advantage for EPD-certified suppliers.
- Cold chain expansion:Refrigerated logistics and pharmaceutical distribution are specifying vacuum insulation panels for ultra-low-temperature transport.
- Building-integrated photovoltaics convergence:Insulation-embedded solar thermal collectors are opening envelope-system bundling opportunities in Nordic markets.
Industry Challenges
- EPD certification timelines:Third-party verified environmental product declarations require 12-18 month data collection cycles that lag regulatory deadlines.
- Installer skill fragmentation:Spray polyurethane foam application demands certified technician networks that remain thin outside major metropolitan construction corridors.
- Legacy building stock heterogeneity:Retrofit contractors encounter unpredictable substrate conditions that complicate standardized insulation system design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insulation Market |
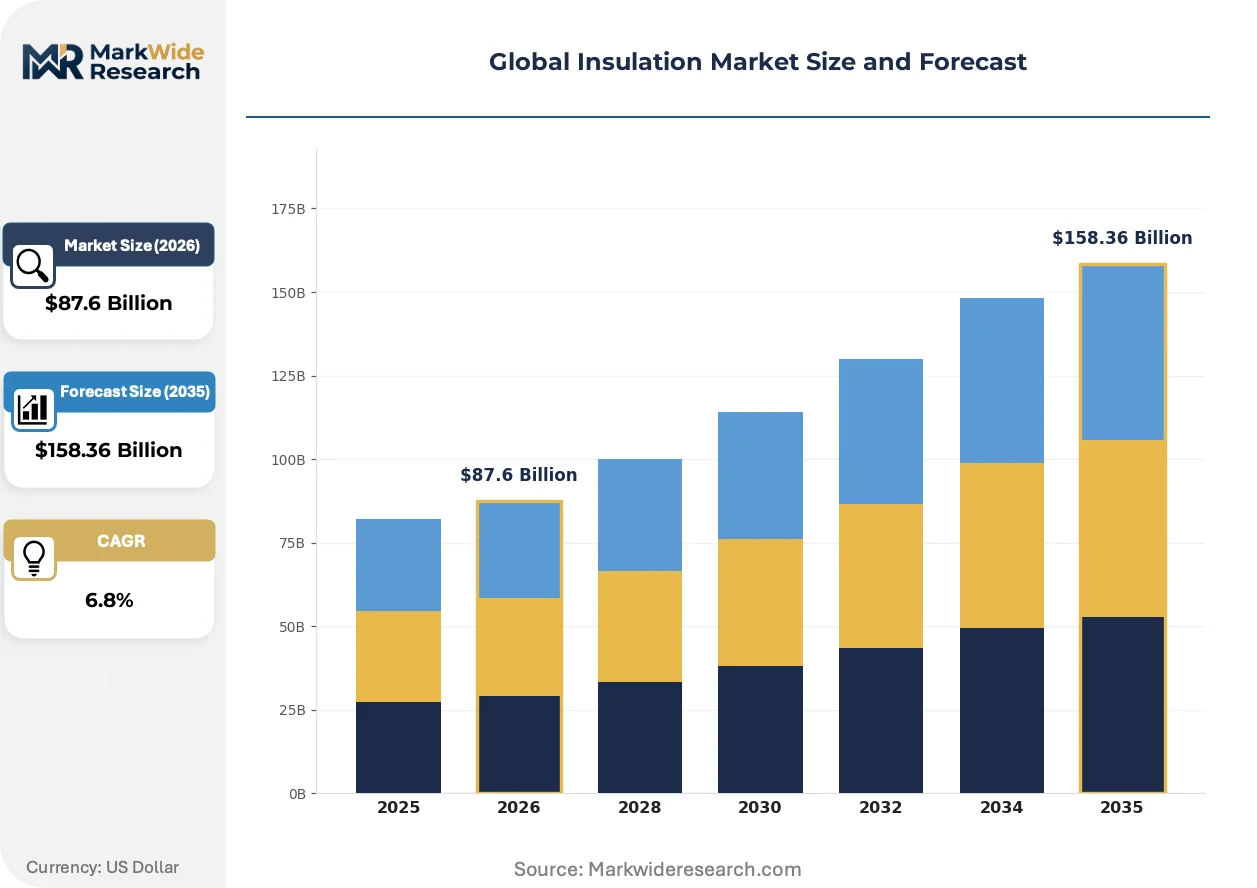
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Foam, Cellulose, Mineral Wool Application: Residential, Commercial, Industrial, Automotive End User: Building Contractors, Manufacturers, DIY Consumers, Insulation Installers Material: Polystyrene, Polyurethane, Natural Fibers, Others |
| Companies Covered | Owens Corning, Saint-Gobain, Rockwool International A/S, Knauf Insulation, Kingspan Group, Johns Manville, BASF SE, 3M, Morgan Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insulation Market Strategic Shifts
Material science advances and procurement digitization are converging to compress specification cycles and elevate performance transparency as primary competitive differentiators.
Aerogel-enhanced blankets are hybridizing conventional silica-based thermal barriers with flexible substrates to serve industrial pipe insulation and aerospace applications. Oil and gas facility operators in the US Gulf Coast are specifying these composites for cryogenic LNG infrastructure. The technology is hybridizing the performance tier between rigid vacuum panels and conventional mineral wool, capturing margin pools in temperature-extreme process equipment.
REACH restrictions on flame retardant chemistries are forcing reformulation of expanded polystyrene and polyurethane systems across European construction. Manufacturers are shifting to halogen-free alternatives that maintain fire ratings under EN 13501-1 protocols. German and Dutch residential developers are absorbing 8-12% material cost premiums to maintain CE marking compliance and avoid specification exclusion.
Digital building passports are altering how facility managers evaluate lifecycle thermal performance rather than upfront installed cost. Commercial real estate investment trusts in the United Kingdom and Australia are embedding insulation EPDs into asset valuation models. This behavior is most visible in Class A office retrofits where green bond financing eligibility hinges on verified embodied carbon thresholds.
Global Insulation Market Segmentation
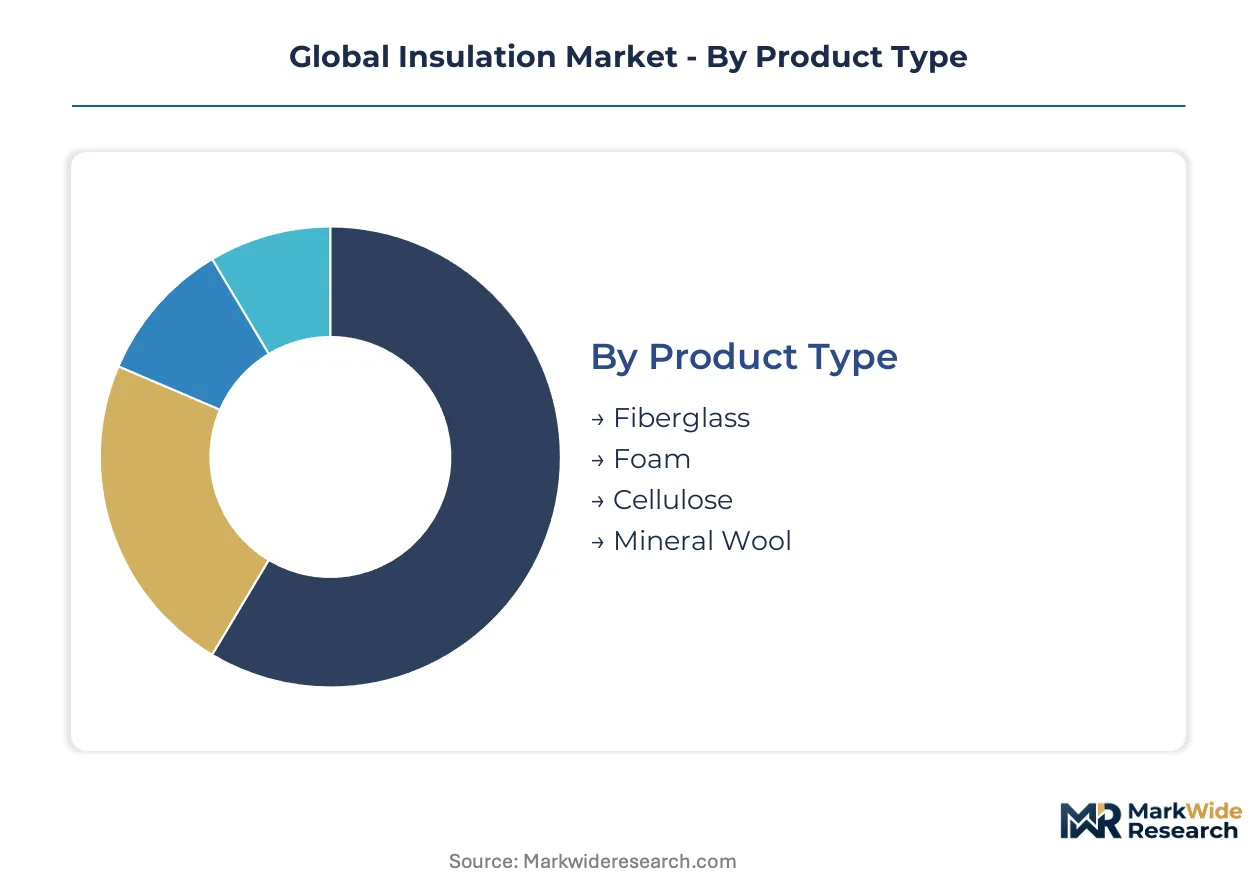
Insulation specification varies sharply by thermal performance requirements, fire code mandates, and installation constraints. Segment boundaries determine margin pools, with premium materials commanding lifecycle-based pricing in commercial envelopes while commodity products compete on installed cost in residential new construction.
Product Type:
After-sales service intensity diverges dramatically across product categories, with spray foam demanding certified technician networks for warranty validity while fiberglass and mineral wool tolerate broader installer bases.
- Fiberglass:Composed of fine glass fibers bound with phenolic resin, delivering R-values between 2.9 and 3.8 per inch depending on density and batt configuration. Demand concentrates in US residential new construction where tract home builders prioritize installed cost over space efficiency; IRA tax credits are pulling some volume into deep-energy retrofits previously dominated by air-sealing upgrades. Fiberglass holds the largest share; momentum sits with foam systems in space-constrained commercial assemblies.
- Foam:Comprises closed-cell polyurethane and open-cell variants achieving R-values of 6.0 to 7.0 per inch, with spray application creating monolithic air barriers. Specification is accelerating in German and French commercial retrofits where EU Green Deal renovation targets mandate higher thermal performance in limited envelope depths; installation complexity limits adoption outside major metropolitan contractor networks.
- Cellulose:Recycled paper fiber treated with borate fire retardants, blown into wall cavities and attics at R-values near 3.5 per inch. DIY consumers in North America favor this material for attic top-ups where loose-fill application requires minimal specialized equipment.
- Mineral Wool:Spun from basalt or industrial slag, delivering non-combustible performance rated to 1,000°C. Fire-rated assemblies in UK and Australian commercial high-rises specify this material where building codes mandate zero flame spread indices.
Fiberglass dominates installed volume; foam systems are climbing the fastest in commercial retrofit specifications.
Application:
Cost tier stratification separates residential commodity procurement from industrial process equipment where thermal failure carries catastrophic operational consequences.
- Residential:Single-family and multifamily climate envelope applications including attics, walls, and foundations. US Department of Energy rebate programs are reshaping material mix toward higher-performance options in owner-occupied housing; production builders in Texas and Florida remain cost-driven with fiberglass dominant.
- Commercial:Office, retail, and institutional envelope systems where energy code compliance and green bond financing eligibility intersect. UK Class A office REITs are embedding EPD documentation into asset valuation models, elevating specification transparency.
- Industrial:Process equipment, storage tanks, and high-temperature piping in steel, petrochemical, and power generation facilities. MEE enforcement of energy intensity standards in China is expanding demand for calcium silicate and ceramic fiber systems in Jiangsu and Shandong province steel mills.
- Automotive:NVH dampening and thermal management in electric vehicle battery enclosures and cabin comfort systems. OEMs are specifying aerogel composites for lithium-ion thermal runaway protection where space and weight constraints collide with safety mandates.
Residential captures the greatest unit volume; industrial applications command the steepest price premiums per installed square meter.
End User:
Customer type determines procurement sophistication, with building contractors negotiating annual supply agreements while DIY consumers respond to seasonal promotional cycles at retail.
- Building Contractors:General and specialty contractors procuring materials for new construction and major renovation projects. Large US homebuilders are consolidating supplier relationships with Owens Corning and Johns Manville to secure volume pricing and dedicated logistics scheduling.
- Manufacturers:OEMs and subsystem integrators embedding insulation into appliances, HVAC equipment, and transportation platforms. Refrigeration equipment manufacturers in Germany specify vacuum insulation panels for ultra-low-temperature pharmaceutical storage units.
- DIY Consumers:Homeowners purchasing retail-format batts, rolls, and loose-fill for attic and basement projects. Big-box retailers in Canada and Australia stock expanded product ranges during shoulder seasons preceding heating and cooling peaks.
- Insulation Installers:Specialized contractors focused exclusively on thermal envelope and mechanical insulation services. Spray foam certification requirements in California and New York limit market entry to established operators with technician training infrastructure.
Building contractors move the greatest material tonnage; manufacturers represent the fastest-expanding specification channel with embedded insulation in electrification infrastructure.
Material:
Supply concentration shapes competitive dynamics, with polyurethane feedstock tied to MDI capacity controlled by BASF, Covestro, and Huntsman while natural fiber sources fragment across agricultural suppliers.
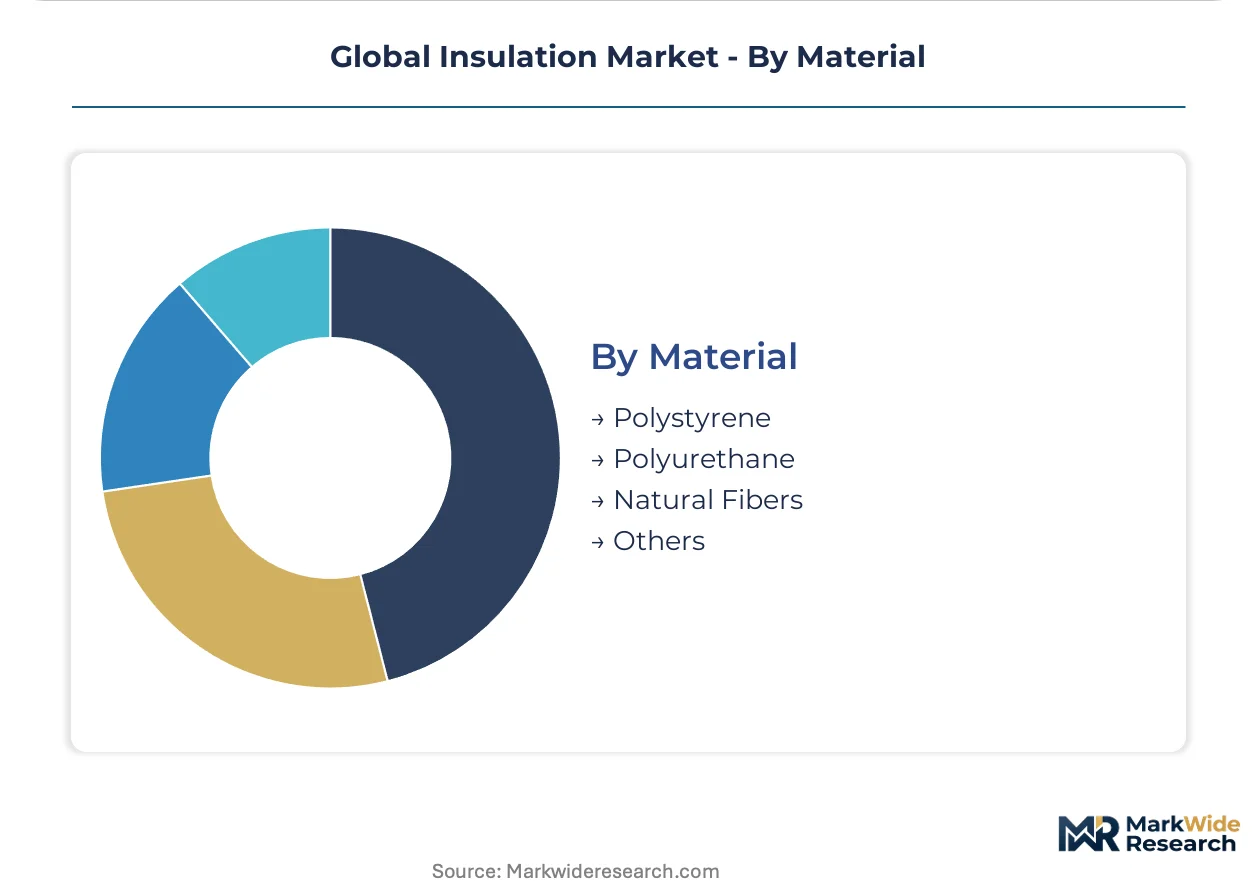
- Polystyrene:Expanded and extruded variants offering moisture resistance and moderate R-values at low material cost. REACH flame retardant restrictions are forcing European producers toward halogen-free formulations absorbing 8-12% cost premiums to maintain CE marking compliance.
- Polyurethane:Reaction of polyols and isocyanates creating rigid foam boards and spray-applied systems. In-house polyol production at BASF SE anchors supply security for high-performance commercial specifications where thermal bridging elimination justifies material premiums.
- Natural Fibers:Hemp, flax, and sheep wool insulation targeting low-embodied-carbon building certifications. German and Dutch residential developers specify these materials for Passivhaus and BREEAM projects where environmental product declarations determine tender eligibility.
- Others:Aerogel, vacuum insulation panels, and phase-change materials serving temperature-extreme and space-constrained niches. LNG facility operators on the US Gulf Coast specify aerogel-enhanced blankets for cryogenic pipe insulation where conventional materials fail.
Polystyrene retains broadest adoption; natural fibers are expanding most quickly in EU Green Deal-aligned construction procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia remain acutely price-sensitive, squeezing margins on commodity fiberglass and polystyrene. German and US procurement teams absorb 15-20% premiums for certified low-carbon materials where green bond financing and regulatory compliance override first-cost considerations.
United States
IRA energy efficiency tax credits administered by the Department of Energy are accelerating deep-energy retrofits in owner-occupied housing. The EPA's emerging embodied carbon disclosure requirements for federal construction projects are elevating demand for EPD-certified products. Houston and Dallas-Fort Worth construction corridors concentrate spray polyurethane foam installation capacity serving commercial envelope retrofits.
Germany
Mandatory building renovation targets under EU Green Deal enforcement are pulling mineral wool and bio-based insulation into commercial retrofit pipelines. The country's national building energy regulator BAFA channels subsidies toward Passivhaus-certified assemblies. The Rhine-Ruhr industrial cluster anchors Rockwool and Knauf production facilities supplying renovation demand across Benelux and Northern France.
China
MEE enforcement of industrial energy intensity standards is expanding calcium silicate and ceramic fiber demand in steel and petrochemical process equipment. Dual carbon goals are tightening building envelope codes in tier-one cities. Jiangsu and Shandong province steel mills represent the fastest-growing specification channel for high-temperature insulation systems.
India
BIS energy conservation standards for commercial construction remain underenforced, creating first-mover positioning for EPD-certified suppliers. The Bureau of Energy Efficiency's ECBC code adoption varies sharply across states. Maharashtra and Gujarat commercial construction corridors concentrate near-term demand as Mumbai and Ahmedabad developers pilot green building certifications.
United Kingdom
Class A office REITs are embedding insulation EPDs into asset valuation models, elevating specification transparency beyond installed cost metrics. The Building Safety Regulator's post-Grenfell fire safety mandates are displacing combustible materials in high-rise residential retrofits. London and Southeast England commercial retrofit pipelines concentrate demand for mineral wool in fire-rated assemblies.
Global Insulation Market Competitive Environment
Capability concentration sits with specialized mineral wool and aerogel producers commanding premium pricing in fire-rated and temperature-extreme applications; scale advantage sits with integrated fiberglass and foam manufacturers leveraging raw material security and contractor channel control. The market structures around three tiers: multinational building materials conglomerates with roofing-to-insulation integration, regional mineral wool specialists with slag and basalt fiber captive supply, and chemical majors with in-house polyol and isocyanate production. Dominant competitive moves include backward integration into raw material production and bundling installation services with material sales to capture lifecycle value.
Among North American integrated building materials suppliers, Owens Corning and Johns Manville occupy positions exemplifying roofing-insulation channel convergence. BASF SE anchors the chemical-major tier with captive polyol production securing polyurethane foam supply security. Saint-Gobain represents the European mineral wool specialist archetype with building chemistry adjacencies reinforcing specification influence in commercial retrofit tenders.
| Leading Market Players |
|---|
| Owens Corning |
| Saint-Gobain |
| Rockwool International A/S |
| Knauf Insulation |
| Kingspan Group |
| Johns Manville |
| BASF SE |
| 3M |
| Morgan Advanced Materials |
| Others |
Value Chain & Pricing Dynamics
MDI capacity concentration in Germany, China, and the United States anchors polyurethane foam pricing power with BASF SE, Covestro, and Huntsman controlling polyol-isocyanate feedstock. This upstream consolidation funnels margin capture toward integrated chemical majors while constraining independent foam fabricators to commodity pricing tiers.
Pricing Analysis
Installation service bundling drives lifetime value capture as manufacturers like Owens Corning and Saint-Gobain embed certified technician networks into material contracts. Three-tier pricing structure across premium, standard, and economy levels separates EPD-certified low-carbon systems from conventional fiberglass and entry-grade polystyrene. Cost compression in commodity fiberglass intensifies as Chinese exports and domestic production capacity expand. DIY consumers exhibit highest price sensitivity, while UK Class A office REITs absorb material premiums for green bond eligibility.
Supply Chain Analysis
Upstream feedstock for mineral wool draws from basalt and slag fiber production clustering in Poland and the Czech Republic, with Rockwool and Knauf operating captive smelter partnerships. Polyurethane systems rest on benzene derivatives and crude oil-linked MDI pricing, exposing margins to petrochemical volatility. Single-source vulnerability concentrates in European basalt fiber supply where energy cost spikes disrupt furnace operations. Distribution runs through contractor-direct channels for commercial projects and big-box retail for residential DIY segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's mandatory renovation targets and the US IRA's efficiency tax credits constitute a dual regulatory inflection accelerating specification shifts toward high-performance, low-embodied-carbon insulation systems. This policy convergence compresses adoption timelines for materials previously confined to premium niches.
For Market Incumbents: Pre-empt margin erosion in commodity fiberglass by securing EPD certification ahead of carbon border adjustment enforcement, while anchoring contractor channel control through installation service bundling that locks out independent foam applicators. Backward integration into slag and basalt fiber supply insulates mineral wool producers from European energy cost volatility threatening Polish and Czech furnace operations. For New Entrants and Emerging Players: India's underenforced BIS energy conservation standards create first-mover positioning for EPD-certified suppliers targeting Maharashtra and Gujarat commercial construction corridors before code tightening accelerates. Aerogel-enhanced blanket technology offers white-space entry into cryogenic LNG infrastructure on the US Gulf Coast where conventional materials fail temperature-extreme specifications. Partner with certified spray foam technician training networks to overcome installer skill fragmentation blocking market entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional mineral wool specialists possessing slag fiber captive supply but lacking EPD documentation for EU Green Deal tender eligibility. Long-term viability hinges on regulatory compliance infrastructure rather than production scale alone. Watch for MEE enforcement intensity in Jiangsu and Shandong province steel mills as the signal indicating high-temperature insulation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | BASF SE's captive supply secures polyurethane foam margin pools in commercial specifications. |
| EPD Certification Investment | Third-party verified declarations unlock EU Green Deal and UK green bond procurement eligibility. |
| Installation Service Bundling | Owens Corning's contractor channel control captures lifecycle value beyond material sales. |
| Technician Certification Network Expansion | Spray foam warranty validity demands certified applicators thin outside major metropolitan corridors. |
| Natural Fiber Product Line Development | German Passivhaus and BREEAM projects specify hemp and flax for low-embodied-carbon compliance. |
Study Parameters
The analysis maps fiberglass, foam, mineral wool, and aerogel sub-sectors, each validated through insulation procurement managers at commercial REITs, spray foam contractor networks, and industrial facility engineers. Plant managers at Jiangsu and Shandong steel mills, BAFA subsidy administrators, and EPA embodied carbon policy specialists provided primary input. Secondary sources include EU Green Deal regulatory filings, US Department of Energy IRA implementation guidance, MEE energy intensity enforcement records, and building code adoption databases across Indian states. Bottom-up material tonnage estimates triangulate with top-down construction spending forecasts.
Assumptions held EU Green Deal renovation targets and US IRA tax credit continuity fixed across the analysis window, while MDI pricing volatility and REACH flame retardant reformulation timelines were modeled as scenario variables. Segmentation dimensions include product type thermal performance tier, application envelope depth constraints, end-user procurement sophistication, and regional regulatory enforcement intensity. CAGRs derive from construction activity projections cross-referenced with energy code adoption curves and industrial energy intensity reduction mandates.
Practitioners should monitor carbon border adjustment implementation timelines and MEE enforcement intensity for early signals of specification shift velocity. Forecasts reflect assumptions regarding regulatory continuity and construction spending patterns that commodity price shocks or policy reversals could revise. Cross-checking against national building permit databases and industrial energy audit disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Cold-Air Diffusion Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Mineral Wool Insulation Market
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Thin Insulation Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
US Industrial Insulation Market
Insulation Materials
Refrigeration Insulation Materials Market