
 Fire Stopping Materials Market | 2026-2036
Fire Stopping Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Stopping Materials Market Analysis
Software-defined fire safety monitoring is rebalancing how contractors procure passive protection systems, shifting capital toward integrated service contracts over standalone material purchases. 3M leverages its intumescent coating portfolio to anchor specification relationships with multinational construction firms. Hilti Corporation sustains channel control through direct-to-contractor distribution networks that bundle installation tooling with firestop product lines.
Fire stopping materials comprise engineered compounds including intumescent acrylics, silicone sealants, and cementitious mortars designed to restore fire-resistance ratings where penetrants breach rated assemblies. These materials function by expanding, charring, or insulating when exposed to elevated temperatures, thereby maintaining compartmentation integrity in building envelopes. Sealants and intumescent formulations occupy the deepest margin pools due to specification stickiness and code-mandated re-inspection cycles. Joint systems and electrical installation applications lead volume growth as data center construction and EV charging infrastructure multiply cable penetration complexity.
NFPA standards, the International Building Code, and ASTM E814 testing protocols collectively shape product certification requirements and market access thresholds for fire stopping material suppliers. OSHA enforcement of workplace fire safety compliance further tightens installation quality standards across commercial and industrial projects. Stakeholders must monitor evolving green building certifications that increasingly reward low-VOC firestop formulations without compromising hourly fire ratings.
Market Dynamics
Software-defined fire safety monitoring is compressing procurement cycles for passive protection systems, forcing material suppliers to bundle installation services and predictive maintenance into long-term contracts rather than transactional product sales.
Growth Catalysts
- International Building Code updates:Stricter compartmentation mandates in North America are accelerating retrofit volumes across aging commercial infrastructure.
- Data center construction:Cable penetration complexity in hyperscale facilities is multiplying specification requirements for intumescent sealants and joint systems.
- EV charging infrastructure:Electrical installation applications are expanding as utility-scale charging networks require fire-rated cable transit assemblies.
Market Restraints
- Petrochemical feedstock volatility:Silicone polymer and acrylic resin prices fluctuate with crude oil indices, compressing margin predictability for sealant formulators.
- Specialized installer scarcity:Certified firestop applicator shortages in secondary metropolitan markets delay project completion and inflate labor costs.
- Cementitious mortar weight penalties:Structural load constraints in high-rise retrofits limit deployment of traditional heavy-density firestopping compounds.
Strategic Opportunities
- Green building certification alignment:LEED and BREEAM point systems now reward low-VOC firestop formulations that maintain hourly fire ratings without compromising indoor air quality.
- Prefabricated modular construction:Off-site building manufacturing creates demand for factory-applied intumescent coatings and pre-tested penetration assemblies.
- Integrated digital compliance platforms:Software vendors are embedding firestop specification databases into BIM workflows, creating new channel partnerships for material suppliers.
Industry Challenges
- ASTM E814 testing backlog:Certification laboratory capacity constraints extend product approval timelines by six to twelve months for novel formulations.
- Multi-jurisdiction code harmonization:Variations between NFPA standards and local amendments complicate national product rollouts and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Stopping Materials Market |
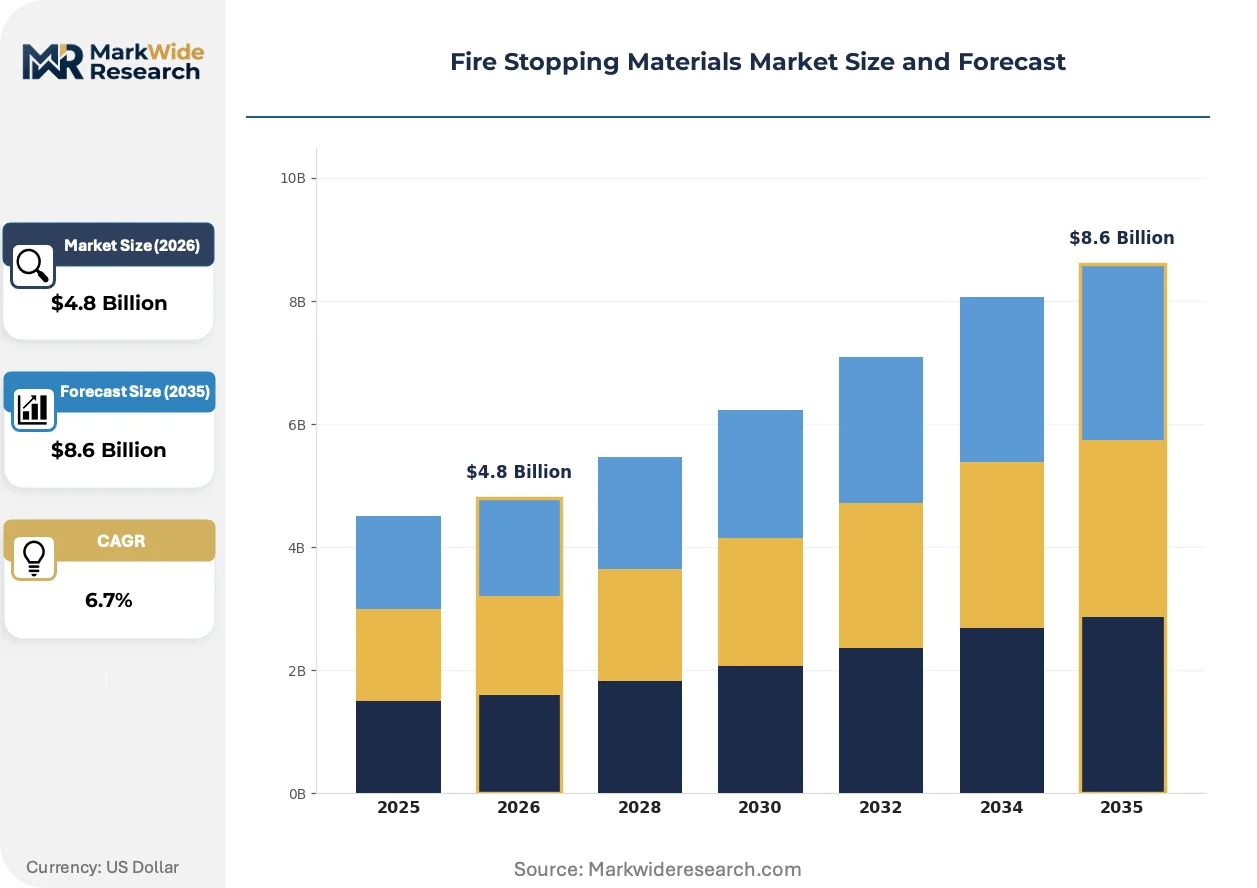
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealants, Mortars, Putty, Coatings Application: Wall Penetrations, Floor Penetrations, Joint Systems, Electrical Installations End User: Construction, Commercial, Residential, Industrial Material: Gypsum, Intumescent, Cementitious, Silicone |
| Companies Covered | 3M, Hilti Corporation, Sika AG, RPM International Inc, Etex Group, Specified Technologies Inc., RectorSeal, Rockwool International A/S, Promat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Stopping Materials Market Emerging Trajectories
Material science advances and digital compliance tools are converging to reshape how fire stopping systems are specified, installed, and monitored across building lifecycles.
Water-based intumescent coatings are overtaking solvent-borne formulations in commercial specifications due to reduced VOC emissions and simplified site handling. Multinational construction firms are mandating these formulations in sustainability-driven procurement frameworks. The shift is compressing demand for traditional epoxy-intumescent hybrids in new vertical construction.
OSHA enforcement of workplace fire safety compliance is tightening installation quality standards across commercial and industrial projects. Inspectors now require documented installer certification and photographic penetration mapping. General contractors in the United States are responding by embedding third-party firestop commissioning into standard project workflows.
Specification stickiness is fragmenting as cloud-based product databases enable real-time substitution analysis by cost consultants. Quantity surveyors in high-rise developments now compare hourly fire ratings and material costs across competing sealant brands during tender phases. This transparency is most pronounced in United Kingdom commercial construction where public sector frameworks mandate open specification protocols.
Fire Stopping Materials Market Segmentation
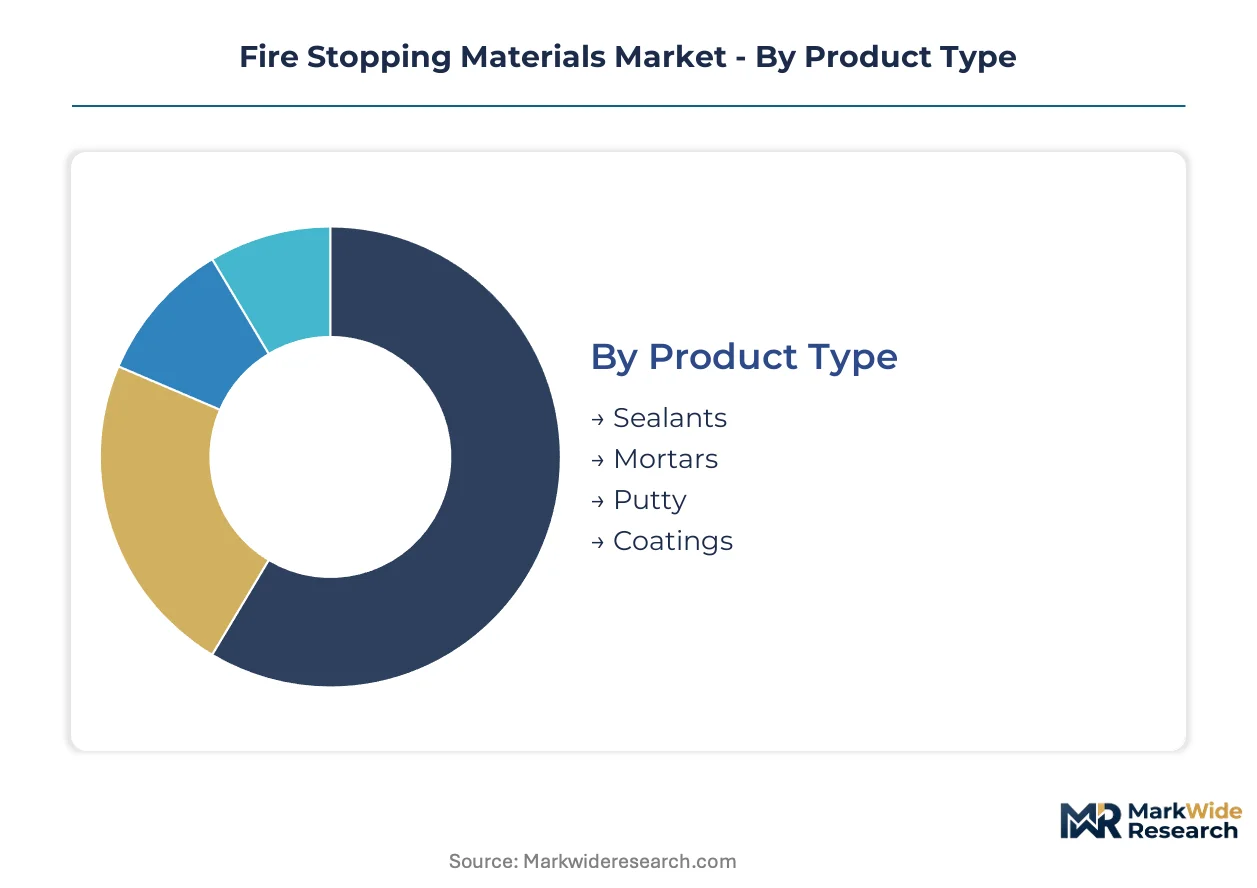
Fire stopping material specifications vary sharply by penetration geometry and fire-resistance rating requirements. Certification burdens fall unevenly across product categories, with intumescent formulations facing ASTM E814 testing cycles that simpler cementitious compounds avoid.
Product Type:
ASTM E814 and UL 1479 certifications impose distinct testing burdens: sealants require dynamic cycling validation, while mortars face structural load verification. Intumescent coatings carry the heaviest approval weight due to thickness-dependent performance curves.
- Sealants:Acrylic and silicone formulations dominate cable penetration sealing with intumescent variants expanding up to 40 times original volume under heat exposure. Data center construction in Northern Virginia and Frankfurt drives specification intensity as hyperscale operators mandate factory-tested penetration assemblies for fiber optic bundles.
- Mortars:Cementitious compounds restore fire ratings in large-format floor openings where structural load-bearing capacity intersects with hourly fire resistance. High-rise retrofits in Chicago and Manhattan encounter weight penalties that limit deployment, pushing demand toward lightweight gypsum-based alternatives in buildings exceeding 40 stories.
- Putty:Hand-moldable compounds fill irregular penetrations in electrical conduits and small-diameter pipe transits. Commercial office renovations in London specify putty for its reworkability during tenant improvement cycles.
- Coatings:Spray-applied intumescent and subliming formulations protect structural steel in atrium spaces and exposed architectural elements. Water-based formulations are displacing solvent-borne systems in California and New York projects subject to VOC emission caps.
Leading the category by volume: Sealants. Expanding most quickly: Coatings.
Application:
Penetration geometry dictates material selection and labor intensity. Floor assemblies face gravitational load constraints absent in vertical wall penetrations, while joint systems accommodate structural movement that static seals cannot tolerate.
- Wall Penetrations:Pipe, cable, and duct breaches through rated drywall or masonry assemblies require compressible sealants that accommodate differential thermal expansion. Healthcare construction in Texas and Florida specifies antimicrobial-grade silicone for infection control in patient tower penetrations.
- Floor Penetrations:Openings for vertical risers and mechanical shafts demand load-bearing mortars or intumescent wraps that maintain integrity under foot traffic and equipment weight. Data center slab penetrations in Ashburn, Virginia, require zero-smoke formulations to protect server environments from corrosive combustion byproducts.
- Joint Systems:Head-of-wall, perimeter, and expansion joints accommodate structural drift and seismic movement while preserving fire-resistance ratings. High-rise residential towers in Toronto and Vancouver specify preformed compression seals that install faster than field-applied alternatives.
- Electrical Installations:Cable transit assemblies and busway penetrations multiply in complexity with voltage tier and conductor density. EV charging infrastructure deployment across Germany and the Netherlands requires fire-rated cable glands and intumescent pillows for high-amperage feeder installations.
Deepest specification stickiness: Electrical Installations. Steepest volume climb: Joint Systems.
End User:
Procurement authority and compliance enforcement intensity vary by building ownership structure. Institutional clients embed firestop commissioning into capital projects, while residential developers prioritize cost minimization until code enforcement intervenes.
- Construction:General contractors and construction managers procure fire stopping materials through specification-driven frameworks that favor approved manufacturer lists. Skanska and Turner Construction mandate third-party firestop inspection across their United States project portfolios.
- Commercial:Office, retail, and hospitality owners retrofit aging infrastructure to meet updated International Building Code compartmentation standards. Class-A office repositioning in Manhattan and Chicago drives sealant specification for MEP upgrades in 1960s-era towers.
- Residential:Multi-family developers face compressed schedules and cost constraints that limit firestop inspection rigor. Mid-rise wood-frame construction in Seattle and Portland encounters heightened scrutiny as local amendments tighten penetration sealing requirements.
- Industrial:Manufacturing, warehousing, and energy facilities face OSHA Process Safety Management enforcement that elevates firestop installation documentation. Petrochemical facilities along the Texas Gulf Coast require explosion-rated cable transit assemblies that exceed standard commercial specifications.
Highest compliance spend per square foot: Industrial. Gaining share fastest: Commercial.
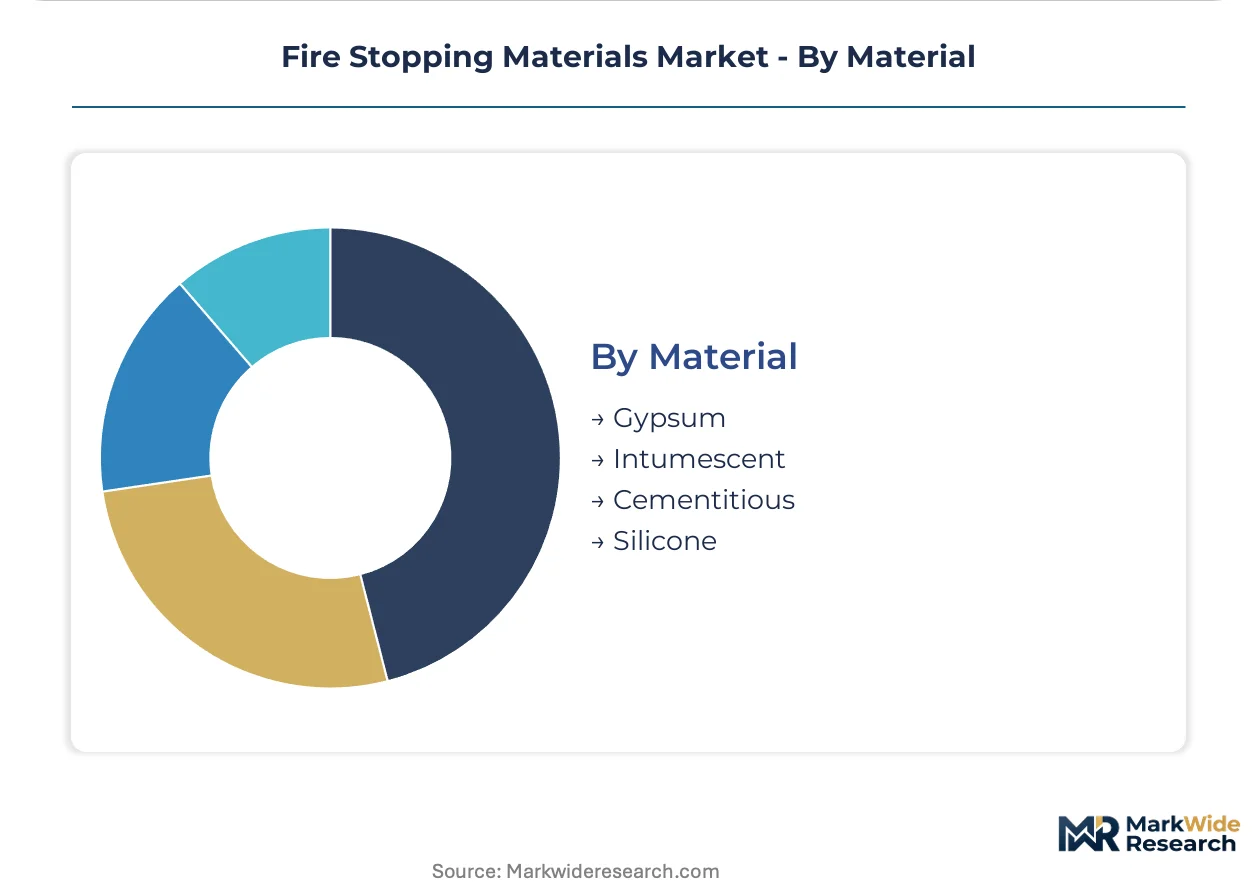
Material:
Base chemistry determines expansion mechanism, temperature threshold, and environmental compatibility. Silicone and intumescent formulations command specification premiums, while gypsum and cementitious compounds compete on installed cost.
- Gypsum:Hydrated calcium sulfate compounds provide economical fire resistance in non-load-bearing partitions and ceiling plenums. Drywall contractors in the Sun Belt specify gypsum-based firestop for its compatibility with standard taping tools and rapid finishing.
- Intumescent:Graphite-based and ammonium polyphosphate formulations expand into insulating char layers that protect penetrants and substrates alike. Steel protection in London's commercial high-rises drives water-based intumescent coating specification as BREEAM point systems reward low-VOC alternatives.
- Cementitious:Portland cement and vermiculite blends offer thermal mass and abrasion resistance in industrial floor penetrations. Weight constraints in Singapore and Hong Kong high-rises limit cementitious deployment to low-rise podium structures.
- Silicone:Room-temperature-vulcanizing formulations maintain elasticity across temperature extremes and accommodate joint movement without cracking. Façade penetration sealing in Dubai and Riyadh specifies UV-stable silicone for desert climate exposure.
Widest specification breadth: Intumescent. Narrowing to specialty applications: Cementitious.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ashburn, Virginia anchors hyperscale data center construction, driving specification intensity for cable penetration assemblies across the United States. Frankfurt and London commercial towers mandate water-based intumescent coatings under tightening VOC regulations. Singapore and Dubai high-rises encounter structural load constraints that limit traditional firestopping deployment.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth multiplies cable penetration complexity. OSHA enforces workplace fire safety compliance with documented installer certification requirements. Chicago and Manhattan high-rise retrofits push demand for lightweight gypsum-based alternatives in buildings exceeding 40 stories.
Germany
Utility-scale EV charging networks across Bavaria and North Rhine-Westphalia require fire-rated cable transit assemblies for high-amperage installations. The country's national building regulator enforces compartmentation standards aligned with EU Green Deal carbon reduction targets. Frankfurt commercial construction specifies low-VOC intumescent sealants to meet BREEAM point systems.
United Kingdom
Class-A office repositioning in London drives sealant specification for MEP upgrades in 1960s-era towers. Public sector frameworks mandate open specification protocols that enable real-time substitution analysis by cost consultants. Birmingham and Manchester commercial developments specify preformed compression seals for faster installation.
China
Yangtze River Delta and Pearl River Delta data center clusters multiply specification requirements for intumescent joint systems. GB standards and dual carbon goals shape product certification requirements for low-emission formulations. Shenzhen and Shanghai high-rises encounter cementitious mortar weight penalties that push demand toward lightweight alternatives.
United Arab Emirates
Desert climate exposure in Dubai and Riyadh commercial towers specifies UV-stable silicone sealants for façade penetration sealing. MOHAP and local building authorities enforce fire-resistance rating compliance across hospitality and retail developments. Abu Dhabi sustainable city initiatives reward low-VOC firestop formulations in green building certifications.
Fire Stopping Materials Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the fire stopping materials landscape. The market structure consolidates around multinational chemical conglomerates with diversified construction portfolios, while regional specialists occupy niche penetration geometries. Three archetypes dominate: diversified industrial conglomerates with intumescent coating portfolios, construction-focused distributors bundling installation tooling, and mineral wool specialists with cementitious firestop lines. M&A activity concentrates on acquiring certified installer networks, while portfolio diversification drives expansion into predictive maintenance software.
Within the diversified conglomerate tier, 3M and Sika AG exemplify specification-driven market presence through global distribution infrastructure. Hilti Corporation anchors the construction-tooling-integrated archetype, leveraging direct-to-contractor relationships that bundle installation equipment with passive protection systems. Rockwool International A/S occupies a position representing mineral-based firestop specialists with upstream control over raw material supply chains.
| Leading Market Players |
|---|
| 3M |
| Hilti Corporation |
| Sika AG |
| RPM International Inc |
| Etex Group |
| Specified Technologies Inc. |
| RectorSeal |
| Rockwool International A/S |
| Promat |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between UL-listed intumescent formulations and uncertified commodity sealants manifests in both pricing power and supply chain configurations, with ASTM E814 testing costs creating a moat that concentrates premium tier supply among diversified chemical conglomerates while commodity tiers fragment across regional mortar blenders.
Pricing Analysis
Cost compression in commodity cementitious tiers traces to petrochemical feedstock volatility and Asian import competition, while premium silicone and intumescent formulations defend margins through specification stickiness and code-mandated re-inspection cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by UL certification depth and installer training bundling. Pricing pressure intensifies in standard-grade sealants as cloud-based product databases enable real-time substitution analysis by cost consultants. Residential developers exhibit highest price sensitivity, while data center operators and petrochemical facilities prioritize certified performance over unit cost.
Supply Chain Analysis
Reverse logistics for firestop materials center on expired inventory returns from distributor networks and jobsite surplus reclamation, with shelf-life limitations on water-based intumescents driving periodic write-downs. Manufacturing concentrates in the United States, Germany, and China, with formulation plants proximate to major construction clusters to minimize VOC transport restrictions. Raw material supply draws from silicone polymer producers in Japan, graphite suppliers in China, and acrylic resin networks anchored in South Korea. Single-source vulnerability sits with specialized intumescent additive suppliers serving ASTM E814 certification pipelines. Distribution runs through construction-focused distributors bundling installation tooling with material supply, supplemented by direct-to-contractor channels for large multinational accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire stopping materials function as a cost-of-compliance market where International Building Code compartmentation mandates create durable barrier-to-entry moats for ASTM E814-certified suppliers, insulating compliant players from price erosion while penalizing specification laggards.
For Market Incumbents: Deepen specification relationships with multinational construction firms by embedding firestop commissioning into standard project workflows, countering the threat of cloud-based substitution analysis that fragments specification stickiness. Prioritize backward integration into specialized intumescent additive supply to secure ASTM E814 certification pipeline continuity against laboratory testing backlogs. For New Entrants and Emerging Players: BIM-integrated software vendors represent the most penetrable channel partner type for material suppliers seeking specification influence, as digital compliance platforms create new partnership architectures outside incumbent distributor control. Target prefabricated modular construction factories for factory-applied intumescent coatings, where off-site manufacturing bypasses field installer scarcity constraints. Lead with integrated service contracts bundling predictive maintenance over transactional product sales. For Investors and Strategic Acquirers: Re-rating potential sits with certified installer network aggregators given OSHA enforcement tightening that elevates documented installer certification requirements. Long-term viability favors archetypes with captive supply of low-VOC formulations aligned to LEED and BREEAM point systems. Monitor ASTM E814 laboratory capacity expansion as the inflection signal for novel formulation approval timelines and new entrant market access.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM E814 Certification Investment | Accelerates product approval timelines and unlocks specification relationships with Skanska and Turner Construction portfolios. |
| Installer Network Acquisition | Captures scarce certified applicator capacity in secondary metropolitan markets where labor shortages delay project completion. |
| Low-VOC Formulation Development | Aligns product portfolios with LEED and BREEAM point systems that reward indoor air quality without compromising hourly fire ratings. |
| BIM Workflow Integration | Embeds firestop specification databases into digital compliance platforms used by quantity surveyors during tender phases. |
| Prefabricated Construction Partnership | Secures factory-applied intumescent coating demand from off-site building manufacturers seeking pre-tested penetration assemblies. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with firestop specification engineers, certified installer network managers, construction procurement leads, and building code officials. Secondary sources encompassed International Building Code amendment tracking, OSHA enforcement databases, ASTM E814 certification registries, and construction material customs records. Bottom-up project pipeline analysis triangulated against top-down construction spending forecasts across commercial, industrial, and residential verticals.
Data-stream reconciliation across shipment volumes, specification frequencies, and certification timelines informed the analytical framework. Segmentation dimensions encompassed product type, penetration geometry, end-use sector, and base chemistry grade. CAGRs derived from regression analysis of historic retrofit intensity against code adoption curves and infrastructure age profiles. Forecast inputs incorporated data center construction clusters in Northern Virginia and Frankfurt, plus EV charging infrastructure deployment across Germany and the Netherlands.
Caveats apply where petrochemical feedstock volatility, ASTM E814 laboratory capacity constraints, or multi-jurisdiction code harmonization failures could materially shift the outlook. Practitioners should monitor OSHA enforcement intensity and green building certification point system revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
Multi-Layer Cryogenic Insulation Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Global Molded Foams Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
Dielectric Materials Market