
 Global High Temperature Filters Market | 2026-2036
Global High Temperature Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Temperature Filters Market Intelligence
The integration of sensor-based predictive maintenance services is realigning the traditional product-centric sales model for high temperature filters. Donaldson Company, Inc. leverages its expertise in filtration media to offer comprehensive solutions for complex industrial environments. Camfil AB differentiates through its focus on energy efficiency and air quality consulting alongside its filter products. Parker Hannifin sustains a strong market position through its extensive distribution network and broad portfolio covering multiple end-user applications.
High temperature filters are engineered systems for removing particulate matter from gas streams operating above 250°C. They are essential for pollution control and process protection in applications like metal processing and power generation. While baghouse filters represent a mature segment, cartridge filters show higher growth due to easier maintenance. PTFE coated and other synthetic materials are increasingly specified over traditional fiberglass for demanding chemical processing environments.
The US Environmental Protection Agency (EPA) sets stringent National Emission Standards for Hazardous Air Pollutants, mandating the use of high-efficiency filters. Similarly, the European Union's Industrial Emissions Directive and China's GB standards for air pollutants compel industries to adopt best available filtration technologies. Navigating the evolving landscape of material regulations, particularly concerning PFAS compounds under frameworks like REACH, will be a critical decision point for filter media manufacturers.
Market Dynamics
The imperative to meet increasingly stringent air quality mandates, such as the US EPA's emission standards and China's GB standards, is the central force shaping the high temperature filters market, compelling a continuous cycle of material innovation and system-level engineering.
Growth Catalysts
- Stringent Regulations:China's dual carbon goals and associated GB standards for industrial pollutants mandate advanced filtration in sectors like steel, cement, and non-ferrous metal production, creating substantial domestic demand.
- Waste-to-Energy Expansion:The development of new waste-to-energy and biomass power facilities, particularly across the European Union, provides a consistent demand driver for high-performance filters capable of handling complex flue gases.
- Material Advancement:The increasing specification of synthetic materials like PTFE-coated fiberglass enables filters to operate reliably in chemically aggressive environments common in chemical processing, displacing traditional media.
Market Restraints
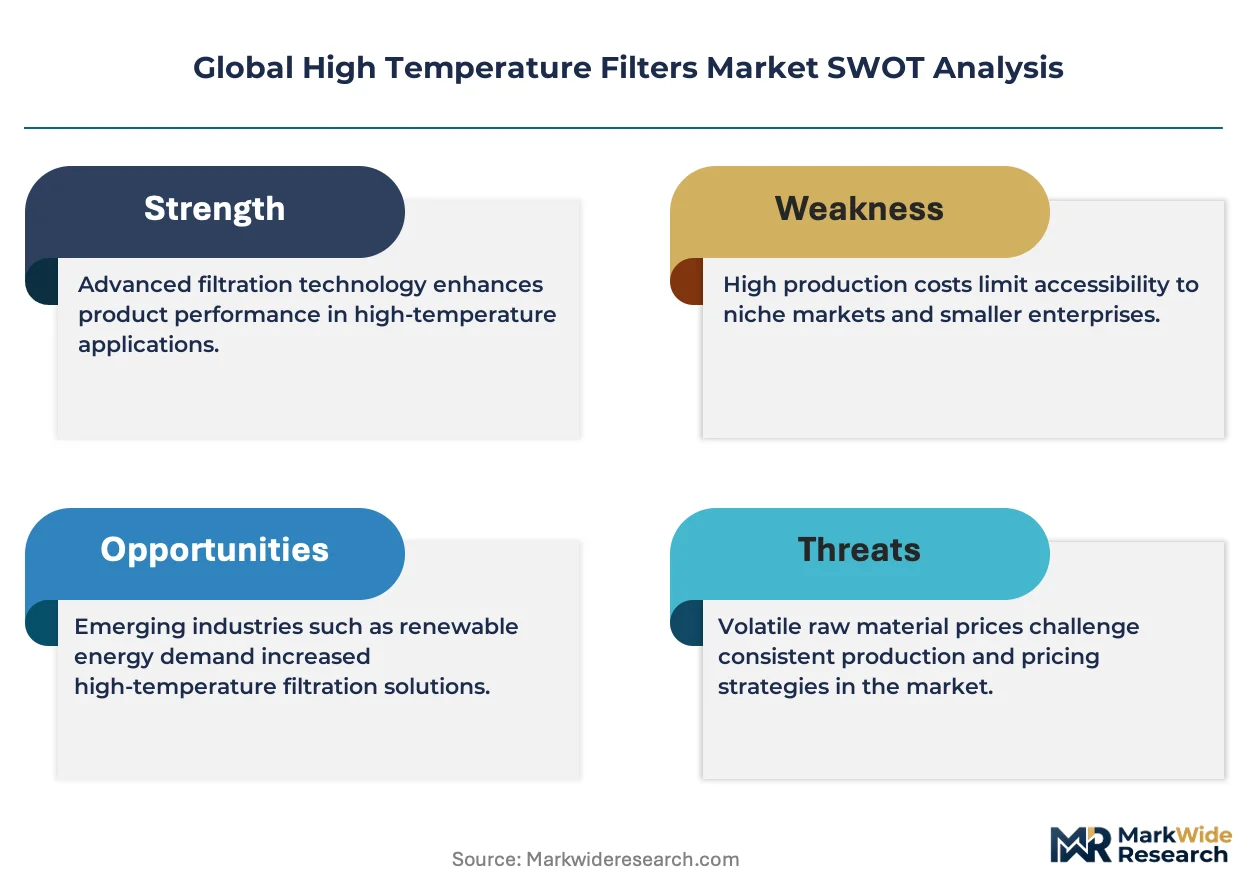
- High Initial Capex:The significant upfront investment required for installing or retrofitting large-scale baghouse filtration systems acts as a barrier for small and medium-sized enterprises in heavy industry.
- Material Performance Limits:Certain filter media exhibit degradation in ultra-high temperature environments above 500°C, which are encountered in specialized metallurgical and glass manufacturing processes, limiting applicability.
- Regulatory Uncertainty:Evolving regulations concerning PFAS compounds under frameworks like the EU's REACH create uncertainty for manufacturers, impacting long-term material selection and R&D investment decisions.
Strategic Opportunities
- Underpenetrated Geographies:India's rapidly industrializing economy presents a significant opportunity, with growing enforcement of pollution norms in its power generation, steel, and cement sectors requiring new filtration installations.
- Emerging Applications:The growth of the green hydrogen sector creates a new application space, as high-temperature electrolysis and related processes require fine particulate control from gas streams.
- Service Model Integration:Offering sensor-based predictive maintenance and filtration-as-a-service models provides a path to create recurring revenue streams and deeper customer integration beyond one-time filter sales.
Industry Challenges
- Technical Skill Gaps:A shortage of technicians qualified to install, operate, and maintain increasingly complex and automated filtration systems poses an operational challenge for both end-users and service providers.
- Compliance Fragmentation:Manufacturers face complexity in designing products for a global market due to the lack of harmonization between major regulatory regimes like the US EPA, EU's IED, and China's MEE.
- Retrofit Complexity:Integrating modern, compact cartridge filter systems into older industrial facilities designed for bulkier baghouses often presents significant engineering challenges related to space, ducting, and airflow management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Temperature Filters Market |
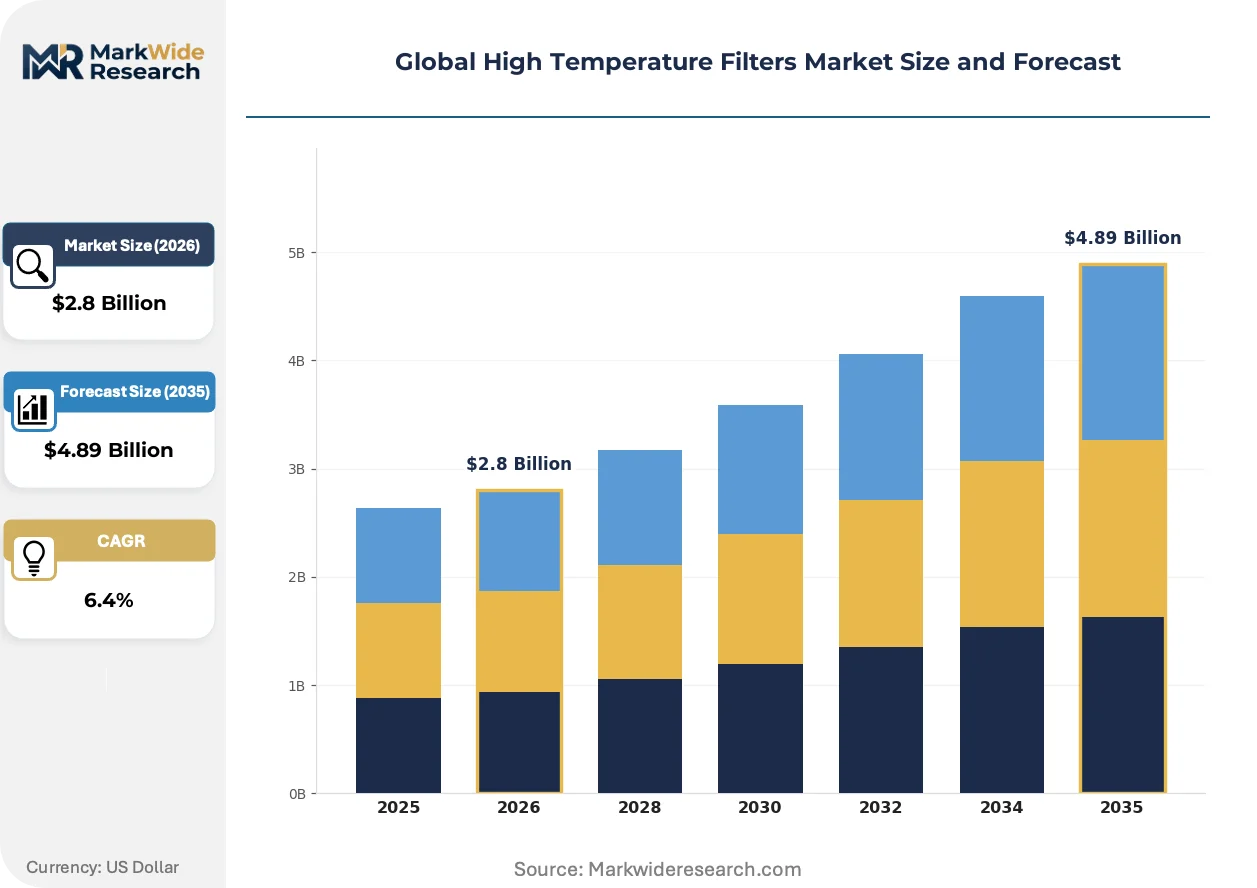
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Filter Type: Baghouse, Cartridge, HEPA, Ceramic, Metal Mesh, Felt Material: PTFE Coated, Fiberglass, Stainless Steel, Nomex, Polytetrafluoroethylene, Aramid Application: Metal Processing, Power Generation, Cement Manufacturing, Chemical Processing, Waste-to-Energy, Food Processing End User: Manufacturing Facilities, Energy Producers, Construction Plants, Petrochemical Industries, Incineration Units, Food Production Companies |
| Companies Covered | Camfil AB, Freudenberg Filtration Technologies, Donaldson Company, Inc., Pall Corporation, MANN+HUMMEL, Parker Hannifin, Walker Filtration, Filtration Group, American Air Filter Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Temperature Filters Market Strategic Shifts & Innovations
A fundamental shift from product-centric sales toward integrated, performance-guaranteed systems is underway. This evolution is driven by advances in material science and the embedding of digital monitoring technologies directly into filtration assets to ensure uptime and compliance.
Advanced catalytic filter media combine particulate removal with the destruction of gaseous pollutants like dioxins and furans in a single step. These multifunctional materials see adoption in demanding applications such as hazardous waste incineration and secondary aluminum smelting. The technology is consolidating multiple air pollution control stages into one unit, simplifying plant design and reducing capital expenditure for operators.
The European Union's Industrial Emissions Directive (IED) and its associated Best Available Techniques (BAT) reference documents are forcing a continuous improvement cycle. This framework compels operators in industries like cement and power generation to not just meet a fixed limit but to adopt the most effective filtration technologies available. The non-ferrous metals sector is particularly affected, driving investment in higher-efficiency membrane laminates and advanced filter materials.
End-user buying behavior is evolving from transactional purchases of replacement filters to contracting for guaranteed operational outcomes like emission levels or plant availability. This change disrupts traditional component sales through distributors, favoring direct relationships with manufacturers capable of providing comprehensive service and monitoring packages. This trend is most pronounced in the North American power sector and European waste-to-energy facilities, where operational reliability is critical.
Global High Temperature Filters Market Segmentation
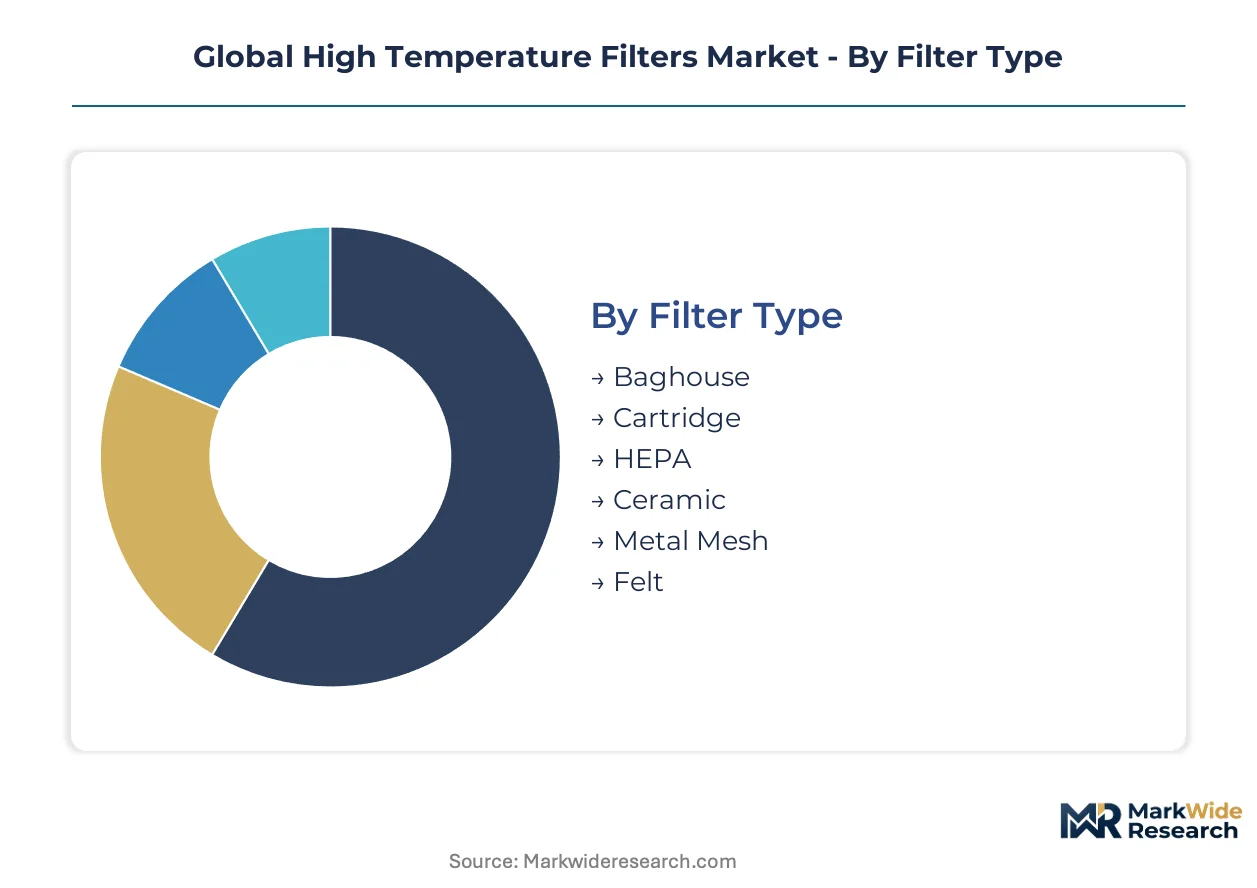
High temperature filters require precise segmentation to understand how different product configurations integrate into complex industrial systems. This analysis dissects the market by critical attributes, revealing the interplay between filter design, material science, and specific operational demands across various end-use sectors.
Filter Type:
The integration depth of high temperature filters varies significantly, with some types functioning as standalone units and others embedded within larger air pollution control systems.
- Cartridge:These filters typically consist of pleated media housed in a rigid structure, offering high filtration efficiency and easier replacement. Demand concentrates in facilities seeking operational flexibility and reduced maintenance downtime, particularly in chemical processing plants.
- Baghouse:These systems employ multiple fabric filter bags to capture particulate matter from large gas volumes, often used in heavy industrial settings. Power generation and cement manufacturing facilities remain significant end-users driven by their need for high-volume gas stream purification.
- HEPA:High-Efficiency Particulate Air filters provide superior particulate removal, essential for controlled environments in specialized manufacturing.
- Ceramic:Ceramic filters offer exceptional thermal stability and chemical resistance, making them suitable for ultra-high temperature applications like hot gas filtration.
- Metal Mesh:Composed of woven or sintered metal fibers, these filters provide robust performance in high-temperature, corrosive environments, particularly in metal processing.
- Felt:Industrial felt filters are used for coarse particulate removal in less demanding high-temperature applications, balancing cost and performance.
Volume placements concentrate in Baghouse filters; the faster expansion belongs to Cartridge filters.
Material:
Material selection for high temperature filters often reflects a balance between initial investment and long-term performance requirements, creating distinct cost tiers.
- PTFE Coated:These materials feature a polytetrafluoroethylene layer applied to a substrate, enhancing chemical resistance and particulate release properties in aggressive environments. Chemical processing and waste-to-energy facilities increasingly specify PTFE-coated media for improved longevity.
- Fiberglass:Comprising woven glass fibers, fiberglass is a traditional and cost-effective material offering good thermal stability for continuous operation. Power generation and cement plants utilize fiberglass filters extensively due to their proven performance.
- Stainless Steel:Stainless steel filters provide excellent mechanical strength and corrosion resistance, suitable for very high temperatures and harsh chemical conditions.
- Nomex:A meta-aramid fiber, Nomex offers good thermal stability and chemical resistance for moderate high-temperature applications.
- Polytetrafluoroethylene:Pure PTFE membranes offer superior chemical inertness and non-stick properties, crucial for pharmaceutical and food processing applications.
- Aramid:Aramid fibers, including meta-aramids like Nomex, provide strength and thermal resistance for industrial filtration in various sectors.
Market preference is shifting from Fiberglass towards PTFE Coated due to enhanced chemical resistance and particulate release properties.
Application:
The diverse industrial landscape drives specific application requirements for high temperature filters, each demanding tailored filtration solutions.
- Power Generation:High temperature filters are critical for removing particulate matter from flue gases in coal-fired, gas-fired, and biomass power plants. Stringent emission regulations from bodies like the US EPA compel continuous investment in advanced filtration systems within this sector.
- Waste-to-Energy:These facilities incinerate waste to produce energy, requiring robust high temperature filters to manage complex and corrosive flue gas streams. European Union directives for industrial emissions drive substantial demand for high-performance filtration in this application.
- Metal Processing:Foundries and smelters use high temperature filters to control emissions from furnaces and other high-heat processes.
- Cement Manufacturing:Filters are essential in cement kilns to capture dust and particulate emissions, ensuring compliance with air quality standards.
- Chemical Processing:This application requires filters capable of handling corrosive gases and high temperatures, often utilizing specialized synthetic media.
- Food Processing:High temperature filters ensure product purity and prevent contamination in drying, baking, and sterilization processes.
The most significant demand originates from Power Generation; while Waste-to-Energy represents a rapidly expanding niche.
End User:
High temperature filter end-users span a broad spectrum of industrial operations, each with unique scale, regulatory compliance, and operational reliability needs.
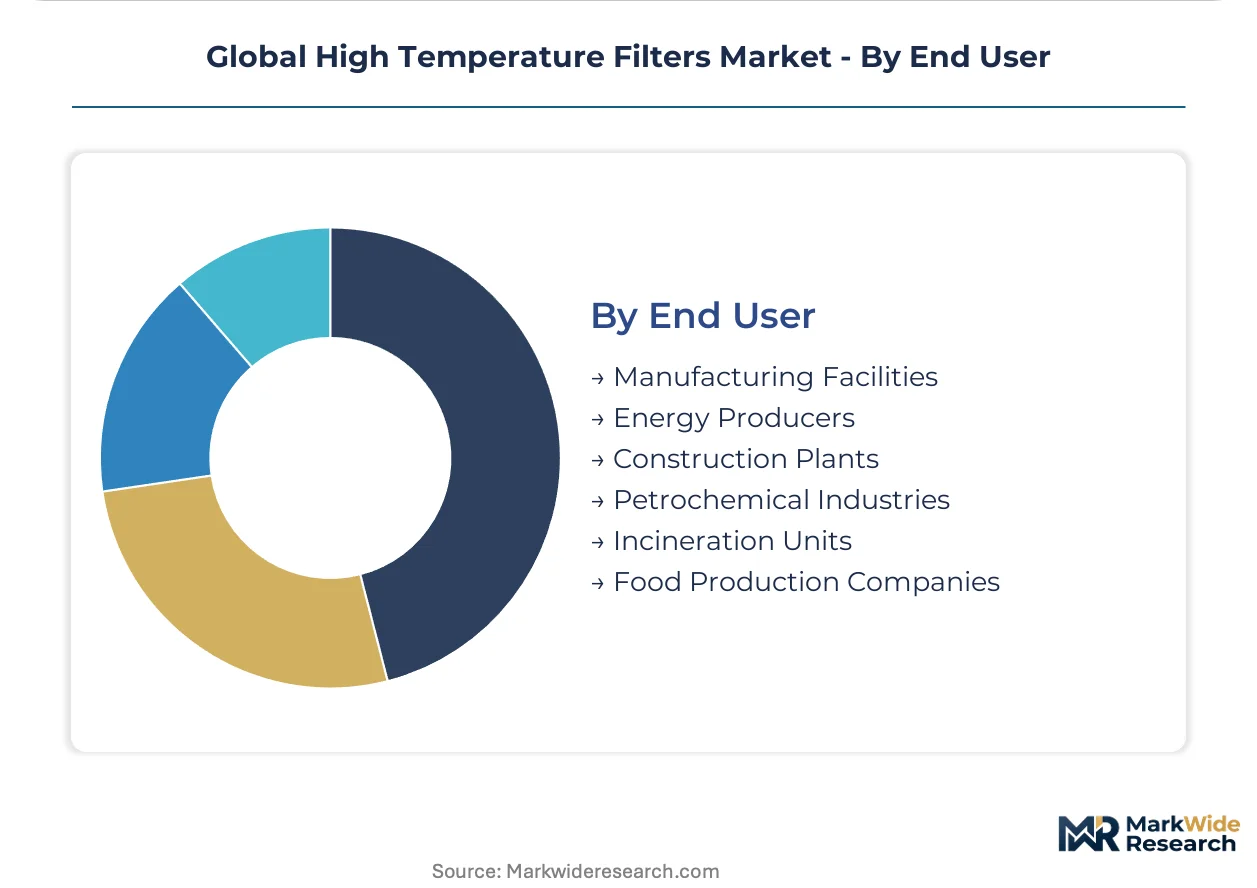
- Energy Producers:This segment includes utilities and independent power producers operating thermal power plants and waste-to-energy facilities. Operational reliability and continuous compliance with emission limits are paramount for these large-scale industrial customers.
- Manufacturing Facilities:Encompassing diverse industries like metal processing and chemical production, these facilities require high temperature filters for process protection and emission control. China's dual carbon goals significantly influence filter adoption within its extensive manufacturing base.
- Construction Plants:Cement and asphalt plants fall under this category, using filters to manage dust and particulate emissions from their production processes.
- Petrochemical Industries:These industries utilize high temperature filters for gas stream purification in refining and chemical synthesis, often in corrosive environments.
- Incineration Units:Facilities for hazardous and municipal waste incineration rely on high-efficiency filters to control toxic emissions.
- Food Production Companies:These companies use high temperature filters in processes requiring clean air and high thermal resistance, such as baking and drying.
Compliance pressure drives substantial procurement among Energy Producers, whereas Food Production Companies focuses on specialized, high-purity applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial heartland, particularly the Yangtze River Delta, drives significant demand for high temperature filters. This region's intensive manufacturing output, coupled with stringent environmental policies, compels widespread adoption of advanced filtration technologies across diverse sectors. Industrial clusters throughout Asia and Europe also demonstrate strong procurement patterns.
China
Demand for high temperature filters in China stems from its expansive steel, cement, and non-ferrous metal production. The country's dual carbon goals and associated GB standards for industrial pollutants mandate advanced filtration systems. Industrial zones in the Yangtze River Delta and Pearl River Delta are witnessing substantial investments in modern air pollution control equipment.
United States
The United States market is largely driven by its mature power generation sector and robust metal processing industries. The US Environmental Protection Agency (EPA) sets rigorous emission standards, compelling continuous upgrades in filtration technology. Major petrochemical complexes along the Gulf Coast are also significant end-users, requiring specialized high-temperature solutions.
Germany
Germany's demand for high temperature filters is strongly influenced by its advanced waste-to-energy facilities and sophisticated chemical processing plants. The European Union's Industrial Emissions Directive (IED) compels industries to adopt best available techniques for emission reduction. The industrial heartland of the Ruhr Valley remains a key area for high-performance filtration installations.
India
India's rapidly industrializing economy presents a significant opportunity for high temperature filter manufacturers. Growing enforcement of pollution norms in its power generation, steel, and cement sectors requires new filtration installations. Gujarat's extensive industrial corridors and the manufacturing hubs around Maharashtra are experiencing heightened demand for robust air quality solutions.
Japan
Japan's industrial landscape, characterized by advanced manufacturing and metal processing, necessitates high-performance filtration. Strict national regulations, including JIS standards for industrial emissions, ensure continuous investment in sophisticated air pollution control. The Kansai region, with its heavy industry and chemical plants, represents a concentrated area of high-temperature filter application.
Global High Temperature Filters Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the high temperature filters market, creating a tiered competitive structure. The market comprises large, diversified industrial conglomerates offering broad portfolios alongside specialized filtration experts focused on niche material science. Strategic archetypes include integrated solutions providers, material innovation specialists, and extensive distribution network operators. Dominant competitive moves involve strategic partnerships for technology co-development and geographic expansion into emerging industrial economies.
Within the integrated solutions provider archetype, US-based Donaldson Company, Inc. leverages its filtration media expertise to deliver comprehensive systems for complex industrial environments. Sweden-based Camfil AB differentiates through its focus on energy efficiency and air quality consulting, complementing its filter products. Parker Hannifin, an Inc. entity, sustains a strong market position through its extensive distribution network and broad portfolio covering multiple end-user applications.
| Leading Market Players |
|---|
| Camfil AB |
| Freudenberg Filtration Technologies |
| Donaldson Company, Inc. |
| Pall Corporation |
| MANN+HUMMEL |
| Parker Hannifin |
| Walker Filtration |
| Filtration Group |
| American Air Filter Company, Inc. |
| Others |
Cost & Logistics Intelligence
China's dual carbon goals gate qualified supply for advanced high temperature filters and enable premium-tier pricing access for high-efficiency solutions. This environmental mandate compels manufacturers to invest in sophisticated material science, influencing both production costs and market value for compliant filtration systems.
Pricing Analysis
Outcome-based contracting is becoming the dominant pricing model for high temperature filters, where pricing often ties to guaranteed emission levels or system uptime. Price differentiation stems from filter material composition, with PTFE-coated and ceramic filters commanding higher prices than traditional fiberglass. After-sales service bundles, including predictive maintenance, also drive premium pricing. Pricing pressure stems from the increasing commoditization of traditional fiberglass filters in less demanding applications. Small and medium-sized enterprises (SMEs) are generally most price-sensitive, while large energy producers prioritize long-term operational reliability over initial cost.
Supply Chain Analysis
Logistics and freight costs significantly influence the final pricing of high temperature filters, particularly for specialized media transported across continents. Geographic supply concentration centers in China for basic components, alongside Germany and the United States for advanced filtration media and systems. Raw material dependencies include specialized fiberglass, PTFE resins, and various metal alloys for structural components. Regulatory uncertainty regarding PFAS compounds creates a structural risk for material manufacturers, potentially disrupting the supply of synthetic media. Distribution runs through a combination of direct sales channels to large industrial end-users and specialized industrial distributors for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High temperature filters are in a technology-transition phase where advanced catalytic filter media are replacing multi-stage air pollution control systems, streamlining industrial processes.
For Market Incumbents:
Deploy sensor-based predictive maintenance platforms to transition from product-centric sales to comprehensive service models. This strategy counters the commoditization of traditional media and reinforces customer loyalty. Invest in material science R&D for PFAS-free alternatives to mitigate future regulatory risks. Pursue certifications for new synthetic materials to maintain a competitive edge against emerging entrants.
For New Entrants and Emerging Players:
China's GB standards for industrial pollutants open a window for specialized cartridge filter providers. Target underpenetrated geographies like India's rapidly industrializing power generation and cement sectors. Focus on emerging applications such as green hydrogen production, which requires precise particulate control from gas streams. A go-to-market angle emphasizing compact, high-efficiency cartridge systems with lower installation footprints offers a distinct advantage.
For Investors and Strategic Acquirers:
Increased adoption of PTFE-coated filters in chemical processing is the leading indicator that material innovation drives market share. Long-term viability rests on advanced material development and digital service integration over the next decade. Identify mid-sized firms with proprietary synthetic filter media or robust digital monitoring capabilities as prime acquisition targets. New government mandates for ultra-low emission technologies serve as a critical signal to watch for accelerated market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Material Science R&D Investment | Developing next-generation filter media enhances performance and addresses evolving regulatory requirements. |
| Digital Service Platform Development | Integrating predictive maintenance services creates recurring revenue streams and deepens customer relationships. |
| Geographic Expansion into India | Leveraging India's industrial growth provides access to a large, underserved market for new installations. |
| Strategic Partnerships for Green Hydrogen | Collaborating on filtration solutions for emerging energy sectors secures early market positioning. |
| Acquisition of Niche Technology Firm | Gaining proprietary filtration technologies strengthens product portfolios and expands application capabilities. |
Research Approach
Multi-period observation of industrial emissions data anchored the trend analysis, supplemented by interviews with plant managers, procurement leads, environmental compliance officers, and R&D directors. Secondary validation included US EPA reports, EU Industrial Emissions Directive documents, China's MEE publications, and customs data. This approach facilitated a robust bottom-up and top-down triangulation of market insights.
A rigorous segment-weighting approach informed the market size estimations across the analysis window. Segmentation dimensions modeled included filter type, material, application, end-user, and regional regulatory framework. Compound annual growth rates were derived from historical growth patterns and projected industrial expansion. Industry-specific forecast inputs included planned waste-to-energy facility capacity additions and steel production forecasts.
The model assumes a particular technology adoption path; alternative pathways for advanced catalytic filter media would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement and technological advancements. Unforeseen regulatory changes concerning PFAS compounds or economic downturns impacting industrial CAPEX represent key risk factors. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Melt-Blown Polypropylene Filters Market
Filters
United States Activated Carbon Market
Filters
Global Pleated Filters Market
Filters
Industrial Filtration Market
Filters
Global Hollow Fiber Filtration Market
Filters
Filter Media Market
Filters
Aerospace Filter Market
Filters
Residential Filters Market
Filters
Diatomaceous Filter Aid Market
Filters
Filtering Centrifuges Market
Filters
Global Sterile Filtration Market
Filters
Global Industrial Filters Market
Filters
Global Cartridge Filters Market
Filters
Global Gas Filtration Media Market
Filters
Global Baghouse Filters Market
Filters
Hydraulic Filters Market