
 Global Pleated Filters Market | 2026-2036
Global Pleated Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pleated Filters Market Foresight
Asset-light leasing models for industrial filtration systems is tilting competitive dynamics toward service-integrated suppliers. Donaldson Company leverages its captive distribution network to bundle filter replacement contracts with equipment uptime guarantees. MANN+HUMMEL anchors its position through backward integration into synthetic media production, controlling raw material quality and cost structures. Camfil specializes in cleanroom-grade pleated configurations, occupying the premium tier where certification requirements create sticky customer relationships.
Pleated filters are air and liquid filtration elements constructed from media folded into parallel pleats to maximize surface area within a compact form factor, typically achieving MERV 13-16 efficiency ratings or HEPA-grade particle retention depending on media composition and pleat geometry. Their primary purpose is to remove particulate contaminants from process streams, intake air, or recirculating systems across industrial, commercial, and critical-environment applications. HEPA filters and synthetic media filters command the deepest margin pools due to stringent certification requirements and specialized manufacturing equipment that limit new entrants. HVAC systems and cleanrooms represent the most structurally differentiated application segments, with the former driven by replacement volume and the latter by performance-linked pricing and long validation cycles.
EPA National Ambient Air Quality Standards, EU F-Gas Regulation, and ISO 16890 filtration testing protocols collectively elevate product performance thresholds and compress the viable supplier base. These frameworks mandate documented efficiency degradation curves and pressure-drop performance, forcing manufacturers to invest in accredited testing laboratories. Stakeholders must monitor how China's GB standards evolution and India's BIS certification expansion reshape market access rules for imported pleated filter assemblies.
Market Dynamics
Replacement cycle compression driven by tightening EPA air quality standards and EU F-Gas Regulation is restructuring procurement patterns, forcing facility operators to treat filtration as a compliance-linked operating expense rather than a discretionary maintenance item.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based systems is accelerating HVAC retrofit programs across Germany, France, and Italy, generating synchronized filter replacement demand.
- Semiconductor fabrication:Advanced node production in Taiwan, South Korea, and the United States requires HEPA-grade pleated configurations with documented efficiency degradation curves.
- Synthetic media advancement:Nanofiber-coated substrates are extending service intervals while maintaining MERV 14-16 performance, reducing total cost of ownership for industrial buyers.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and fiberglass mat prices fluctuate with crude oil indices, compressing margin predictability for media converters.
- Testing laboratory scarcity:ISO 16890 and EN 1822 certification requires accredited facilities concentrated in Germany and the United States, creating bottlenecks for new product validation.
- Electrostatic precipitator substitution:Heavy industrial facilities in China and India are retrofitting wet scrubber systems that reduce pleated filter dependency in high-dust environments.
Strategic Opportunities
- India BIS certification expansion:Mandatory ISI marking for HVAC filtration components is creating a compliance-driven replacement market previously served by unbranded imports.
- Data center liquid cooling:Immersion and direct-to-chip architectures require specialized pleated configurations for coolant filtration, opening a performance-premium segment.
- Filter-as-a-service models:Leasing structures bundled with predictive pressure-drop monitoring are displacing spot procurement in pharmaceutical and food processing facilities.
Industry Challenges
- Cleanroom validation timelines:FDA and EMA facility inspections require 12-18 month filter qualification cycles, freezing supplier switches and extending incumbent retention.
- Legacy ERP integration:Automated filter reordering systems must interface with decades-old maintenance management platforms prevalent in institutional buildings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pleated Filters Market |
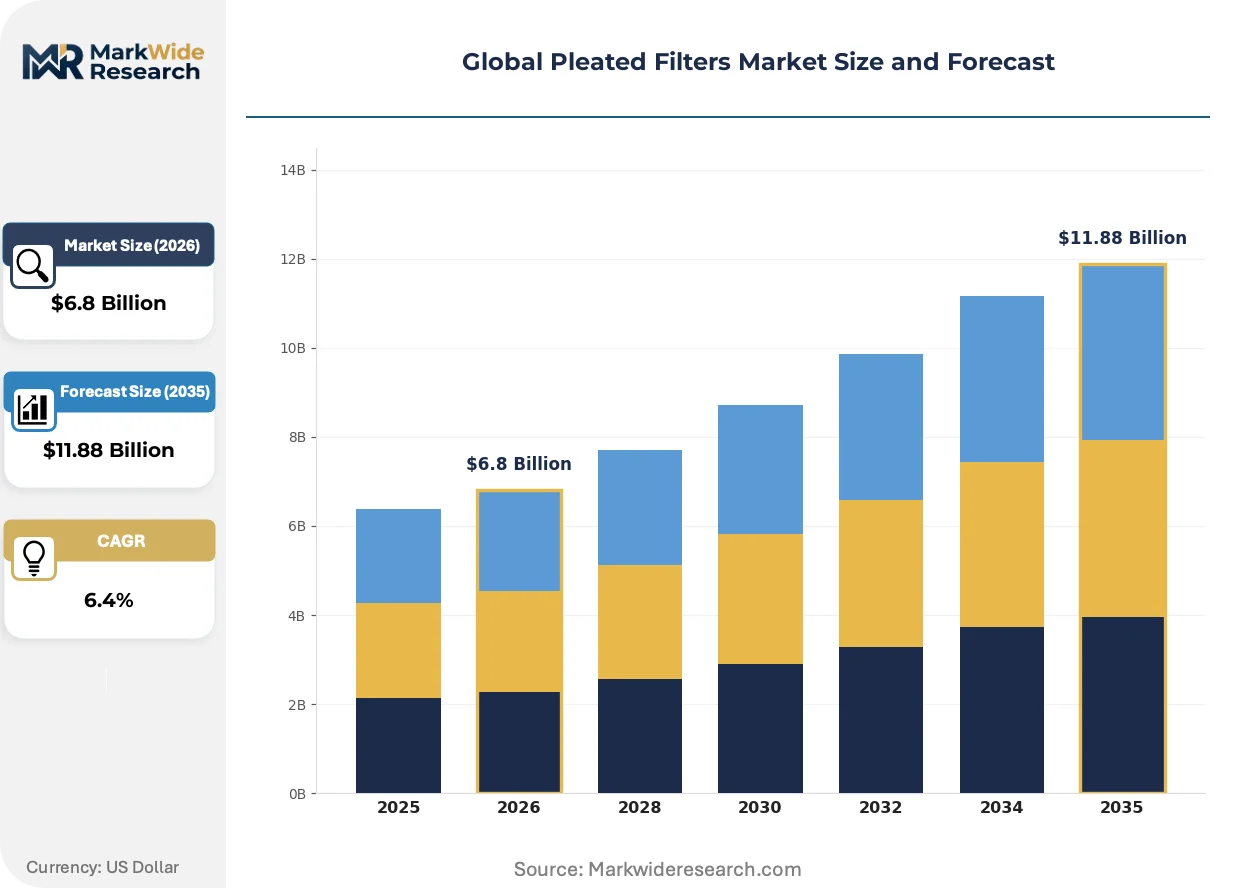
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Carbon Filters, Electrostatic Filters, Synthetic Media Filters, Cellulose Filters Application: HVAC Systems, Industrial Air Filtration, Cleanrooms, Automotive Air Purification, Food & Beverage Processing End User Industry: Pharmaceutical Manufacturing, Data Centers, Commercial Buildings, Transportation, Electronics Assembly Distribution Channel: Direct Sales, Online Retail, Distributors, System Integrators, OEM Partnerships |
| Companies Covered | 3M, Donaldson Company, Honeywell International, Freudenberg Filtration Technologies, Parker Hannifin Corporation, SUEZ, Camfil, MANN+HUMMEL, Airex Filter Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pleated Filters Market Shifts & Advancements
Active materials research and regulatory harmonization efforts are compressing product development cycles while elevating performance verification requirements across all major demand centers.
Electrospun nanofiber layers laminated onto synthetic substrates is hybridizing conventional depth-loading with surface-loading mechanisms. Pharmaceutical cleanroom operators in Switzerland and Singapore are specifying these configurations for critical Grade A environments. The technology is hybridizing competitive positioning by enabling smaller footprints at equivalent efficiency ratings, compressing the viable supplier base to those with nanofiber production capability.
The EPA's revised National Ambient Air Quality Standards for fine particulate matter is tightening allowable PM2.5 thresholds. Industrial facilities in the Ohio River Valley and California Central Valley face accelerated compliance deadlines. Commercial HVAC OEMs are responding with higher MERV default specifications, shifting volume toward pleated configurations previously considered premium tier.
Pharmaceutical manufacturers are consolidating filter procurement under single-source technical service agreements. This behavior is displacing fragmented spot purchasing through distributor networks. The shift is most pronounced in Germany and the United States, where quality agreement templates now mandate supplier audit rights and batch traceability systems.
Global Pleated Filters Market Segmentation
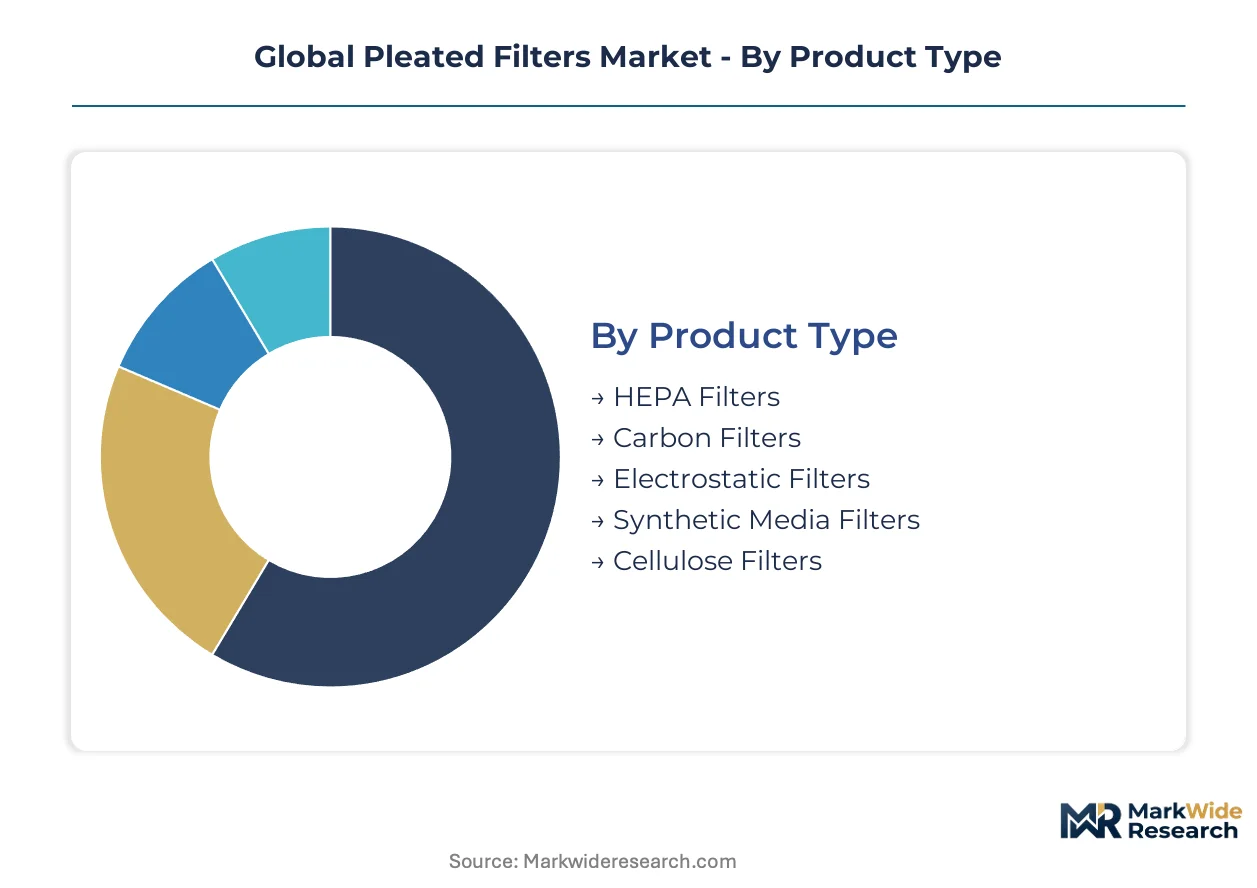
Pleated filter procurement patterns diverge sharply across product grades and end-use environments. Service contract penetration, validation complexity, and replacement frequency create distinct commercial profiles within each segment cluster.
Product Type:
After-sales intensity peaks in certified-grade categories where validation documentation and scheduled replacement programs lock in multi-year supplier relationships.
- HEPA Filters:Constructed from pleated glass microfiber media sealed in aluminum or wood frames, achieving 99.97% retention at 0.3 microns per EN 1822 protocols. Demand concentrates in pharmaceutical cleanrooms across Germany, Switzerland, and Singapore where FDA and EMA inspections mandate documented efficiency degradation curves and 12-18 month qualification cycles.
- Synthetic Media Filters:Polypropylene and polyester substrates support nanofiber surface coatings for extended service intervals. Industrial facilities in the Ohio River Valley specify these for EPA PM2.5 compliance under revised National Ambient Air Quality Standards, compressing replacement cycles to quarterly intervals.
- Carbon Filters:Activated carbon pleats adsorb gaseous contaminants in commercial HVAC and automotive cabin applications.
- Electrostatic Filters:Permanently charged synthetic media capture sub-micron particles without pressure-drop penalties in residential and light commercial systems.
- Cellulose Filters:Wood-pulp based media serve cost-sensitive industrial pre-filtration stages with lower efficiency requirements.
HEPA filters hold the largest share; momentum sits with synthetic media configurations gaining traction in EPA-regulated industrial environments.
Application:
Margin structures stratify sharply between volume-driven replacement markets and performance-premium segments where certification creates pricing power.
- HVAC Systems:Commercial and institutional buildings drive replacement volume through standardized MERV 13-16 pleated configurations. Germany, France, and Italy synchronize filter procurement with EU F-Gas Regulation HVAC retrofit programs, bundling upgrades with refrigerant system overhauls.
- Cleanrooms:Semiconductor fabrication in Taiwan, South Korea, and the United States requires HEPA-grade pleated filters with continuous particle monitoring and batch traceability systems. Grade A pharmaceutical environments in Switzerland specify electrospun nanofiber laminates for critical process zones.
- Industrial Air Filtration:Heavy manufacturing facilities deploy pleated configurations for process protection and occupational compliance.
- Automotive Air Purification:Cabin air filtration specifications tighten across OEM platforms in Germany, Japan, and the United States.
- Food & Beverage Processing:Dairy and beverage facilities in the Netherlands and Denmark specify pleated filters for sterile air and liquid clarification.
HVAC systems dominate volume; cleanrooms command the steepest expansion trajectory as semiconductor node advancement accelerates.
End User Industry:
Procurement centralization varies by regulatory exposure, with pharmaceutical and electronics sectors consolidating under technical service agreements while commercial buildings fragment across distributor networks.
- Pharmaceutical Manufacturing:Sterile process environments in Germany and the United States drive demand for validated HEPA configurations with supplier audit rights and quality agreements. Single-source technical service contracts displace fragmented spot purchasing through distributor channels.
- Data Centers:Immersion and direct-to-chip liquid cooling architectures require specialized pleated configurations for coolant filtration. Hyperscale facilities in Northern Virginia and Frankfurt specify performance-premium segments with predictive pressure-drop monitoring.
- Commercial Buildings:Institutional and office facilities generate replacement demand through standardized maintenance schedules.
- Transportation:Rail and aviation applications specify fire-rated pleated media for HVAC and pressurization systems.
- Electronics Assembly:Surface-mount and wafer-level packaging facilities in Taiwan and South Korea require cleanroom-grade filtration for yield protection.
Pharmaceutical manufacturing anchors revenue concentration; data center liquid cooling represents the fastest-climbing application.
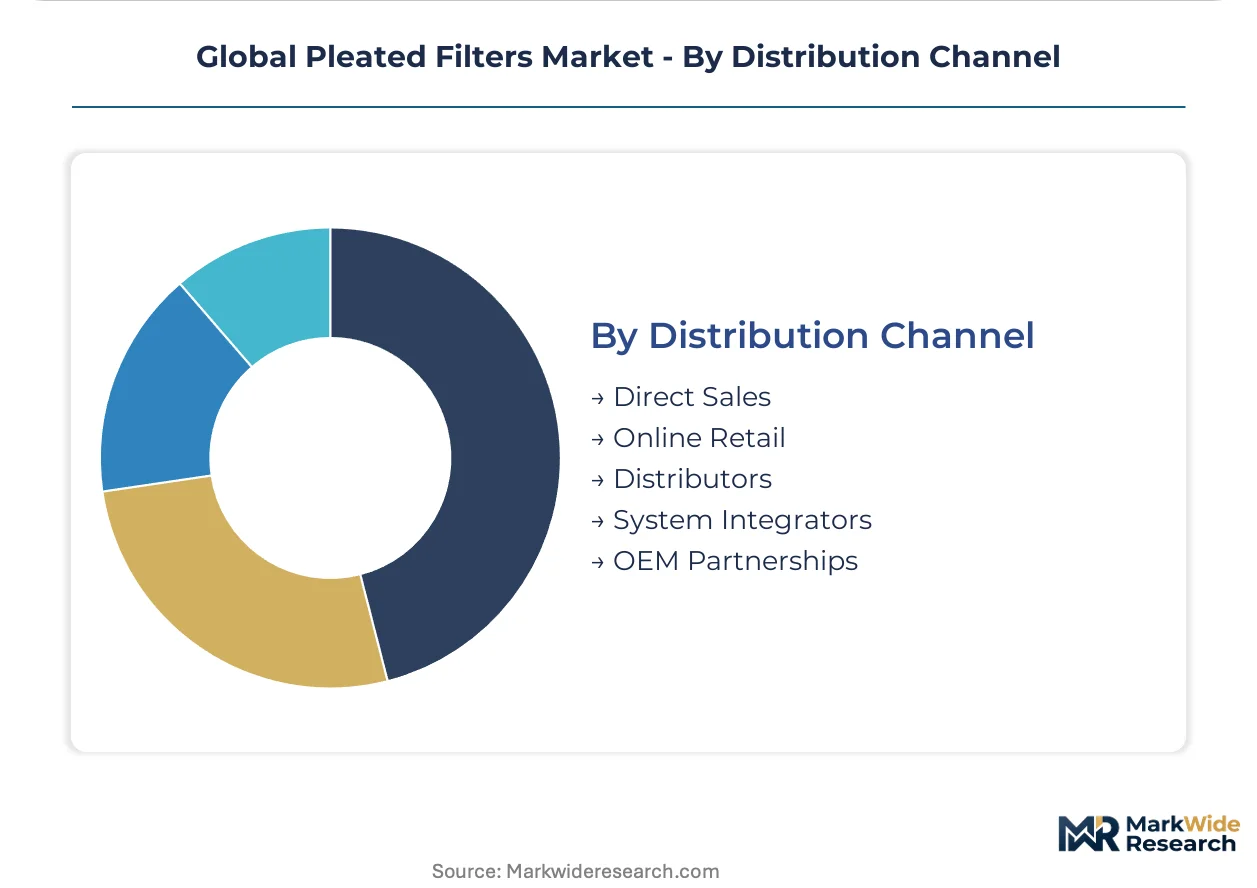
Distribution Channel:
Channel selection tracks customer scale and technical complexity, with direct engagement dominating certified environments and digital channels penetrating standardized replacement markets.
- Direct Sales:Filter-as-a-service models bundle predictive monitoring with scheduled replacement for pharmaceutical and food processing facilities in Germany and the United States. Technical service agreements mandate supplier audit rights and batch traceability infrastructure.
- Distributors:Independent and captive networks serve commercial HVAC and industrial maintenance markets with stocked inventory and local technical support.
- Online Retail:Standardized MERV-rated configurations for residential and light commercial applications migrate to digital procurement platforms.
- System Integrators:Turnkey cleanroom and HVAC contractors specify pleated filters within bundled installation and maintenance contracts.
- OEM Partnerships:Equipment manufacturers embed pleated filter specifications into original design and warranty programs.
Direct sales capture the premium tier; online retail channels are expanding most quickly in standardized commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phasedown and EPA National Ambient Air Quality Standards revision are synchronizing HVAC retrofit cycles across industrialized markets. Semiconductor fabrication expansion and pharmaceutical cleanroom investment are concentrating demand in specific metropolitan clusters.
United States
Data center liquid cooling infrastructure in Northern Virginia and hyperscale facilities in Dallas-Fort Worth drive specialized pleated filter procurement for coolant filtration. EPA revised PM2.5 thresholds under National Ambient Air Quality Standards compress replacement cycles in Ohio River Valley manufacturing. Pharmaceutical cleanroom operators in Greater Boston and Research Triangle Park consolidate procurement under single-source technical service agreements with mandated supplier audit rights.
Germany
EU F-Gas Regulation implementation accelerates HVAC system retrofits across industrial facilities in North Rhine-Westphalia and Baden-Württemberg. EMA inspection protocols and quality agreement templates freeze supplier switches through 12-18 month validation timelines. Mannheim and Stuttgart automotive clusters specify cabin air filtration upgrades as OEM platforms tighten particulate specifications.
China
Semiconductor fabrication capacity expansion in Shanghai and Hefei requires HEPA-grade pleated configurations with continuous particle monitoring infrastructure. GB standards evolution for filtration performance reshapes market access rules for imported filter assemblies. Wet scrubber retrofits in heavy industrial zones around Tangshan reduce pleated filter dependency in high-dust steel production environments.
South Korea
Advanced node semiconductor production in Pyeongtaek and Yongin demands documented efficiency degradation curves for cleanroom-grade pleated media. MFDS pharmaceutical manufacturing guidelines align with FDA and EMA inspection standards for sterile process environments. Busan-Ulsan petrochemical complexes face feedstock volatility in polypropylene mat pricing tied to regional crude indices.
India
BIS mandatory ISI marking expansion for HVAC filtration components creates compliance-driven replacement markets in Delhi-NCR and Mumbai Metropolitan Region. Pharmaceutical manufacturing facilities in Hyderabad and Bengaluru expand pleated filter procurement for sterile process environments under CDSCO oversight. Unbranded import displacement accelerates as certification requirements consolidate procurement toward accredited domestic and international suppliers.
Global Pleated Filters Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. Consolidation pressure concentrates among service-integrated suppliers bundling predictive monitoring with scheduled replacement programs. Three archetypes dominate: captive distribution network operators, backward-integrated media producers, and cleanroom-grade certification specialists. Strategic moves center on filter-as-a-service model expansion and nanofiber coating capability acquisition.
Within the certification-specialist tier, Camfil exemplifies premium-tier positioning through cleanroom-grade configurations. Donaldson Company and MANN+HUMMEL occupy distinct structural positions—one leveraging captive distribution networks for replacement contract bundling, the other anchoring cost control through in-house synthetic media production. Parker Hannifin Corporation represents the diversified industrial conglomerate archetype with filtration embedded within broader motion and control portfolios.
| Leading Market Players |
|---|
| 3M |
| Donaldson Company |
| Honeywell International |
| Freudenberg Filtration Technologies |
| Parker Hannifin Corporation |
| SUEZ |
| Camfil |
| MANN+HUMMEL |
| Airex Filter Corporation |
| Others |
Supply & Pricing Matrix
Polypropylene feedstock volatility tethered to crude oil indices compresses margin predictability across media converters while simultaneously widening spreads between certified-grade HEPA configurations and commodity cellulose alternatives. This cost instability forces procurement officers to weight total cost of ownership calculations more heavily toward service-interval extension rather than unit price minimization.
Pricing Analysis
Certification level (ISO 16890/EN 1822/FDA-grade) creates the primary spread between premium HEPA configurations and standard MERV-rated alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects validation documentation burden, nanofiber coating capability, and after-sales service bundling. Cost compression in cellulose pre-filtration tiers is intensifying because of electrostatic precipitator substitution in heavy industrial zones. Pharmaceutical cleanroom operators demonstrate lowest price sensitivity due to 12-18 month qualification cycle lock-in, while commercial HVAC maintenance contractors in institutional buildings exhibit highest sensitivity to per-unit procurement costs.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic sourcing decisions for aluminum frame components and glass microfiber media. Synthetic media production concentrates in Germany, China, and the United States, with nanofiber coating capability concentrated further in Switzerland and Singapore. Raw material dependencies rest on polypropylene resin, fiberglass mat, and activated carbon feedstocks. Single-source vulnerability in ISO 16890-accredited testing laboratories creates validation bottlenecks for new product introductions. Distribution runs through captive networks for pharmaceutical and semiconductor accounts, independent distributors for commercial HVAC replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filter-as-a-service platform economics are displacing spot procurement as predictive pressure-drop monitoring enables outcome-based contracting. Interoperability between automated reordering systems and legacy ERP platforms determines supplier stickiness in institutional building accounts.
For Market Incumbents: Entrench position through backward integration into synthetic media production and acquisition of nanofiber coating specialists. Electrospun laminate capability scarcity threatens margin pools for pure-play assemblers. Certification investment in India's BIS-accredited testing infrastructure secures first-mover advantage as ISI marking mandates consolidate procurement. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point for standardized MERV 13-16 configurations displacing unbranded imports. Data center liquid cooling filtration for immersion architectures offers performance-premium positioning without cleanroom validation timelines. Digital-first procurement platforms with same-day fulfillment capabilities unlock distributor-bypass routes. For Investors and Strategic Acquirers: Nanofiber coating specialists with pharmaceutical cleanroom validation credentials command scarcity premiums in consolidation scenarios. Long-term viability hinges on exposure to semiconductor fabrication expansion versus HVAC replacement cyclicality. Watch for MFDS and CDSCO alignment with FDA inspection protocols as signal for quality-agreement template globalization.| Strategic Initiative | Industry Significance |
|---|---|
| Filter-as-a-Service Model Expansion | Predictive monitoring bundled with scheduled replacement displaces spot procurement in pharmaceutical facilities. |
| Backward Integration into Synthetic Media | In-house polypropylene substrate production insulates margin pools from petrochemical feedstock volatility. |
| Nanofiber Coating Capability Acquisition | Electrospun laminate technology enables Grade A cleanroom positioning with documented efficiency degradation curves. |
| BIS Certification Infrastructure Investment | Accredited testing capacity in India captures compliance-driven replacement market from unbranded imports. |
| Legacy ERP Integration Partnership | Automated reordering interoperability with decades-old maintenance platforms secures institutional building accounts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and equipment manufacturer technical specifications. Interviews with cleanroom validation managers, pharmaceutical procurement directors, HVAC maintenance contractors, and synthetic media plant engineers inform demand-side segmentation. Secondary validation draws from EPA enforcement actions, EMA inspection databases, BIS certification registries, and semiconductor fab construction permits. Bottom-up unit economics triangulate against top-down industry absorption rates.
Forecast inputs incorporate filter replacement cycle compression under tightening air quality standards, semiconductor node advancement timelines, and HVAC retrofit synchronization with refrigerant phasedown schedules. Segmentation dimensions span certification grade, media composition, application environment, and end-user industry procurement centralization patterns. CAGRs derive from installed base modeling and replacement frequency shifts rather than greenfield demand projection. Industry-specific inputs include GB standards evolution trajectory and wet scrubber retrofit penetration in heavy industrial zones.
Practitioners should monitor feedstock price volatility, regulatory harmonization pace between FDA/EMA/MFDS/CDSCO, and electrostatic precipitator substitution rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Ceramic Filters Market
Filters
Global Liquid Filtration Market
Filters
Residential Filters Market
Filters
Industrial Filter Paper Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Global High Temperature Filters Market
Filters
Coolant Filtration Systems Market
Filters
Round Plate Filter Press Market
Filters
Europe Industrial Air Filtration Market
Filters
Aerospace Filter Market
Filters
United States Activated Carbon Market
Filters
Drum Filters Market
Filters
Hydraulic Filters Market
Filters
Global Gas Phase Filtration Market
Filters
Global Industrial Filters Market
Filters
Filter Bag Market