
 Global Cartridge Filters Market | 2026-2036
Global Cartridge Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cartridge Filters Market Analysis
Multi-layer nanofiber media is reconfiguring how cartridge filters achieve sub-micron retention without sacrificing flow rates. Parker Hannifin Corporation leverages its vertically integrated membrane production to control porosity specifications across pleated product lines. Donaldson Company anchors its position in industrial dust and liquid filtration through proprietary Tetratex expanded PTFE membranes. Meissner Filtration Products specializes in single-use capsules for biopharmaceutical sterile filtration, competing on validation documentation and extractables testing.
Cartridge filters are cylindrical filtration elements housing pleated, wound, or bonded media within a rigid core and outer cage, rated for particle retention from 0.04 microns to 100 microns depending on application requirements. Their primary purpose is to protect downstream equipment and ensure fluid purity in continuous or batch process streams. Pleated cartridges command premium positioning in semiconductor and pharmaceutical ultrapure water systems where high surface area translates to extended service intervals. String wound products dominate municipal and industrial pre-filtration on cost efficiency, while melt blown cartridges serve as disposable final filters in residential reverse osmosis systems.
EPA effluent limitation guidelines and EU REACH chemical restrictions are forcing industrial end users to upgrade filtration infrastructure or face operational penalties. FDA process validation requirements for pharmaceutical manufacturing create stickiness in supplier relationships once cartridges are qualified into drug master files. China's GB standards for drinking water quality and MEE discharge permits are expanding addressable volume in Asia-Pacific municipal treatment retrofits. Stakeholders must monitor how regional carbon border adjustments and PFAS restrictions reshape material specifications for polypropylene and polyester media substrates.
Market Dynamics
Multi-layer nanofiber media is compressing the performance gap between depth filters and membrane cartridges, forcing incumbent suppliers to requalify legacy pleated products across pharmaceutical and semiconductor validation protocols.
Growth Catalysts
- Biologics manufacturing scale-up:Single-use filtration systems are displacing stainless-steel infrastructure in mammalian cell culture facilities, with validation documentation requirements locking in cartridge specifications for multi-year production campaigns.
- EPA effluent limitation guidelines:Tightened discharge standards for industrial wastewater are compelling upstream oil and gas operators to retrofit produced water treatment trains with high-capacity pleated cartridges rated for sub-micron oil droplet separation.
- Semiconductor fabrication clustering:Ultrahigh-purity water systems in Hsinchu, Dresden, and Chandler are specifying hydrophilic PTFE membrane cartridges with 0.03-micron absolute ratings to protect EUV lithography equipment from particle contamination.
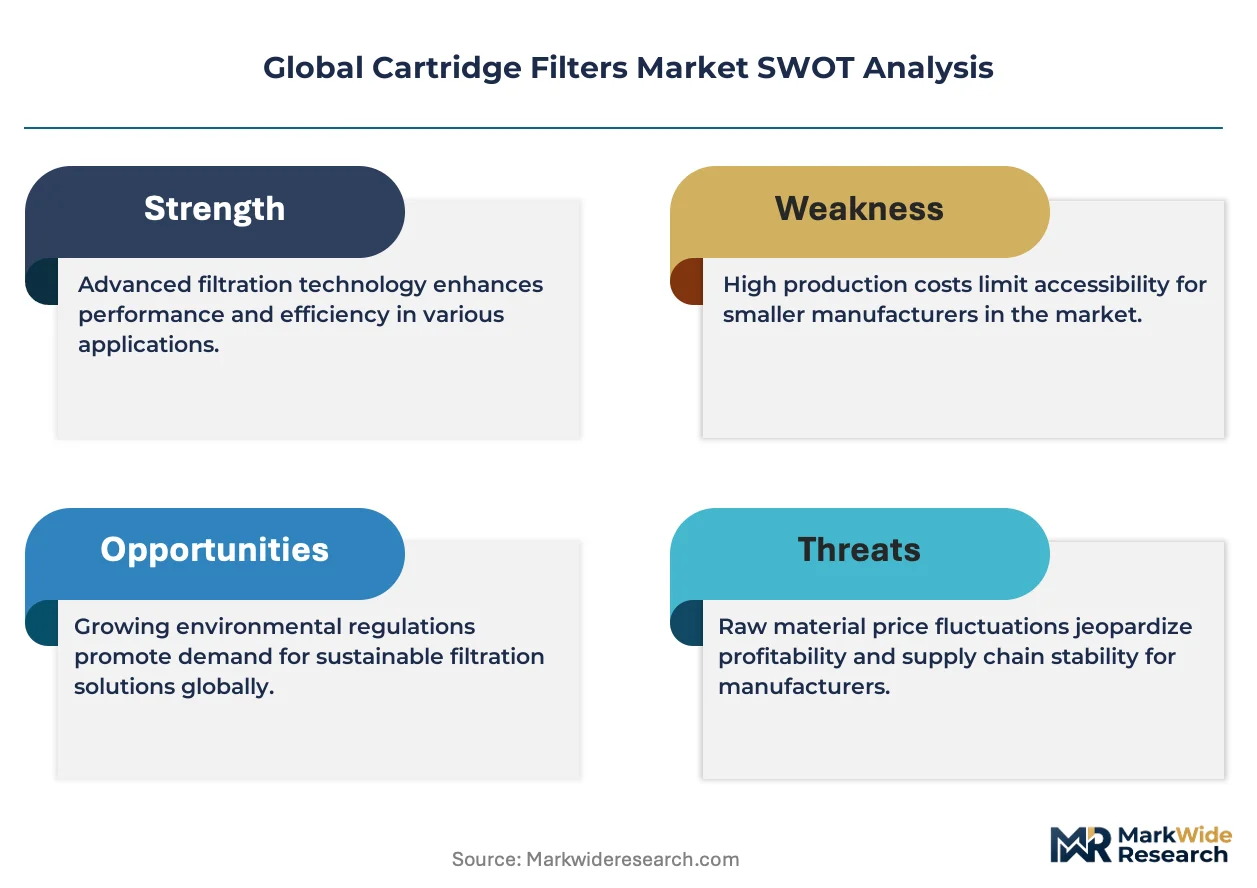
Market Restraints
- Polypropylene resin price volatility:Spunbond and melt-blown media substrates face margin compression when propylene feedstock costs spike, disproportionately affecting disposable cartridge producers without backward integration into polymer production.
- Validation timeline stickiness:FDA process validation requirements for pharmaceutical manufacturing create switching costs that protect incumbent suppliers but deter innovative entrants with superior retention efficiency from displacing qualified legacy products.
- Cross-flow filtration substitution:Tangential flow systems with reusable hollow-fiber modules are capturing volume in large-scale bioprocessing where batch volumes exceed 10,000 liters and single-use consumables become cost-prohibitive.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO regulatory alignment with ICH Q5A guidelines is accelerating biologics facility construction in Hyderabad and Bengaluru, creating demand for pre-sterilized gamma-stable capsule filters with validated extractables profiles.
- PFAS remediation infrastructure:Emerging treatment mandates for per- and polyfluoroalkyl substances in groundwater are specifying activated carbon-impregnated cartridge systems for point-of-entry municipal installations, opening a retrofit channel distinct from traditional industrial applications.
- Digital twin integration:Predictive pressure-drop monitoring via IoT sensors is enabling condition-based replacement contracts that bundle cartridge supply with remote diagnostics, shifting revenue from transactional product sales to recurring service arrangements.
Industry Challenges
- Cleanroom manufacturing capacity constraints:ISO Class 7 assembly environments for pharmaceutical-grade cartridges require capital-intensive facility construction, with 18-24 month qualification timelines delaying capacity expansion in response to demand surges.
- Extractables testing protocol divergence:Inconsistent guidance between USP <661.1>, EP 3.1, and BPOG standardized testing is forcing suppliers to maintain multiple validation datasets for the same polymeric media, inflating regulatory affairs overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cartridge Filters Market |
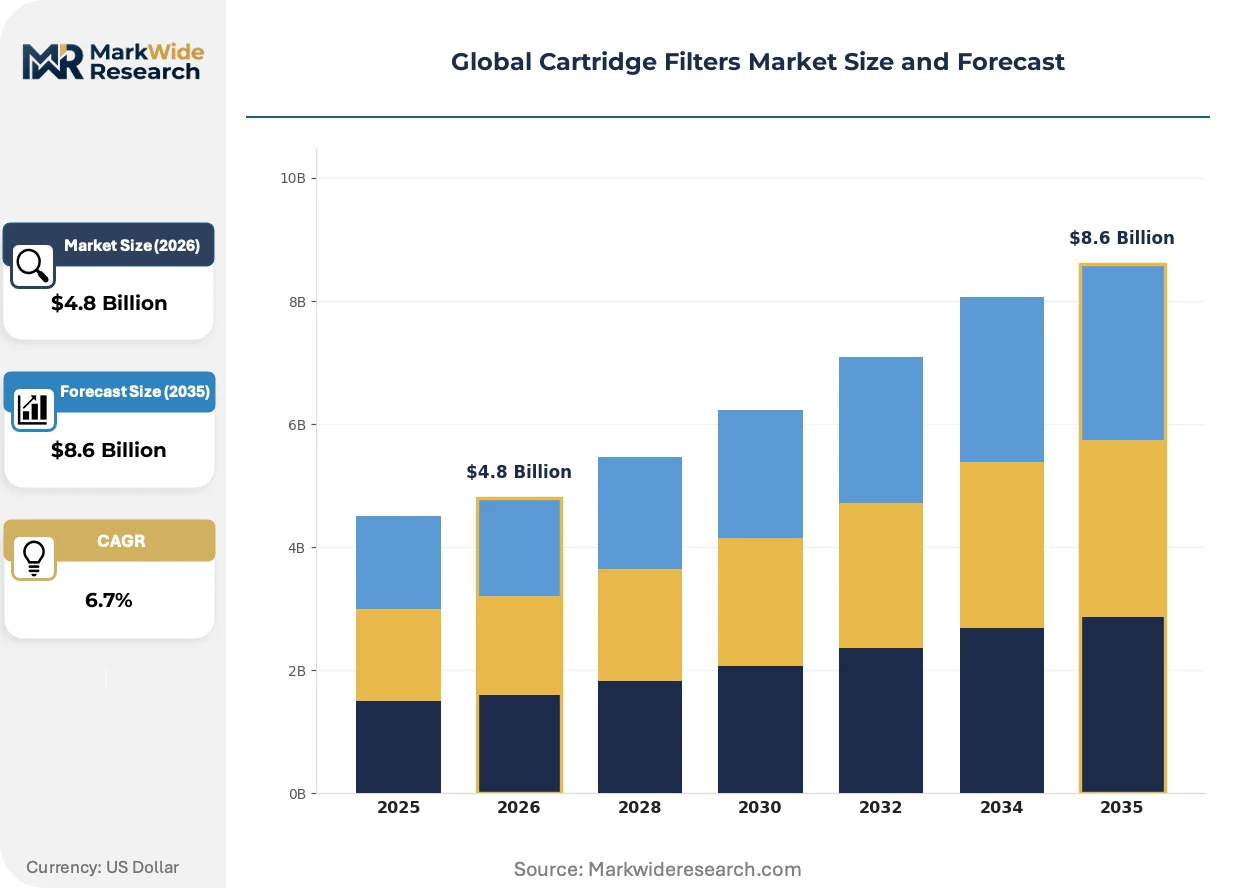
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Wound, Pleated, Melt Blown, Granular Application: Water Treatment, Chemical Processing, Oil & Gas, Food & Beverage Material: Polypropylene, Polyester, PVC, Activated Carbon End User: Industrial, Municipal, Commercial, Residential |
| Companies Covered | Parker Hannifin Corporation, 3M Company, Pall Corporation, Eaton Corporation, Pentair plc, Filtration Group Corporation, Donaldson Company, Meissner Filtration Products, SUEZ Water Technologies & Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cartridge Filters Market Emerging Trajectories
Filtration media architecture is converging with advanced manufacturing techniques that enable gradient porosity control, while regulatory chemical restrictions are reshaping material selection across end-use verticals.
Electrospun nanofiber surface layers are achieving 0.1-micron retention ratings on polypropylene microfiber substrates without the flow restriction of traditional membrane laminates. Biopharmaceutical sterile filtration applications in parenteral drug manufacturing are adopting these composite structures to extend batch processing volumes before terminal pressure-drop limits. The technology is migrating from niche virus filtration pre-treatment into mainstream final-fill applications, compressing the addressable market for standalone PES membrane cartridges in low-risk aqueous formulations.
EU REACH restrictions on perfluorinated substances are phasing out PTFE membrane production using traditional emulsion polymerization processes by 2027. Industrial chemical processors dependent on oleophobic cartridge ratings for hydrocarbon clarification must qualify alternative fluorine-free surface modifications or absorb supply chain transition costs. German mechanical engineering firms serving the chemical sector are accelerating validation of ceramic-coated cellulose media that replicate PTFE's non-wetting properties without regulatory liability exposure.
Consolidated procurement through integrated device manufacturers is displacing decentralized plant-level purchasing in semiconductor and pharmaceutical verticals. Buyers at TSMC, Samsung Biologics, and Lonza are mandating single-supplier frameworks with multi-year volume commitments in exchange for dedicated manufacturing capacity and co-developed product roadmaps. This concentration is most visible in Singapore and South Korea, where cluster economics enable just-in-time cartridge replenishment synchronized with production scheduling systems.
Global Cartridge Filters Market Segmentation
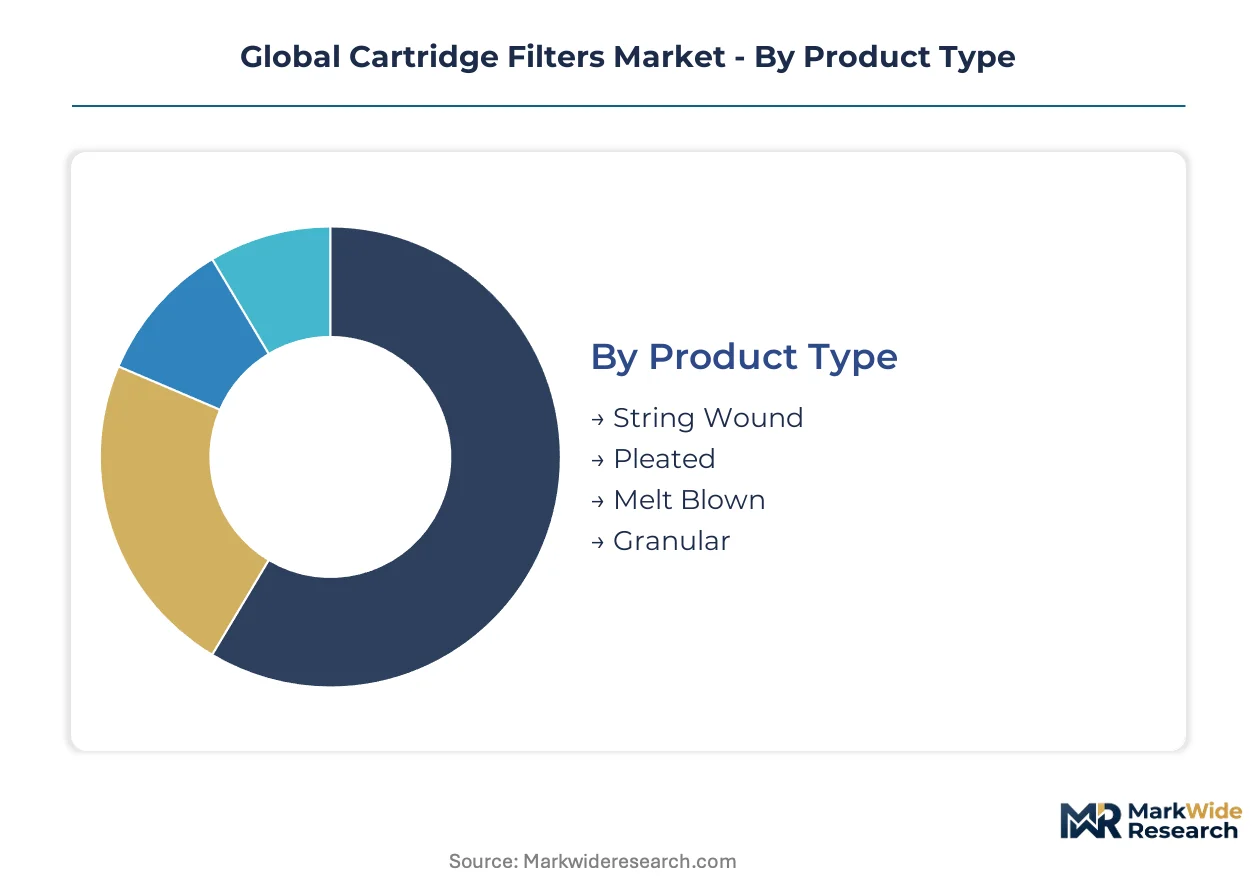
Cartridge filter segmentation reflects divergent technical requirements across fluid purity thresholds and operational scale. Product architecture, media material, and end-use environment collectively determine specification margins and supplier qualification protocols.
Product Type:
Mature formats dominate high-volume pre-filtration while engineered configurations capture premium ultrapure applications.
- Pleated:High-surface-area media folded into cylindrical geometries achieve extended service intervals in semiconductor ultrapure water systems. Hsinchu and Dresden fabrication clusters specify hydrophilic PTFE membrane cartridges with absolute ratings below 0.05 microns to protect EUV lithography equipment from particle contamination.
- String Wound:Continuous filament roving wound around perforated cores provides depth filtration for sediment-laden industrial streams. Municipal treatment facilities in the United States deploy polypropylene string wound cartridges as cost-efficient pre-filters upstream of reverse osmosis membranes.
- Melt Blown:Thermally bonded microfiber matrices without supporting cores serve as disposable final filters in residential point-of-use systems.
- Granular:Loose activated carbon or ion exchange resin packed within permeable housings addresses adsorptive contaminant removal in point-of-entry installations.
Pleated configurations retain volume leadership in value terms; melt blown products hold the steepest expansion curve in residential aftermarket channels.
Application:
Regulatory discharge standards and process validation requirements create divergent specification stickiness across verticals.
- Water Treatment:Municipal and industrial facilities deploy cartridge trains for particulate removal, disinfection byproduct control, and membrane protection. EPA effluent limitation guidelines compel upstream oil and gas operators to retrofit produced water treatment with high-capacity pleated cartridges rated for sub-micron oil droplet separation.
- Chemical Processing:Aggressive solvent streams and high-temperature operations demand chemically resistant media specifications. German mechanical engineering firms validate ceramic-coated cellulose media to replicate PTFE non-wetting properties under EU REACH perfluorinated substance restrictions.
- Oil & Gas:Produced water and completion fluid filtration specify cartridges with oleophobic surface modifications for hydrocarbon clarification.
- Food & Beverage:FDA process validation requirements for sterile filtration create supplier stickiness once cartridges qualify into drug master files for beverage processing.
Water treatment commands absolute volume; chemical processing is gaining share fastest as fluorine-free material transitions accelerate replacement cycles.
Material:
Polymer selection balances chemical compatibility, mechanical strength, and emerging regulatory liability exposure.
- Polypropylene:Dominant thermoplastic for melt-blown and spunbond media substrates offers broad chemical resistance and thermal stability to 80°C. Spunbond and melt-blown producers without backward integration into polymer production face margin compression when propylene feedstock costs spike.
- Polyester:Higher tensile strength and temperature tolerance suit hot water and steam sterilization applications in biopharmaceutical manufacturing.
- PVC:Rigid housing and support cage material provides dimensional stability in high-pressure industrial installations.
- Activated Carbon:Impregnated or granular forms address emerging PFAS remediation mandates in groundwater treatment infrastructure.
Polypropylene retains material volume leadership; activated carbon is climbing the fastest as per- and polyfluoroalkyl substance treatment mandates expand municipal retrofit specifications.
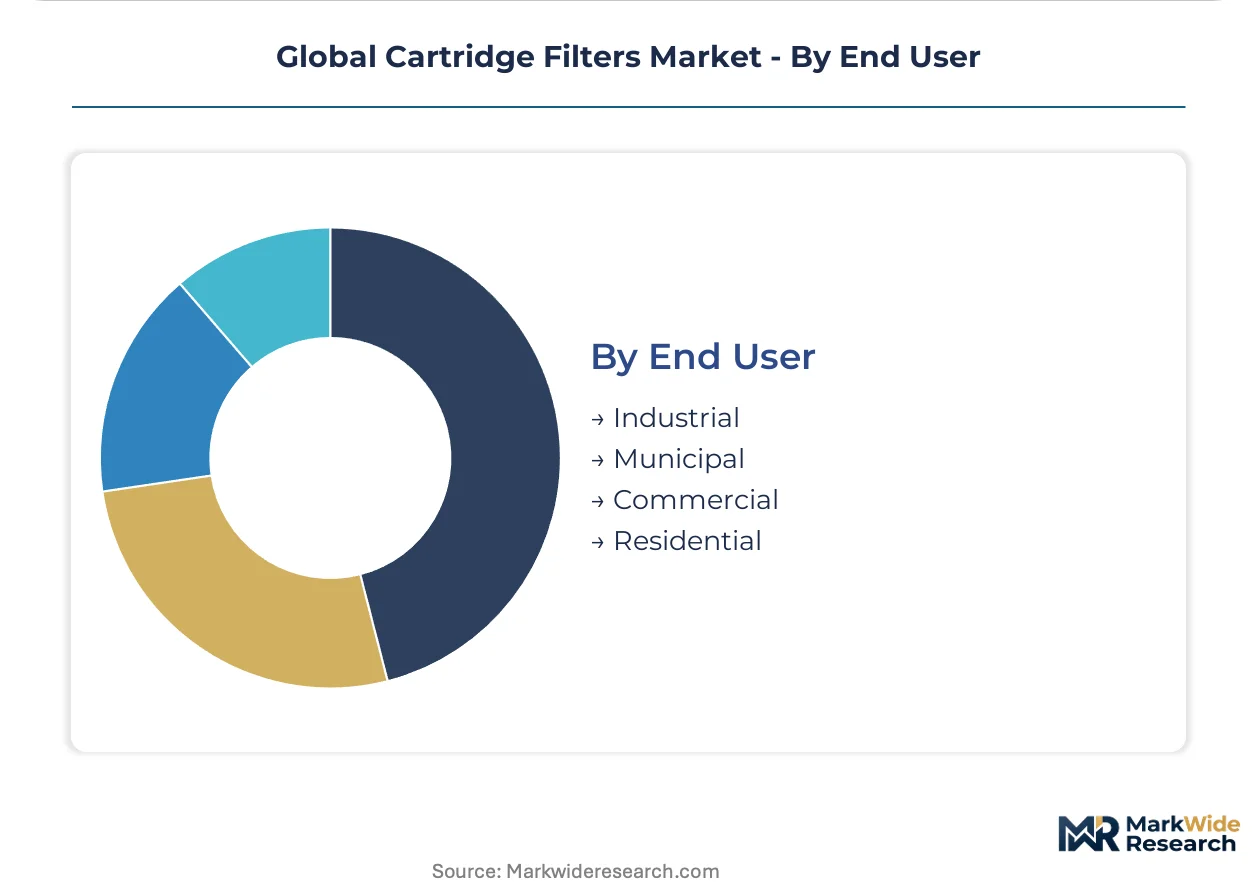
End User:
Procurement concentration and technical specification authority vary sharply across customer categories.
- Industrial:Process-scale operations with centralized engineering functions negotiate multi-year supply agreements. Integrated device manufacturers at TSMC and Samsung Biologics mandate single-supplier frameworks with dedicated manufacturing capacity.
- Municipal:Public procurement cycles and federal infrastructure funding influence replacement timing for drinking water and wastewater treatment facilities.
- Commercial:Building-scale HVAC and foodservice applications specify mid-tier cartridges through distribution channels.
- Residential:Point-of-use and point-of-entry systems rely on aftermarket replacement through retail and e-commerce channels.
Industrial end users retain value leadership; municipal segment is gaining share fastest as China GB standards and MEE discharge permits expand Asia-Pacific treatment retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German filtration component exports supply semiconductor fabrication clusters in Taiwan and South Korea, while Chinese membrane manufacturers serve domestic pharmaceutical and electronics sectors through captive production networks.
United States
Biologics manufacturing expansion in Massachusetts and North Carolina drives demand for single-use sterile filtration capsules. EPA effluent limitation guidelines compel upstream oil and gas operators in Texas and Louisiana to retrofit produced water treatment trains. The Permian Basin specifies high-capacity pleated cartridges for sub-micron oil droplet separation.
Germany
Mechanical engineering firms validate ceramic-coated cellulose media to replicate PTFE non-wetting properties under EU REACH perfluorinated substance restrictions. Dresden's semiconductor cluster sources hydrophilic membrane cartridges with absolute ratings below 0.05 microns. Bavarian pharmaceutical manufacturers expand single-use filtration systems as mammalian cell culture facilities scale production.
China
GB standards for drinking water quality and MEE discharge permits expand municipal treatment retrofits across Yangtze River Delta municipalities. Hsinchu fabrication clusters in Taiwan—supplied heavily by mainland component trade—specify ultrapure water systems requiring 0.03-micron absolute rated cartridges. Shanghai semiconductor foundries concentrate procurement through integrated device manufacturer frameworks.
India
CDSCO regulatory alignment with ICH Q5A guidelines accelerates biologics facility construction in Hyderabad and Bengaluru. Pre-sterilized gamma-stable capsule filters with validated extractables profiles qualify into drug master files for parenteral manufacturing. Karnataka's pharmaceutical corridor attracts dedicated manufacturing capacity from multinational suppliers.
South Korea
Samsung Biologics and Lonza mandate single-supplier frameworks with multi-year volume commitments in exchange for co-developed product roadmaps. Singapore cluster economics enable just-in-time cartridge replenishment synchronized with production scheduling systems. Seoul Capital Area biomanufacturing campuses validate filtration specifications for multi-year production campaigns.
Global Cartridge Filters Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive membrane production, mid-scale filtration specialists with vertical integration into polymer media, and application-focused niche suppliers with validation documentation capabilities. Dominant competitive moves include capacity expansion in ISO Class 7 cleanroom environments and strategic partnerships for digital twin integration with IoT-enabled condition monitoring.
Among diversified industrial conglomerates, Parker Hannifin Corporation and Eaton Corporation occupy positions defined by backward integration into membrane manufacturing and broad cross-sector distribution reach. Mid-scale specialists such as Donaldson Company exemplify the product-specialist archetype through proprietary expanded PTFE membrane capabilities. Application-focused players including Meissner Filtration Products represent the validation-intensive tier serving biopharmaceutical sterile filtration with extractables testing documentation.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| 3M Company |
| Pall Corporation |
| Eaton Corporation |
| Pentair plc |
| Filtration Group Corporation |
| Donaldson Company |
| Meissner Filtration Products |
| SUEZ Water Technologies & Solutions |
| Others |
Supply Flow & Price Mechanics
Hsinchu and Dresden fabrication clusters anchor cartridge filter supply capacity for semiconductor ultrapure water systems, with dedicated manufacturing lines commanding pricing premiums over standard industrial grades. Their captive cleanroom infrastructure and multi-year qualification timelines insulate premium tiers from commoditization pressure in disposable melt-blown segments.
Pricing Analysis
Next-generation electrospun nanofiber surface layers command substantial premiums over legacy pleated membrane cartridges and conventional depth-filter predecessors. Pricing stratifies across premium, standard, and economy tiers based on ISO Class 7 certification status and validated extractables documentation for pharmaceutical applications. Cost compression in melt-blown polypropylene segments is intensifying because propylene feedstock volatility squeezes non-integrated producers. Municipal water treatment facilities exhibit highest price sensitivity, while semiconductor fabs prioritize absolute retention ratings over unit economics.
Supply Chain Analysis
Taiwanese and South Korean contract manufacturers hold concentrated capacity for hydrophilic PTFE membrane production serving EUV lithography protection systems. Raw material flows draw from German mechanical engineering networks for ceramic-coated cellulose alternatives, Chinese polypropylene resin suppliers, and Japanese precision filtration component specialists. Single-source vulnerability persists in pharmaceutical-grade gamma-stable capsule assembly where ISO Class 7 qualification timelines extend eighteen to twenty-four months. Distribution runs through integrated device manufacturer procurement frameworks at TSMC and Samsung Biologics, bypassing traditional distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through consolidated procurement frameworks at integrated device manufacturers and biologics contract manufacturers, fragmenting traditional plant-level purchasing autonomy across semiconductor and pharmaceutical verticals.
For Market Incumbents: Entrench market position through backward integration into electrospun nanofiber media production and capacity expansion in ISO Class 7 cleanroom environments serving CDSCO-aligned Indian pharmaceutical corridors. Cross-flow filtration substitution with reusable hollow-fiber modules threatens single-use cartridge volumes in large-scale bioprocessing above ten-thousand-liter batches. For New Entrants and Emerging Players: Pursue white-space opportunities in PFAS remediation infrastructure for municipal point-of-entry installations and digital twin-enabled condition-based replacement contracts bundling cartridge supply with IoT diagnostics. India's Hyderabad and Bengaluru biologics construction wave offers the most penetrable geography, with pre-sterilized gamma-stable capsule filters qualifying into drug master files as the specific go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core filtration divisions lacking pharmaceutical validation documentation capabilities. Long-term viability hinges on regulatory affairs overhead management across divergent USP, EP, and BPOG extractables testing protocols. Watch for EU REACH perfluorinated substance restriction enforcement as the inflection signal triggering alternative fluorine-free material validation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO Class 7 facility construction in Karnataka and Singapore addresses pharmaceutical and semiconductor demand surges with eighteen-month qualification timelines. |
| Backward Integration into Nanofiber Media | In-house electrospun surface layer production protects margin structure against membrane laminate suppliers and enables gradient porosity control. |
| Digital Twin Integration Partnership | IoT-enabled pressure-drop monitoring shifts revenue from transactional cartridge sales to recurring predictive maintenance service arrangements. |
| PFAS Remediation Product Line | Activated carbon-impregnated cartridge systems capture municipal retrofit volume distinct from traditional industrial oil and gas applications. |
| Regulatory Alignment Investment | Unified extractables testing datasets across USP, EP, and BPOG protocols reduce overhead for multinational pharmaceutical supplier qualification. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at semiconductor fabrication facilities, pharmaceutical sterile filtration specialists, municipal water treatment procurement officers, and oil and gas produced water treatment managers. Secondary validation drew from EPA effluent limitation guideline filings, EU REACH restriction updates, CDSCO regulatory alignment notifications, SEC 10-K disclosures from diversified industrial conglomerates, and customs trade data on polypropylene resin flows. Bottom-up cartridge volume estimates triangulated against top-down market sizing from identified end-use verticals.
Calibration against historical qualification timeline data and capacity expansion announcements anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, media material composition, end-use environment, and regional regulatory cluster. CAGRs were derived from trend extrapolation of biologics manufacturing scale-up rates, semiconductor fab construction pipelines, and municipal treatment retrofit cycles. Industry-specific inputs incorporated EUV lithography equipment protection specifications and single-use filtration system displacement curves for mammalian cell culture facilities.
Sensitivities concentrate around propylene feedstock cost volatility, EU REACH perfluorinated substance restriction enforcement timing, and cross-flow filtration technology substitution thresholds in large-scale bioprocessing. Forecasts embed assumptions regarding cleanroom manufacturing capacity expansion timelines and pharmaceutical validation documentation harmonization. Quarterly review of biologics facility construction permits, semiconductor fab equipment procurement data, and municipal infrastructure funding allocations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Global Pleated Filters Market
Filters
Activated Carbon Filter Market
Filters
Coolant Filtration Skids Market
Filters
Global Gas Filtration Media Market
Filters
Nonwoven Filter Media Market
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
US Baghouse Filters Market
Filters
North America Gas Filtration Media Market
Filters
United States Activated Carbon Market
Filters
Filters and Particle Monitoring Market
Filters
Coolant Filtration Systems Market
Filters
Aerospace Filter Market
Filters
Industrial Air Filtration Market
Filters
Fabric Filter System Market
Filters
Ceramic Filters Market
Filters
ePTFE Filter Film Market