
 Metallurgical Silicon Market | 2026-2036
Metallurgical Silicon Market Size, Share, and Industry Trends Forecast 2026-2036
Metallurgical Silicon Market Analysis
Downstream alloy formulation services is rewriting margin capture across the value chain, pulling profitability away from raw smelting toward technical advisory and custom blending. Ferroglobe leverages integrated quartz mining and smelting assets across Spain and the United States to sustain cost discipline. Elkem ASA anchors its position through captive ferrosilicon capacity and deep relationships with European steelmakers. Hoshine Silicon Industry dominates volume through massive smelter complexes in southwestern China that benefit from preferential electricity tariffs.
Metallurgical silicon refers to silicon metal produced via carbothermic reduction of quartz in submerged-arc furnaces, typically achieving purity levels of 98.0% to 99.0% silicon content with iron and aluminum as principal impurities, serving primarily as an alloying additive in steel and aluminum production. Ferro silicon commands the largest product type share due to its irreplaceable role in steel deoxidization and magnesium ferrosilicon inoculation for ductile iron casting. Silicon metal for aluminum alloys represents the fastest-expanding product category as automakers substitute aluminum for steel in vehicle body structures to meet emissions standards. Solar cell applications within the application dimension are absorbing premium-grade silicon metal volumes even though semiconductor-grade material requires subsequent purification beyond metallurgical standards.
The European Union's REACH chemicals framework and F-Gas Regulation constrain smelter emissions and process gas management, while China's Ministry of Ecology and Environment enforces dual carbon goals that restrict coal-powered furnace operations and redirect capacity toward hydropower-dependent provinces. The United States EPA and OSHA jointly govern particulate emissions and workplace silica exposure limits at domestic smelters including Mississippi Silicon's facility in Burnsville. Stakeholders must track electricity tariff reforms in China's southwestern provinces and European carbon border adjustment implementation to anticipate cost shifts between Asian and North American supply origins.
Market Dynamics
Automotive lightweighting mandates are compressing the traditional steel-aluminum substitution timeline, forcing aluminum alloy producers to secure metallurgical silicon supply chains ahead of contract cycles. This demand acceleration coincides with smelter energy sourcing constraints from China's dual carbon enforcement and the EU F-Gas Regulation.
Growth Catalysts
- Automotive Emissions Standards:EU CO2 fleet targets and US EPA tailpipe rules mandate aluminum body-in-white adoption, expanding silicon metal consumption in 6xxx-series alloys. OEMs in Germany and Michigan are locking multi-year silicon supply agreements.
- REACH and F-Gas Compliance:European chemical frameworks restrict fluorinated process gases in smelter operations, creating certified-supplier premiums for compliant Chinese and Nordic producers. This redirects procurement toward hydropower-verified origins.
- Yunnan Smelter Cluster Expansion:Southwestern China's hydropower-abundant provinces concentrate new submerged-arc furnace capacity, displacing coal-dependent capacity in Henan and Shanxi. Grid tariff reforms accelerate this geographic shift.
Market Restraints
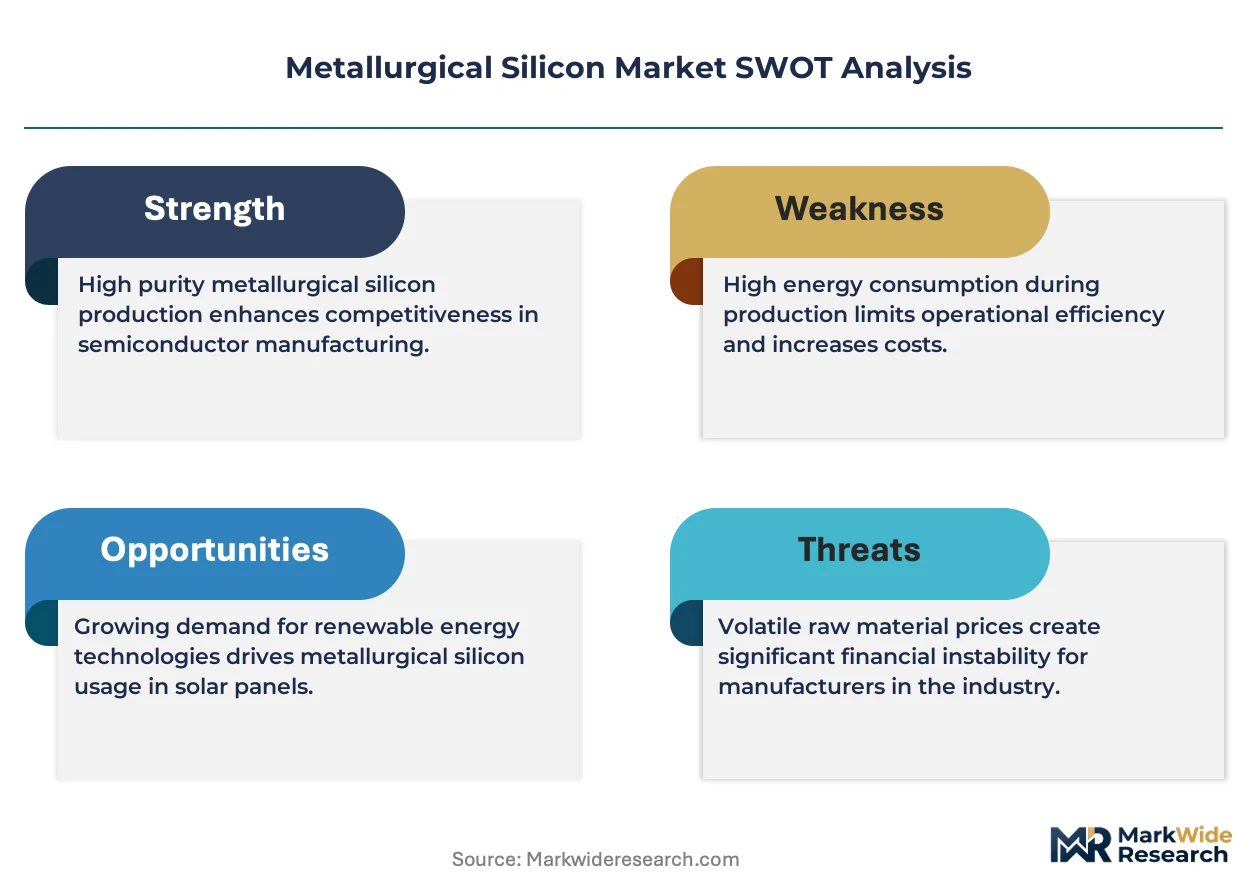
- Quartz Feedstock Concentration:High-purity quartz deposits suitable for metallurgical-grade silicon concentrate in Brazil's Minas Gerais and Spruce Pine, North Carolina, exposing smelters to single-source geological risk and maritime freight volatility.
- Energy Cost Asymmetry:Coal-to-hydropower furnace conversions in China require capital intensity that smaller European smelters cannot match, widening cost spreads between Yunnan-based and Spanish-based production.
- Semiconductor-Grade Diversion:Solar polysilicon purification lines absorb metallurgical silicon feedstock that would otherwise supply aluminum alloys, tightening 98.5%-purity availability for traditional metallurgical buyers.
Strategic Opportunities
- Secondary Aluminum Integration:Scrap-based aluminum smelters in Ohio and Ontario seek captive silicon metal blending capabilities to bypass merchant market volatility. This creates service-layer margins for alloy formulation specialists.
- Carbon Border Adjustment Arbitrage:The EU CBAM phase-in rewards verified low-carbon silicon from Norwegian and Icelandic smelters with tariff exemptions, incentivizing production relocation to geothermal and hydropower jurisdictions.
- Magnesium Ferrosilicon Ductile Iron:Wind turbine hub and nacelle casting demand in Denmark and Scotland expands inoculation-grade ferrosilicon requirements, a segment less exposed to automotive cycle volatility.
Industry Challenges
- Furnace Control Engineering Talent:Submerged-arc furnace electrode positioning and thermal profile optimization require expertise concentrated among retiring European operators. Chinese smelters face knowledge transfer gaps as they scale capacity.
- Silica Dust Compliance:OSHA permissible exposure limits and MEE workplace standards mandate capital-intensive baghouse and wet scrubber retrofits at US and Chinese facilities simultaneously, squeezing mid-tier operator margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallurgical Silicon Market |
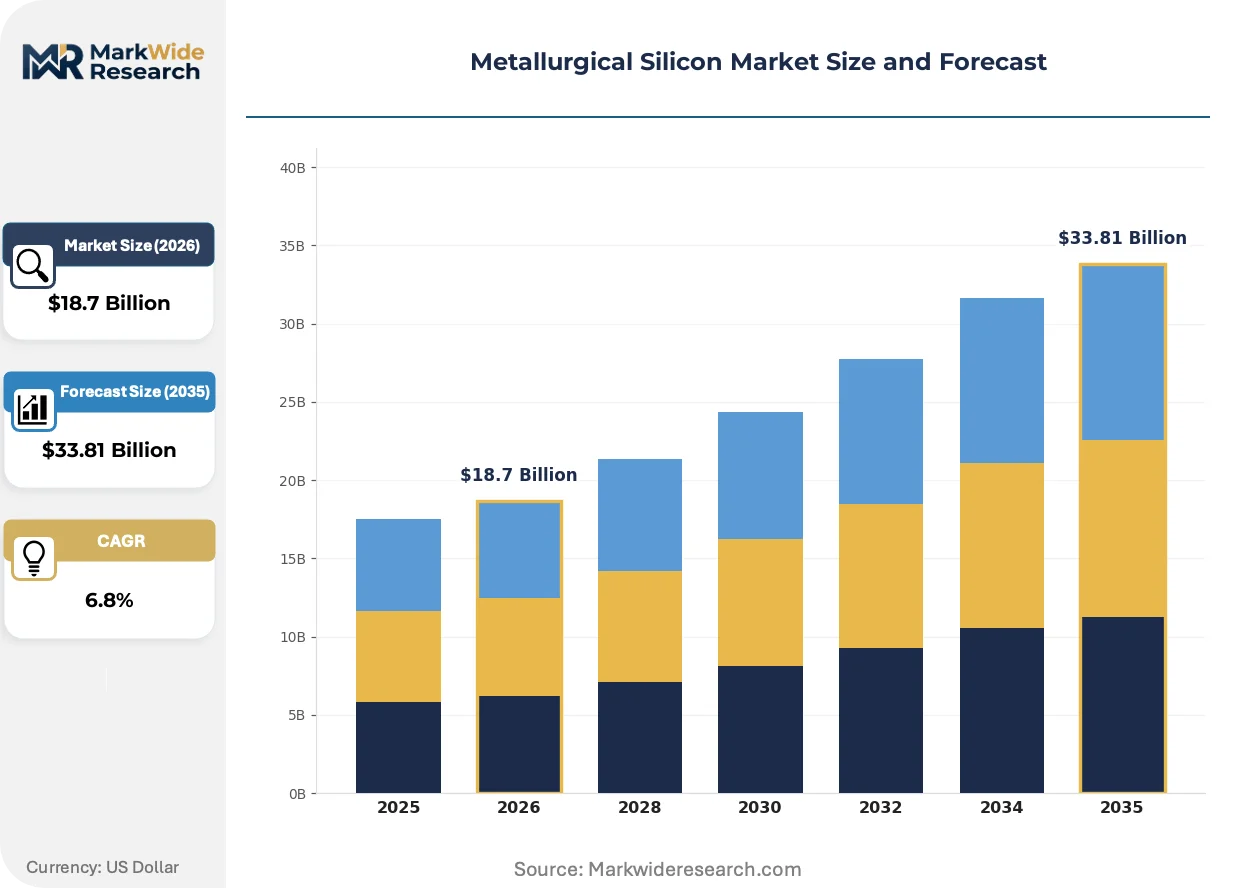
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferro Silicon, Silicon Metal, Silicon Carbide, Silicon Alloys End User: Electronics, Automotive, Chemical, Energy Application: Conductors, Semiconductors, Solar Cells, Steel Production Distribution Channel: Direct Sales, Distributors, Online Retail, Exporters |
| Companies Covered | RIMA Group, Wacker Chemie, Ferroglobe, Anyang Wanhua Metal Material, Baidao Silicon Industry, Elkem ASA, Mississippi Silicon, Zhejiang Kaihua Huantong Silicon Industry, Hoshine Silicon Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallurgical Silicon Market Emerging Trajectories
Smelter technology and alloy formulation services are converging to capture value that raw material production alone cannot retain. Process digitization and energy verification systems are becoming competitive differentiators rather than operational luxuries.
Continuous electrode baking technology is collapsing the energy intensity gap between traditional batch furnace operations and modern prebaked anode systems. Elkem and Ferroglobe are retrofitting Spanish and US facilities with automated paste plants that reduce electrode consumption per ton of silicon metal. This compression of thermal inefficiency enables smaller European smelters to defend position against Chinese scale advantages.
China's Ministry of Ecology and Environment dual carbon enforcement is accelerating coal furnace shutdowns in Henan and redirecting capacity quotas to Yunnan and Sichuan hydropower zones. Smelters must now document renewable energy certificates to maintain operating licenses. European buyers are responding with supply contract clauses mandating verified low-carbon silicon for automotive aluminum supply chains.
Alloy buyers are consolidating procurement through technical service contracts rather than spot silicon metal purchases. Tier-1 aluminum producers in Michigan and Bavaria now specify custom ferrosilicon blends with guaranteed inoculation performance, shifting supplier relationships from commodity transactions to joint formulation development. This behavioral shift concentrates volume among integrated quartz-to-alloy operators with laboratory capabilities.
Metallurgical Silicon Market Segmentation
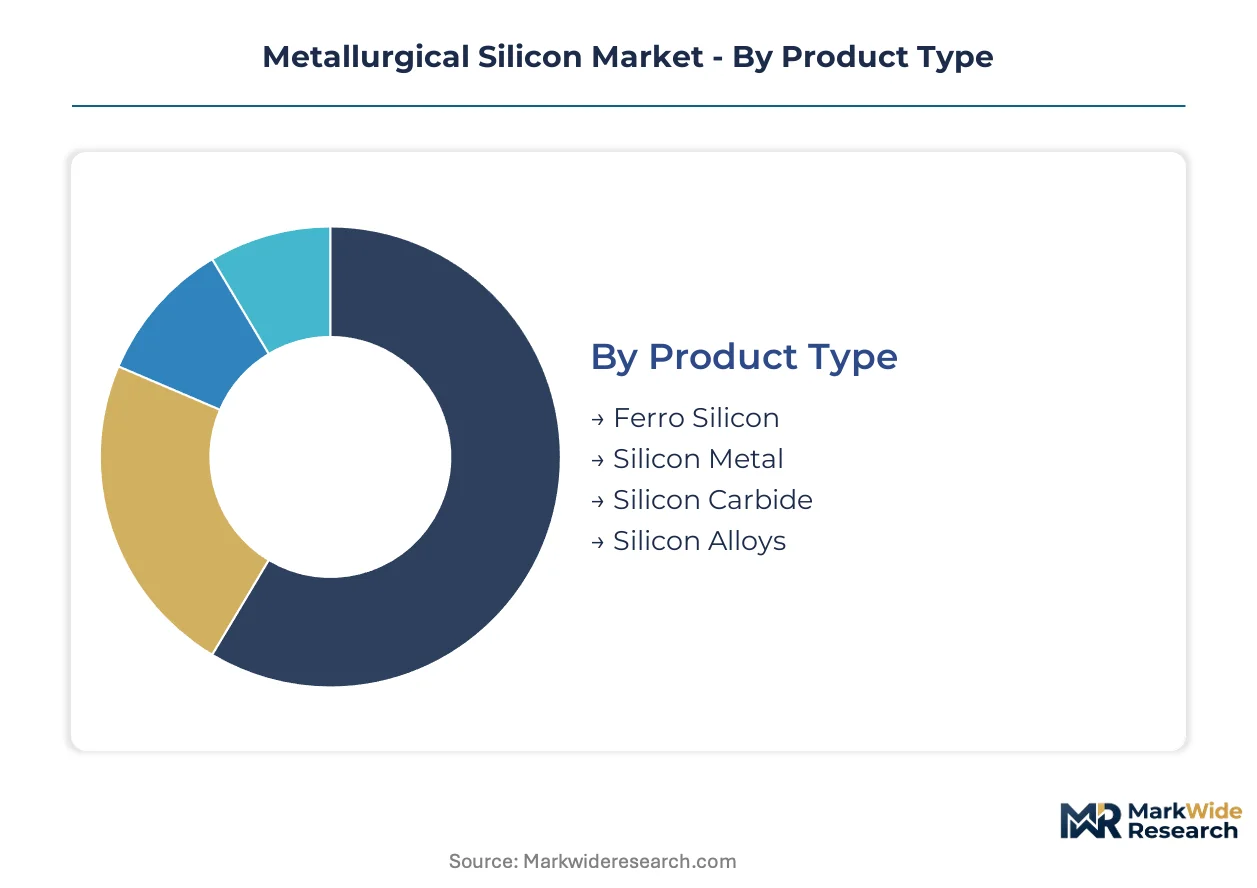
Metallurgical silicon serves radically different performance requirements across steel deoxidation, aluminum alloying, and solar feedstock preparation. Segmentation reveals how purity thresholds, energy intensity, and customer proximity reshape competitive positioning within each slice of the value chain.
Product Type:
Use-case spectrum spans commodity steel additives to precision aluminum alloys and abrasive materials, with each tier demanding distinct furnace configurations and quartz feedstock grades.
- Ferro Silicon:Iron-silicon alloy typically containing 75% silicon content serves as the primary deoxidizer in carbon steel production and as an inoculant for ductile iron casting. Demand concentrates in German and US automotive foundries where EPA and OSHA silica exposure rules favor suppliers with baghouse-equipped facilities.
- Silicon Metal:Metallurgical-grade material at 98.0-99.0% purity supplies aluminum alloy producers for automotive lightweighting and polysilicon feedstock for solar cell manufacturing. Michigan and Bavaria-based OEMs are locking multi-year supply agreements ahead of contract cycles as dual carbon enforcement in China restricts coal-powered furnace output.
- Silicon Carbide:Hard ceramic compound produced from quartz and petroleum coke serves abrasive grinding wheels and refractory linings for steel ladles.
- Silicon Alloys:Custom ferrosilicon-magnesium blends and complex master alloys target specialized inoculation requirements for wind turbine castings in Denmark.
The dominant share belongs to Ferro Silicon, while Silicon Metal is closing the gap fastest.
End User:
Customer archetypes range from process-integrated manufacturers to specification-driven assemblers, with procurement patterns diverging sharply between spot commodity buying and technical service contracts.
- Automotive:Aluminum body-in-white programs at German and Michigan OEMs drive 6xxx-series alloy consumption, with tier-1 suppliers now specifying custom ferrosilicon blends with guaranteed inoculation performance rather than commodity silicon metal.
- Electronics:Solar cell manufacturers absorb premium-grade metallurgical silicon for subsequent polysilicon purification, tightening 98.5%-purity availability for traditional metallurgical buyers as purification lines expand capacity.
- Energy:Wind turbine hub and nacelle casting demand in Scotland expands magnesium ferrosilicon requirements for ductile iron inoculation.
- Chemical:Silicone precursor producers and fume silica manufacturers source specific particle size distributions for downstream silicone polymerization.
Automotive commands the largest procurement volume, though Electronics is expanding most quickly as solar installation targets accelerate.
Application:
Functional requirements split between electrical conductivity enhancement, structural alloying, and photovoltaic energy conversion, with purity thresholds escalating across each tier.
- Steel Production:Deoxidation and alloying in electric arc furnaces and basic oxygen steelmaking consumes the majority of ferro silicon output, with US EPA particulate emissions rules governing smelter operations at facilities like Mississippi Silicon in Burnsville.
- Solar Cells:Metallurgical silicon feedstock undergoes Siemens process purification to reach semiconductor-grade purity for photovoltaic wafers, diverting material that would otherwise supply aluminum alloys.
- Semiconductors:Ultra-high purity requirements exceed metallurgical standards, though metallurgical-grade material serves as the essential feedstock for subsequent purification.
- Conductors:Aluminum-silicon electrical transmission alloys leverage silicon additions to improve castability and reduce hot cracking in continuous casting operations.
Steel Production retains the foundational demand position, while Solar Cells is gaining share fastest amid renewable energy procurement mandates.
Distribution Channel:
Supply chain configuration varies from furnace-direct relationships for volume consumers to fragmented intermediary networks for smaller alloy blenders and foundries.
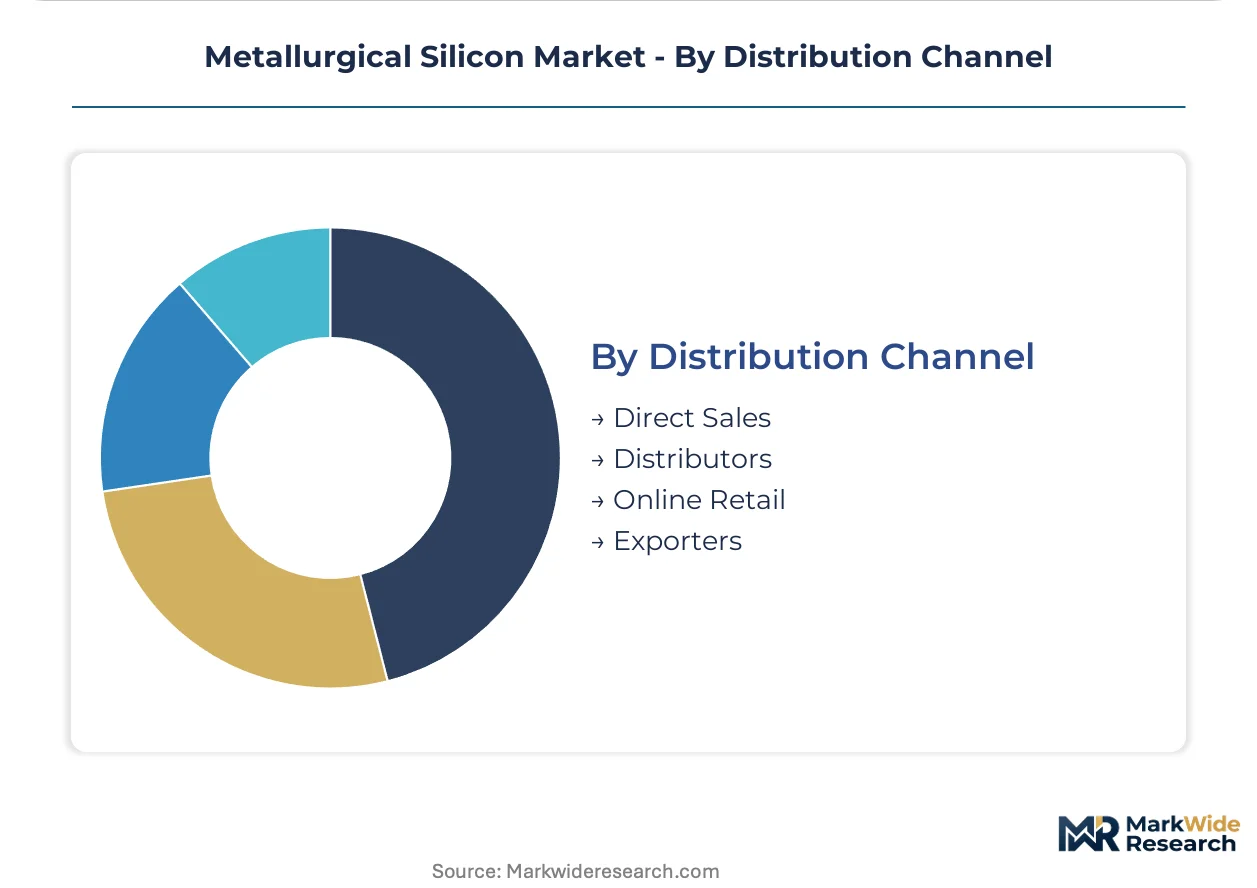
- Direct Sales:Integrated quartz-to-alloy operators with laboratory capabilities supply tier-1 aluminum producers through technical service contracts rather than spot transactions, capturing formulation-layer margins.
- Distributors:Regional metal service centers stock standard ferro silicon grades for smaller Ohio and Ontario scrap-based aluminum smelters seeking captive blending capabilities.
- Exporters:Yunnan and Xinjiang smelter clusters supply global silicon metal output through maritime bulk shipment to European and North American alloy producers.
- Online Retail:Limited to specialty silicon carbide abrasives and small-laboratory quantities, with negligible share in bulk metallurgical silicon.
Direct Sales dominates volume and margin capture, though Distributors are expanding fastest as secondary aluminum integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smelter capacity clusters tightly around hydropower-rich geographies where electricity costs determine competitive survival. China dominates absolute output volume while European and North American producers defend position through carbon-verified supply chains and proximity to automotive alloy demand.
China
Aluminum alloy consumption for electric vehicle lightweighting and solar polysilicon feedstock absorption drive procurement intensity. The Ministry of Ecology and Environment enforces dual carbon goals that shutter coal-powered furnaces in Henan and redirect operating quotas to Yunnan and Xinjiang provinces. Southwestern smelter complexes leverage preferential grid tariffs to supply global silicon metal output.
United States
Automotive OEMs in Michigan and Ohio lock multi-year ferrosilicon agreements for ductile iron casting and aluminum body-in-white programs. The EPA and OSHA jointly govern particulate emissions and workplace silica exposure limits at domestic facilities. Mississippi Silicon's Burnsville operation anchors North American merchant supply amid import dependency for high-purity grades.
Norway
Geothermal and hydropower smelters capture EU carbon border adjustment arbitrage as the CBAM phase-in rewards verified low-carbon origins with tariff exemptions. Elkem ASA operates integrated quartz mining and submerged-arc furnace assets. Rjukan and Salten industrial clusters supply automotive aluminum producers in Germany with documented renewable energy certificates.
Spain
Ferroglobe sustains cost discipline through captive quartz deposits and smelting integration across Asturias and Catalonia. The EU REACH chemicals framework and F-Gas Regulation constrain process gas management and emissions intensity. Iberian producers retrofit facilities with automated paste plants to compress thermal inefficiency against Chinese scale competition.
Brazil
High-purity quartz deposits in Minas Gerais state expose global smelters to single-source geological risk for metallurgical-grade feedstock. The country's mining regulator governs extraction permits for Spruce Pine-comparable crystalline silica. Maritime freight volatility from South Atlantic ports amplifies cost uncertainty for Asian and European alloy consumers.
Metallurgical Silicon Market Vendor Landscape
Integrated quartz-to-smelter operators and electricity-advantaged scale producers split the market into divergent margin architectures. Consolidation concentrates volume among Asian smelter clusters while European and North American players defend niche positions through carbon verification and technical service layers. Strategic archetypes include hydropower-leveraged volume leaders, integrated mining-smelting specialists, and alloy formulation service providers. Competitive moves center on coal-to-renewable furnace conversions and backward integration into quartz mining assets.
Among Nordic integrated operators, Elkem ASA exemplifies the captive ferrosilicon capacity archetype with deep European steelmaker relationships. Ferroglobe occupies the transatlantic mining-smelting specialist position through Spanish and United States assets. Hoshine Silicon Industry represents the scale-driven hydropower-leveraged model with massive southwestern China smelter complexes. These three anchors illustrate how geography, energy sourcing, and integration depth stratify competitive positioning.
| Leading Market Players |
|---|
| RIMA Group |
| Wacker Chemie |
| Ferroglobe |
| Anyang Wanhua Metal Material |
| Baidao Silicon Industry |
| Elkem ASA |
| Mississippi Silicon |
| Zhejiang Kaihua Huantong Silicon Industry |
| Hoshine Silicon Industry |
| Others |
Supply Flow & Price Mechanics
Single-source quartz dependency in Brazil's Minas Gerais and North Carolina's Spruce Pine determines both the premium spread for high-purity metallurgical silicon and the maritime-heavy supply chain structure that Asian smelters navigate. This geological concentration forces alloy producers to absorb freight volatility and certificate-of-origin premiums that separate hydropower-verified supply from coal-tainted alternatives.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure by mandating fluorinated gas management compliance that coal-powered Chinese smelters cannot easily satisfy. Three-tier pricing structure across premium, standard, and economy levels separates Norwegian hydropower-certified silicon from standard Yunnan grid-tied output and economy-grade coal furnace material. Cost compression in the economy tier is intensifying because MEE dual carbon enforcement shutters Henan capacity and redirects quotas to southwestern provinces. Tier-1 automotive aluminum producers in Michigan and Bavaria exhibit lowest price sensitivity, while secondary scrap-based smelters in Ohio and Ontario face acute margin pressure.
Supply Chain Analysis
High-purity quartz deposits anchor upstream feedstock security, drawing from Brazilian crystalline silica mines and Appalachian pegmatite formations. Smelter capacity concentrates in China's Yunnan and Xinjiang provinces, Norway's Rjukan and Salten clusters, and Spain's Asturias region. Supply chain risk centers on maritime chokepoint exposure through South Atlantic and Pacific routes that connect Brazilian feedstock to Asian furnace operations. Distribution runs through direct technical service contracts for tier-1 automotive alloy producers and regional metal service centers for smaller foundry customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metallurgical silicon market sits in early cyclical recovery as automotive lightweighting mandates force aluminum alloy procurement ahead of traditional contract cycles.
For Market Incumbents: Insulate margin position through captive quartz mining assets and automated electrode baking retrofits that compress thermal inefficiency against Chinese scale. Secure MEE renewable energy certificate documentation to maintain operating licenses in Yunnan and Sichuan. Defend against Elkem and Ferroglobe's carbon-verified positioning by accelerating coal-to-hydropower furnace conversions before EU CBAM phase-in deepens. For New Entrants and Emerging Players: Pursue secondary aluminum integration opportunities in Ohio and Ontario where scrap-based smelters seek captive silicon blending capabilities to bypass merchant volatility. Target magnesium ferrosilicon inoculation for wind turbine castings in Denmark and Scotland, a segment less exposed to automotive cycle swings. Lead with alloy formulation laboratory services rather than commodity silicon metal to capture technical advisory margins. For Investors and Strategic Acquirers: The market sits at a supply-constrained phase that favors integrated quartz-to-smelter operators with documented low-carbon credentials. Long-term viability across the projection horizon hinges on electricity sourcing advantages and backward integration into high-purity quartz deposits. Watch for EU carbon border adjustment enforcement intensity as the inflection signal separating premium-tier from stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| Coal-to-Hydropower Furnace Conversion | MEE dual carbon enforcement redirects operating quotas to Yunnan and Sichuan provinces with preferential grid tariffs. |
| Captive Quartz Mining Integration | Brazilian Minas Gerais deposits and Spruce Pine formations reduce single-source geological risk for smelter feedstock security. |
| Automotive Alloy Formulation Services | Michigan and Bavaria OEMs now specify custom ferrosilicon blends with guaranteed inoculation performance rather than commodity purchases. |
| EU Carbon Border Adjustment Compliance | Norwegian and Icelandic smelters capture tariff exemptions through verified renewable energy certificates for automotive supply chains. |
| Continuous Electrode Baking Retrofit | Elkem and Ferroglobe compress energy intensity gaps against Chinese competition through automated paste plant installations. |
Methodological Framework
Cross-validation between primary interviews with submerged-arc furnace operators, aluminum alloy procurement directors, and quartz mining executives anchors the qualitative findings against secondary trade data and MEE regulatory filings. Smelter plant managers, European steelmaker technical directors, and automotive tier-1 supplier metallurgists provided operational perspective. Customs records, SEC 10-K disclosures from listed producers, and EU ETS carbon registry data supplied quantitative grounding. Bottom-up capacity modeling and top-down demand segmentation were reconciled through iterative triangulation.
Calibration against historical furnace output data and electricity tariff trajectories shaped the projection framework across the analysis window. Segmentation dimensions include purity grade tier, end-use application, energy sourcing profile, and regional production cluster. CAGRs were derived from elasticity modeling against aluminum alloy demand intensity and solar polysilicon absorption rates. Forecast inputs incorporated automotive emissions standard stringency indices and Chinese provincial grid tariff reform schedules.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity pricing, maritime freight indices, or EU CBAM enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about furnace technology diffusion and regulatory compliance timelines. Cross-checking against IEA industrial power price benchmarks and LME aluminum alloy contract volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Nickel Oxide Target Market
Metals
Titanium Powder Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
Aluminium Powder Market
Metals
North America Metal Casting Market
Metals
Seamless Stainless Steel Products Market
Metals
Cold Drawn Wire Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Liquid Metal Thermal Pad Market
Metals
North America Aluminum Casting Market
Metals
Copper Wire Market
Metals
Silver Nitrate Market
Metals
Saudi Arabia Aluminum Market
Metals
Nickel Powder Plating Market
Metals
Global Tantalum Market
Metals
Copper and Copper Alloy Market