
 Ceramic Filters Market | 2026-2036
Ceramic Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Filters Market Intelligence
Direct procurement between ceramic filter manufacturers and municipal water authorities is rewriting traditional distributor relationships in the water treatment sector. Pall Corporation leverages its vertically integrated membrane production to sustain long-term supply contracts with large-scale utilities. 3M Company competes through specialized depth filtration media for industrial pre-treatment applications. Corning anchors its position in gas purification through high-temperature ceramic honeycomb substrates for automotive and stationary emissions control.
Ceramic filters are rigid, inorganic porous structures manufactured from alumina, zirconia, silicon carbide, or cordierite, typically featuring pore sizes from 0.1 to 100 microns and operating temperatures exceeding 1000°C for thermal gas separation. Sintering and sol-gel processes dominate high-performance membrane production, while extrusion remains the workhorse for large-format water and exhaust filtration elements. Porous ceramic filters lead in installed volume across water treatment, though membrane variants command premium pricing in pharmaceutical sterile filtration where absolute retention ratings are mandatory. Phase-inversion ceramics are gaining traction in chemical processing for aggressive solvent environments where polymer membranes degrade.
EPA drinking water standards and the EU Drinking Water Directive are tightening turbidity and pathogen removal requirements, directly expanding demand for certified ceramic barrier systems in municipal infrastructure. REACH and RoHS frameworks in Europe restrict certain raw material additives, pushing manufacturers toward cleaner alumina and titania formulations. China's GB standards and Ministry of Ecology and Environment discharge rules are accelerating ceramic membrane adoption in industrial wastewater reuse. Stakeholders must track evolving certification requirements across multiple jurisdictions while positioning manufacturing capacity to serve regional specification divergence.
Market Dynamics
Municipal water authorities in emerging economies are bypassing conventional distributor networks to contract directly with ceramic membrane manufacturers, compressing channel margins while locking in decade-long supply agreements.
Growth Catalysts
- EPA and EU Drinking Water Directive:Stricter turbidity and pathogen removal mandates are forcing utilities to upgrade from sand filtration to certified ceramic barrier systems.
- China's wastewater infrastructure:Ministry of Ecology and Environment discharge rules are accelerating ceramic membrane adoption in industrial reuse applications.
- Phase-inversion ceramics:Chemical processors are deploying these for aggressive solvent environments where polymer membranes degrade rapidly.
Market Restraints
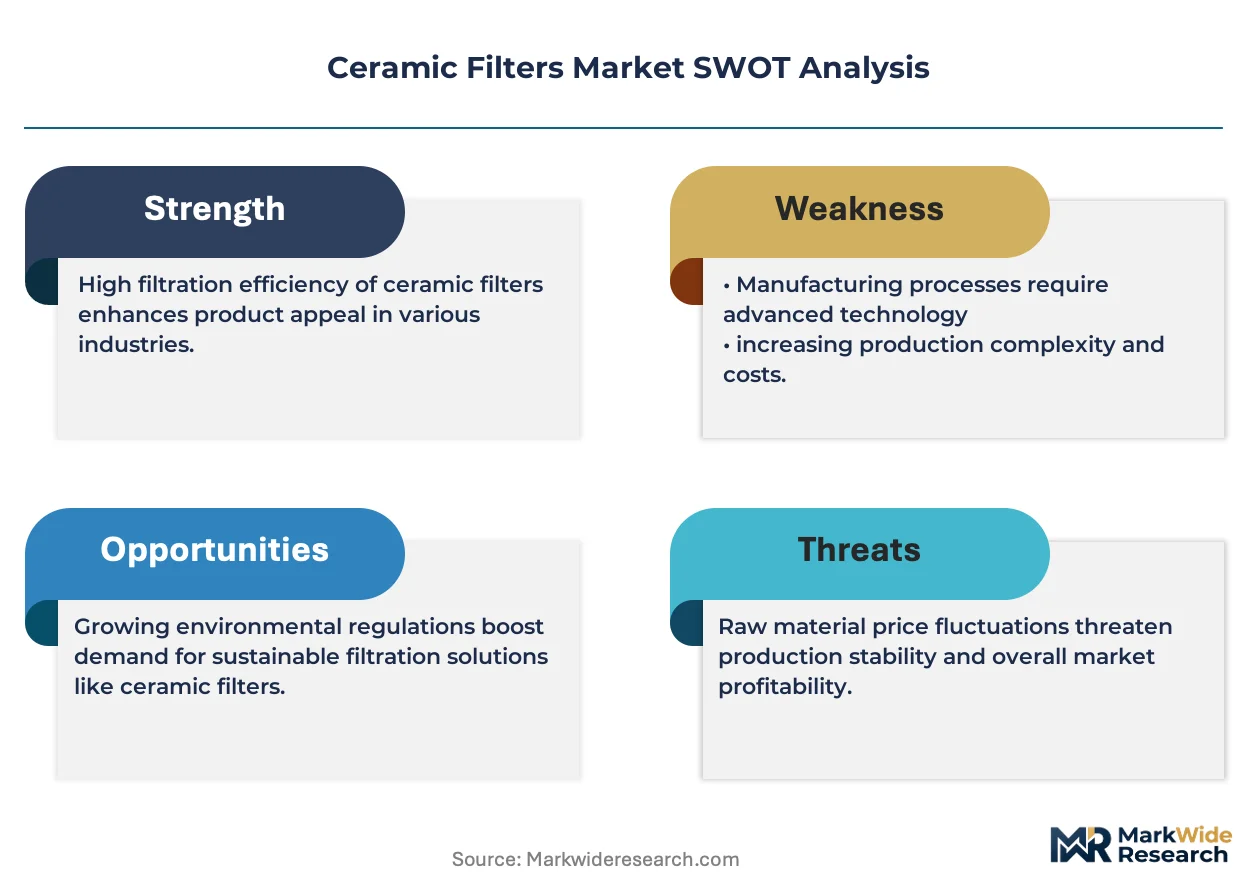
- High-purity alumina supply:Concentration of specialty alumina feedstock in select mining jurisdictions creates input cost volatility and security-of-supply risk.
- Sintering energy intensity:Kiln operations for high-performance membranes face carbon cost exposure under EU carbon border adjustment mechanisms.
- Polymer hollow-fiber substitution:Biopharmaceutical sterile filtration retains share in low-temperature applications where absolute retention ratings are not mandatory.
Strategic Opportunities
- India's industrial water reuse:Central Pollution Control Board mandates on zero-liquid-discharge are opening membrane bioreactor installations for textile and tannery clusters.
- Automotive emissions control:Corning's high-temperature honeycomb substrates are extending into stationary power generation and marine applications.
- Direct manufacturer-utility contracting:Long-term service agreements bundling membrane replacement and performance monitoring are replacing spot procurement.
Industry Challenges
- Membrane certification timelines:NSF/ANSI 61 and EU hygiene approvals for drinking water contact require 18-24 month validation cycles that delay revenue recognition.
- Cross-border technical standards:Divergent pore-size classification systems between ASTM and ISO create specification friction for multinational equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Filters Market |
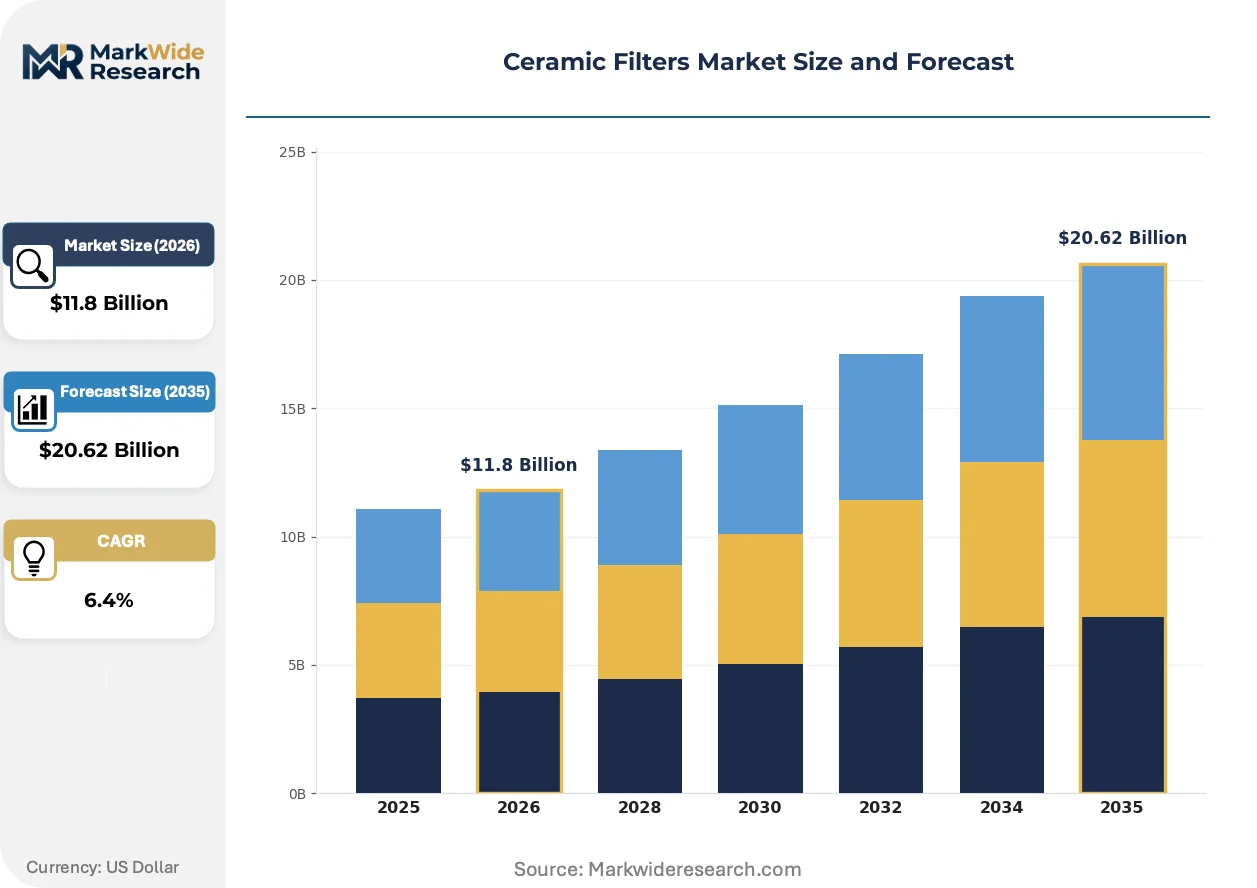
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porous, Membrane, Depth, Phase-Inversion Technology: Sintering, Tape Casting, Injection Molding, Extrusion, Sol-Gel Application: Water Treatment, Gas Purification, Chemical Processing, Pharmaceuticals End User: Manufacturing Plants, Research Laboratories, Power Stations, Food & Beverage Units |
| Companies Covered | Pall Corporation, 3M Company, Haldor Topsoe A/S, Doulton Ceramics, Unifrax I LLC, Veolia, Aquacera, Corning, CeramTec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Filters Market Strategic Shifts & Innovations
Manufacturing process innovation and procurement model disruption are converging to redefine competitive advantage in ceramic filtration, with material science breakthroughs enabling performance tiers previously unattainable.
Sol-gel derived ceramic membranes are migrating from laboratory-scale pharmaceutical sterile filtration into bulk municipal water treatment, where Singapore's PUB and California's Orange County Water District are piloting units for direct potable reuse. Equipment suppliers are compressing lead times from 26 weeks to 14 weeks by standardizing module geometries across utility specifications.
REACH and RoHS frameworks are restricting certain raw material additives in European manufacturing, pushing formulators toward cleaner titania and high-purity alumina chemistries. Ceramic membrane producers are relocating finishing operations to serve regional specification divergence without cross-border compliance burden.
Performance-based contracting is displacing capital purchase models in large-scale utility procurement, with membrane suppliers assuming operational risk for flux maintenance and fouling recovery. China's state-owned water groups are pioneering 15-year service agreements in Yangtze River Delta municipalities, transferring technical accountability from plant operators to original equipment providers.
Ceramic Filters Market Segmentation
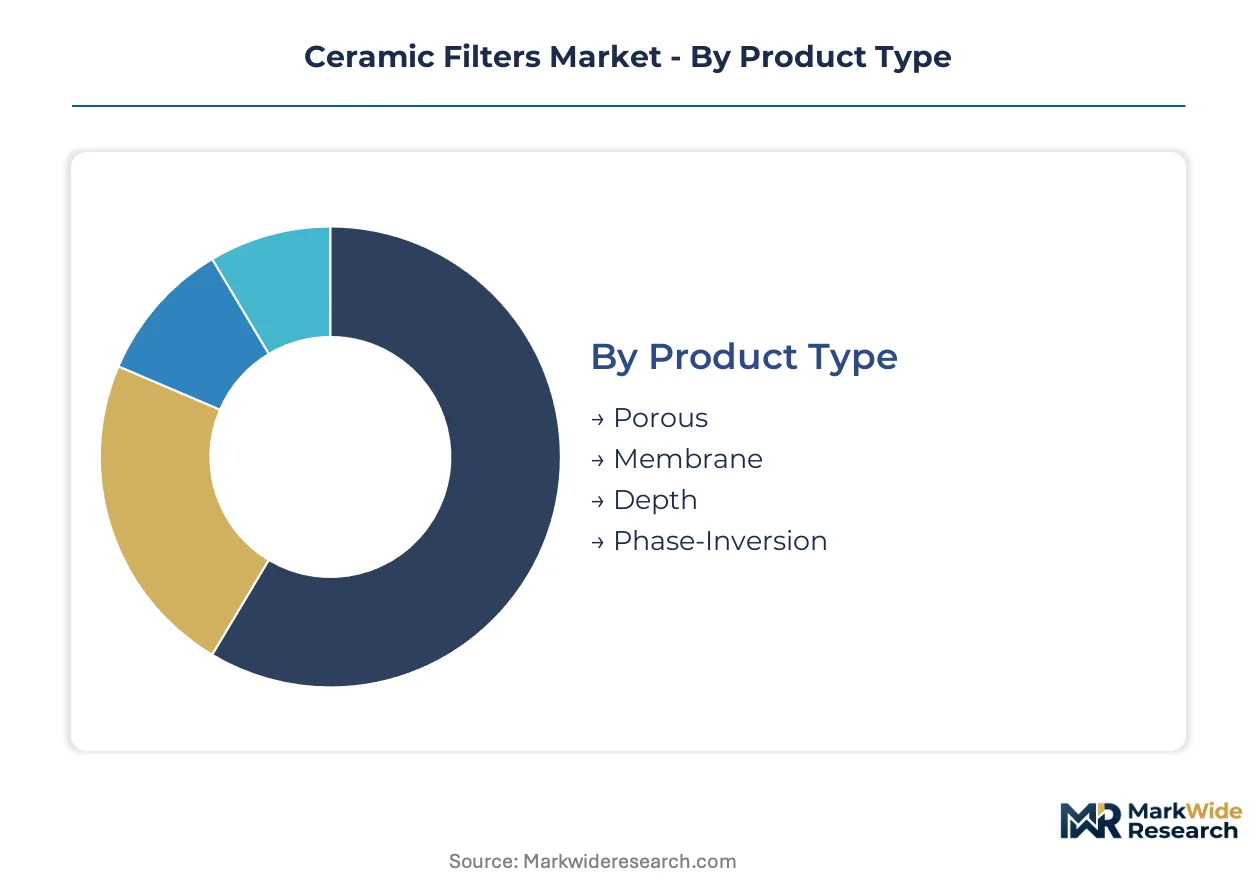
Ceramic filter architectures diverge sharply across thermal tolerance, pore precision, and mechanical rigidity requirements. Procurement patterns in this market track directly to these technical boundaries, with municipal utilities, pharmaceutical sterile suites, and emissions control OEMs each demanding distinct performance tiers.
Product Type:
Porous ceramics dominate installed base across exhaust aftertreatment and bulk water clarification, while membrane variants command specification-critical applications.
- Porous:Rigid structures with interconnected pore networks from 0.1 to 100 microns, manufactured via extrusion or pressing of alumina, cordierite, or silicon carbide. Demand concentrates in automotive catalytic converters and stationary emissions control, where Corning's honeycomb substrates face tightening EPA and EU F-Gas Regulation thermal efficiency mandates.
- Membrane:Thin selective layers on porous supports achieving absolute retention ratings below 0.1 microns. Singapore's PUB and California's Orange County Water District are piloting these for direct potable reuse, driven by EPA turbidity standards and EU Drinking Water Directive pathogen limits.
- Depth:3M Company specializes in graded-density structures for industrial pre-treatment, capturing suspended solids across variable feedwater quality.
- Phase-Inversion:Emerging chemistry for aggressive solvent environments where polymer membranes degrade, gaining traction in chemical processing clusters.
Established volume favors Porous; emerging adoption favors Membrane.
Technology:
Process selection determines cost structure, lead time, and performance ceiling, with thermal methods anchoring high-temperature segments and chemical routes penetrating precision barriers.
- Sintering:High-temperature kiln consolidation of ceramic powders for structural integrity exceeding 1000°C. Dominates automotive honeycomb and industrial gas filtration, though EU carbon border adjustments threaten energy-intensive operations.
- Tape Casting:Thin-sheet formation for planar membrane supports, enabling Pall Corporation's vertically integrated production of multi-layer water treatment modules.
- Injection Molding:Complex geometries for specialized fittings and housings, serving research laboratory and pharmaceutical OEM integration requirements.
- Extrusion:Continuous forming of large-format elements, standardizing module geometries that compress utility lead times from 26 weeks to 14 weeks.
- Sol-Gel:Colloidal deposition creating nanoscale selective layers, migrating from pharmaceutical sterile filtration into bulk municipal pilots.
Cost concentration sits with Sintering; margin expansion favors Sol-Gel.
Application:
End-use thermal and purity requirements partition the market into four distinct procurement ecosystems with divergent certification cycles.
- Water Treatment:Municipal and industrial reuse systems, where China's Ministry of Ecology and Environment discharge rules and India's Central Pollution Control Board zero-liquid-discharge mandates accelerate ceramic membrane adoption.
- Gas Purification:Automotive, marine, and stationary power emissions control, governed by EPA standards and EU F-Gas Regulation thermal efficiency requirements.
- Chemical Processing:Aggressive solvent and high-temperature separations, where REACH and RoHS frameworks push formulators toward cleaner titania chemistries.
- Pharmaceuticals:Sterile filtration requiring absolute retention ratings, with NSF/ANSI 61 and EU hygiene approvals demanding 18-24 month validation cycles.
Volume leadership belongs to Water Treatment; steepest expansion trajectory runs through Pharmaceuticals.
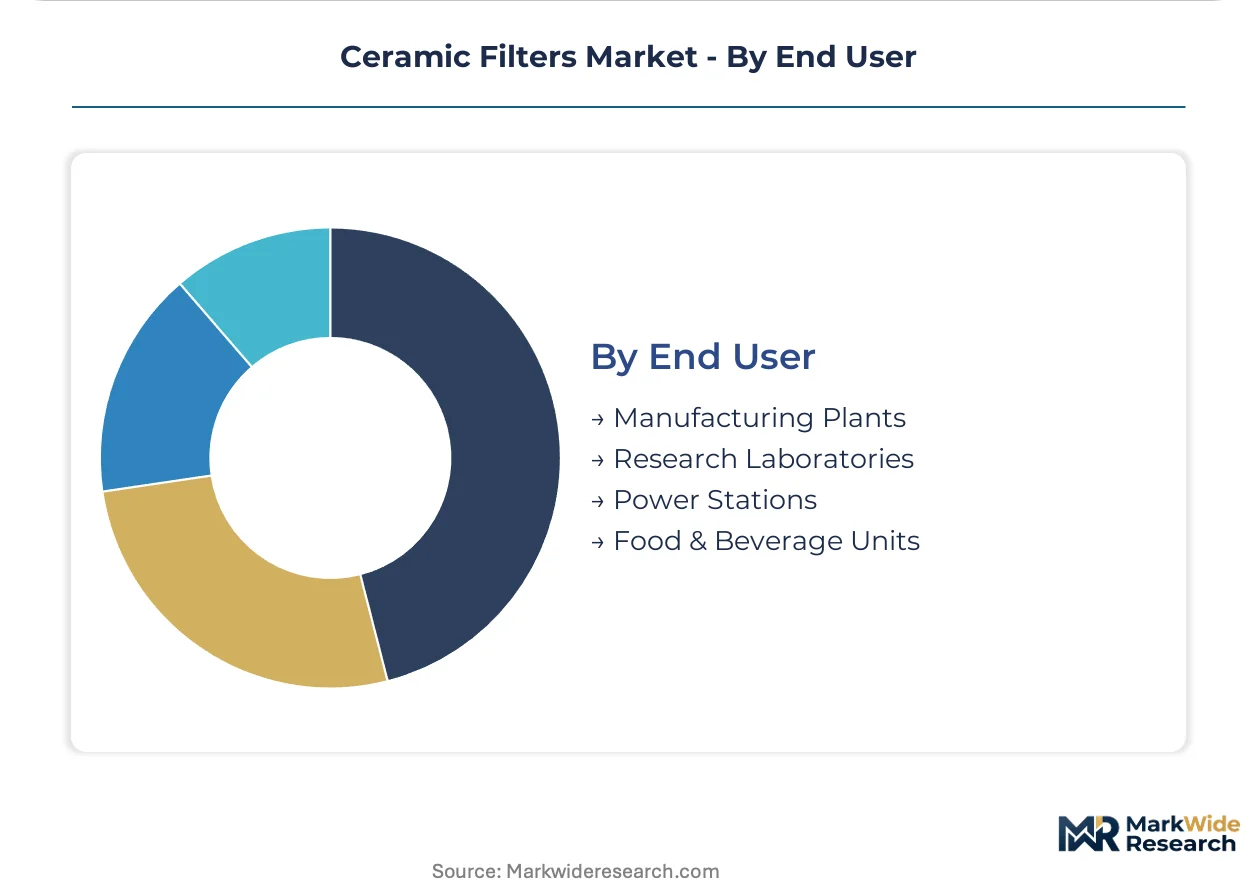
End User:
Customer scale and technical sophistication determine contracting structure, from decade-long utility service agreements to spot procurement for research applications.
- Manufacturing Plants:Industrial water reuse and process filtration, where China's state-owned water groups pioneer 15-year performance-based contracts transferring operational risk to membrane suppliers.
- Research Laboratories:Small-batch, high-specification procurement with extended qualification timelines and premium pricing tolerance.
- Power Stations:Cooling water and flue gas treatment, subject to FERC environmental compliance and regional emissions trading schemes.
- Food & Beverage Units:FDA and FSSAI-regulated contact applications requiring certified barrier systems for pathogen and particulate control.
Contract duration peaks with Manufacturing Plants; price elasticity favors Research Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA turbidity mandates and China's Ministry of Ecology and Environment discharge rules are redirecting procurement toward certified ceramic barrier systems across four major national markets.
China
Municipal wastewater treatment capacity is expanding rapidly in the Yangtze River Delta. GB standards and MEE discharge rules are accelerating ceramic membrane adoption for industrial reuse. State-owned water groups in Shanghai and Jiangsu province are pioneering 15-year performance-based service agreements with membrane suppliers.
United States
California's Orange County Water District pilots sol-gel derived ceramic membranes for direct potable reuse. EPA drinking water standards are tightening pathogen removal requirements, forcing utilities to upgrade from sand filtration. Singapore's PUB collaboration models are influencing procurement structures in Arizona and Texas water authorities.
Germany
REACH and RoHS frameworks are restricting raw material additives, pushing manufacturers toward cleaner alumina and titania formulations. The EU Drinking Water Directive's turbidity mandates are expanding demand for certified ceramic barrier systems in municipal infrastructure. Industrial clusters in North Rhine-Westphalia are deploying phase-inversion ceramics for aggressive solvent environments.
India
Central Pollution Control Board zero-liquid-discharge mandates are opening membrane bioreactor installations for textile and tannery clusters. Ceramic membrane adoption is concentrating in Gujarat and Tamil Nadu industrial zones. Performance-based contracting is displacing capital purchase models in large-scale utility procurement.
Singapore
PUB's direct potable reuse pilots are validating sol-gel ceramic membranes for municipal-scale deployment. The national water agency's technical specifications are becoming reference standards for Southeast Asian utilities. Advanced manufacturing capabilities support regional membrane module finishing operations.
Ceramic Filters Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated membrane producers and specialized materials fabricators. Three strategic archetypes dominate: diversified filtration conglomerates with captive ceramic production, dedicated membrane technology specialists, and industrial ceramics manufacturers extending into filtration applications. Competitive moves center on backward integration into high-purity alumina feedstock and long-term service contracting with municipal utilities.
Among diversified technology conglomerates, 3M Company and Corning exemplify scale-driven positions spanning multiple filtration end-uses. Pall Corporation and CeramTec GmbH occupy specialist tiers focused on precision membrane and technical ceramic applications respectively. Veolia represents the service-integrated archetype, bundling membrane supply with operational accountability under performance-based contracts. These four anchors illustrate the market's bifurcation between materials science depth and utility service breadth.
| Leading Market Players |
|---|
| Pall Corporation |
| 3M Company |
| Haldor Topsoe A/S |
| Doulton Ceramics |
| Unifrax I LLC |
| Veolia |
| Aquacera |
| Corning |
| CeramTec GmbH |
| Others |
Cost & Logistics Intelligence
Yangtze River Delta port congestion and trans-Pacific container rates are compressing margins for ceramic membrane importers while amplifying price spreads between certified NSF/ANSI 61 systems and uncertified alternatives. Supply concentration in high-purity alumina feedstock and kiln-intensive sintering operations creates asymmetric pricing power that favors producers with captive raw material access.
Pricing Analysis
Certification level (NSF/ANSI 61 versus EU hygiene-grade) creates the primary spread between premium membrane modules and standard porous elements. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade differentiation and after-sales service bundling. Cost compression in economy-tier extruded elements is intensifying because of polymer hollow-fiber substitution in low-temperature applications. Municipal water authorities exhibit lowest price sensitivity due to performance-based contracting structures, while research laboratories face highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for ceramic membrane distributors. Geographic supply concentration centers on China for alumina feedstock and membrane module finishing, Germany for precision tape-casting equipment, and Japan for high-purity zirconia. Raw material dependencies draw from specialty alumina, silicon carbide powders, and titania formulations. Single-source vulnerability in high-purity alumina mining jurisdictions threatens input security. Distribution runs through direct manufacturer-utility contracting that bypasses traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ceramic filters market is entering a cyclical recovery phase driven by EPA and EU Drinking Water Directive upgrade cycles forcing municipal infrastructure replacement. Capital deployment timing should align with certification backlog clearance and utility procurement reactivation.
For Market Incumbents: Insulate membrane replacement revenue streams by locking 15-year performance-based service agreements with state-owned water groups before competitors establish operational accountability frameworks. Secure captive supply of high-purity alumina through backward integration or long-term offtake contracts to defend against feedstock cost volatility. Invest in sol-gel nanoscale selective layer R&D to maintain premium positioning as chemical processors adopt phase-inversion ceramics for aggressive solvent applications.
For New Entrants and Emerging Players: India's Central Pollution Control Board zero-liquid-discharge mandates for textile and tannery clusters represent the most penetrable entry point for membrane bioreactor specialists lacking utility-scale track records. Chemical processing phase-inversion applications offer second-mover advantage where polymer membrane degradation creates substitution windows. Partner with regional equipment fabricators to compress module geometry standardization timelines and bypass 18-24 month NSF/ANSI 61 certification cycles.
For Investors and Strategic Acquirers: Sol-gel ceramic membrane specialists with municipal pilot validation represent the highest-conviction acquisition archetype for exposure to direct potable reuse expansion. Long-term viability across the analysis window hinges on positioning for drinking water contact certification rather than industrial pre-treatment commoditization. Monitor EPA turbidity mandate enforcement intensity and China's MEE discharge rule implementation pace as inflection indicators for procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Alumina | Secures feedstock supply against mining jurisdiction concentration and carbon border adjustment exposure. |
| Performance-Based Service Contracting | Transfers operational risk from municipal utilities to membrane suppliers under 15-year agreements. |
| Sol-Gel Nanoscale Layer Migration | Enables absolute retention ratings for pharmaceutical sterile filtration and direct potable reuse pilots. |
| Regional Finishing Operation Relocation | Positions manufacturing to serve REACH and RoHS specification divergence without cross-border compliance burden. |
| Phase-Inversion Chemistry Development | Captures chemical processing demand in aggressive solvent environments where polymer membranes degrade. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with membrane technology directors, municipal procurement officers at water authorities, ceramic materials R&D leads, and industrial plant engineers; alongside secondary validation through EPA enforcement databases, EU Drinking Water Directive implementation reports, China MEE discharge compliance records, and SEC filings of diversified filtration conglomerates. Bottom-up triangulation across utility procurement pipelines and top-down reconciliation against alumina feedstock trade flows anchored volume estimates.
Forecast inputs considered membrane architecture type, application thermal requirements, end-user contracting structure, and regional regulatory enforcement intensity across the modeling period. CAGRs were derived from segmented demand build-ups weighted by certification cycle timelines and utility capital expenditure patterns. Industry-specific inputs included kiln energy cost trajectories under EU carbon border mechanisms and polymer membrane substitution elasticity in biopharmaceutical sterile filtration.
Practitioners should monitor EPA turbidity standard revision timing, China MEE discharge rule enforcement consistency, and high-purity alumina mining jurisdiction policy shifts for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Filter Media Market
Filters
Global Laboratory Filtration Market
Filters
Hydraulic Filters Market
Filters
Respirator Cartridges and Filters Market
Filters
Filtering Centrifuges Market
Filters
Industrial Filtration Market
Filters
ePTFE Filter Film Market
Filters
Global Industrial Filters Market
Filters
High Purity Chemical Filters Market
Filters
Aerospace Filter Market
Filters
Chloramine Filter Market
Filters
Industrial Filter Paper Market
Filters
Global Baghouse Filters Market
Filters
Anti-Microbial Filter Market
Filters
Global High Temperature Filters Market
Filters
Sintered Metal Filters Market