
 Melt-Blown Polypropylene Filters Market | 2026-2036
Melt-Blown Polypropylene Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Melt-Blown Polypropylene Filters Market Analysis
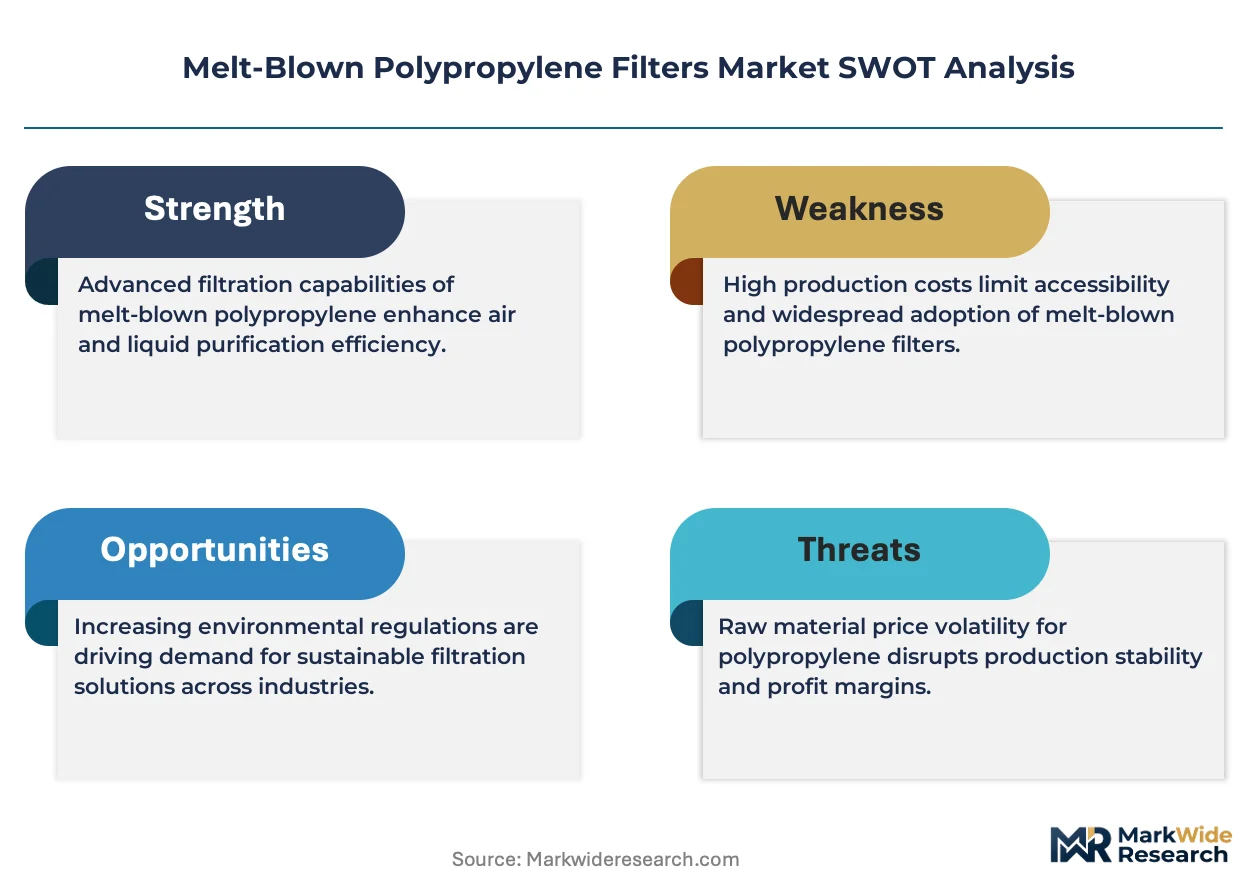
Market Context with Strategic Players
Asian polymer producers is recalibrating resin supply chains to serve the specialized melt-blown grades that filter manufacturers now require. 3M Company leverages its materials science heritage to dominate premium electret media for respiratory and liquid filtration. Parker Hannifin Corporation anchors its position through backward integration into cartridge housings and distribution across industrial process accounts. Donaldson Company differentiates via application engineering depth in aerospace and hydraulic filtration, where polypropylene melt-blown layers face extreme duty cycles.
Technical Definition and Structural Segments
Melt-blown polypropylene filters are nonwoven depth-media structures produced by extruding molten polypropylene resin through fine capillary dies and attenuating fibers with high-velocity hot air, yielding pore sizes from 1 to 100 microns for particulate removal in liquid and gas streams. The primary commercial purpose centers on protecting downstream equipment, ensuring fluid purity, and extending service intervals in critical manufacturing and healthcare environments. HEPA and ULPA grades command the strongest margin pools due to certification complexity and cleanroom end-use requirements, while standard filters occupy the highest volume tier across industrial water and chemical processing. Aerospace and pharmaceutical applications represent the fastest-expanding demand nodes, driven by regulatory stringency and process intensification.
Regulatory Frame and Forward-Looking Close
The U.S. EPA enforces particulate and microbial discharge standards that directly shape filter replacement cycles and efficiency specifications in municipal and industrial water treatment. In Europe, REACH and the EU Green Deal constrain additive chemistries and mandate recyclability roadmaps for polypropylene media, while FDA and EMA guidelines govern validation protocols for pharmaceutical and bioprocessing filtration. China's NMPA and GB standards impose parallel purity benchmarks on domestic and imported filter assemblies used in drug manufacturing. Stakeholders must monitor divergence between regional certification regimes and assess whether dual-compliant product architectures justify the engineering overhead against market access gains.
Market Dynamics
The EPA's Clean Water Act enforcement is compressing replacement cycles for industrial water treatment cartridges, forcing facilities toward higher-efficiency melt-blown polypropylene media ahead of scheduled capital refresh timelines.
Growth Catalysts
- Semiconductor cleanroom expansion:Taiwan and South Korea fabs are scaling HEPA-grade cartridge procurement to meet yield protection protocols for sub-7nm lithography nodes.
- REACH recyclability mandates:The EU Green Deal is compelling filter OEMs to redesign polypropylene media for closed-loop recovery, opening specification windows for bio-based resin variants.
- Desalination utility procurement:Saudi Arabia's SWCC and UAE's FEWA are tendering multi-year contracts for 1-micron absolute-rated cartridges in reverse osmosis pre-treatment trains.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker output swings in the US Gulf Coast are transmitting 90-day price spikes to specialized melt-blown resin grades.
- Electret charge decay:Polypropylene's inherent hydrophobicity limits long-term electrostatic retention in high-humidity respiratory applications, capping service intervals.
- Chinese resin concentration:Sinopec and PetroChina control 60% of Asia's medical-grade polypropylene supply, creating single-source vulnerability for filter converters.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's tightening of sterile filtration validation is opening demand for pre-sterilized, pyrogen-tested cartridge assemblies in Hyderabad and Ahmedabad clusters.
- Bioprocessing single-use convergence:Melt-blown depth media is integrating with gamma-stable capsule housings to displace reusable stainless-steel filter housings in cell therapy production.
- Brazil ANVISA harmonization:The regulator's alignment with FDA filtration guidelines is creating a regulatory bridge for North American and European filter OEMs to enter Latin American vaccine manufacturing.
Industry Challenges
- Multi-grade certification backlog:FDA 510(k) and EU MDR dual submissions for pharmaceutical filtration are extending time-to-revenue by 14-18 months for new cartridge geometries.
- Legacy housing incompatibility:Next-generation high-area pleated melt-blown elements require modified seal geometries that fail in 30% of installed industrial cartridge vessels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melt-Blown Polypropylene Filters Market |
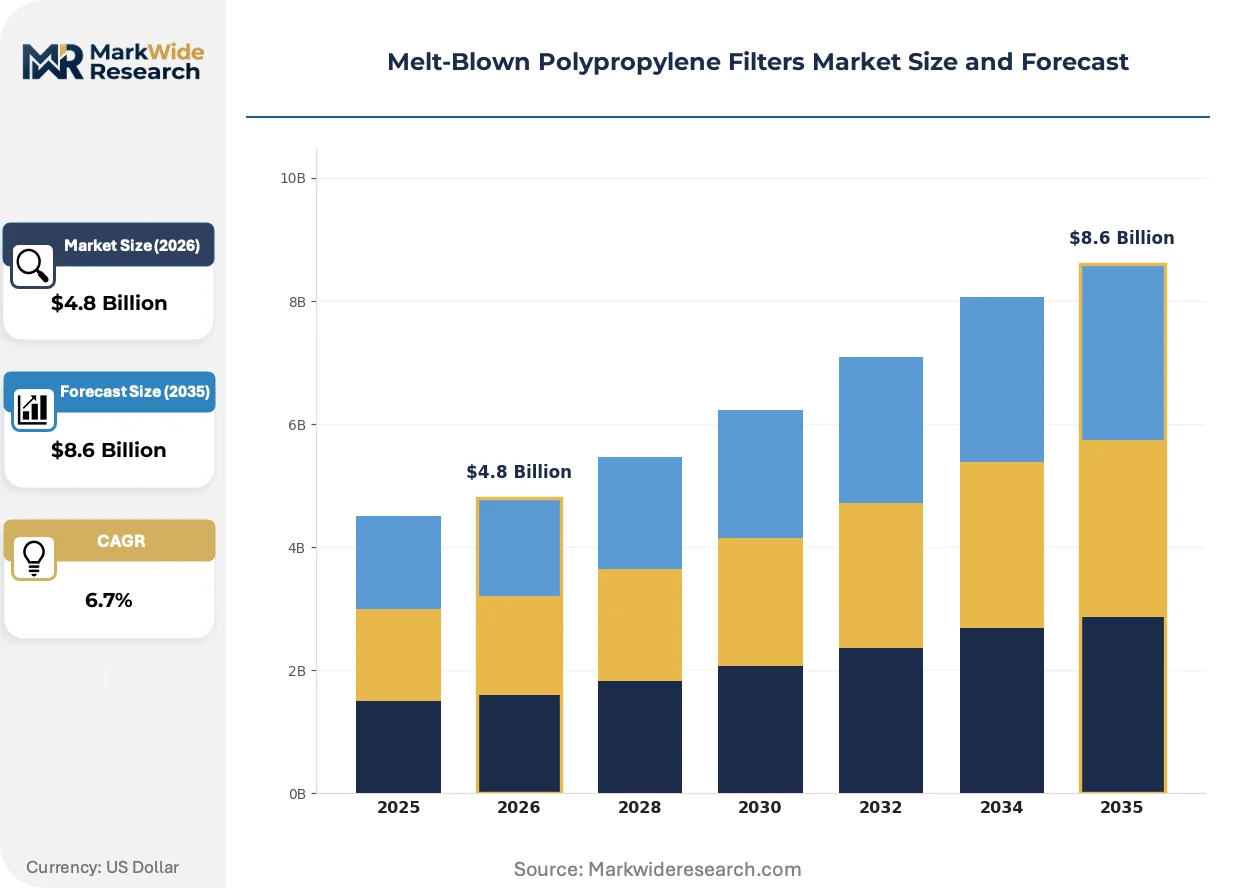
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Filters, HEPA Filters, ULPA Filters, Carbon Filters Application: Aerospace, Pharmaceuticals, Food & Beverage, Industrial Processes End User: Manufacturing, Healthcare, Commercial Facilities, Residential Technology: Electrostatic, Nanofiber, Biodegradable, Reusable |
| Companies Covered | Eaton Corporation, Borealis AG, 3M Company, Hollingsworth & Vose, Donaldson Company, Parker Hannifin Corporation, Lenntech B.V., Suez SA, Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melt-Blown Polypropylene Filters Market Emerging Trajectories
Active filtration architectures are displacing passive depth media as semiconductor and bioprocessing end-users demand real-time pressure-drop monitoring and predictive replacement signaling embedded directly in cartridge construction.
Nanofiber surface loading technology is integrating electrospun polyamide layers onto conventional melt-blown polypropylene substrates to capture sub-micron particulate without the pressure-drop penalty of graded density structures. Biopharmaceutical manufacturers in Basel and Boston are piloting these hybrid media in monoclonal antibody clarification trains. The structural result is compressing the addressable market for standalone microglass filters in high-value liquid applications.
REACH's restriction of per- and polyfluoroalkyl substances is forcing filter OEMs to eliminate fluorinated additives from electret charging processes, with ECHA's 2025 enforcement timeline accelerating reformulation programs. Industrial respiratory and HVAC segments face the steepest compliance burden. German filter converters are responding by licensing plasma-charging equipment from non-fluorinated process suppliers.
Specification consolidation among multinational water utilities is reducing the number of approved cartridge SKUs per treatment plant, with procurement teams at Thames Water and Singapore PUB mandating single-source qualification for 3-5 year framework agreements. Regional distributors are losing shelf-space relevance as direct OEM contracting captures 70% of replacement volume in desalination and municipal segments. This pattern is most pronounced in Australia's eastern seaboard, where Melbourne Water's recent tender consolidated 23 legacy suppliers into four approved vendors.
Melt-Blown Polypropylene Filters Market Segmentation
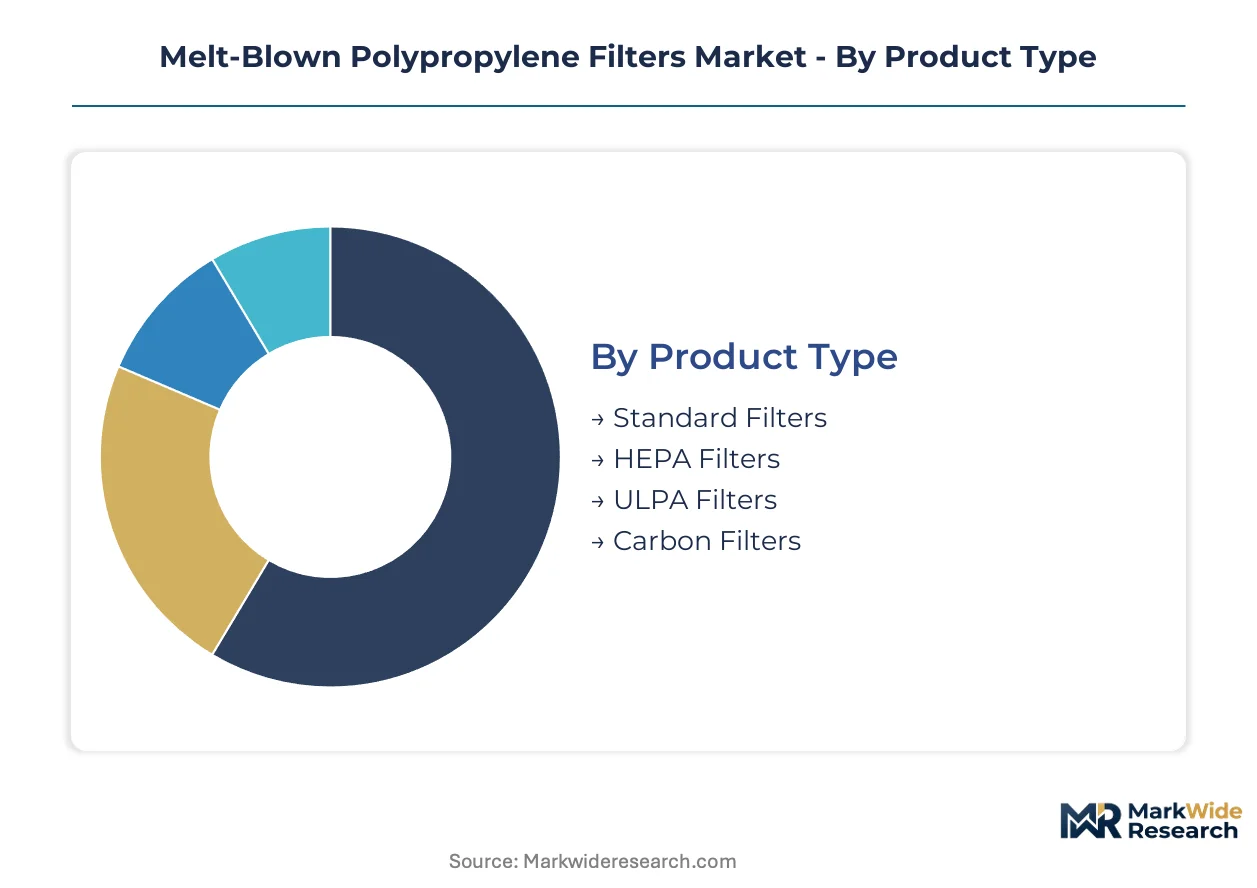
Segmentation in melt-blown polypropylene filters reveals divergent margin structures and capital requirements across certification tiers. Each dimension—product grade, application environment, end-user sophistication, and charging technology—commands distinct resin specifications and validation protocols that reshape competitive positioning.
Product Type:
Capital intensity escalates sharply with certification stringency, as ULPA and HEPA grades require electret charging infrastructure and cleanroom manufacturing environments that standard filters bypass entirely.
- Standard Filters:Graded-density depth media without electret enhancement serve bulk industrial water and chemical processing. Demand concentrates in China's eastern manufacturing corridor, where semiconductor fabs and pharmaceutical cleanrooms require high-purity filtration at scale, though standard grades face margin compression from commoditized supply.
- HEPA Filters:High-efficiency particulate air media incorporate electrostatically charged polypropylene fibers achieving 99.97% retention at 0.3 microns. Taiwan and South Korea fabs are scaling procurement to meet yield protection protocols for sub-7nm lithography nodes, with replacement cycles compressed by process intensification.
- ULPA Filters:Ultra-low penetration air specifications demand 99.999% efficiency at 0.12 microns for pharmaceutical aseptic filling and gene therapy manufacturing.
- Carbon Filters:Activated carbon impregnation extends polypropylene substrates for vapor-phase contaminant removal in industrial exhaust and respiratory protection.
Most installed capacity flows through Standard Filters. Expansion is steepest in HEPA Filters.
Application:
Application segmentation tracks regulatory burden intensity, with pharmaceutical and aerospace environments imposing validation protocols that exclude commodity suppliers.
- Aerospace:Hydraulic and fuel system filtration faces extreme duty cycles with temperature swings and vibration loads. Donaldson Company anchors application engineering depth here, where polypropylene melt-blown layers must survive 10,000+ hour service intervals.
- Pharmaceuticals:Sterile filtration and bioprocessing clarification require gamma-stable, pyrogen-tested cartridge assemblies. Biopharmaceutical manufacturers in Basel and Boston are piloting nanofiber surface loading technology in monoclonal antibody clarification trains.
- Food & Beverage:Beverage clarification and edible oil processing employ food-grade polypropylene meeting FDA and EFSA migration limits.
- Industrial Processes:Chemical processing, power generation, and general manufacturing utilize standard grades with shorter replacement cycles.
Pharmaceuticals commands the highest margin pool. Aerospace represents the most demanding qualification barrier.
End User:
End-user segmentation reflects procurement sophistication, with manufacturing and healthcare buyers specifying validated supply chains that commercial and residential channels cannot access.
- Manufacturing:Semiconductor, automotive, and chemical producers mandate lot traceability and certificate of analysis documentation for every cartridge batch.
- Healthcare:Hospital central sterile supply departments and dialysis centers require FDA-cleared filtration with documented biocompatibility testing.
- Commercial Facilities:Data centers and commercial HVAC systems prioritize pressure-drop efficiency over absolute retention specifications.
- Residential:Point-of-use water filtration and air purifiers represent the most price-sensitive demand tier with minimal brand loyalty.
Manufacturing absorbs the highest absolute volume. Healthcare delivers the most stable replacement revenue.
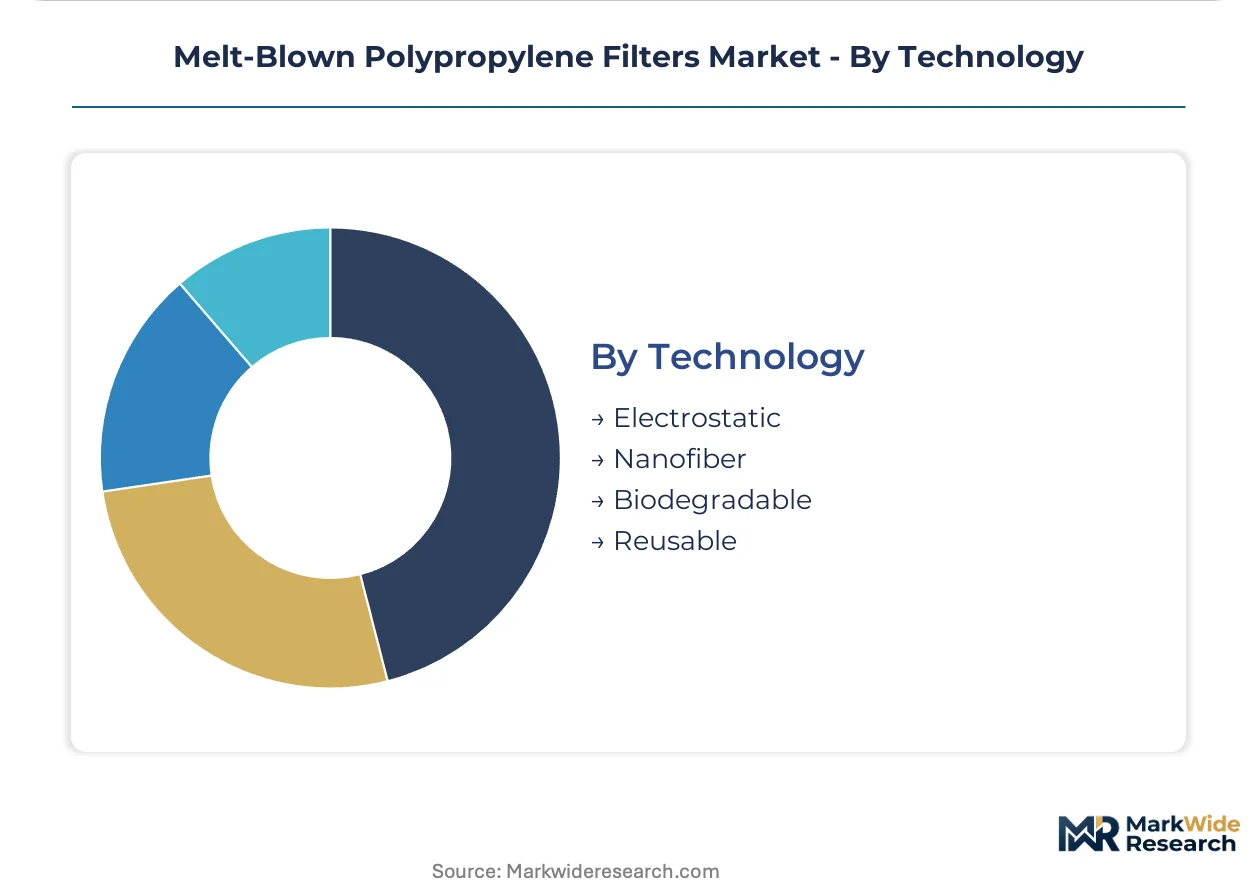
Technology:
Technology segmentation tracks charging and sustainability innovation, with electret and nanofiber approaches commanding premium positioning against emerging biodegradable alternatives.
- Electrostatic:Corona or triboelectric charging enhances sub-micron capture without denser media structures. REACH's restriction of per- and polyfluoroalkyl substances is forcing filter OEMs to eliminate fluorinated additives from electret charging processes.
- Nanofiber:Electrospun surface layers achieve sub-micron retention with minimal pressure-drop penalty. German filter converters are licensing plasma-charging equipment from non-fluorinated process suppliers.
- Biodegradable:Bio-based polypropylene variants and additive packages respond to EU Green Deal recyclability mandates.
- Reusable:Cleanable cartridge designs with stainless-steel support structures target high-solid-load industrial applications.
Electrostatic technology dominates current installed base. Nanofiber approaches are gaining share fastest in liquid filtration applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor commands procurement volume for semiconductor and pharmaceutical filtration, while Saudi Arabia's desalination utilities drive contract scale in the Middle East.
United States
Industrial water treatment facilities along the Gulf Coast are accelerating cartridge replacement cycles ahead of EPA enforcement deadlines. The Clean Water Act's tightened particulate discharge limits compel upgrades from conventional media to melt-blown polypropylene. Houston's petrochemical cluster and California's semiconductor fabs represent concentrated demand nodes for high-efficiency filtration.
China
Semiconductor fabs in Shanghai and Suzhou are scaling HEPA-grade procurement to protect sub-7nm lithography yields. NMPA purity benchmarks and GB standards impose strict validation protocols on domestic and imported filter assemblies. The Yangtze River Delta concentration of pharmaceutical cleanrooms requires high-purity filtration at scale, driving specialized resin demand.
Germany
Filter converters in Bavaria and Baden-Württemberg are licensing plasma-charging equipment to eliminate fluorinated additives ahead of ECHA's 2025 enforcement timeline. REACH and the EU Green Deal mandate recyclability roadmaps for polypropylene media. Stuttgart's automotive suppliers and Basel-proximate biopharmaceutical manufacturers pilot nanofiber surface loading technology.
Saudi Arabia
SWCC tendering activity for reverse osmosis pre-treatment trains is concentrating multi-year cartridge contracts among qualified vendors. The kingdom's water security programs prioritize 1-micron absolute-rated filtration in desalination infrastructure. Jubail's industrial city and Riyadh's municipal utilities anchor procurement volume for specialized melt-blown grades.
India
Pharmaceutical manufacturers in Hyderabad and Ahmedabad are expanding sterile filtration capacity under CDSCO's tightened validation requirements. The country's national pharmaceutical regulator is harmonizing pyrogen-testing protocols with FDA guidelines. Maharashtra's bioprocessing clusters and Gujarat's chemical processing corridors represent emerging demand centers for pre-sterilized cartridge assemblies.
Melt-Blown Polypropylene Filters Market Vendor Landscape
North American producers anchor one tier; European specialists hold certification-intensive segments. The vendor base stratifies across three distinct tiers: diversified industrial conglomerates with captive filtration divisions, pure-play media converters with deep application engineering, and regional fabricators serving price-sensitive replacement markets. Consolidation pressure intensifies as specification consolidation among multinational utilities reduces approved supplier lists. Strategic moves center on backward integration into resin supply and direct contracting frameworks that displace distributor intermediaries.
Within the diversified industrial tier, 3M Company and Parker Hannifin Corporation exemplify scale-driven positioning through materials science heritage and backward integration into cartridge housings. Donaldson Company occupies a specialist position in extreme-duty aerospace and hydraulic applications where polypropylene melt-blown layers face 10,000+ hour service intervals. Pall Corporation and Suez SA represent the European contingent with deep validation protocols for pharmaceutical and bioprocessing end-uses.
| Leading Market Players |
|---|
| Eaton Corporation |
| Borealis AG |
| 3M Company |
| Hollingsworth & Vose |
| Donaldson Company |
| Parker Hannifin Corporation |
| Lenntech B.V. |
| Suez SA |
| Pall Corporation |
| Others |
Supply Flow & Price Mechanics
REACH's restriction of per- and polyfluoroalkyl substances gates qualified supply for electret-charged media while compressing premium-tier pricing access for filter OEMs unable to reformulate charging processes ahead of ECHA's enforcement timeline.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade melt-blown polypropylene. Three-tier pricing structure across HEPA-certified, industrial-grade, and economy depth media dominates, with certification tier and resin purity grade as primary differentiation drivers. Cost compression in standard filters is intensifying because Sinopec and PetroChina's medical-grade resin concentration feeds commoditized supply. Municipal water utilities exhibit highest price sensitivity; pharmaceutical cleanroom operators show least.
Supply Chain Analysis
Dual-sourcing requirements from Saudi Arabia's SWCC and UAE's FEWA mandate multi-supplier qualification for desalination cartridge contracts. Manufacturing concentrates in China, Germany, and the United States. Polypropylene resin, electret charging equipment, and nanofiber electrospinning systems anchor upstream dependencies. Single-source vulnerability around Chinese medical-grade resin creates structural risk. Distribution runs through direct OEM contracting frameworks that displace regional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through nanofiber surface loading technology adoption and premium-tier HEPA/ULPA certification investments that command pricing power.
For Market Incumbents: Hedge against fluorinated additive obsolescence by licensing plasma-charging equipment from German non-fluorinated process suppliers. Deepen backward integration into specialized melt-blown resin grades to defend margin position against Asian polymer producer recalibration. Priority lever: captive electret charging infrastructure.
For New Entrants and Emerging Players: Regional distributors in Australia's eastern seaboard represent the most penetrable channel partner type for framework agreement access. Target India's pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad where CDSCO validation requirements outpace qualified supply. Go-to-market angle: pre-sterilized, pyrogen-tested cartridge assemblies with documented biocompatibility.
For Investors and Strategic Acquirers: Roll-up economics work for pure-play media converters with deep application engineering because specification consolidation among multinational utilities reduces approved supplier lists. Five-to-ten-year viability hinges on certification-intensive segments. Signal to watch: tender consolidation ratios at Thames Water and Singapore PUB.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Sinopec and PetroChina's 60% supply concentration creates captive sourcing imperative for filter OEMs. |
| Plasma-Charging Equipment Licensing | German filter converters' ECHA compliance pathway eliminates fluorinated additive dependencies ahead of enforcement. |
| Nanofiber Surface Loading Adoption | Basel and Boston biopharmaceutical manufacturers pilot hybrid media for monoclonal antibody clarification trains. |
| Direct OEM Contracting Frameworks | Melbourne Water's tender consolidation from 23 to 4 vendors signals distributor displacement acceleration. |
| Dual-Compliant Product Architecture Investment | FDA and EU MDR parallel submissions justify engineering overhead for pharmaceutical market access. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down resin supply tracking forms the analytical core of this study. Primary interviews with plant managers at semiconductor fabs, procurement leads at water treatment utilities, technical R&D directors at filter OEMs, and channel partners in industrial distribution were cross-validated against secondary sources including EPA enforcement disclosures, ECHA restriction timelines, SEC 10-K filings from diversified industrial conglomerates, and customs data on polypropylene resin trade flows.
Input-output matrices segment volume and value across product grade, application environment, charging technology, and regional regulatory cluster throughout the forecast period. CAGRs derive from replacement cycle compression rates, capacity expansion announcements, and certification backlog timelines. Forecast inputs incorporate semiconductor node transition schedules and desalination utility tender pipelines.
Revisions become necessary when propylene feedstock volatility exceeds historical bands or when ECHA accelerates fluorinated substance enforcement timelines. Deviation in Chinese resin export licensing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Homopolymer Acrylic Filter Bags Market
Filters
Hydraulic Filters Market
Filters
Global Pleated Filters Market
Filters
Industrial Filter Paper Market
Filters
United States Activated Carbon Market
Filters
Global Liquid Filtration Market
Filters
Sintered Metal Filters Market
Filters
Filter Paper Market
Filters
Ceramic Filters Market
Filters
Drum Filters Market
Filters
GCC Industrial Air Filtration Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
Filter Bag Market
Filters
Filtering Centrifuges Market
Filters
Anti-Microbial Filter Market
Filters
Filter Media Market