
 Global Industrial Filters Market | 2026-2036
Global Industrial Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Filters Market Outlook
China's Yangtze River Delta manufacturing belt is rewriting competitive dynamics for industrial filtration supply. Parker Hannifin leverages its hydraulics heritage to dominate high-pressure liquid filtration for mobile equipment. Donaldson Company anchors its position through proprietary nanofiber media technology in engine and industrial air intake systems. Mann+Hummel competes by extending its automotive filter expertise into industrial process applications across European and Asian production networks.
Industrial filters are mechanical or media-based separation devices engineered to remove particulate, chemical, or biological contaminants from air, liquid, gas, or oil process streams, typically rated by micron retention efficiency, flow capacity, and pressure-drop tolerance. Their primary purpose is protecting downstream equipment, ensuring product purity, and maintaining compliance with occupational and environmental exposure limits. Liquid filtration for chemical processing occupies the deepest margin pools due to corrosion-resistant alloy housings and custom membrane specifications. HEPA technology leads in pharmaceutical cleanroom and electronics fabrication applications where particle counts below 0.3 microns determine yield rates. Activated carbon segments are maturing in solvent recovery and odor control roles across food processing and wastewater treatment facilities.
The US EPA enforces National Emission Standards for Hazardous Air Pollutants that mandate continuous particulate monitoring and control, directly expanding demand for high-efficiency industrial baghouse and cartridge filters. China's MEE implements GB standards for industrial wastewater discharge that force upgrades across steel, textile, and chemical plants. ISO 16890 for air filter classification and ISO 29463 for HEPA and ULPA performance create cross-border product equivalence that eases market access for certified manufacturers. Stakeholders must monitor how evolving PFAS restrictions in Europe and North America reshape membrane material selection and disposal liabilities across the filter value chain.
Market Dynamics
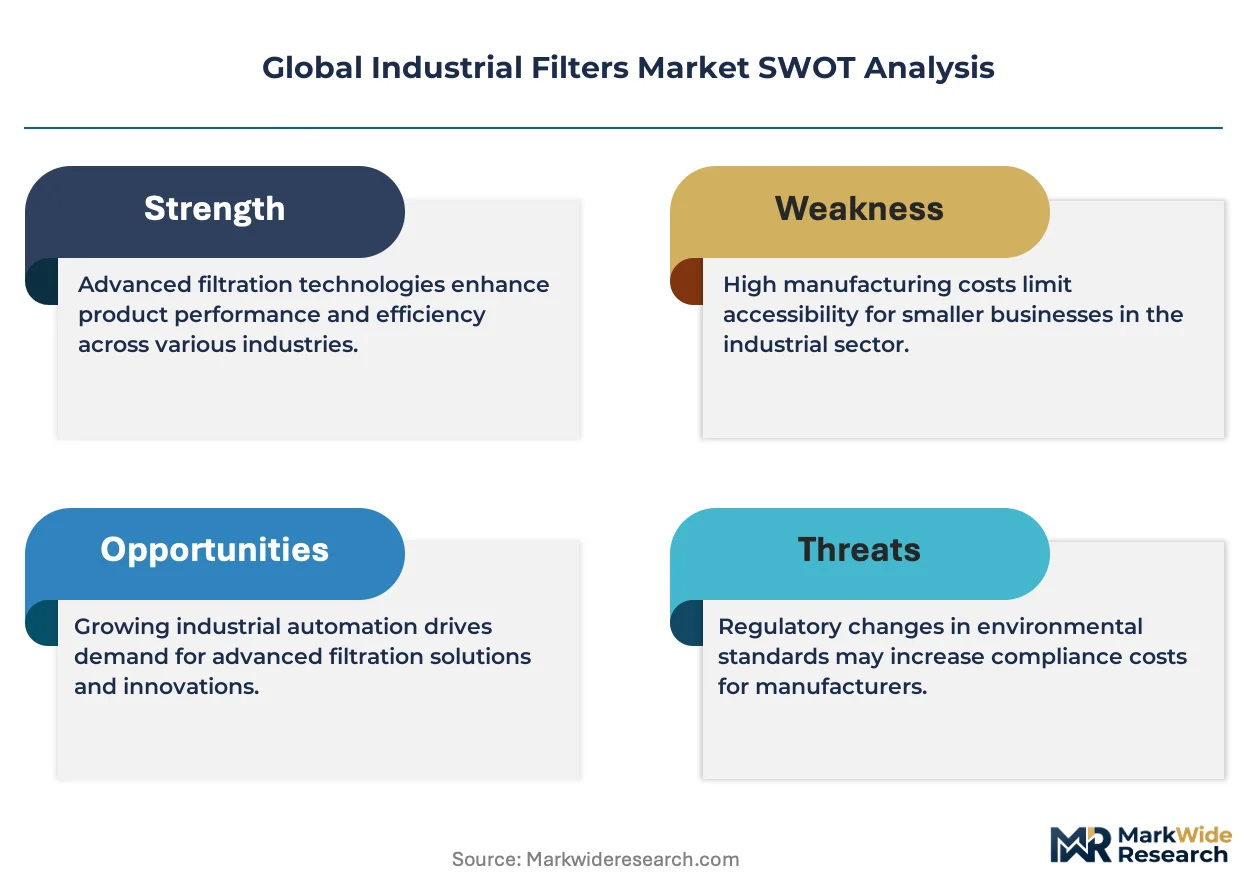
Filter media suppliers face relentless pressure from tightening emissions protocols that force replacement cycles shorter than equipment depreciation schedules. China's MEE wastewater standards and the EU F-Gas Regulation are compressing payback periods for filtration infrastructure investments across chemical processing and power generation clusters.
Growth Catalysts
- Asia-Pacific power generation expansion:Coal and gas turbine operators in India and Vietnam are installing high-capacity baghouse systems to meet national air quality mandates ahead of plant commissioning.
- REACH substance restrictions:The EU's phased limitations on PFAS-containing membranes are accelerating R&D into bio-based polymer alternatives with comparable chemical resistance.
- Nanofiber coating technology:Advanced surface layering techniques are extending filter service intervals in cement and steel applications where particulate loading is extreme.
Market Restraints
- Stainless steel alloy volatility:Housing fabrication costs for corrosive chemical environments swing with nickel and molybdenum spot markets, eroding quoted project margins.
- Membrane supply concentration:Polytetrafluoroethylene and polyethersulfone media production clusters in Germany and Japan create single-source vulnerability for critical pharmaceutical and electronics applications.
- Technical limitation in high-temperature gas streams:Ceramic and sintered metal filters above 400°C remain prohibitively expensive for widespread adoption in metallurgical off-gas treatment.
Strategic Opportunities
- Indonesian industrial corridor development:The Batang integrated industrial estate is attracting petrochemical investments that require turnkey filtration packages for process water and vent gas treatment.
- EU Green Deal carbon border adjustments:Export-oriented manufacturers in Turkey and Ukraine must install certified emission control systems to maintain market access, creating retrofit demand.
- Digital twin integration:Predictive pressure-drop modeling combined with IoT sensor networks is enabling filter replacement scheduling that minimizes unplanned downtime in continuous chemical processes.
Industry Challenges
- Cross-functional engineering scarcity:Filter system design now demands simultaneous expertise in fluid dynamics, materials science, and regulatory compliance that training pipelines have not scaled to match.
- Legacy equipment interoperability:Retrofitting advanced membrane modules into 1980s-vintage housing geometries requires custom fabrication that extends project timelines and certification costs.
- ISO 16890 transition complexity:Laboratories and manufacturers face backlog in retesting entire product portfolios against the ePM classification system, delaying market launches.
Report Scope
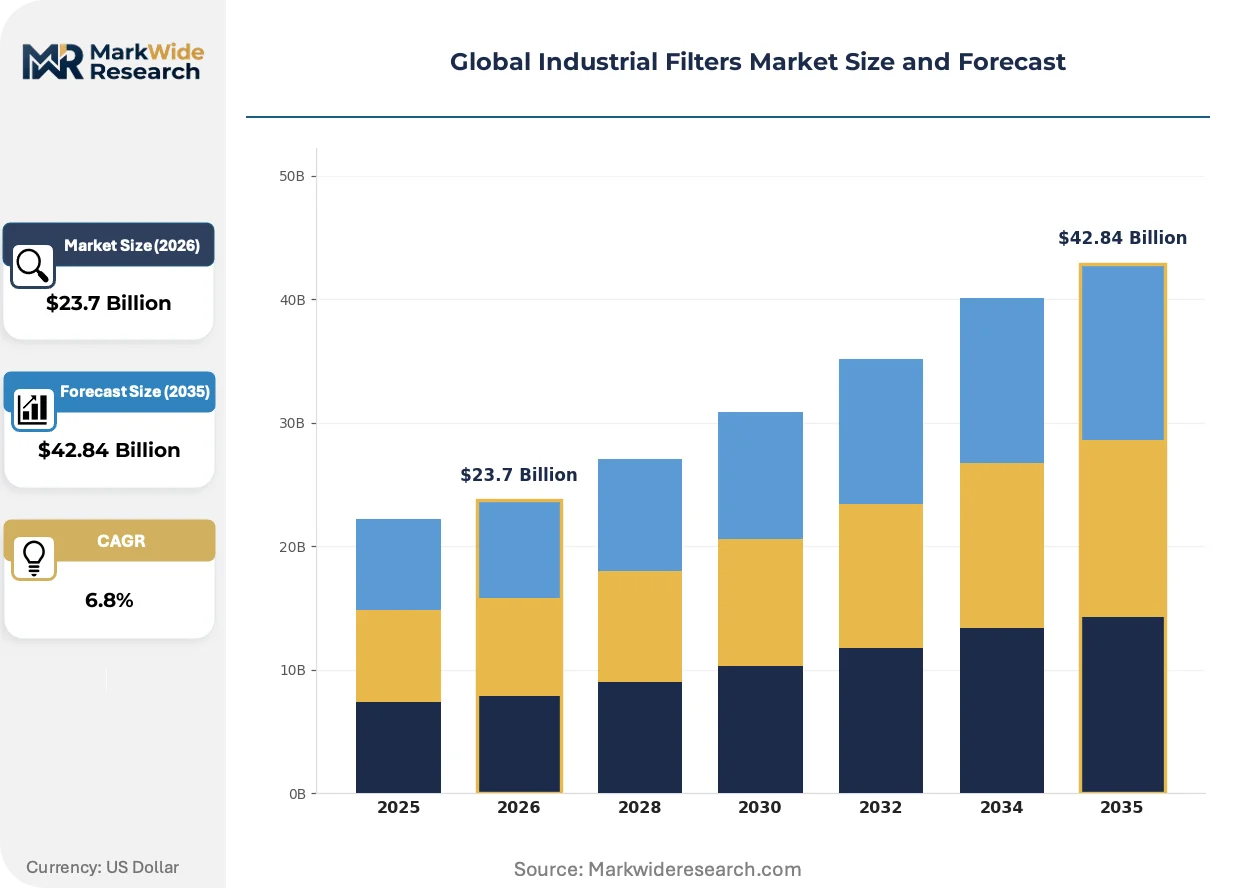
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Filters Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Filters, Liquid Filters, Gas Filters, Oil Filters Application: Manufacturing, Food Processing, Pharmaceuticals, Chemical Processing End User: Automotive, Aerospace, Electronics, Power Generation Technology: PLEATED, HEPA, UV-C, Activated Carbon |
| Companies Covered | Parker Hannifin, Donaldson Company, 3M, Pall Corporation, Eaton Corporation, Hydac International, Mann+Hummel, Alfa Laval, Filtration Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Filters Market Strategic Shifts
Filtration technology is pivoting toward predictive maintenance architectures and material substitutions that reduce lifecycle environmental liability. The convergence of sensor miniaturization with advanced polymer chemistry is compressing the gap between commodity and performance-tier product boundaries.
Self-cleaning backpulse systems with ceramic membrane cores are rendering obsolete manual cartridge replacement protocols in food and beverage CIP applications. Dairy processors and brewery operators are adopting these units to eliminate production interruptions during filter maintenance windows. The shift is compressing aftermarket spare parts revenue pools while expanding upfront system pricing power for integrated solution vendors.
The EPA's proposed updates to National Emission Standards for Hazardous Air Pollutants will tighten particulate limits for secondary aluminum smelters and foundries. Metal casting operators must upgrade from standard baghouse configurations to pleated cartridge systems with higher air-to-cloth ratios. Equipment fabricators in Ohio and Pennsylvania are pre-engineering modular skids to accelerate compliance timelines for regional foundry clusters.
Specification authority is migrating from plant maintenance departments to corporate procurement functions with centralized sustainability scorecards. Filter vendors now face consolidated purchasing agreements that bundle air, liquid, and dust collection requirements across multi-site manufacturing networks. This concentration is most pronounced in German automotive supplier networks where OEM sustainability audits cascade requirements through tiered production contracts.
Global Industrial Filters Market Segmentation
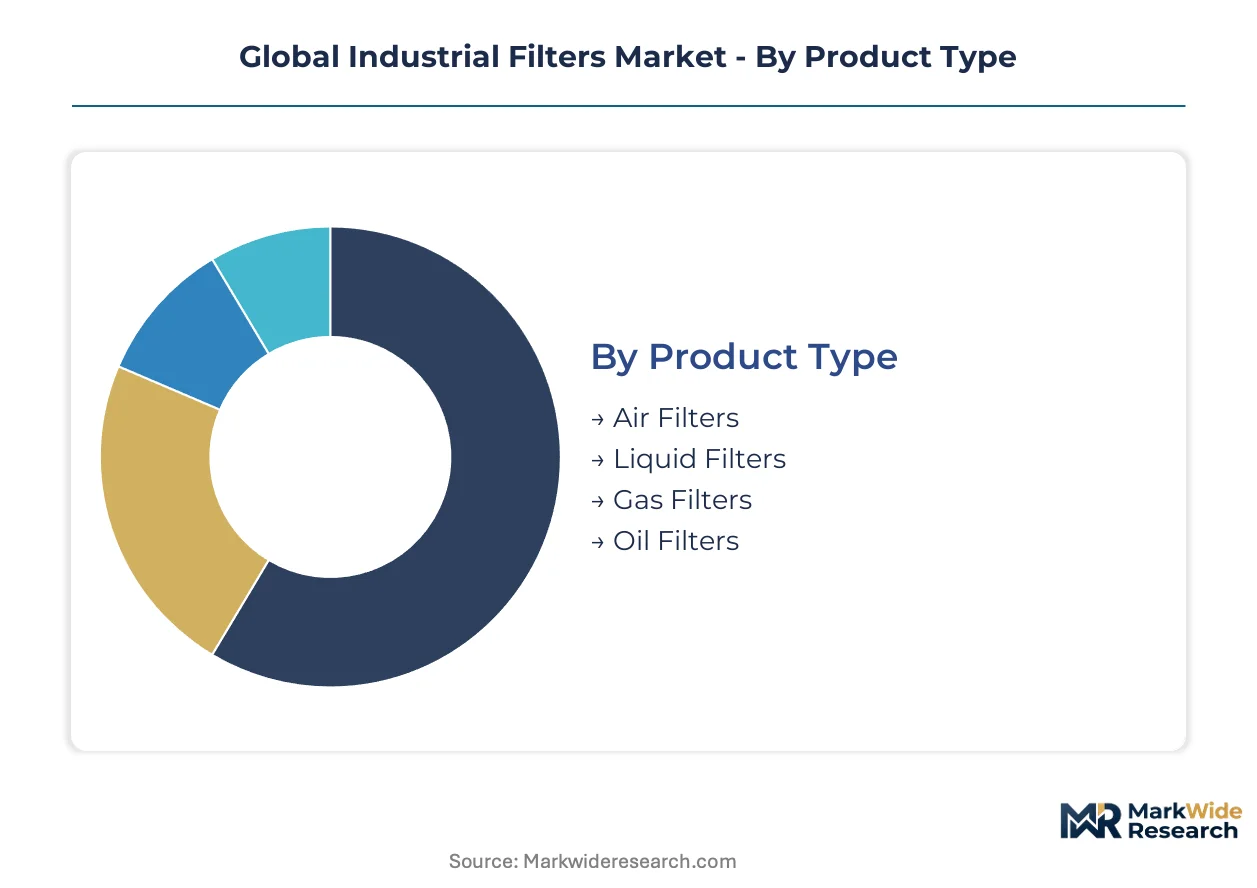
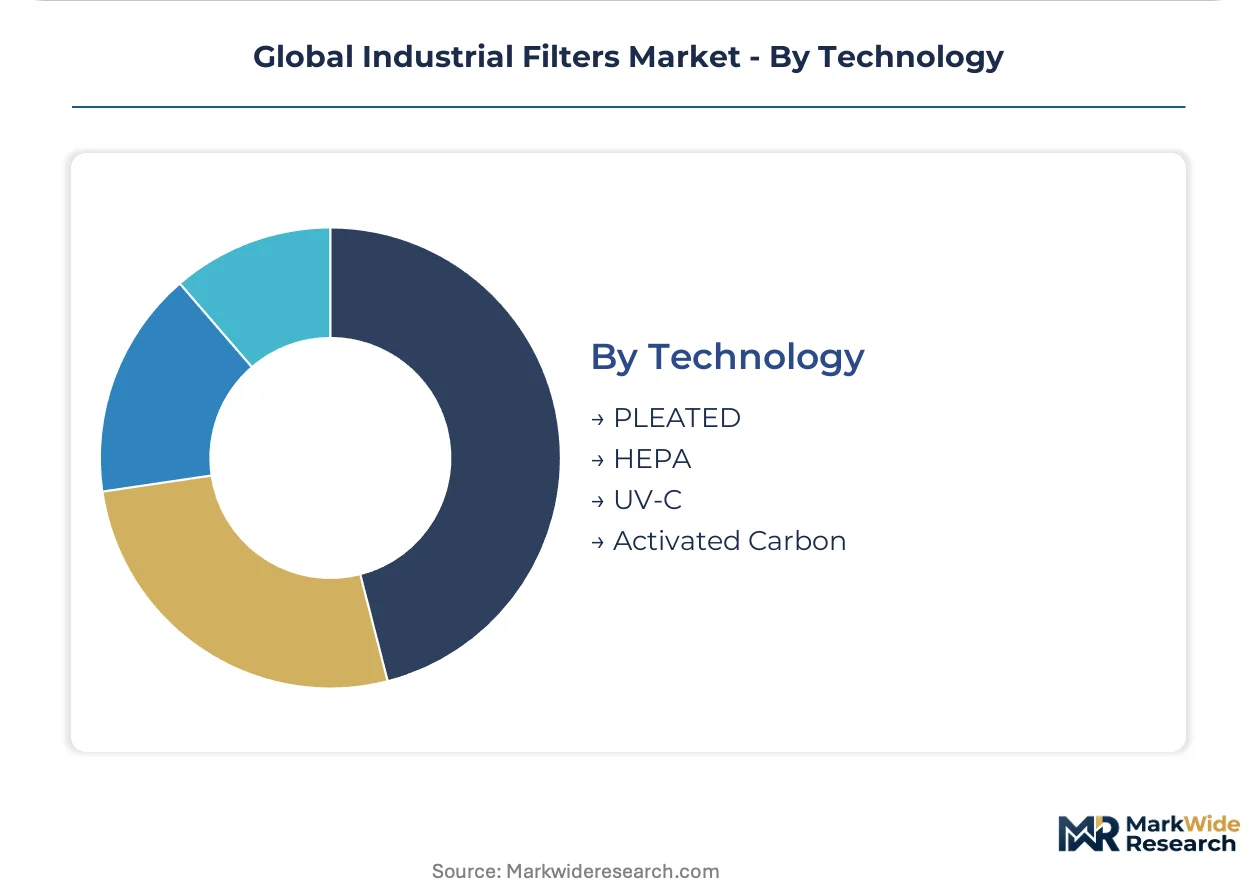
Industrial filter procurement decisions cascade through four distinct segmentation lenses, each reshaping vendor engagement models and margin structures. Product type determines materials science requirements, while technology selection locks in replacement cycle economics and regulatory compliance pathways.
Product Type:
Cost tier differentiation separates commodity media from engineered housings requiring corrosion-resistant alloys and custom membrane specifications.
- Air Filters:Engineered from synthetic fiber mats, pleated paper, or nanofiber composites with MERV ratings dictating particulate capture efficiency. Demand concentrates in China's Yangtze River Delta manufacturing belt where automotive paint booths and electronics cleanrooms require ISO 16890-certified ePM1 performance.
- Liquid Filters:Constructed with polypropylene, PTFE, or stainless steel mesh elements rated by micron retention and flow capacity. Chemical processing plants in Germany's BASF-Ludwigshafen corridor specify these for aggressive solvent streams under REACH substance restrictions.
- Gas Filters:Deploy ceramic, sintered metal, or polymer membranes for corrosive process streams and compressed air systems. Semiconductor fabrication facilities in Japan's Kyushu region specify these for ultrapure gas delivery.
- Oil Filters:Combine cellulose or synthetic media with bypass valves for lubrication system protection. Mining operations in Western Australia's Pilbara region drive replacement demand for mobile equipment fleets.
Air filters hold installed capacity. Liquid filters are rotating up the share rankings.
Application:
Application segmentation tracks contamination risk tolerance and regulatory exposure intensity across process industries.
- Manufacturing:Spanning metalworking coolant filtration, paint booth overspray capture, and pneumatic system air drying. Automotive stamping plants in Michigan and Ontario specify these for continuous production reliability.
- Food Processing:Requiring FDA-compliant materials, CIP-compatible designs, and allergen control protocols. Dairy processors in Wisconsin and the Netherlands adopt self-cleaning backpulse systems to eliminate maintenance windows.
- Pharmaceuticals:Mandating HEPA and ULPA grades per ISO 29463 with validated sterilization protocols. Fill-finish operations in Switzerland's Basel region specify these for aseptic processing compliance.
- Chemical Processing:Demanding corrosion-resistant housings and chemically inert media for aggressive streams. Petrochemical complexes on the US Gulf Coast and in Saudi Arabia's Jubail Industrial City drive specification complexity.
Manufacturing anchors volume throughput. Pharmaceuticals is climbing the fastest on margin contribution.
End User:
Customer type concentration determines whether procurement emphasizes total cost of ownership or upfront capital minimization.
- Automotive:Spanning paint shop air filtration, engine test cell exhaust treatment, and machining coolant systems. OEMs in Germany's supplier pyramid cascade sustainability scorecard requirements through tiered contracts.
- Aerospace:Requiring lightweight, high-reliability filtration for fuel systems, hydraulic circuits, and cabin air. MRO facilities in Singapore and Dubai specify these for fleet maintenance programs.
- Electronics:Demanding sub-0.3-micron particle control for wafer fabrication and flat-panel display production. Cleanroom operators in South Korea's Gyeonggi Province specify molecular contamination control.
- Power Generation:Requiring high-capacity baghouse and cartridge systems for coal, gas, and biomass combustion emissions. Operators in India's National Capital Region install these ahead of commissioning to meet air quality mandates.
Automotive commands specification authority. Electronics is expanding most quickly on cleanroom buildouts.
Technology:
Technology maturity curves separate proven architectures from emerging platforms still establishing reliability records.
- PLEATED:Maximizing surface area within compact housings through folded media geometries. Cement and steel applications in Vietnam adopt nanofiber-coated variants for extreme particulate loading.
- HEPA:Achieving 99.97% efficiency at 0.3 microns through glass fiber mats in aluminum separators. Pharmaceutical cleanrooms in Ireland and North Carolina specify these for EU GMP and FDA compliance.
- UV-C:Integrating germicidal irradiation with mechanical filtration for biological control. Wastewater treatment plants in Australia's major cities pilot these for pathogen reduction.
- Activated Carbon:Adsorbing VOCs, odors, and solvent vapors through porous carbon structures. Food processors in Brazil deploy these for odor control and solvent recovery compliance.
PLEATED dominates unit volume. UV-C is gaining share fastest on biological safety tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deep-water port complex underwrites China's dominance in industrial filtration procurement. Germany's Rhine-Main-Danube waterway corridor anchors European supply chain integration for engineered filter systems.
United States
Secondary aluminum smelters in Ohio and Pennsylvania drive baghouse upgrade demand as EPA's NESHAP particulate limits tighten. The EPA enforces continuous monitoring mandates that accelerate replacement cycles for foundry dust collection infrastructure. Houston's petrochemical corridor specifies corrosion-resistant liquid filtration for aggressive solvent streams under Gulf Coast process safety protocols.
Germany
Automotive supplier networks cascade sustainability scorecard requirements through tiered production contracts. ECHA's REACH substance restrictions force membrane material substitutions away from PFAS-containing formulations. BASF-Ludwigshafen's chemical processing cluster specifies custom alloy housings for high-temperature gas filtration in specialty chemical production.
China
Steel and textile plants along the Yangtze River Delta retrofit wastewater systems to meet MEE's GB discharge standards. The MEE implements phased effluent quality mandates that compress payback periods for filtration infrastructure investments. Suzhou's electronics cleanroom buildouts specify ISO 16890-certified ePM1 air filtration for semiconductor fabrication yield protection.
India
Coal and gas turbine operators in the National Capital Region install high-capacity baghouse systems ahead of plant commissioning. The Central Electricity Authority mandates air quality compliance timelines that front-load filtration procurement for power generation assets. Gujarat's petrochemical investments at Dahej and Hazira require turnkey filtration packages for process water and vent gas treatment.
Japan
Semiconductor fabrication facilities in Kyushu's silicon island cluster specify ultrapure gas filtration for molecular contamination control. METI's industrial decarbonization roadmap accelerates replacement cycles for energy-intensive filtration processes. Osaka-Kansai's pharmaceutical fill-finish operations demand ISO 29463-validated HEPA systems for aseptic processing compliance.
Global Industrial Filters Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in media and membrane supply. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with filtration divisions, pure-play filtration specialists with vertical technology stacks, and regional fabricators serving localized aftermarket demand. Consolidation pressure concentrates among mid-scale housing fabricators facing stainless steel alloy cost volatility. Dominant competitive moves include backward integration into membrane manufacturing and geographic expansion through distribution partnerships in Southeast Asian industrial corridors.
Among diversified industrial conglomerates, Parker Hannifin and Eaton Corporation exemplify platform integrators leveraging hydraulics and electrical systems heritage to anchor filtration within broader fluid power portfolios. Donaldson Company occupies a specialist position, representing the pure-play archetype through concentrated investment in proprietary media technology. Mann+Hummel exemplifies the European automotive-to-industrial extension model, translating OEM filter expertise into process applications across multi-regional production networks.
| Leading Market Players |
|---|
| Parker Hannifin |
| Donaldson Company |
| 3M |
| Pall Corporation |
| Eaton Corporation |
| Hydac International |
| Mann+Hummel |
| Alfa Laval |
| Filtration Group |
| Others |
Value Chain & Pricing Dynamics
German and Japanese membrane production clusters for PTFE and polyethersulfone media concentrate upstream supply, directing margin capture toward housing fabricators with corrosion-resistant alloy capabilities and certified system integrators serving pharmaceutical and electronics cleanroom applications.
Pricing Analysis
Volume-discount tiering structures dominate procurement across multi-site manufacturing networks, with three-tier pricing separating ISO 29463-validated HEPA systems from standard pleated configurations and commodity baghouse media. Price differentiation rests on certification grade and after-sales service bundling, where validated sterilization protocols command substantial premiums. Cost compression in standard pleated tiers is intensifying because specification authority has migrated to corporate procurement functions with centralized sustainability scorecards. Automotive supplier networks demonstrate least price sensitivity due to OEM audit cascades, while regional fabricators serving legacy aftermarket demand face greatest pricing pressure.
Supply Chain Analysis
Contract manufacturing capacity for filter housings concentrates with specialized metal fabricators in Germany, China, and the United States serving distinct regional demand clusters. Raw material dependencies center on nickel and molybdenum alloys for corrosive chemical environments, PTFE membranes for ultrapure applications, and nanofiber media for high-efficiency air filtration. Single-source vulnerability in German and Japanese membrane production creates structural supply chain risk for critical pharmaceutical and electronics applications. Distribution runs through OEM-direct channels for large system integrators and specialized industrial distributors for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as corporate procurement functions consolidate multi-site purchasing agreements, fragmenting specification authority away from plant maintenance departments and compressing vendor margins through bundled air, liquid, and dust collection requirements.
For Market Incumbents: Insulate market position through backward integration into membrane manufacturing to reduce single-source exposure, while expanding certified service networks in China's Yangtze River Delta to capture retrofit demand from MEE wastewater compliance deadlines. Priority rests on securing ISO 16890 laboratory accreditation ahead of competitor retesting backlogs. For New Entrants and Emerging Players: Pursue white-space opportunities in Indonesian petrochemical corridor development at Batang integrated industrial estate, where turnkey filtration packages for process water and vent gas treatment lack established vendor relationships. Target digital twin integration services for continuous chemical processes as the most penetrable technology entry point, leveraging IoT sensor partnerships with established automation suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale housing fabricators with captive alloy sourcing capabilities and existing certification infrastructure, positioned for consolidation as stainless steel volatility erodes standalone margins. Long-term viability favors platform integrators with backward integration into media technology. Monitor EPA NESHAP enforcement intensity for secondary aluminum smelters as inflection signal for baghouse upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captive PTFE supply reduces German and Japanese single-source vulnerability for pharmaceutical applications. |
| ISO 16890 Laboratory Accreditation Investment | Retesting backlog clearance accelerates product launches ahead of competitor certification delays. |
| Digital Twin Platform Development | Predictive pressure-drop modeling minimizes unplanned downtime for continuous chemical processors. |
| Indonesian Distribution Partnership | Batang industrial estate petrochemical investments require turnkey filtration packages without incumbent relationships. |
| Corrosion-Resistant Alloy Capacity Expansion | Nickel and molybdenum volatility protection secures margin stability for chemical processing specifications. |
Study Parameters
Cross-validation between primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchors the qualitative findings against secondary validation from customs trade data, SEC filings of diversified industrial conglomerates, filtration industry association reports, and regulatory disclosure databases. Bottom-up segment sizing triangulates against top-down macroeconomic calibration.
Calibration against historical replacement cycle data and regulatory compliance deadline clustering shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application contamination risk tolerance, end-user procurement concentration, and technology maturity curves. CAGRs derive from installed base growth, replacement frequency acceleration under tightening emissions protocols, and penetration rate assumptions for emerging membrane materials.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles and nickel alloy spot market volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution rates. Quarterly review of EPA NESHAP proposal finalization, EU PFAS restriction phase-in schedules, and MEE GB standard implementation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Sintered Metal Filters Market
Filters
Industrial Air Filtration Market
Filters
Industrial Filtration Market
Filters
Coolant Filtration Skids Market
Filters
Activated Carbon Filter Market
Filters
Fabric Filter System Market
Filters
Hydraulic Filters Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Aerospace Filter Market
Filters
Global Laboratory Filtration Market
Filters
Drum Filters Market
Filters
Global High Temperature Filters Market
Filters
Global Baghouse Filters Market
Filters
Anti-Microbial Filter Market
Filters
Global Sterile Filtration Market
Filters
Air Filtration Media Market